
 Automatic Hand Sanitizer Dispenser Market | 2026-2036
Automatic Hand Sanitizer Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Hand Sanitizer Dispenser Market Analysis
Stainless steel is repositioning ABS plastic in premium automatic hand sanitizer dispenser housings as durability expectations rise in high-traffic healthcare settings. Diversey leverages its institutional cleaning heritage to anchor hospital procurement contracts across North America. Ecolab competes through integrated hygiene service bundles that pair dispensers with consumable supply agreements. Gojo Industries dominates touchless technology leadership with sensor-optimized dispensing systems that reduce waste per activation.
An automatic hand sanitizer dispenser is an electromechanical or mechanical device engineered to deliver controlled volumes of alcohol-based or non-alcohol sanitizing solution through infrared proximity detection, pressure activation, or manual pump mechanisms, typically housing reservoirs between 500 mL and 5 L capacity for commercial deployment. Wall mounted units sustain the largest installed base across hospitals and office complexes where permanent fixture integration reduces floor congestion. Touchless infrared technology captures the fastest expansion trajectory as sensor miniaturization drives unit cost reductions below pressure-based alternatives. Direct sales channels occupy the dominant margin pool by eliminating distributor markups for bulk institutional purchasers.
EPA antimicrobial device registration and FDA facility sanitation guidance shape product compliance thresholds for manufacturers serving healthcare end users. OSHA workplace hygiene mandates and Joint Commission accreditation standards drive replacement cycles in U.S. hospitals and long-term care facilities. Stakeholders must monitor evolving touchless sensor reliability benchmarks and battery-life specifications as procurement committees weigh total cost of ownership against upfront hardware expenditure.
Market Dynamics
Touchless infrared sensor miniaturization is compressing unit economics and accelerating replacement cycles across institutional procurement channels.
Growth Catalysts
- Joint Commission accreditation standards:U.S. hospitals face mandatory hygiene infrastructure audits that specify touchless dispensing systems in patient care zones.
- Germany:Healthcare facility renovation cycles are accelerating as federal hospital modernization funds unlock capital expenditure for infection control hardware.
- Sensor-optimized dispensing:Waste reduction per activation creates measurable operational savings that procurement committees quantify in total cost of ownership models.
Market Restraints
- Stainless steel input volatility:Premium housing material costs fluctuate with commodity markets, squeezing margin on high-durability units.
- Supply concentration in East Asian sensor foundries:Infrared proximity module production clusters create single-source vulnerability for tier-two assemblers.
- Battery chemistry limitations:Lithium primary cells in high-traffic installations require replacement intervals that inflate field service costs.
Strategic Opportunities
- India:Underpenetrated hospital infrastructure presents whitespace as private healthcare chains expand tertiary care capacity in tier-two cities.
- Integrated hygiene service bundles:Dispensers paired with consumable supply agreements lock in recurring revenue streams and reduce competitive bidding exposure.
- EPA antimicrobial device registration:Tightening certification requirements create barrier-to-entry advantages for early-compliant manufacturers.
Industry Challenges
- Embedded systems firmware talent:Shortage of engineers with proximity sensor calibration and low-power wireless integration expertise delays product development cycles.
- FDA facility sanitation guidance compliance:Extended validation timelines for healthcare-grade units stretch working capital requirements.
- Legacy mechanical dispenser retrofit:Backward compatibility with existing wall fixtures complicates touchless upgrade paths in aged hospital infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Hand Sanitizer Dispenser Market |
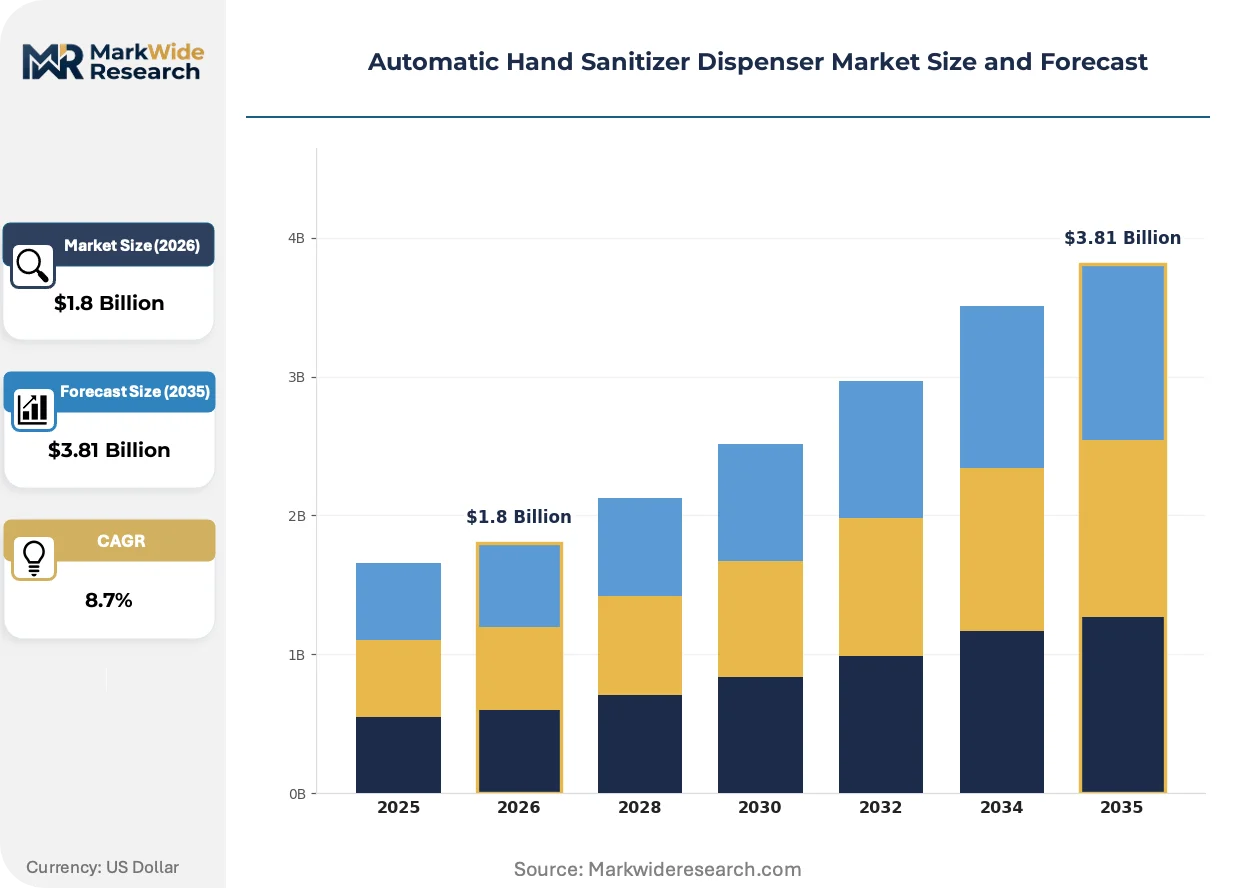
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Mounted, Tabletop, Floor Standing, Portable Technology: Infrared, Pressure, Touchless, Manual End User: Hospitals, Offices, Schools, Public Transport Distribution Channel: Online Retail, Supermarkets, Distributors, Direct Sales |
| Companies Covered | Diversey, Tork, Gojo Industries, Safetec, ECOtouch, Kimberly-Clark, Deb Group, Medline, Ecolab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Hand Sanitizer Dispenser Market Emerging Trajectories
Electromechanical architectures are fragmenting into interchangeable subsystems that let procurement teams customize dispenser specifications without engineering new housings.
Sensor-optimized dispensing technology is modularizing around standardized infrared proximity cores that slot into multiple housing form factors. Hospital procurement teams in Japan are specifying these interchangeable modules to reduce spare parts inventory. This architecture is compressing supplier switching costs and enabling multi-source qualification for critical components.
EPA antimicrobial device registration requirements are tightening validation protocols for alcohol-based solution compatibility. Manufacturers must now submit extended material degradation testing that extends product launch timelines by eight to fourteen months. Healthcare distributors in the United States are prioritizing compliant SKUs in contract negotiations, marginalizing uncertified competitors.
Facility managers are unbundling after-sales service contracts from hardware procurement, selecting third-party maintenance providers based on response-time guarantees rather than manufacturer affiliation. This pattern is most pronounced in Germany where hospital engineering departments maintain in-house technician pools. Channel intermediaries are capturing service margin that previously accrued to original equipment suppliers.
Automatic Hand Sanitizer Dispenser Market Segmentation
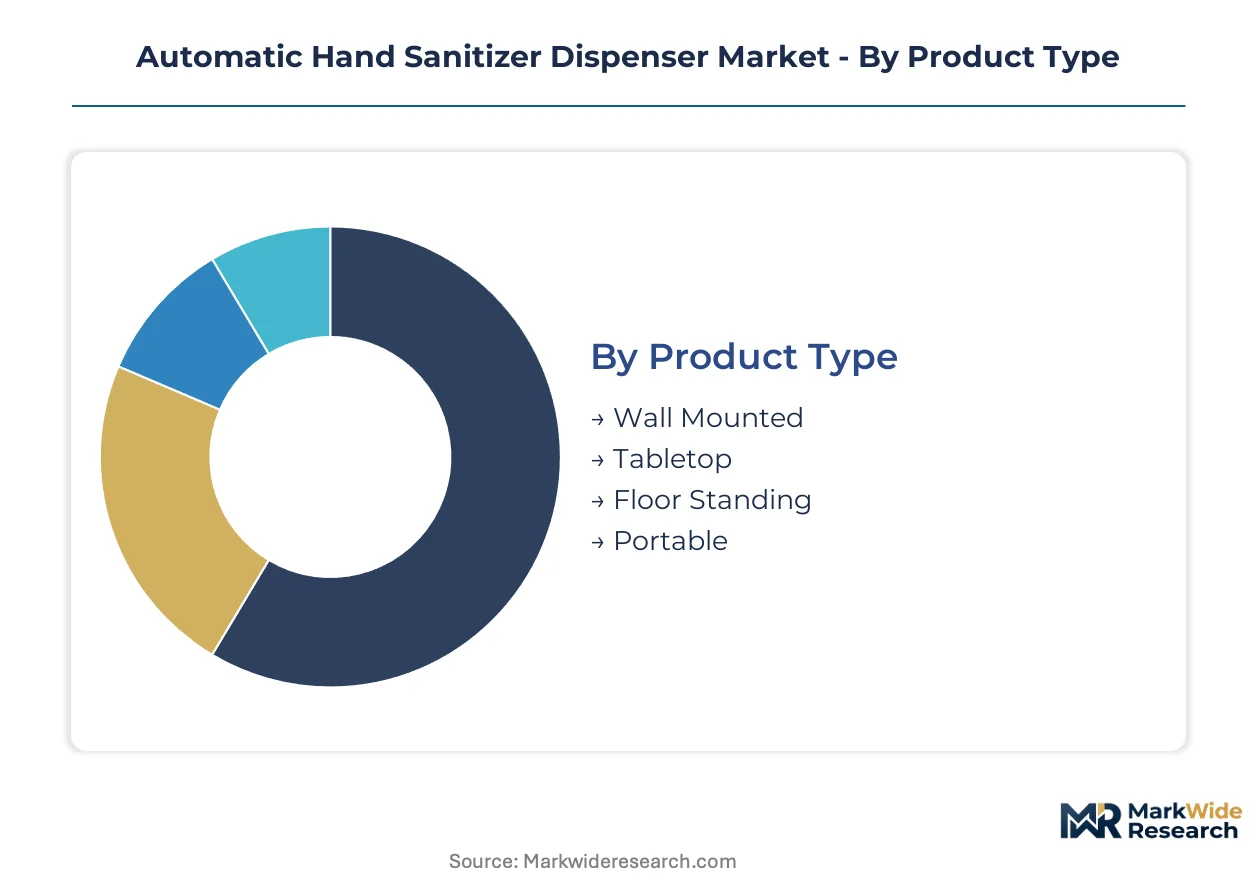
Dispenser procurement committees segment demand by fixture permanence, activation technology, and facility compliance requirements. Each category carries distinct margin structures and replacement cycle dynamics that shape supplier positioning.
Product Type:
Facility managers differentiate purchases by installation permanence and traffic density tolerance.
- Wall Mounted:Permanent fixture integration dominates hospital and office complex deployments where floor congestion reduction drives specification. Germany's federal hospital modernization funds are accelerating replacement cycles for legacy mechanical units in patient care zones. Volume sits with Wall Mounted; growth tilts toward Floor Standing.
- Floor Standing:Freestanding units with weighted bases serve high-traffic lobbies and transit hubs requiring repositioning flexibility. Japan's hospital engineering departments specify these for emergency department triage areas where rapid layout reconfiguration is essential.
- Tabletop:Compact countertop units target reception desks and examination room sinks with 500 mL reservoir capacity.
- Portable:Battery-powered handheld or clip-on dispensers serve field medical teams and mobile vaccination sites.
Procurement volume clusters in permanent fixtures; mobility features command premium pricing in emergency response applications.
Technology:
Sensor reliability and power consumption separate institutional-grade specifications from consumer alternatives.
- Infrared:Proximity detection modules using LED-photodiode pairs now dominate institutional procurement as sensor miniaturization compresses unit costs below pressure-based alternatives. EPA antimicrobial device registration requirements are tightening validation protocols for touchless systems in U.S. healthcare facilities. Volume sits with Infrared; growth tilts toward Touchless optimization.
- Touchless:Sensor-optimized dispensing with calibrated activation zones reduces waste per activation and creates measurable operational savings in high-traffic installations.
- Pressure:Mechanical elbow or foot pedals persist in budget-constrained facilities and food processing environments where electronic component failure risks are unacceptable.
- Manual:Spring-loaded pump mechanisms retain share in developing markets and backup redundancy configurations.
Electromechanical architectures are fragmenting into interchangeable subsystems that procurement teams customize without engineering new housings.
End User:
Compliance thresholds and infection control liability shape buyer willingness to pay for certified hardware.
- Hospitals:Joint Commission accreditation standards mandate touchless dispensing in patient care zones, driving specification of EPA-registered units with extended material degradation testing. U.S. hospitals face mandatory hygiene infrastructure audits that accelerate replacement cycles. Volume sits with Hospitals; growth tilts toward Public Transport.
- Offices:Corporate facility managers prioritize total cost of ownership models that quantify waste reduction from sensor-optimized activation.
- Schools:K-12 districts and university systems balance upfront hardware expenditure against battery replacement service intervals.
- Public Transport:Airports, rail stations, and bus terminals are expanding touchless infrastructure as passenger volume recovery justifies capital expenditure.
Healthcare compliance requirements concentrate margin in certified units; transit infrastructure expansion is climbing the fastest.
Distribution Channel:
Channel selection determines margin capture and customer relationship depth for suppliers.
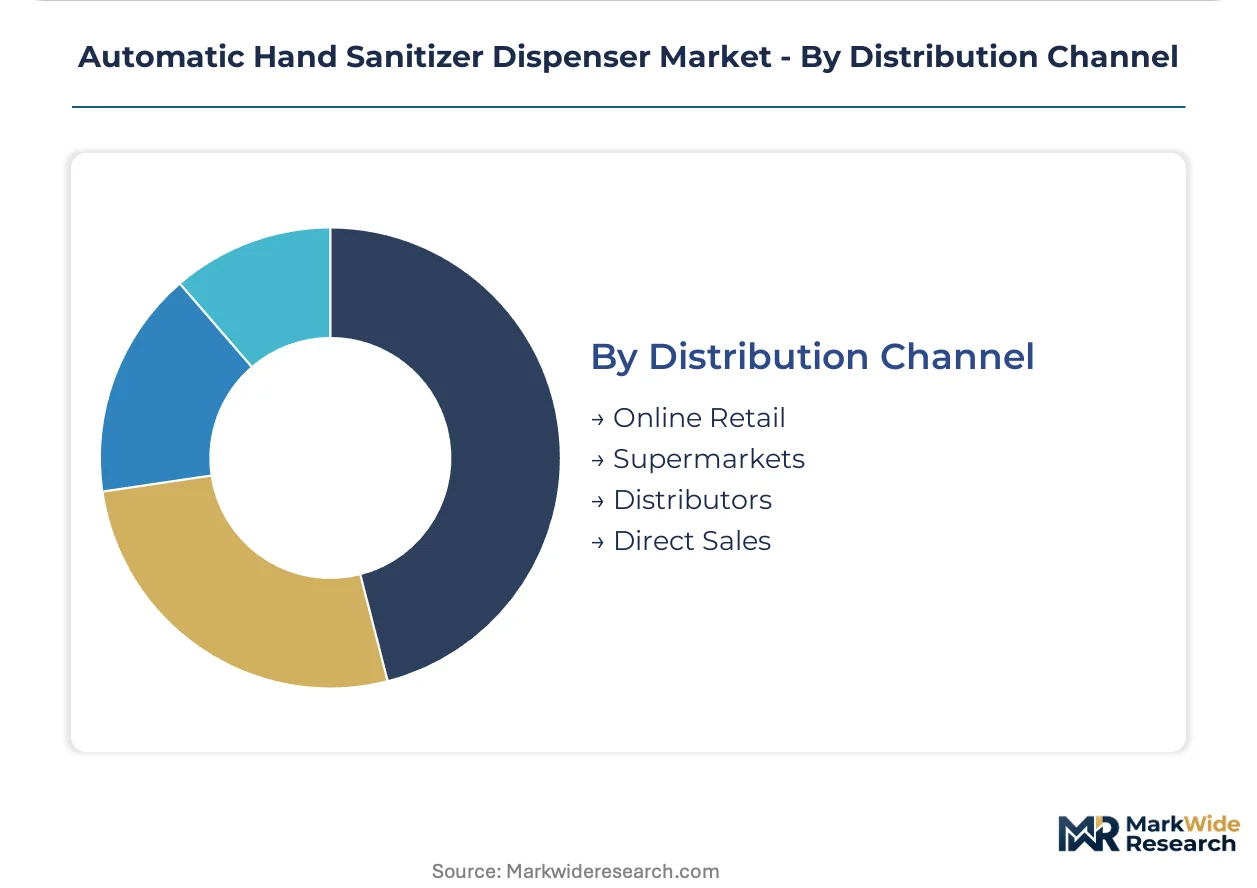
- Direct Sales:Bulk institutional procurement through manufacturer sales teams eliminates distributor markups and enables integrated hygiene service bundling. Hospital procurement committees in the United States favor direct relationships for multi-year consumable supply agreements. Volume sits with Direct Sales; growth tilts toward Online Retail.
- Distributors:Healthcare and janitorial supply intermediaries maintain field service capabilities that manufacturers are unbundling in Germany.
- Online Retail:E-commerce platforms serve small office and residential demand with rapid delivery and SKU breadth.
- Supermarkets:Mass retail channels move consumer-grade tabletop units with limited institutional penetration.
Institutional direct relationships lock in recurring revenue; digital channels are expanding most quickly in small-facility segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for automatic hand sanitizer dispensers clusters in healthcare systems with active facility renovation programs and stringent accreditation standards. Procurement committees in Germany, the United States, and Japan currently drive the largest volume commitments, while emerging installations in India and Brazil are accelerating from low bases.
Germany
Federal hospital modernization funds are unlocking capital expenditure for infection control hardware across university medical centers and municipal hospital networks. The country's healthcare procurement framework prioritizes EPA-equivalent antimicrobial device registration for touchless systems. Bavaria's medical technology cluster around Munich is witnessing accelerated replacement cycles for legacy mechanical dispensers in patient care zones.
United States
Joint Commission accreditation standards mandate touchless dispensing infrastructure during mandatory hygiene audits in acute care facilities. OSHA workplace hygiene mandates and FDA facility sanitation guidance shape compliance thresholds for manufacturers serving hospital end users. Texas Medical Center in Houston and the Cleveland Clinic corridor in Ohio represent concentrated demand nodes where procurement committees specify sensor-optimized units.
Japan
Hospital engineering departments are specifying modular infrared proximity systems to reduce spare parts inventory across multi-site networks. METI industrial standards for medical device interoperability influence procurement specifications for electromechanical hygiene equipment. The Kansai region around Osaka is seeing concentrated deployments in emergency department triage areas requiring rapid layout reconfiguration capabilities.
India
Private healthcare chains are expanding tertiary care capacity in tier-two cities with limited existing touchless hygiene infrastructure. The country's national pharmaceutical regulator and hospital accreditation bodies are gradually tightening infection control equipment standards. Maharashtra's Mumbai-Pune corridor and Karnataka's Bangalore cluster are emerging as focal points for initial institutional-grade dispenser installations.
Brazil
Airport and rail terminal operators are expanding touchless infrastructure as passenger volume recovery justifies capital expenditure in transit hubs. ANVISA medical device registration requirements are creating compliance barriers for uncertified imported equipment. São Paulo's healthcare procurement cooperatives are piloting integrated hygiene service bundles that pair dispensers with consumable supply agreements.
Automatic Hand Sanitizer Dispenser Market Vendor Landscape
Integrated hygiene service bundling dominates the current landscape as manufacturers seek to lock in recurring revenue streams beyond hardware margins. The vendor base fragments across institutional cleaning heritage companies, medical supply distributors, and specialized electromechanical fabricators. Three strategic archetypes have emerged: heritage institutional hygiene providers leveraging procurement relationships, integrated facility service bundlers capturing consumable attach rates, and sensor-optimized technology specialists competing on waste reduction metrics. Geographic expansion into underpenetrated hospital markets and technology licensing for modular infrared subsystems represent the two most visible competitive moves.
Among heritage institutional hygiene providers, Diversey and Ecolab exemplify archetypes anchored in decades-long hospital procurement relationships. Gojo Industries occupies a position within the sensor-optimized technology tier, representing touchless innovation leadership through proximity detection engineering. These three companies illustrate how competitive positioning stratifies across relationship depth, service integration breadth, and technical differentiation rather than scale alone.
| Leading Market Players |
|---|
| Diversey |
| Tork |
| Gojo Industries |
| Safetec |
| ECOtouch |
| Kimberly-Clark |
| Deb Group |
| Medline |
| Ecolab |
| Others |
Supply Flow & Price Mechanics
EPA antimicrobial device registration mandates gate qualified supply and premium-tier pricing access for manufacturers serving healthcare end users. Compliance validation timelines stretch working capital requirements, compressing margin on uncertified alternatives while concentrating procurement volume with early-compliant suppliers.
Pricing Analysis
Volume sits with wall-mounted infrared units in institutional direct sales channels; margin concentrates in sensor-optimized touchless systems with integrated consumable bundling. Price differentiation hinges on EPA registration tier and stainless steel housing grade versus ABS plastic alternatives. Pricing pressure stems from lithium battery chemistry limitations inflating field service costs in high-traffic installations. K-12 school districts exhibit highest price sensitivity due to constrained capital budgets; hospital procurement committees prioritize total cost of ownership over upfront hardware expenditure.
Supply Chain Analysis
Warehouse-distribution layer consolidation around regional healthcare supply hubs in Germany, the United States, and Japan shapes downstream fulfillment economics. Infrared proximity module production clusters in East Asian foundries; stainless steel sheet inputs draw from German and Japanese mills. Single-source vulnerability in sensor foundries creates supply chain risk for tier-two assemblers lacking multi-source qualification. Distribution runs through institutional cleaning supply distributors with unbundled field service capabilities capturing margin from original equipment suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
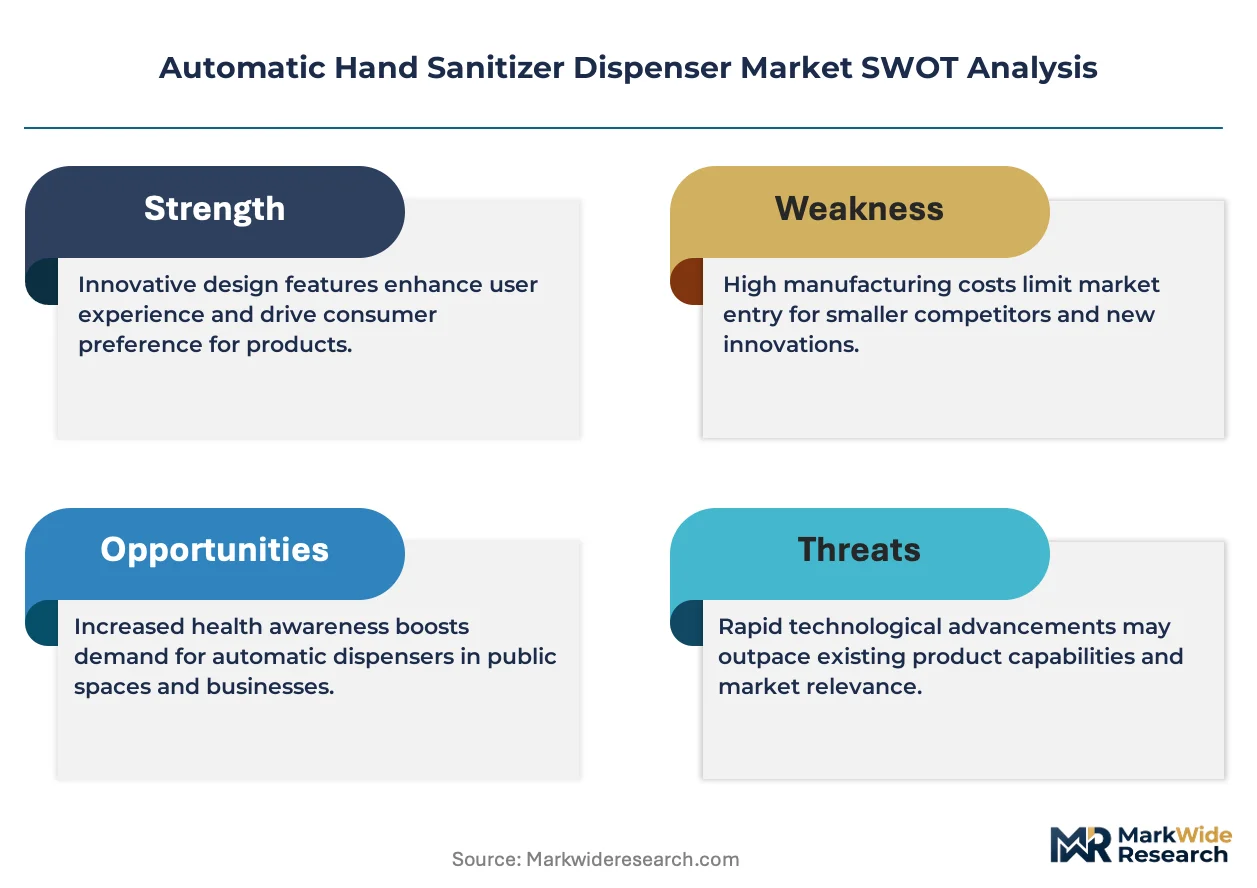
EPA antimicrobial device registration functions as a cost-of-compliance barrier-to-entry moat, marginalizing uncertified competitors while rewarding early investment in extended material degradation testing protocols.
For Market Incumbents: Hedge against sensor foundry concentration by qualifying secondary infrared module suppliers in alternative geographies. Anchor hospital procurement relationships through integrated hygiene service bundles that pair dispenser hardware with consumable supply agreements, locking in recurring revenue streams against emerging electromechanical fabricators. For New Entrants and Emerging Players: Launch via direct sales to private healthcare chains in India's tier-two cities where touchless infrastructure remains underpenetrated. Target tabletop and portable form factors for mobile vaccination sites and field medical teams, segments where established players maintain weaker positioning and certification requirements permit faster market entry. For Investors and Strategic Acquirers: Joint Commission accreditation audit failure rates are the leading indicator that replacement cycle acceleration will concentrate procurement volume with compliant suppliers. Position acquisition screening around modular infrared subsystem specialists with METI interoperability certification and hospital engineering department relationships, watching for EPA registration backlog clearance as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EPA Antimicrobial Device Registration | Extended validation protocols create eight-to-fourteen month launch barriers for uncertified competitors. |
| Integrated Hygiene Service Bundling | Dispensers paired with consumable agreements lock in recurring revenue and reduce competitive bidding exposure. |
| Sensor Module Multi-Source Qualification | Secondary infrared foundry relationships mitigate single-source vulnerability from East Asian concentration. |
| Stainless Steel Housing Transition | Durability expectations in high-traffic healthcare settings reposition premium materials against ABS plastic. |
| Third-Party Maintenance Partnership | Unbundled service contracts in Germany capture margin previously accruing to original equipment suppliers. |
Methodological Framework
Multi-period observation of hospital procurement contract awards, sensor module pricing indices, and regulatory submission timelines anchored the trend analysis, supplemented by interviews with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and institutional cleaning supply distributors. Secondary validation drew from FDA facility sanitation guidance documents, EPA antimicrobial device registration databases, hospital procurement cooperative records, and customs trade data for stainless steel and electronic component imports. Bottom-up unit shipment estimates triangulated against top-down healthcare capital expenditure projections.
Segment-weighting across product type, activation technology, end-user facility category, and distribution channel shaped volume and value outputs across the analysis window. CAGRs were derived from fitted growth curves incorporating replacement cycle dynamics, accreditation mandate compliance deadlines, and federal hospital modernization fund disbursement patterns. Industry-specific forecast inputs included Joint Commission audit scheduling density and METI medical device interoperability standard adoption trajectories.
Regulatory submission backlog fluctuations, lithium battery supply disruptions, and healthcare facility renovation funding delays are the dominant revision risks that could alter trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Global Healthcare Distribution Market
Healthcare Products
Hand Sanitizer Market
Healthcare Products
Consumer Healthcare Market
Healthcare Products
GCC Healthcare Packaging Market
Healthcare Products
Incontinence Products Market
Healthcare Products
Global Clinical Trial Consumables Market
Healthcare Products
Global Life Science Products Market
Healthcare Products
Dementia Care Products Market
Healthcare Products
Organ Care Products Market
Healthcare Products
Blood and Blood Components Market
Healthcare Products
Menstrual Sponge Market
Healthcare Products
Europe Blood and Blood Components Market
Healthcare Products
Cooling Mattress Market
Healthcare Products
Ejiao Health Products Market
Healthcare Products
Birth Tissue Products Market
Healthcare Products
Contraceptive Sponges Market