
 Global Clinical Documentation Improvement Market | 2026-2036
Global Clinical Documentation Improvement Market Size, Share, and Industry Trends Forecast 2026-2036
Global Clinical Documentation Improvement Market Foresight
A shift from single-source vendor relationships toward multi-source CDI ecosystems is rebalancing procurement strategies across health systems. 3M Health Information Systems leverages natural language processing depth to anchor enterprise contracts with large integrated delivery networks. Nuance Communications sustains technology leadership in ambient clinical intelligence that auto-generates documentation from patient encounters. Optum competes through vertical integration with payer data assets that sharpen risk adjustment accuracy for provider clients.
Clinical Documentation Improvement encompasses processes, technologies, and professional services that enhance the accuracy, specificity, and completeness of medical record documentation to reflect true patient acuity and support appropriate reimbursement. Software solutions dominate product-type revenue as health systems prioritize automated query generation and real-time physician nudges embedded within EHR workflows. Revenue cycle optimization and risk adjustment applications capture disproportionate investment as Medicare Advantage penetration and value-based contracting expand the financial upside of precise coding. Cloud-based deployment modes are displacing on-premise installations as hospitals seek faster implementation cycles and reduced infrastructure overhead.
FDA oversight of clinical decision support software, HIPAA privacy and security mandates, and CMS quality reporting programs collectively shape CDI technology requirements and market access conditions in the United States. EMA's evolving expectations for real-world evidence quality and the EU AI Act's risk classification framework for health applications are introducing parallel compliance layers for vendors operating across jurisdictions. Stakeholders must monitor how reimbursement rulemaking by national health authorities redefines the return on investment calculus for documentation precision investments.
Market Dynamics
Natural language processing integration into electronic health record workflows is compressing documentation cycles from hours to minutes, forcing CDI vendors to reposition around real-time clinical intelligence rather than retrospective coding review.
Growth Catalysts
- CMS Quality Reporting Programs:United States hospitals face escalating financial penalties for documentation gaps, accelerating investment in automated query engines that flag specificity deficiencies during patient encounters.
- Diagnosis-Related Group Refinements:Germany's Institut für das Entgeltsystem im Krankenhaus recalibrated reimbursement weights, pressuring providers toward precision coding that captures true patient acuity.
- Medicare Advantage Penetration:Risk-adjusted contracting models reward documentation accuracy with direct revenue upside, concentrating vendor development on Hierarchical Condition Category capture tools.
Market Restraints
- Interoperability Friction:HL7 FHIR implementation gaps between legacy EHR architectures and cloud-native CDI platforms prolong deployment timelines and inflate integration costs.
- Physician Workflow Resistance:Alert fatigue from intrusive documentation nudges triggers user abandonment, undermining query response rates and program ROI.
- Cloud Infrastructure Concentration:Reliance on hyperscale providers for NLP compute creates vendor lock-in and data sovereignty complications for European health systems under GDPR.
Strategic Opportunities
- EU AI Act Compliance:Risk classification frameworks for clinical decision support software create first-mover advantage for vendors pre-certifying high-risk documentation automation tools.
- Outpatient CDI Expansion:Ambulatory surgical centers and specialty clinics remain underpenetrated relative to inpatient settings, offering greenfield deployment potential.
- Real-World Evidence Integration:Convergence of CDI data pipelines with pharmaceutical outcomes research opens adjacent revenue streams in life sciences contracting.
Industry Challenges
- Clinical Informaticist Shortage:Health systems struggle to recruit professionals bridging medicine, coding, and data science, constraining program scaling velocity.
- Legacy EHR Integration Complexity:Custom interface development for aged Cerner and Epic installations consumes 40-60% of implementation budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Clinical Documentation Improvement Market |
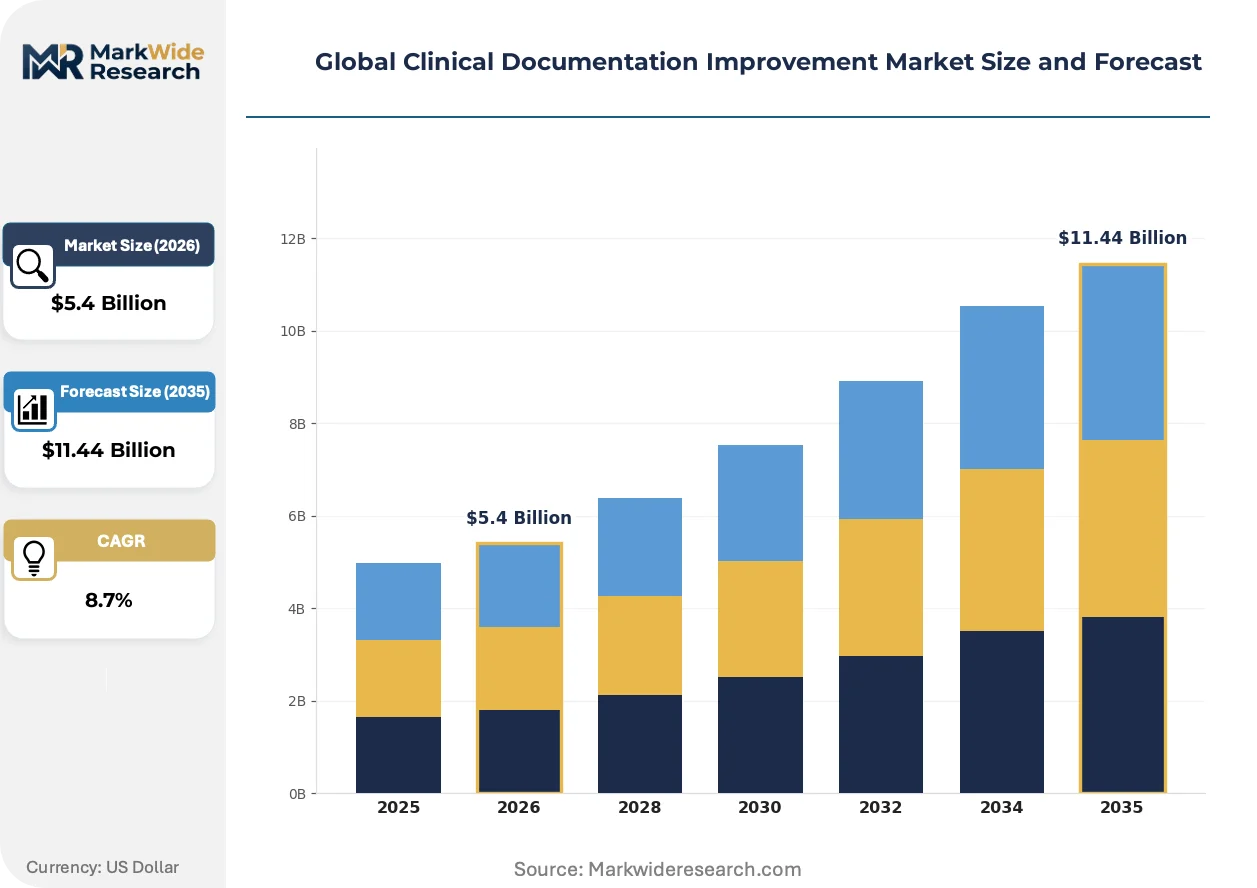
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $11.44 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Consulting Services, Training Programs, Data Analytics Platforms Application: Quality Management, Revenue Cycle Optimization, Regulatory Compliance, Patient Care Enhancement, Risk Adjustment End User Industry: Hospitals, Physician Practices, Health Information Management, Payer Organizations, Ambulatory Care Centers Deployment Mode: On-Premise, Cloud-Based, Hybrid, Hosted |
| Companies Covered | 3M Health Information Systems, Optum, Nuance Communications, Dolbey Systems, nThrive, Streamline Health, ChartWise, Epic Systems, Cerner Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Clinical Documentation Improvement Market Shifts & Advancements
Ambient clinical intelligence is dissolving the boundary between patient encounter and billable documentation, compressing the revenue cycle from weeks to days while elevating coding specificity through machine-generated encounter summaries.
Large language models fine-tuned on medical ontologies are automating physician query generation, converting vague documentation into diagnosis-specific prompts embedded within EHR workflows. Academic medical centers and large integrated delivery networks pilot these tools aggressively. The technology is automating retrospective chart review, collapsing coder review cycles from 72 hours to under four hours.
The EU AI Act's risk classification framework for health applications is mandating conformity assessments for clinical decision support software, elevating documentation burdens for vendors seeking CE marking. German and French health authorities now require algorithmic impact assessments for NLP tools influencing reimbursement coding. CDI vendors with established quality management systems are capturing market access advantages in these jurisdictions.
Hospital procurement committees now demand outcome-based contracting tied to measured coding accuracy improvements and query response rate elevations, displacing traditional software licensing models. Large health systems consolidate vendor relationships around platforms demonstrating measurable revenue cycle impact. This pattern concentrates most visibly in United States markets where Medicare Advantage penetration has sharpened CFO scrutiny of documentation ROI.
Global Clinical Documentation Improvement Market Segmentation
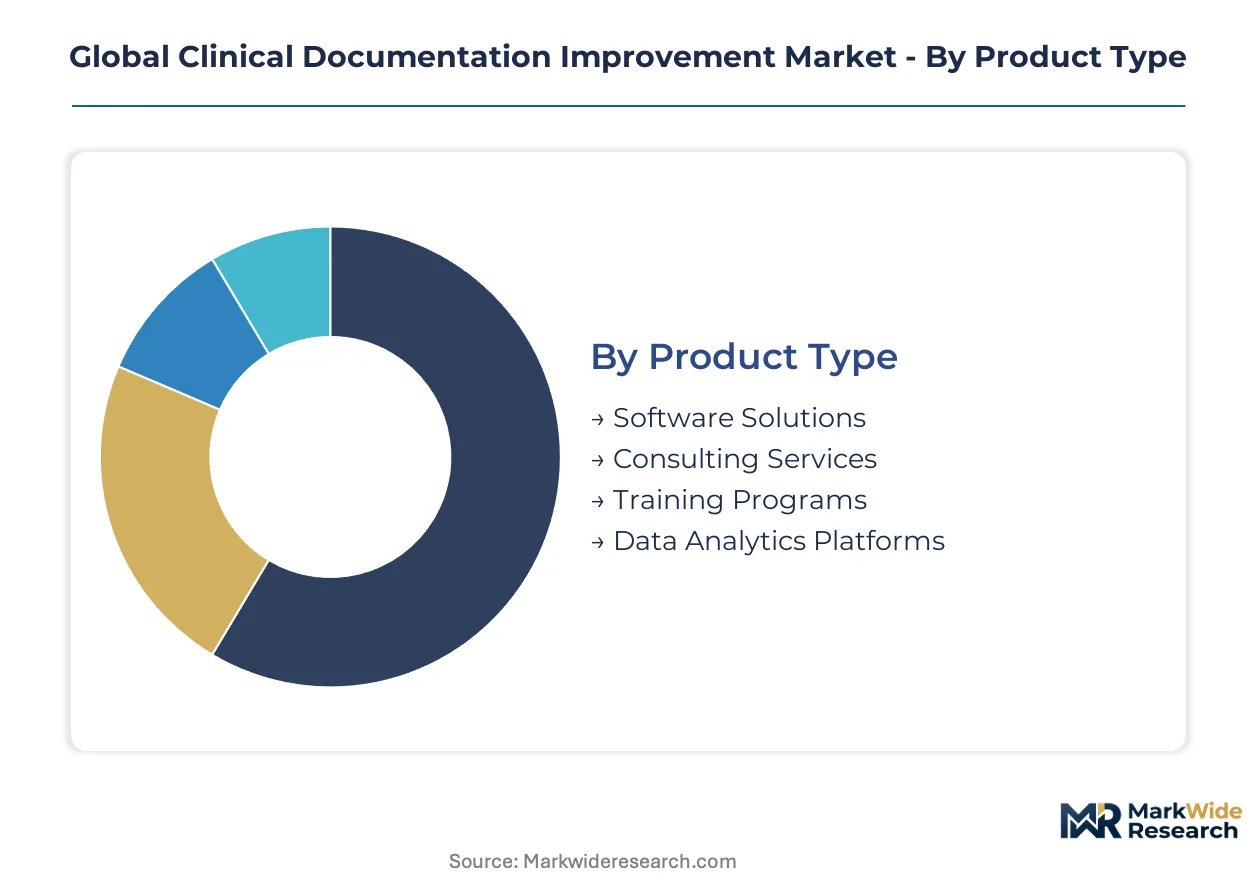
CDI procurement patterns diverge sharply across deployment modes and end-user scale, with capital intensity determining vendor selection criteria. Health systems weighing cloud migration against legacy infrastructure retention face fundamentally different implementation economics and compliance architectures.
Product Type:
Software solutions demand the heaviest upfront investment in NLP engine licensing and EHR integration engineering, while services require lower capital outlay but higher recurring labor costs.
- Software Solutions:NLP-powered query engines and real-time physician nudge systems embed directly into Epic and Cerner workflows. United States health systems concentrate procurement here as CMS quality penalties escalate, prioritizing automated specificity flagging over manual coder review.
- Consulting Services:Clinical documentation specialists embed within hospital quality departments to redesign physician query workflows. German providers under InEK DRG pressure represent concentrated demand, seeking external expertise to recalibrate coding specificity without permanent technology commitments.
- Training Programs:Physician education modules on documentation specificity reduce query response friction.
- Data Analytics Platforms:Retrospective chart mining tools identify revenue leakage from undercoded encounters.
Most installed capacity flows through Software Solutions. Expansion is steepest in Data Analytics Platforms.
Application:
Revenue cycle applications command premium pricing due to measurable ROI linkage, while quality management deployments face longer payback periods despite regulatory pressure.
- Revenue Cycle Optimization:Automated coding specificity tools capture reimbursement uplift from Hierarchical Condition Category documentation. Medicare Advantage penetration in Florida and California health systems drives concentrated adoption as risk-adjusted contracting rewards precision.
- Risk Adjustment:HCC capture automation for payer contracts requires specialized NLP training on chronic condition patterns. United States payer organizations and provider-sponsored health plans represent primary demand concentration.
- Quality Management:Documentation completeness scoring for CMS star ratings and hospital compare metrics.
- Regulatory Compliance:Audit trail generation and HIPAA documentation for OCR investigations.
- Patient Care Enhancement:Clinical decision support integration from improved documentation granularity.
Revenue Cycle Optimization absorbs the largest share of current spending. Risk Adjustment is gaining share fastest as value-based contracts proliferate.
End User Industry:
Hospital procurement committees control the largest budget pools, though ambulatory sites offer faster implementation cycles and lower customization demands.
- Hospitals:Enterprise CDI programs spanning inpatient, emergency, and surgical documentation require multi-module platform deployment. Academic medical centers in Boston and Cleveland anchor technology piloting, with community hospitals following in adoption waves.
- Physician Practices:Ambulatory documentation improvement targets E&M coding specificity and chronic condition capture. United States multi-specialty groups exceeding 50 providers represent the addressable core.
- Health Information Management:Centralized coding departments within integrated delivery networks.
- Payer Organizations:Retrospective chart review for risk adjustment validation and fraud detection.
- Ambulatory Care Centers:Surgical and procedural documentation for ASC reimbursement optimization.
Hospital deployments constitute the dominant installed base. Ambulatory Care Centers are expanding most quickly as outpatient surgical volumes rise.
Deployment Mode:
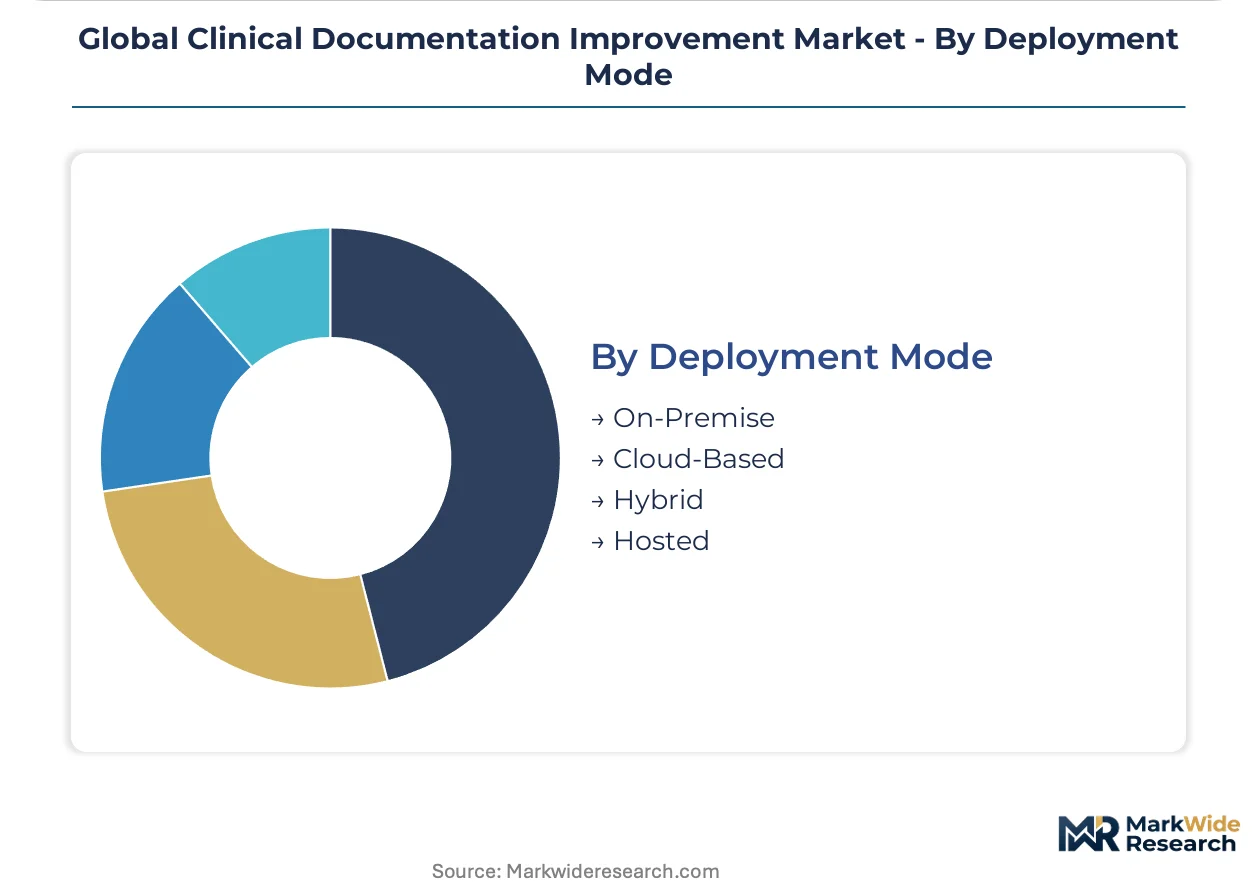
Cloud infrastructure eliminates data center capital expenditure but introduces recurring compute costs and GDPR sovereignty complications for European installations.
- Cloud-Based:SaaS delivery of NLP engines and query platforms via AWS, Azure, or Google Cloud infrastructure. United States health systems prioritize this mode for sub-90-day implementation timelines and reduced IT staffing demands.
- Hybrid:Sensitive patient data remains on-premise while NLP processing leverages cloud compute. German and French hospitals favor this architecture under GDPR and EU AI Act data localization requirements.
- On-Premise:Legacy installations within defense health systems and critical access hospitals with limited connectivity.
- Hosted:Single-tenant cloud deployments managed by vendor or third-party data centers.
Cloud-Based deployments carry the majority of new installations. Hybrid architectures are climbing the fastest as European compliance frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital networks in the United States anchor CDI technology deployment, with academic medical centers in Boston and Cleveland piloting ambient clinical intelligence tools. Germany's Institut für das Entgeltsystem im Krankenhaus recalibrations pressure providers toward precision coding investments. Japan's aging population and universal health coverage reforms concentrate demand for automated documentation in Tokyo and Osaka metropolitan hospitals.
United States
Medicare Advantage penetration and CMS quality reporting penalties drive hospital procurement of NLP-powered query engines. HIPAA privacy mandates and FDA oversight of clinical decision support software shape vendor compliance requirements. Florida and California health systems concentrate risk adjustment technology adoption as value-based contracting expands.
Germany
Diagnosis-Related Group refinements by InEK pressure providers to capture severity of illness data with greater specificity. The EU AI Act's risk classification framework mandates conformity assessments for NLP tools influencing reimbursement coding. University hospitals in Berlin and Munich anchor pilot programs for automated physician query generation.
Japan
Universal health coverage cost containment and aging demographics accelerate investment in documentation efficiency tools. METI guidance on healthcare AI deployment creates regulatory clarity for CDI vendors seeking market access. Tokyo and Osaka metropolitan hospital networks concentrate procurement of EHR-embedded coding automation.
United Kingdom
NHS England's digitization targets and clinical coding backlogs create demand for automated retrospective chart review. GDPR compliance requirements and MHRA oversight of software-as-medical-device classifications shape vendor entry strategies. London and Manchester academic medical centers pilot large language model applications for encounter summarization.
India
Medical tourism quality accreditation and NABH standards drive private hospital investment in documentation completeness tools. CDSCO regulatory pathways for clinical decision support software remain under development, creating uncertainty for foreign vendors. Apollo and Max Healthcare networks in Delhi-NCR and Chennai concentrate early adoption of cloud-based CDI platforms.
Global Clinical Documentation Improvement Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue ambient clinical intelligence and real-time physician nudge systems. The vendor base stratifies across three tiers: enterprise platform providers anchoring multi-hospital contracts, specialized NLP engine developers licensing technology, and consulting services firms embedding clinical documentation specialists within provider quality departments. Consolidation pressures intensify as procurement committees demand outcome-based contracting tied to measurable coding accuracy improvements. Two dominant competitive moves reshape positioning: backward integration into payer data assets to sharpen risk adjustment tools, and strategic partnerships with hyperscale cloud providers to secure NLP compute capacity.
Within the enterprise platform tier, 3M Health Information Systems and Nuance Communications exemplify divergent strategic positioning. 3M leverages natural language processing depth to anchor contracts with large integrated delivery networks across the United States. Nuance sustains technology leadership in ambient clinical intelligence that auto-generates documentation from patient encounters. Optum occupies a distinct position through upstream control over payer data assets that sharpen risk adjustment accuracy for provider clients. These three entities collectively represent the competitive archetypes—technology depth, ambient automation, and vertical data integration—through which remaining vendors must differentiate.
| Leading Market Players |
|---|
| 3M Health Information Systems |
| Optum |
| Nuance Communications |
| Dolbey Systems |
| nThrive |
| Streamline Health |
| ChartWise |
| Epic Systems |
| Cerner Corporation |
| Others |
Supply & Pricing Matrix
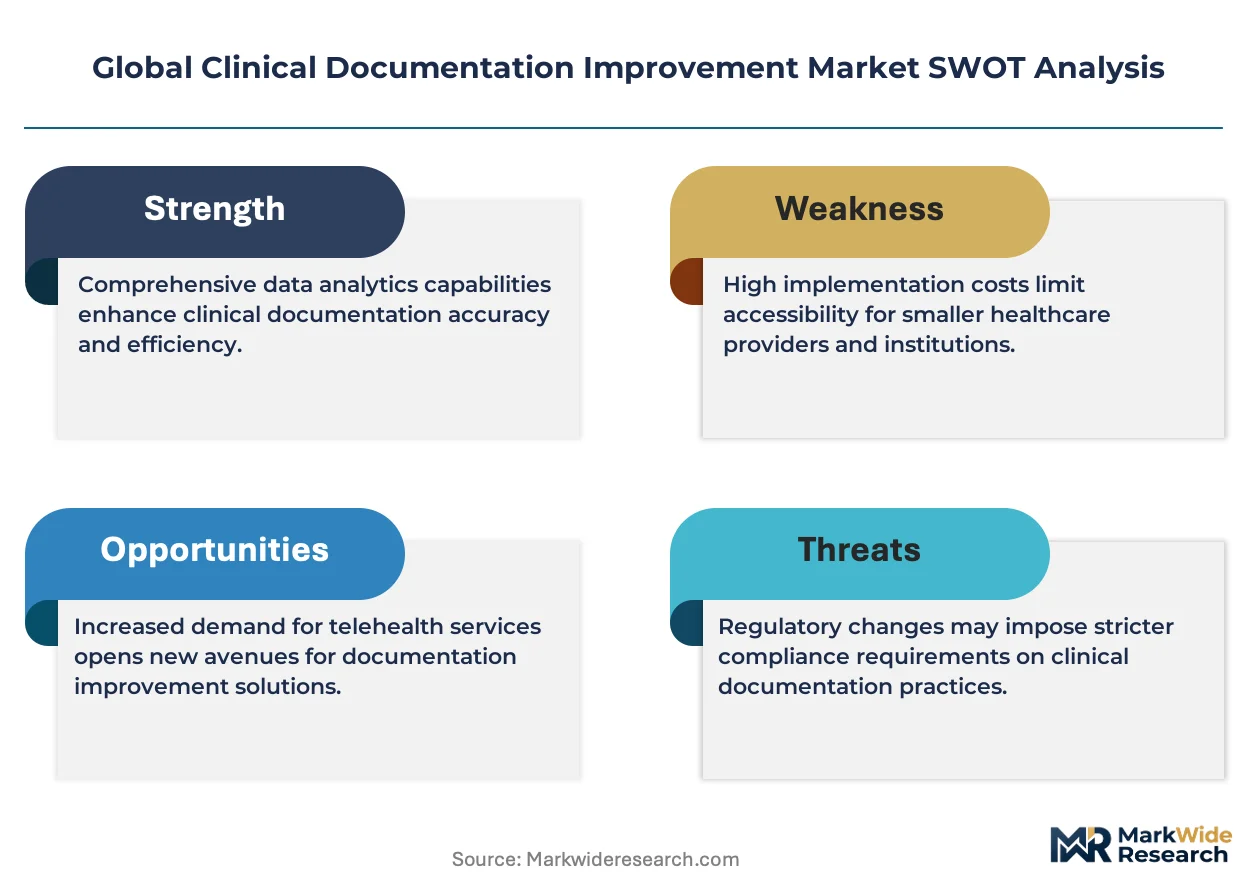
EU AI Act conformity assessment mandates gate qualified supply access for NLP engine vendors and anchor premium-tier pricing for CE-marked clinical decision support tools. Hospitals in Germany and France now require algorithmic impact documentation before procurement, compressing margins for non-compliant suppliers while elevating pricing power for vendors with established quality management systems.
Pricing Analysis
Input-cost pass-through from hyperscale cloud compute fees shapes SaaS-tiered subscription models across the CDI software stack. Price differentiation rests on NLP training data quality and FDA 510(k) clearance tier, with ambient clinical intelligence platforms commanding premiums over retrospective coding tools. Pricing pressure stems from procurement committee demands for outcome-based contracting tied to measured revenue cycle impact. Community hospital systems exhibit highest price sensitivity, while academic medical centers prioritize integration depth over licensing cost.
Supply Chain Analysis
Single-source vulnerability sits with United States-based hyperscale cloud providers for GPU-intensive NLP processing capacity. Software development concentrates in the United States, Germany, and India, with clinical ontology curation anchored in Boston and Berlin academic medical centers. Raw material dependencies span annotated medical corpora, FHIR-compliant EHR middleware, and certified clinical informaticist labor pools. Supply chain risk centers on GDPR data localization requirements that fragment cloud infrastructure deployment across European jurisdictions. Distribution runs through direct enterprise sales teams and EHR vendor channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in clinical documentation improvement hinges on ambient intelligence automation compressing labor-dependent service revenue into high-margin software tiers. Cloud infrastructure cost optimization and physician workflow integration depth separate profitable scale from commoditized query-tool vendors.
For Market Incumbents: Cement platform stickiness through deep Epic and Cerner workflow embedding that raises switching costs for hospital clients. Defend against ambient clinical intelligence disruptors by acquiring specialized NLP training data assets and securing payer data partnerships for risk adjustment accuracy. Prioritize EU AI Act pre-certification to capture German and French procurement committees ahead of compliance deadlines. For New Entrants and Emerging Players: Direct-to-physician mobile channels offer lower customer acquisition cost than enterprise sales cycles for outpatient CDI tools. Target ambulatory surgical centers in Florida and California as the most penetrable segment, with Medicare Advantage penetration creating immediate ROI visibility. Pursue white-label partnerships with existing EHR vendors rather than standalone platform competition. For Investors and Strategic Acquirers: Roll-up economics work for specialized NLP engine developers because hospital procurement committees now consolidate vendor relationships around integrated platforms. Five-to-ten year viability favors vendors with captive clinical informaticist training pipelines and established payer data access. Watch CMS quality reporting penalty escalation rates as the signal for CDI investment urgency inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep Epic and Cerner workflow embedding raises hospital switching costs and contract renewal rates. |
| Strategic Partnership | Payer data alliances with UnitedHealth or Kaiser sharpen risk adjustment accuracy for provider clients. |
| Regulatory Pre-Certification | EU AI Act conformity assessments create first-mover access to German and French procurement committees. |
| Acquisition of Specialist Firm | Clinical informaticist training programs address talent scarcity constraining program scaling velocity. |
| Geographic Expansion | Tokyo and Osaka metropolitan hospitals offer concentrated demand under METI healthcare AI guidance. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital CIOs, clinical documentation specialists, EHR integration engineers, and payer risk adjustment officers with secondary validation against CMS Medicare data, hospital procurement databases, GPO contracts, FDA 510(k) filings, and EMA guidance documents. Bottom-up sizing of NLP engine deployments and top-down reconciliation against health system IT spending budgets provided cross-verification.
Segment-weighting across deployment modes, end-user scale tiers, and application types drove analytical framework construction across the projection horizon. Software solutions, consulting services, training programs, and data analytics platforms each carried distinct growth assumptions based on automation feasibility and labor substitution economics. CAGRs derived from provider IT budget growth rates, Medicare Advantage penetration curves, and regulatory penalty escalation patterns.
The model assumes a particular technology adoption path; alternative pathways for large language model integration would alter the outlook if physician workflow resistance proves more persistent than baseline assumptions. Forecasts reflect embedded assumptions about HIPAA enforcement continuity, EU AI Act implementation timelines, and CMS quality program stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Ambulatory Software Market
Medical Information Systems
Global Pharmacy Information System Market
Medical Information Systems
Global Medical Transcription Software Market
Medical Information Systems
Critical Care Information Systems Market
Medical Information Systems
Anesthesia Information Management Systems Market
Medical Information Systems
Medical Coding Market
Medical Information Systems
Medical Saas System Market
Medical Information Systems
Global Medical Writing Market
Medical Information Systems
Ophthalmology EMR Software Market
Medical Information Systems
Global Oncology Information System Market
Medical Information Systems
Global Clinical EHR Systems Market
Medical Information Systems
Electronic Medical Record Market
Medical Information Systems
Global Medical Scheduling Software Market
Medical Information Systems
Medical Simulation Software Market
Medical Information Systems
Medical Information Market
Medical Information Systems
Medical Software Market