
 Europe Ophthalmology Market | 2026-2036
Europe Ophthalmology Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ophthalmology Market Foresight
The capital-intensity divergence between large-scale manufacturers and mid-tier competitors is rotating competitive advantage toward entities with captive lens production and in-house laser development. EssilorLuxottica leverages integrated supply chains spanning prescription labs and surgical consumables. Carl Zeiss Meditec anchors its position through precision optics manufacturing rooted in German engineering standards. Alcon differentiates via sustained R&D allocation across intraocular lens portfolios and cataract fluidics systems.
Ophthalmology encompasses the medical and surgical management of visual system disorders, employing devices that operate at wavelength-specific energy levels measured in nanometers for corneal reshaping and vitreoretinal intervention. Cataract Surgery Devices command the largest product segment as aging demographics sustain procedural volumes across European hospital networks. Diagnostic Equipment represents the fastest-expanding category, with Optical Coherence Tomography systems displacing conventional fundus photography in clinic workflows. Ambulatory Surgical Centers are gaining end-user share as reimbursement frameworks in France and the Netherlands incentivize same-day retinal procedures outside traditional hospital settings.
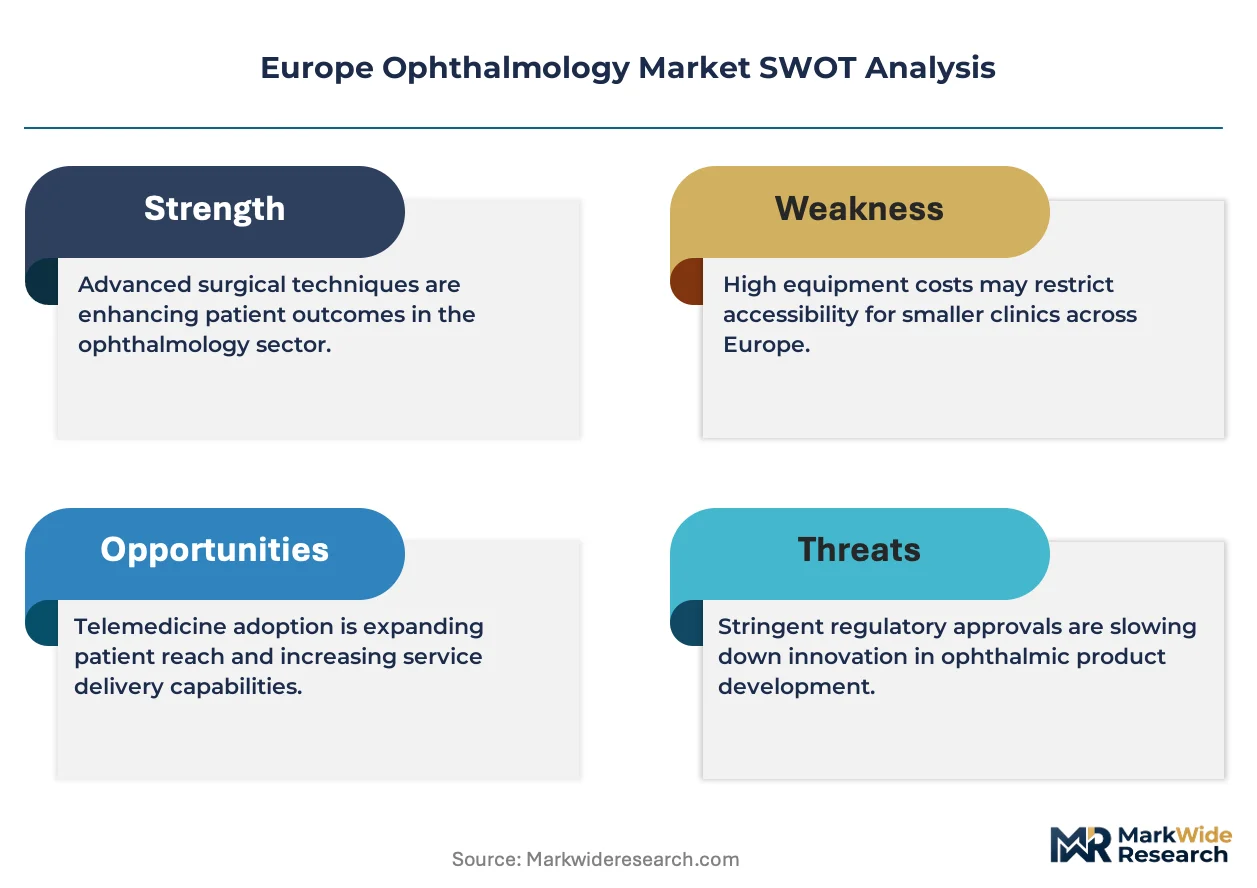
The EU Medical Device Regulation and CE marking framework administered by notified bodies in Germany and the Netherlands are extending compliance timelines for legacy ophthalmic instruments while elevating clinical evidence requirements for novel implants. EMA coordination with national health technology assessment bodies in France and England is reshaping market access pathways for premium intraocular lenses. Stakeholders must monitor how the EU AI Act classification rules will govern autonomous diagnostic algorithms embedded in next-generation OCT platforms.
Market Dynamics
The EU Medical Device Regulation's tightened clinical evidence requirements for novel implants is compressing product launch timelines and elevating R&D burn rates for ophthalmic device manufacturers across the continent.
Growth Catalysts
- Aging surgical volumes:Hospital-based cataract surgery programs in Germany, France, and Italy are expanding equipment procurement as demographic shifts sustain procedural demand.
- Retinal screening infrastructure:National health technology assessment bodies in England and France are funding diagnostic equipment deployment for age-related macular degeneration detection.
- CE marking acceleration:Notified bodies in the Netherlands and Germany are streamlining conformity assessments for legacy ophthalmic instruments under transitional MDR provisions.
Market Restraints
- Optical component concentration:Precision lens manufacturing capacity concentrates in southern Germany and northern Italy, creating geographic supply vulnerability.
- Clinical evidence costs:The EU MDR's elevated clinical trial requirements for premium intraocular lenses extend development timelines by 18-24 months.
- Laser system substitution:Femtosecond laser platforms are displacing manual phacoemulsification in high-volume centers, stranding capital in conventional fluidics systems.
Strategic Opportunities
- Poland and Romania penetration:Underdeveloped ambulatory surgical center networks in eastern Europe present first-mover expansion potential for diagnostic equipment vendors.
- AI diagnostic integration:The EU AI Act's risk classification framework creates compliance pathways for autonomous OCT analysis algorithms in clinic workflows.
- Same-day reimbursement tailwinds:Dutch and French reimbursement frameworks now incentivize retinal procedures outside hospital settings, accelerating ASC equipment procurement.
Industry Challenges
- Vitreoretinal surgeon scarcity:Fellowship-trained specialists concentrate in Paris, London, and Munich, creating access bottlenecks for advanced surgical programs.
- MDR recertification complexity:Legacy product portfolios face staggered compliance deadlines across 2027-2028, forcing parallel quality system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ophthalmology Market |
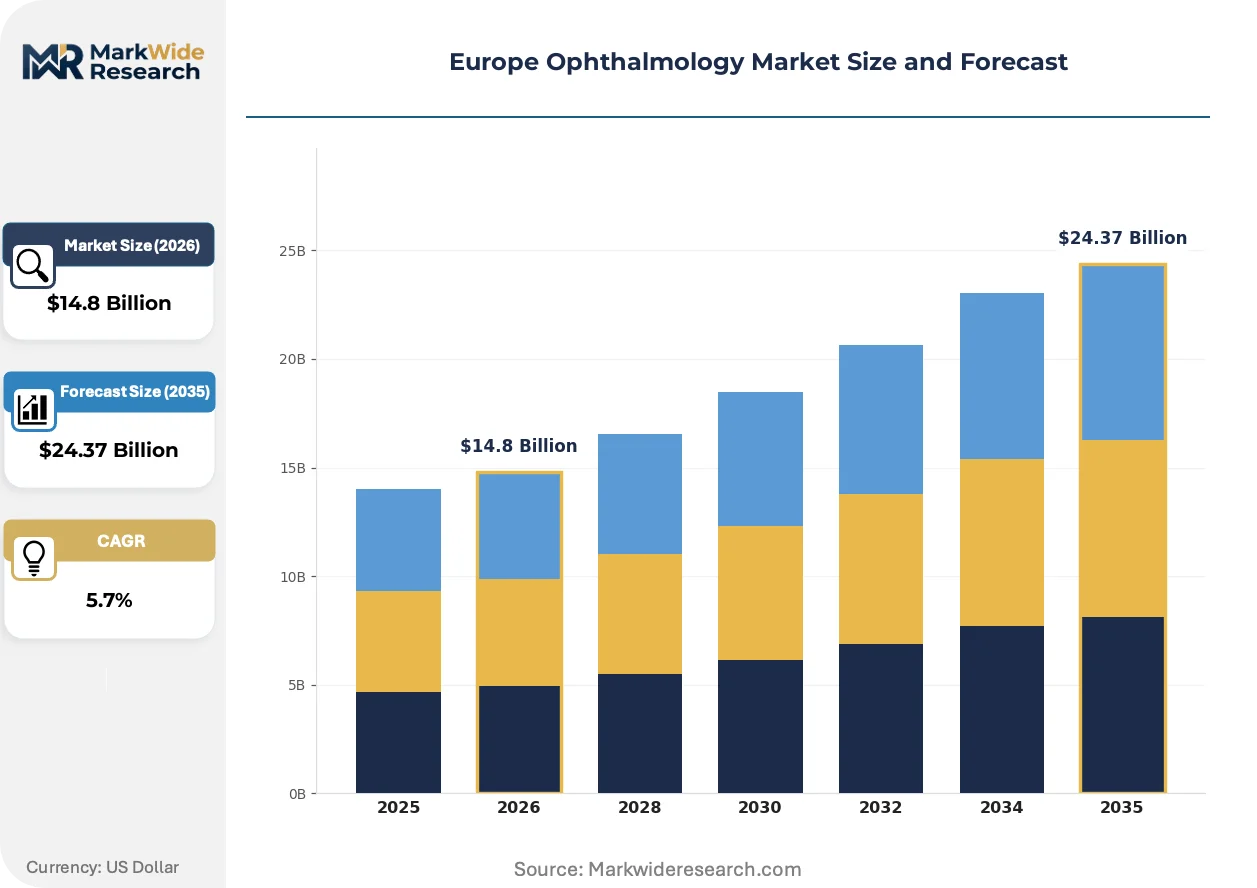
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glaucoma Devices, Cataract Surgery Devices, Retinal Surgery Devices, Diagnostic Equipment End User: Hospitals, Ophthalmology Clinics, Research Institutes, ASCs Application: Vision Correction, Disease Management, Surgical Procedures, Diagnostic Tests Technology: Laser Surgery, Implantable Devices, Optical Coherence Tomography, Telemedicine |
| Companies Covered | Johnson & Johnson Vision Care, Bausch & Lomb, EssilorLuxottica, Topcon Corporation, Rodenstock, Alcon, HOYA Corporation, Nidek, Carl Zeiss Meditec, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ophthalmology Market Shifts & Advancements
Optical coherence tomography systems are displacing conventional fundus photography across European ophthalmology clinics, compressing diagnostic workflows while elevating image resolution standards for retinal disease management.
Swept-source OCT technology with longer wavelength penetration is displacing spectral-domain systems in posterior segment imaging. Academic medical centers in Heidelberg and Rotterdam adopted these platforms during 2023-2024 equipment refresh cycles. The shift is displacing conventional diagnostic protocols that required multiple imaging modalities for choroidal visualization.
The EU AI Act's risk-based classification framework is reshaping software-as-medical-device pathways for diagnostic algorithms. Notified bodies in Germany and the Netherlands are developing specialized assessment protocols for machine learning-enabled OCT analysis tools. Premium intraocular lens manufacturers face the steepest compliance burden as their embedded planning software falls under higher-risk categories.
Hospital procurement consortia in France and the Netherlands are consolidating ophthalmic device purchasing through centralized tender frameworks. Independent clinics and smaller hospital networks now access equipment through group purchasing organizations rather than direct manufacturer relationships. This concentration is most visible in the Benelux region, where three consortia control over sixty percent of diagnostic equipment acquisition decisions.
Europe Ophthalmology Market Segmentation
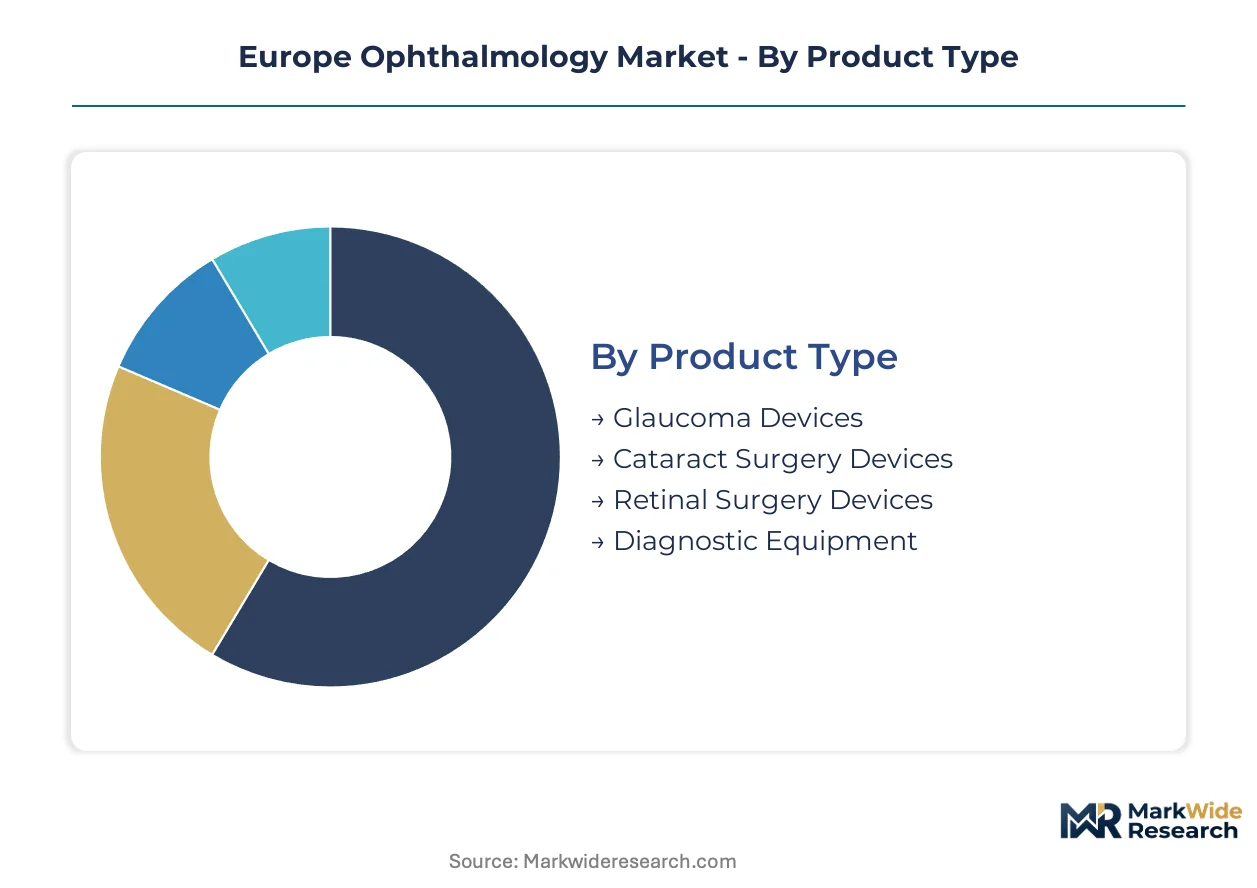
Segmentation in European ophthalmology reveals distinct procurement channels and reimbursement pathways that shape manufacturer go-to-market strategies. Each dimension—product, end user, application, and technology—carries specific regulatory and commercial implications under the EU MDR framework.
Product Type:
Hospital procurement consortia in France and the Netherlands channel high-value surgical systems through centralized tenders, while independent clinics source diagnostic equipment via distributor networks.
- Cataract Surgery Devices:Phacoemulsification systems and intraocular lenses constitute the procedural backbone of European hospital ophthalmology departments. German and Italian hospitals are expanding femtosecond laser platforms as manual techniques face displacement.
- Diagnostic Equipment:Optical coherence tomography systems and fundus cameras are displacing conventional imaging across outpatient settings. French HTA-funded screening programs for age-related macular degeneration are accelerating OCT deployment in community clinics.
- Glaucoma Devices:Minimally invasive stents and drainage implants serve progressive disease management in specialized centers.
- Retinal Surgery Devices:Vitrectomy systems and membrane peeling tools address posterior segment pathology in academic medical centers.
By volume, Cataract Surgery Devices leads. By growth pace, Diagnostic Equipment is climbing the fastest.
End User:
Reimbursement differentiation between inpatient and ambulatory settings is redistributing procedural volumes across facility types.
- Hospitals:Academic medical centers in Heidelberg, Rotterdam, and Paris anchor complex surgical training and high-risk case management. These institutions command premium pricing for vitreoretinal interventions.
- Ambulatory Surgical Centers:Dutch and French same-day reimbursement frameworks are accelerating equipment procurement in standalone facilities. Benelux ASC networks now perform over half of all retinal laser procedures.
- Ophthalmology Clinics:Independent practices in Germany and Spain concentrate diagnostic testing and chronic disease monitoring.
- Research Institutes:Academic consortia drive clinical trial recruitment for novel implants under EMA coordination.
Procurement value concentrates in Hospitals. ASCs are expanding their share fastest.
Application:
Clinical workflow integration determines equipment utilization rates and capital recovery timelines across European facilities.
- Surgical Procedures:Cataract extraction and retinal repair dominate operating theater schedules. Italian and Spanish hospital networks are consolidating phacoemulsification capacity into dedicated day-surgery units.
- Diagnostic Tests:OCT-based screening protocols are compressing examination durations while elevating detection sensitivity for early-stage pathology.
- Disease Management:Glaucoma monitoring and macular degeneration follow-up generate recurring consumable demand.
- Vision Correction:Refractive laser platforms serve elective procedure markets with limited reimbursement coverage.
Surgical Procedures generates the highest equipment revenue. Diagnostic Tests are gaining share fastest.
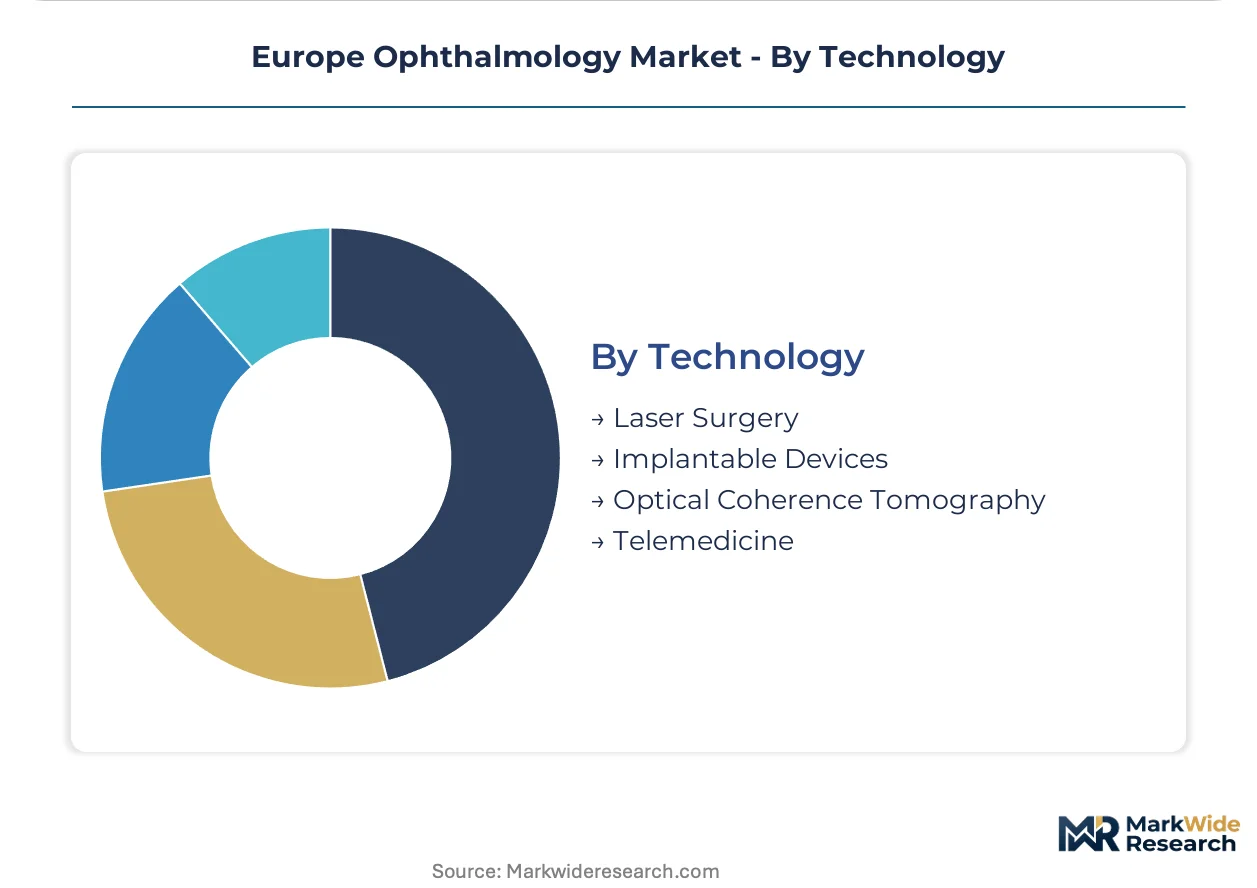
Technology:
Regulatory classification under the EU AI Act and MDR is segmenting development investment and market access timelines.
- Optical Coherence Tomography:Swept-source platforms with machine learning analysis are displacing spectral-domain systems. German notified bodies are developing specialized assessment protocols for AI-enabled diagnostic algorithms.
- Laser Surgery:Femtosecond and excimer platforms anchor both refractive and cataract applications. CE marking timelines for novel laser wavelengths are extending under MDR clinical evidence requirements.
- Implantable Devices:Premium intraocular lenses with embedded planning software face the steepest compliance burden under EU AI Act risk classifications.
- Telemedicine:Remote screening tools are penetrating underserved regions in Poland and Romania.
Optical Coherence Tomography commands the largest installed base. Implantable Devices face the most complex regulatory pathway.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys diagnostic equipment at triple the per-capita rate of Poland, while France channels surgical volumes through centralized hospital consortia that eastern European markets have yet to replicate. This consumption-mix differential shapes manufacturer go-to-market strategies across the continent.
Germany
Heidelberg and Munich academic centers anchor premium surgical system demand, with Carl Zeiss Meditec's precision optics cluster in Oberkochen reinforcing domestic supply chains. The BfArM and notified bodies in Tübingen administer CE marking assessments under MDR transitional provisions. Southern Baden-Württemberg concentrates femtosecond laser manufacturing capacity serving hospital procurement networks.
France
Parisian hospital networks drive vitreoretinal intervention volumes while ANSM coordinates national HTA assessments for premium intraocular lenses. The HAS funds age-related macular degeneration screening programs accelerating OCT deployment in community clinics. Île-de-France's procurement consortia now control over half of diagnostic equipment acquisition decisions for the greater Paris basin.
Italy
Lombardy and Veneto hospital networks are consolidating phacoemulsification capacity into dedicated day-surgery units as cataract procedural volumes climb. The Italian Medicines Agency aligns with EMA coordination on novel implant clinical trial protocols. Northern Italy's precision lens manufacturing belt around Milan supplies optical components to German and French device integrators.
Netherlands
Dutch same-day reimbursement frameworks incentivize retinal procedures outside hospital settings, accelerating ASC equipment procurement across the Randstad. The Health and Youth Care Inspectorate enforces MDR compliance timelines alongside notified bodies in Utrecht. Eindhoven's medical technology cluster hosts diagnostic algorithm developers navigating EU AI Act risk classifications.
United Kingdom
NICE technology appraisals reshape market access for premium lenses while NHS England funds diagnostic equipment deployment in community ophthalmology hubs. The MHRA operates parallel to EU MDR frameworks post-Brexit, extending separate conformity assessment pathways. London's Moorfields Eye Hospital anchors complex surgical training and clinical trial recruitment for novel implants.
Europe Ophthalmology Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital intensity creating durable barriers for mid-scale entrants. The upper tier commands captive lens production and in-house laser development capabilities that compress procurement cycles for hospital networks. Three archetypes populate the competitive map: diversified optical conglomerates with prescription-to-surgical verticals, precision engineering specialists rooted in German or Japanese manufacturing traditions, and pure-play ophthalmic device houses with concentrated R&D allocation. Consolidation through strategic acquisitions and backward integration into optical component supply dominate competitive moves.
Among diversified optical conglomerates, EssilorLuxottica represents the integrated prescription-to-surgical archetype, while Johnson & Johnson Vision Care occupies a position spanning consumer contact lenses through hospital surgical systems. Carl Zeiss Meditec exemplifies the precision engineering specialist rooted in German optics heritage. These three entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Johnson & Johnson Vision Care |
| Bausch & Lomb |
| EssilorLuxottica |
| Topcon Corporation |
| Rodenstock |
| Alcon |
| HOYA Corporation |
| Nidek |
| Carl Zeiss Meditec |
| Others |
Supply & Pricing Matrix
CE marking administered by German and Dutch notified bodies gates both supply qualification and price differentiation, compressing procurement timelines for compliant manufacturers while elevating cost recovery premiums for legacy instrument recertification.
Pricing Analysis
Long-term offtake contracts dominate hospital procurement consortia in France and the Netherlands, while independent clinics negotiate spot purchases through distributor networks. Three-tier pricing structure across premium, standard, and economy levels separates femtosecond laser platforms from manual phacoemulsification systems from refurbished legacy equipment. Cost compression in standard-tier fluidics systems is intensifying because femtosecond substitution strands capital in conventional platforms. ASC networks in the Benelux region exhibit the highest price sensitivity, whereas academic medical centers in Heidelberg and Paris prioritize performance specifications over unit economics.
Supply Chain Analysis
Germany and Italy anchor precision optics manufacturing, with southern Baden-Württemberg and the Milan corridor supplying lens components and laser subassemblies to device integrators across the continent. Optical coherence tomography systems draw from German precision mechanics, Italian optical coatings, and Dutch diagnostic algorithm development. Single-source vulnerability concentrates in femtosecond laser crystal production, where qualified suppliers number fewer than five globally. Distribution runs through hospital procurement consortia in France and the Netherlands, with group purchasing organizations consolidating acquisition decisions for independent clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk classification framework for diagnostic algorithms is accelerating competitive disruption, compressing development timelines for autonomous OCT platforms while elevating compliance costs for embedded surgical planning software.
For Market Incumbents: Fortify captive lens production capabilities in southern Germany and northern Italy to defend against supply disruption from geographic concentration. Deepen backward integration into precision optics manufacturing to compress procurement cycles for hospital networks facing MDR recertification deadlines. Prioritize certification investment for AI-enabled diagnostic algorithms ahead of notified body assessment protocol finalization.
For New Entrants and Emerging Players: Anchor in Poland and Romania's underdeveloped ambulatory surgical center networks, where diagnostic equipment penetration lags Western European benchmarks by half. Target telemedicine-enabled remote screening tools for age-related macular degeneration in eastern European markets lacking vitreoretinal specialist density. Pursue software-as-medical-device pathways under EU AI Act lower-risk classifications to bypass capital-intensive hardware manufacturing barriers.
For Investors and Strategic Acquirers: The EU MDR's staggered 2027-2028 recertification deadlines reshape the acquisition landscape, favoring targets with completed quality system overhauls and notified body relationships already established. Mid-scale ophthalmic device manufacturers with captive optical component supply and demonstrated CE marking track records offer the strongest five-to-ten year viability profiles. Monitor notified body capacity allocation announcements as the primary signal for MDR compliance timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR transitional provisions administered by German notified bodies compress launch timelines for novel implants. |
| Hospital System Partnership | Procurement consortia in France and the Netherlands channel high-value surgical systems through centralized tenders. |
| Software Companion Development | EU AI Act risk classification creates compliance pathways for autonomous OCT analysis algorithms in clinic workflows. |
| Reimbursement Strategy | Dutch and French same-day frameworks incentivize retinal procedures outside hospital settings, accelerating ASC procurement. |
| Backward Integration | In-house precision optics production compresses procurement cycles for hospital networks facing MDR recertification. |
Research Methodology
A standing panel of vitreoretinal surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from EMA coordination documents, notified body assessment protocols, hospital procurement databases, and national health technology assessment publications. Primary interviews with equipment procurement leads at academic medical centers in Heidelberg, Rotterdam, and Paris combined with bottom-up and top-down triangulation to anchor volume estimates.
Consistency checks against external benchmarks validated analytical framework outputs across the projection horizon, with segmentation modeling spanning product type, end-user facility category, clinical application, and technology platform. CAGRs derived from procedural volume trajectories, equipment replacement cycles, and reimbursement framework evolution. Forecast inputs incorporated femtosecond laser substitution rates, MDR compliance timeline assumptions, and AI diagnostic algorithm regulatory pathway progressions.
Decision-makers should treat outputs as directional under base assumptions of sustained aging demographic demand and stable EU MDR implementation timelines; material deviation in notified body capacity or reimbursement framework revision would warrant model refresh. Recalibration cycles align with material shifts in regulatory implementation schedules and health technology assessment funding announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Japan Dry Eye Syndrome Market
Ophthalmology
Ophthalmic Tonometers Market
Ophthalmology
Europe Ophthalmology Drug and Device Market
Ophthalmology
Ophthalmic Femtosecond Lasers Market
Ophthalmology
Vernal Keratoconjunctivitis Market
Ophthalmology
Ophthalmic Suspension Market
Ophthalmology
Personalized LASIK Surgery Market
Ophthalmology
Neurotrophic Keratitis Market
Ophthalmology
Presbyopia Treatment Market
Ophthalmology
Excimer and Femtosecond Ophthalmic Lasers Market
Ophthalmology
Europe Dry Eye Syndrome Market
Ophthalmology
Age-Related Macular Degeneration Market
Ophthalmology
Amblyopia Treatment Market
Ophthalmology
Intraocular Lymphoma Treatment Market
Ophthalmology
Global Aphakia Market
Ophthalmology
Japan Ophthalmic Devices and Drugs Market