
 US Medical Coding Market | 2026-2036
US Medical Coding Market Size, Share, and Industry Trends Forecast 2026-2036
US Medical Coding Market Intelligence
Outpatient facilities is redrawing procurement patterns across the US Medical Coding Market as hospital systems decentralize surgical volumes. Optum leverages its payer-provider integration to bundle coding with revenue cycle management. 3M Health Information Systems anchors institutional sales through its encoder software installed base. Omega Healthcare Management Services competes on labor arbitrage with offshore delivery centers.
Medical coding assigns standardized alphanumeric identifiers to diagnoses, procedures, equipment, and services using classification systems such as ICD-10-CM with 70,000+ codes and CPT with time-based relative value units for physician reimbursement. The primary commercial purpose is ensuring accurate claims submission, compliant billing, and proper reimbursement from Medicare, Medicaid, and commercial payers. ICD classification systems occupy the largest product type segment due to mandatory diagnosis reporting for all patient encounters, while cloud-based deployment models represent the fastest-growing structural category as HIPAA-compliant infrastructure migrates away from capital-intensive on-premises servers.
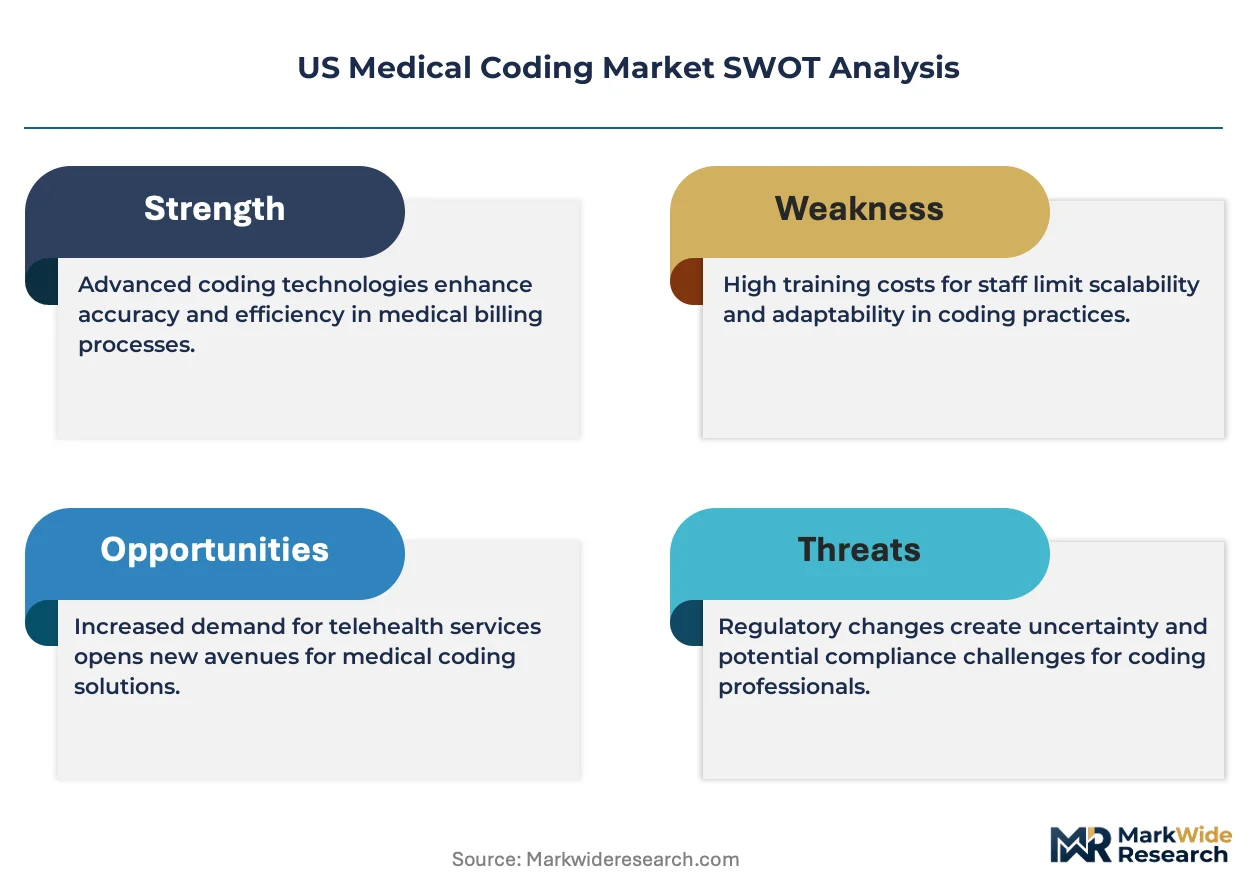
FDA oversight of clinical decision support software intersects with CMS reimbursement policies and HIPAA privacy mandates to create a compliance architecture that shapes vendor product roadmaps and buyer procurement criteria. The Office of the National Coordinator for Health IT establishes interoperability standards that determine how coding data flows between electronic health record systems and clearinghouses. Stakeholders must monitor whether CMS accelerates value-based payment models that tie coding accuracy directly to quality metrics and financial penalties.
Market Dynamics
The transition from ICD-10 to ICD-11 classification standards is compressing vendor upgrade cycles while CMS reimbursement rule tightening forces infrastructure refreshes across hospital systems and ambulatory networks.
Growth Catalysts
- CMS reimbursement tightening:Physician practices accelerate coding outsourcing to avoid claim denials and payment delays under stricter documentation requirements.
- Cloud migration:HIPAA-compliant cloud infrastructure is supplanting capital-intensive on-premises servers across Texas and Florida ambulatory networks.
- ICD-11 implementation:The expanded code set with enhanced granularity drives encoder software upgrades and specialized training demand.
Market Restraints
- Skilled coder shortage:AHIMA-certified professionals command premium wages, inflating labor costs for in-house operations.
- Offshore delivery risks:Data localization requirements under HIPAA create friction for Philippines and India-based coding centers.
- Legacy system debt:Decades-old EHR integrations resist API-based interoperability without expensive middleware.
Strategic Opportunities
- Value-based payment acceleration:CMS quality metric linkages create demand for coding accuracy tied to HCC risk adjustment.
- AI-assisted coding tools:Natural language processing convergence with clinical documentation improvement platforms opens automation white space.
- Rural health clinic penetration:Federally qualified health centers in Mississippi and Alabama remain underserved by specialized vendors.
Industry Challenges
- ICD-11 transition complexity:Dual coding periods and staff retraining compress implementation timelines for health systems.
- Interoperability fragmentation:ONC certification gaps between EHR vendors delay seamless coding data flows to clearinghouses.
- Cybersecurity compliance burden:HIPAA breach notification rules and state privacy laws multiply audit requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Medical Coding Market |
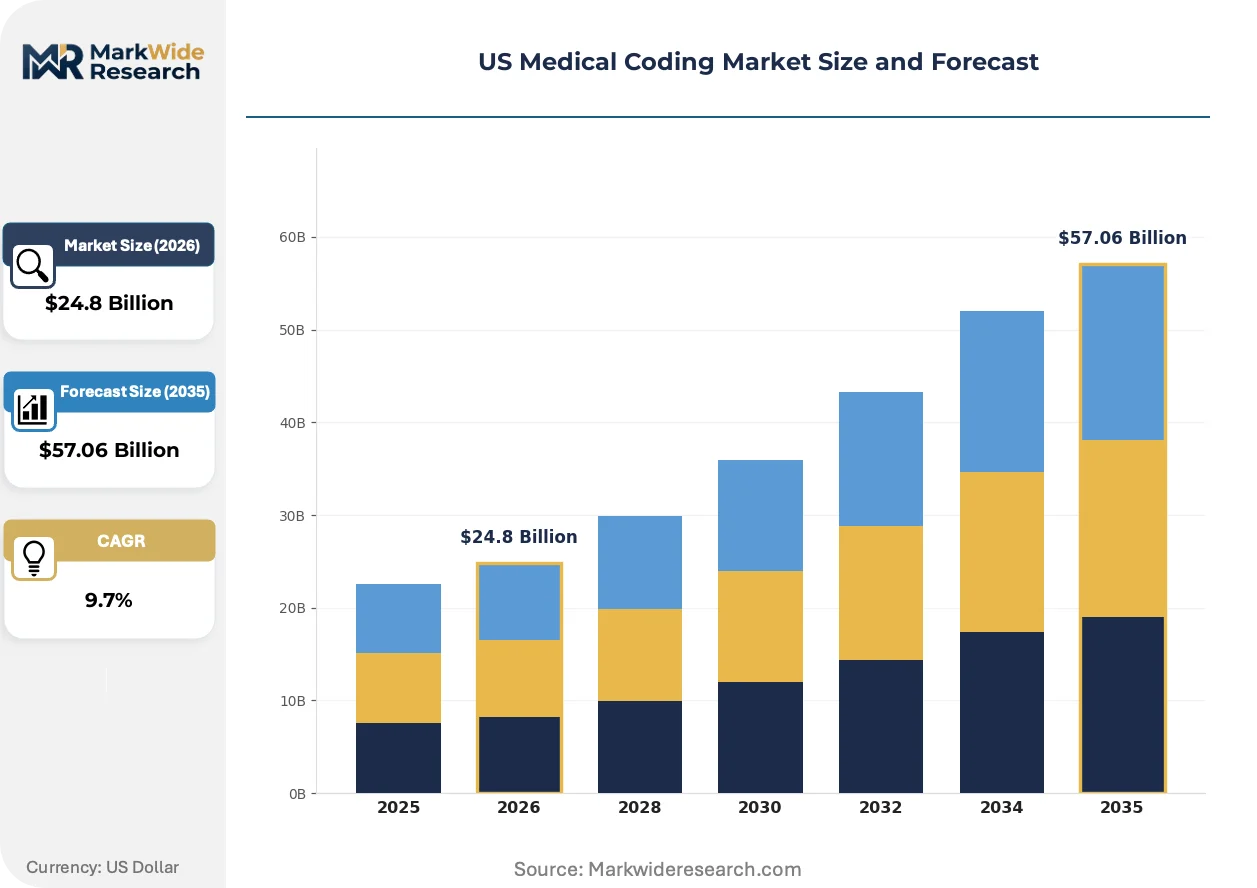
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $57.06 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ICD, CPT, HCPCS, NDC End User: Hospitals, Physician Practices, Outpatient Facilities, Home Health Agencies Deployment Model: On-premises, Cloud-based, Web-based, Hybrid Service Type: Consulting, Auditing, Training, Software Development |
| Companies Covered | Oracle, Maxim Healthcare Services, Aviacode Inc., Verisk Analytics, Inc., Parexel International Corporation, Optum, Dolbey, Omega Healthcare Management Services, 3M Health Information Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Medical Coding Market Strategic Shifts & Innovations
Automation and regulatory convergence are restructuring how coding accuracy gets delivered, priced, and integrated into revenue cycle operations across US healthcare delivery organizations.
Computer-assisted coding platforms leveraging natural language processing are supplanting manual abstraction in emergency department documentation. Large health systems in California and New York deploy these tools to reduce coder backlog and capture missed charges. The technology compresses revenue cycle timelines while shifting human roles toward exception handling and clinical validation.
CMS value-based payment models now tie coding specificity directly to HCC risk scores and shared savings calculations. Hospital systems respond by embedding clinical documentation improvement specialists within service lines. Medicare Advantage penetration in Florida and Arizona intensifies this pressure as plans audit provider submissions for hierarchical condition category capture.
Ambulatory surgery centers now demand bundled coding and billing services rather than standalone encoder licenses. Vendor pricing models pivot toward per-claim or percentage-of-collections structures. This preference concentrates in Texas and Colorado markets where private equity-backed ASC rollups centralize procurement decisions.
US Medical Coding Market Segmentation
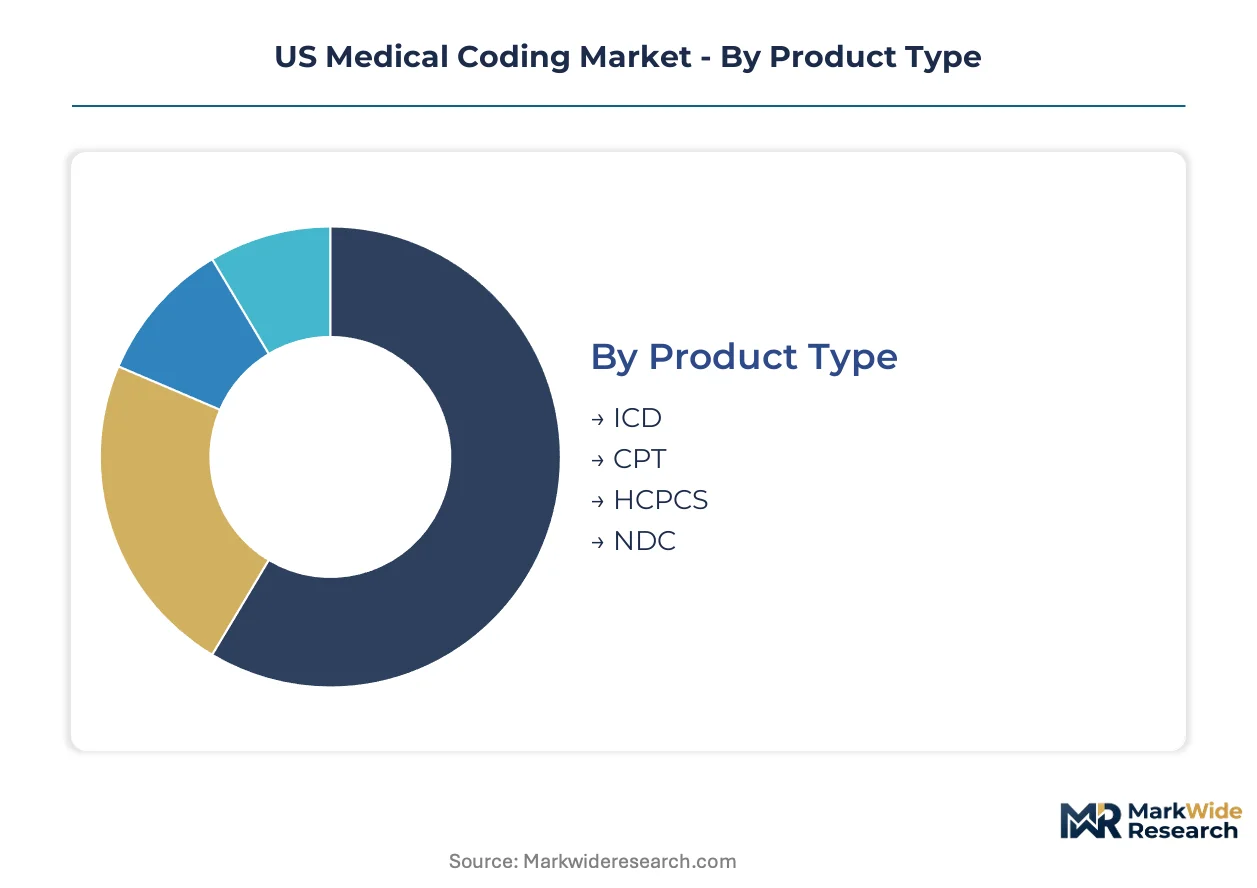
Segmentation in the US Medical Coding Market reveals distinct procurement patterns across product types, end users, deployment models, and service categories. Each dimension carries different margin structures and vendor competitive dynamics that shape go-to-market strategies.
Product Type:
Margin pools concentrate where regulatory mandates force mandatory adoption and specialized training creates switching costs.
- ICD:The International Classification of Diseases system anchors diagnosis coding with over 70,000 alphanumeric codes under ICD-10-CM. Hospital systems in California and Texas drive demand as CMS reimbursement rules tighten documentation requirements for inpatient encounters. Mandatory reporting across all patient encounters locks in institutional purchasing cycles.
- CPT:Current Procedural Terminology codes govern physician reimbursement through time-based relative value units assigned by the AMA. Ambulatory surgery centers in Florida and Arizona prioritize CPT accuracy as Medicare Advantage plans audit hierarchical condition category capture for risk adjustment payments.
- HCPCS:Healthcare Common Procedure Coding System covers supplies, equipment, and services outside CPT scope.
- NDC:National Drug Code identifiers track pharmaceutical products for billing and inventory.
The dominant share belongs to ICD, while CPT is closing the gap fastest.
End User:
Volume concentration shifts toward decentralized care settings as surgical procedures migrate away from inpatient facilities.
- Hospitals:Large health systems maintain captive coding departments with encoder software licenses from established vendors. Texas Medical Center and New York-Presbyterian networks drive enterprise procurement for integrated revenue cycle management platforms.
- Physician Practices:Small and mid-size groups accelerate outsourcing to avoid AHIMA-certified coder wage premiums. Mississippi and Alabama rural clinics remain underserved by specialized vendors.
- Outpatient Facilities:Ambulatory surgery centers demand bundled coding and billing services rather than standalone licenses.
- Home Health Agencies:Post-acute providers face unique documentation challenges for remote patient encounters.
Hospitals retain the largest installed base, though outpatient facilities are expanding most quickly.
Deployment Model:
Customer type determines infrastructure preferences as capital constraints reshape technology acquisition patterns.
- Cloud-based:HIPAA-compliant cloud infrastructure eliminates capital-intensive server investments while enabling automatic software updates. Texas and Florida ambulatory networks lead migration away from on-premises systems as private equity-backed rollups centralize procurement decisions.
- On-premises:Legacy installations persist in health systems with decades-old EHR integrations resistant to API-based interoperability without expensive middleware.
- Web-based:Browser-accessible platforms serve smaller practices with limited IT support resources.
- Hybrid:Mixed environments accommodate transition periods during ICD-11 implementation.
Cloud-based deployment commands the steepest expansion trajectory, while on-premises retains entrenched positions in legacy health systems.
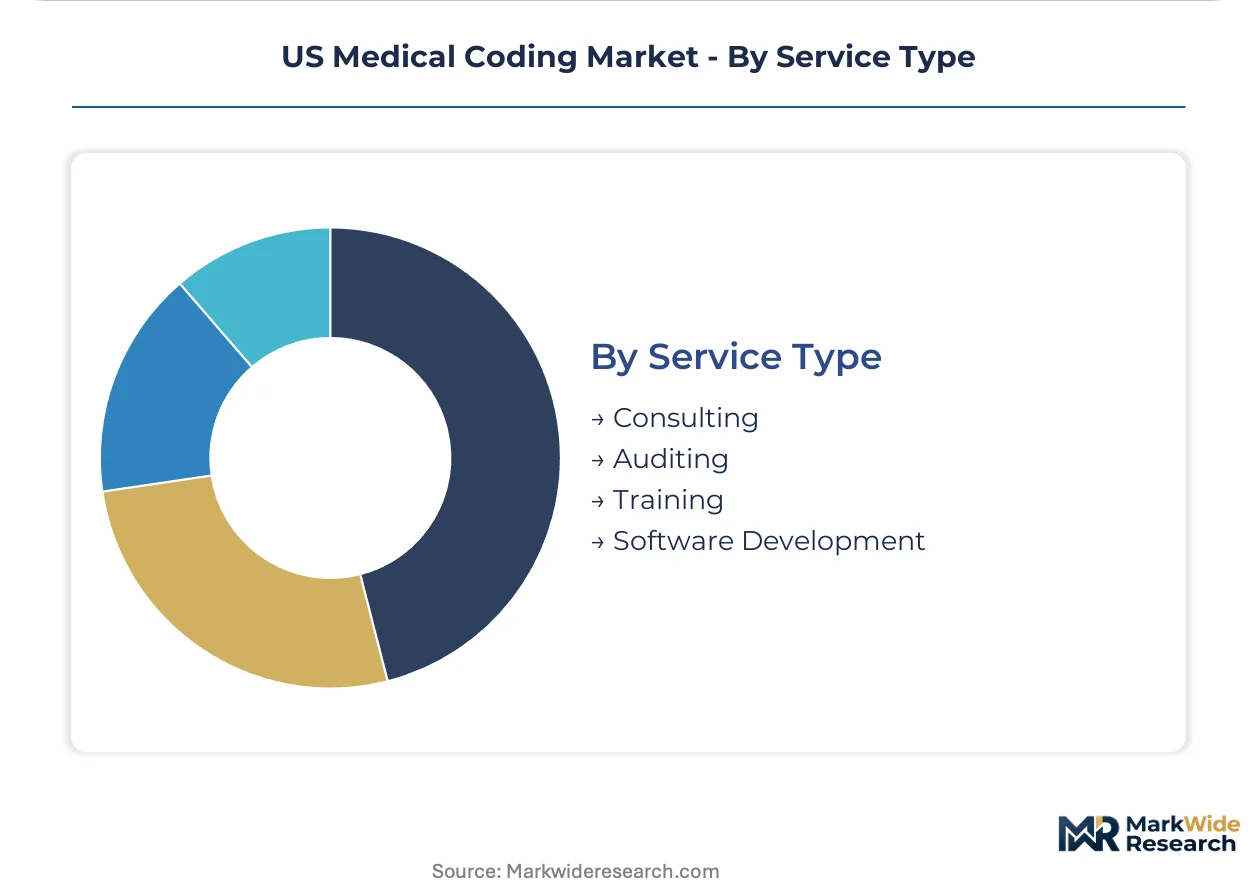
Service Type:
Maturity curves diverge as automation displaces labor-intensive offerings while creating demand for adjacent expertise.
- Consulting:Advisory services guide health systems through ICD-11 transition complexity and dual coding periods. Vendor teams embed within California and New York facilities to compress implementation timelines.
- Auditing:Retrospective claim reviews identify missed charges and compliance gaps before payer audits.
- Training:Specialized education addresses AHIMA-certified coder shortages through credentialing programs.
- Software Development:Custom integration work connects encoder platforms to EHR systems and clearinghouses.
Consulting holds the dominant share, with software development gaining share fastest as interoperability demands intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical coding services flow from India and the Philippines into US hospital systems and ambulatory networks, with domestic delivery concentrated in Texas, Florida, and California health corridors.
Texas
Texas Medical Center in Houston and Dallas-Fort Worth ambulatory networks drive enterprise procurement for integrated revenue cycle platforms. CMS reimbursement tightening forces rural clinics in the Panhandle and Rio Grande Valley to accelerate outsourcing partnerships. Private equity-backed ASC rollups in Austin and San Antonio centralize coding vendor selection under single procurement umbrellas.
Florida
Medicare Advantage penetration in Miami-Dade and Tampa Bay intensifies HCC risk adjustment auditing demands. Florida Hospital Association members embed clinical documentation improvement specialists to capture hierarchical condition categories. The I-4 corridor between Orlando and Tampa concentrates ambulatory surgery center expansion with bundled coding and billing requirements.
California
Large health systems in Los Angeles and the Bay Area deploy computer-assisted coding platforms to reduce emergency department coder backlog. Kaiser Permanente and Sutter Health networks mandate encoder software upgrades for ICD-11 readiness. Sacramento-area federally qualified health centers pilot AI-assisted documentation tools for Medicaid encounter coding.
New York
New York-Presbyterian and Northwell Health systems maintain captive coding departments with specialized trauma and academic medical center complexity. HIPAA breach notification enforcement by the New York State Department of Financial Services elevates cybersecurity audit requirements for vendor selection. Brooklyn and Queens physician practices outsource to avoid AHIMA-certified coder wage premiums.
Illinois
Chicago-based health systems including Advocate Aurora and Northwestern Medicine refresh encoder infrastructure for dual coding periods during ICD-10 to ICD-11 transition. Downstate rural hospitals in Peoria and Springfield participate in shared service arrangements for coding labor arbitrage. Illinois Medicaid managed care expansion drives encounter coding volume for Molina and Centene plans.
US Medical Coding Market Key Industry Players
Listed leaders compete with private specialists across payer-provider integration depth, with market structure consolidating around three tiers. Vertically integrated health IT conglomerates anchor the top tier through bundled revenue cycle offerings. Mid-tier vendors compete on encoder software installed base and clinical documentation improvement platforms. Labor arbitrage specialists occupy the bottom tier with offshore delivery center networks. Dominant competitive moves include strategic partnerships with EHR vendors and geographic expansion into underserved rural markets.
Within the payer-provider integration tier, Optum exemplifies vertical consolidation through its UnitedHealth Group affiliation. Among encoder software specialists, 3M Health Information Systems anchors institutional sales through decades-long hospital system relationships. Omega Healthcare Management Services represents the labor arbitrage archetype with offshore delivery center positioning. These three patterns capture the competitive spectrum without exhaustive enumeration of participant strategies.
| Leading Market Players |
|---|
| Oracle |
| Maxim Healthcare Services |
| Aviacode Inc. |
| Verisk Analytics, Inc. |
| Parexel International Corporation |
| Optum |
| Dolbey |
| Omega Healthcare Management Services |
| 3M Health Information Systems |
| Others |
Cost & Logistics Intelligence
Cloud-based encoder platforms substituting for on-premises server infrastructure simultaneously shift supply geography toward HIPAA-compliant data centers in Texas and Florida while compressing pricing economics through SaaS subscription models that eliminate capital expenditure barriers for ambulatory networks.
Pricing Analysis
Legacy on-premises encoder licenses, current-generation SaaS subscriptions, and emerging AI-assisted coding platforms stratify across three distinct pricing tiers. The dominant structure runs on per-claim or percentage-of-collections SaaS models, with price differentiation anchored in AHIMA certification levels and integration complexity with Epic or Cerner EHR systems. Pricing pressure stems from offshore delivery centers in India and the Philippines competing on labor arbitrage for standard coding volumes. Physician practices in Mississippi and Alabama exhibit highest price sensitivity, while Texas Medical Center health systems prioritize accuracy guarantees over cost minimization.
Supply Chain Analysis
Strategic stockpiling of AHIMA-certified coding talent supersedes just-in-time labor procurement as health systems brace for ICD-11 transition deadlines. Supply concentrates in India, the Philippines, and domestic delivery hubs across Texas and Florida, with raw material dependencies spanning specialized encoder software licenses, NLP training datasets, and CMS documentation guidelines. Single-source vulnerability runs through Philippines-based coding centers facing HIPAA data localization scrutiny. Distribution runs through direct enterprise sales for hospital systems and channel partnerships for rural physician practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Medical Coding Market sits in early-cycle expansion as CMS value-based payment models accelerate adoption of HCC risk adjustment coding services, creating penetration tailwinds across Medicare Advantage-heavy states.
For Market Incumbents: Secure encoder software installed base loyalty through embedded clinical documentation improvement specialists who compress ICD-11 implementation timelines. Deepen backward integration into AI-assisted coding platforms to neutralize NLP automation threats from cloud-native entrants. Prioritize channel control via exclusive EHR vendor partnerships with Epic and Cerner.
For New Entrants and Emerging Players: AHIMA certification fast-track programs open white-space access in federally qualified health centers across Mississippi and Alabama where specialized vendor penetration remains minimal. Target ambulatory surgery center rollups in Texas and Colorado demanding bundled coding-billing services. Pursue go-to-market angles anchored in per-claim pricing transparency versus legacy percentage-of-collections opacity.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertical integration plays combining encoder software with revenue cycle management platforms. Long-term viability hinges on AI automation readiness and CMS regulatory alignment. Acquisition target archetypes include clinical documentation improvement platforms with existing hospital system relationships. The signal to watch is CMS acceleration of value-based payment model mandates that tie coding accuracy directly to quality metrics.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Documentation Improvement Platform Acquisition | Captures HCC risk adjustment revenue tied to Medicare Advantage penetration in Florida. |
| HIPAA-Compliant Cloud Infrastructure Expansion | Enables Texas and Florida ambulatory network migration from capital-intensive on-premises systems. |
| AHIMA Certification Pipeline Investment | Addresses skilled coder shortage inflating labor costs for in-house hospital operations. |
| Epic EHR Integration Partnership | Secures encoder software distribution through dominant hospital system procurement channels. |
| ICD-11 Transition Consulting Services Launch | Monetizes dual coding period complexity compressing health system implementation timelines. |
Research Approach
Cross-validation between primary interviews with health system revenue cycle directors and secondary validation through CMS Medicare cost reports anchors the qualitative findings. Conversations with AHIMA-certified coding managers, ambulatory surgery center procurement officers, and clinical documentation improvement specialists informed operational dynamics. Secondary sources encompassed hospital procurement databases, GPO contracts, ONC interoperability standards filings, and HIPAA breach notification records. Bottom-up coding volume estimates triangulated against top-down healthcare expenditure allocations.
Sensitivity analysis around ICD-11 transition timing and CMS value-based payment adoption rates stress-tested projections across the analysis window. Segmentation dimensions modeled encompassed product type, end-user facility category, deployment architecture, and service delivery mode. CAGRs derived from logarithmic trend fitting of historical reimbursement rule change impacts. Forecast inputs incorporated Medicare Advantage enrollment trajectories and cloud infrastructure migration patterns specific to Texas and Florida health corridors.
Underlying assumptions cover stable HIPAA enforcement intensity and gradual ICD-11 code set adoption, with deviation risk concentrated in CMS acceleration of quality metric linkages or Philippines data localization restrictions. Revision becomes warranted when Medicare Advantage penetration in target states crosses threshold inflection points or AI-assisted coding accuracy rates achieve clinical validation benchmarks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Dentistry EMR Software Market
Medical Information Systems
Global Clinical EHR Systems Market
Medical Information Systems
Healthcare Information Software Market
Medical Information Systems
Healthcare ERP Market
Medical Information Systems
Medical Information Market
Medical Information Systems
Medical Simulation Software Market
Medical Information Systems
Global Clinical Documentation Improvement Market
Medical Information Systems
Urology EMR Software Market
Medical Information Systems
US Healthcare ERP Market
Medical Information Systems
Hospital Information Systems Market
Medical Information Systems
Ophthalmology EMR Software Market
Medical Information Systems
Global Medical Decision Support Systems for Sepsis Market
Medical Information Systems
Global Clinical Information System Market
Medical Information Systems
Global Medical Writing Market
Medical Information Systems
OBGYN EHR Market
Medical Information Systems
Medical Saas System Market