
 Critical Care Information Systems Market | 2026-2036
Critical Care Information Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Critical Care Information Systems Market Outlook
The gap between enterprise-grade critical care platforms and fragmented point solutions is repositioning procurement priorities across health systems. Cerner Corporation leverages its embedded EHR footprint to anchor long-term contracts with academic medical centers. Epic Systems Corporation sustains dominance through tightly integrated clinical and billing workflows that reduce interface complexity.
Critical care information systems comprise hardware-software architectures that capture, integrate, and visualize real-time physiologic data from ventilators, infusion pumps, and multi-parameter monitors to support clinical decision-making in high-acuity settings. These systems rely on HL7 FHIR interoperability standards and sub-second latency thresholds to ensure alarm integrity across distributed device networks. Cloud-based solutions now lead new deployments as hospitals prioritize remote access and disaster resilience, while on-premise systems retain share among institutions with stringent data-locality policies. Patient monitoring systems command the largest installed base, though clinical decision support tools represent the fastest-expanding margin pool as predictive analytics modules gain contractual attachment rates.
FDA oversight of Software as a Medical Device, HIPAA security rule enforcement by the Office for Civil Rights, and ONC interoperability certification requirements collectively elevate compliance costs for new entrants while locking in incumbent platforms. Health systems must now evaluate whether their current architecture accommodates pending federal mandates for standardized application programming interfaces and algorithmic transparency. Stakeholders should monitor how regulatory timelines for artificial-intelligence-enabled diagnostic modules reshape vendor roadmaps and capital allocation.
Market Dynamics
Real-time physiologic data integration is compressing procurement cycles as health systems replace fragmented monitoring stacks with unified platforms that satisfy ONC interoperability mandates.
Growth Catalysts
- FDA Software as a Medical Device oversight:The framework accelerates clearance pathways for algorithm-driven clinical decision support, expanding reimbursable indications for predictive analytics modules.
- Cloud infrastructure migration:Tertiary care centers in the United States are prioritizing disaster-resilient architectures that enable remote intensivist coverage and reduce on-premise hardware maintenance burdens.
- HL7 FHIR standardization:Mandated API specifications are dissolving data silos between ventilators, infusion pumps, and EHR systems, creating network effects that favor integrated platform vendors.
Market Restraints
- HIPAA Security Rule enforcement:OCR audit expansion elevates compliance costs for encryption, access logging, and breach notification infrastructure, particularly burdening mid-size community hospitals.
- Specialized biomedical engineering talent scarcity:Integration of legacy bedside devices with modern middleware requires expertise in both proprietary serial protocols and contemporary REST APIs.
- Sub-second latency requirements:Alarm integrity thresholds for distributed device networks constrain architectural choices, complicating cloud migration for high-acuity telemetry.
Strategic Opportunities
- Underpenetrated rural critical access hospitals:These facilities lack capital for enterprise platforms, creating white space for subscription-based remote monitoring services with centralized clinical decision support.
- AI-enabled sepsis prediction modules:Early-warning algorithms that integrate multi-parameter trends represent attachable high-margin extensions to base monitoring contracts.
- Tele-ICU network expansion:Regional health systems are consolidating nighttime intensivist coverage across multiple hospitals, requiring centralized data aggregation platforms with standardized visualization.
Industry Challenges
- Biomedical informaticist recruitment:Health systems struggle to hire personnel capable of configuring device-to-EHR mappings, managing alarm fatigue protocols, and optimizing clinical workflow integration.
- Legacy device interoperability:Decades-old ventilators and monitors with proprietary data formats require expensive middleware gateways or complete replacement to achieve FHIR compliance.
- ONC certification timeline compression:Vendors must synchronize development roadmaps with uncertain federal deadlines for standardized APIs and algorithmic transparency requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Critical Care Information Systems Market |
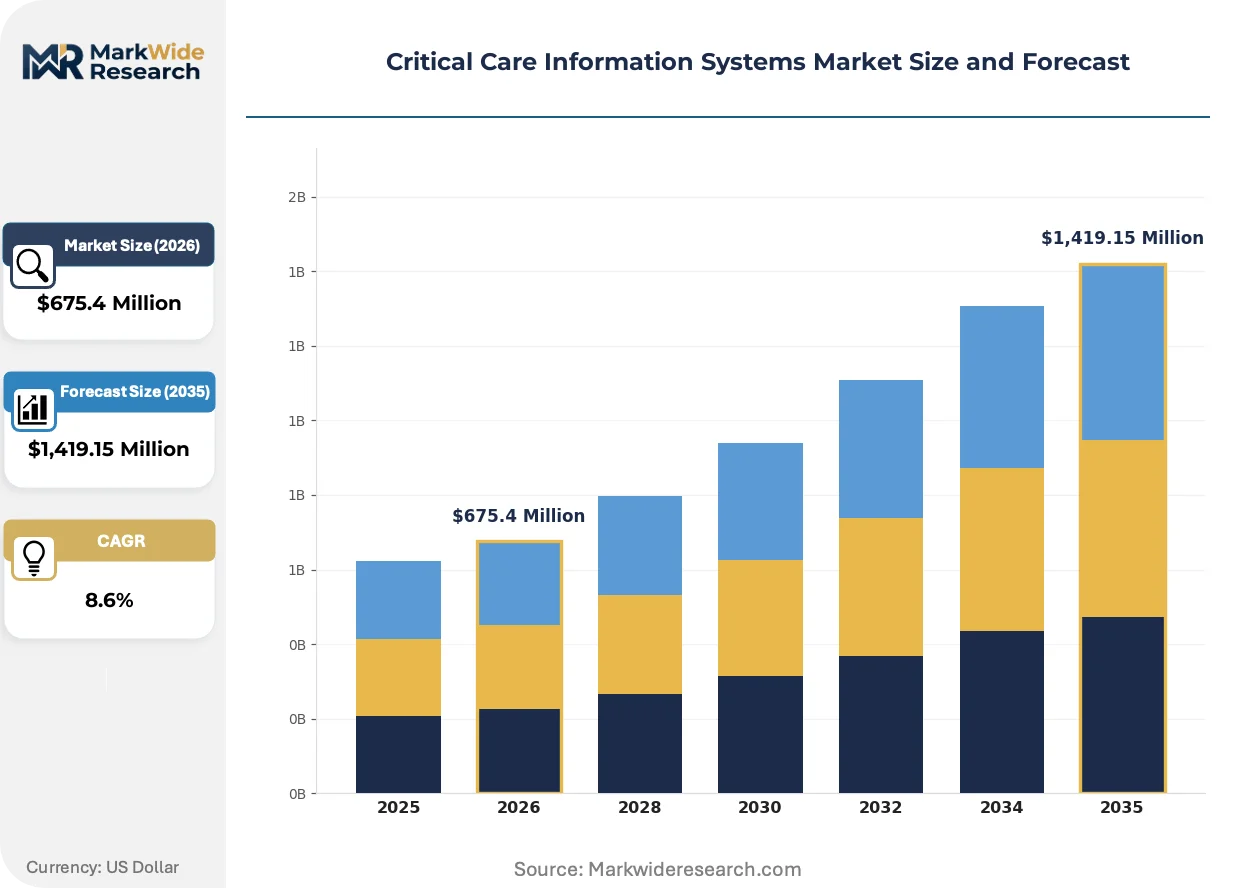
| Market Size in 2026 | $675.4 Million |
| Market Size in 2035 | $1,419.15 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patient Monitoring Systems, Data Management Software, Clinical Decision Support Tools, Integration Platforms End User: Hospitals, Ambulatory Surgical Centers, Long-term Care Facilities, Home Healthcare Providers Technology: Cloud-based Solutions, On-premise Systems, Mobile Platforms, Wearable Devices Application: Emergency Care, Surgical Care, Post-Operative Monitoring, Critical Care Unit Management |
| Companies Covered | Cerner Corporation, Epic Systems Corporation, Siemens Healthineers, Koninklijke Philips, GE HealthCare, McKesson Corporation, Optum, Allscripts Healthcare Solutions, Picis Clinical Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Critical Care Information Systems Market Strategic Shifts
Artificial intelligence modules are embedding directly into monitoring workflows, shifting value capture from hardware sensors to predictive software layers that anticipate deterioration before vital signs cross thresholds.
Edge computing architectures are converging with traditional bedside monitoring to enable local processing of high-frequency physiologic streams. Academic medical centers in the United States are piloting these configurations to reduce cloud latency for alarm-critical telemetry. This convergence is compressing the distinction between device manufacturers and software vendors, forcing hardware-centric suppliers to build or acquire analytics capabilities.
The FDA's evolving guidance on predetermined change control plans for machine-learning-based devices is reshaping validation requirements for sepsis and respiratory failure prediction algorithms. Manufacturers must now document anticipated modifications and monitoring protocols prior to market entry. Intensive care units deploying these tools face expanded documentation burdens for algorithm performance auditing.
Hospital procurement committees are unbundling after-sales service contracts from initial platform purchases, negotiating separate agreements for clinical optimization and technical support. Health systems with mature informatics teams increasingly self-manage configuration and training, displacing vendor-delivered implementation services. This pattern is most pronounced in integrated delivery networks with centralized IT governance across multiple facilities.
Critical Care Information Systems Market Segmentation
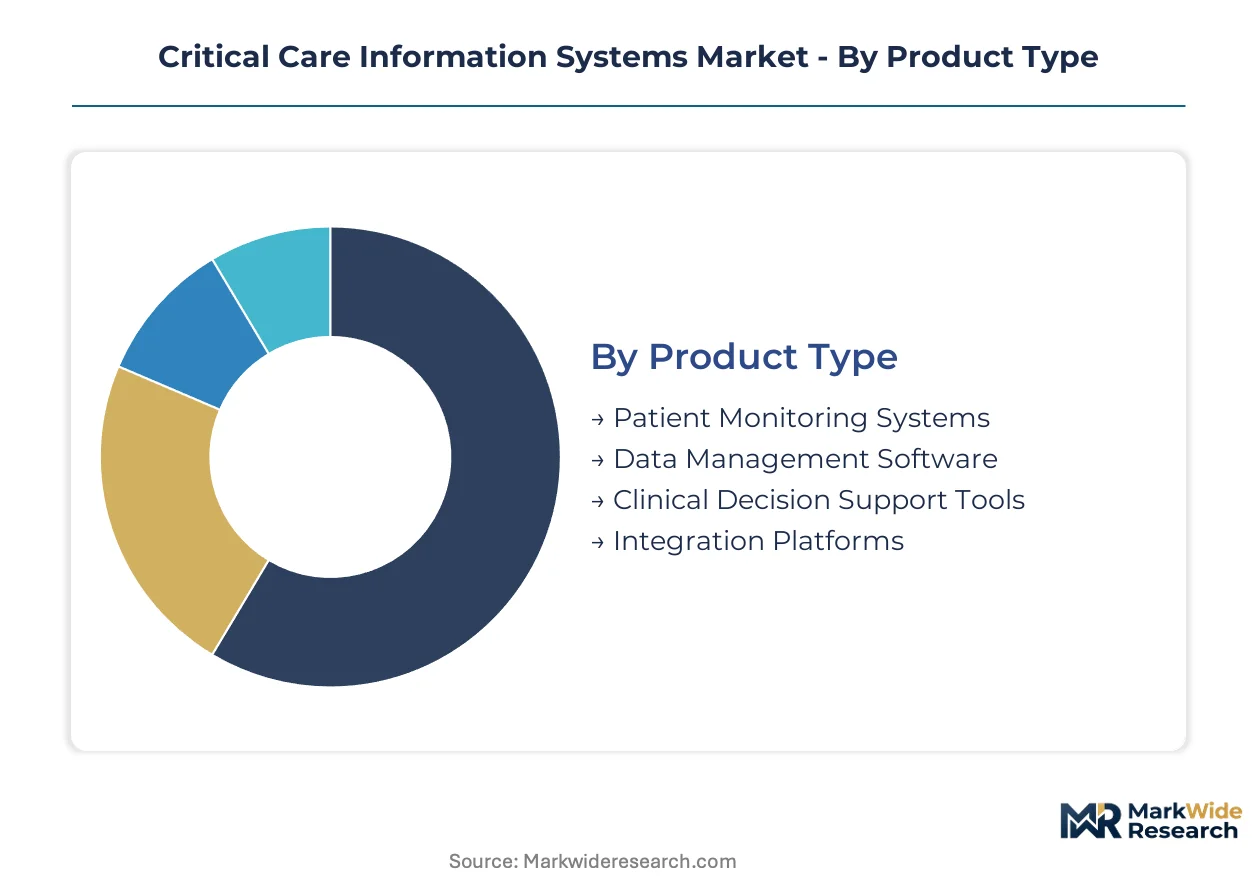
Critical care information systems segment across hardware-software boundaries, procurement models, and clinical workflows. Understanding these divisions reveals where capital concentrates and which architectures command premium pricing versus commodity replacement cycles.
Product Type:
Volume deployment concentrates in hardware-centric monitoring infrastructure, while margin capture shifts toward algorithmic software layers that integrate disparate device streams.
- Patient Monitoring Systems:Multi-parameter bedside devices capture real-time physiologic streams from ventilators, infusion pumps, and cardiac monitors. Demand concentrates in United States tertiary care centers replacing fragmented telemetry stacks with unified platforms that satisfy ONC interoperability mandates.
- Clinical Decision Support Tools:Predictive analytics modules process trend data to anticipate deterioration before threshold breaches. Academic medical centers in the United States attach these to base monitoring contracts, creating the steepest expansion trajectory as FDA Software as a Medical Device pathways clarify reimbursement for algorithm-driven diagnostics.
- Data Management Software:Middleware architectures normalize proprietary device protocols into HL7 FHIR-compliant formats for EHR consumption.
- Integration Platforms:Enterprise orchestration layers unify monitoring, documentation, and billing workflows across distributed device networks.
Mature deployment sits with Patient Monitoring Systems. Newer deployment is concentrated in Clinical Decision Support Tools.
End User:
Procurement authority and integration complexity vary sharply across facility types, with capital availability determining whether health systems pursue enterprise platforms or point solutions.
- Hospitals:Integrated delivery networks and academic medical centers dominate capital allocation, driving replacement cycles for enterprise-grade platforms with centralized IT governance across multiple facilities.
- Ambulatory Surgical Centers:These facilities prioritize lightweight, interoperable monitoring stacks that integrate with hospital EHR networks for continuity of care without dedicated biomedical engineering staff.
- Long-term Care Facilities:Skilled nursing operators seek remote monitoring capabilities to reduce transfer rates to acute settings.
- Home Healthcare Providers:Post-acute services deploy wearable telemetry for early discharge programs, though reimbursement uncertainty constrains platform investment.
Enterprise contracting authority rests with Hospitals. Subscription-based remote services are penetrating Long-term Care Facilities fastest.
Technology:
Architecture choices reflect trade-offs between latency sensitivity, data sovereignty requirements, and disaster resilience planning.
- Cloud-based Solutions:Remote-access architectures with elastic compute for predictive analytics now lead new deployments in United States tertiary centers prioritizing tele-ICU coverage and reduced on-premise maintenance burdens.
- On-premise Systems:Local infrastructure retains share among institutions with stringent data-locality policies or sub-second latency requirements for alarm-critical telemetry that cloud migration complicates.
- Mobile Platforms:Smartphone and tablet interfaces extend visualization to rounding clinicians and remote intensivists.
- Wearable Devices:Continuous telemetry patches enable ambulatory monitoring within hospital wards and early discharge programs.
Established infrastructure remains On-premise Systems. Cloud-based Solutions are capturing new deployment preference fastest.
Application:
Clinical setting determines device density, alarm criticality, and the economic case for predictive analytics investment.
- Critical Care Unit Management:High-acuity settings with ventilator-dependent patients and multi-infusion protocols generate the densest device integration requirements and strongest ROI for sepsis prediction algorithms.
- Emergency Care:Triage and resuscitation bays demand rapid deployment, mobile form factors, and interoperability with hospital admission systems to compress door-to-treatment intervals.
- Surgical Care:Operating rooms require anesthesia information management integration and device synchronization for hemodynamic monitoring during procedures.
- Post-Operative Monitoring:Step-down units balance surveillance intensity against resource constraints, creating demand for automated early-warning scores.
Device integration maturity centers on Critical Care Unit Management. Emergency Care is expanding predictive analytics adoption most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Boston corridor anchors North American critical care information systems deployment, where academic medical centers pilot edge-computing telemetry architectures alongside FDA-cleared predictive analytics modules.
United States
Tertiary care centers in the United States drive replacement cycles for enterprise-grade platforms with centralized IT governance across multi-facility networks. FDA Software as a Medical Device oversight accelerates clearance pathways for algorithm-driven clinical decision support tools. The Mayo Clinic corridor in Rochester, Minnesota, pilots sub-second latency architectures for alarm-critical telemetry in distributed device networks.
Germany
University hospitals in Germany prioritize HL7 FHIR-compliant middleware to normalize proprietary device protocols from legacy ventilator fleets. The EU Medical Device Regulation elevates post-market surveillance requirements for predictive analytics modules. The Rhine-Ruhr metropolitan region concentrates vendor certification activity for interoperability mandates from the European Health Data Space initiative.
United Kingdom
NHS trusts in England consolidate procurement for cloud-based critical care platforms to enable remote intensivist coverage across regional networks. The National Institute for Health and Care Excellence evaluates reimbursement pathways for AI-enabled sepsis prediction algorithms. The Oxford-Cambridge-London arc hosts pilot programs for standardized application programming interfaces in acute care settings.
Japan
Metropolitan hospitals in Tokyo and Osaka integrate clinical decision support tools with existing bedside monitoring infrastructure to address intensivist staffing constraints. The Pharmaceuticals and Medical Devices Agency streamlines approval processes for machine-learning-based diagnostic software. The Kansai region's medical device cluster advances edge-computing configurations for local processing of high-frequency physiologic streams.
Australia
State health departments in Australia standardize on cloud architectures for disaster resilience and tele-ICU network expansion across vast rural territories. The Therapeutic Goods Administration aligns software regulation with FDA precedent for predetermined change control plans. The Melbourne biomedical precinct concentrates validation activity for algorithmic transparency requirements in predictive monitoring systems.
Critical Care Information Systems Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the critical care information systems landscape, with consolidated platform vendors anchoring long-term enterprise contracts against specialized middleware suppliers. The vendor base stratifies into three archetypes: embedded EHR incumbents leveraging existing footprint, standalone clinical decision specialists attaching predictive modules, and hardware-integrated device manufacturers bundling software layers. Dominant competitive moves include strategic partnerships between device OEMs and cloud infrastructure providers, plus portfolio diversification into subscription-based remote monitoring services for underpenetrated rural markets.
Within the embedded EHR tier, Cerner Corporation and Epic Systems Corporation exemplify platform consolidation strategies that reduce interface complexity through tightly integrated clinical and billing workflows. Siemens Healthineers occupies a position bridging device manufacturing with enterprise software orchestration, reflecting the convergence of hardware-centric suppliers with analytics capabilities. These three anchors represent distinct strategic postures: EHR-native platform extension, standalone clinical decision specialization, and vertical integration across the device-to-software stack.
| Leading Market Players |
|---|
| Cerner Corporation |
| Epic Systems Corporation |
| Siemens Healthineers |
| Koninklijke Philips |
| GE HealthCare |
| McKesson Corporation |
| Optum |
| Allscripts Healthcare Solutions |
| Picis Clinical Solutions |
| Others |
Value Chain & Pricing Dynamics
Biomedical engineering labor costs cascade through critical care information systems pricing tiers, with specialized integration expertise commanding premium rates in United States tertiary centers while subscription-based remote monitoring compresses entry-level pricing for rural critical access hospitals.
Pricing Analysis
Value-based pricing anchored to patient throughput and clinical outcome metrics dominates enterprise contracts with academic medical centers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared algorithmic modules from basic monitoring dashboards and unbundled middleware configurations. Pricing pressure stems from health systems unbundling after-sales service contracts and self-managing implementation with mature informatics teams. Mid-size community hospitals exhibit highest price sensitivity due to OCR audit compliance burdens, while integrated delivery networks with centralized IT governance demonstrate lowest sensitivity given scale economies.
Supply Chain Analysis
Direct-to-hospital channels handle enterprise platform demand from academic medical centers and integrated delivery networks, while value-added resellers and GPO contracts serve mid-tier installations. Hardware component manufacturing concentrates in Germany, Japan, and the United States, with cloud infrastructure services anchored in domestic data center regions to satisfy HIPAA data-locality requirements. Legacy bedside device integration depends on proprietary protocol gateways sourced from specialized middleware vendors. Single-source vulnerability in FDA-cleared algorithm modules creates supply risk, as predetermined change control plans lock vendors into specific validation pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized biomedical engineering talent scarcity props pricing power for vendors with captive integration capabilities, constraining rapid capacity expansion across the forecast horizon.
For Market Incumbents: Acquire predictive analytics specialist firms to anchor algorithmic capabilities before FDA Software as a Medical Device pathways mature. Consolidate middleware expertise to counter emerging cloud-native entrants threatening alarm integrity latency advantages. Backward integration into edge-computing hardware secures sub-second telemetry performance as a differentiated lock-in mechanism. For New Entrants and Emerging Players: The mid-tier pricing gap between Epic-Cerner enterprise platforms and fragmented point solutions creates entry space for subscription-based remote monitoring services. Rural critical access hospitals in the United States represent the most penetrable segment given capital constraints and intensivist staffing shortages. Lead with tele-ICU network aggregation capabilities to bypass direct EHR integration complexity. For Investors and Strategic Acquirers: ONC certification timeline announcements are the leading indicator that vendor consolidation windows are opening. Five-to-ten year viability favors platforms with embedded EHR footprint and algorithmic module attach rates. Target acquisition archetype: clinical decision support specialists with FDA-cleared sepsis prediction algorithms and established hospital pilot data.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | HL7 FHIR-compliant middleware dissolves data silos between ventilators and EHR systems. |
| Strategic Partnership | Cloud infrastructure alliances enable disaster-resilient architectures for tele-ICU coverage. |
| Acquisition of Specialist Firm | Predictive analytics capabilities compress alarm response times before threshold breaches. |
| Hospital System Partnership | Academic medical center pilots validate edge-computing configurations for latency-critical telemetry. |
| Reimbursement Strategy | FDA Software as a Medical Device clearance unlocks payer coverage for algorithm-driven diagnostics. |
Study Parameters
Document review covered FDA 510(k) filings, ONC certification databases, and hospital procurement records, complemented by interviews with critical care physicians, biomedical engineers, hospital purchasing committee members, and GPO contracts managers. Secondary validation drew from CMS Medicare reimbursement data, HIMSS analytics surveys, and SEC filings of publicly traded health IT vendors. Bottom-up sizing of installed base volumes triangulated against top-down expenditure estimates from health system capital budget disclosures.
Cross-referencing historical deployment trajectories against panel input from vendor strategy executives shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user facility category, deployment architecture, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves incorporating FDA guidance timeline uncertainty and ONC interoperability mandate compliance schedules.
Inputs from hospital procurement databases and GPO contract repositories were available through the study window; gaps in rural critical access hospital spending patterns introduce uncertainty bands at the segment periphery. Forecasts reflect assumptions regarding regulatory timeline adherence and cloud migration velocity in high-acuity settings. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Global Healthcare Software As a Service Market
Medical Information Systems
Global Medical Terminology Software Market
Medical Information Systems
Medical Talent Management IT Market
Medical Information Systems
Hospital Information Systems Market
Medical Information Systems
Artificial Intelligence in Medical Software Market
Medical Information Systems
Electronic Medical Record Market
Medical Information Systems
AI Medical Service Market
Medical Information Systems
Healthcare Mobile Computers Market
Medical Information Systems
Post-Marketing Pharmacovigilance and Medical Information Market
Medical Information Systems
Global Allergy EMR Software Market
Medical Information Systems
Medical 3D Software Market
Medical Information Systems
Healthcare Information Software Market
Medical Information Systems
AI in Medical Coding Market
Medical Information Systems
Ambulatory Software Market
Medical Information Systems
Ophthalmology EMR Software Market
Medical Information Systems
Donor Management Software Market