
 Canada Patient Monitoring Devices Market | 2026-2036
Canada Patient Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Patient Monitoring Devices Market Outlook
Multi-source procurement of sensor modules and telemetry hardware is shifting toward vertically integrated domestic suppliers. GE Healthcare anchors its Canadian operations through localized manufacturing of multi-parameter monitors for hospital networks. Masimo Corporation differentiates through proprietary pulse oximetry algorithms that sustain premium positioning in acute care settings. Abbott Laboratories competes via wearable glucose and cardiac monitoring platforms targeting homecare expansion.
Patient monitoring devices encompass electronic systems that acquire, process, and display physiological parameters including electrocardiography waveforms, blood oxygen saturation, respiratory rate, and invasive pressures, typically operating with sampling frequencies between 125 Hz and 1000 Hz depending on parameter criticality. These systems serve primarily to enable early clinical intervention, reduce adverse events, and support decentralized care delivery outside traditional facility settings. Cardiac monitors and multi-parameter monitors occupy the mature core of the product mix, while wearable technology and remote patient monitoring represent the fastest-expanding technology categories as provincial health authorities fund hospital-at-home initiatives. Wireless monitoring infrastructure underpins cloud-based solution deployment, though margin pools currently concentrate in hardware-software integrated platforms rather than standalone connectivity components.
Health Canada's Medical Devices Directorate classifies patient monitors as Class II or Class III devices depending on invasiveness and parameter criticality, requiring ISO 13485 quality management certification and specific cybersecurity attestations for networked equipment. The Canadian Standards Association maintains electrical safety and electromagnetic compatibility standards aligned with IEC 60601-1 that manufacturers must satisfy for market authorization. Provincial health technology assessment bodies, notably Ontario Health and INESSS in Quebec, increasingly evaluate remote monitoring solutions for reimbursement eligibility based on demonstrated readmission reduction. Stakeholders must monitor evolving cybersecurity mandates and provincial procurement frameworks that will determine which integrated platform vendors secure long-term supply agreements.
Market Dynamics
Provincial hospital-at-home funding mandates are compressing deployment timelines for wireless monitoring infrastructure across Ontario and Quebec, forcing vendors to accelerate cloud platform certification cycles.
Growth Catalysts
- Health Canada Cybersecurity Directives:Class III networked device requirements are accelerating firmware upgrade cycles and creating recurring revenue pools for platform vendors serving acute care networks.
- Ontario Health Technology Assessment:Reimbursement eligibility tied to readmission reduction metrics is expanding procurement budgets for remote cardiac monitoring in rural hospital networks.
- Multi-parameter Telemetry Convergence:Integration of pulse oximetry, ECG, and respiratory rate into single wearable form factors is reducing bedside equipment density in tertiary care wards.
Market Restraints
- Semiconductor Component Concentration:Dependency on Taiwanese foundry output for wireless SoCs creates 16-24 week lead time volatility for domestic monitor assembly operations.
- ISO 13485 Certification Friction:Quality management audits for Class III device reclassification are extending market authorization timelines by 8-14 months for software-enabled platforms.
- Legacy Hardwired Infrastructure:Sunk capital in 1990s-era bedside monitor networks in Quebec's aging hospital stock slows wireless retrofit adoption despite provincial funding availability.
Strategic Opportunities
- Alberta Rural Health Expansion:Underpenetrated remote communities present first-mover advantage for cellular-enabled cardiac monitors with store-and-forward capabilities.
- AI-Enabled Arrhythmia Detection:Machine learning classification algorithms embedded at the edge are creating differentiation in ambulatory ECG segments previously commoditized by hardware.
- Homecare Channel Direct Distribution:Bypassing traditional Group Purchasing Organizations through provincial tender exceptions for hospital-at-home programs is unlocking margin expansion.
Industry Challenges
- Firmware Validation Bottlenecks:Health Canada's Software as a Medical Device guidance requires documented regression testing for every over-the-air update, compressing release velocity.
- Interoperability Fragmentation:Lack of unified data exchange standards between provincial electronic health record systems forces redundant integration engineering for multi-hospital deployments.
- Clinical Workflow Redesign:Nursing staff resistance to remote alarm management protocols in Ontario ICU networks is delaying full utilization of centralized telemetry stations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Patient Monitoring Devices Market |
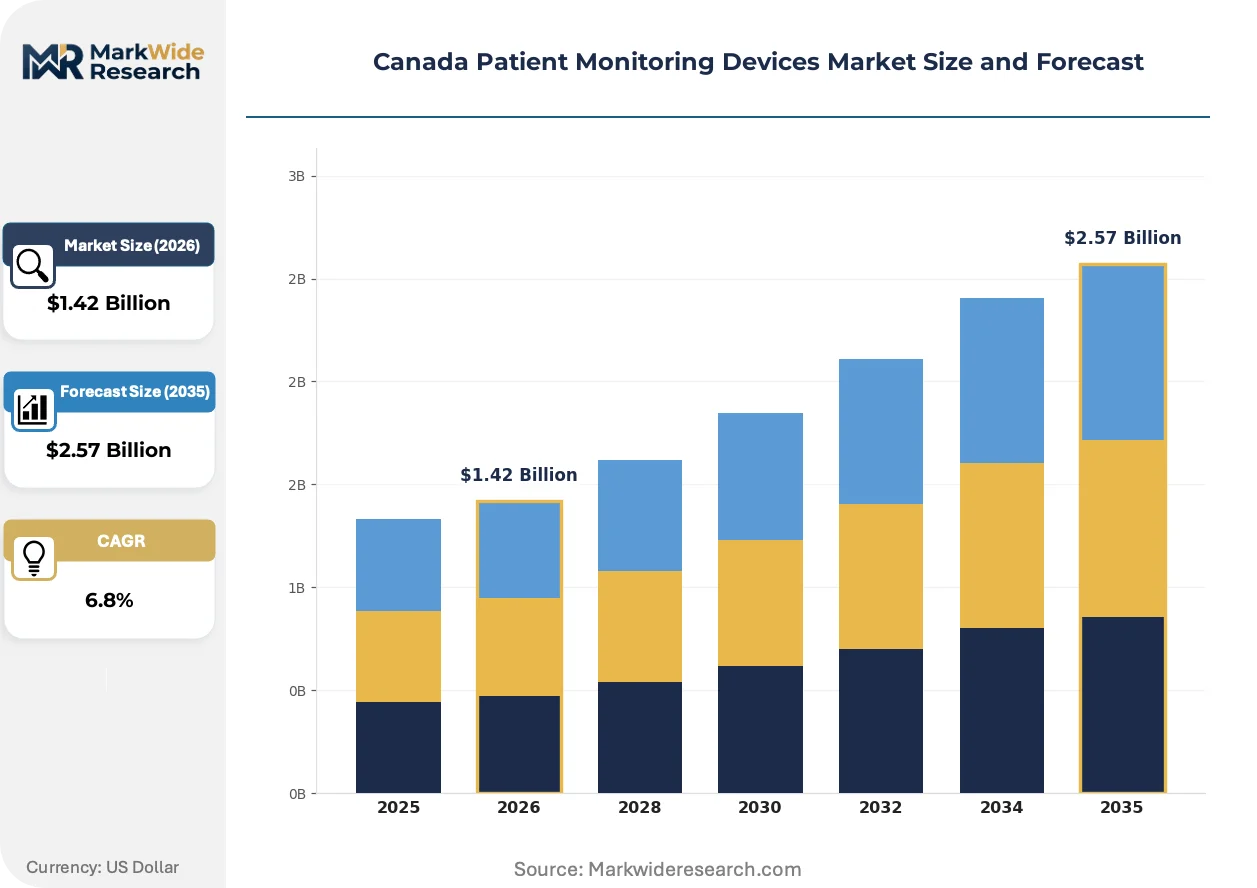
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiac Monitors, Respiratory Monitors, Neurological Monitors, Multi-Parameter Monitors Technology: Wireless Monitoring, Cloud-Based Solutions, Wearable Technology, Remote Patient Monitoring End User: Hospitals, Homecare Settings, Diagnostic Laboratories, Ambulatory Surgical Centers Application: Chronic Disease Management, Postoperative Care, Maternal Health, Emergency Care |
| Companies Covered | GE Healthcare, Boston Scientific Corporation, Medtronic PLC, Masimo Corporation, Becton, Dickinson and Company, Omron Corporation, Koninklijke Philips NV, Baxter International Inc., Abbott Laboratories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Patient Monitoring Devices Market Strategic Shifts
Continuous glucose monitoring architectures are migrating toward multi-analyte platforms that consolidate metabolic and cardiac biomarker tracking into unified wearable ecosystems.
Photoplethysmography signal processing at the edge is rewriting how ambulatory arrhythmia detection reaches community-dwelling patients. Rural health authorities in Saskatchewan and Manitoba are piloting prescription-based deployment of wrist-worn monitors with automated cardiologist alert routing. This compression of diagnostic latency is displacing traditional Holter monitoring volumes in primary care referral pathways.
Health Canada's Medical Devices Directorate tightened cybersecurity attestation requirements for networked patient monitors in 2024, mandating SBOM documentation and vulnerability disclosure protocols. Device manufacturers serving Canadian hospital networks must now embed automated patch management infrastructure into Class III platform architectures. Quebec's INESSS evaluation framework now weights cybersecurity compliance parity with clinical efficacy in reimbursement determinations.
Hospital procurement committees are unbundling hardware acquisition from multi-year service agreements, shifting toward subscription-based telemetry platform licensing. Ontario Health's centralized contracting unit is leading this transition through pilot frameworks that separate sensor hardware from cloud analytics access fees. This disintermediation of capital expenditure models is most visible in Toronto and Ottawa hospital network tenders, where five-year total cost of ownership evaluations now dominate award criteria.
Canada Patient Monitoring Devices Market Segmentation
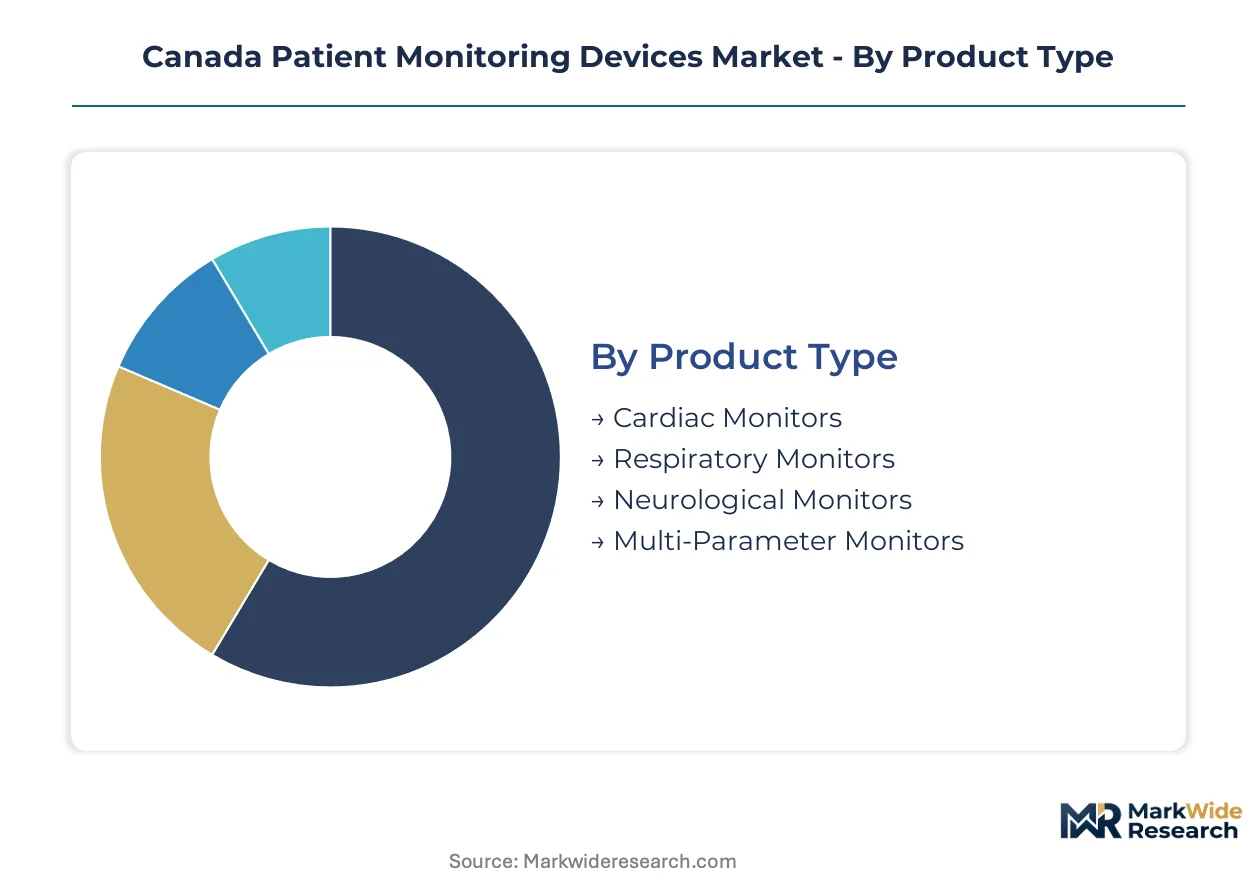
Patient monitoring devices segment across hardware form factors, connectivity architectures, care settings, and clinical use cases. Each dimension carries distinct procurement pathways, regulatory requirements, and margin structures that shape vendor positioning within Canadian healthcare networks.
Product Type:
Hospital procurement committees differentiate devices by parameter criticality and bedside integration requirements.
- Cardiac Monitors:Electrocardiography systems sample at 250-1000 Hz with ST-segment analysis algorithms. Ontario Health's centralized contracting favors these for tertiary care telemetry wards where arrhythmia detection drives clinical outcomes.
- Multi-Parameter Monitors:Consolidated platforms integrate ECG, pulse oximetry, respiratory rate, and invasive pressures into single bedside units. Quebec's aging hospital infrastructure creates retrofit demand for wireless-enabled replacements that reduce cable clutter in ICU environments.
- Respiratory Monitors:Capnography and spirometry systems track end-tidal CO2 and flow-volume loops. These serve postoperative recovery wards across Vancouver and Calgary hospital networks.
- Neurological Monitors:EEG and intracranial pressure systems target neurocritical care units. Limited deployment concentrates in Toronto's specialized stroke centers and Montreal's trauma hospitals.
Volume sits with Multi-Parameter Monitors; growth tilts toward Cardiac Monitors.
Technology:
Connectivity architecture determines deployment velocity and cybersecurity compliance burden.
- Remote Patient Monitoring:Cellular and Wi-Fi enabled platforms transmit physiological data to centralized telemetry stations. Alberta's rural health expansion prioritizes these for communities beyond two-hour ambulance response windows.
- Wearable Technology:Wrist-worn and patch-based sensors with photoplethysmography and accelerometry. Saskatchewan's prescription-based pilot programs for community-dwelling cardiac patients are accelerating ambulatory deployment.
- Wireless Monitoring:Bluetooth and proprietary radio protocols eliminate bedside tethering. Health Canada's Class III cybersecurity attestations for networked equipment extend authorization timelines for these platforms.
- Cloud-Based Solutions:Software layers hosting analytics, alarm management, and longitudinal data storage. Ontario hospital-at-home funding mandates are compressing certification cycles for these architectures.
Deployment concentrates in Wireless Monitoring; expansion runs fastest through Wearable Technology.
End User:
Procurement authority and reimbursement pathways diverge sharply across care settings.
- Hospitals:Acute care networks dominate capital expenditure through Group Purchasing Organizations. Toronto and Ottawa hospital systems anchor demand for integrated telemetry platforms with centralized alarm management.
- Homecare Settings:Provincial hospital-at-home programs bypass traditional GPOs through tender exceptions. Quebec's INESSS reimbursement framework now weights remote monitoring efficacy alongside cybersecurity compliance.
- Diagnostic Laboratories:Holter monitoring and sleep study services maintain steady replacement demand. These facilities concentrate in urban corridors with cardiology referral density.
- Ambulatory Surgical Centers:Same-day procedure venues require compact multi-parameter units for post-anesthesia recovery. British Columbia's outpatient expansion is diversifying procurement beyond hospital networks.
Revenue pools concentrate in Hospitals; policy momentum favors Homecare Settings.
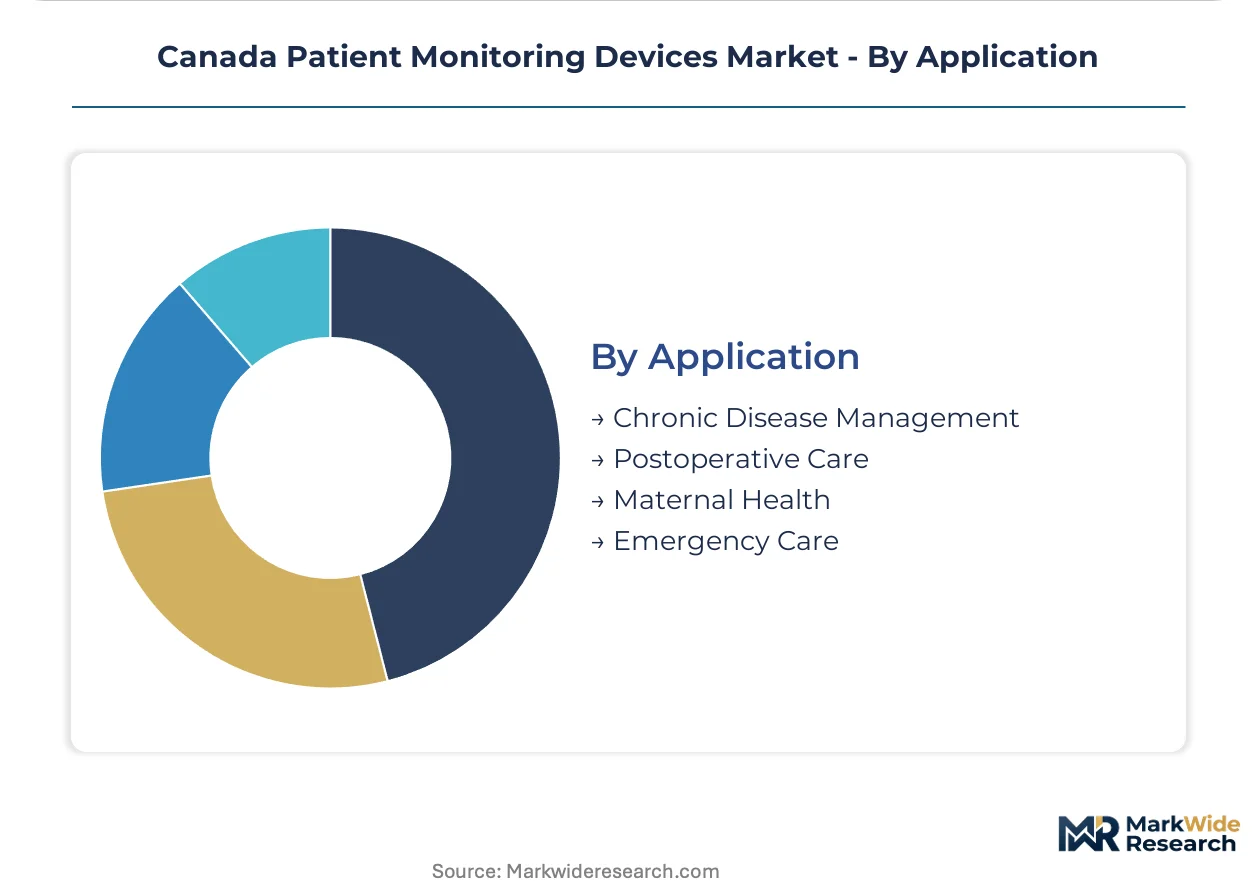
Application:
Clinical indication determines sensor configuration, alarm threshold protocols, and integration with electronic health records.
- Chronic Disease Management:Longitudinal monitoring for heart failure and COPD patients with automated clinician alerts. Manitoba's rural health authorities are piloting prescription-based wrist-worn deployment for this indication.
- Postoperative Care:Continuous surveillance during recovery from cardiac and orthopedic procedures. Ontario's readmission reduction metrics prioritize these applications in bundled payment frameworks.
- Emergency Care:Rapid-deployment monitors for triage and resuscitation bays. These require ruggedized hardware with minimal startup calibration.
- Maternal Health:Fetal heart rate and uterine contraction monitoring for labor and delivery units. Deployment concentrates in tertiary perinatal centers with neonatal intensive care backup.
Installed base concentrates in Postoperative Care; policy tailwinds favor Chronic Disease Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's semiconductor fabrication corridor supplies telemetry chipsets to domestic monitor assemblers, anchoring the eastern manufacturing base while Alberta's energy sector workforce drives demand for occupational health monitoring systems.
Ontario
Toronto's hospital networks anchor procurement for multi-parameter telemetry platforms, with centralized alarm management systems serving tertiary care wards. Health Canada's Medical Devices Directorate maintains its Ottawa headquarters, streamlining Class III device authorization for vendors targeting Ontario Health's contracting frameworks. The Waterloo-Toronto corridor concentrates firmware engineering talent for wireless monitoring platform development.
Quebec
Montreal's specialized stroke centers and trauma hospitals sustain demand for neurological monitoring systems with intracranial pressure tracking capabilities. INESSS evaluation frameworks now weight cybersecurity compliance equally with clinical efficacy in reimbursement determinations for remote monitoring solutions. Aging hospital infrastructure in Quebec City and Sherbrooke creates retrofit demand for wireless-enabled monitor replacements.
Alberta
Rural communities beyond two-hour ambulance response windows drive cellular-enabled cardiac monitor deployment with store-and-forward diagnostic capabilities. The provincial health authority's rural expansion program funds prescription-based wrist-worn monitor distribution for community-dwelling cardiac patients. Calgary's hospital networks pilot AI-enabled arrhythmia detection algorithms in ambulatory care settings.
British Columbia
Vancouver's outpatient surgical expansion diversifies procurement beyond traditional hospital networks toward compact multi-parameter units for post-anesthesia recovery. The province's mountain and coastal rural health authorities test satellite-connected monitoring for isolated communities. Victoria's diagnostic laboratories maintain steady replacement demand for Holter monitoring systems serving cardiology referral density.
Atlantic Canada
Nova Scotia and New Brunswick health authorities consolidate procurement through regional Group Purchasing Organizations for cost efficiency in smaller market scales. Federal transfer payment structures influence capital expenditure timing for bedside monitor network upgrades. Halifax anchors the region's neurocritical care capacity with limited but specialized neurological monitor deployment.
Canada Patient Monitoring Devices Market Competitive Environment
Strategic partnerships dominate the current landscape as vendors align with provincial health authorities on hospital-at-home program specifications. The vendor base organizes around three tiers: diversified medical technology conglomerates with full-platform capabilities, specialized sensor technology firms with algorithm differentiation, and emerging wearable-focused entrants targeting direct-to-homecare distribution channels. Competitive intensity concentrates on cloud platform certification velocity and cybersecurity attestation compliance rather than hardware specification alone. M&A activity and technology licensing agreements represent the primary vectors for capability expansion among mid-scale participants.
Among diversified medical technology conglomerates, GE Healthcare anchors Canadian operations through localized manufacturing capabilities serving hospital network procurement. Masimo Corporation exemplifies the specialized sensor technology archetype through proprietary signal processing algorithms that sustain premium positioning in acute care settings. Abbott Laboratories occupies a position bridging hardware and wearable platforms, targeting homecare expansion through integrated glucose and cardiac monitoring ecosystems.
| Leading Market Players |
|---|
| GE Healthcare |
| Boston Scientific Corporation |
| Medtronic PLC |
| Masimo Corporation |
| Becton, Dickinson and Company |
| Omron Corporation |
| Koninklijke Philips NV |
| Baxter International Inc. |
| Abbott Laboratories |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap sensor manufacturers anchor Canadian patient monitor assembly operations, translating captive component sourcing into disciplined pricing power against hospital procurement committees. Their ownership structure insulates margin targets from quarterly earnings pressure, allowing selective participation in Ontario Health's subscription-based telemetry tenders without capitulating on per-unit hardware economics.
Pricing Analysis
Warranty and multi-year service bundling now separates winning bids from commodity hardware-only proposals in provincial hospital network tenders. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification grade and cybersecurity attestation depth rather than raw sensor specification. Cost compression in economy-tier bedside monitors intensifies because Group Purchasing Organizations consolidate volume across aging Quebec hospital infrastructure. Homecare procurement committees show highest price sensitivity as they evaluate total cost of ownership across five-year telemetry platform licensing, while neurocritical care units in Toronto's stroke centers remain least sensitive given life-critical parameter requirements.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese foundry output for wireless SoCs and South Korean memory suppliers, creating propagation risk through domestic monitor assembly lead times. Canadian device manufacturing draws from Malaysian sensor packaging operations and Chinese PCB fabrication for telemetry hardware substrate. Tariff exposure on semiconductor components imported through USMCA corridors threatens landed cost stability for Class III networked platform vendors. Distribution runs through regional Group Purchasing Organizations in Atlantic Canada and direct provincial tender channels in Ontario and Quebec hospital-at-home programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor component concentration props pricing discipline as foundry allocation priority favors automotive and consumer electronics over medical device volumes. Supply-constrained procurement timelines force hospital networks toward multi-year platform commitments rather than spot hardware purchases.
For Market Incumbents: Deepen backward integration into domestic firmware engineering capabilities within the Waterloo-Toronto corridor to compress Health Canada Software as a Medical Device validation cycles. Secure long-term foundry allocation agreements with Taiwanese suppliers before automotive sector demand recovery accelerates. Anchor cloud platform certification velocity as the primary defensive moat against wearable-focused entrants targeting direct-to-homecare distribution. For New Entrants and Emerging Players: Enter via Alberta's rural health expansion corridor where cellular-enabled cardiac monitors with store-and-forward capabilities face minimal incumbent saturation. Target prescription-based deployment models in Saskatchewan and Manitoba community-dwelling patient programs that bypass traditional Group Purchasing Organization gatekeeping. Pursue provincial tender exceptions for hospital-at-home initiatives as the most penetrable procurement pathway. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized sensor technology firms with proprietary pulse oximetry algorithms in acute care settings where premium positioning sustains through reimbursement volatility. Long-term viability hinges on cybersecurity attestation infrastructure that satisfies Health Canada's evolving Class III mandates. Watch for AI-enabled arrhythmia detection algorithm FDA breakthrough designations as signal for ambulatory ECG segment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Class III Cybersecurity Attainment | Accelerates market authorization timelines for networked telemetry platforms serving Ontario hospital networks. |
| Provincial Hospital-at-Home Partnership | Unlocks direct distribution margins bypassing traditional Group Purchasing Organization fee structures. |
| AI-Enabled Arrhythmia Algorithm Development | Differentiates ambulatory ECG offerings previously commoditized by hardware specification competition. |
| Domestic Firmware Engineering Expansion | Compresses Software as a Medical Device validation cycles for over-the-air update architectures. |
| Multi-Analyte Wearable Platform Integration | Consolidates metabolic and cardiac biomarker tracking into unified ecosystems targeting Quebec INESSS reimbursement. |
Study Parameters
Independent corroboration across hospital procurement database analysis, Health Canada Medical Devices Directorate filing records, and provincial health technology assessment documentation underwrites the qualitative findings. Primary interviews with biomedical engineers, Group Purchasing Organization contracts managers, hospital purchasing committee chairs, and remote monitoring program directors combined with secondary validation from ISO 13485 audit registries, GPO tender award disclosures, and INESSS reimbursement determination archives. Bottom-up telemetry platform deployment estimates triangulate against top-down provincial health expenditure allocations.
Comparable-period anchoring to historical hospital capital expenditure cycles and homecare program rollout velocity shaped the projection horizon. Segmentation modeling spans product type, connectivity architecture, care setting, and clinical application dimensions with cybersecurity attestation tier as an industry-specific cross-cutting variable. CAGRs derive from installed base replacement schedules, provincial funding mandate acceleration curves, and wearable technology prescription pilot expansion trajectories. Firmware upgrade cycle frequency and cloud platform subscription conversion rates inform recurring revenue assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption scenarios and Health Canada regulatory reclassification events. Forecasts reflect documented assumptions regarding provincial hospital-at-home funding continuity and cybersecurity directive implementation timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Smart Medication Adherence Sensors Market
Patient Monitoring
Neonatal and Fetal Monitors Market
Patient Monitoring
United Kingdom Remote Patient Monitoring Market
Patient Monitoring
Drowsiness Monitoring System Market
Patient Monitoring
Patient Monitoring Systems Market
Patient Monitoring
Middle East and Africa Fetal and Neonatal Monitoring Market
Patient Monitoring
Sleep Tracking Devices Market
Patient Monitoring
Europe Hemodynamic Monitoring Market
Patient Monitoring
Telemonitoring Systems Market
Patient Monitoring
Continuous Cardiac Monitoring Devices Market
Patient Monitoring
Asia-Pacific Fetal and Neonatal Monitoring Market
Patient Monitoring
Patient Monitoring and Ultrasound Devices Display Market
Patient Monitoring
China ICU Patient Monitor Market
Patient Monitoring
Online Patient Observation Market
Patient Monitoring
MR Vital Sign Monitors Market
Patient Monitoring
Monitoring Wristband Market