
 Global Medical Transcription Software Market | 2026-2036
Global Medical Transcription Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Transcription Software Market Foresight
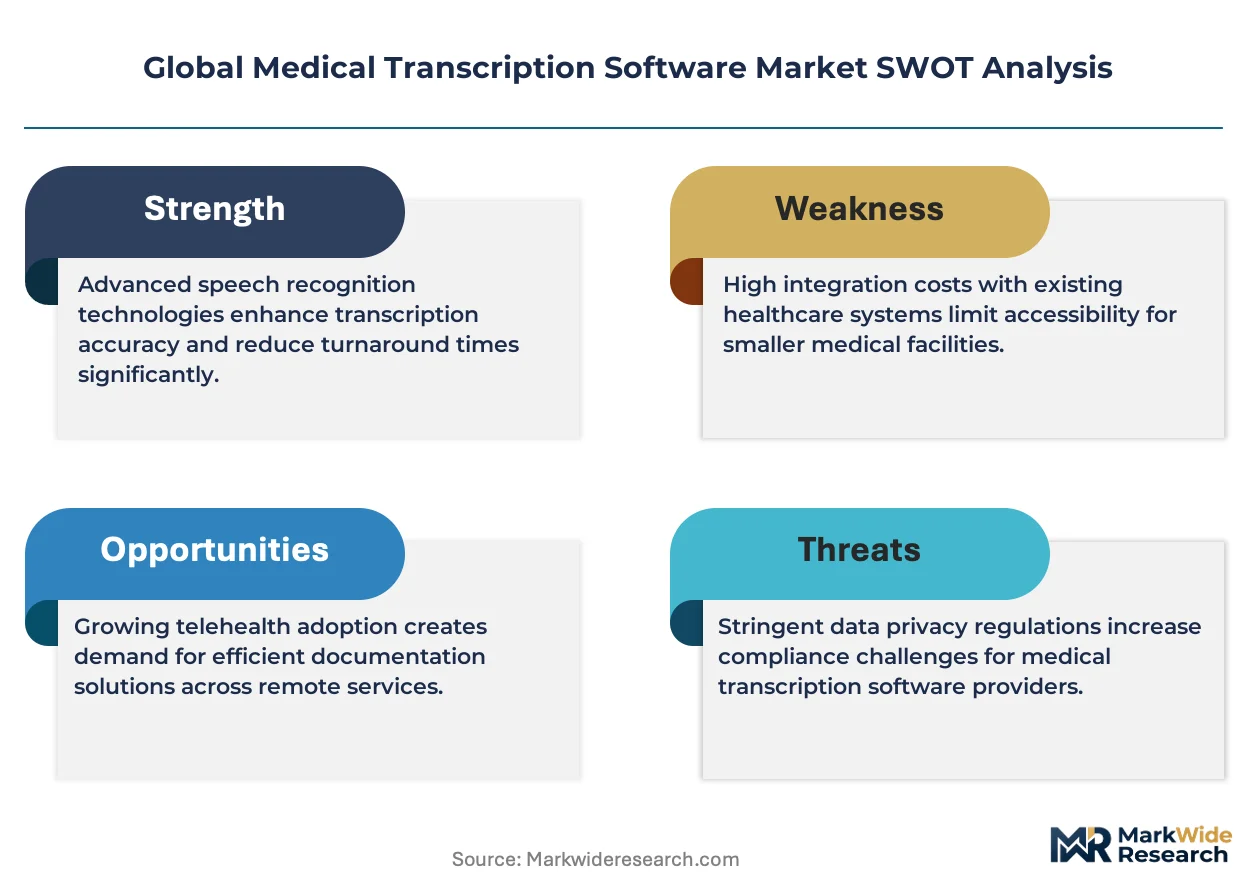
Cloud-native speech recognition paired with ambient clinical intelligence is rewriting how documentation workflows integrate with electronic health records. Microsoft Corporation leverages its Nuance acquisition to anchor enterprise-grade conversational AI across major hospital networks. Amazon Web Services, Inc. competes through AWS HealthScribe and scalable infrastructure for telehealth documentation. 3M sustains its position through deep specialization in clinical terminology engines and coding-adjacent transcription services.
Medical transcription software encompasses platforms that convert clinician dictation into structured clinical text using automatic speech recognition, natural language processing, and domain-specific medical vocabularies. These systems typically process audio at sampling rates of 16 kHz or higher, apply SNOMED CT and ICD-10 ontologies for semantic normalization, and output discrete data elements directly into EHR fields to eliminate manual re-entry. Cloud-based deployment dominates current procurement as health systems prioritize elastic scaling and reduced IT overhead, while radiology and pathology applications command premium positioning due to complex terminology requirements and subspecialist workflow integration. The enterprise deployment tier captures the deepest margin pools through multi-year contracts with integrated training and customization services.
FDA oversight of clinical decision support functions, HIPAA security rule enforcement by the Office for Civil Rights, and ONC certification requirements for EHR interoperability collectively shape product development roadmaps and market access conditions for vendors. The EU AI Act and MDR frameworks impose additional conformity obligations for any transcription software generating diagnostic or treatment recommendations within European health systems. Stakeholders must monitor how evolving liability standards for AI-generated clinical notes reshape vendor risk profiles and purchasing contract structures.
Market Dynamics
Cloud-native speech recognition paired with ambient clinical intelligence is compressing deployment timelines from eighteen months to under ninety days, forcing vendors to rearchitect delivery models around API-first integration rather than on-premise installation.
Growth Catalysts
- HIPAA Security Rule enforcement:The Office for Civil Rights has intensified audit frequency for documentation workflows, compelling health systems to replace manual transcription with auditable automated pipelines.
- Physician burnout reduction mandates:US hospital networks face accreditation pressure to reduce documentation burden, accelerating procurement of voice-to-EHR platforms that eliminate after-hours charting.
- SNOMED CT semantic normalization:Standardized clinical terminology engines enable cross-system interoperability, unlocking federal interoperability incentive payments for compliant deployments.
Market Restraints
- GPU compute cost volatility:Real-time speech recognition inference requires specialized silicon whose spot pricing fluctuates with cryptocurrency mining demand, squeezing SaaS margins.
- ONC certification friction:EHR interoperability testing adds fourteen to twenty-two months to product release cycles, freezing feature roadmaps for smaller vendors.
- Dictation habit stickiness:Subspecialist physicians in radiology and pathology exhibit entrenched workflow patterns resistant to ambient listening technologies.
Strategic Opportunities
- India's hospital digitization wave:The country's PLI scheme for medical devices creates subsidy pathways for cloud transcription platforms serving its emerging corporate hospital chains.
- Telehealth documentation automation:Asynchronous visit recordings require structured note generation without real-time clinician presence, opening subscription models for virtual-first providers.
- EU AI Act diagnostic liability carve-outs:Transcription software avoiding treatment recommendations faces lighter conformity obligations than clinical decision support tools, favoring pure documentation plays in European tenders.
Industry Challenges
- Clinical informaticist scarcity:Health systems lack personnel capable of tuning NLP models to institutional documentation conventions, forcing vendors to embed implementation teams.
- Legacy EHR API fragmentation:Proprietary data exchange protocols at older hospital systems demand costly connector development for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Transcription Software Market |
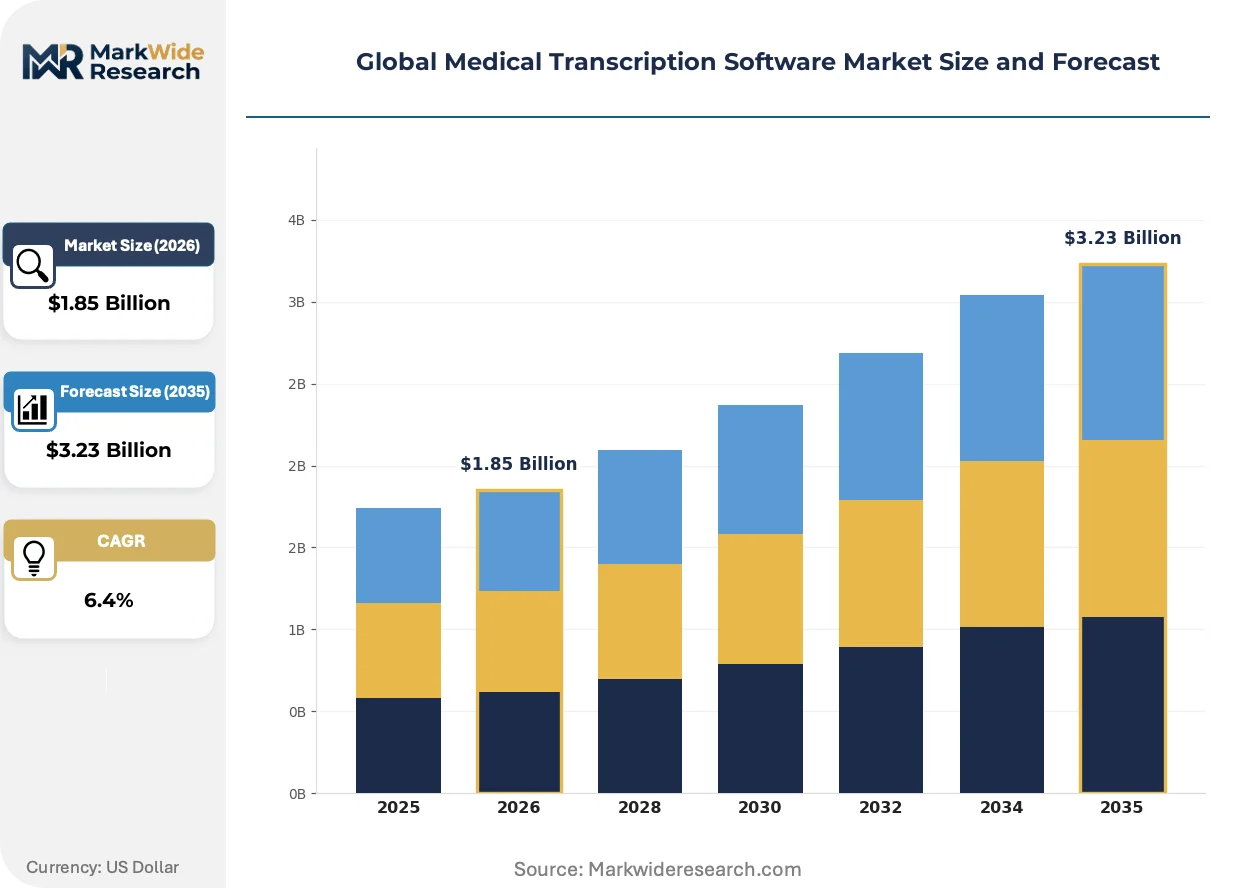
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premise, Hybrid, Mobile, Web-enabled Application: Radiology, Pathology, Cardiology, Neurology, Oncology End User: Hospitals, Clinics, Diagnostic Centers, Telehealth Providers, Research Institutes Deployment Type: Single-user, Multi-user, Enterprise, Departmental |
| Companies Covered | Microsoft Corporation (Nuance Communications, Inc.), 3M, Amazon Web Services, Inc., DeepScribe, Augmedix, NextGen Healthcare, iMedX, Aquity Solutions, Verbit.ai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Transcription Software Market Shifts & Advancements
Documentation workflow architecture is bifurcating between ambient multimodal systems that capture entire encounters and specialized dictation tools optimized for high-complexity subspecialties.
Large language model fine-tuning for clinical domains is migrating from general-purpose foundation models to medically pre-trained architectures that incorporate ICD-10 and SNOMED CT embeddings during initial training rather than post-hoc adaptation. Academic medical centers in the United States are piloting these systems for operative note generation, compressing documentation time from twenty-three minutes to under four per case. The structural consequence is collapsing differentiation between transcription pure-plays and full-stack EHR vendors.
The EU AI Act risk classification framework imposes conformity assessment obligations on transcription software generating diagnostic impressions, forcing vendors to either excise interpretation capabilities or pursue notified body certification. German hospital procurement offices now require MDR-aligned technical documentation for any AI-assisted coding functionality. Radiology departments across France, Germany, and the Netherlands are delaying purchasing decisions pending clarity on liability allocation between software vendors and interpreting physicians.
Hospital purchasing committees are consolidating vendor relationships around platforms offering transcription, coding, and quality analytics as unified subscriptions rather than point solutions. Integrated delivery networks in the United States favor multi-year enterprise agreements with dedicated customer success resources over transactional SaaS licensing. This concentration is most pronounced among nonprofit health systems with centralized IT governance structures.
Global Medical Transcription Software Market Segmentation
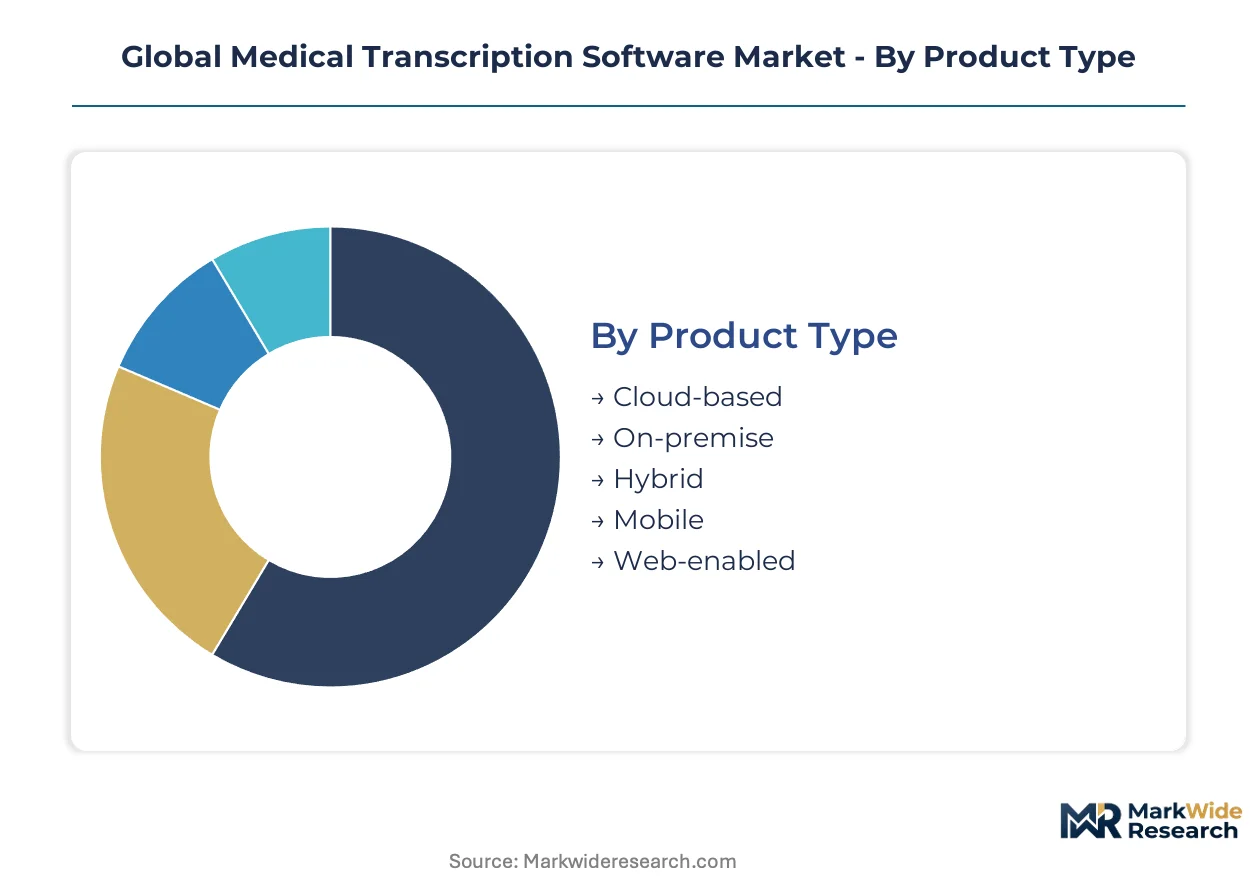
Segmentation in medical transcription software reveals divergent procurement cycles and margin structures across deployment models and clinical specialties. Cloud-native architectures compress implementation timelines while subspecialty applications command premium pricing due to terminology complexity.
Product Type:
Cloud-based platforms turn over procurement contracts fastest at ninety-day cycles, while on-premise installations stretch across eighteen to twenty-four months with heavy customization.
- Cloud-based:Elastic infrastructure enables HIPAA-compliant scaling without capital expenditure. Large US hospital networks favor this model for reduced IT overhead and automatic security patching. Federal interoperability mandates accelerate replacement of legacy systems.
- On-premise:Air-gapped installations serve defense health systems and research institutes with classified data requirements. High upfront licensing and perpetual maintenance contracts create sticky revenue but slower refresh cycles.
- Hybrid:Sensitive dictation processes locally while leveraging cloud NLP for non-PHI workloads.
- Mobile:Point-of-care capture for ambulatory workflows with offline synchronization capabilities.
- Web-enabled:Browser-based access eliminating client-side installation for distributed clinical teams.
Cloud-based deployments anchor the volume base while mobile solutions gain share at the steepest rate.
Application:
Cost tier stratification separates high-complexity subspecialties with dedicated terminology engines from general medical documentation with standardized vocabularies.
- Radiology:Structured reporting templates integrate with PACS workstations, requiring DICOM compatibility and subspecialist workflow customization. Academic medical centers in the United States drive demand for AI-assisted impression generation.
- Pathology:Synoptic reporting for cancer protocols demands SNOMED CT mapping to CAP checklists. German university hospitals lead European adoption for molecular pathology documentation.
- Cardiology:Integration with hemodynamic monitoring systems and structured cath lab reporting.
- Neurology:EEG and EMG correlation with narrative findings for seizure and movement disorder documentation.
- Oncology:Chemotherapy regimen documentation tied to billing code accuracy for infusion centers.
Radiology maintains the deepest installed base while pathology shows the steepest expansion trajectory among subspecialty applications.
End User:
Customer type determines contract structure, with integrated delivery networks consolidating vendors while independent clinics prioritize per-seat flexibility.
- Hospitals:Enterprise agreements span transcription, coding, and quality analytics as unified subscriptions. Nonprofit health systems with centralized IT governance drive multi-year procurement.
- Clinics:Small-practice SaaS licensing with minimal implementation support and month-to-month terms.
- Diagnostic Centers:High-volume radiology and pathology groups requiring turnaround time guarantees.
- Telehealth Providers:Asynchronous visit documentation without real-time clinician presence.
- Research Institutes:Protocol-specific data capture with CDISC compliance for clinical trials.
Hospitals dominate current revenue concentration while telehealth providers expand most quickly among emerging customer categories.
Deployment Type:
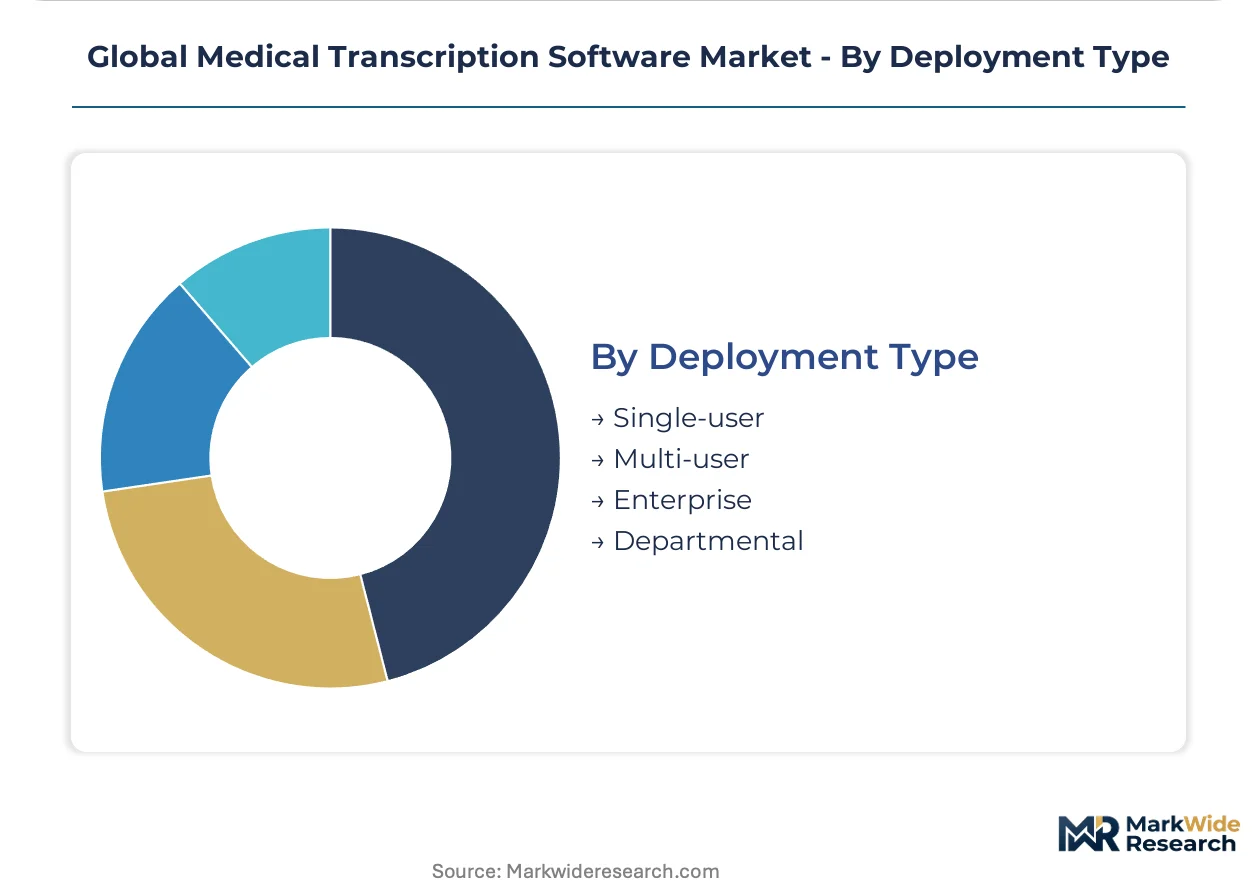
Volume concentration sits with enterprise installations serving thousands of concurrent users, though departmental deployments offer faster pilot-to-production pathways.
- Enterprise:Multi-hospital networks with dedicated customer success resources and custom NLP model tuning. These contracts capture the deepest margin pools through three to five year terms.
- Departmental:Single-service-line pilots that expand organization-wide upon demonstrated ROI in documentation time reduction.
- Multi-user:Mid-size group practices with shared vocabulary management across specialties.
- Single-user:Individual physician dictation with personal vocabulary training.
Enterprise deployments anchor the volume base while departmental configurations gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States drive the largest contract volumes, while Germany and India represent contrasting expansion archetypes shaped by regulatory frameworks and digitization subsidies.
United States
Integrated delivery networks consolidate vendor relationships around unified transcription-coding-analytics subscriptions. HIPAA Security Rule enforcement by the Office for Civil Rights accelerates replacement of manual documentation workflows. The Mayo Clinic and Cleveland Clinic anchor demand for ambient clinical intelligence platforms with multi-year enterprise terms.
Germany
University hospitals in Bavaria and Baden-Württemberg pilot AI-assisted pathology documentation tied to CAP synoptic reporting protocols. The EU AI Act and MDR frameworks impose conformity assessment obligations on diagnostic impression generation. Charité Berlin and Heidelberg University Hospital lead procurement for structured cancer reporting systems.
India
Corporate hospital chains in Maharashtra and Karnataka expand cloud transcription procurement under the PLI scheme for medical devices. The country's national health regulator emphasizes data localization requirements for patient records. Apollo Hospitals and Max Healthcare in Delhi-NCR drive demand for voice-to-EHR platforms serving telehealth workflows.
United Kingdom
NHS trusts in London and the Midlands prioritize API-first integration with legacy EHR systems. GDPR compliance frameworks shape vendor selection for cloud-hosted clinical documentation. Guy's and St Thomas' NHS Foundation Trust anchors pilot programs for operative note automation using medically pre-trained language models.
Japan
Academic medical centers in Tokyo and Osaka adopt speech recognition for radiology structured reporting integrated with PACS workstations. METI guidelines on healthcare AI safety influence procurement specifications for diagnostic-adjacent transcription tools. Keio University Hospital and Osaka University Hospital drive demand for subspecialty terminology engines.
Global Medical Transcription Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Cloud hyperscalers leverage infrastructure dominance to bundle transcription with broader health cloud offerings. Clinical terminology specialists sustain margin pools through deep coding-adjacent integration. Ambient intelligence pure-plays compress deployment timelines through API-first architectures. Consolidation pressure intensifies as health systems demand unified documentation-to-revenue-cycle platforms, forcing point-solution vendors toward strategic partnerships or acquisition.
Within the infrastructure-anchored tier, Microsoft Corporation and Amazon Web Services, Inc. occupy positions that exemplify platform leverage over specialized workflow tools. Microsoft leverages its Nuance acquisition to anchor enterprise-grade conversational AI across major hospital networks. Amazon Web Services competes through AWS HealthScribe and scalable infrastructure for telehealth documentation. 3M sustains its position through deep specialization in clinical terminology engines, representing the coding-adjacent archetype that resists pure-platform displacement.
| Leading Market Players |
|---|
| Microsoft Corporation (Nuance Communications, Inc.) |
| 3M |
| Amazon Web Services, Inc. |
| DeepScribe |
| Augmedix |
| NextGen Healthcare |
| iMedX |
| Aquity Solutions |
| Verbit.ai |
| Others |
Supply & Pricing Matrix
GPU foundry capacity concentrates in Taiwan and South Korea, concentrating inference cost leverage with NVIDIA and TSMC while SaaS vendors absorb spot pricing volatility through annual contract lock-ins. This upstream silicon scarcity forces transcription platforms to tier customer commitments by compute reservation, embedding margin protection into multi-year enterprise terms.
Pricing Analysis
Cost-plus contracts indexed to cloud compute spot rates dominate enterprise procurement, with HIPAA compliance tiering and SNOMED CT engine customization as primary price differentiation drivers. Pricing pressure stems from GPU spot rate spikes tied to cryptocurrency mining cycles, squeezing SaaS margins unless hedged through reserved capacity. Independent clinics exhibit highest price sensitivity, while integrated delivery networks accept premium positioning for dedicated customer success resources.
Supply Chain Analysis
Upstream feedstock for speech recognition inference draws from Taiwan semiconductor foundries, South Korean memory fabrication, and US-based cloud hyperscaler infrastructure. Critical dependencies include NVIDIA A100/H100 accelerators, high-bandwidth memory modules, and fiber-optic submarine cables for transcontinental data transit. Single-source vulnerability concentrates in advanced node GPU supply, while distribution runs through direct hyperscaler marketplaces and channel partner systems integrators serving hospital IT departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical transcription software functions as a service-attach play where NLP model retraining subscriptions and compliance audit support expand faster than base platform licensing. The recurring revenue layer deepens customer lifetime value as health systems prioritize continuous regulatory alignment over perpetual licenses.
For Market Incumbents: Insulate enterprise relationships by embedding implementation teams that tune domain-specific vocabularies to institutional documentation conventions. Pursue backward integration into clinical terminology engines through acquisition of coding-adjacent specialists, countering displacement risk from ambient intelligence pure-plays. Secure multi-year contracts with compute cost pass-through clauses to defend margins against GPU spot volatility.
For New Entrants and Emerging Players: Mid-market corporate hospital chains in India represent the most penetrable entry point, with PLI scheme subsidies reducing customer acquisition friction and data localization requirements favoring regional cloud partnerships. Telehealth-first virtual providers in the United States offer second white-space targeting, with asynchronous documentation needs underserved by real-time ambient systems. Lead with API-first integration messaging to compress pilot-to-production timelines against incumbent deployment cycles.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed clinical documentation pure-plays lacking ambient intelligence capabilities or coding integration. Long-term viability over a multi-year horizon hinges on convergence toward unified documentation-to-revenue-cycle platforms. Monitor ONC certification timeline clarity as inflection signal—accelerated interoperability mandates favor consolidated vendors with compliance resources, while extended friction preserves fragmentation.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified transcription-coding-analytics bundles capture hospital procurement consolidation toward single-vendor relationships. |
| Strategic Partnership | Hyperscaler alliances with AWS or Azure embed transcription within broader health cloud commitments, reducing standalone sales friction. |
| Acquisition of Specialist Firm | Clinical terminology engine targets deepen moats against ambient intelligence displacement in radiology and pathology subspecialties. |
| Geographic Expansion | India PLI scheme alignment and data localization compliance unlock corporate hospital chain procurement in Maharashtra and Karnataka. |
| Product Launch | EU AI Act-constrained diagnostic impression modules require notified body certification, creating regulated product tier separation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings from publicly traded health IT vendors, CMS Medicare reimbursement databases, and ONC certification records. Primary interviews engaged hospital CIOs, clinical informaticists, GPO contracts managers, and NLP platform engineers across integrated delivery networks and academic medical centers. Bottom-up deployment counts by health system were triangulated against top-down market sizing from hyperscaler health cloud revenue disclosures.
Forecast inputs span deployment model segmentation across cloud-native, hybrid, and on-premise architectures; end-user tiering from enterprise IDNs to independent clinics; and regional adoption patterns tied to interoperability mandate timelines. CAGRs were derived from elasticity modeling of documentation burden reduction ROI against platform subscription costs across the projection horizon. Industry-specific inputs include HIPAA audit frequency trends and EU AI Act risk classification implementation pacing.
Stress conditions across GPU spot pricing volatility, ONC certification timeline extensions, and physician workflow adoption resistance were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding federal interoperability incentive continuity and cloud hyperscaler capacity expansion commitments. Cross-checking against hospital procurement database contract values is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Healthcare Mobile Computers Market
Medical Information Systems
Medical Saas System Market
Medical Information Systems
Ophthalmology EMR Software Market
Medical Information Systems
Medical Alert Systems Market
Medical Information Systems
Global Clinical Documentation Improvement Market
Medical Information Systems
Medical Information Market
Medical Information Systems
Global Medical Scheduling Software Market
Medical Information Systems
Global Cardiovascular Information System Market
Medical Information Systems
Global Pharmacy Information System Market
Medical Information Systems
Medical Talent Management IT Market
Medical Information Systems
Global Medical Document Management Systems Market
Medical Information Systems
Medical Simulation Software Market
Medical Information Systems
Global Medical Decision Support Systems for Sepsis Market
Medical Information Systems
Case Coder Market
Medical Information Systems
India EMR (Electronic Medical Records) Market
Medical Information Systems
Healthcare Information Software Market