
 Medical 3D Software Market | 2026-2036
Medical 3D Software Market Size, Share, and Industry Trends Forecast 2026-2036
Medical 3D Software Market Insights
FDA 510(k) premarket notification requirements is bifurcating the competitive landscape between established platform vendors and emerging point-solution developers. Materialise NV leverages its decades-long regulatory dossier to sustain hospital purchasing committee confidence across European and North American accounts. Siemens Healthineers anchors its position through deep integration with existing imaging modality workflows, while 3D Systems competes via specialized dental and cranio-maxillofacial application modules that occupy high-margin niches.
Medical 3D software encompasses computational platforms that convert DICOM imaging datasets into volumetric models, mesh structures, or simulation-ready geometries using algorithms such as marching cubes reconstruction and finite element analysis. These tools serve primarily to enable patient-specific surgical planning, prosthetic customization, and additive manufacturing file preparation in regulated healthcare environments. Visualization software dominates current hospital IT budgets due to its direct integration with radiology PACS infrastructure, whereas simulation software represents the fastest-expanding category as virtual surgical rehearsal gains traction in complex orthopedic and cardiovascular procedures. Cloud-based solutions are capturing disproportionate growth among mid-tier medical device manufacturers seeking scalable computational resources without capital-intensive on-premise deployments.
FDA, EMA, and ISO 13485 quality management standards collectively shape product development cycles, with FDA's emerging guidance on 3D-printed medical devices directly influencing software validation requirements for patient-specific outputs. The EU Medical Device Regulation imposes additional clinical evidence burdens that extend certification timelines for visualization and analysis platforms marketed in Europe. Stakeholders must monitor evolving software-as-a-medical-device classifications in major jurisdictions to anticipate compliance cost trajectories and competitive barrier shifts.
Market Dynamics
Cloud-native computational architectures are compressing capital barriers for mid-tier manufacturers while simultaneously fragmenting purchasing authority across hospital IT, surgical departments, and procurement committees.
Growth Catalysts
- Japan's reimbursement expansion:METI-aligned coverage frameworks for patient-specific implants are validating software expenditures in orthopedic and cranio-maxillofacial workflows.
- FDA 510(k) pathway streamlining:Pre-market notification efficiencies for surgical guides are accelerating vendor qualification cycles and reducing time-to-revenue for visualization platforms.
- Finite element analysis convergence:Real-time biomechanical simulation modules are displacing static anatomical models in pre-surgical rehearsal protocols.
Market Restraints
- ISO 13485 compliance costs:Quality management system documentation for software-as-a-medical-device classifications imposes six-figure certification burdens on specialized developers.
- GPU compute price volatility:Cloud rendering dependencies expose mid-tier vendors to NVIDIA hardware supply constraints and spot-pricing fluctuations.
- Substitution by open-source meshing:Free alternatives such as 3D Slicer are capturing academic medical center budgets and compressing commercial licensing margins.
Strategic Opportunities
- India's hospital digitization:CDSCO regulatory harmonization with IMDRF standards is creating first-mover advantages for DICOM-to-mesh platforms in tier-2 metropolitan clusters.
- AI-assisted segmentation:Deep learning autosegmentation is converging with traditional marching cubes reconstruction to reduce manual annotation labor by surgical planning teams.
- Germany's DiPA pathway:The Digital Health Applications fast-track is reimbursing software-enabled surgical planning, opening institutional procurement channels previously reserved for capital equipment.
Industry Challenges
- Computational pathology skill scarcity:Hybrid expertise spanning radiology informatics and additive manufacturing file preparation commands salary premiums that strain vendor hiring pipelines.
- PACS integration complexity:Legacy radiology archive systems require custom HL7 FHIR middleware development, extending implementation timelines and eroding project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical 3D Software Market |
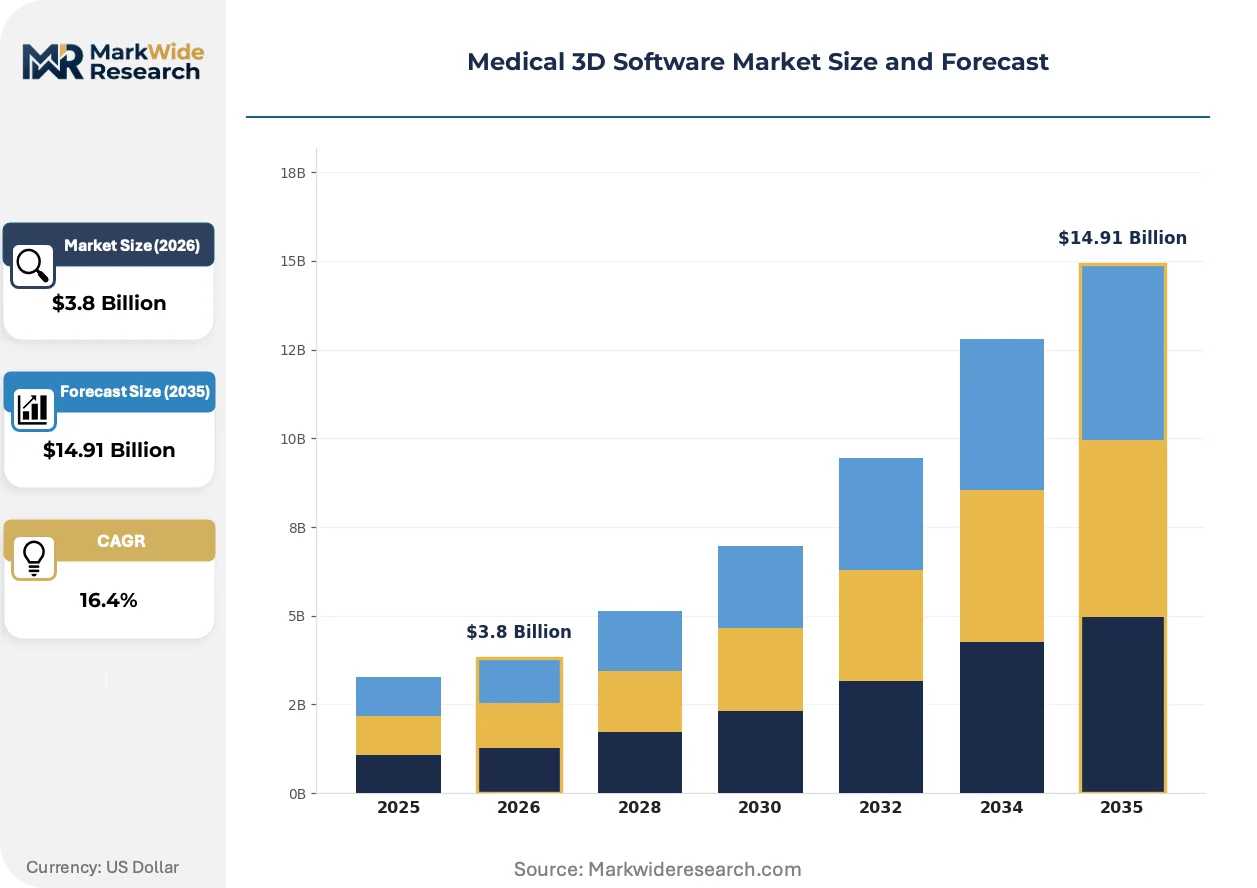
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Visualization Software, Simulation Software, Design Software, Analysis Software Application: Surgical Planning, Prosthetic Design, Medical Imaging, Manufacturing Supports End User: Hospitals, Research Institutions, Medical Device Manufacturers, Educational Institutions Technology: Cloud-Based Solutions, Desktop Solutions, AR-Based Solutions, VR-Based Solutions |
| Companies Covered | Materialise NV, 3D Systems, Stratasys, Formlabs, GE Healthcare, Siemens Healthineers, Koninklijke Philips NV, Canon Medical Systems, Agfa-Gevaert, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical 3D Software Market Trends and Innovations
Generative mesh optimization and real-time haptic feedback are compressing the boundary between pre-operative visualization and intra-operative navigation, reshaping how surgical teams consume anatomical intelligence.
Neural radiance fields (NeRF) are displacing traditional surface mesh reconstruction in cranial and thoracic applications. Academic medical centers in Boston and Heidelberg are piloting volumetric neural rendering for complex tumor margin delineation. The technology is displacing conventional segmentation workflows by eliminating manual threshold tuning and reducing file preparation from hours to minutes.
The EU Medical Device Regulation's software-specific annexes are extending clinical evidence requirements for patient-specific output modules. European notified bodies are demanding prospective validation studies for algorithms generating surgical guide geometries. Visualization platforms marketed in France and the Netherlands are responding by embedding ISO 14971 risk management documentation directly into release pipelines.
Subscription-based licensing is displacing perpetual seat licenses among mid-tier orthopedic device manufacturers. Annual recurring revenue models are capturing procurement budgets previously allocated to capital expenditure cycles. This transition is most visible in the United States, where hospital supply chain committees are consolidating software vendors under enterprise framework agreements that bundle visualization, simulation, and additive manufacturing preparation modules.
Medical 3D Software Market Segmentation
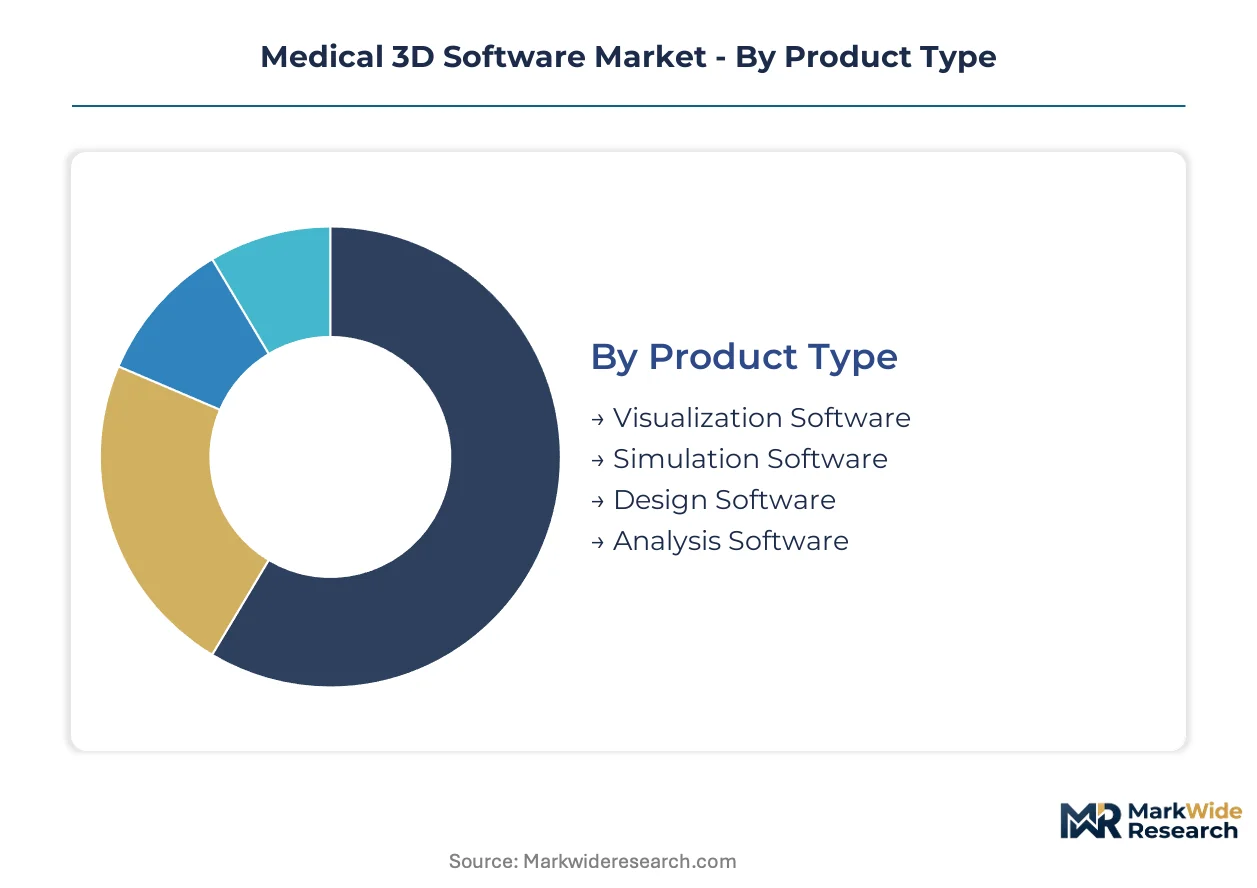
Segmentation in medical 3D software reveals how procurement authority fragments across hospital IT departments, surgical units, and device manufacturers. Each dimension—product, application, end user, and technology—carries distinct margin profiles and regulatory burdens that reshape vendor go-to-market strategies.
Product Type:
Channel mix varies sharply: visualization platforms flow through radiology PACS integrators, while simulation modules sell direct to surgical departments bypassing traditional IT procurement.
- Visualization Software:Converts DICOM datasets into volumetric models using marching cubes reconstruction. Demand clusters in United States hospital systems integrating with legacy PACS infrastructure, constrained by HL7 FHIR middleware development costs.
- Simulation Software:Enables finite element analysis and virtual surgical rehearsal through biomechanical modeling. German orthopedic centers are expanding procurement fastest under DiPA reimbursement pathways for pre-operative planning.
- Design Software:Generates patient-specific geometries for additive manufacturing file preparation.
- Analysis Software:Performs computational validation of implant fit and stress distribution.
Visualization Software dominates installed base. Simulation Software is where expansion concentrates.
Application:
Cost tier stratification separates high-margin patient-specific workflows from commoditized imaging support functions.
- Surgical Planning:Patient-specific pre-operative rehearsal using volumetric neural rendering and haptic feedback. Japan's METI-aligned reimbursement frameworks are validating software expenditures in cranio-maxillofacial workflows.
- Prosthetic Design:Custom implant geometry generation with ISO 13485-compliant documentation pipelines. FDA 510(k) pathway streamlining is accelerating vendor qualification cycles for patient-specific outputs.
- Medical Imaging:DICOM-to-mesh conversion for diagnostic annotation and tumor margin delineation.
- Manufacturing Supports:Build preparation and support structure optimization for metal and polymer additive systems.
Surgical Planning commands premium pricing. Prosthetic Design is climbing the fastest as regulatory pathways mature.
End User:
Customer type determines sales cycle length and compliance documentation intensity.
- Hospitals:Enterprise procurement committees consolidate visualization, simulation, and manufacturing modules under framework agreements. United States supply chain committees are shifting from perpetual licenses to subscription models.
- Medical Device Manufacturers:Mid-tier orthopedic firms are adopting cloud-native architectures to avoid capital-intensive on-premise GPU clusters.
- Research Institutions:Academic medical centers in Boston and Heidelberg pilot neural radiance field reconstruction.
- Educational Institutions:Training programs for computational pathology and additive manufacturing file preparation.
Hospitals anchor volume. Medical Device Manufacturers are gaining share fastest as cloud deployment lowers entry barriers.
Technology:
Maturity curves separate established desktop deployments from emerging immersive interfaces.
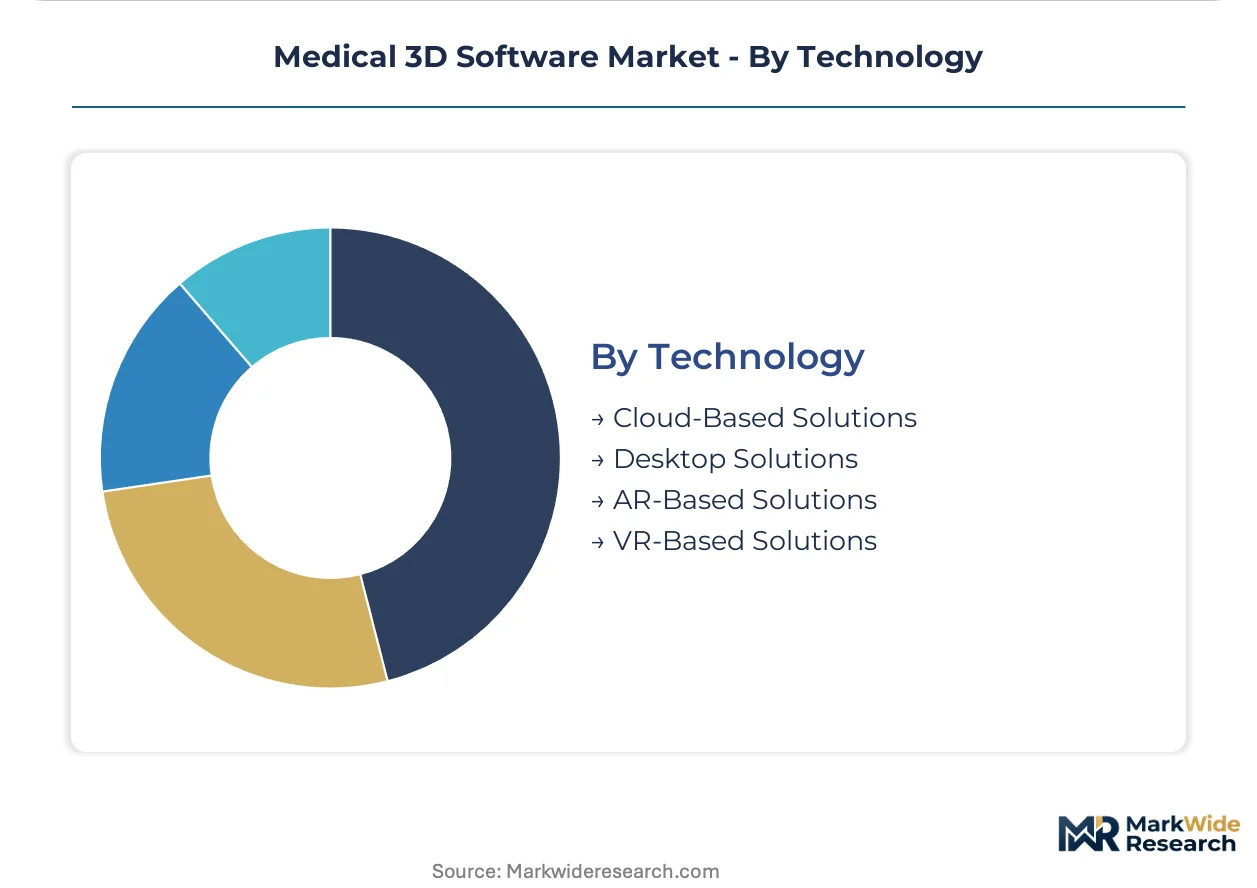
- Cloud-Based Solutions:Scalable computational resources for finite element analysis without captive GPU infrastructure. India's tier-2 metropolitan clusters are adopting these platforms as CDSCO harmonizes with IMDRF standards.
- Desktop Solutions:On-premise installations with full data sovereignty for sensitive patient datasets.
- AR-Based Solutions:Intra-operative overlay of 3D anatomical models onto surgical fields.
- VR-Based Solutions:Immersive surgical rehearsal environments with real-time haptic feedback.
Desktop Solutions retain majority installed base. Cloud-Based Solutions are expanding most quickly among mid-tier manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement frameworks for patient-specific implants are reshaping procurement patterns across major healthcare systems. Software expenditures gain institutional validation where regulatory pathways for 3D-printed surgical guides have matured. The analysis identifies five countries where policy alignment with additive manufacturing workflows is concentrating market development.
United States
Hospital supply chain committees are consolidating visualization, simulation, and manufacturing modules under enterprise framework agreements. FDA 510(k) premarket notification efficiencies are accelerating vendor qualification cycles for surgical planning platforms. Academic medical centers in Boston pilot neural radiance field reconstruction for complex tumor margin delineation.
Germany
Orthopedic centers are expanding procurement of finite element analysis modules under DiPA reimbursement pathways for pre-operative planning. EMA software-specific annexes are extending clinical evidence requirements for patient-specific output modules. The Heidelberg cluster anchors validation studies for algorithms generating surgical guide geometries.
Japan
METI-aligned coverage frameworks for patient-specific implants are validating software expenditures in cranio-maxillofacial workflows. PMDA regulatory harmonization with IMDRF standards is streamlining certification timelines for DICOM-to-mesh platforms. Tokyo metropolitan hospitals are deploying cloud-native architectures for virtual surgical rehearsal.
India
CDSCO regulatory harmonization with IMDRF standards is creating first-mover advantages for visualization platforms in tier-2 metropolitan clusters. The country's national pharmaceutical regulator is aligning quality management documentation with ISO 13485 benchmarks. Bangalore and Hyderabad are emerging as adoption centers for scalable computational resources without capital-intensive on-premise GPU deployments.
United Kingdom
NHS supply chain frameworks are shifting procurement from perpetual licenses to subscription models for mid-tier orthopedic device manufacturers. MHRA post-Brexit regulatory autonomy is maintaining alignment with EU Medical Device Regulation software validation requirements. The London-Southeast corridor concentrates pilot programs for AI-assisted segmentation converging with traditional marching cubes reconstruction.
Medical 3D Software Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with captive imaging modality ecosystems. Market structure exhibits tiered concentration where regulatory dossier depth separates established platform vendors from emerging point-solution developers. Two strategic archetypes dominate: imaging-anchored conglomerates leveraging PACS integration, and specialized additive manufacturing software houses occupying high-margin cranio-maxillofacial niches. Competitive moves center on cloud-native architecture deployment and AI-assisted segmentation module acquisition.
Within the regulatory-dossier tier, Materialise NV and Siemens Healthineers exemplify contrasting positioning strategies. The Belgian firm leverages decades-long FDA and EMA filing histories to sustain hospital purchasing committee confidence across European and North American accounts. The German conglomerate anchors its position through deep integration with existing imaging modality workflows rather than standalone software sales. 3D Systems occupies a specialized position among additive manufacturing software houses, with its corporate structure reflecting historical roots in stereolithography hardware before portfolio diversification into dental and cranio-maxillofacial application modules.
| Leading Market Players |
|---|
| Materialise NV |
| 3D Systems |
| Stratasys |
| Formlabs |
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips NV |
| Canon Medical Systems |
| Agfa-Gevaert |
| Others |
Pricing and Supply Chain Analysis
Cloud-native computational architectures displacing on-premise GPU clusters are redrawing supply geography toward hyperscaler data centers in the United States and Germany while compressing pricing premiums previously commanded by captive hardware infrastructure. This substitution simultaneously fragments purchasing authority across hospital IT committees and surgical departments, eroding traditional vendor lock-in economics.
Pricing Analysis
Certification level (ISO 13485/FDA-grade) creates the primary spread between enterprise visualization platforms and point-solution developers. Three-tier pricing structure across premium, standard, and economy levels tracks regulatory dossier depth and PACS integration maturity. Cost compression in mid-tier simulation modules is intensifying because open-source meshing alternatives capture academic medical center budgets. Medical device manufacturers exhibit highest price sensitivity due to capital expenditure constraints, while hospital surgical departments show lowest sensitivity where DiPA and METI-aligned reimbursement frameworks validate software expenditures.
Supply Chain Analysis
Inbound logistics costs for NVIDIA GPU hardware through Los Angeles and Rotterdam ports expose mid-tier vendors to container availability volatility and spot-pricing fluctuations. Software development concentrates in the United States, Belgium, and Germany where regulatory expertise clusters. Supply chains draw from cloud hyperscaler infrastructure, specialized DICOM parsing libraries, and finite element analysis compute kernels. Single-source vulnerability sits with NVIDIA hardware supply constraints for real-time rendering workloads. Distribution runs through radiology PACS integrators for visualization platforms and direct surgical department sales for simulation modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across hospital IT, surgical departments, and device manufacturer procurement committees creates multiple niche entry points. Cloud deployment lowering capital barriers accelerates this splintering.
For Market Incumbents: Consolidate regulatory dossier depth through ISO 14971 risk management documentation embedded in release pipelines. Acquire AI-assisted segmentation modules to defend against neural radiance field displacement in cranial applications. Deepen PACS integration moats via HL7 FHIR middleware investments that extend implementation timelines for challengers. For New Entrants and Emerging Players: Anchor in India's tier-2 metropolitan clusters where CDSCO harmonization with IMDRF standards creates first-mover windows without entrenched vendor relationships. Target cloud-native finite element analysis for mid-tier orthopedic manufacturers seeking scalable computational resources. Pursue channel partnerships with additive manufacturing hardware distributors to bypass direct hospital procurement complexity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed additive manufacturing software houses occupying cranio-maxillofacial niches. Five-to-ten year viability hinges on reimbursement pathway maturation rather than technology differentiation alone. Monitor FDA 510(k) clearance velocity for surgical guide platforms as inflection indicator for enterprise valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Segmentation Module Acquisition | Deep learning autosegmentation reduces manual annotation labor by surgical planning teams in Boston and Heidelberg academic centers. |
| Cloud-Native Architecture Deployment | Scalable computational resources bypass capital-intensive on-premise GPU clusters for mid-tier orthopedic device manufacturers. |
| DiPA Reimbursement Pathway Alignment | German Digital Health Applications fast-track opens institutional procurement channels previously reserved for capital equipment. |
| PACS Integration Partnership | HL7 FHIR middleware development extends implementation timelines and erodes project margins for competitors lacking radiology archive connectivity. |
| ISO 13485 Certification Investment | Quality management system documentation sustains hospital purchasing committee confidence across European and North American accounts. |
Research Methodology
Operator-level perspectives from hospital purchasing committee chairs, surgical planning department heads, biomedical engineers at additive manufacturing centers, and GPO contracts managers anchored the qualitative base. These primary inputs combined with secondary validation from FDA 510(k) filings, EMA software-specific annex submissions, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up vendor revenue triangulation against top-down healthcare IT expenditure estimates established market sizing boundaries.
Sensitivity analysis across deployment model, organization size, vertical application, and regional adoption pattern shaped the analytical framework. Segmentation dimensions modeled include product type, application workflow, end-user archetype, and technology architecture across the projection horizon. CAGRs derived from regression analysis of historical procurement cycles and reimbursement pathway maturation trajectories. Forecast inputs incorporate neural radiance field adoption curves and cloud infrastructure cost compression rates.
Underlying assumptions cover regulatory pathway streamlining continuity, GPU hardware supply stabilization, and reimbursement framework expansion, with deviation risk concentrated in ISO 13485 compliance cost inflation and open-source substitution acceleration. Recalibration cycles align with material shifts in FDA guidance issuance and notified body interpretation changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Global Clinical Documentation Improvement Market
Medical Information Systems
Global Clinical EHR Systems Market
Medical Information Systems
Healthcare ERP Market
Medical Information Systems
Global Healthcare Information Systems Market
Medical Information Systems
Global Healthcare Software As a Service Market
Medical Information Systems
Global Pharmacy Information System Market
Medical Information Systems
Mobile Medical Apps Market
Medical Information Systems
Global Medical Transcription Software Market
Medical Information Systems
Global Computerized Physician Order Entry Market
Medical Information Systems
ICD-10 Market
Medical Information Systems
Artificial Intelligence in Medical Software Market
Medical Information Systems
Global Medical Document Management Systems Market
Medical Information Systems
Donor Management Software Market
Medical Information Systems
AI Medical Service Market
Medical Information Systems
Medical Saas System Market
Medical Information Systems
US Medical Coding Market