
 Donor Management Software Market | 2026-2036
Donor Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Donor Management Software Market Outlook
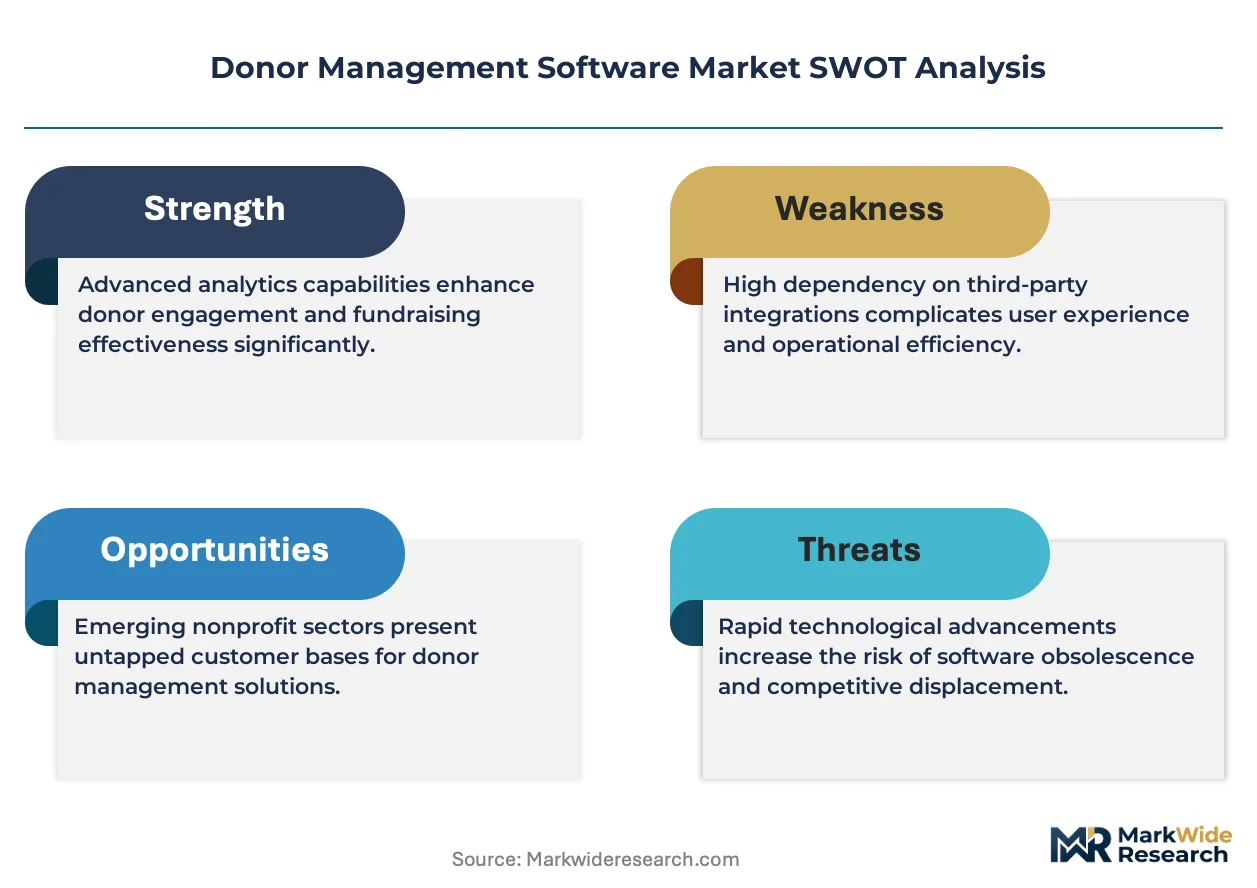
The functional gap between premium donor management suites and commodity fundraising tools is shifting toward integration depth and AI-driven engagement scoring. Blackbaud Raiser's Edge NXT anchors the premium tier through deep vertical integration with advancement services. Salesforce Nonprofit Cloud leverages its platform ecosystem to compete across mid-market and enterprise segments. Bloomerang specializes in usability-focused design for smaller nonprofits, occupying a distinct price-performance niche.
Donor management software constitutes a specialized constituent relationship management platform engineered for fundraising operations, incorporating gift processing, donor segmentation, campaign tracking, and automated stewardship workflows with SOC 2 Type II security certification. Cloud-based deployment leads structural growth as nonprofits abandon server maintenance burdens and demand elastic capacity during giving seasons. Subscription-based delivery models concentrate recurring revenue pools, while data analytics capabilities within technology segments command premium pricing due to predictive giving intelligence.
US nonprofits navigate IRS 990 filing requirements alongside state-level charitable solicitation registrations that mandate audit-ready donation records. HIPAA intersects with healthcare foundation operations, while GDPR and emerging US state privacy laws constrain cross-border donor data flows. Stakeholders must monitor evolving AI disclosure mandates affecting automated donor outreach before committing to platform roadmaps.
Market Dynamics
Cloud migration mandates under data sovereignty frameworks are forcing procurement rewrites across nonprofit advancement offices, compressing on-premise infrastructure lifecycles while elastic capacity requirements reshape vendor selection criteria.
Growth Catalysts
- IRS 990 Compliance Automation:US nonprofits face intensified audit scrutiny on donation documentation, driving demand for audit-ready record systems with automated gift receipt generation.
- AI-Driven Engagement Scoring:Machine learning algorithms now predict donor propensity with precision that manual segmentation cannot match, embedding predictive intelligence into core platform roadmaps.
- Higher Education Modernization:University advancement offices are replacing legacy alumni databases with integrated advancement suites capable of multi-channel stewardship orchestration.
Market Restraints
- Data Sovereignty Fragmentation:GDPR in Europe and emerging US state privacy laws create conflicting cross-border data flow requirements that complicate multi-national nonprofit operations.
- Specialized Talent Scarcity:The intersection of fundraising operations and database administration skills remains thin, inflating implementation costs and extending deployment timelines.
- Server Infrastructure Stranding:Organizations with recent on-premise investments face accelerated depreciation as cloud-native competitors deliver superior total cost of ownership.
Strategic Opportunities
- Healthcare Foundation Expansion:HIPAA-covered healthcare foundations represent an underpenetrated vertical requiring specialized compliance modules that generalist platforms lack.
- Mobile-First Donor Engagement:Text-to-give and mobile-responsive donor portals capture younger donor cohorts that desktop-centric legacy systems fail to reach.
- State-Level Privacy Harmonization:Emerging US state privacy frameworks may eventually consolidate, creating first-mover advantage for platforms with adaptable consent management architectures.
Industry Challenges
- SOC 2 Type II Certification Burden:Security attestation requirements demand sustained audit investment that stretches mid-market vendor engineering resources.
- Legacy CRM Migration Complexity:Decades of donor history in proprietary formats resist clean extraction, forcing expensive data transformation projects before platform transitions complete.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Donor Management Software Market |
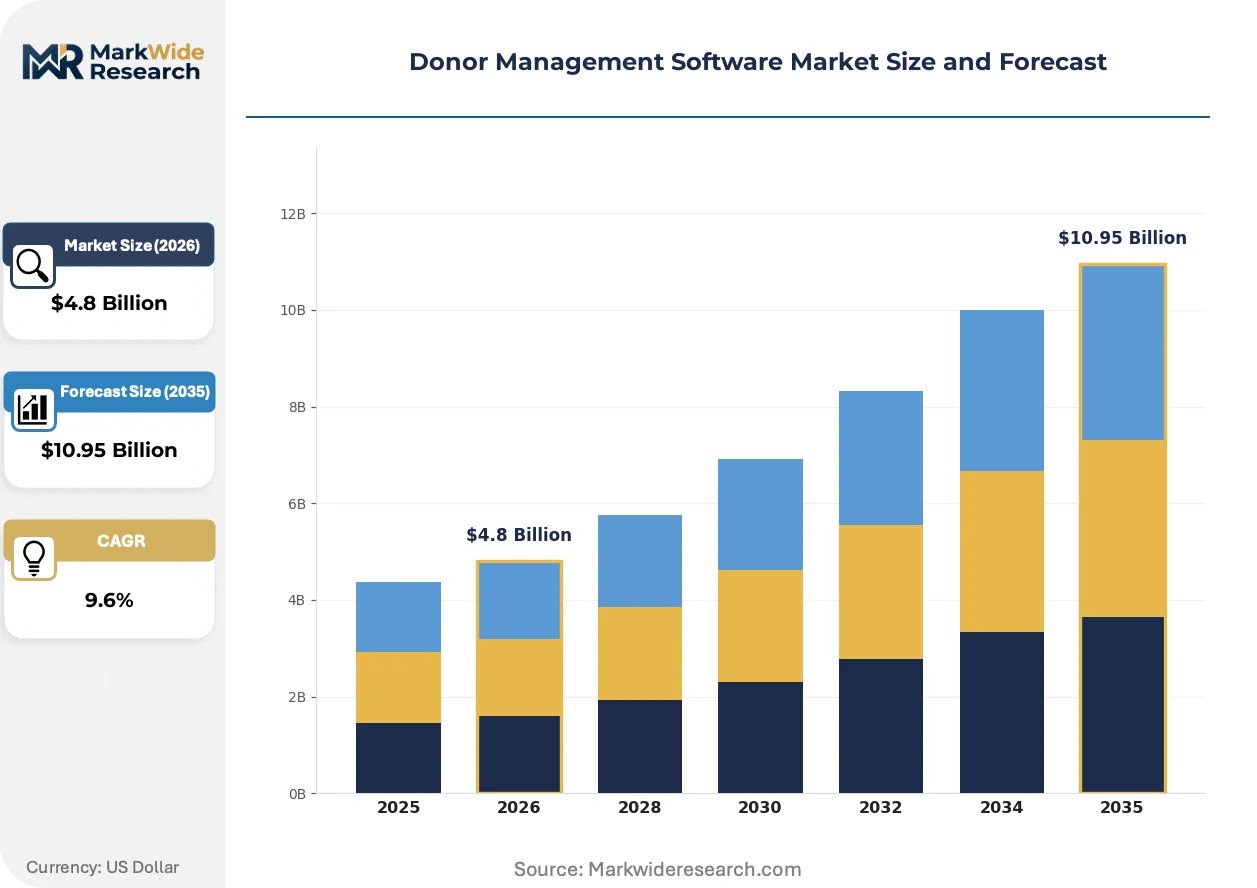
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.95 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premise, Hybrid, Open-source End User: Nonprofit Organizations, Charities, Educational Institutions, Fundraising Agencies Technology: Mobile Solutions, Web-based Solutions, Data Analytics, Integration Tools Delivery Model: Subscription-based, License-based, Freemium, Usage-based |
| Companies Covered | Bloomerang, Blackbaud Raiser's Edge NXT, DonorPerfect, Neon One, CharityEngine, Bonterra, Salesforce Nonprofit Cloud, Keela, Donorbox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Donor Management Software Market Strategic Shifts
Artificial intelligence is embedding predictive capabilities throughout donor lifecycle management, compressing the gap between data collection and actionable stewardship intervention while redefining competitive differentiation beyond core CRM functionality.
Blockchain-based donation tracking is decentralizing gift transparency verification, allowing donors to trace contribution flows through intermediary organizations without centralized clearinghouse dependency. Mid-sized international development nonprofits are piloting these architectures fastest. The technology is decentralizing trust mechanisms that previously required third-party audit relationships, compressing verification costs for cross-border giving.
GDPR enforcement actions by CNIL in France and parallel regulatory bodies across Europe are tightening consent documentation requirements for EU donor outreach. Organizations now face substantial penalties for inadequate opt-in record retention. Multi-national nonprofits with European supporter bases are restructuring data architecture to isolate EU data processing, fragmenting previously unified global databases.
Subscription-based platform access is displacing perpetual license purchases across the nonprofit technology procurement landscape. Finance committees prefer predictable operational expenditure over capital-intensive server investments. This preference shift is most visible among faith-based organizations with constrained IT capital budgets and seasonal fundraising volatility requiring elastic capacity scaling.
Donor Management Software Market Segmentation
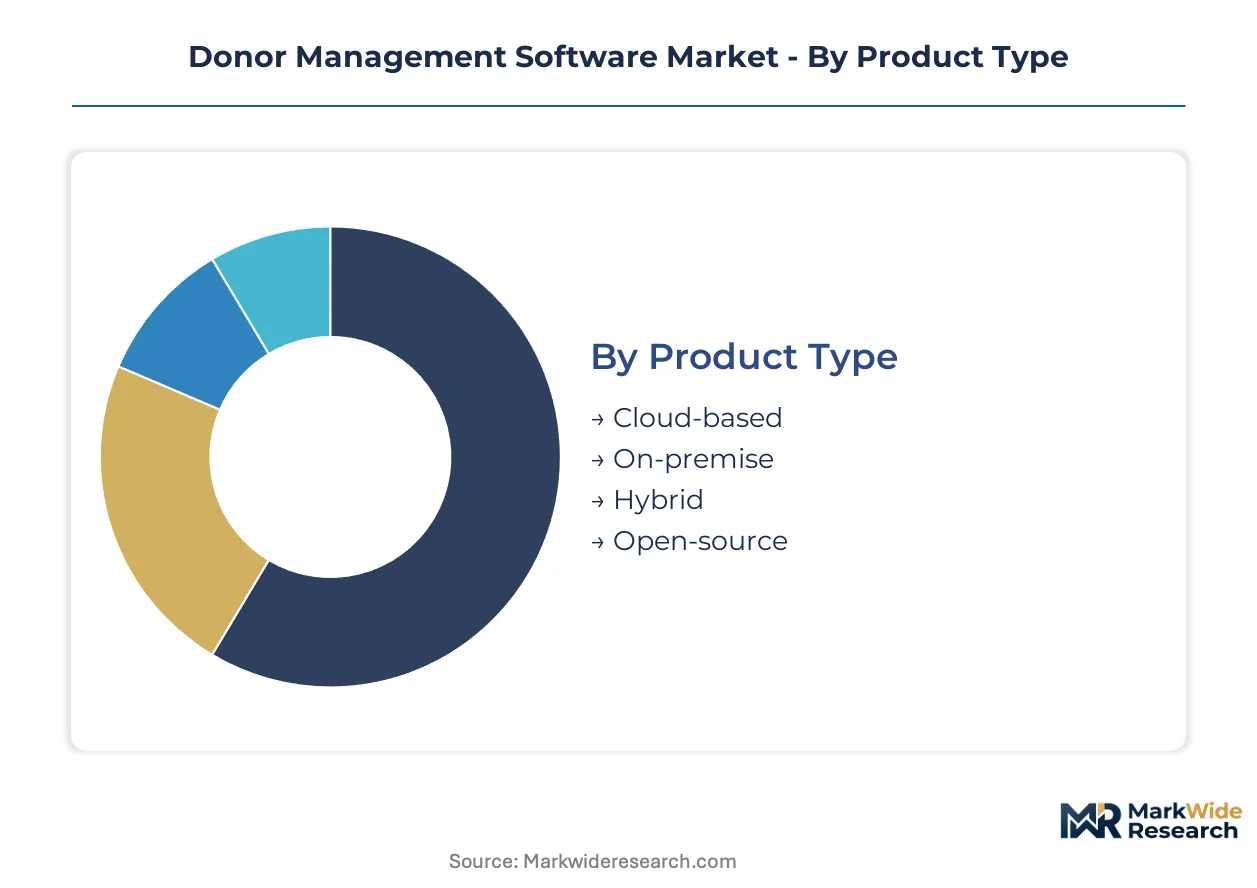
Donor management software segmentation reveals how deployment architecture, user sophistication, and commercial models create distinct competitive arenas. Technology choices directly constrain compliance posture and integration depth for fundraising operations.
Product Type:
Deployment architecture determines security certification requirements and total cost of ownership trajectories for advancement offices.
- Cloud-based:Multi-tenant SaaS architectures with elastic capacity scaling handle giving season traffic spikes without infrastructure overprovisioning. Higher education advancement offices in the United States concentrate demand here as they modernize legacy alumni databases under compressed procurement timelines.
- On-premise:Self-hosted server installations retain direct physical control over donor data for organizations with stringent data residency mandates. Healthcare foundations subject to HIPAA audit requirements maintain preference for this architecture despite accelerating cloud migration pressure.
- Hybrid:Split architectures isolate sensitive donor records on local servers while pushing engagement tools to cloud edge nodes.
- Open-source:Community-developed codebases with self-managed hosting appeal to technically staffed nonprofits with constrained licensing budgets.
Mature deployment sits with On-premise. Newer deployment is concentrated in Cloud-based.
End User:
Organizational scale and mission complexity drive feature requirements and implementation sophistication.
- Nonprofit Organizations:Generalist charitable entities with diverse funding streams require flexible campaign tracking and automated receipt generation. Mid-sized environmental and social service nonprofits in the United States represent expanding demand as digital transformation accelerates.
- Educational Institutions:University advancement offices manage multi-decade alumni lifecycles with complex major gift cultivation workflows. Institutions replacing legacy advancement databases drive premium suite adoption requiring deep vertical integration with student information systems.
- Charities:Mission-focused entities with concentrated fundraising events demand rapid-deployment solutions with minimal configuration overhead.
- Fundraising Agencies:Third-party consultancies managing donor programs for multiple clients require multi-tenant architectures with strict data isolation between accounts.
Revenue concentration sits with Educational Institutions. Steepest expansion trajectory belongs to Nonprofit Organizations.
Technology:
Interface and intelligence layers differentiate commodity CRM from specialized fundraising platforms.
- Mobile Solutions:Native applications and responsive web interfaces enable text-to-give and peer-to-peer fundraising from smartphones. Younger donor cohort acquisition depends on these touchpoints that desktop-centric legacy systems fail to reach.
- Data Analytics:Predictive modeling engines score donor propensity and optimize solicitation timing. Machine learning segmentation now matches capabilities that previously required dedicated data science teams.
- Web-based Solutions:Browser-accessible portals with donor self-service capabilities reduce administrative overhead.
- Integration Tools:API ecosystems and pre-built connectors link donor records to accounting, marketing automation, and event management systems.
Established capability sits with Web-based Solutions. Capability expansion concentrates in Data Analytics.
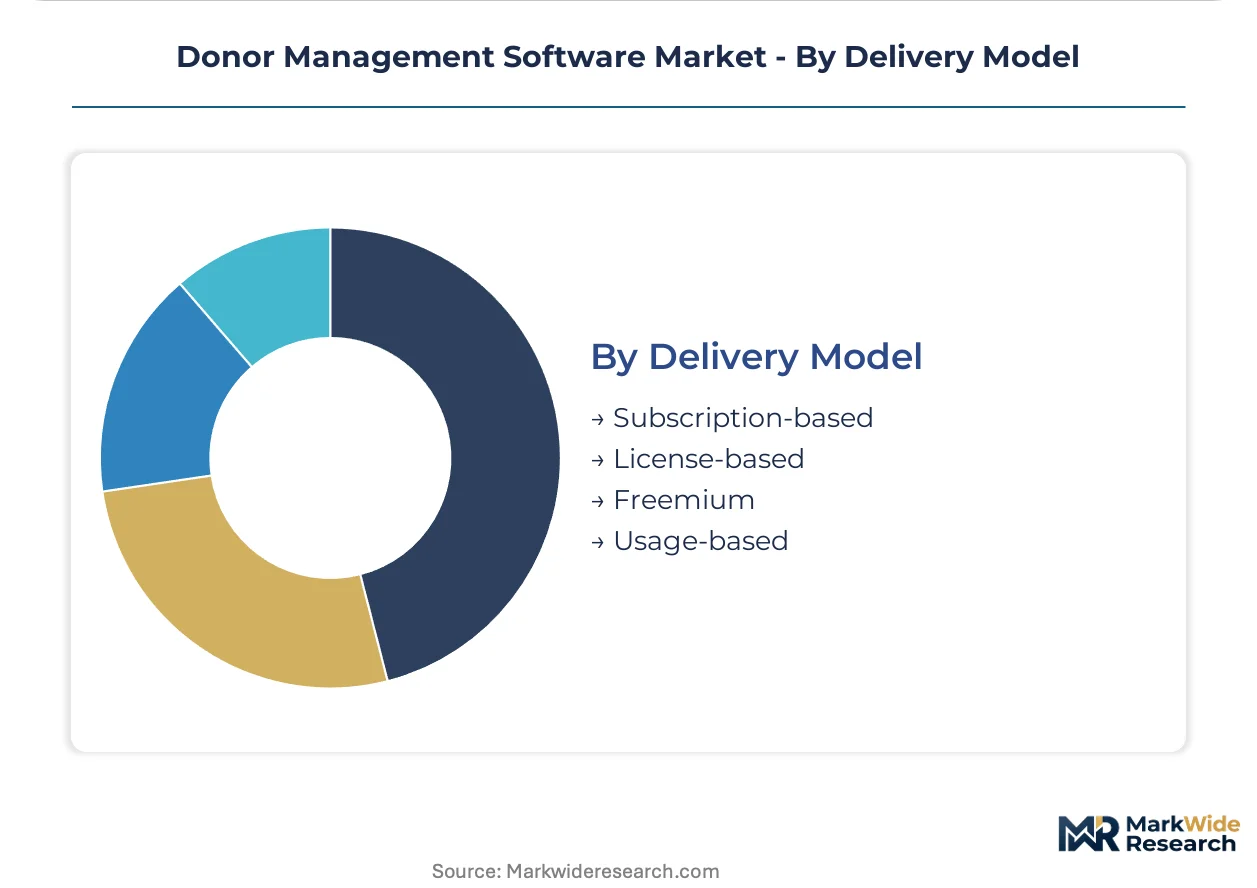
Delivery Model:
Commercial terms structure vendor cash flow predictability and customer switching costs.
- Subscription-based:Recurring monthly or annual fees convert capital expenditure to operational expenditure preferred by finance committees. Faith-based organizations with seasonal fundraising volatility and constrained IT capital budgets drive fastest adoption of this model.
- License-based:Perpetual software purchases with maintenance contracts appeal to organizations with depreciation schedules and long-term asset management practices.
- Freemium:Tiered access with core functionality at no cost and advanced features behind paywalls lowers entry barriers for emerging nonprofits.
- Usage-based:Metered pricing tied to transaction volume or contact database size aligns costs with fundraising scale.
Legacy preference sits with License-based. Market momentum concentrates in Subscription-based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley anchors the donor management software ecosystem through its concentration of cloud infrastructure providers and venture-backed nonprofit technology ventures. The region's SaaS engineering talent pools and proximity to major university endowment offices create unique conditions for platform development.
United States
University advancement offices and healthcare foundations drive premium platform adoption across the country. IRS 990 compliance automation requirements intensify audit-ready record system procurement from Boston to Los Angeles. The Research Triangle in North Carolina hosts emerging mid-market vendors targeting faith-based organizations with subscription pricing models.
United Kingdom
Charitable trusts and higher education institutions modernize legacy fundraising databases under compressed timelines. GDPR enforcement by the Information Commissioner's Office mandates consent documentation architectures that fragment previously unified global databases. London's fintech corridor incubates blockchain-based donation transparency pilots for international development nonprofits.
Germany
Mittelstand-sized charitable foundations demand hybrid deployment architectures balancing data residency mandates with cloud scalability. The Federal Data Protection Act intersects with state-level church tax administration requirements for audit-ready donation records. Berlin's startup ecosystem produces open-source donor management alternatives targeting technically staffed nonprofits with constrained licensing budgets.
France
CNIL enforcement actions tighten consent documentation requirements for EU donor outreach operations. Higher education grandes écoles replace legacy alumni databases with integrated advancement suites capable of multi-channel stewardship. The Paris-Saclay cluster concentrates demand from research foundation networks requiring predictive giving intelligence.
Canada
Healthcare foundations subject to provincial privacy statutes maintain preference for on-premise architectures despite cloud migration pressure. The Canada Revenue Agency's charitable registration requirements mandate gift receipt generation capabilities that align with US IRS 990 structures. Toronto's nonprofit technology corridor hosts vendors specializing in mid-market environmental and social service organizations.
Donor Management Software Market Competitive Environment
Premium-margin players sit above commodity-margin players across integration depth and AI-driven engagement scoring capabilities. The market structure concentrates around three tiers: enterprise advancement suites with deep vertical integration, mid-market cloud-native platforms leveraging ecosystem partnerships, and usability-focused solutions for smaller nonprofits with constrained implementation resources. Dominant competitive moves include strategic acquisitions to consolidate advancement service capabilities and API ecosystem expansion to capture integration-dependent revenue pools.
Within the premium-tier vector, Blackbaud Raiser's Edge NXT anchors deep vertical integration with advancement services. Salesforce Nonprofit Cloud occupies a position leveraging platform ecosystem breadth across mid-market and enterprise segments. Bloomerang exemplifies the usability-focused design archetype for smaller nonprofits, representing a distinct price-performance niche with minimal configuration overhead requirements.
| Leading Market Players |
|---|
| Bloomerang |
| Blackbaud Raiser's Edge NXT |
| DonorPerfect |
| Neon One |
| CharityEngine |
| Bonterra |
| Salesforce Nonprofit Cloud |
| Keela |
| Donorbox |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure spot pricing indices from AWS, Azure, and Google Cloud Platform cascade through SaaS vendor cost structures, compressing mid-tier subscription rates while elastic capacity premiums concentrate in higher education advancement offices with seasonal giving volatility.
Pricing Analysis
Value-based pricing anchored to donor lifetime value throughput stratifies the market into three tiers: premium suites command rates tied to predictive giving intelligence accuracy, mid-market platforms compete on per-seat SaaS subscriptions, and entry-level tools price by contact database size. SOC 2 Type II certification grade and AI-driven engagement scoring capability differentiate premium from standard tiers. Pricing pressure stems from open-source alternatives and freemium entrants targeting smaller nonprofits. Faith-based organizations with constrained IT capital budgets exhibit highest price sensitivity; university advancement offices with endowment-backed procurement show lowest.
Supply Chain Analysis
Direct-to-institution channels handle enterprise advancement office demand, while value-added resellers and nonprofit technology consultants serve mid-market segments. Engineering talent concentrates in the United States, United Kingdom, and Germany, with cloud infrastructure dependencies on hyperscale providers in the US and Ireland. Raw material inputs include proprietary machine learning training datasets, SOC 2 audit services, and API ecosystem development. Single-source vulnerability sits with hyperscale cloud infrastructure concentration. Distribution runs through vendor-direct sales for premium tiers and partner networks for volume segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum is accelerating as vendors pursue captive control over AI training data pipelines and advancement services bundling to escape commodity SaaS pricing traps.
For Market Incumbents: Cement platform stickiness through backward integration into predictive analytics data pipelines and exclusive advancement services partnerships. Acquire specialized healthcare foundation compliance modules before HIPAA-covered competitors consolidate. Threat of cloud-native entrants with superior UX design demands preemptive UX overhaul investments.
For New Entrants and Emerging Players: GDPR enforcement actions in France and parallel consent documentation mandates across Europe open a window for privacy-native architectures that fragment legacy global databases. Target mid-sized international development nonprofits with blockchain-based donation transparency pilots. Go-to-market through peer-to-peer fundraising platform integrations that bypass incumbent direct sales channels.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-market SaaS vendors with subscription revenue concentration above sixty percent and healthcare foundation customer bases in the United States. Long-term viability hinges on AI-driven engagement scoring differentiation that escapes commodity CRM positioning. Watch for state-level privacy law harmonization signals as inflection indicator for adaptable consent management architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Engagement Scoring Development | Predictive giving intelligence commands premium pricing from university advancement offices. |
| Healthcare Foundation Compliance Module Launch | HIPAA-covered verticals remain underpenetrated by generalist platform competitors. |
| API Ecosystem Expansion | Pre-built connectors to student information systems lock in higher education demand. |
| Mobile-First Donor Portal Introduction | Text-to-give capabilities capture younger donor cohorts that desktop systems miss. |
| Subscription Pricing Model Migration | Recurring revenue conversion appeals to faith-based organizations with capital constraints. |
Study Parameters
Document review covered SEC 10-K filings from publicly traded vendors, IRS 990 data from nonprofit technology adopters, and CNIL enforcement actions, complemented by interviews with university advancement officers, nonprofit CIOs, healthcare foundation compliance leads, and SaaS platform product managers. Secondary sources included cloud infrastructure capex disclosures, higher education procurement databases, and GDPR regulatory filings. Bottom-up segmentation modeling triangulated against top-down market sizing from subscription revenue aggregation.
Historical growth trajectories cross-referenced against expert panel inputs on cloud migration timelines and AI adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled included deployment architecture, organizational scale, integration complexity, and regional regulatory cluster. CAGRs derived from elasticity-adjusted subscription growth rates and technology segment penetration curves. Forecast inputs incorporated seasonal giving volatility patterns and data sovereignty compliance cost estimates.
Caveats apply where state-level privacy law fragmentation or AI disclosure mandate acceleration could materially shift the outlook. Forecasts reflect assumptions on cloud infrastructure cost trajectories and nonprofit digital transformation budgets. Periodic stress-testing of base assumptions against regulatory enforcement patterns and higher education endowment performance is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Global Clinical EHR Systems Market
Medical Information Systems
Global Medical Decision Support Systems for Sepsis Market
Medical Information Systems
Healthcare Mobile Computers Market
Medical Information Systems
Master Patient Index Software Market
Medical Information Systems
Hospital Information Systems Market
Medical Information Systems
Global Laboratory Information Management System for Forensic Science Market
Medical Information Systems
Medical Software Market
Medical Information Systems
Global Medical Scheduling Software Market
Medical Information Systems
Artificial Intelligence in Medical Software Market
Medical Information Systems
Middle East Secure Messaging in Healthcare Market
Medical Information Systems
Urology EMR Software Market
Medical Information Systems
Healthcare Information Governance Solution Market
Medical Information Systems
Global Clinical Information System Market
Medical Information Systems
Global Allergy EMR Software Market
Medical Information Systems
Global Pharmacy Information System Market
Medical Information Systems
Global Healthcare Information Systems Market