
 Medical Talent Management IT Market | 2026-2036
Medical Talent Management IT Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Talent Management IT Market Outlook
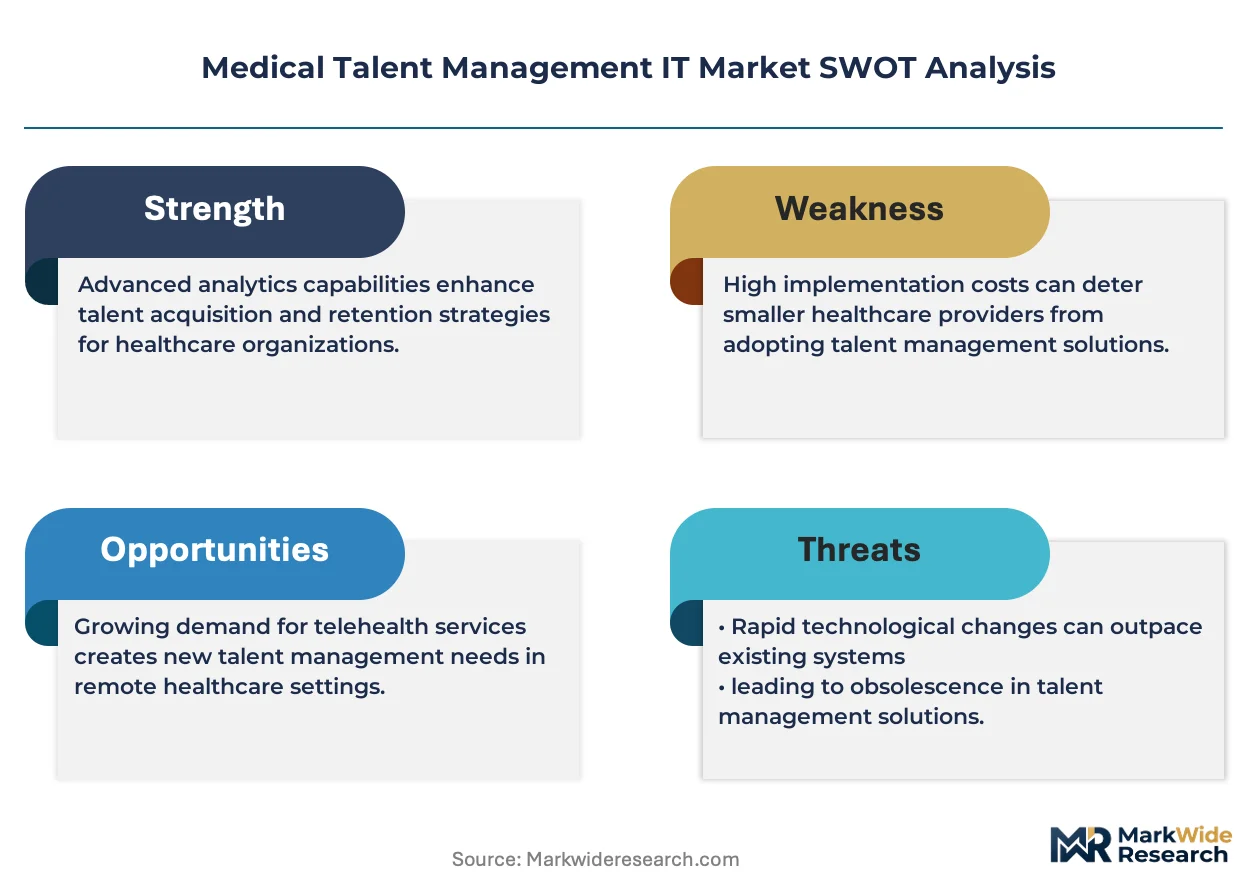
Health systems are reorganizing their workforce technology priorities faster than standalone hospitals or small clinics. Oracle leverages its Cerner integration to anchor clinical and HR data on unified cloud architectures. SAP competes through deep ERP interoperability that sustains long-term contracts with multi-facility operators. Workday specializes in consumer-grade interfaces that differentiate its platform among nursing staff and rotating clinicians.
Medical Talent Management IT encompasses software platforms that automate credential verification, schedule optimization, competency tracking, and regulatory compliance for healthcare workforces, typically integrating with electronic health record systems through HL7 FHIR or proprietary APIs. The primary purpose is reducing administrative burden on clinical managers while maintaining Joint Commission readiness. Recruitment Software and Credentialing Management occupy the largest revenue pools because licensing verification delays directly impact revenue cycle performance. AI-Driven Solutions represent the fastest-expanding technology segment as predictive models reduce overtime expenditures and turnover-driven vacancy costs.
FDA oversight of clinical decision support intersects with HIPAA privacy mandates to shape how vendors architect workforce data access controls and audit trails. OSHA reporting requirements and state-level nurse staffing ratio laws further complicate scheduling algorithm design, creating compliance-driven switching costs for incumbent platforms. Stakeholders must monitor how emerging state licensure compacts and interstate telehealth expansion reshape credentialing workflows across multi-state health systems.
Market Dynamics
Hospital consolidation into multi-facility health systems is compressing vendor selection cycles and forcing workforce platforms to prove enterprise-scale interoperability before contract award.
Growth Catalysts
- Interstate licensure compacts:The Nurse Licensure Compact now covers forty-one US states, collapsing credentialing timelines for traveling clinicians and expanding addressable pools for scheduling algorithms.
- OSHA workplace violence mandates:New reporting requirements for healthcare settings are embedding safety incident tracking directly into workforce management dashboards.
- Predictive analytics engines:Machine learning models trained on EHR admission patterns now generate staffing forecasts seventy-two hours forward, cutting premium labor dependence.
Market Restraints
- HL7 FHIR implementation costs:Health systems face seven-figure integration expenses to achieve seamless data exchange between talent platforms and Cerner or Epic architectures.
- Concentrated cloud infrastructure:Three hyperscalers control over eighty percent of healthcare-compliant hosting, creating single-point-of-failure exposure for workforce SaaS vendors.
- Joint Commission audit complexity:Competency documentation requirements span thousands of clinical roles, forcing vendors to maintain expensive rule-engine customization teams.
Strategic Opportunities
- Rural critical access hospitals:Two thousand US facilities operate without dedicated workforce IT, representing greenfield deployment potential for cloud-native platforms with telehealth credentialing modules.
- AI-natural language processing convergence:Voice-enabled shift bidding and automated policy query resolution are reducing training burdens for non-technical nursing managers.
- CMS value-based purchasing alignment:Hospital reimbursement now ties to patient satisfaction scores, creating procurement pull for scheduling tools that match clinician continuity to care quality metrics.
Industry Challenges
- Clinical informaticist scarcity:Health systems lack personnel who bridge nursing workflow knowledge and API configuration expertise, stalling platform optimization post-implementation.
- Legacy time-clock hardware:Biometric punch systems installed in the 2010s resist cloud migration, forcing expensive parallel infrastructure during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Talent Management IT Market |
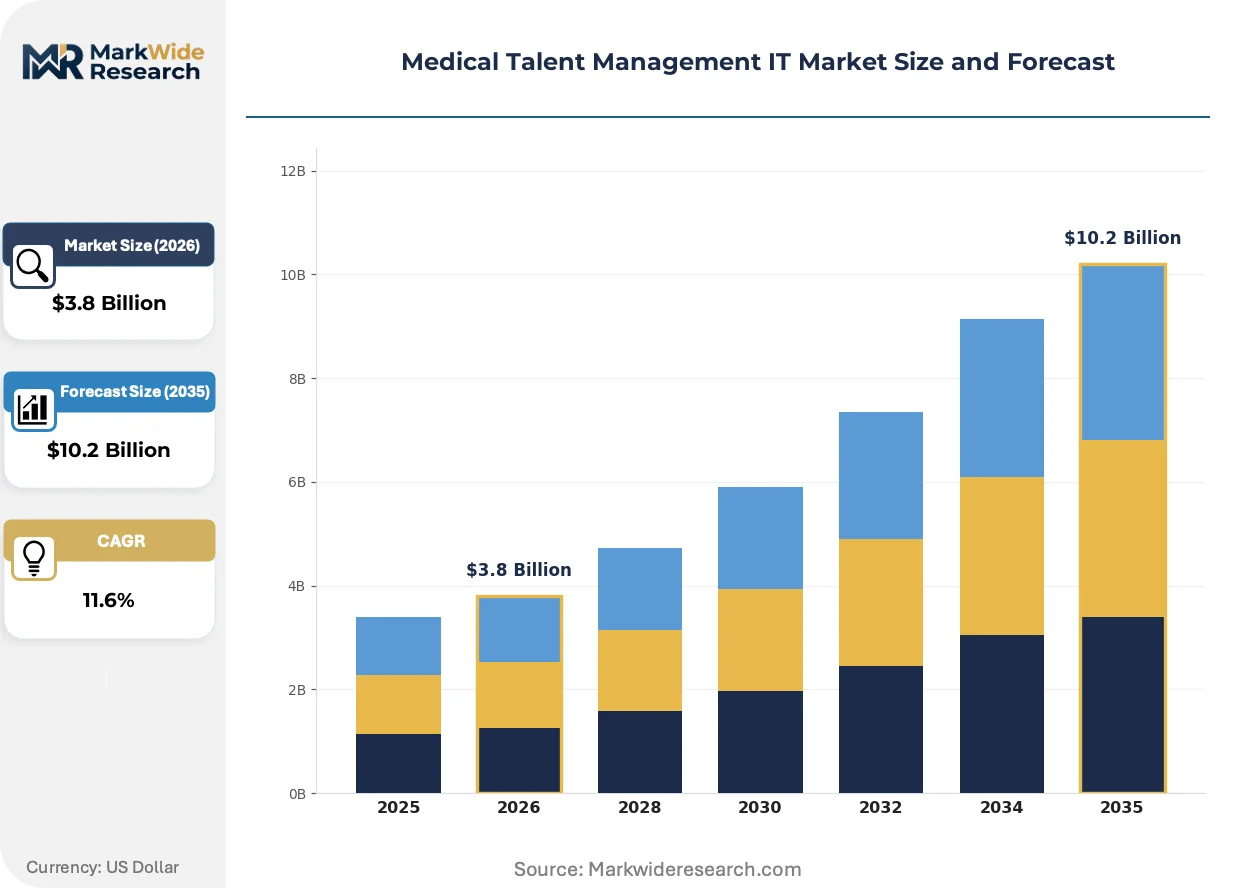
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
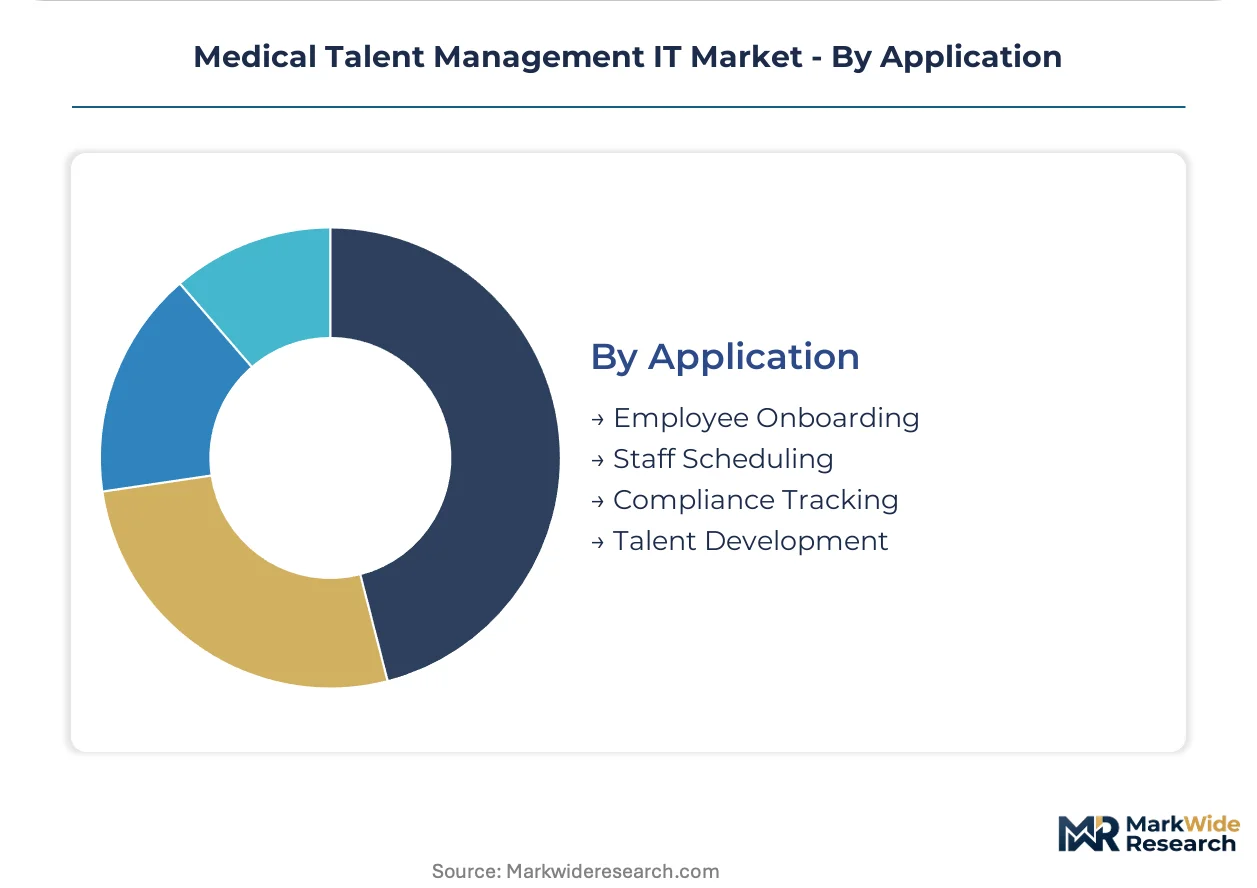
| Segmentation | Product Type: Recruitment Software, Credentialing Management, Performance Management, Learning Management End User: Hospitals, Clinics, Health Systems, Staffing Agencies Technology: Cloud-Based, On-Premise, Mobile Applications, AI-Driven Solutions Application: Employee Onboarding, Staff Scheduling, Compliance Tracking, Talent Development |
| Companies Covered | Oracle, SAP, IBM, Workday, Symplr, Cornerstone OnDemand, SumTotal Systems, UKG, ADP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Talent Management IT Market Strategic Shifts
Workforce technology in healthcare is pivoting from administrative record-keeping toward real-time clinical operations orchestration, with three forces determining competitive survival.
Generative AI for shift scheduling is bifurcating the vendor landscape between platforms that automate routine swap approvals and those requiring manual manager intervention. Large integrated delivery networks in Texas and Florida are piloting autonomous scheduling for ninety-day trial periods. The technology is compressing overtime expenditure while creating liability exposure around algorithmic bias in shift allocation.
FDA guidance on clinical decision support software is reshaping how workforce platforms handle predictive staffing alerts that touch patient care decisions. Vendors must now document algorithm training data and performance validation for any recommendation engine suggesting nurse-to-patient ratios. Multi-state health systems are responding by segregating pure scheduling functions from clinical workload forecasting into separate architectural modules.
Subscription fatigue among hospital CFOs is shortening enterprise software evaluation cycles from eighteen months to nine. Procurement committees now demand proof-of-concept deployments in live clinical units before full-contract commitment. This compression is most visible in the southeastern United States, where private equity-backed hospital chains are standardizing workforce stack decisions at holding-company level rather than facility-by-facility.
Medical Talent Management IT Market Segmentation
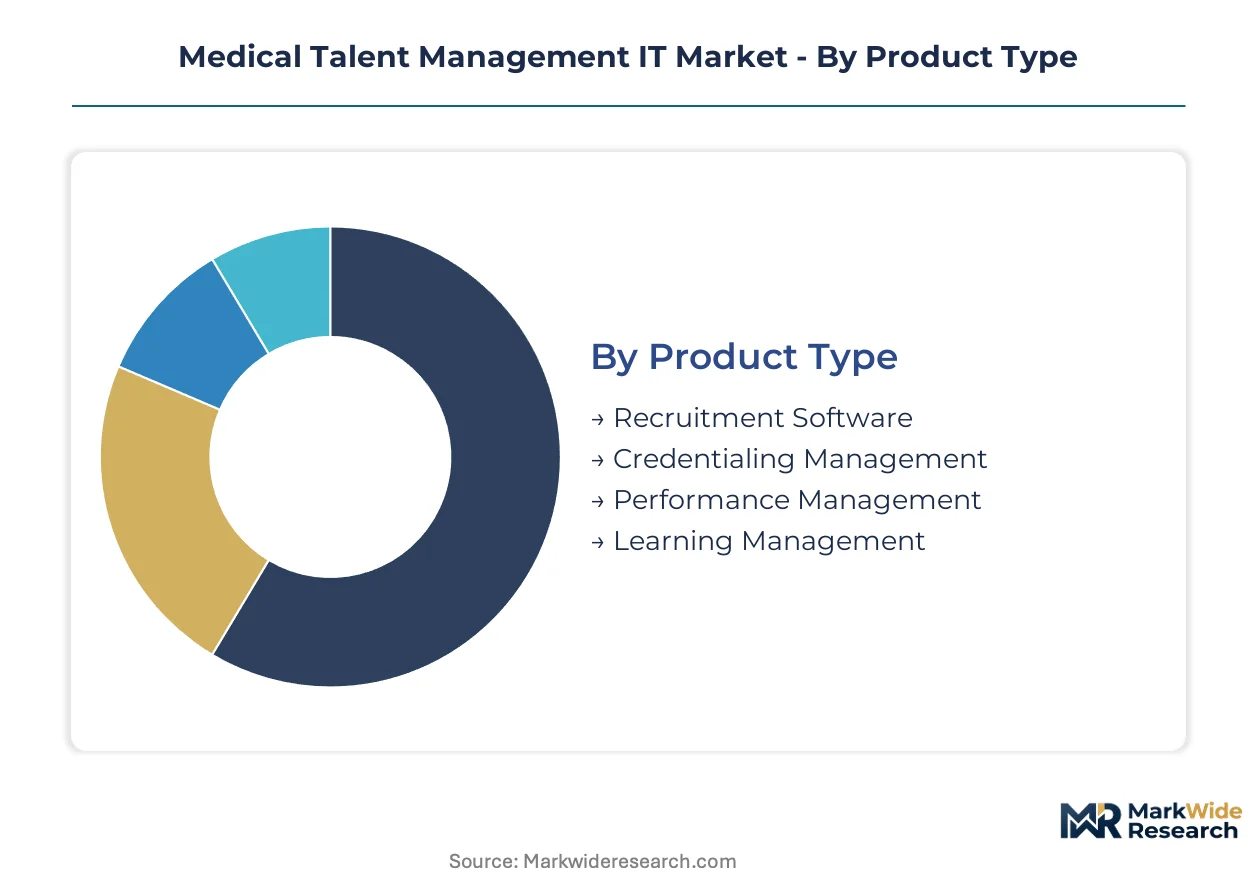
Medical Talent Management IT procurement varies sharply by channel. Enterprise health systems favor integrated suites through direct vendor relationships, while independent clinics rely on reseller networks and group purchasing organizations.
Product Type:
Channel mix splits between direct enterprise sales for credentialing platforms and distributor-mediated deployment for modular point solutions.
- Recruitment Software:Applicant tracking systems with healthcare-specific compliance filtering automate license verification and background checks during hiring workflows. Demand concentrates in staffing agencies serving Texas and Florida health systems, where travel nurse volume surges strain manual recruitment processes.
- Credentialing Management:Primary source verification engines cross-reference state licensing boards, DEA registrations, and malpractice histories through automated API connections. Hospital revenue cycle teams in California and New York prioritize these tools because credentialing delays directly block billing eligibility for new clinical staff.
- Performance Management:Competency assessment frameworks align Joint Commission documentation with individualized development plans.
- Learning Management:Continuing education platforms track CEU completion for license renewal cycles.
By volume, Recruitment Software leads. By growth pace, Credentialing Management is ahead.
End User:
Cost tier stratification separates enterprise health system investments from budget-constrained clinic deployments.
- Hospitals:Standalone acute care facilities deploy workforce platforms focused on shift optimization and overtime reduction. Midwestern community hospitals in Ohio and Illinois represent concentrated demand as they compete for nursing talent against larger integrated systems.
- Health Systems:Multi-facility operators require unified talent platforms spanning dozens of sites with centralized credentialing pools. These organizations in North Carolina and Pennsylvania drive the steepest expansion trajectory for AI-driven scheduling modules that balance labor costs across geographically distributed campuses.
- Clinics:Ambulatory settings prioritize lightweight mobile-first solutions for part-time clinician coordination.
- Staffing Agencies:Travel nurse and locum tenens firms demand rapid-credentialing platforms for multi-state deployment.
Health Systems capture the highest per-contract value. Staffing Agencies show the fastest adoption velocity.
Technology:
Application maturity separates established cloud architectures from emerging AI deployments still in validation phases.
- Cloud-Based:Multi-tenant SaaS platforms with HL7 FHIR connectivity dominate new procurement, eliminating on-premise maintenance overhead. Health systems in Georgia and Arizona favor these deployments for automatic compliance updates as OSHA and CMS rules evolve.
- AI-Driven Solutions:Predictive staffing algorithms trained on EHR admission patterns forecast demand seventy-two hours forward. Early adopters in Massachusetts and Washington state measure ROI through reduced premium labor expenditure and improved nurse retention metrics.
- On-Premise:Legacy client-server installations persist in facilities with strict data residency requirements.
- Mobile Applications:Native iOS and Android tools enable shift bidding and credential upload from personal devices.
Cloud-Based platforms hold installed base dominance. AI-Driven Solutions are climbing the fastest.
Application:
Customer workflow integration determines whether platforms serve HR administrative functions or embed directly into clinical operations.
- Staff Scheduling:Automated rostering tools balance nurse-to-patient ratios against labor budget targets while respecting state-mandated break rules. Florida and Texas hospitals deploy these most aggressively as patient volume volatility strains manual scheduling processes.
- Compliance Tracking:Real-time dashboards monitor expiring licenses, incomplete training modules, and Joint Commission documentation gaps. Risk officers at Colorado and Michigan health systems prioritize these capabilities given escalating survey scrutiny and immediate jeopardy findings.
- Employee Onboarding:Digital workflows accelerate credential packet completion before first shift assignment.
- Talent Development:Succession planning tools identify high-potential nurses for leadership pipeline progression.
Staff Scheduling generates the highest transaction volume. Compliance Tracking is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States healthcare cloud infrastructure underwrites North American dominance in Medical Talent Management IT procurement, with fiber-optic interconnects between Dallas, Phoenix, and Northern Virginia data centers enabling real-time workforce orchestration across multi-state health systems.
United States
Hospital consolidation into multi-facility operators drives enterprise-scale platform investments, with CFOs demanding proof-of-concept deployments before contract award. OSHA workplace violence mandates embed safety incident tracking directly into workforce dashboards. Texas and Florida health systems pilot autonomous scheduling for ninety-day trial periods, compressing overtime expenditure through predictive algorithms.
Germany
Multi-facility hospital chains prioritize ERP interoperability for long-term contract sustainability with workforce platform vendors. The EU AI Act shapes documentation requirements for algorithmic staffing recommendations that touch patient care decisions. Bavarian health networks deploy cloud-native credentialing modules to address cross-border clinician mobility within the European Economic Area.
United Kingdom
NHS trust consolidation accelerates vendor selection cycles, favoring platforms with consumer-grade interfaces for nursing staff adoption. GDPR compliance mandates govern workforce data access controls and audit trail architectures. London and Southeast England health systems lead AI-driven scheduling adoption, measuring ROI through reduced agency nursing expenditure.
Japan
Aging demographics intensify demand for scheduling optimization as nursing shortages strain acute care capacity. METI guidelines on healthcare digitalization incentivize cloud migration away from legacy client-server installations. Kanto region hospitals around Tokyo deploy mobile-first shift bidding tools to retain part-time clinicians in competitive labor markets.
Australia
State-level nurse staffing ratio laws complicate scheduling algorithm design for multi-site operators spanning New South Wales and Victoria. The Therapeutic Goods Administration intersects with workforce platforms when predictive staffing alerts influence clinical workload decisions. Melbourne and Sydney health networks invest in competency tracking dashboards to maintain accreditation readiness amid escalating survey scrutiny.
Medical Talent Management IT Market Competitive Environment
Concentration sits with enterprise software conglomerates that anchor clinical and HR data on unified cloud architectures. The vendor landscape bifurcates between integrated suite providers and modular point-solution specialists, with procurement committees shortening evaluation cycles from eighteen months to nine. Three strategic archetypes dominate: ERP-native platforms leveraging deep interoperability, cloud-native specialists emphasizing consumer-grade interfaces, and healthcare-specific vendors embedding regulatory compliance engines. Competitive moves center on Cerner and Epic integration partnerships and AI-driven scheduling module acquisitions.
Within the ERP-native tier, Oracle and SAP exemplify architectures that sustain long-term contracts with multi-facility operators through unified data layers. Workday occupies a distinct position among cloud-native specialists, differentiating through mobile-first experiences that reduce training burdens for nursing managers. These three anchors represent contrasting approaches to the same procurement priority: reducing administrative burden while maintaining Joint Commission readiness.
| Leading Market Players |
|---|
| Oracle |
| SAP |
| IBM |
| Workday |
| Symplr |
| Cornerstone OnDemand |
| SumTotal Systems |
| UKG |
| ADP |
| Others |
Value Chain & Pricing Dynamics
Cloud-native SaaS architectures displacing legacy on-premise installations simultaneously shift supply geography toward hyperscaler-dominated US data centers and compress pricing premiums for maintenance-heavy incumbent platforms. Health systems now negotiate enterprise contracts based on API interoperability rather than per-seat licensing, eroding traditional software margin structures.
Pricing Analysis
Volume-discount tiering structures dominate enterprise procurement, with health systems commanding 40-60% unit-cost reductions against standalone hospital pricing. Price differentiation rests on HL7 FHIR certification grade and Epic or Cerner integration depth. Pricing pressure stems from CFO scrutiny shortening evaluation cycles from eighteen months to nine. Staffing agencies exhibit highest price sensitivity; multi-facility health systems demonstrate lowest.
Supply Chain Analysis
Just-in-time deployment preferences dominate as health systems demand proof-of-concept validation before full-contract commitment. Supply concentrates in the United States, Ireland, and India for cloud infrastructure and software development. Raw material dependencies include GPU compute capacity, healthcare-compliant data center real estate, and clinical informaticist labor pools. Single-source vulnerability runs through AWS, Azure, and Google Cloud controlling eighty-plus percent of compliant hosting. Distribution runs through direct vendor relationships for enterprise suites and reseller networks for modular point solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern driven by hospital consolidation waves that compress vendor selection cycles and force platform standardization across multi-facility operators.
For Market Incumbents: Shield installed-base revenue by embedding AI-driven scheduling modules that create switching costs through clinician workflow dependence. Accelerate certification investment in FDA-guided clinical decision support documentation to outpace regulatory complexity. Prioritize backward integration into data center capacity through dedicated healthcare cloud instances.
For New Entrants and Emerging Players: Lead with voice-enabled natural language interfaces targeting rural critical access hospitals lacking dedicated workforce IT infrastructure. Penetrate the two-thousand-facility greenfield segment through telehealth credentialing modules that collapse multi-state licensing timelines. Deploy mobile-first shift bidding tools through group purchasing organization channels.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed hospital chains standardizing workforce stack decisions at holding-company level. Five-to-ten-year viability favors vendors with proven Epic and Cerner integration architectures. Monitor interstate licensure compact expansion as inflection indicator for credentialing platform addressable market growth.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Scheduling Module Launch | Autonomous shift allocation reduces overtime expenditure for Texas and Florida health systems piloting ninety-day trials. |
| Epic and Cerner Integration Partnership | Unified data layers sustain long-term contracts with multi-facility operators demanding seamless EHR connectivity. |
| Healthcare-Compliant Cloud Migration | Automatic OSHA and CMS rule updates eliminate on-premise maintenance overhead for Georgia and Arizona deployments. |
| Acquisition of Credentialing Specialist | Primary source verification engines accelerate revenue cycle performance for California and New York hospital billing teams. |
| Mobile-First Interface Development | Consumer-grade experiences reduce training burdens for nursing managers at NHS trusts and Japanese Kanto region hospitals. |
Study Parameters
A spread of perspectives from health system CFOs, clinical informaticists, hospital procurement committees, and GPO contracts managers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through hospital procurement databases, CMS Medicare reimbursement data, GPO contract filings, and hyperscaler healthcare cloud capex disclosures. Bottom-up deployment estimates triangulated against top-down health system IT budget benchmarks.
Segmentation dimensions modeled span deployment architecture, organization scale, EHR integration complexity, and regional regulatory cluster across the projection horizon. CAGRs derive from logistic adoption curves fitted to health system consolidation velocity and AI module penetration rates. Forecast inputs include interstate licensure compact coverage expansion and OSHA workplace violence mandate implementation timelines.
Forecasts assume regulatory continuity in FDA oversight regimes for clinical decision support and HIPAA privacy mandates; material policy shifts would require re-modeling. Revision becomes warranted when Joint Commission audit complexity or cloud infrastructure concentration crosses disruption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Global Cardiovascular Information System Market
Medical Information Systems
Ophthalmology EMR Software Market
Medical Information Systems
Urology EMR Software Market
Medical Information Systems
Medical Saas System Market
Medical Information Systems
Global Computerized Physician Order Entry Market
Medical Information Systems
Global Healthcare Software As a Service Market
Medical Information Systems
Dentistry EMR Software Market
Medical Information Systems
AI in Medical Billing Market
Medical Information Systems
Medical Software Market
Medical Information Systems
Global Clinical EHR Systems Market
Medical Information Systems
Global Medical Document Management Systems Market
Medical Information Systems
India EMR (Electronic Medical Records) Market
Medical Information Systems
Global Medical Writing Market
Medical Information Systems
Medical Alert Systems Market
Medical Information Systems
Hospital Information Systems Market
Medical Information Systems
Healthcare Information Governance Solution Market