
 Artificial Intelligence in Medical Software Market | 2026-2036
Artificial Intelligence in Medical Software Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence in Medical Software Market Insights
Subscription-based software-defined feature layers is recalibrating how vendors monetize AI medical platforms. NVIDIA Corporation leverages its GPU compute architecture to anchor development pipelines for radiology AI startups and established device makers alike. GE Healthcare differentiates through embedded AI within imaging hardware, creating captive demand for its proprietary software modules. Siemens Healthineers AG sustains R&D intensity across computer vision algorithms for pathology and cardiology workflows.
Artificial intelligence in medical software encompasses algorithmic systems that process clinical data, medical images, patient records, and operational signals to generate diagnostic recommendations, predictive risk scores, or automated workflow triggers, typically operating through cloud-hosted or edge-deployed architectures with latency requirements under 300 milliseconds for real-time surgical guidance. Clinical decision support platforms command the deepest margin pools due to integration complexity with hospital IT stacks and recurring certification burdens. Deep learning within imaging software represents the fastest-expanding technology-application intersection, driven by FDA-cleared algorithms for diabetic retinopathy and lung nodule detection. Natural language processing applied to patient management shows accelerating adoption as health systems automate clinical documentation and coding workflows.
FDA premarket review under its AI/ML-based Software as a Medical Device framework shapes product development timelines and evidence requirements for US market entrants. EMA and EU MDR compliance in Europe impose additional clinical validation standards that filter out lower-maturity algorithms. China's NMPA has established a dedicated AI medical device review pathway that accelerates domestic approvals while requiring local clinical trials. Stakeholders must monitor divergence between regulatory evidentiary standards across jurisdictions when prioritizing development roadmaps and market entry sequencing.
Market Dynamics
Subscription-based monetization is compressing upfront license revenue into recurring streams, forcing vendors to restructure R&D capitalization and customer acquisition economics around lifetime value metrics rather than perpetual sale margins.
Growth Catalysts
- FDA AI/ML-based SaMD framework:The premarket review pathway provides regulatory clarity that accelerates commercialization timelines for algorithm developers seeking US market entry.
- Diagnostic laboratories in Germany:Procurement of AI-enabled imaging tools is expanding under EMA and EU MDR compliance deadlines, creating concentrated demand for validated algorithms.
- Deep learning architectures:Convolutional neural networks for pathology slide analysis are reducing diagnostic variability and enabling quantitative biomarker extraction at scale.
Market Restraints
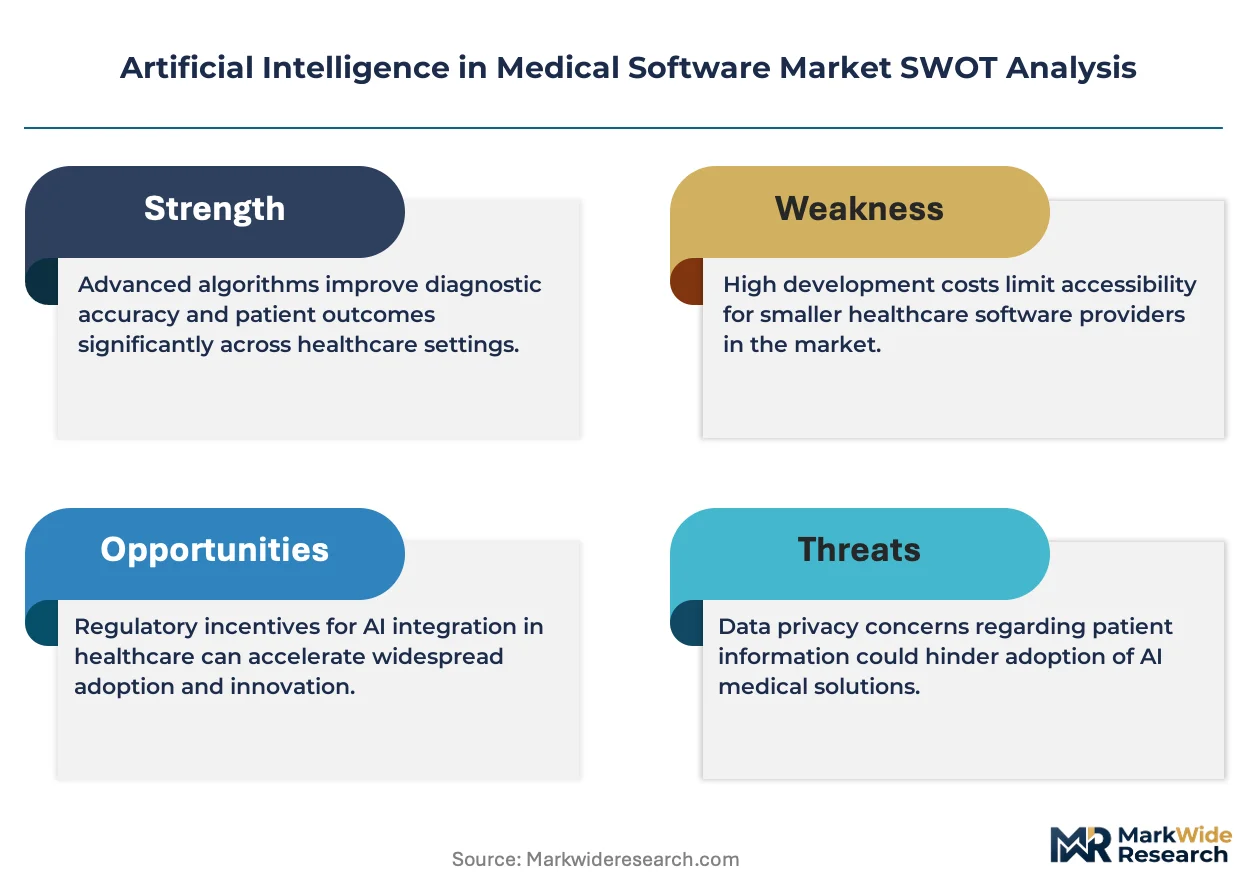
- GPU compute cost volatility:Training infrastructure for large medical imaging models remains exposed to NVIDIA supply allocation and cloud pricing tiers.
- EU MDR clinical validation burden:The expanded evidence requirements for AI algorithms filter out lower-maturity developers and extend time-to-revenue.
- Interoperability limitations:Proprietary data formats from incumbent imaging hardware vendors create switching costs that slow platform consolidation.
Strategic Opportunities
- Natural language processing for clinical documentation:Health systems in Japan are automating coding workflows to address physician workforce constraints.
- Edge deployment for surgical guidance:Latency requirements under 300 milliseconds are driving co-location of inference engines with operating room equipment.
- China NMPA domestic trial pathway:The dedicated AI medical device review channel accelerates approvals for algorithms with local clinical evidence.
Industry Challenges
- Regulatory divergence across FDA, EMA, and NMPA:Evidentiary standard misalignment forces parallel validation studies that duplicate development costs.
- Integration complexity with legacy EHR infrastructure:Hospital IT stacks require custom API development and data normalization that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence in Medical Software Market |
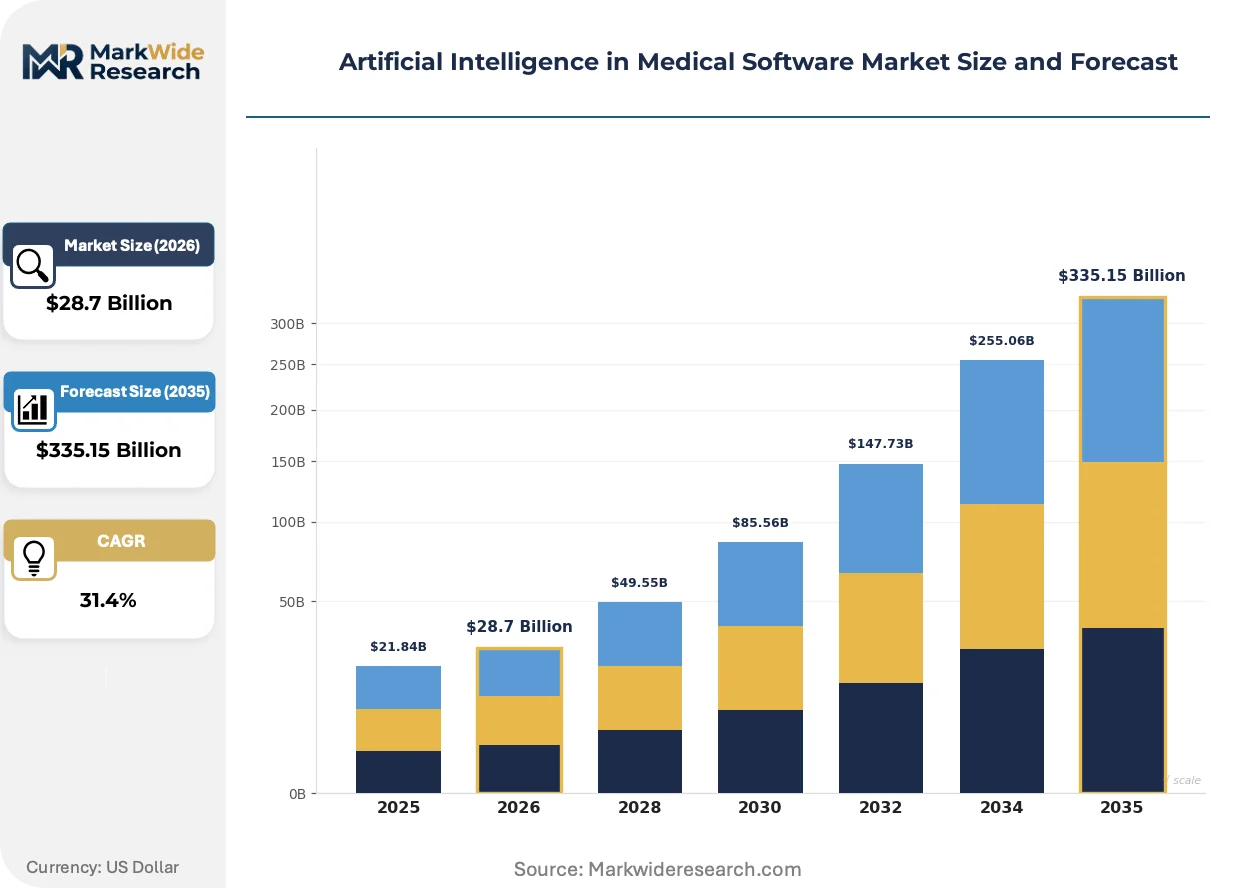
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $335.15 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clinical Decision Support, Remote Monitoring Systems, Imaging Software, Predictive Analytics Technology: Machine Learning, Natural Language Processing, Deep Learning, Computer Vision End User: Hospitals, Diagnostic Laboratories, Research Institutions, Outpatient Clinics Application: Diagnosis Assistance, Patient Management, Treatment Personalization, Workflow Optimization |
| Companies Covered | NVIDIA Corporation, GE Healthcare, Siemens Healthineers AG, Microsoft, IBM, Intel Corporation, Nuance Communications, Inc., Enlitic Inc., Aidoc Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence in Medical Software Market Trends and Innovations
Federated learning architectures and foundation models trained on multi-institutional datasets are redrawing competitive boundaries between cloud-native entrants and hardware-embedded incumbents.
Multimodal foundation models that jointly process imaging, genomics, and clinical text are absorbing the function of narrow single-task algorithms that previously required separate regulatory clearances. Academic medical centers in the United States are piloting these systems for tumor board decision support. The compression of multiple diagnostic workflows into unified model architectures is absorbing vendor market share from point-solution developers.
EU AI Act risk classification for medical devices is imposing conformity assessment obligations that stratify the vendor landscape by compliance capability. High-risk AI systems face third-party audit requirements that favor established players with dedicated regulatory affairs functions. European hospital procurement teams are revising vendor qualification criteria to prioritize CE-marked algorithms with documented post-market monitoring protocols.
Health system purchasing committees are consolidating algorithm procurement under centralized IT governance rather than departmental autonomy. Radiology and pathology divisions that previously selected AI tools independently now route decisions through enterprise architecture review boards. This behavioral shift is most visible in integrated delivery networks across the United States, where standardization mandates favor platform vendors with broad modular portfolios over specialized point solutions.
Artificial Intelligence in Medical Software Market Segmentation
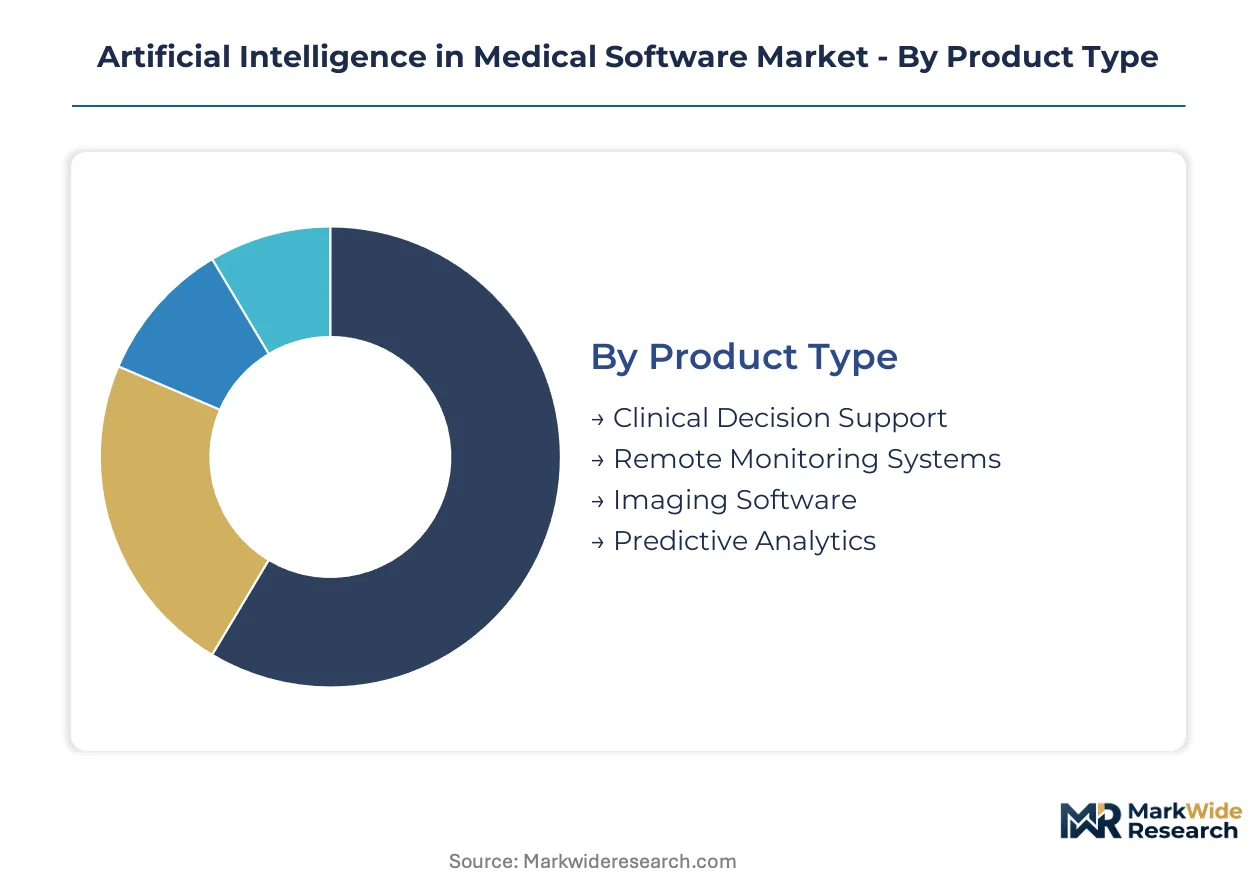
Segmentation in AI medical software reveals how procurement committees weight integration complexity against clinical utility. Buyers prioritize regulatory clearance status and EHR interoperability over algorithmic performance metrics alone.
Product Type:
Hospital procurement committees differentiate software tiers by integration burden and recurring certification costs.
- Clinical Decision Support:Algorithmic platforms that synthesize patient data streams to generate diagnostic recommendations and alert triggers. Deep margin pools attract established health IT vendors. Demand concentrates in US hospital systems facing physician workforce constraints and liability exposure.
- Imaging Software:FDA-cleared convolutional neural networks for radiology and pathology workflows, typically deployed via cloud API or on-premise GPU clusters. Diagnostic laboratories in Germany are expanding procurement under EMA compliance deadlines. Regulatory validation burden filters out lower-maturity entrants.
- Remote Monitoring Systems:Edge-deployed inference engines processing continuous physiological signals for chronic disease management.
- Predictive Analytics:Risk stratification tools that flag deterioration events or readmission probability from EHR-derived features.
Volume sits with Clinical Decision Support; growth tilts toward Imaging Software.
Technology:
Technology selection follows the data modality of target clinical workflows rather than algorithmic sophistication alone.
- Deep Learning:Multi-layer neural architectures trained on labeled medical images for detection and segmentation tasks. Convolutional networks for pathology slide analysis are reducing diagnostic variability. Academic medical centers in the United States pilot multimodal foundation models for tumor board support.
- Natural Language Processing:Transformer-based models extracting structured data from unstructured clinical notes and automating documentation workflows. Health systems in Japan deploy these tools to address physician coding burdens. Procurement is accelerating as reimbursement rules tighten.
- Machine Learning:Traditional supervised and unsupervised methods for tabular clinical data and operational forecasting.
- Computer Vision:Specialized architectures for surgical guidance and endoscopic video analysis requiring sub-300-millisecond latency.
Deep Learning commands current revenue concentration; Natural Language Processing is climbing the fastest as documentation automation becomes mandatory.
End User:
End-user segmentation tracks capital availability and regulatory sophistication across care delivery settings.
- Hospitals:Integrated delivery networks with dedicated IT governance committees and enterprise architecture review boards. US health systems concentrate demand for platforms with broad modular portfolios. Standardization mandates favor vendors with proven EHR integration.
- Diagnostic Laboratories:High-volume pathology and radiology operations seeking quantitative biomarker extraction at scale. German laboratories drive procurement of AI-enabled imaging tools under EU MDR timelines. Compliance capability stratifies vendor selection.
- Research Institutions:Academic medical centers piloting foundation models and federated learning architectures.
- Outpatient Clinics:Smaller care settings prioritizing cloud-hosted solutions with minimal infrastructure requirements.
Hospital systems absorb the largest deployment volume; Diagnostic Laboratories show the steepest procurement acceleration.
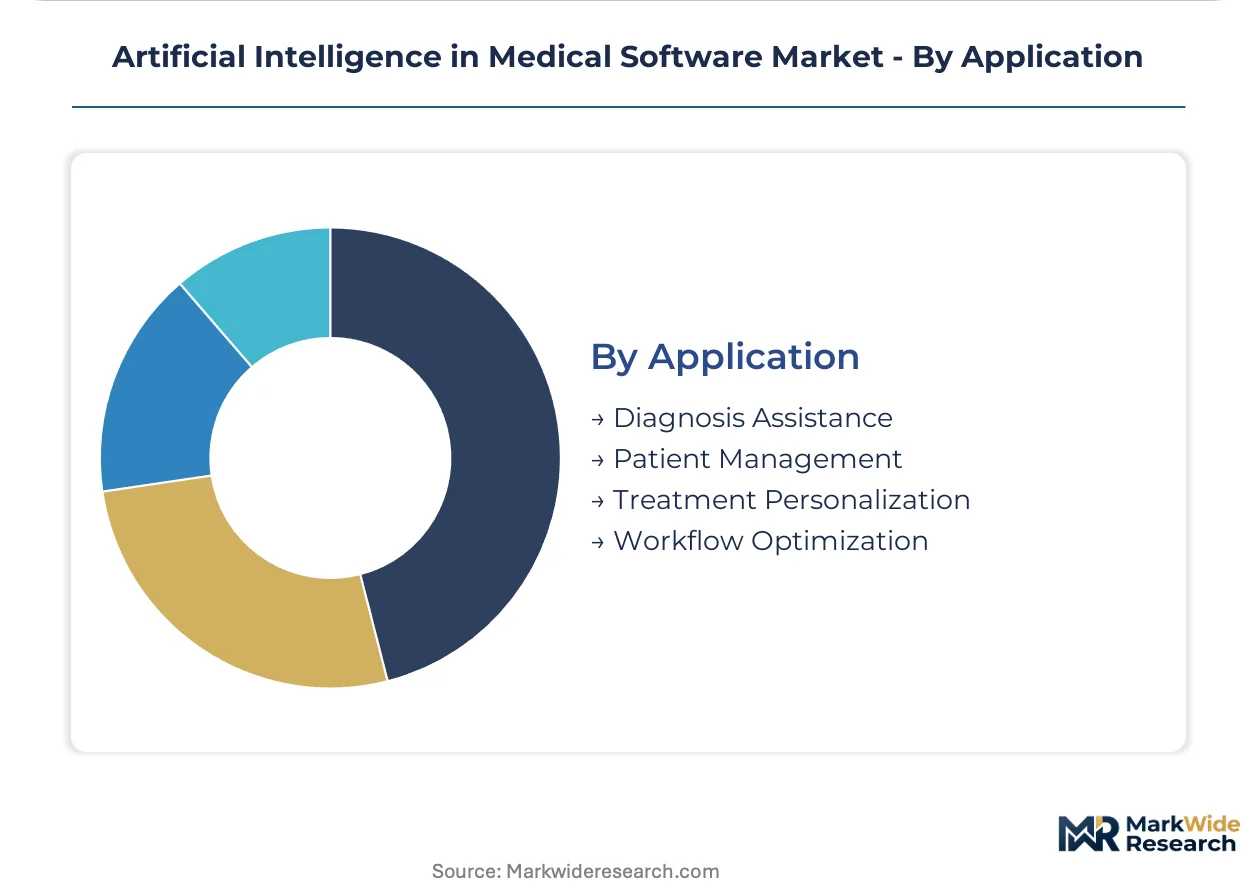
Application:
Application segmentation reflects where AI substitutes for cognitive tasks versus augmenting existing workflows.
- Diagnosis Assistance:Algorithms generating differential diagnoses or flagging critical findings for clinician confirmation. FDA-cleared diabetic retinopathy and lung nodule detection algorithms anchor commercial traction. China's NMPA domestic trial pathway accelerates approvals for locally validated algorithms.
- Workflow Optimization:Operational AI scheduling equipment utilization, staffing, and patient flow. Hospital systems facing margin pressure deploy these tools to extract capacity from fixed assets. Implementation requires custom API development with legacy infrastructure.
- Patient Management:Automated care coordination and population health stratification tools.
- Treatment Personalization:Genomic and pharmacokinetic modeling for therapy selection and dosing.
Diagnosis Assistance holds established revenue; Workflow Optimization is gaining share fastest as operational pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates algorithm development and cloud infrastructure investment, while Germany and Japan absorb disproportionate procurement volume for clinical deployment. China balances domestic regulatory acceleration with import substitution mandates.
United States
FDA premarket review under its AI/ML-based Software as a Medical Device framework accelerates commercialization timelines for algorithm developers. Hospital systems across the country concentrate demand for clinical decision support platforms that integrate with existing electronic health record infrastructure. Academic medical centers in Boston and the San Francisco Bay Area pilot multimodal foundation models for tumor board decision support.
Germany
Diagnostic laboratories in Bavaria and North Rhine-Westphalia are expanding procurement of AI-enabled imaging tools under EMA and EU MDR compliance deadlines. The EU AI Act risk classification imposes conformity assessment obligations that stratify the vendor landscape by compliance capability. Berlin hosts Siemens Healthineers AG headquarters, anchoring R&D intensity across computer vision algorithms for pathology workflows.
China
NMPA has established a dedicated AI medical device review pathway that accelerates domestic approvals while requiring local clinical trials. Hospital procurement committees in Shanghai and Beijing are consolidating algorithm procurement under centralized IT governance rather than departmental autonomy. The Yangtze River Delta region concentrates health system purchasing power for platforms with broad modular portfolios.
Japan
Health systems in Tokyo and Osaka are automating clinical documentation and coding workflows through natural language processing to address physician workforce constraints. METI guidance shapes reimbursement rules that tighten documentation requirements. The Kansai region shows accelerating adoption of transformer-based models extracting structured data from unstructured clinical notes.
United Kingdom
NHS procurement frameworks prioritize CE-marked algorithms with documented post-market monitoring protocols under EU MDR alignment periods. London and the Southeast concentrate health system purchasing committees revising vendor qualification criteria. The Midlands region hosts radiology divisions previously selecting AI tools independently, now routing decisions through enterprise architecture review boards.
Artificial Intelligence in Medical Software Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the AI medical software sector. NVIDIA Corporation anchors GPU compute infrastructure for training pipelines, while cloud-native entrants build atop rented silicon rather than captive fabrication. The market structures around three archetypes: hardware-embedded incumbents with imaging equipment captive demand, cloud-native algorithm specialists, and health IT platforms with EHR integration depth. Dominant competitive moves include strategic partnerships between chip vendors and device makers, plus portfolio diversification into adjacent clinical workflows.
Within the hardware-embedded tier, GE Healthcare and Siemens Healthineers AG occupy positions that leverage imaging equipment installed bases to drive proprietary software module adoption. NVIDIA Corporation exemplifies the infrastructure anchor archetype, supplying GPU architecture that radiology AI startups and established device makers alike depend upon for development pipelines. These three entities represent the concentration of technical and regulatory capability that filters lower-maturity developers from commercial traction.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| GE Healthcare |
| Siemens Healthineers AG |
| Microsoft |
| IBM |
| Intel Corporation |
| Nuance Communications, Inc. |
| Enlitic Inc. |
| Aidoc Medical |
| Others |
Pricing and Supply Chain Analysis
Machine learning engineer concentration in the San Francisco Bay Area and Boston anchors labor-cost differentials that widen pricing-tier spreads between premium FDA-cleared platforms and economy-grade diagnostic tools lacking regulatory validation.
Pricing Analysis
Margin tightening in cloud-hosted SaaS tiers reflects NVIDIA GPU supply allocation constraints and cloud pricing volatility. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA clearance status and EHR integration depth. Certification-grade differentiation separates CE-marked algorithms with post-market monitoring from unvalidated point solutions. Diagnostic laboratories in Germany show lowest price sensitivity due to EU MDR compliance mandates; outpatient clinics in emerging markets face acute cost-down pressure.
Supply Chain Analysis
Direct-to-hospital channels handle enterprise procurement for integrated delivery networks with centralized IT governance. GPU fabrication concentrates in Taiwan and South Korea; algorithm development clusters in the United States and China. Training infrastructure draws from NVIDIA A100/H100 accelerators, cloud compute credits, and annotated medical imaging datasets. Single-source vulnerability around NVIDIA supply allocation creates procurement risk. Distribution runs through health system GPO contracts and direct radiology vendor partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU AI Act third-party audit requirements erect barrier-to-entry moats favoring established players with dedicated regulatory affairs functions.
For Market Incumbents: To counter multimodal foundation model displacement of narrow single-task algorithms, anchor R&D investment in pathology and cardiology computer vision pipelines while deepening EHR integration moats through API standardization. Siemens Healthineers AG and GE Healthcare leverage imaging equipment installed bases to drive proprietary software module adoption.
For New Entrants and Emerging Players: Enter via clinical documentation automation in Japanese health systems facing physician workforce constraints and METI-guided reimbursement tightening. Natural language processing for coding workflows offers the most penetrable white-space target, with cloud-native deployment minimizing infrastructure barriers.
For Investors and Strategic Acquirers: Re-rating potential sits with cloud-native algorithm specialists possessing FDA-cleared imaging algorithms and proven hospital system partnerships given consolidation of procurement under enterprise IT governance. Long-term viability hinges on regulatory clearance velocity across FDA, EMA, and NMPA jurisdictions. Monitor divergence between EU AI Act implementation timelines and FDA premarket review pathway efficiency as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA AI/ML-based SaMD Submission | Accelerates commercialization timelines for algorithm developers seeking US market entry under premarket review pathway clarity. |
| CE Marking Pathway under EU MDR | Filters lower-maturity developers through expanded clinical validation requirements for high-risk AI system classification. |
| Hospital System Partnership | Captures procurement consolidation under centralized IT governance favoring vendors with broad modular portfolios. |
| Software Companion Development | Creates embedded AI demand within imaging hardware installed bases for proprietary module differentiation. |
| Reimbursement Strategy Alignment | Secures favorable coding for automated clinical documentation under METI guidance in Japanese health systems. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs leads at algorithm developers combined with FDA 510(k) databases, EMA submission records, and hospital procurement databases. Bottom-up modeling of algorithm deployment volumes and top-down validation against health system IT spending patterns ensured triangulation integrity.
Segmentation granularity modeled deployment architecture, integration complexity, regulatory clearance status, and end-user capital availability across the projection horizon. Technology-application intersections, geographic adoption patterns, and buyer archetype procurement behaviors structured the analytical framework. CAGRs derived from fitted growth curves against validated base-year estimates, with sensitivity testing around GPU supply constraints and regulatory timeline divergence.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NMPA domestic trial pathway acceleration or EU AI Act audit requirement delays. Periodic stress-testing of base assumptions is recommended given regulatory evidentiary standard divergence and cloud infrastructure pricing volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Donor Management Software Market
Medical Information Systems
Healthcare ERP Market
Medical Information Systems
Medical Coding Market
Medical Information Systems
Electronic Medical Record Market
Medical Information Systems
Ophthalmology EMR Software Market
Medical Information Systems
Medical Alert Systems Market
Medical Information Systems
AI in Medical Coding Market
Medical Information Systems
Medical Information Market
Medical Information Systems
Global Medical Writing Market
Medical Information Systems
AI in Medical Billing Market
Medical Information Systems
Medical Simulation Software Market
Medical Information Systems
Global Clinical Documentation Improvement Market
Medical Information Systems
Global Computerized Physician Order Entry Market
Medical Information Systems
Healthcare Information Software Market
Medical Information Systems
Global Medical Decision Support Systems for Sepsis Market
Medical Information Systems
Global Allergy EMR Software Market