
 ICD-10 Market | 2026-2036
ICD-10 Market Size, Share, and Industry Trends Forecast 2026-2036
ICD-10 Market Foresight
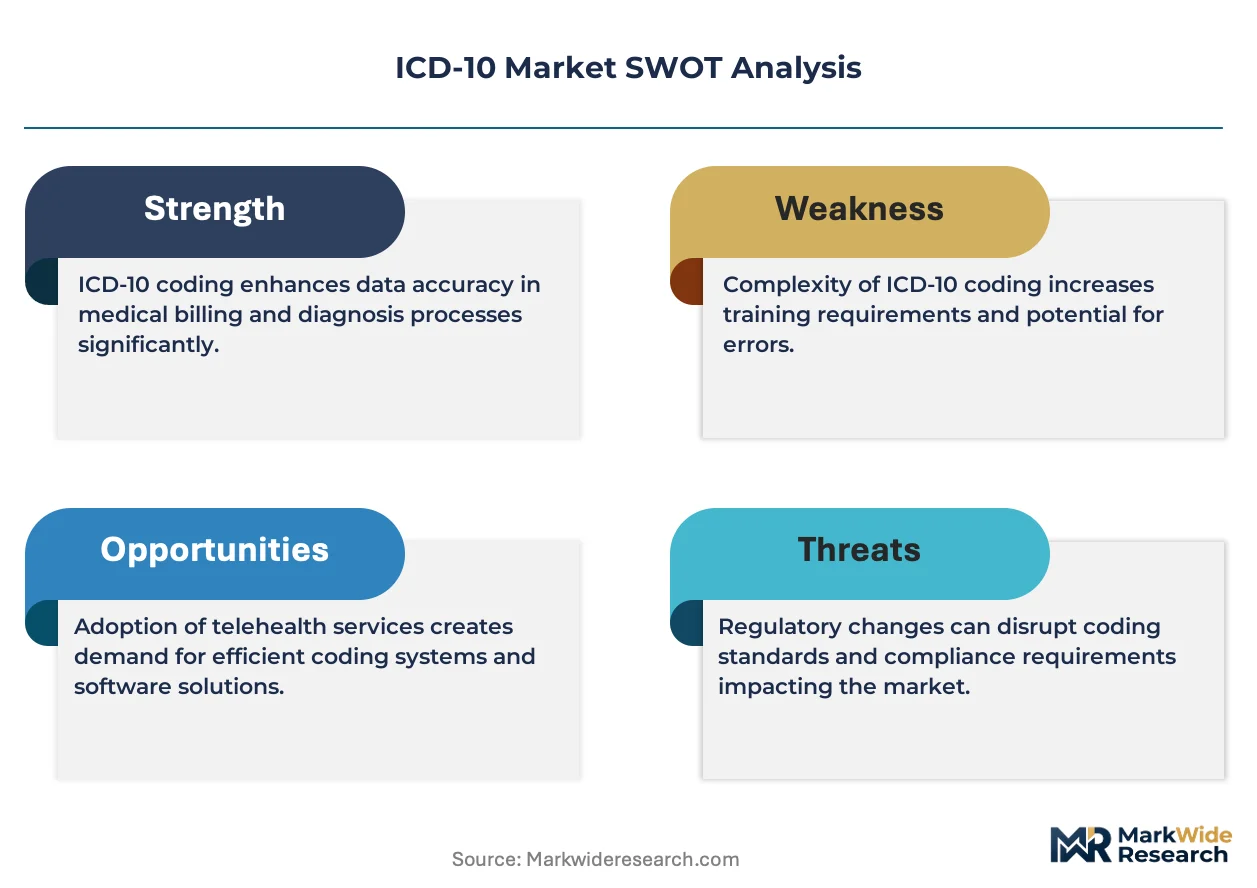
Legacy on-premise coding infrastructure is shifting toward cloud-native architectures as health systems seek elastic capacity for seasonal patient volume spikes. Epic Systems leverages deep EHR integration to anchor clinical documentation workflows across large hospital networks. Oracle Health competes through database-layer connectivity that sustains real-time analytics for coding accuracy audits. Nuance specializes in voice-enabled coding assistance that extends physician productivity in high-volume emergency departments.
ICD-10 constitutes the tenth revision of the International Classification of Diseases, a standardized alphanumeric coding system maintained by the World Health Organization that catalogs diagnoses, symptoms, and procedures for mortality and morbidity statistics, billing, and clinical research. The classification spans approximately 68,000 codes versus ICD-9's 13,000, enabling granular tracking of disease severity, laterality, and encounter context for population health management and reimbursement accuracy. Cloud-based deployment leads structural growth as health systems migrate capital expenditure to operational models with automatic regulatory updates. Revenue cycle management captures concentrated margin pools where coding accuracy directly determines claim acceptance rates and denial recovery velocity. Hospitals dominate end-user demand given their complex multi-specialty documentation requirements and exposure to Medicare severity diagnosis-related group adjustments.
The Centers for Medicare and Medicaid Services mandates ICD-10-CM and ICD-10-PCS for all HIPAA-covered transactions, shaping vendor product roadmaps around federal compliance timelines. The Office of the National Coordinator for Health Information Technology certifies EHR interoperability standards that determine market access for integrated coding platforms. Stakeholders must monitor whether artificial intelligence coding engines achieve sufficient accuracy thresholds to reduce human auditor dependency without triggering False Claims Act exposure.
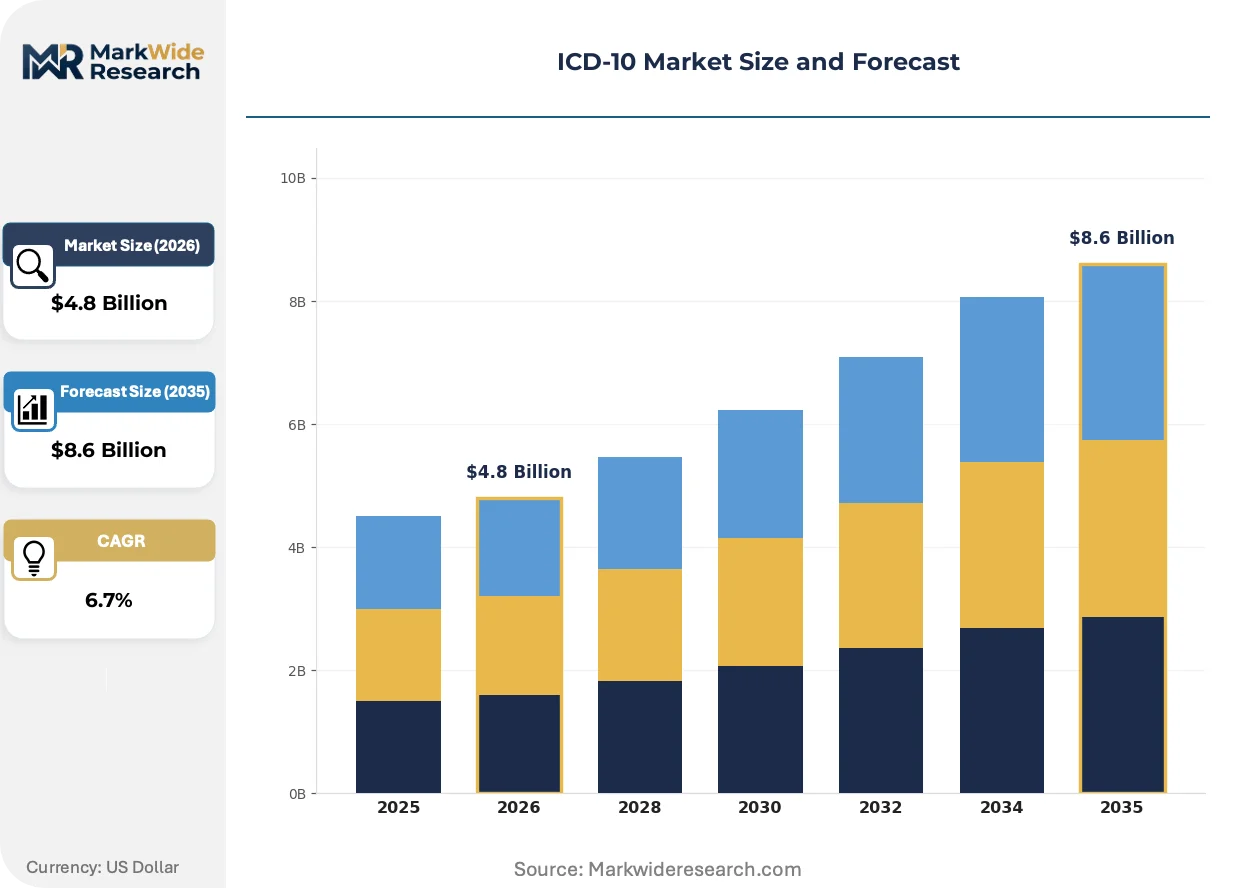
Market Dynamics
Cloud-native architectures are displacing on-premise coding infrastructure across hospital networks, driven by elastic capacity requirements for seasonal patient volume fluctuations and automatic regulatory update delivery.
Growth Catalysts
- Medicare Severity Diagnosis-Related Group Adjustments:CMS reimbursement formulas penalize coding inaccuracy, compelling hospitals to invest in automated clinical documentation improvement platforms.
- Natural Language Processing Engines:Voice-enabled coding assistance reduces physician administrative burden in high-volume emergency departments, accelerating encounter closure rates.
- Population Health Management:Granular ICD-10-CM specificity enables health systems to stratify risk and negotiate value-based contracts with commercial payers.
Market Restraints
- Implementation Cost Structure:Multi-year EHR integration projects require substantial capital allocation, straining community hospital balance sheets.
- Human Auditor Dependency:Artificial intelligence coding engines have not achieved accuracy thresholds sufficient to eliminate manual claim review without False Claims Act exposure.
- Legacy System Technical Debt:Decades-old billing platforms in rural health systems resist API-based connectivity with modern coding modules.
Strategic Opportunities
- Ambulatory Surgery Center Expansion:Freestanding surgical facilities in the United States lack sophisticated coding infrastructure, creating greenfield deployment potential.
- Real-Time Analytics Convergence:Database-layer connectivity with clinical decision support systems enables concurrent coding during patient encounters.
- India's Healthcare Digitization:Ayushman Bharat health insurance expansion mandates standardized diagnostic coding for reimbursement, opening implementation services demand.
Industry Challenges
- Certified Professional Coder Shortage:AAPC-credentialed specialists command premium compensation, constraining scaling velocity for revenue cycle management vendors.
- Interoperability Standard Complexity:ONC certification requirements for EHR integration create prolonged sales cycles and implementation delays.
- Physician Workflow Disruption:Documentation specificity demands generate clinician resistance, requiring change management investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ICD-10 Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Clinical Documentation, Medical Coding, Revenue Cycle Management, Patient Management End User: Hospitals, Physician Practices, Diagnostic Centers, Clinics Deployment: On-Premises, Cloud-Based, Hybrid, Remote Technology: Health Information Systems, EHR Solutions, Coding Software, Analytics Tools |
| Companies Covered | TransCure, AGS Health, GeBBS Healthcare, CureMD, The Coding Network, Epic Systems, Oracle Health, Solventum, Nuance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ICD-10 Market Shifts & Advancements
Artificial intelligence is restructuring clinical documentation workflows, compressing the gap between patient encounter and claim submission while raising accuracy thresholds for automated coding systems.
Computer-assisted coding software is modularizing around specialty-specific engines for cardiology, orthopedics, and emergency medicine. Large hospital networks deploy these modules incrementally rather than enterprise-wide, reducing implementation risk. This architecture is modularizing vendor competitive positioning, allowing best-of-breed point solutions to penetrate accounts held by integrated EHR incumbents.
The Office of the National Coordinator for Health Information Technology has tightened EHR interoperability certification standards, mandating standardized APIs for coding data exchange. Vendors must reengineer integration layers to maintain market access. Hospital IT departments are prioritizing platforms with pre-built ONC-compliant connectors, compressing vendor evaluation timelines.
Physician documentation behavior is shifting toward voice-first capture in high-velocity care settings. Emergency departments and urgent care centers are replacing keyboard-based coding workflows with ambient clinical intelligence. This pattern is most visible in United States health systems where clinician burnout has reached acute levels, forcing administrative burden reduction to the top of operational priorities.
ICD-10 Market Segmentation
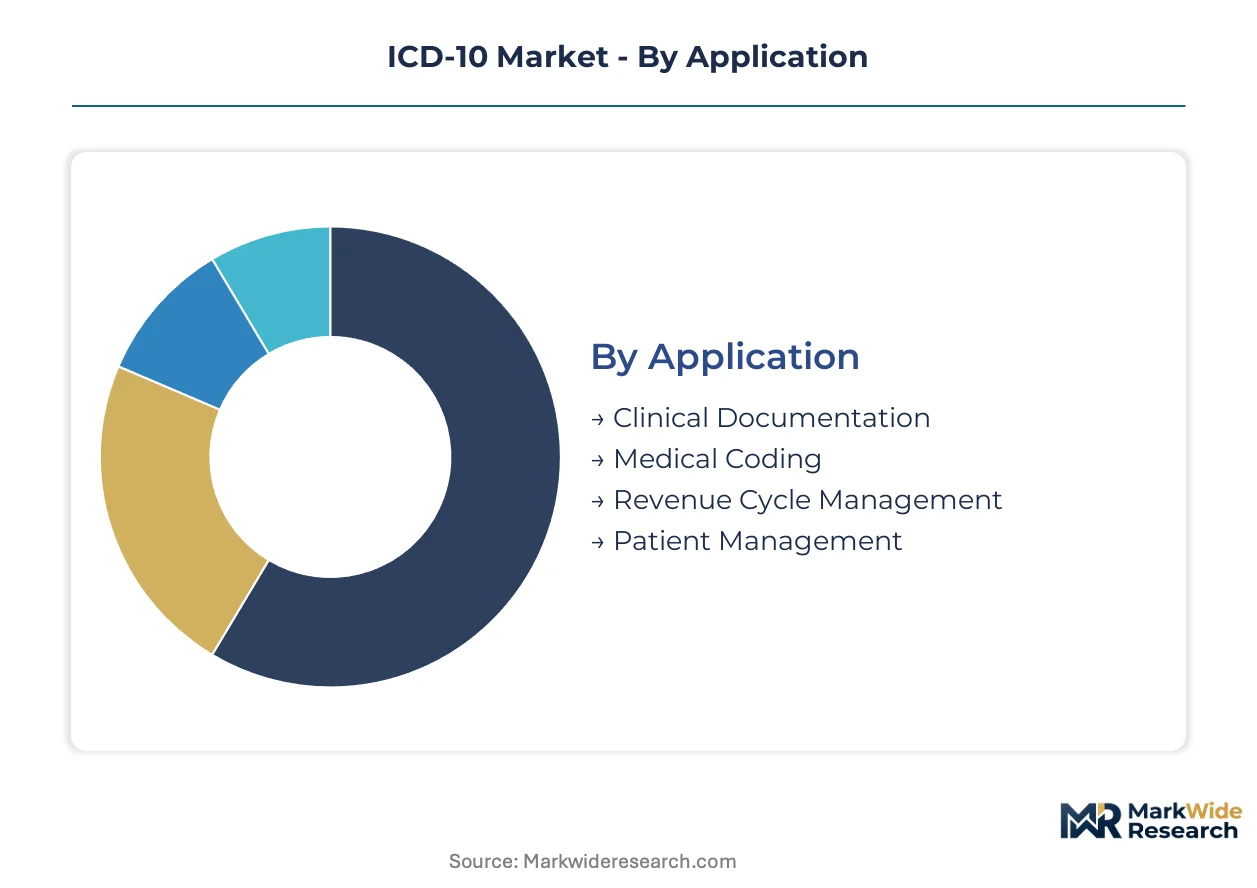
ICD-10 market segmentation reveals divergent technology maturity across healthcare delivery settings. Deployment models and application intensity vary sharply between capital-rich hospital networks and resource-constrained ambulatory sites.
Application:
Volume concentration sits with high-frequency administrative workflows, while premium value accumulates in specialized clinical domains.
- Clinical Documentation:Computer-assisted documentation platforms embed ICD-10 specificity at the point of care. Epic Systems and Oracle Health dominate deployment across United States academic medical centers where CMS reimbursement penalties for imprecise coding reach maximum severity.
- Revenue Cycle Management:End-to-end claim lifecycle platforms integrate coding accuracy audits with denial management workflows. Demand concentrates in multi-hospital health systems where Medicare Severity Diagnosis-Related Group adjustments directly impact operating margins.
- Medical Coding:Standalone coding workstations support certified professional coders in specialty practices.
- Patient Management:Population health stratification tools leverage ICD-10-CM granularity for risk scoring.
Mature deployment sits with Revenue Cycle Management. Newer deployment is concentrated in Clinical Documentation.
End User:
Customer sophistication spans from enterprise IT departments managing thousand-bed facilities to single-physician practices purchasing SaaS subscriptions.
- Hospitals:Complex multi-specialty documentation requirements drive demand for integrated EHR-coding platforms. United States hospital networks allocate substantial capital to cloud-native architectures that deliver automatic regulatory updates and elastic capacity for seasonal volume spikes.
- Physician Practices:Smaller patient panels and limited IT staffing favor lightweight, voice-enabled coding assistance. Nuance ambient clinical intelligence penetrates this segment where clinician burnout has elevated administrative burden reduction to operational priority.
- Diagnostic Centers:Imaging and laboratory workflows require procedure-specific coding modules.
- Clinics:Federally qualified health centers seek cost-effective solutions for Medicaid billing compliance.
Enterprise-grade deployment dominates Hospitals. Lightweight, rapid-deployment solutions are climbing fastest in Physician Practices.
Deployment:
Capital expenditure preferences are shifting toward operational models that transfer infrastructure risk to vendors.
- Cloud-Based:Subscription pricing with automatic CMS regulatory updates eliminates version migration projects. United States health systems lead migration away from on-premise data centers toward AWS and Azure-hosted coding platforms.
- Hybrid:Sensitive patient data remains on-premise while analytics workloads shift to cloud. Large hospital networks deploy this architecture where HIPAA security risk assessments mandate localized control of protected health information.
- On-Premises:Legacy installations persist in rural health systems with decades-old billing platform technical debt.
- Remote:Distributed coder workforces access centralized platforms through VPN connections.
Established infrastructure characterizes On-Premises. Cloud-Based architectures are gaining share fastest.
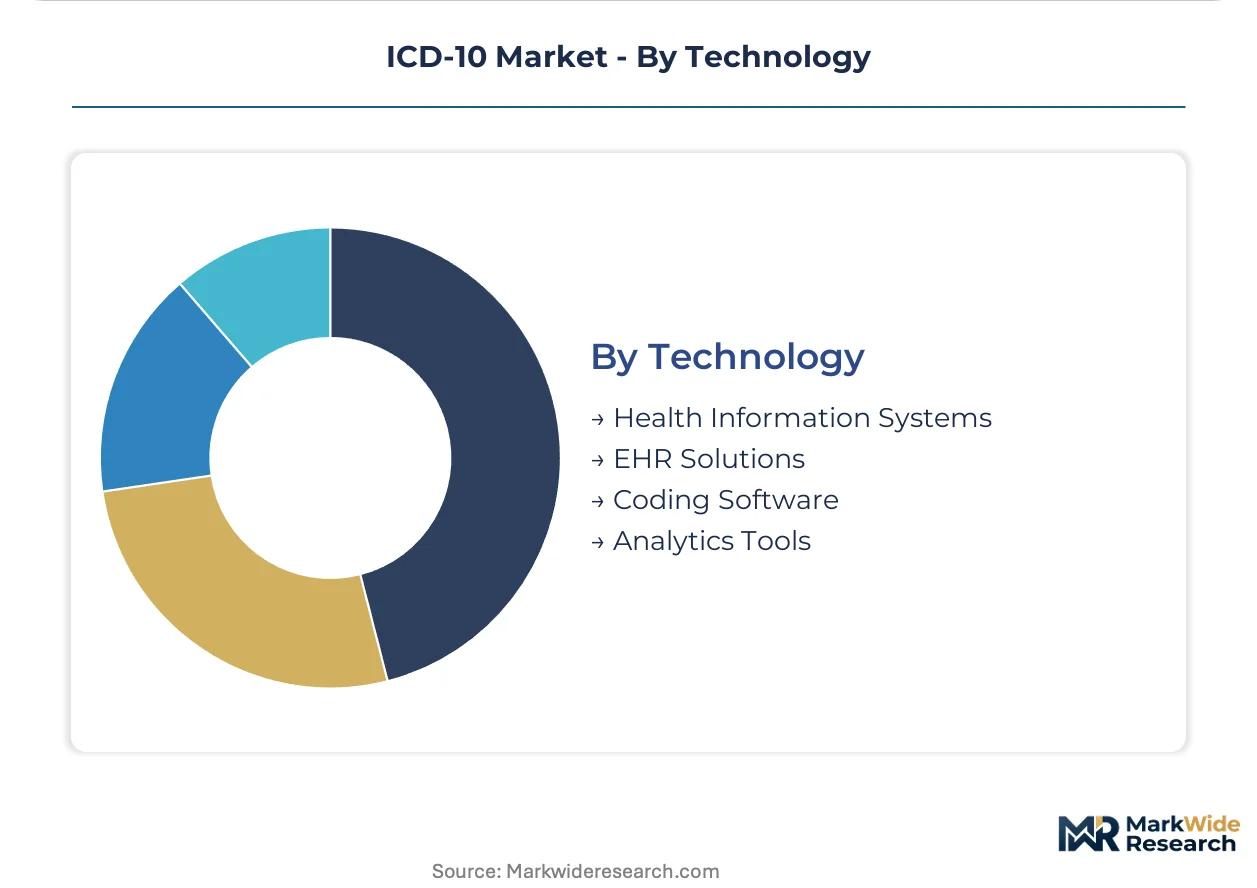
Technology:
Platform integration depth determines vendor competitive positioning across the technology stack.
- EHR Solutions:Deep clinical workflow integration anchors coding specificity at documentation origin. Epic Systems leverages this position to bundle coding modules with core EHR contracts across large United States hospital networks.
- Analytics Tools:Real-time coding accuracy dashboards enable concurrent audit during patient encounters. Oracle Health competes through database-layer connectivity that sustains population health reporting and reimbursement optimization.
- Health Information Systems:Enterprise data repositories support interoperability requirements.
- Coding Software:Standalone encoder applications serve specialty practices with limited EHR integration needs.
Deep integration defines EHR Solutions. Point-solution agility is expanding most quickly in Analytics Tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare technology special economic zones in Hyderabad and Bengaluru accelerate ICD-10 platform development, concentrating vendor R&D investment and implementation services capacity across select metropolitan clusters.
United States
Medicare Severity Diagnosis-Related Group reimbursement penalties drive hospital investment in automated coding platforms. The Centers for Medicare and Medicaid Services mandates ICD-10-CM and ICD-10-PCS for all HIPAA-covered transactions. Epic Systems anchors clinical documentation workflows across academic medical centers in Boston and the San Francisco Bay Area.
Germany
Hospital digitization programs under the Hospital Future Act fund EHR-coding integration projects. The Federal Institute for Drugs and Medical Devices oversees software certification for clinical decision support systems. Healthcare IT clusters in Munich and Berlin host implementation specialists serving Central European hospital networks.
India
Ayushman Bharat health insurance expansion mandates standardized diagnostic coding for reimbursement eligibility. The National Health Authority specifies ICD-10-CM compatibility for empaneled hospitals. Hyderabad's healthcare technology corridor attracts offshore medical coding operations serving United States health systems.
United Kingdom
NHS Digital's adoption of ICD-10 for secondary care classification drives procurement of coding accuracy platforms. The Medicines and Healthcare products Regulatory Agency regulates clinical software safety standards. London's hospital trusts pilot voice-enabled documentation tools in emergency department settings.
Australia
The Australian Institute of Health and Welfare maintains ICD-10-AM for national morbidity statistics, requiring hospital compliance investments. The Therapeutic Goods Administration certifies clinical software for safety and performance. Melbourne's digital health precinct hosts vendors specializing in population health analytics integration.
ICD-10 Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated EHR vendors commanding enterprise hospital accounts while standalone coding specialists penetrate ambulatory and mid-market sites. The vendor landscape organizes around three archetypes: EHR-anchored platforms, revenue cycle pure-plays, and voice-enabled documentation specialists. Consolidation pressure intensifies as health systems demand unified workflows spanning clinical documentation through claim submission. Strategic partnerships between coding vendors and cloud infrastructure providers accelerate migration away from on-premise deployments.
Within the EHR-anchored tier, Epic Systems and Oracle Health occupy positions defined by database-layer integration depth and enterprise-scale deployment capacity. Nuance exemplifies the voice-enabled specialist archetype, with ambient clinical intelligence products targeting physician burnout reduction in high-velocity care settings. AGS Health and GeBBS Healthcare represent the revenue cycle pure-play segment, offering implementation and managed services that transfer operational risk from hospital billing departments.
| Leading Market Players |
|---|
| TransCure |
| AGS Health |
| GeBBS Healthcare |
| CureMD |
| The Coding Network |
| Epic Systems |
| Oracle Health |
| Solventum |
| Nuance |
| Others |
Supply & Pricing Matrix
HIPAA security risk assessment mandates gate qualified supply for cloud-native coding platforms and determine premium-tier pricing access for health systems requiring localized PHI control. Cloud infrastructure vendors with FedRAMP authorization command pricing power over uncertified competitors, while hybrid deployment premiums reflect the cost of maintaining on-premise data sovereignty alongside elastic cloud capacity.
Pricing Analysis
Short lead-time deployment premiums attach to pre-built ONC-compliant connectors that compress hospital IT evaluation timelines. The market operates on a subscription-SaaS tiered model with annual contracts scaling by bed count and encounter volume. Price differentiation rests on EHR integration depth and voice-enabled specialty module availability. Pricing pressure stems from certified professional coder shortages that force vendors to absorb training costs. Community hospital networks exhibit highest price sensitivity; academic medical centers prioritize compliance-grade features over cost.
Supply Chain Analysis
Dual-sourcing requirements in United States health systems mandate multi-cloud qualification across AWS and Azure for operational resilience. Supply concentration centers on India for offshore medical coding operations, the United States for EHR platform engineering, and Germany for clinical decision support certification. Raw material dependencies include NLP training datasets, specialized medical ontologies, and API middleware licenses. Single-source vulnerability sits with Epic Systems' deep EHR integration moat. Distribution runs through direct enterprise sales teams serving hospital networks and channel partners penetrating physician practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native architectures are displacing legacy on-premise coding infrastructure across hospital networks, with ambient clinical intelligence replacing keyboard-based physician workflows. This technology transition phase demands strategic repositioning across stakeholder archetypes.
For Market Incumbents:Cement EHR integration depth as the primary defensive moat against standalone AI coding entrants. Acquire voice-enabled documentation specialists to neutralize Nuance's ambient intelligence advantage. Expand FedRAMP and HIPAA BAA certification coverage to maintain premium pricing access in United States federal and academic hospital segments.
For New Entrants and Emerging Players:Natural language processing-first wedges penetrate ambulatory surgery centers lacking sophisticated coding infrastructure. Target India's empaneled Ayushman Bharat hospitals where standardized diagnostic coding mandates create greenfield implementation demand. Pursue white-label partnerships with existing revenue cycle pure-plays to bypass lengthy ONC certification cycles.
For Investors and Strategic Acquirers:CMS reimbursement penalty rate adjustments are the leading indicator that automated clinical documentation improvement platforms will capture disproportionate capital allocation. Long-term viability favors vendors with concurrent coding capabilities that compress encounter-to-claim timelines. Monitor AAPC-certified coder wage inflation as the signal for AI substitution inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep Epic Systems and Oracle Health EHR embedding secures hospital network renewals. |
| Acquisition of Specialist Firm | Voice-enabled coding modules address clinician burnout in emergency departments. |
| Geographic Expansion | India's Ayushman Bharat coding mandates open implementation services revenue pools. |
| Strategic Partnership | Cloud infrastructure alliances with AWS and Azure transfer capital expenditure risk. |
| Product Launch | Specialty-specific cardiology and orthopedics engines modularize competitive positioning. |
Research Methodology
CMS Medicare reimbursement databases, hospital procurement contract filings, and ONC interoperability certification records formed the secondary backbone. Primary interviews with revenue cycle management executives, certified professional coders, hospital IT procurement officers, and EHR integration specialists validated demand-side assumptions. Bottom-up and top-down triangulation cross-referenced vendor revenue disclosures against health system technology spend surveys.
Bottom-up modeling anchored volume estimates in hospital bed counts, encounter volumes, and coding workstation deployment ratios across the projection horizon. Segmentation dimensions included deployment model, end-user setting, application workflow, and technology integration depth. CAGRs were derived from elasticity-adjusted pricing trajectories and technology substitution curves. Forecast inputs incorporated CMS regulatory update cadence and AAPC credentialing pipeline constraints.
Several conditions sit outside the modeled scope, including False Claims Act enforcement intensity and artificial general intelligence breakthroughs in autonomous coding. Forecasts reflect assumptions around human auditor retention thresholds and cloud migration velocity. Deviation in CMS reimbursement penalty severity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Case Coder Market
Medical Information Systems
Medical Software Market
Medical Information Systems
Medical Coding Market
Medical Information Systems
Global Oncology Information System Market
Medical Information Systems
Ophthalmology EMR Software Market
Medical Information Systems
Urology EMR Software Market
Medical Information Systems
Master Patient Index Software Market
Medical Information Systems
India EMR (Electronic Medical Records) Market
Medical Information Systems
Hospital Information Systems Market
Medical Information Systems
Global Clinical Information System Market
Medical Information Systems
Ambulatory Software Market
Medical Information Systems
Healthcare Information Governance Solution Market
Medical Information Systems
US Healthcare ERP Market
Medical Information Systems
Healthcare ERP Market
Medical Information Systems
Medical Alert Systems Market
Medical Information Systems
AI in Medical Billing Market