
 China Scar Treatment Market | 2026-2036
China Scar Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
China Scar Treatment Market Insights
China's dual carbon goals and green healthcare procurement mandates from the National Health Commission are shifting hospital purchasing criteria toward energy-efficient laser platforms and biodegradable topical formulations. Cynosure, Inc. leverages its established service infrastructure across tier-one cities to sustain recurring revenue from device maintenance contracts. Mölnlycke Health Care anchors the premium silicone dressing segment through direct supply agreements with burn centers. Beijing Toplaser Technology Co., Ltd. competes aggressively on localized regulatory compliance and domestic manufacturing cost structures.
Scar treatment encompasses medical and aesthetic interventions designed to remodel collagen architecture, reduce fibrous tissue visibility, and restore functional skin elasticity through pharmacological, thermal, or mechanical modalities. Laser therapy systems typically operate at wavelengths between 585 nm and 10,600 nm, targeting hemoglobin or water chromophores to induce controlled dermal remodeling. Topical solutions command the largest volume share due to low entry barriers and pharmacy accessibility, while laser therapy captures disproportionate value per procedure in dermatology centers. Surgical treatments occupy a mature, hospital-dependent niche with stable but slower expansion trajectories.
NMPA's Class III medical device registration requirements and GB standards for laser safety equipment shape product development timelines and market entry costs for international manufacturers. The country's dual carbon goals and provincial green procurement policies increasingly influence hospital capital expenditure decisions, favoring equipment with lower energy consumption profiles. Stakeholders must monitor NMPA's evolving technical review guidelines for combination devices and anticipate how municipal green building standards for healthcare facilities will reshape installation requirements.
Market Dynamics
NMPA's streamlined Class III medical device approval pathway is compressing domestic innovation cycles while dual carbon procurement mandates from the National Health Commission restructure hospital capital allocation toward energy-efficient laser platforms.
Growth Catalysts
- Dual carbon goals:Municipal green building standards for healthcare facilities are accelerating replacement demand for low-energy laser systems in Shanghai's private dermatology corridor.
- Urban millennials:Rising aesthetic consciousness among this demographic is expanding clinic-based laser therapy volumes beyond traditional burn and trauma reconstruction.
- GB standards alignment:Streamlined laser safety equipment certification is reducing domestic manufacturers' time-to-market for combination devices.
Market Restraints
- Import component dependency:High-power laser diodes and precision optical assemblies concentrate supply among German and Japanese specialty manufacturers, exposing domestic device makers to input cost volatility and extended lead times.
- NMPA technical review complexity:Evolving guidelines for combination devices incorporating both thermal and pharmacological modalities create regulatory friction, extending registration timelines for novel hybrid platforms.
- Silicone raw material concentration:Medical-grade silicone feedstock for topical dressings relies on concentrated petrochemical supply chains, subjecting Mölnlycke Health Care and domestic competitors to feedstock price swings.
Strategic Opportunities
- Tier-two city penetration:Chengdu and Hangzhou hospital networks remain underpenetrated for fractional CO2 laser systems, offering whitespace for equipment vendors with localized service infrastructure.
- Biodegradable topical convergence:Combination of hyaluronic acid microspheres with polylactic acid scaffolds creates next-generation dressing categories aligned with green procurement mandates.
- Direct-to-clinic distribution:Bypassing traditional medical device distributors through manufacturer-owned service contracts is capturing margin and shortening replacement cycles.
Industry Challenges
- Laser safety officer certification:Shortage of clinicians trained to GB standards for Class IV laser operation limits installation throughput in expanding hospital networks.
- Legacy device integration:New energy-efficient platforms face interoperability friction with existing electronic medical record systems and treatment planning software in Beijing's tertiary hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Scar Treatment Market |
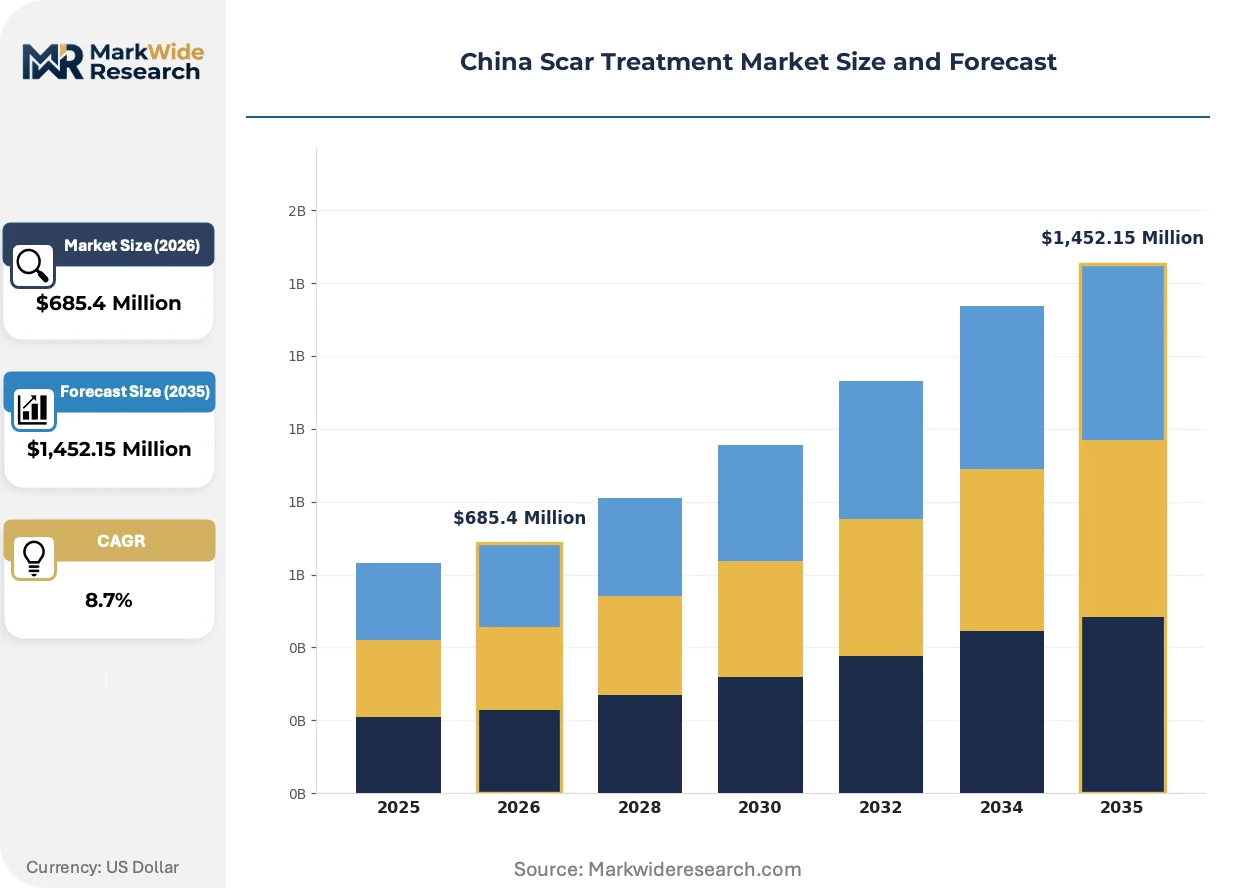
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Solutions, Laser Therapy, Surgical Treatments, Injectable Fillers End User: Hospitals, Clinics, Homecare, Dermatology Centers Application: Acne Scars, Surgical Scars, Keloid Scars, Stretch Marks Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Direct Sales |
| Companies Covered | Cynosure, Inc., Syneron Medical Ltd., Mölnlycke Health Care, Ostar Beauty Sci-Tech Co., Ltd., Shanghai Fosun Pharmaceutical Co. Ltd., Beijing Toplaser Technology Co., Ltd., Merz Pharma, Smith & Nephew PLC, Lumenis, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Scar Treatment Market Trends and Innovations
Fractional laser technology is overtaking continuous-wave systems in dermatology centers, while biodegradable polymer formulations and direct service contracting models are simultaneously restructuring product and channel economics.
Picosecond-domain laser systems operating at 755 nm and 1064 nm wavelengths is overtaking nanosecond platforms for hypertrophic scar remodeling. Shanghai's private dermatology corridor is adopting these devices at twice the replacement pace of conventional CO2 systems. The technology is overtaking established pricing benchmarks by enabling premium per-procedure positioning while reducing thermal collateral damage and shortening recovery protocols.
NMPA's evolving technical review guidelines for combination devices are mandating separate clinical evidence packages for thermal and pharmacological components. Domestic manufacturers must now generate distinct safety and efficacy datasets for hybrid platforms incorporating laser delivery with topical active agents. The regulation most affects Beijing's tertiary hospital networks, which are responding by consolidating procurement around single-modality devices with established registration histories.
Clinic procurement committees are unbundling after-sales service from equipment purchase contracts, creating standalone maintenance subscription markets. Device vendors now compete on service response time and spare parts availability rather than bundled warranty periods. This pattern is most visible in Shanghai's private dermatology corridor, where Cynosure's established service infrastructure sustains recurring revenue independent of new system sales.
China Scar Treatment Market Segmentation
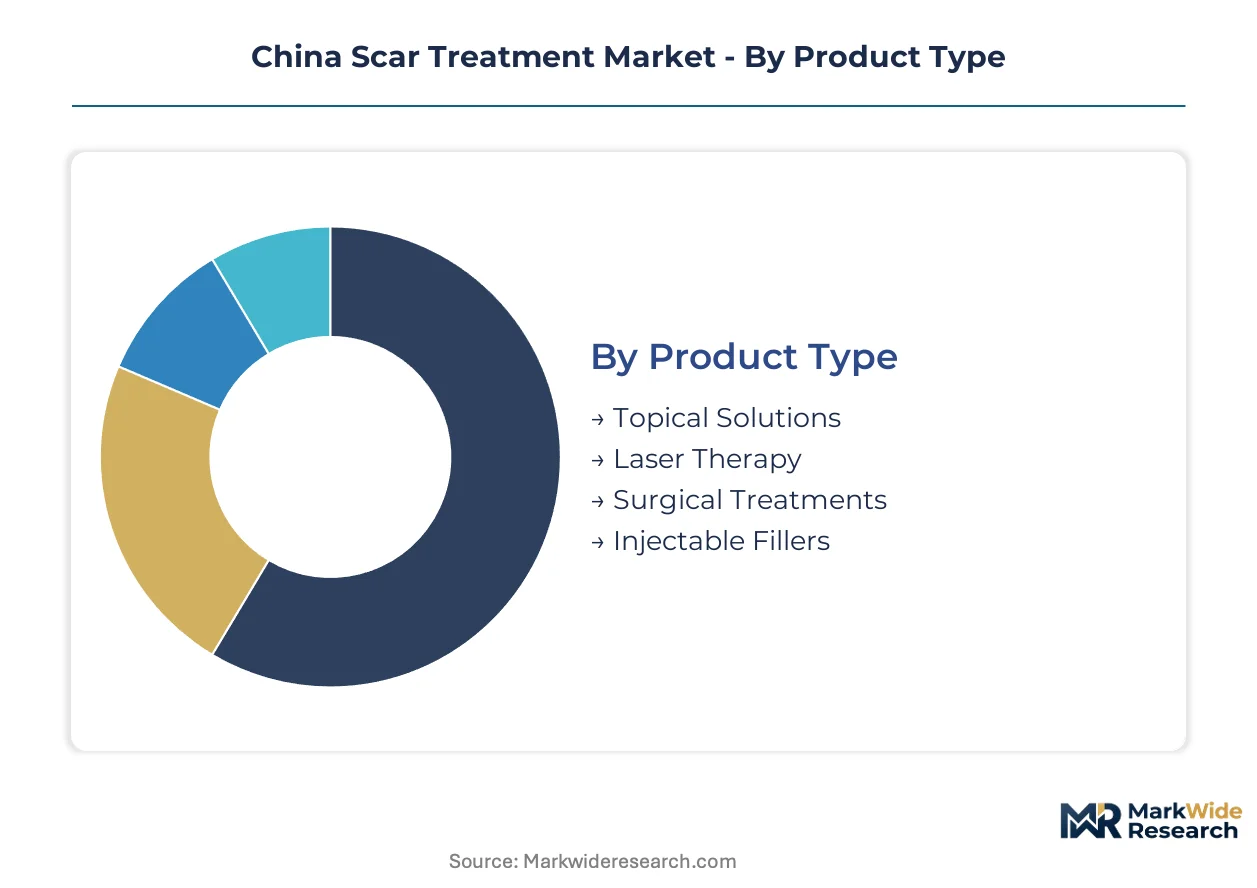
Segmentation in China's scar treatment market reveals divergent regulatory pathways and margin structures. Product type determines NMPA classification burden, while end-user concentration shapes channel economics and service intensity requirements.
Product Type:
Certification requirements split sharply across this category: Class III medical device registration governs laser systems and surgical instruments, while topical formulations navigate cosmetic or pharmaceutical pathways depending on active ingredient claims.
- Laser Therapy:Systems operating at 585 nm to 10,600 nm wavelengths target hemoglobin or water chromophores for controlled dermal remodeling. Demand concentrates in Shanghai's private dermatology corridor, where NMPA's streamlined Class III approval pathway is accelerating domestic innovation cycles.
- Topical Solutions:Silicone-based gels, sheets, and biodegradable polymer formulations command volume leadership through pharmacy accessibility and low entry barriers. Beijing's tertiary hospital networks favor premium silicone dressings for burn center protocols, though green procurement mandates are shifting criteria toward biodegradable alternatives.
- Surgical Treatments:Scar revision procedures and tissue expansion techniques occupy hospital-dependent niches with stable expansion trajectories.
- Injectable Fillers:Hyaluronic acid and polylactic acid microspheres address atrophic scar depression through minimally invasive delivery.
Leading the category by volume: Topical Solutions. Growing fastest: Laser Therapy.
End User:
Service intensity and procurement authority vary dramatically across this dimension, with capital expenditure decisions concentrating in hospital procurement committees while clinic networks prioritize per-procedure economics.
- Dermatology Centers:Shanghai's private dermatology corridor drives disproportionate value capture for fractional CO2 and picosecond laser platforms. Cynosure's established service infrastructure sustains recurring revenue through maintenance contracts independent of new system sales.
- Hospitals:Beijing's tertiary hospital networks anchor demand for combination devices and surgical reconstruction, though NMPA's evolving technical review guidelines for hybrid platforms are consolidating procurement around single-modality devices with established registration histories.
- Clinics:Tier-two city networks in Chengdu and Hangzhou remain underpenetrated for advanced laser systems, offering whitespace for vendors with localized service infrastructure.
- Homecare:Pharmacy-distributed topical solutions and silicone dressings serve post-procedure maintenance and mild scar management.
Highest margin concentration: Dermatology Centers. Steepest expansion trajectory: Clinics.
Application:
Treatment complexity and reimbursement eligibility diverge across scar etiologies, with trauma reconstruction commanding hospital budgets and aesthetic indications driving private clinic volumes.
- Acne Scars:Fractional laser resurfacing and injectable fillers dominate this aesthetic-heavy segment. Urban millennials in Shanghai and Beijing are expanding clinic-based laser therapy volumes beyond traditional medical reconstruction.
- Surgical Scars:Hypertrophic and keloid-prone post-surgical marks require combination approaches. NMPA's technical review complexity for thermal-pharmacological hybrid platforms creates regulatory friction in this application.
- Keloid Scars:Aggressive fibroproliferative responses demand specialized intervention protocols and carry higher recurrence risk.
- Stretch Marks:Aesthetic laser and topical collagen-stimulating treatments address striae distensae with variable efficacy.
Largest addressable population: Acne Scars. Most specialized intervention requirements: Keloid Scars.
Distribution Channel:
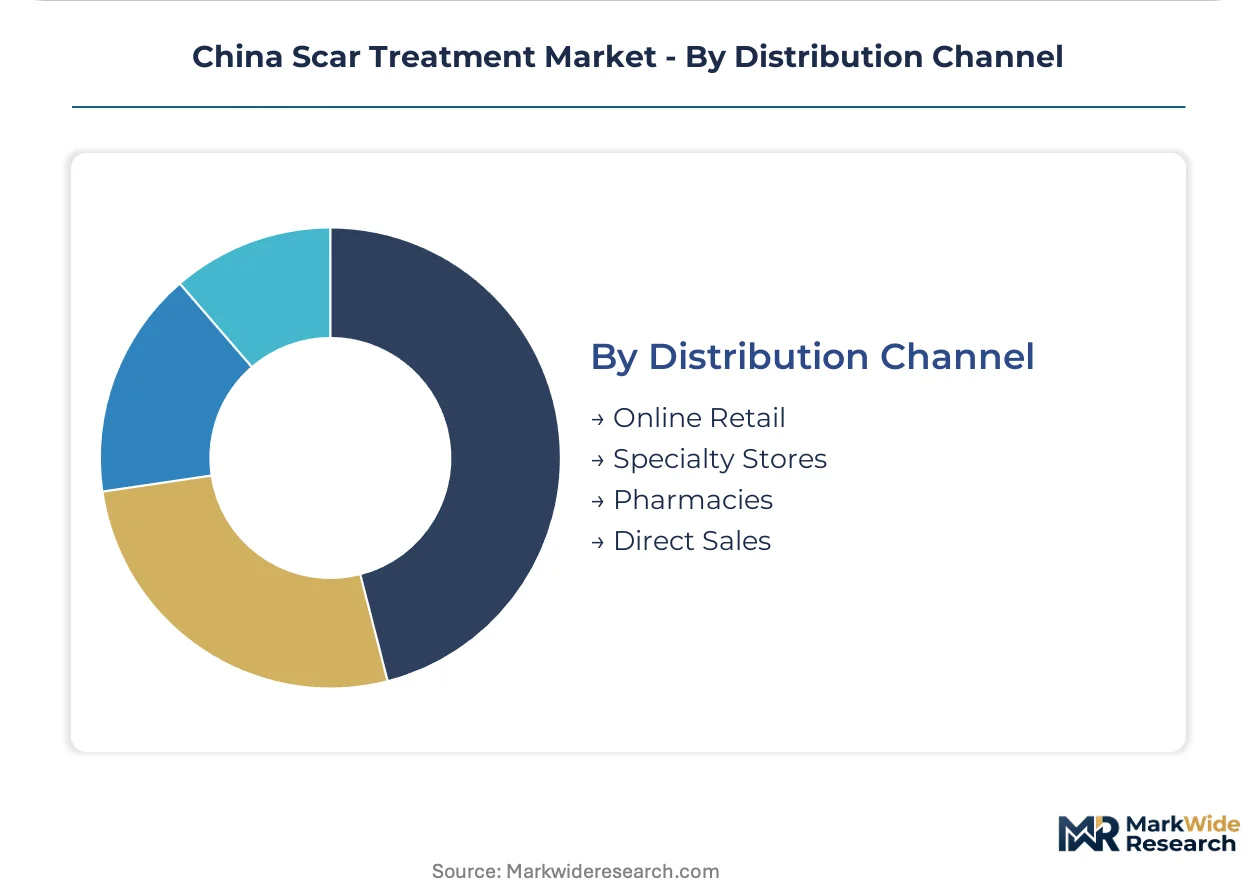
Channel selection directly determines margin retention and customer relationship depth, with direct models capturing service subscription value while retail pathways maximize volume reach.
- Direct Sales:Manufacturer-owned service contracts are capturing margin and shortening replacement cycles in Shanghai's private dermatology corridor. Clinic procurement committees are unbundling after-sales service from equipment purchase contracts, creating standalone maintenance subscription markets.
- Pharmacies:Topical silicone gels and sheets achieve broad accessibility through retail pharmacy networks, though green procurement mandates are beginning to influence formulary decisions.
- Specialty Stores:Medical device retailers serve intermediate segments with moderate clinical oversight requirements.
- Online Retail:E-commerce platforms expand geographic reach for established topical brands with NMPA cosmetic or pharmaceutical registrations.
Highest service attachment: Direct Sales. Widest geographic coverage: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of laser therapy systems clusters in Beijing and Shanghai, while consumption spreads across tier-one and tier-two hospital networks. NMPA's regulatory gravity concentrates device innovation in these coastal manufacturing hubs.
Beijing-Tianjin-Hebei
Tertiary hospital networks anchor demand for combination devices and surgical reconstruction protocols. NMPA's evolving technical review guidelines for hybrid platforms are consolidating procurement around single-modality devices with established registration histories. Beijing's medical device corridor hosts domestic manufacturers competing on localized regulatory compliance.
Yangtze River Delta
Shanghai's private dermatology corridor drives disproportionate value capture for fractional CO2 and picosecond laser platforms. Municipal green building standards for healthcare facilities are accelerating replacement demand for low-energy laser systems. Cynosure's established service infrastructure sustains recurring revenue through maintenance contracts independent of new system sales.
Pearl River Delta
Guangzhou and Shenzhen clinic networks are expanding laser therapy volumes beyond traditional burn reconstruction into aesthetic indications. Provincial green procurement policies increasingly influence hospital capital expenditure decisions, favoring equipment with lower energy consumption profiles. Manufacturing subcontractors for precision optical assemblies concentrate in Dongguan industrial zones.
Sichuan-Chongqing
Chengdu hospital networks remain underpenetrated for advanced fractional CO2 laser systems, offering whitespace for vendors with localized service infrastructure. Western China development initiatives are expanding healthcare infrastructure investment in secondary cities. Chongqing's medical device distribution hubs serve as gateway points for equipment penetration into central provinces.
Shandong Peninsula
Qingdao and Jinan manufacturing zones host silicone dressing producers supplying domestic burn center networks. Medical-grade silicone feedstock reliance on concentrated petrochemical supply chains subjects regional producers to feedstock price volatility. Provincial health commission procurement frameworks are beginning to incorporate biodegradable formulation preferences into formulary decisions.
China Scar Treatment Market Competitive Landscape
The competitive structure tilts toward multinational device manufacturers with established service infrastructure. Domestic players compete aggressively on NMPA registration speed and manufacturing cost structures. Two strategic archetypes dominate: global laser system vendors with recurring revenue service models, and regional topical formulation specialists with pharmacy distribution depth. Competitive moves concentrate on direct-to-clinic distribution bypass and biodegradable product line expansion.
Among multinational laser therapy vendors, Cynosure, Inc. and Lumenis occupy positions anchored by maintenance contract revenue streams. Beijing Toplaser Technology Co., Ltd. exemplifies the domestic regulatory compliance archetype, while Mölnlycke Health Care represents premium silicone dressing specialists with burn center supply agreements. These three entities illustrate the market's tripartite segmentation across service-intensive devices, localized manufacturing, and specialty topical formulations.
| Leading Market Players |
|---|
| Cynosure, Inc. |
| Syneron Medical Ltd. |
| Mölnlycke Health Care |
| Ostar Beauty Sci-Tech Co., Ltd. |
| Shanghai Fosun Pharmaceutical Co. Ltd. |
| Beijing Toplaser Technology Co., Ltd. |
| Merz Pharma |
| Smith & Nephew PLC |
| Lumenis |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap silicone dressing producers anchor China's topical scar treatment supply base, transmitting feedstock volatility directly into hospital formulary pricing while constraining margin flexibility for multinational competitors.
Pricing Analysis
Cost-down pressure on premium laser systems accelerates as Beijing's tertiary hospital procurement committees unbundle after-sales service from equipment purchase contracts. Pricing stratifies across premium, standard, and economy tiers based on NMPA Class III certification status and bundled maintenance subscription depth. Domestic manufacturers compete aggressively on manufacturing cost structures, forcing margin compression on imported platforms. Dermatology centers in Shanghai's private corridor exhibit lowest price sensitivity due to premium per-procedure positioning, while tier-two city clinics in Chengdu and Hangzhou demand aggressive equipment financing terms.
Supply Chain Analysis
GB standards laser safety certification gates component sourcing for domestic device manufacturers, restricting high-power laser diode procurement to qualified German and Japanese specialty suppliers. Precision optical assemblies concentrate in Dongguan industrial zones, while medical-grade silicone feedstock draws from Shandong Peninsula petrochemical corridors. Single-source vulnerability in specialty optical coatings exposes domestic manufacturers to extended lead time volatility. Distribution runs through manufacturer-owned service contracts in tier-one cities, shifting to regional medical device distributors for western China penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
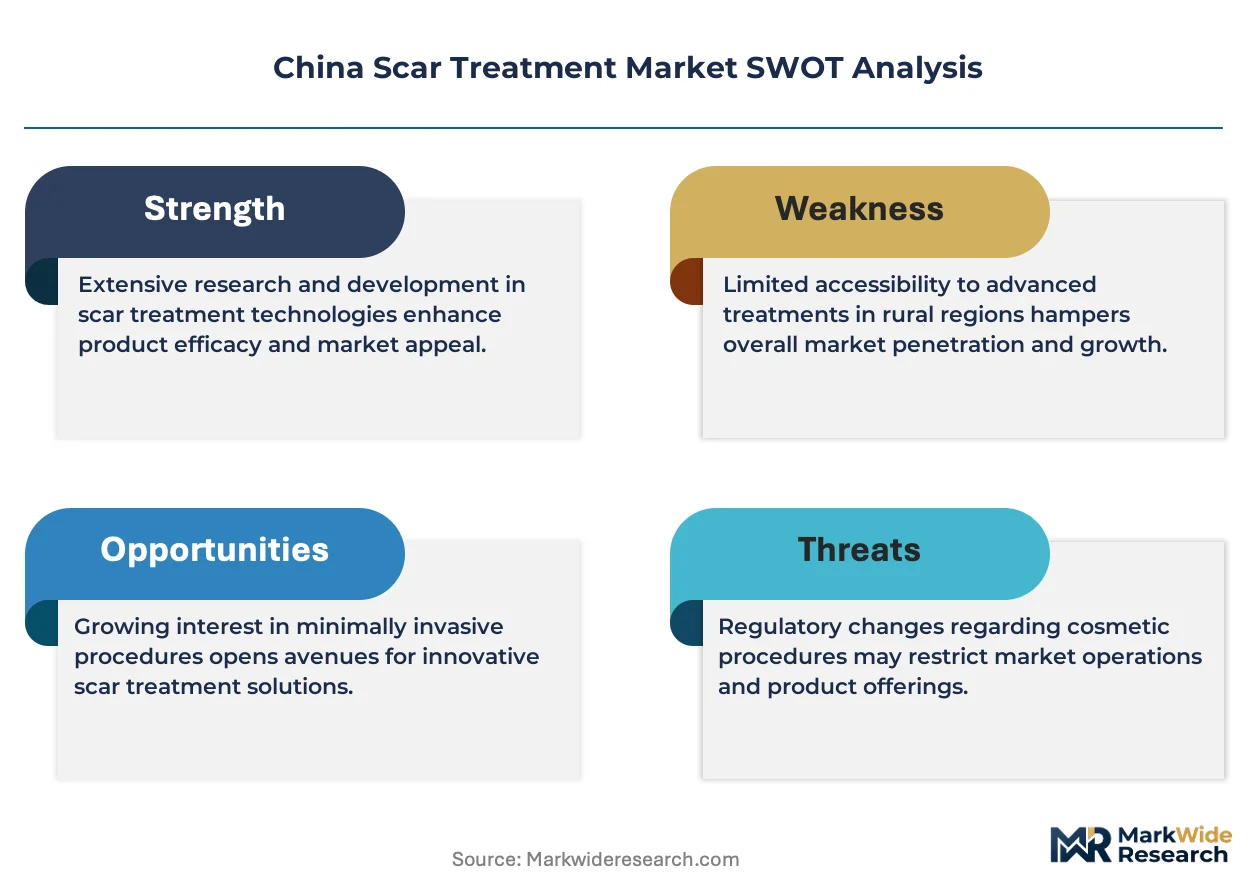
China's scar treatment market is becoming a vertical-integration race, with domestic manufacturers pursuing backward integration into precision optical component production to escape import dependency on German and Japanese laser diode suppliers.
For Market Incumbents: Deepen captive service infrastructure in Shanghai's private dermatology corridor to defend maintenance contract revenue against emerging domestic competitors with localized regulatory compliance speed. Consolidate procurement relationships with Beijing's tertiary hospital networks before NMPA's evolving technical review guidelines for combination devices further extend registration timelines for hybrid platforms. Prioritize energy-efficient laser platform R&D to align with National Health Commission dual carbon procurement mandates reshaping capital expenditure criteria. For New Entrants and Emerging Players: Launch via direct-to-clinic distribution bypassing traditional medical device distributors to capture margin and accelerate replacement cycle penetration in underpenetrated Chengdu and Hangzhou hospital networks. Target biodegradable topical formulation segments where green procurement mandates are shifting hospital formulary preferences away from conventional silicone dressings. Exploit whitespace in tier-two city fractional CO2 laser installation by offering manufacturer-owned service contracts with guaranteed spare parts availability. For Investors and Strategic Acquirers: NMPA's streamlined Class III approval pathway accelerating domestic innovation cycles is the leading indicator that regulatory compliance speed will determine long-term competitive viability. Acquisition target archetype: vertically integrated mid-cap specialists with captive silicone polymer production and established burn center supply agreements. Monitor municipal green building standards adoption velocity across provincial health commissions as the inflection signal for energy-efficient laser platform replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Optics | Reduces dependency on German and Japanese laser diode suppliers for domestic device manufacturers. |
| Biodegradable Formulation Development | Aligns product portfolios with National Health Commission green procurement mandates reshaping hospital formulary decisions. |
| Direct-to-Clinic Distribution Launch | Bypasses traditional medical device distributor margins and shortens replacement cycles in tier-two city networks. |
| GB Standards Laser Safety Certification Investment | Accelerates NMPA Class III registration timelines for combination devices entering Beijing's tertiary hospital procurement. |
| Energy-Efficient Platform R&D Expansion | Positions equipment vendors for dual carbon procurement preference in Shanghai's municipal green building standard compliance. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining structured interviews with dermatology center procurement directors, hospital biomedical engineers, NMPA regulatory affairs specialists, and silicone dressing supply chain managers. Primary fieldwork validated against NMPA Class III device registration databases, GB standards laser safety equipment certification records, National Health Commission green procurement policy documents, and provincial hospital capital expenditure disclosures. Bottom-up equipment installation tracking and top-down market size triangulation cross-validated segmentation outputs.
Granularity-level modeling deployed wavelength-specific laser system categorization, end-user procurement authority tiers, and scar etiology application complexity across the projection horizon. Product type splits followed NMPA classification pathways distinguishing Class III medical devices from cosmetic or pharmaceutical topical formulations. End-user segmentation captured service intensity variation between dermatology centers, tertiary hospitals, and clinic networks. CAGRs derived from procedure volume elasticity to aesthetic consciousness indicators and equipment replacement cycle compression in tier-one versus tier-two city networks.
Regulatory guideline revisions, feedstock price volatility in medical-grade silicone supply chains, and import component lead time disruptions are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding NMPA technical review pathway stability and provincial green procurement policy implementation velocity. A model refresh is warranted upon material change in dual carbon mandate enforcement intensity across municipal health commission procurement frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Global Radiodermatitis Market
Dermatology
Dermatology Cryosurgery Units Market
Dermatology
Japan Scar Treatment Market
Dermatology
Microneedling Market
Dermatology
Chronic Spontaneous Urticaria Market
Dermatology
Telogen Effluvium Treatment Market
Dermatology
Hyperpigmentation Disorder Treatment Market
Dermatology
Saudi Arabia Hair Transplant Market
Dermatology
Keratoacanthoma Market
Dermatology
UK Scar Treatment Market
Dermatology
Darier Disease Drugs Market
Dermatology
Folliculitis Market
Dermatology
Rosacea Treatment Market
Dermatology
Lichen Sclerosus Treatment Market
Dermatology
Europe Scar Treatment Market
Dermatology
Scar Treatment Oils Market