
 India EMR (Electronic Medical Records) Market | 2026-2036
India EMR (Electronic Medical Records) Market Size, Share, and Industry Trends Forecast 2026-2036
India EMR (Electronic Medical Records) Market Insights
Subscription-based financing and pay-per-use cloud models is tilting competitive dynamics toward asset-light vendors that bypass heavy upfront capital requirements. Practo Technologies Pvt. Ltd. leverages its consumer health platform to channel clinic subscribers into integrated EMR workflows. Cerner Healthcare Solutions Pvt. Ltd. anchors enterprise deployments across multi-specialty hospital chains with on-premise customization capabilities. HealthPlix specializes in physician-centric mobile-first documentation tools that reduce training friction in small practices.
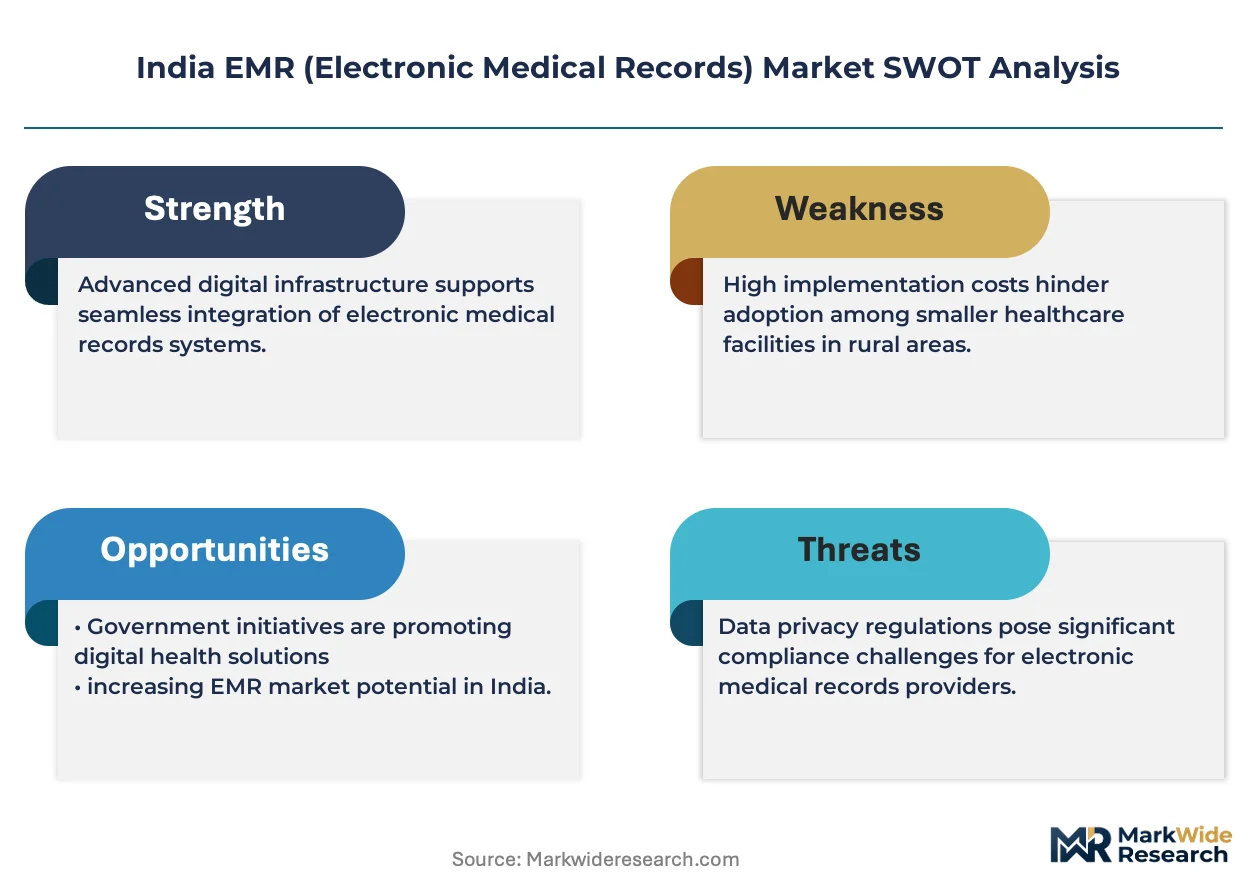
Electronic Medical Records comprise digital repositories of patient health information structured around standardized data fields, clinical vocabularies, and interoperable exchange protocols such as HL7 FHIR, enabling longitudinal care coordination across provider networks. Their primary commercial purpose is to replace paper-based workflows with searchable, shareable clinical data that supports billing accuracy, quality reporting, and population health management. Cloud-based EMR now leads new deployments among mid-size hospital chains seeking scalable infrastructure without dedicated IT staffing, while hybrid EMR captures margin pools from institutions migrating legacy on-premise archives toward phased cloud integration. Patient Management functionality generates recurring revenue through per-bed licensing tied to admission-discharge-transfer modules, whereas Billing Systems integration with India's Goods and Services Tax framework creates stickier vendor relationships.
CDSCO's data localization expectations for clinical software, BIS certification requirements for health IT infrastructure, and the Ministry of Health and Family Welfare's Ayushman Bharat Digital Mission interoperability standards collectively determine product architecture and market access pathways for EMR vendors. The Digital Information Security in Healthcare Act framework shapes how patient consent mechanisms and cross-border data flows must be engineered into platform design. Stakeholders must monitor whether state-level health mission procurement centralization will favor consolidated vendor panels or preserve fragmentation across public and private care tiers.
Market Dynamics
The Ayushman Bharat Digital Mission is compressing procurement cycles for Tier-II and Tier-III hospitals, forcing vendors to reconfigure cloud architectures around BIS certification requirements and state-level interoperability mandates.
Growth Catalysts
- CDSCO data localization mandates:Clinical software vendors must store patient records within Indian jurisdiction, creating captive demand for domestic cloud infrastructure providers.
- Tier-III hospital digitization:State health missions in Maharashtra and Karnataka are channeling central funds toward EMR procurement for district hospitals previously reliant on paper systems.
- HL7 FHIR adoption:Standardized exchange protocols enable longitudinal care coordination across multi-hospital chains, reducing integration friction for new deployments.
Market Restraints
- Legacy system lock-in:Large hospital chains with decade-old on-premise installations face prohibitive migration costs and data migration risks.
- Broadband infrastructure gaps:Rural clinics in Bihar and Uttar Pradesh lack reliable connectivity for real-time cloud synchronization.
- Specialized workforce scarcity:Health informatics professionals with dual clinical-technical training command premium salaries that strain small-practice budgets.
Strategic Opportunities
- North-eastern state expansion:Assam and Manipur health missions remain underpenetrated by major vendors, presenting first-mover advantages for localized deployment models.
- Telemedicine-EMR convergence:Integration of remote consultation workflows with longitudinal patient records creates new revenue streams for platform providers.
- PLI scheme alignment:Domestic hardware manufacturing incentives reduce server and device costs for vendors assembling EMR infrastructure within India.
Industry Challenges
- Ayushman Bharat Digital Mission compliance timelines:Vendors must reengineer consent management modules to meet evolving interoperability standards while maintaining existing customer deployments.
- Interoperability testing bottlenecks:BIS certification queues for health IT infrastructure create six-to-nine month product launch delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India EMR (Electronic Medical Records) Market |
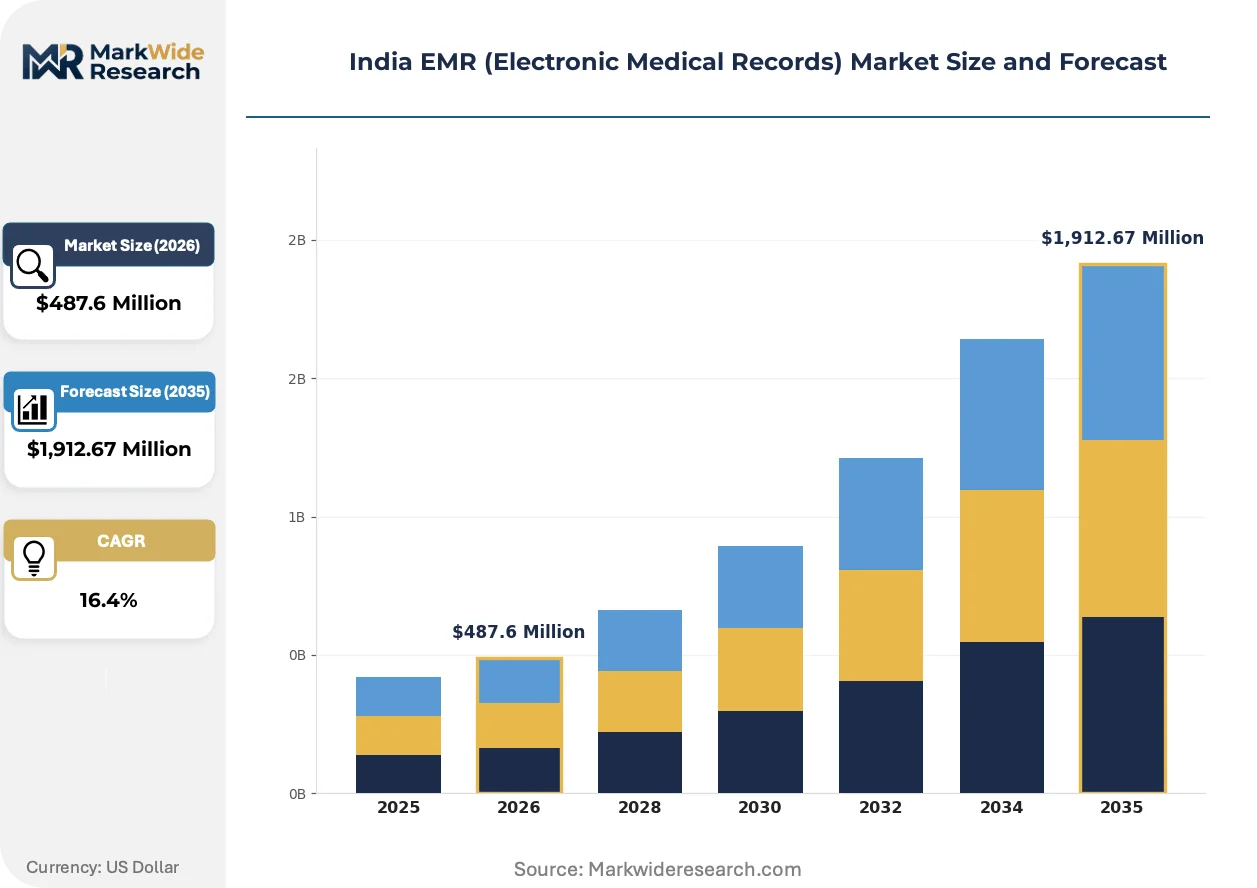
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,912.67 Million |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based EMR, On-premise EMR, Hybrid EMR, Mobile EMR End User: Hospitals, Clinics, Physicians, Nursing Homes Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Local Server Functionality: Clinical Documentation, Patient Management, Billing Systems, Reporting Tools |
| Companies Covered | Practo Technologies Pvt. Ltd., DocEngage Informatics, Athenahealth, Veradigm LLC, Medical Information Technology, Inc., Cerner Healthcare Solutions Pvt. Ltd., HealthPlix, Healthray, KareXpert, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India EMR (Electronic Medical Records) Market Trends and Innovations
Cloud-native architectures are displacing monolithic on-premise systems across mid-size hospital chains, while regulatory pressure on data localization accelerates domestic infrastructure investment.
Hybrid EMR deployments are migrating from pilot testing to standard procurement practice among hospital chains with 200-500 beds. These organizations require phased cloud integration that preserves legacy archive access while enabling real-time clinical workflows. The structural consequence is margin compression for pure on-premise vendors unable to offer subscription-based transition pathways.
Digital Information Security in Healthcare Act provisions are mandating granular patient consent mechanisms and audit trails for all cross-border data flows. CDSCO's parallel data localization expectations require vendors to architect separate domestic cloud instances. Multi-specialty hospital chains in Tamil Nadu and Karnataka are responding by consolidating vendor relationships around platforms with pre-certified compliance modules.
Pay-per-use financing is displacing perpetual licensing in clinic segments with irregular patient volumes. Asset-light vendors offering per-consultation billing capture share from traditional enterprise software providers. This shift concentrates in Maharashtra's urban outpatient networks where physician entrepreneurs prioritize operational flexibility over capital ownership.
India EMR (Electronic Medical Records) Market Segmentation
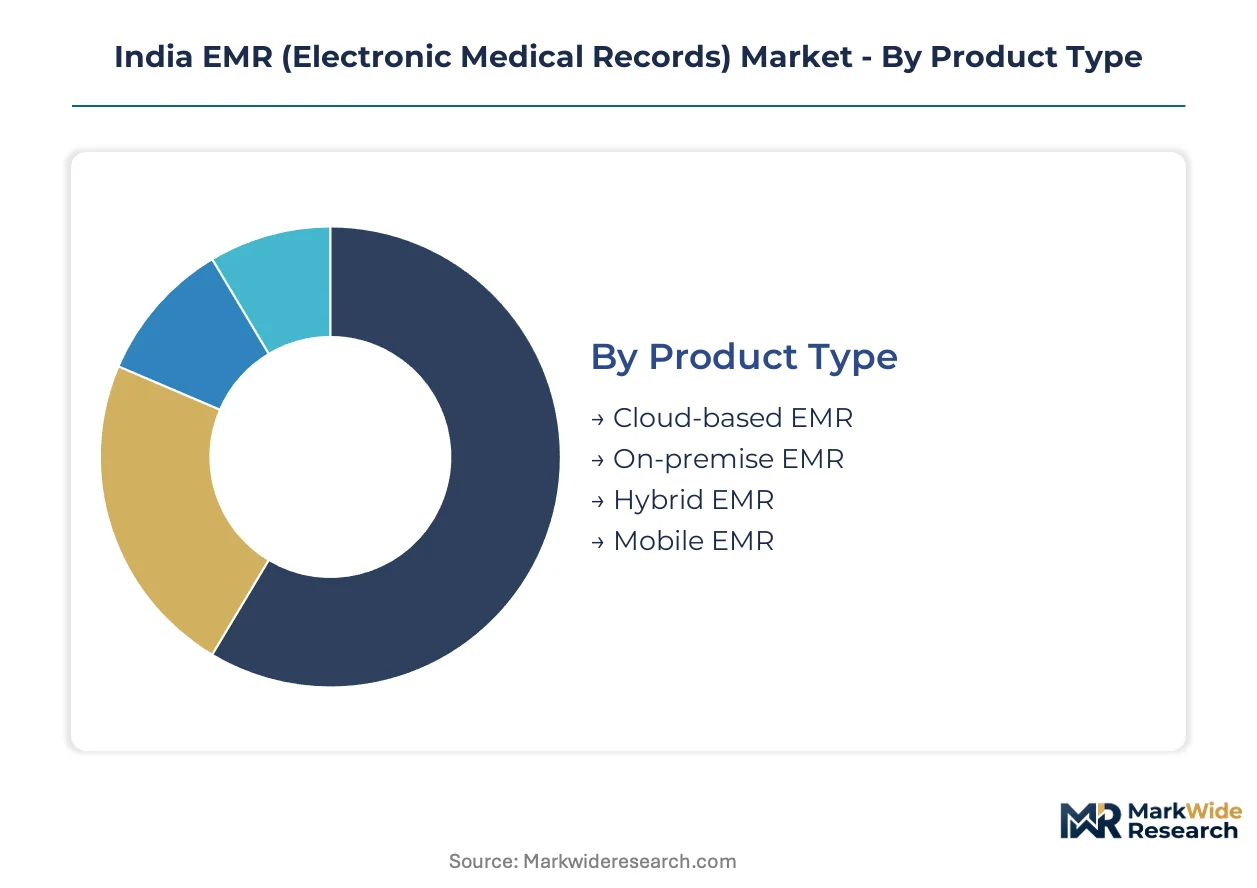
EMR procurement cycles vary dramatically across product architectures and care settings. Cloud deployments close in weeks while on-premise installations stretch across quarters. Understanding these velocity differentials helps vendors align sales resource allocation with revenue recognition timing.
Product Type:
Cloud-based EMR turns over fastest in mid-size hospital chains seeking scalable infrastructure without dedicated IT staffing. On-premise EMR cycles slowest due to capital committee approvals and hardware procurement timelines.
- Cloud-based EMR:Multi-tenant SaaS architectures with automatic updates eliminate server maintenance burdens. Maharashtra's hospital chains and Karnataka's state health missions drive concentrated demand as they bypass heavy upfront capital requirements.
- Hybrid EMR:Phased migration pathways preserve legacy archive access while enabling real-time clinical workflows. Tamil Nadu's multi-specialty hospital chains with 200-500 beds favor this architecture for risk-managed cloud transition.
- On-premise EMR:Single-tenant installations with full data sovereignty control serve institutions with stringent security mandates.
- Mobile EMR:Physician-centric documentation tools reduce training friction in small outpatient practices across urban Maharashtra.
On-premise EMR dominates installed base. Cloud-based EMR is where expansion concentrates.
End User:
Hospital procurement cycles extend 12-18 months with tender processes and committee approvals. Physician practices convert fastest through self-service subscription models with minimal sales touch.
- Hospitals:Enterprise-grade deployments spanning admission-discharge-transfer modules and multi-department integration. Tier-II and Tier-III institutions in Maharashtra, Karnataka, and Tamil Nadu channel central health mission funds into large-scale rollouts.
- Clinics:Outpatient-focused systems with streamlined scheduling and prescription management. Urban physician entrepreneurs in Maharashtra's dense metropolitan networks prioritize per-consultation billing flexibility.
- Physicians:Individual practitioner tools emphasizing rapid documentation and mobile accessibility.
- Nursing Homes:Long-term care documentation with medication administration records and care plan tracking.
Hospitals anchor current revenue. Clinics represent the steepest expansion trajectory.
Deployment Model:
Public cloud deployments accelerate where broadband infrastructure supports real-time synchronization. Local server installations persist in connectivity-constrained geographies.
- Public Cloud:Shared infrastructure with utility pricing and automatic scaling. Karnataka's district hospitals leverage this model under state health mission central procurement.
- Private Cloud:Dedicated single-tenant instances meeting CDSCO data localization mandates. Tamil Nadu hospital chains consolidate vendor relationships around pre-certified compliance modules.
- Hybrid Cloud:Workload-specific routing between on-premise and cloud resources.
- Local Server:Fully captive infrastructure for institutions with intermittent connectivity in Bihar and Uttar Pradesh.
Local server retains legacy dominance. Private cloud is gaining share fastest.
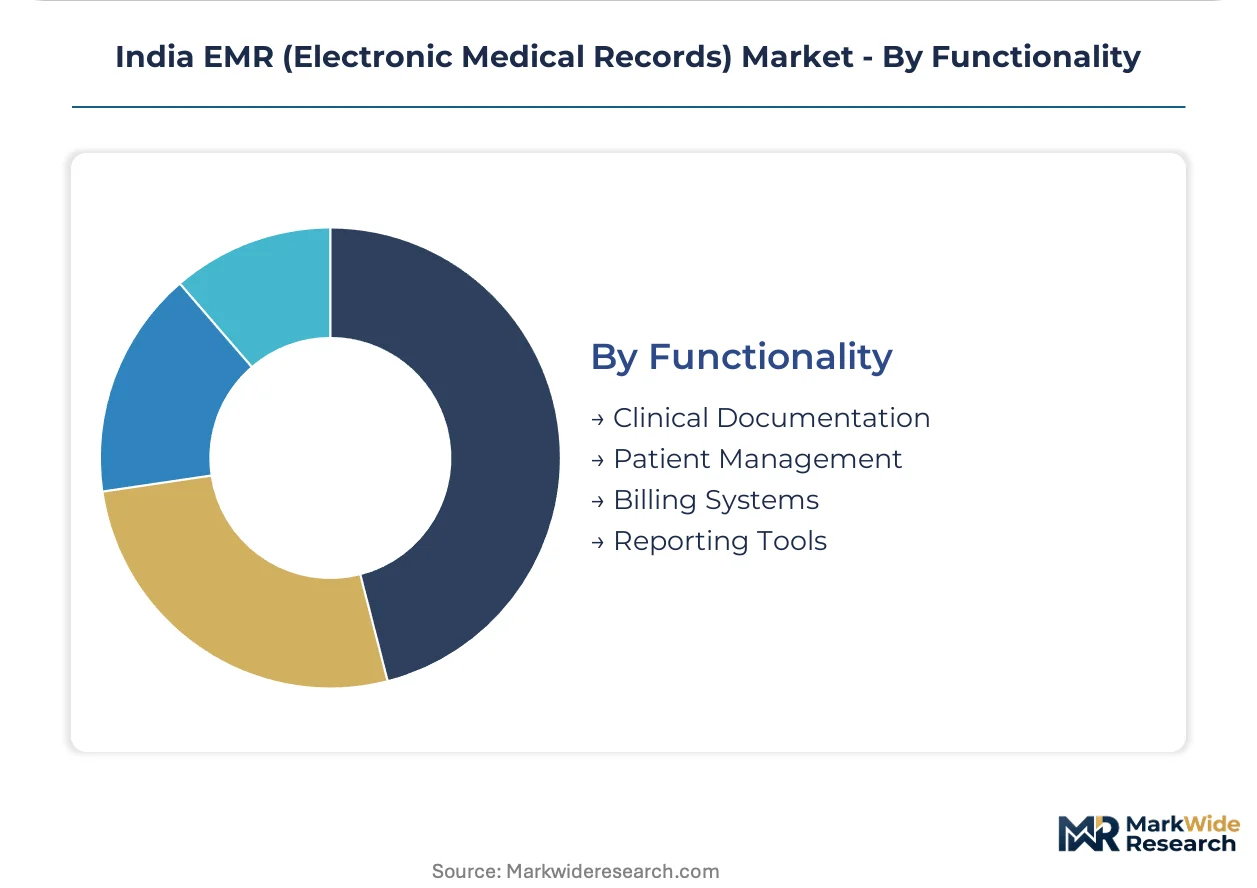
Functionality:
Patient Management modules generate recurring per-bed licensing revenue with predictable renewal cycles. Billing Systems integration creates stickier vendor relationships through GST framework compliance complexity.
- Clinical Documentation:Structured data entry with standardized vocabularies and voice-to-text acceleration. Physician practices in Maharashtra adopt mobile-first tools to minimize training overhead.
- Patient Management:Admission-discharge-transfer tracking with bed occupancy optimization. Hospital chains across Karnataka integrate this core module with state health mission reporting requirements.
- Billing Systems:GST-compliant invoicing with insurance claim integration.
- Reporting Tools:Population health dashboards and quality metrics for accreditation compliance.
Patient Management commands the largest installed base. Clinical Documentation is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's EMR market operates as a net importer of enterprise software components, with domestic vendors assembling localized platforms atop foreign cloud infrastructure. State-level health mission procurement now drives regional divergence in deployment velocity.
Maharashtra
Mumbai and Pune hospital chains anchor western India's EMR adoption, channeling central health mission funds into cloud-native deployments. The state's Directorate of Medical Education and Research mandates interoperability reporting for all public hospitals. Tier-II cities like Nagpur and Nashik are emerging as satellite hubs where physician entrepreneurs adopt pay-per-use billing models.
Karnataka
Bangalore's health-tech ecosystem generates concentrated demand for mobile-first documentation tools among outpatient networks. The state's Arogya Karnataka scheme compresses procurement timelines for district hospitals previously reliant on paper systems. Mysore and Hubli-Dharwad clusters are witnessing phased hybrid EMR rollouts among mid-size hospital chains with 200-500 beds.
Tamil Nadu
Chennai's multi-specialty hospital chains favor private cloud architectures meeting CDSCO data localization mandates. The Tamil Nadu Medical Services Corporation centralizes vendor relationships around pre-certified compliance modules. Coimbatore and Madurai are expanding as secondary markets where nursing homes deploy long-term care documentation systems.
Telangana
Hyderabad's pharmaceutical and hospital corporate headquarters drive enterprise-grade EMR procurement with GST-integrated billing requirements. The state's e-Health initiative channels funds toward digitizing district hospital networks. Warangal and Nizamabad remain underpenetrated, presenting first-mover opportunities for localized deployment models.
Delhi-NCR
The National Capital Region concentrates policy influence and central government hospital procurement, with AIIMS and Safdarjung Hospital setting technical standards. The Ministry of Health and Family Welfare's Digital Health Mission interoperability mandates reshape vendor selection criteria. Gurugram and Noida host vendor development centers engineering consent management modules for national compliance.
India EMR (Electronic Medical Records) Market Competitive Landscape
On the supply side, the industry is bifurcating between asset-light cloud vendors and legacy enterprise providers with customization capabilities. Market structure tilts toward fragmentation in the clinic segment while hospital chains consolidate around fewer vendor relationships. Two archetypes dominate: consumer health platforms channeling users into EMR workflows, and physician-centric mobile-first tools reducing training friction. Competitive moves center on strategic partnerships with state health missions and portfolio diversification into telemedicine-EMR convergence.
Within the enterprise tier, Cerner Healthcare Solutions Pvt. Ltd. and Athenahealth occupy positions emphasizing multi-specialty hospital chain deployments, while Practo Technologies Pvt. Ltd. exemplifies the consumer-platform archetype leveraging its health services user base. HealthPlix represents the physician-centric specialization, anchoring mobile-first adoption among small practices. These three companies illustrate the strategic divergence between enterprise customization, consumer-channel leverage, and workflow friction reduction.
| Leading Market Players |
|---|
| Practo Technologies Pvt. Ltd. |
| DocEngage Informatics |
| Athenahealth |
| Veradigm LLC |
| Medical Information Technology, Inc. |
| Cerner Healthcare Solutions Pvt. Ltd. |
| HealthPlix |
| Healthray |
| KareXpert |
| Others |
Pricing and Supply Chain Analysis
The Mumbai-Delhi freight corridor's escalating logistics costs compress margins for hardware-dependent EMR deployments, concentrating pricing power among domestic cloud infrastructure providers while forcing Tier-III hospitals toward subscription models that externalize server capital expenditure.
Pricing Analysis
Hospital procurement committees anchor pricing structures around three-tier subscription frameworks separating enterprise multi-department bundles from mid-tier departmental licenses and basic outpatient modules. Price differentiation hinges on BIS certification tier and HL7 FHIR integration depth, with pre-certified vendors commanding premiums over uncertified competitors. Pricing pressure stems from state health mission bulk procurement centralization in Maharashtra and Karnataka, which squeezes per-seat margins. Small physician practices exhibit highest price sensitivity, while multi-specialty hospital chains prioritize compliance-grade premiums over cost minimization.
Supply Chain Analysis
Tariff exposure between India and China for server hardware components dominates supply chain risk assessment for on-premise EMR vendors. Domestic assembly draws from Taiwan-manufactured semiconductors, Chinese-produced storage arrays, and Indian-fabricated rack infrastructure. Single-source vulnerability concentrates in specialized clinical data encryption modules sourced from limited certified suppliers. Distribution runs through state health mission procurement portals for public hospital contracts, while private hospital chains negotiate direct enterprise licensing with vendor implementation teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India EMR market constitutes a high-growth disruption as Ayushman Bharat Digital Mission interoperability mandates force wholesale platform rearchitecture across installed vendor bases.
For Market Incumbents: Entrench compliance-grade product lines through accelerated BIS certification investment, converting certification queues into competitive moats against uncertified challengers. Capture margin protection by anchoring hospital chain relationships around private cloud migration pathways that preserve legacy archive access while enabling real-time clinical workflows. Prioritize vertical integration into domestic server assembly to offset hardware import cost volatility. For New Entrants and Emerging Players: Establish a beachhead in Assam and Manipur district hospital networks where major vendor presence remains sparse and state health mission funds channel toward first-time digitization. Target nursing home long-term care documentation segments in Coimbatore and Madurai expansion zones with mobile-first medication administration tools. Pursue telemedicine-EMR convergence as the primary go-to-market angle, bundling remote consultation workflows with longitudinal patient record access. For Investors and Strategic Acquirers: Cloud-native mid-size vendors with pre-certified compliance modules and existing state health mission contracts represent the most defensible acquisition profile across the projection horizon. Monitor BIS certification queue clearance velocity as the critical inflection signal distinguishing scalable platforms from compliance-lagged competitors. Continuous validation against operating reality is the recommended discipline.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | HL7 FHIR connectivity enables longitudinal care coordination across Maharashtra hospital networks. |
| Strategic Partnership | State health mission alliances in Karnataka compress procurement cycles for district hospital rollouts. |
| Acquisition of Specialist Firm | Mobile-first documentation tools reduce training friction in small physician practices. |
| Geographic Expansion | North-eastern state penetration captures first-mover advantages in underpenetrated Assam markets. |
| Product Launch | GST-integrated billing modules create stickier vendor relationships through compliance complexity. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of CDSCO regulatory filings, Ministry of Health and Family Welfare policy circulars, state health mission procurement databases, and hospital GPO contracts. Primary interviews engaged EMR vendor product managers, hospital biomedical engineers, state health mission procurement officers, and clinic physician-owners. Secondary validation drew from BIS certification registries, cloud infrastructure capex disclosures, and trade data on health IT hardware imports. Bottom-up unit deployment estimates triangulate against top-down health mission budget allocation analysis.
Forecast inputs incorporate deployment model adoption curves, organization size segmentation, vertical specialization depth, integration complexity tiers, and regional broadband infrastructure maturity across the projection horizon. CAGR derivation rests on hospital bed expansion trajectories, clinic digitization rates, and cloud migration velocity among mid-size chains. Industry-specific inputs include Ayushman Bharat Digital Mission compliance timeline acceleration and PLI scheme hardware cost reduction impacts.
Stress conditions across BIS certification queue duration, rural broadband deployment delays, and health mission funding continuity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and state procurement centralization pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Global Clinical Information System Market
Medical Information Systems
Ambulatory Software Market
Medical Information Systems
Post-Marketing Pharmacovigilance and Medical Information Market
Medical Information Systems
Global Medical Writing Market
Medical Information Systems
Global Computerized Physician Order Entry Market
Medical Information Systems
Global Clinical EHR Systems Market
Medical Information Systems
Global Laboratory Information Management System for Forensic Science Market
Medical Information Systems
Healthcare ERP Market
Medical Information Systems
Medical Coding Market
Medical Information Systems
US Healthcare ERP Market
Medical Information Systems
AI in Medical Billing Market
Medical Information Systems
Healthcare Information Software Market
Medical Information Systems
ICD-10 Market
Medical Information Systems
Medical Talent Management IT Market
Medical Information Systems
Anesthesia Information Management Systems Market
Medical Information Systems
Global Medical Decision Support Systems for Sepsis Market