
 North America Saliva Test Devices Market | 2026-2036
North America Saliva Test Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Saliva Test Devices Market Analytics
United States diagnostic reagent manufacturers is recalibrating production schedules to meet surging orders from workplace wellness programs and clinical networks. OraSure Technologies, Inc. leverages proprietary collection device patents to dominate infectious disease screening channels. Thermo Fisher Scientific Inc. sustains laboratory-grade assay supply through integrated reagent-instrument bundles. Salimetrics, LLC specializes in cortisol and biomarker research panels, anchoring demand from academic medical centers.
Saliva test devices collect and analyze oral fluid specimens using absorbent pads, buffer solutions, and immunochromatographic or nucleic acid amplification methods to detect analytes without venipuncture. These systems typically process samples within 15 minutes for rapid formats or 2-4 hours for laboratory PCR workflows, serving decentralized diagnostics and patient self-collection needs. Rapid Tests capture the highest volume share in workplace and criminal justice screening programs where turnaround speed determines contract awards. Laboratory Tests retain premium pricing through chain-of-custody protocols and confirmatory accuracy requirements in forensic and clinical settings. Lateral Flow technology dominates manufacturing scale due to minimal equipment requirements, while Microfluidics commands development investment for multiplexed biomarker quantification.
FDA 510(k) premarket notification requirements and Clinical Laboratory Improvement Amendments standards govern analytical validity claims and testing site certification across the United States. Health Canada regulates device licensing through its Medical Devices Bureau, creating parallel compliance obligations for cross-border suppliers. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring and home-based diagnostic services as payers recalibrate coverage policies for saliva-based alternatives to blood draws.
Market Dynamics
Point-of-care decentralization is compressing traditional laboratory workflows as employers and health systems demand same-day infectious disease results without venipuncture infrastructure.
Growth Catalysts
- FDA 510(k) pathway streamlining:Pre-market notification compression is accelerating over-the-counter diagnostic clearances, reducing manufacturer time-to-revenue cycles.
- Workplace wellness mandates:Large employers across California, Texas, and New York are integrating saliva-based screening into occupational health protocols.
- Microfluidics convergence:Multiplexed biomarker quantification on single cartridges is expanding research applications beyond infectious disease into endocrine monitoring.
Market Restraints
- Buffer reagent cost volatility:Supply chain concentration for specialized chemistries in Massachusetts and North Carolina contract manufacturing creates input price instability.
- Confirmatory testing requirements:Chain-of-custody protocols for forensic applications mandate parallel laboratory infrastructure, limiting pure point-of-care penetration.
- Blood draw substitution ceiling:Lipid panels and certain metabolic assays remain inaccessible to oral fluid matrices, capping addressable test volume.
Strategic Opportunities
- Remote patient monitoring reimbursement:CMS coding evolution for home-based diagnostic services is creating coverage parity for saliva alternatives to phlebotomy.
- Canadian market underpenetration:Health Canada device licensing lags US FDA clearances by 18-24 months, presenting first-mover expansion potential for validated assays.
- Criminal justice diversion programs:Drug courts in Florida and Arizona are adopting oral fluid monitoring as alternatives to urine collection, opening institutional procurement channels.
Industry Challenges
- Assay validation timeline compression:Clinical Laboratory Improvement Amendments proficiency testing requirements demand extended analytical performance documentation before commercial launch.
- Cross-platform integration friction:Electronic health record connectivity standards vary across Epic, Cerner, and MEDITECH deployments, complicating result transmission architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Saliva Test Devices Market |
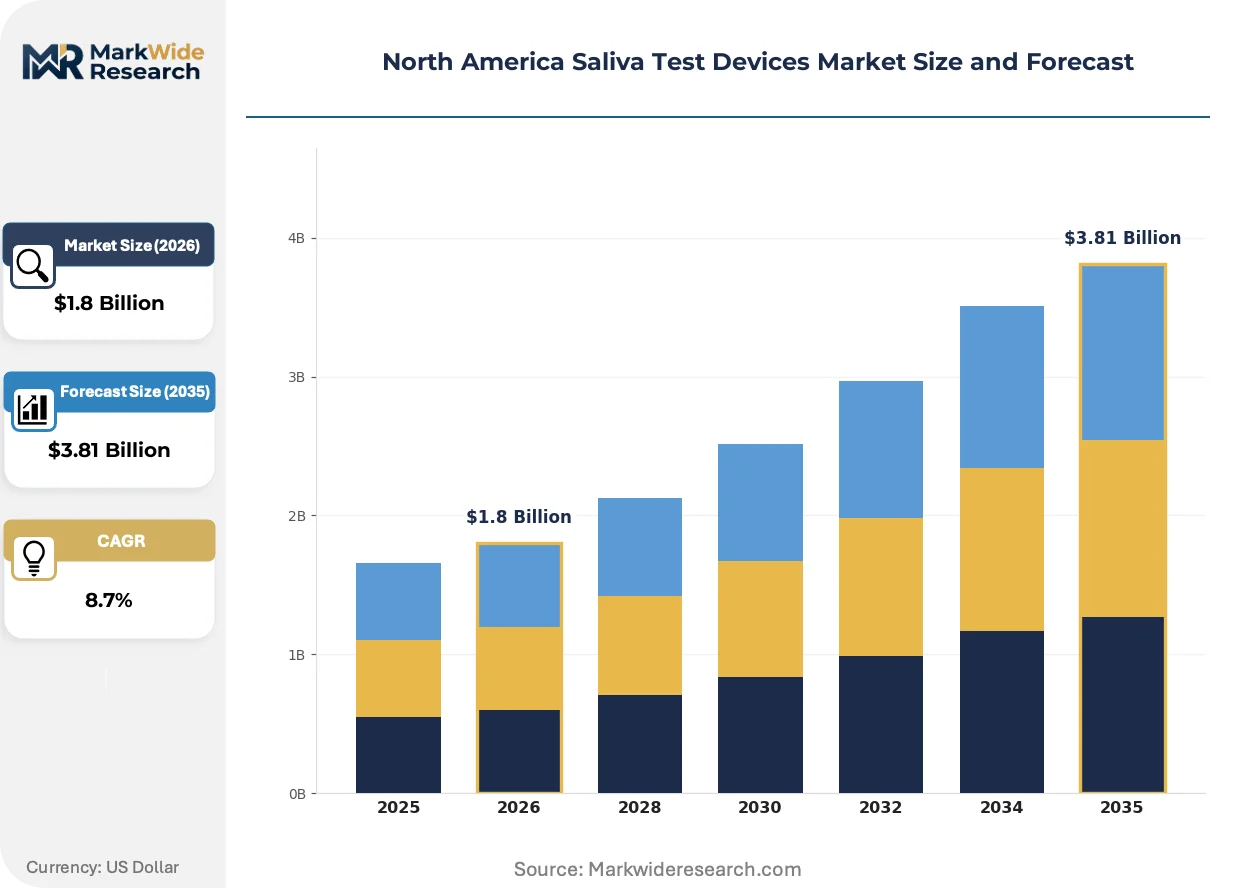
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid Tests, Laboratory Tests, Diagnostic Kits, Microneedle Devices Technology: Immunoassay, PCR, Microfluidics, Lateral Flow End User: Clinics, Diagnostic Laboratories, Home Users, Research Institutions Application: Drug Testing, Disease Diagnosis, Genetic Testing, Health Monitoring |
| Companies Covered | OraSure Technologies, Inc., Thermo Fisher Scientific Inc., Salimetrics, LLC, Abbott, Quest Diagnostics Incorporated, Labcorp, Premier Biotech, Inc., Neogen Corporation, Spectrum Solutions, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Saliva Test Devices Market Evolving Landscape
Device architecture is pivoting from single-analyte lateral flow strips toward integrated sample-to-answer systems that eliminate laboratory handling steps entirely.
Integrated nucleic acid amplification cartridges are rewriting infectious disease detection economics by collapsing extraction, amplification, and readout into disposable cassettes. Urgent care networks across the Midwest are adopting these platforms for respiratory panel screening. The technology is rewriting contract award criteria for occupational health programs where 15-minute turnaround determines vendor selection.
Health Canada's Medical Devices Bureau is tightening clinical evidence requirements for Class III diagnostic licenses, forcing manufacturers to generate Canadian-specific performance data. This regulatory friction is delaying cross-border product launches by 12-18 months. US manufacturers with existing FDA clearances are responding by establishing dedicated Canadian validation cohorts.
Hospital procurement committees are consolidating vendor relationships around integrated reagent-instrument bundles rather than standalone consumable contracts. This concentration is squeezing smaller assay developers dependent on open-platform distribution. The shift is most visible in integrated delivery networks across Pennsylvania and Ohio where standardization mandates override point solution preferences.
North America Saliva Test Devices Market Segmentation
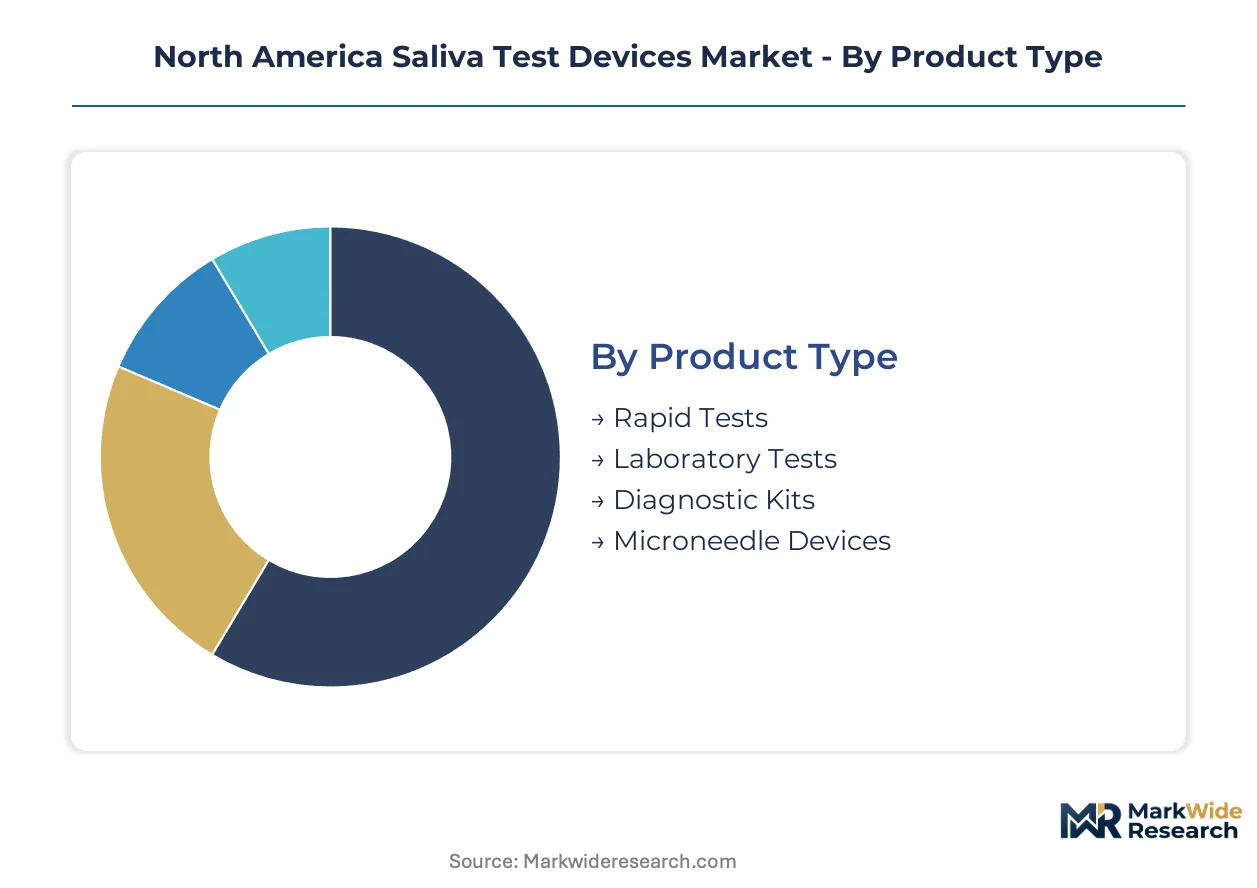
Saliva test device manufacturers configure product portfolios around distinct regulatory pathways, with FDA 510(k) clearance requirements varying sharply by intended use setting. Each segment carries unique reimbursement codes, analytical performance thresholds, and distribution channel constraints that reshape go-to-market economics.
Product Type:
FDA 510(k) premarket notification burdens diverge substantially across this category, with over-the-counter rapid formats facing abbreviated review timelines compared to laboratory-designated systems requiring CLIA complexity certification.
- Rapid Tests:Single-use cassettes integrating absorbent collection pads with pre-loaded reagent buffers deliver qualitative results within 15 minutes. Workplace wellness programs across California and Texas concentrate procurement volume here, driven by same-day turnaround mandates in occupational health contracts.
- Laboratory Tests:Chain-of-custody collection devices paired with high-complexity PCR or immunoassay workflows demand CLIA-certified processing sites. Forensic applications in Arizona and Florida sustain premium positioning through confirmatory accuracy requirements that exclude point-of-care alternatives.
- Diagnostic Kits:Modular reagent sets for open-platform analyzers serve hospital networks standardizing across integrated delivery systems.
- Microneedle Devices:Emerging transdermal-saliva hybrid formats target research applications requiring minimally invasive biomarker access.
Rapid Tests sit at the top of the volume ranking, with Microneedle Devices climbing the fastest.
Technology:
Capital intensity and technical service requirements stratify manufacturing scale, with lateral flow commanding the broadest installed base and microfluidics capturing the steepest R&D allocation.
- Immunoassay:Antibody-antigen binding reactions on porous membranes detect proteins, hormones, and drug metabolites with visual or reader-based quantification. Cortisol panels for academic medical centers anchor demand concentration, fueled by stress research funding from the National Institutes of Health.
- PCR:Nucleic acid amplification enables pathogen detection at trace concentrations, requiring thermal cycling infrastructure. Urgent care networks in the Midwest are adopting integrated cartridge formats that collapse extraction and amplification into single-use disposables.
- Microfluidics:Sub-milliliter channel architectures enable multiplexed biomarker quantification on credit-card-sized cartridges.
- Lateral Flow:Capillary-driven wicking through nitrocellulose strips dominates infectious disease screening volumes with minimal equipment requirements.
Lateral Flow dominates manufacturing output, while Microfluidics is gaining share fastest through research panel expansion.
End User:
Procurement authority and reimbursement access separate institutional buyers from direct-to-consumer channels, with health system consolidation reshaping vendor consolidation patterns.
- Clinics:Federally qualified health centers and urgent care chains deploy CLIA-waived rapid formats for infectious disease screening. Point-of-care decentralization across Pennsylvania and Ohio drives volume as integrated delivery networks standardize on single-vendor reagent-instrument bundles.
- Diagnostic Laboratories:Reference labs and hospital core laboratories process high-complexity assays with chain-of-custody documentation. Workplace wellness mandates from large self-insured employers concentrate specimen flow through national laboratory networks.
- Home Users:Direct-to-consumer collection kits bypass clinical infrastructure for genetic and hormone monitoring applications.
- Research Institutions:Academic medical centers validate novel assay formats under investigational protocols preceding commercial launch.
Diagnostic Laboratories command the highest revenue per test, with Home Users expanding most quickly through remote patient monitoring reimbursement evolution.
Application:
Regulatory scrutiny and evidentiary standards vary by analyte class, with forensic applications demanding the most stringent chain-of-custody protocols.
- Drug Testing:Oral fluid matrices detect recent substance use with shorter detection windows than urine or hair. Criminal justice diversion programs in Florida and Arizona are adopting these formats as alternatives to observed urine collection, opening institutional procurement channels.
- Disease Diagnosis:Respiratory and sexually transmitted infection panels leverage saliva specimen stability for decentralized screening. FDA 510(k) pathway streamlining for over-the-counter infectious disease clearances is accelerating manufacturer time-to-revenue cycles.
- Genetic Testing:DNA extraction from buccal cells enables pharmacogenomic and ancestry applications without phlebotomy.
- Health Monitoring:Cortisol, testosterone, and inflammatory marker tracking serves wellness and chronic disease management use cases.
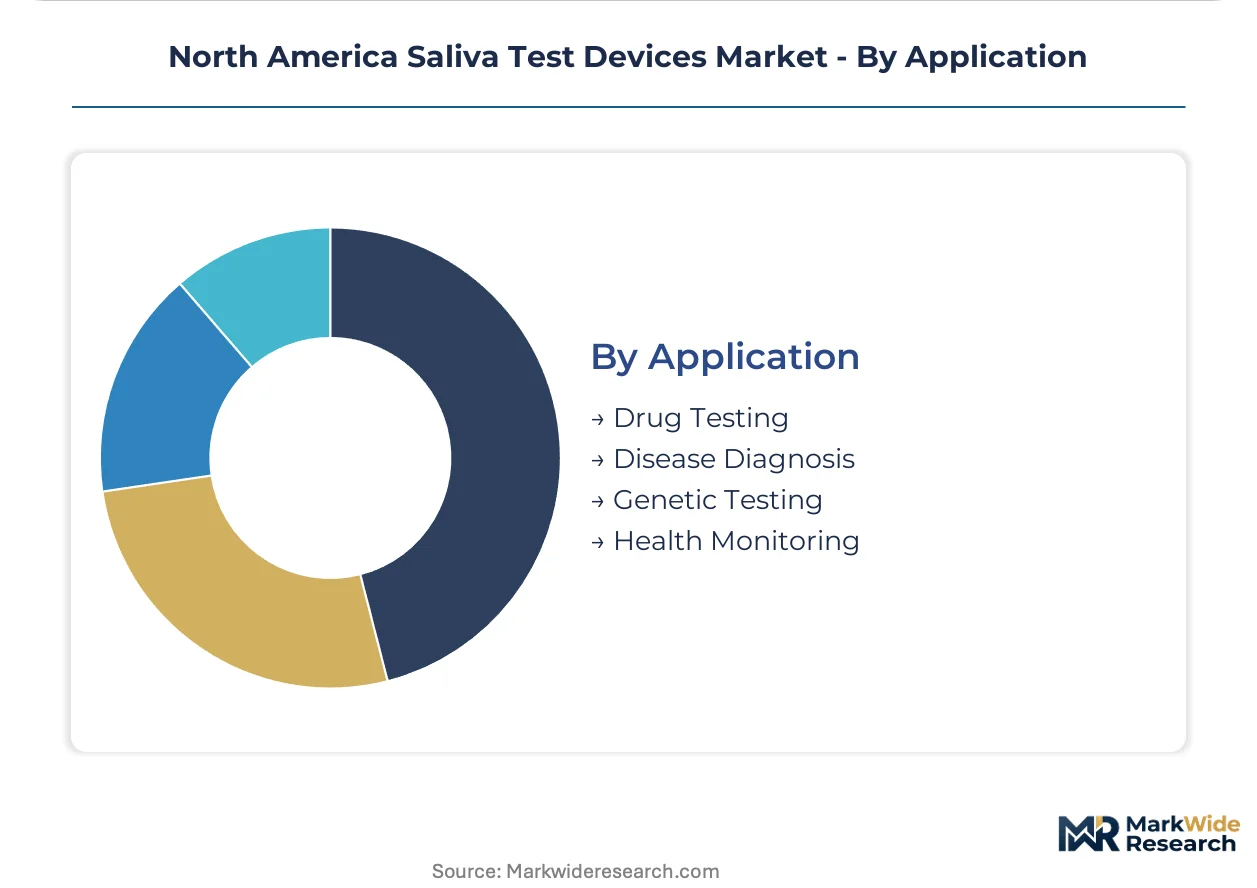
Disease Diagnosis leads by test volume, with Health Monitoring following the steepest expansion trajectory through employer wellness program integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling manufacturing investment toward jurisdictions with compressed FDA clearance timelines, while Health Canada's extended review cycles create 18-24 month launch delays that advantage first-movers with dedicated Canadian validation infrastructure.
United States
California's biotech corridor concentrates contract research organization activity for novel assay validation, while Texas and New York employers drive workplace wellness procurement volume. FDA 510(k) premarket notification streamlining accelerates over-the-counter diagnostic clearances, compressing manufacturer time-to-revenue cycles. Integrated delivery networks across Pennsylvania and Ohio standardize procurement around single-vendor reagent-instrument bundles.
Canada
Health Canada's Medical Devices Bureau imposes tightening clinical evidence requirements for Class III diagnostic licenses, forcing manufacturers to generate Canadian-specific performance data. Ontario and Quebec host reference laboratories processing chain-of-custody specimens for forensic applications. The 12-18 month regulatory friction delay creates first-mover expansion potential for validated US assays.
Mexico
Contract manufacturing for specialized chemistries concentrates in Baja California and Chihuahua, serving US reagent demand amid buffer cost volatility. Mexico's national pharmaceutical regulator maintains parallel compliance obligations for cross-border suppliers. Mexico City clinical networks are adopting point-of-care decentralization for infectious disease screening.
North America Saliva Test Devices Market Competitive Landscape
US producers anchor the premium tier through FDA-cleared integrated systems; Canadian specialists hold forensic and research-panel positions through Health Canada licensing advantages. The vendor base stratifies around three strategic archetypes: diversified life science conglomerates with reagent-instrument bundles, pure-play saliva collection device patent holders, and reference laboratory networks with captive assay development. Competitive moves concentrate on M&A for assay portfolios and strategic partnerships for microfluidics R&D.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and Abbott exemplify integrated reagent-instrument bundling strategies that hospital procurement committees favor. OraSure Technologies, Inc. occupies the specialized collection device archetype, leveraging proprietary IP positions in infectious disease screening channels. These three anchors demonstrate how regulatory clearance depth and manufacturing scale separate premium positioning from commodity competition.
| Leading Market Players |
|---|
| OraSure Technologies, Inc. |
| Thermo Fisher Scientific Inc. |
| Salimetrics, LLC |
| Abbott |
| Quest Diagnostics Incorporated |
| Labcorp |
| Premier Biotech, Inc. |
| Neogen Corporation |
| Spectrum Solutions, LLC |
| Others |
Value Network & Pricing Analysis
Buffer reagent cost volatility originating in Massachusetts and North Carolina contract manufacturing cascades through three pricing tiers downstream, with specialized chemistries commanding premium positioning against commodity absorbent pad formats.
Pricing Analysis
Distributor margins on rapid test cassettes absorb the steepest compression as hospital procurement committees consolidate around integrated reagent-instrument bundles. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared laboratory formats from CLIA-waived point-of-care alternatives and unregulated research-use-only devices. Price differentiation hinges on certification grade and volume scale, with chain-of-custody protocols sustaining premium positioning in forensic applications. Cost compression in economy-tier rapid formats is intensifying because workplace wellness programs are consolidating vendor relationships.
Supply Chain Analysis
Health Canada and FDA dual-qualification requirements gate cross-border supply eligibility, forcing manufacturers to maintain parallel validation cohorts. Geographic supply concentrates in the United States, Mexico, and Canada, with Baja California and Chihuahua hosting contract manufacturing for specialized chemistries. Raw material dependencies center on nitrocellulose membranes, monoclonal antibodies, and thermal-stable polymerases. Single-source vulnerability in Massachusetts-based buffer formulation creates concentration risk. Distribution runs through integrated delivery networks and national laboratory networks rather than open-platform consumable channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 510(k) pathway streamlining functions as a regulatory compounder, compressing time-to-revenue cycles and accelerating manufacturer consolidation around cleared device portfolios.
For Market Incumbents: Lock in procurement relationships with integrated delivery networks across Pennsylvania and Ohio through exclusive reagent-instrument bundling. Deepen backward integration into proprietary collection device manufacturing to defend against patent-expiration pressure from emerging assay developers. Certification investment in Health Canada Class III licenses creates first-mover protection against cross-border entrants. For New Entrants and Emerging Players: FDA 510(k) in the United States opens a window for rapid test formats targeting workplace wellness programs in California and Texas. Remote patient monitoring reimbursement evolution presents the most penetrable white-space, with home-based cortisol and hormone monitoring underserved by incumbent laboratory-centric positioning. Go-to-market through direct-to-consumer channels bypasses hospital procurement committee consolidation. For Investors and Strategic Acquirers: Consolidation pressure builds where Health Canada licensing lags create 18-24 month validation delays that strand smaller developers. Target acquisition archetype: pure-play saliva collection device patent holders with infectious disease screening channel presence. Watch CMS coding evolution for home-based diagnostic services as the inflection signal triggering valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Class III License Pursuit | Canadian-specific validation cohorts unlock 18-24 month first-mover advantage over FDA-cleared competitors awaiting cross-border approval. |
| Integrated Reagent-Instrument Bundle Development | Hospital procurement committees in Pennsylvania and Ohio favor single-vendor standardization over standalone consumable contracts. |
| Microfluidics Multiplexing R&D Partnership | Academic medical center demand for cortisol and biomarker research panels anchors premium positioning beyond infectious disease screening. |
| Remote Patient Monitoring Reimbursement Strategy | CMS coding evolution creates coverage parity for saliva alternatives to phlebotomy in employer wellness program channels. |
| Criminal Justice Diversion Program Channel Expansion | Drug courts in Florida and Arizona are adopting oral fluid monitoring as alternatives to observed urine collection. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each jurisdiction combined with secondary validation. Interviews with FDA regulatory affairs consultants, hospital GPO contracts managers, biomedical engineers at integrated delivery networks, and point-of-care testing coordinators informed demand-side dynamics. Secondary sources include FDA 510(k) premarket notification databases, Health Canada Medical Devices Bureau licensing records, CMS Medicare reimbursement code filings, and hospital procurement databases. Bottom-up device shipment modeling and top-down diagnostic testing volume estimates were triangulated against manufacturer production disclosures.
Granularity-level modeling proceeded at the product type, technology, end user, and application dimensions, with additional cross-section by state-level regulatory cluster and workplace wellness program penetration. CAGRs were derived from logistic diffusion curves fitted to historical clearance timelines and procurement contract award patterns. Forecast inputs incorporated CLIA complexity certification expansion rates and employer occupational health mandate adoption curves across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Health Canada evidence requirement tightening or CMS reimbursement code exclusion scenarios. Model assumptions reflect FDA 510(k) review timeline compression and buffer reagent supply stabilization. A model refresh is warranted upon material change in remote patient monitoring reimbursement policy or CLIA-waived test category expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
MRI Compatible Biopsy Devices Market
Diagnostic Devices
Skin Moisture Detectors Market
Diagnostic Devices
Urine Analyzers Market
Diagnostic Devices
Digital Diagnostic Audiometer Market
Diagnostic Devices
Diagnostic Stopper Market
Diagnostic Devices
Point of Care Diagnostics Market
Diagnostic Devices
Point of Care Blood Testing Devices Market
Diagnostic Devices
Bronchial Biopsy Devices Market
Diagnostic Devices
Breast Biopsy Market
Diagnostic Devices
Portable Diagnostic Devices Market
Diagnostic Devices
Biopsy Guidance System Market
Diagnostic Devices
United States Biopsy Devices Market
Diagnostic Devices
Pelvic Floor Diagnostics Market
Diagnostic Devices
Hearing Screening Diagnostic Devices Market
Diagnostic Devices
Sleep Apnea Diagnostic Systems Market
Diagnostic Devices
Lung Biopsy Systems Market