
 Global Microsurgery Market | 2026-2036
Global Microsurgery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microsurgery Market Foresight
Multi-source procurement of optical subassemblies is consolidating as tier-one manufacturers reduce vendor counts to secure supply continuity. Carl Zeiss Meditec AG leverages captive lens grinding capacity to sustain margin control across microscope platforms. Leica Microsystems anchors its position through premium stereoscopic visualization systems for neurosurgical suites. Olympus Corporation competes by extending video-assisted technology from endoscopy into microsurgical workflows.
Microsurgery encompasses operative techniques performed under high-magnification visualization, typically employing surgical microscopes with resolution thresholds below 10 micrometers and specialized instruments measuring 0.3–0.5 millimeters in shaft diameter. These procedures enable precise tissue manipulation in confined anatomical spaces, serving critical functions in nerve repair, vascular anastomosis, and ocular intervention. Microscope systems command the dominant share of product value due to capital intensity and replacement cycles, while robotics systems represent the fastest-expanding category as hospitals seek tremor filtration and motion scaling. Fluorescence imaging technology is displacing conventional white-light visualization in reconstructive applications where perfusion assessment determines tissue viability.
FDA 510(k) pathways govern device clearance in the United States, while EU MDR and CE marking requirements impose clinical evidence burdens that reshape competitive access across European markets. Japan's PMDA and METI coordinate standards for robotic surgical platforms, creating layered compliance obligations for manufacturers seeking multi-regional distribution. Stakeholders must weigh regulatory capital requirements against the premium pricing enabled by fluorescence and robotic certifications in high-throughput surgical centers.
Market Dynamics
Robotic-assisted microsurgical platforms are compressing the skill gap between specialist surgeons and generalists, forcing capital equipment vendors to bundle training ecosystems with hardware sales. This structural shift concentrates procurement power in high-volume academic medical centers capable of amortizing platform costs across multiple surgical service lines.
Growth Catalysts
- EU MDR conformity pathways:Accelerated validation timelines for fluorescence-guided systems in Germany and France are compressing competitive entry barriers for imaging-integrated microscopes.
- Reconstructive plastic surgery:Rising free flap procedures in South Korea and Brazil are anchoring demand for high-magnification vascular anastomosis visualization.
- Motion-scaling robotics:Tremor filtration capabilities are expanding the addressable surgeon population beyond fellowship-trained microsurgical specialists.
Market Restraints
- Optical-grade fused silica:Concentrated supply from Japanese and German specialty glass manufacturers creates input cost volatility for objective lens assemblies.
- FDA 510(k) clinical evidence burdens:Predicate device requirements for novel fluorescence wavelengths extend clearance timelines and burn development capital.
- Manual microsurgical techniques:Established training pathways in ophthalmology and neurosurgery slow substitution by robotic platforms despite superior precision metrics.
Strategic Opportunities
- India's tier-2 cities:Underpenetrated cataract surgery infrastructure creates white space for portable microscope systems with simplified maintenance protocols.
- Near-infrared fluorescence + indocyanine green:Converging perfusion assessment technologies are opening reconstructive applications beyond traditional oncologic reconstruction.
- Japan's METI innovation subsidies:Domestic production incentives for surgical robotics are lowering effective platform costs for regional hospital networks.
Industry Challenges
- Fellowship-trained microsurgeon scarcity:Extended training pipelines in peripheral nerve repair limit procedure volume expansion regardless of equipment availability.
- Legacy microscope integration:Retrofitting fluorescence modules onto installed base Zeiss and Leica systems requires proprietary adapter engineering that fragments aftermarket service.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microsurgery Market |
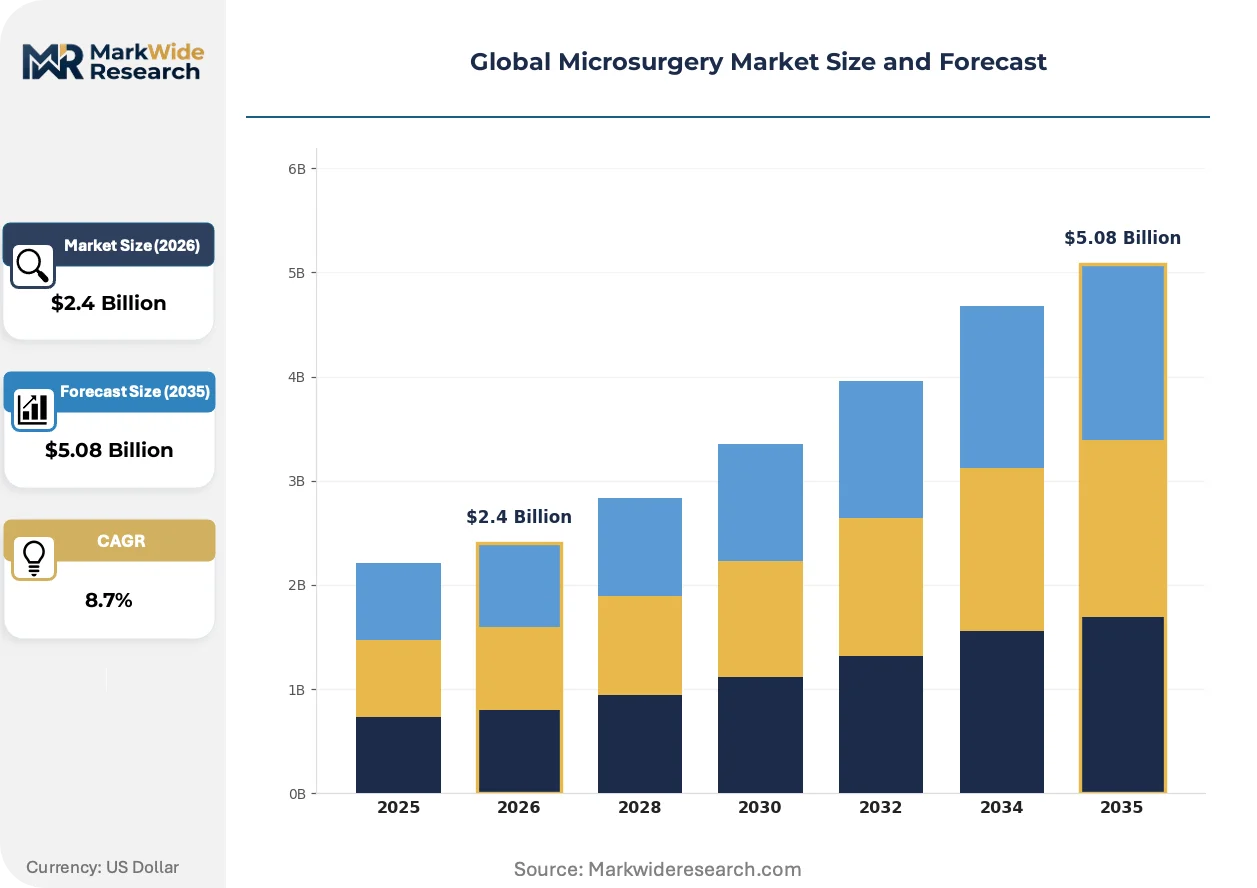
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microscope, Microinstruments, Suture Materials, Robotics Systems Technology: Optical Coherence Tomography, Fluorescence Imaging, 3D Visualization, Video Assistance Application: Neurosurgery, Reconstructive Surgery, Otolaryngology, Ophthalmic Surgery End User: Specialty Clinics, University Hospitals, Ambulatory Surgical Centers, Research Institutes |
| Companies Covered | Carl Zeiss Meditec AG, Leica Microsystems, Olympus Corporation, Haag-Streit Group, B. Braun Melsungen, Alcon Inc., Aesculap, Hu-Friedy Mfg. Co., LLC, Scanlan International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microsurgery Market Shifts & Advancements
Fluorescence imaging is migrating from experimental adjunct to standard-of-care in tissue viability assessment, rewiring procurement criteria around integrated visualization rather than standalone magnification. This shift compresses replacement cycles and elevates software update revenue streams alongside hardware sales.
Indocyanine green angiography is absorbing the perfusion verification function previously performed by clinical judgment alone in free flap reconstruction. University hospitals in the United States and South Korea are standardizing intraoperative fluorescence protocols, and this capability is absorbing capital budget priority from conventional white-light microscope upgrades.
Japan's PMDA and METI coordination on robotic surgical platform standards is tightening software validation requirements for motion-scaling algorithms. Manufacturers targeting multi-regional distribution must now maintain parallel quality management systems, and this regulatory layering is absorbing additional compliance headcount in product development organizations.
Hospital procurement committees are consolidating vendor relationships to secure bundled service agreements covering microscopy, robotics, and imaging modalities. Academic medical centers in Germany and China are negotiating enterprise-wide contracts that displace single-device purchasing, and this concentration is absorbing smaller regional distributors from the channel structure.
Global Microsurgery Market Segmentation
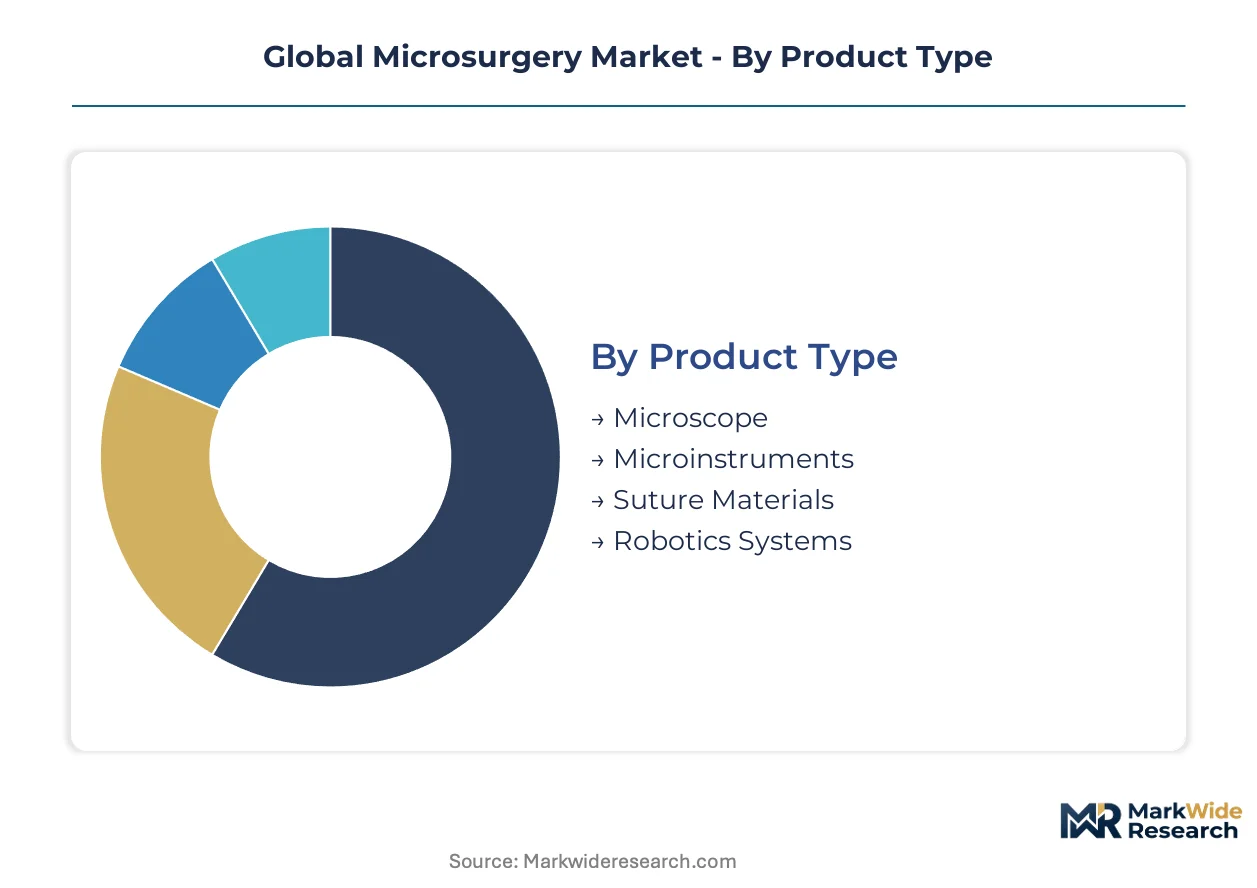
Microsurgery market segmentation reveals divergent capital deployment patterns across visualization hardware, consumable supplies, and emerging robotic platforms. Procurement committees weight replacement cycles against training infrastructure when allocating budgets across these categories.
Product Type:
Capital intensity separates high-value durable equipment from recurring consumable purchases, with robotics commanding premium positioning against established optical systems.
- Microscope:Surgical microscopes with resolution thresholds below 10 micrometers dominate capital expenditure in university hospitals across Germany and Japan. Carl Zeiss Meditec and Leica Microsystems anchor installed base positions through captive lens grinding and stereoscopic visualization capabilities.
- Robotics Systems:Motion-scaling platforms with tremor filtration represent the steepest expansion trajectory as hospitals seek to compress the skill gap between fellowship-trained specialists and general surgeons. FDA clearance pathways and PMDA standards in Japan create layered compliance obligations for manufacturers.
- Microinstruments:Shaft diameters measuring 0.3–0.5 millimeters enable precise tissue manipulation in confined anatomical spaces.
- Suture Materials:Specialized threads for vascular anastomosis and nerve repair procedures.
Mature deployment sits with Microscope systems. Newer deployment is concentrated in Robotics Systems.
Technology:
Visualization modalities are shifting from passive magnification toward active tissue characterization, rewiring procurement criteria around integrated software capabilities.
- Fluorescence Imaging:Near-infrared systems with indocyanine green perfusion assessment are displacing conventional white-light visualization in reconstructive applications. University hospitals in the United States and South Korea standardize intraoperative fluorescence protocols for free flap viability verification.
- 3D Visualization:Stereoscopic depth perception systems reduce operator fatigue during prolonged microsurgical procedures in neurosurgical suites.
- Optical Coherence Tomography:Cross-sectional tissue imaging technology extends from ophthalmology into microsurgical planning workflows.
- Video Assistance:Olympus Corporation extends endoscopic video technology into microsurgical environments for documentation and training.
Established workflows favor Video Assistance. Capability expansion is fastest in Fluorescence Imaging.
Application:
Procedure complexity and reimbursement levels determine equipment specification requirements across surgical specialties.
- Neurosurgery:High-magnification requirements for cranial nerve and vascular procedures sustain demand for premium stereoscopic systems. Leica Microsystems anchors market position through specialized visualization platforms for neurosurgical suites in academic medical centers.
- Reconstructive Surgery:Free flap procedures in South Korea and Brazil drive demand for vascular anastomosis visualization with perfusion assessment capabilities.
- Ophthalmic Surgery:Cataract and retinal procedures represent high-volume applications with established manual technique training pathways.
- Otolaryngology:Microsurgical ear and laryngeal procedures require specialized instrument access angles.
Volume concentration rests with Ophthalmic Surgery. Technology upgrading is most pronounced in Reconstructive Surgery.
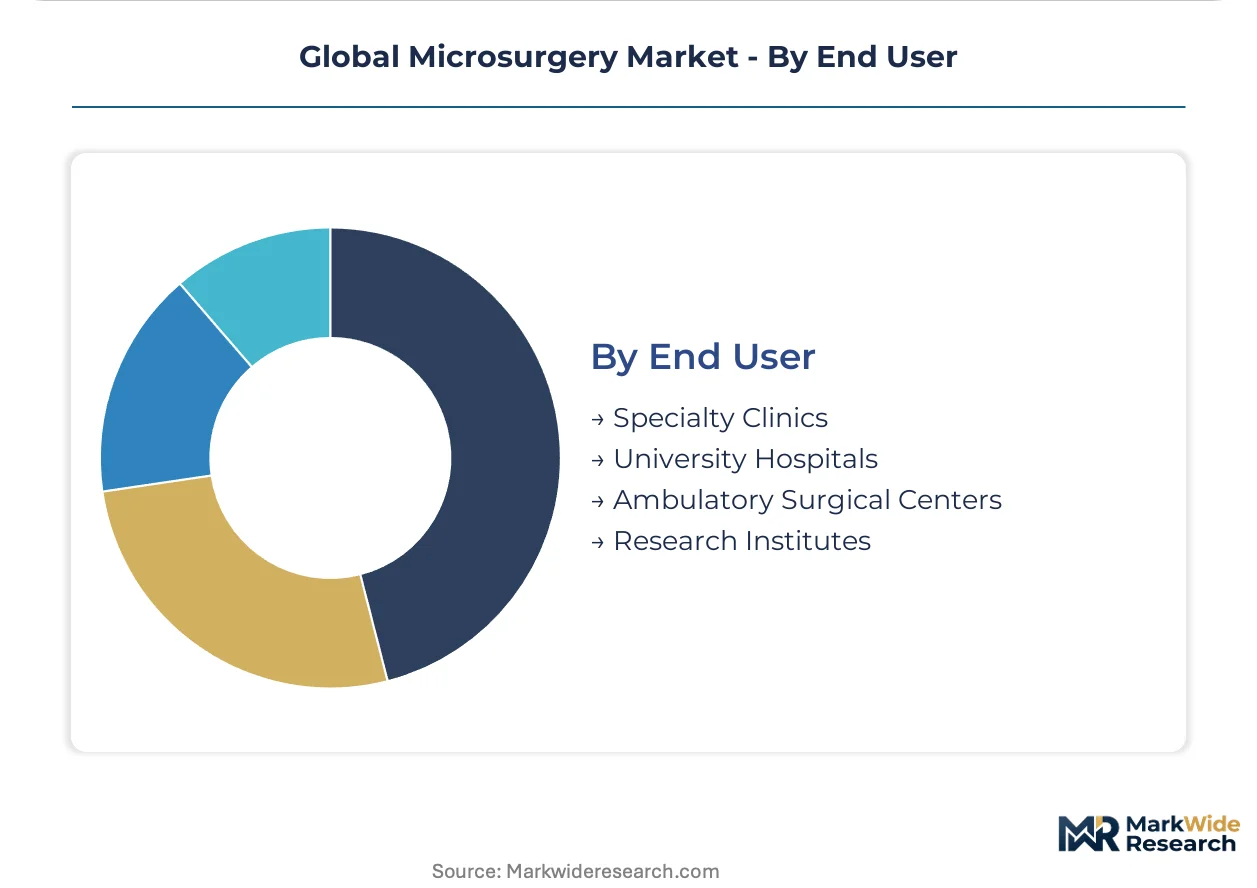
End User:
Procurement authority and capital availability segment the customer base between high-volume institutional purchasers and specialized outpatient facilities.
- University Hospitals:Academic medical centers in the United States, China, and South Korea anchor procurement volumes through multi-service-line platform amortization. Bundled service agreements covering microscopy, robotics, and imaging modalities consolidate vendor relationships.
- Specialty Clinics:Concentrated procedure volumes in Germany and Japan support adoption of robotic-assisted microsurgical platforms with dedicated training ecosystems.
- Ambulatory Surgical Centers:Cost-sensitive settings favor portable microscope systems with simplified maintenance protocols.
- Research Institutes:Experimental fluorescence and robotics applications drive early-stage technology validation.
Platform investment leadership sits with University Hospitals. Accessibility expansion is targeting Ambulatory Surgical Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
University hospitals in the United States, China, and South Korea concentrate procurement volumes for high-magnification surgical microscopes and robotic platforms. Specialty clinics in Germany and Japan are expanding adoption of fluorescence-guided systems. Regulatory validation timelines vary sharply across jurisdictions, reshaping competitive entry patterns.
United States
Academic medical centers in Boston and Houston anchor demand for motion-scaling robotic platforms with bundled training ecosystems. FDA 510(k) clearance pathways govern device validation, with predicate requirements extending timelines for novel fluorescence wavelengths. The Cleveland Clinic and Mayo Clinic networks standardize intraoperative perfusion assessment protocols.
Germany
Specialty reconstructive clinics in Munich and Hamburg drive procurement of integrated fluorescence microscopy systems. EU MDR conformity requirements impose clinical evidence burdens that compress competitive access for non-integrated vendors. The Baden-Württemberg surgical cluster concentrates high-volume free flap procedure volumes.
Japan
Metropolitan hospital networks in Tokyo and Osaka prioritize robotic-assisted platforms with tremor filtration capabilities. PMDA and METI coordinate standards for surgical robotics, creating layered software validation obligations. The Nagoya medical device manufacturing corridor supplies optical subassemblies to tier-one microscope producers.
South Korea
Seoul-based university hospitals standardize near-infrared fluorescence protocols for reconstructive microsurgery. MFDS regulates medical device clearance with accelerated pathways for domestically manufactured components. The Songdo medical cluster hosts training centers for robotic platform adoption.
China
Tier-1 city hospital systems in Shanghai and Beijing deploy capital budgets toward 3D visualization microscopes. NMPA governs device registration with province-level pilot programs for robotic surgery subsidies. The Suzhou industrial park concentrates domestic microscope assembly operations.
Global Microsurgery Market Competitive Landscape
Strategic partnerships dominate the current landscape as capital equipment vendors bundle training ecosystems with hardware sales. The vendor base concentrates around three tiers: integrated optical-robotics platforms, standalone microscope specialists, and consumable instrument suppliers. Archetypes include captive lens manufacturers, video-assisted technology extenders, and motion-scaling robotics developers. M&A activity and geographic licensing agreements represent the primary competitive vectors reshaping market access.
Among German-headquartered diversified medtech groups, Carl Zeiss Meditec AG exemplifies the captive manufacturing archetype through in-house optical component production. Leica Microsystems occupies a position within the premium visualization tier, while Olympus Corporation represents the video technology extension archetype. These three anchors collectively illustrate the strategic segmentation between optical heritage, stereoscopic specialization, and endoscopic platform migration.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| Leica Microsystems |
| Olympus Corporation |
| Haag-Streit Group |
| B. Braun Melsungen |
| Alcon Inc. |
| Aesculap |
| Hu-Friedy Mfg. Co., LLC |
| Scanlan International |
| Others |
Supply & Pricing Matrix
University hospital procurement committees in the United States and Germany are consolidating vendor relationships into enterprise-wide bundled agreements, forcing optical subassembly suppliers to absorb longer payment terms and dedicate engineering resources to proprietary adapter development for legacy microscope retrofits. This buyer concentration is compressing margins for tier-two manufacturers while rewarding captive lens producers with pricing power on integrated fluorescence modules.
Pricing Analysis
High-volume transactional sales to academic medical centers anchor the bottom of the market, while premium pricing attaches to robotics platforms with bundled training ecosystems and software update subscriptions. Price differentiation hinges on FDA 510(k) clearance tier and fluorescence imaging certification level, with EU MDR conformity adding substantial clinical evidence costs that filter into European price premiums. Cost compression in the standard microscope tier is intensifying because Japanese and German specialty glass manufacturers command concentrated supply positions for optical-grade fused silica. Ambulatory surgical centers exhibit the highest price sensitivity, deferring replacement cycles and favoring portable systems with simplified maintenance protocols over integrated robotics platforms.
Supply Chain Analysis
Optical-grade fused silica supply rests on Japanese and German specialty glass manufacturers, with the Nagoya medical device manufacturing corridor and Baden-Württemberg optical cluster anchoring precision lens grinding capacity. Raw material dependencies center on high-purity synthetic quartz, rare-earth doped glass for fluorescence filters, and precision-machined aluminum housings. Single-source vulnerability concentrates in Japanese photonics suppliers subject to METI export coordination policies. Distribution runs through tier-one manufacturers with captive direct sales forces serving university hospitals, while regional distributors handle aftermarket service for installed base retrofit modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation is accelerating as layered regulatory compliance obligations across FDA, EU MDR, PMDA, and NMPA jurisdictions absorb development capital and force smaller players toward acquisition or exit.
For Market Incumbents: Anticipate substitution pressure from video-assisted technology extenders entering from endoscopy markets by deepening software companion development for fluorescence-guided workflows and securing exclusive GPO contracts with multi-hospital systems in the United States and China. Prioritize backward integration into near-infrared sensor modules to defend margin position against commoditization of white-light microscope platforms. For New Entrants and Emerging Players: Specialty distributors serving tier-2 cities in India represent the most penetrable channel, where underdeveloped cataract surgery infrastructure creates white space for portable microscope systems with simplified maintenance protocols and local language training materials. Target reconstructive surgery applications in Brazil through partnerships with free flap training centers, leveraging perfusion assessment technology gaps as the entry wedge. For Investors and Strategic Acquirers: The window for entry favors robotics platform developers with validated motion-scaling algorithms and established PMDA software validation frameworks. Long-term viability hinges on amortizing compliance costs across multi-regional distribution. Watch FDA 510(k) clearance timelines for novel fluorescence wavelengths as the inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Enterprise-wide bundled agreements with Cleveland Clinic and Mayo Clinic networks lock in multi-year platform amortization across service lines. |
| CE Marking Pathway | EU MDR conformity for fluorescence-guided systems compresses competitive access for non-integrated vendors in German specialty clinics. |
| Software Companion Development | Intraoperative perfusion assessment protocols at Seoul-based university hospitals elevate software update revenue alongside hardware sales. |
| FDA Submission | Predicate device requirements for novel wavelengths extend clearance timelines and burn development capital for imaging-integrated microscopes. |
| Reimbursement Strategy | Standardized fluorescence protocols in South Korean reconstructive surgery anchor capital budget priority for perfusion verification capabilities. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation, PMDA robotics platform standards, and hospital procurement database records, complemented by interviews with microsurgeons, biomedical engineers, hospital purchasing committee members, and GPO contracts managers. Secondary validation drew from SEC 10-K disclosures of listed optical equipment manufacturers, customs trade data for optical-grade fused silica, and CMS Medicare procedure volume statistics. Bottom-up equipment shipment modeling and top-down healthcare capital expenditure analysis were triangulated to establish market sizing.
Segment-level outputs across the projection horizon reflect discrete modeling of microscope systems, robotics platforms, microinstruments, and suture materials by technology type including fluorescence imaging, 3D visualization, and video assistance. Application segmentation spanned neurosurgery, reconstructive surgery, ophthalmic surgery, and otolaryngology with end-user differentiation across university hospitals, specialty clinics, ambulatory surgical centers, and research institutes. CAGRs were derived from procedure volume growth rates, replacement cycle compression effects, and capital budget allocation shifts toward integrated visualization systems.
Caveats apply where regulatory timeline delays at FDA or PMDA, supply disruptions in Japanese specialty glass production, or fellowship-trained microsurgeon scarcity constraints could materially shift the outlook for robotics platform adoption rates. A small set of named triggers including EU MDR enforcement intensity, METI innovation subsidy allocation, and NMPA robotic surgery pilot program expansion warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Pneumoperitoneum Market
Surgical Instruments
Germany General Surgical Devices Market
Surgical Instruments
Surgical Hand-Access Port Market
Surgical Instruments
Surgical Headband Market
Surgical Instruments
Ophthalmology Surgical Devices Market
Surgical Instruments
US Veterinary Surgical Instruments Market
Surgical Instruments
Surgical Hemostats Market
Surgical Instruments
Global Veterinary Surgical Instruments Market
Surgical Instruments
Americas Suture Needles Market
Surgical Instruments
Homecare Surgical Drains Market
Surgical Instruments
US Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Knee Surgical Impactor Market
Surgical Instruments
Surgical Pliers Market
Surgical Instruments
Suture Needles Market
Surgical Instruments
Global Biopsy Needles Market
Surgical Instruments
Thoracic Surgery Market