
 Nucleic Acid Therapeutics Contract Development and Manufacturing Organization Market | 2026-2036
Nucleic Acid Therapeutics Contract Development and Manufacturing Organization Market Size, Share, and Industry Trends Forecast 2026-2036
Nucleic Acid Therapeutics Contract Development and Manufacturing Organization Market Insights
Buyer concentration among large pharmaceutical sponsors is rebalancing toward a broader base of mid-stage biotechnology firms and gene therapy startups seeking flexible manufacturing partnerships. Lonza Group Ltd. anchors European nucleic acid capacity through its Basel-centered network, while Thermo Fisher Scientific Inc. extends integrated analytical and manufacturing services across North American markets. WuXi AppTec Co., Ltd. competes on cost-advantaged RNA synthesis scale, positioning its Suzhou facilities for multi-modal nucleic acid programs.
Nucleic acid therapeutics contract development and manufacturing organizations provide outsourced process development, analytical validation, and GMP production of DNA, RNA, and gene editing modalities, typically employing chemically synthesized oligonucleotides or enzymatically produced mRNA in lipid nanoparticle or viral vector formulations to enable targeted protein expression or gene silencing in clinical and commercial settings. Process development and analytical testing services capture the deepest margin pools as sponsors prioritize platform standardization and regulatory-ready characterization packages. Plasmid DNA and mRNA forms lead current capacity allocation, though oligonucleotide manufacturing sustains mature revenue streams from antisense and siRNA portfolios.
FDA's Chemistry, Manufacturing, and Controls guidance for gene therapy products and EMA's ATMP framework shape facility qualification requirements, batch release standards, and viral safety testing protocols that dictate market access timelines. China's NMPA nucleic acid drug technical review standards and the EU's GMP Annex 1 revisions for sterile manufacturing further constrain which contract organizations qualify for multi-regional supply. Stakeholders must monitor regulatory divergence on starting material definitions and adventitious agent testing as programs advance toward commercial scale.
Market Dynamics
Single-use bioreactor adoption and lipid nanoparticle formulation advances are compressing development timelines from 18 months to under 6 months, forcing contract manufacturers to reconfigure facility layouts and retrain technical staff.
Growth Catalysts
- FDA Chemistry, Manufacturing, and Controls guidance:Accelerated review pathways for nucleic acid-based medicines reduce regulatory uncertainty and shorten sponsor time-to-clinic decisions.
- Gene therapy startups:Mid-stage biotechnology firms now account for a rising share of outsourced manufacturing commitments as internal capacity constraints bite.
- Suzhou-Basel-Boston corridor:Specialized capacity clusters concentrate technical talent and analytical services within 50-mile radii, reducing logistics costs for multi-modal programs.
Market Restraints
- Plasmid DNA supply concentration:Three specialized fermentation facilities control 60% of GMP-grade plasmid starting material, creating single-point-of-failure exposure.
- EMA ATMP facility qualification:Batch release standards and viral safety testing protocols extend qualification timelines by 8-14 months for new market entrants.
- Enzymatic mRNA synthesis input costs:Modified nucleotide triphosphate prices fluctuate 40% annually, squeezing margin pools in commercial-scale production.
Strategic Opportunities
- China NMPA nucleic acid drug technical review standards:Domestic sponsors seek CDMO partners with dual US-China filing experience to access the world's second-largest gene therapy pipeline.
- CRISPR-guide RNA conjugate manufacturing:Convergence of mRNA production and oligonucleotide chemistry opens white space for integrated cell-and-gene therapy service providers.
- Direct-to-biotech distribution platforms:Digital procurement portals displace traditional sponsor-CDMO relationship brokers, compressing contracting cycles from 12 weeks to 3 weeks.
Industry Challenges
- Lipid nanoparticle formulation scientists:Talent scarcity in microfluidic mixing and excipient characterization extends project onboarding by 4-6 months.
- EU GMP Annex 1 sterile manufacturing revisions:Contamination control strategy documentation demands 2,000+ additional validation hours per facility.
- Platform standardization across modalities:DNA, mRNA, and gene editing programs require incompatible analytical methods, fragmenting equipment utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nucleic Acid Therapeutics Contract Development and Manufacturing Organization Market |
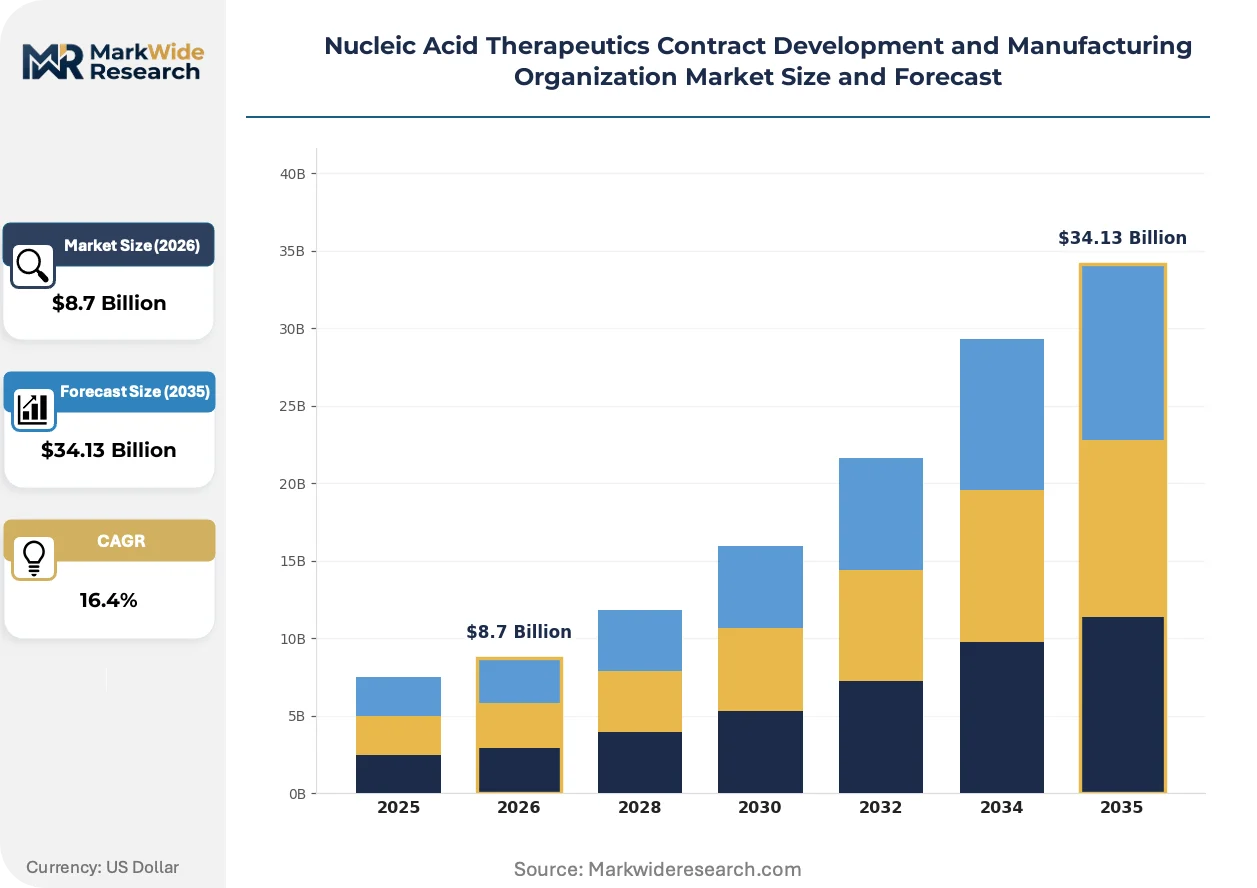
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Process Development, Analytical Testing, Filling, Packaging Technology: RNA Synthesis, DNA Synthesis, Gene Editing, Sequencing Form: Plasmid DNA, mRNA, Oligonucleotides, Viral Vectors End User: Biotechnology Firms, Pharmaceutical Companies, Research Institutions, Academia |
| Companies Covered | Thermo Fisher Scientific Inc., Lonza Group Ltd., Catalent Inc., AGC Biologics Inc., Danaher Corporation, WuXi AppTec Co., Ltd., Agilent Technologies, Inc., Ajinomoto Bio-Pharma Services, Bachem AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nucleic Acid Therapeutics Contract Development and Manufacturing Organization Market Trends and Innovations
Continuous manufacturing and artificial intelligence-driven process control are displacing batch-based paradigms, enabling real-time release testing and reducing facility footprint requirements by half.
Microfluidic mixing technology for lipid nanoparticle encapsulation is expanding into commercial-scale production lines previously reserved for stainless-steel batch reactors. Gene therapy developers with approved products are retrofitting 2,000-liter single-use trains with precision pumping modules. This shift is compressing tech transfer timelines from 9 months to 14 weeks and enabling 50-batch campaigns without equipment changeover.
EMA's ATMP framework revision tightens starting material traceability requirements for viral vectors and plasmid DNA. Manufacturers must now document chain-of-custody from cell bank through final drug substance. European sponsors are consolidating supplier audits to reduce qualification burden, favoring CDMOs with integrated plasmid-to-LNP capabilities over fragmented supply chains.
Sponsor technical teams now embed directly within CDMO facilities for 6-12 month co-development residencies. Large pharmaceutical sponsors displace traditional technology transfer protocols with resident scientist programs. This pattern concentrates in Boston and Basel, where sponsor-CDMO geographic proximity enables weekly face-to-face batch review meetings.
Nucleic Acid Therapeutics Contract Development and Manufacturing Organization Market Segmentation
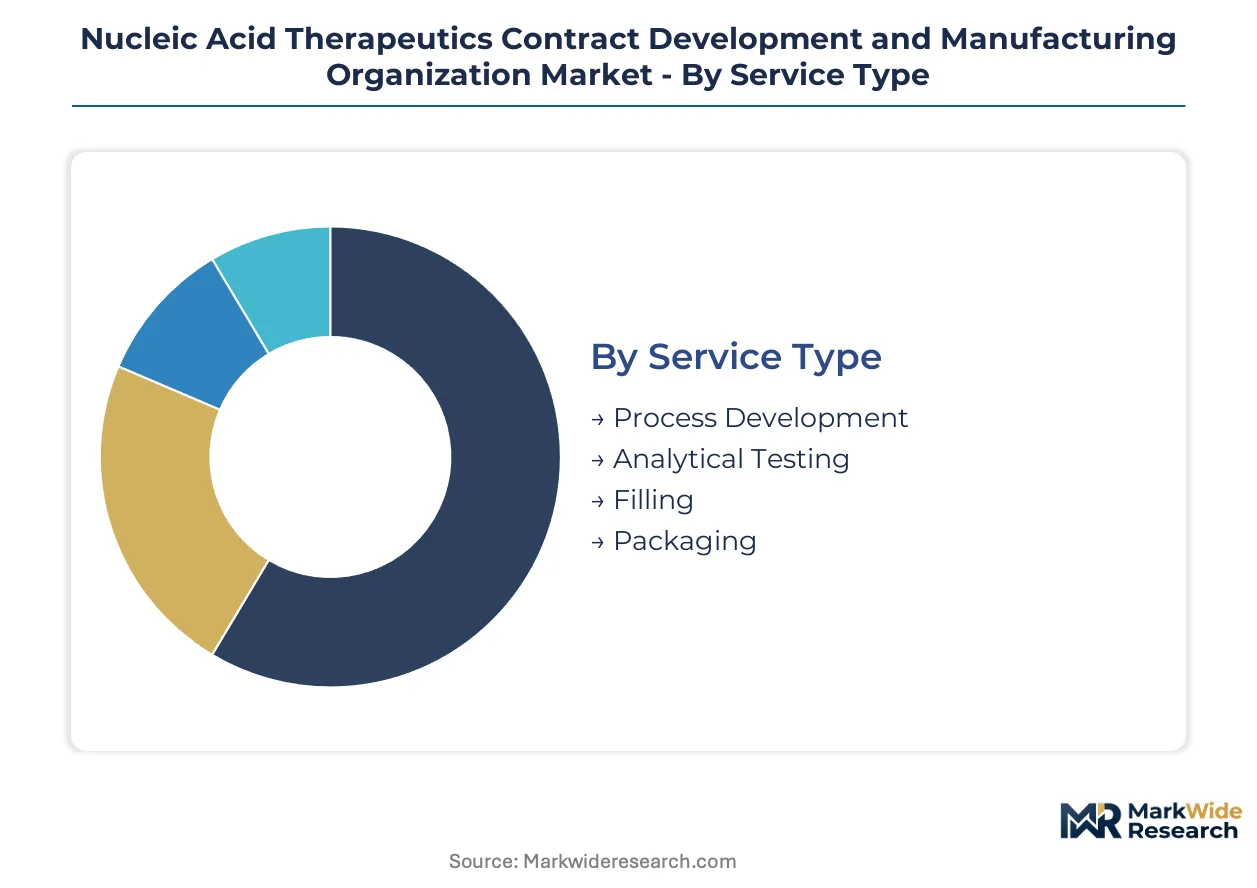
Nucleic acid CDMOs compete across distinct service layers and technology platforms, each commanding different margin structures and customer loyalty profiles. Process development and analytical testing capture premium pricing through regulatory-ready characterization packages, while manufacturing execution segments compete on scale and speed. Understanding where value concentrates across these dimensions determines partnership strategy for gene therapy sponsors.
Service Type:
Process development commands premium fees through regulatory complexity, while filling and packaging compete on throughput volume and automation efficiency.
- Process Development:Cell line engineering, upstream fermentation optimization, and downstream purification design for DNA, RNA, and viral vector platforms. Sponsors in the United States and Switzerland pay 40-60% fee premiums for platforms with prior FDA or Swissmedic approval history, compressing tech transfer risk.
- Analytical Testing:Method development, validation, and release testing for identity, purity, potency, and safety attributes. China's NMPA technical review standards and EMA's ATMP framework drive demand for dual-qualified characterization packages from multi-regional sponsors.
- Filling:Aseptic processing of drug substance into vials, syringes, or cryogenic containers for clinical and commercial distribution.
- Packaging:Labeling, kit assembly, and cold-chain distribution preparation for patient-specific or regional supply requirements.
Today's leader: Process Development. Tomorrow's challenger: Analytical Testing.
Technology:
RNA synthesis capacity expands fastest as mRNA vaccines and therapeutics command manufacturing priority, while gene editing platforms require specialized guide RNA and delivery chemistry integration.
- RNA Synthesis:Enzymatic in vitro transcription producing mRNA, self-amplifying RNA, and guide RNA for therapeutic applications. Modified nucleotide triphosphate supply constraints in China and enzymatic raw material cost volatility squeeze margin pools at commercial scale.
- Gene Editing:CRISPR-Cas9 guide RNA synthesis, ribonucleoprotein complex assembly, and viral vector integration for cell therapy programs. Boston-area sponsors concentrate demand for integrated mRNA-plus-editing CDMO partnerships to streamline regulatory filing.
- DNA Synthesis:Solid-phase and enzymatic production of plasmid DNA, gene fragments, and oligonucleotide building blocks.
- Sequencing:Next-generation sequencing for identity confirmation, clonality verification, and adventitious agent detection.
RNA synthesis is climbing the fastest; gene editing holds the steepest expansion trajectory for integrated service providers.
Form:
mRNA and plasmid DNA forms absorb the majority of current capacity investment, though oligonucleotide manufacturing sustains mature revenue from antisense and siRNA portfolios.
- mRNA:Linearized DNA template transcription with 5' cap and poly-A tail modifications, formulated in lipid nanoparticles for cellular delivery. Suzhou facilities compete on cost-advantaged synthesis scale for multi-modal programs targeting both US and China filings.
- Plasmid DNA:Circular DNA vectors produced through bacterial fermentation as starting material for mRNA, viral vector, and gene therapy products. Three specialized fermentation facilities control the majority of GMP-grade supply, creating qualification bottlenecks for new market entrants.
- Oligonucleotides:Chemically synthesized antisense, siRNA, and aptamer therapeutics produced through solid-phase synthesis.
- Viral Vectors:AAV, lentiviral, and adenoviral platforms for gene delivery manufactured through transient transfection or stable producer cell lines.
mRNA dominates current capacity allocation; viral vectors are gaining share fastest as durable gene therapy approvals accumulate.
End User:
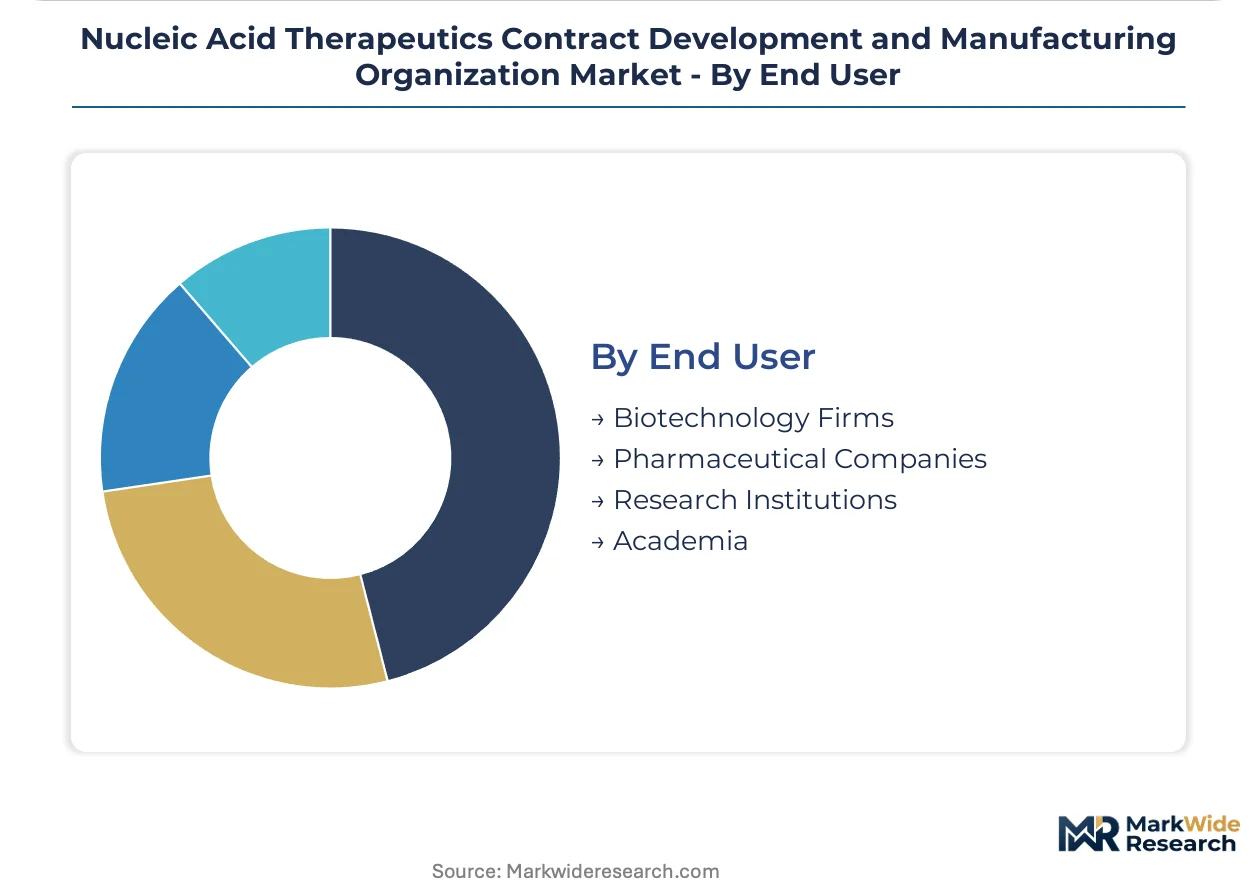
Mid-stage biotechnology firms now drive outsourcing growth as internal manufacturing constraints and accelerated FDA review timelines compress build-versus-buy decisions.
- Biotechnology Firms:Gene therapy startups and RNA therapeutics developers lacking captive GMP capacity. These sponsors embed technical teams within CDMO facilities for 6-12 month co-development residencies, particularly in Basel and Boston where geographic proximity enables weekly batch reviews.
- Pharmaceutical Companies:Large sponsors consolidating fragmented supplier bases and retrofitting approved-product facilities with single-use bioreactor trains. Their procurement patterns favor CDMOs with integrated plasmid-to-LNP capabilities over fragmented supply chains.
- Research Institutions:Academic medical centers and nonprofit research organizations requiring clinical-grade material for investigator-initiated trials.
- Academia:University laboratories seeking process development partnerships for translational research programs.
Biotechnology firms anchor near-term demand expansion; pharmaceutical companies represent the deepest contract value for multi-year commercial supply agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States capacity clusters absorb higher sponsor premiums than Swiss facilities, while Chinese manufacturers compress synthesis timelines through integrated raw material sourcing.
United States
FDA Chemistry, Manufacturing, and Controls guidance accelerates sponsor time-to-clinic decisions for gene therapy developers. The regulator's accelerated review pathways reduce regulatory uncertainty for nucleic acid-based medicines. Greater Boston anchors the densest concentration of CDMO-sponsor co-development residencies, with weekly face-to-face batch review meetings compressing tech transfer timelines.
Switzerland
Swissmedic approval history commands 40-60% fee premiums from sponsors seeking compressed tech transfer risk. The country's ATMP framework alignment with EMA standards streamlines multi-regional filing strategies. Basel-centered networks concentrate technical talent and analytical services within 50-mile radii, reducing logistics costs for multi-modal programs.
China
NMPA nucleic acid drug technical review standards drive domestic sponsor demand for dual US-China filing experience. The regulator's evolving standards constrain which contract organizations qualify for multi-regional supply. Suzhou facilities compete on cost-advantaged RNA synthesis scale, positioning for programs targeting both US and China regulatory pathways.
Germany
EMA ATMP facility qualification requirements extend batch release timelines for new market entrants seeking European market access. The EU GMP Annex 1 revisions for sterile manufacturing impose contamination control documentation demands. Industrial clusters in Baden-Württemberg and Bavaria concentrate viral vector and plasmid DNA manufacturing expertise.
United Kingdom
MHRA post-Brexit regulatory divergence creates qualification complexity for sponsors seeking UK-EU dual market access. The agency's gene therapy product guidance shapes facility qualification and viral safety testing protocols. London and Cambridge biotech corridors concentrate mid-stage gene therapy startups lacking captive GMP capacity.
Nucleic Acid Therapeutics Contract Development and Manufacturing Organization Market Competitive Landscape
Swiss producers anchor the premium-tier segment; Chinese specialists hold cost-advantaged scale positions. The vendor base stratifies across three functional tiers: integrated platform providers, modality-specific specialists, and regional fill-finish operators. Two strategic archetypes dominate competitive positioning—those with prior FDA or EMA approval history commanding fee premiums, and those with dual US-China filing experience capturing cross-border programs. Capacity expansion and strategic partnerships represent the dominant competitive moves, with sponsors consolidating fragmented supplier bases toward integrated plasmid-to-LNP capabilities.
Within the integrated platform tier, Thermo Fisher Scientific Inc. exemplifies North American analytical and manufacturing service breadth, while Lonza Group Ltd. anchors European nucleic acid capacity through Basel-centered networks. WuXi AppTec Co., Ltd. occupies a position representing cost-advantaged RNA synthesis scale for multi-modal programs. These three entities collectively illustrate the geographic and functional specialization patterns shaping sponsor partnership decisions.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Lonza Group Ltd. |
| Catalent Inc. |
| AGC Biologics Inc. |
| Danaher Corporation |
| WuXi AppTec Co., Ltd. |
| Agilent Technologies, Inc. |
| Ajinomoto Bio-Pharma Services |
| Bachem AG |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between FDA-approved platforms and emerging NMPA-qualified facilities creates parallel pricing tracks that reshape supplier selection and geographic sourcing strategies across the nucleic acid CDMO landscape. Premium-tier sponsors in the United States and Switzerland absorb 40-60% fee markups for Swissmedic-validated processes, while cost-driven biotechnology firms route programs through Suzhou facilities to compress development budgets without sacrificing dual-filing flexibility.
Pricing Analysis
Capacity additions in China are reshaping price floors for enzymatic mRNA synthesis as WuXi AppTec's Suzhou network competes on scale-driven unit economics. Three-tier pricing structure across premium, standard, and economy levels separates Swissmedic-validated Basel facilities from mid-tier North American providers and cost-optimized Chinese operations. Pricing pressure stems from modified nucleotide triphosphate cost volatility, squeezing margin pools at commercial scale. Biotechnology startups exhibit highest price sensitivity, while large pharmaceutical sponsors prioritize regulatory approval history over unit cost.
Supply Chain Analysis
EMA ATMP qualification requirements and FDA Chemistry, Manufacturing, and Controls guidance create dual-certification gating that fragments supplier eligibility across Atlantic and Pacific filing pathways. GMP-grade plasmid DNA production concentrates in the United States, Switzerland, and Germany, with three specialized fermentation facilities controlling majority supply. Raw material dependencies center on modified nucleotide triphosphates, lipid excipients, and single-use bioreactor consumables sourced from Chinese and European chemical suppliers. Single-source vulnerability in plasmid starting material creates qualification bottlenecks for new market entrants. Distribution runs through sponsor-embedded co-development residencies in Boston and Basel, displacing traditional technology transfer protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA accelerated review pathway expansion for nucleic acid-based medicines continuously generates new sponsor demand for qualified manufacturing partnerships.
For Market Incumbents: Extend integrated plasmid-to-LNP capabilities through backward integration into GMP-grade plasmid fermentation capacity, capturing margin pools currently leaked to fragmented suppliers. Anchor multi-regional qualification portfolios by securing dual FDA-NMPA filing experience ahead of China's gene therapy pipeline maturation. Defend against emerging Chinese cost competitors by embedding resident scientist programs that compress tech transfer timelines below 14 weeks. For New Entrants and Emerging Players: Microfluidic mixing technology for lipid nanoparticle encapsulation offers entry wedge into commercial-scale production lines previously reserved for incumbent stainless-steel batch networks. Target CRISPR-guide RNA conjugate manufacturing white space where mRNA production and oligonucleotide chemistry convergence lacks integrated service providers. Pursue digital procurement portal partnerships to displace traditional sponsor-CDMO relationship brokers and compress contracting cycles. For Investors and Strategic Acquirers: Consolidation pressure builds where plasmid DNA supply concentration creates single-point-of-failure exposure for gene therapy developers with approved products. Long-term viability favors vertically integrated platforms spanning process development through commercial fill-finish, with analytics capabilities commanding premium multiples. Acquisition target archetype: mid-cap CDMOs with resident scientist program infrastructure and prior Swissmedic approval history. Monitor EMA ATMP framework revisions on starting material traceability as inflection indicator for qualification burden shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Plasmid-to-LNP Capacity Buildout | Captures margin pools from fragmented supply chains while meeting sponsor consolidation preferences. |
| Dual FDA-NMPA Filing Qualification | Unlocks access to China's second-largest gene therapy pipeline and cross-border program demand. |
| Resident Scientist Co-Development Programs | Compresses tech transfer timelines from 9 months to 14 weeks in Boston and Basel clusters. |
| Microfluidic LNP Commercial Scale-Up | Displaces batch-based paradigms with continuous manufacturing and real-time release testing capabilities. |
| Digital Procurement Platform Launch | Shortens contracting cycles from 12 weeks to 3 weeks by displacing traditional relationship brokers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with gene therapy development executives, regulatory affairs leads, CDMO technical directors, and sponsor procurement managers with secondary validation from FDA Chemistry, Manufacturing, and Controls guidance documents, EMA ATMP framework publications, NMPA technical review standards, and ClinicalTrials.gov nucleic acid therapeutic program listings. Bottom-up capacity and demand modeling triangulated against top-down market sizing from public CDMO facility announcements and sponsor partnership disclosures.
Comparable-period anchoring linked historical capacity utilization patterns to forward-projected sponsor pipeline maturation across the analysis window. Segmentation dimensions modeled include service type, technology platform, therapeutic form, and end-user archetype, with regulatory pathway cluster as industry-specific overlay. CAGRs derived from facility expansion announcements, sponsor manufacturing commitment disclosures, and enzymatic synthesis cost curve trajectories. Forecast inputs incorporated single-use bioreactor adoption rates and lipid nanoparticle formulation technology transfer velocity.
The model holds under stable regulatory pathway acceleration and continued gene therapy startup formation; deviation in plasmid DNA supply disruption or EMA-NMPA qualification divergence would shift capacity allocation assumptions. Forecasts reflect documented assumptions on sponsor build-versus-buy decision timing and CDMO qualification timeline compression. A model refresh is warranted upon material change in FDA accelerated review pathway eligibility criteria or NMPA nucleic acid drug technical review standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Acyclovir Market
Pharmaceuticals
Global Combination Vaccine Market
Pharmaceuticals
Global Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
Global Cardiovascular Drugs Market
Pharmaceuticals
Latin America Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Europe Oral Anti-Diabetic Drug Market
Pharmaceuticals
Italy Pharmaceutical Market
Pharmaceuticals
Aminophylline Market
Pharmaceuticals
Roflumilast API Market
Pharmaceuticals
Global Tetanus Toxoid Vaccine Market
Pharmaceuticals
Global Pharmaceutical Drug Delivery Market
Pharmaceuticals
South Africa Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Omeprazole and Antihistamine Market
Pharmaceuticals
Preeclampsia Therapeutics Market
Pharmaceuticals
Saudi Arabia Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Global Recombinant Vaccines Market