
 Surgical Broaches Market | 2026-2036
Surgical Broaches Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Broaches Market Analytics
Hospital procurement channels is tilting toward direct manufacturer partnerships for surgical broaches, bypassing traditional distributors in high-volume orthopedic centers. Smith & Nephew plc leverages its integrated manufacturing network to sustain supply chain control across European hospital systems. Zimmer Biomet Holdings anchors its broach portfolio through specialized product lines for hip and knee reconstruction. Stryker Corporation competes by dominating the North American ambulatory surgical center segment with streamlined instrument kits.
Surgical broaches are precision cutting instruments with fluted, tapered profiles designed to remove bone and prepare medullary canals for implant seating, typically manufactured from hardened stainless steel or titanium alloys through CNC grinding and electrochemical polishing. Disposable broaches command expanding share in ambulatory settings where sterilization infrastructure remains limited, while reusable titanium variants retain margin concentration in tertiary hospital orthopedic departments. Stainless steel dominates unit volume across price-sensitive markets, though alloy compositions incorporating cobalt-chrome elements are gaining traction for revision arthroplasty applications requiring enhanced fatigue resistance.
FDA 510(k) clearance pathways and CE marking under the EU MDR govern instrument validation, with both frameworks mandating biocompatibility testing and fatigue-load documentation that extends development timelines for new broach geometries. ISO 13485 quality management standards further shape supplier qualification, particularly for orthopedic clinics seeking dual-certified vendors. Stakeholders must monitor evolving sterilization validation requirements as healthcare systems weigh capital investment in reusable instrument programs against single-use alternatives.
Market Dynamics
Orthopedic clinics are consolidating instrument procurement around dual-certified suppliers capable of meeting both FDA 510(k) and EU MDR validation timelines, compressing vendor qualification cycles and elevating compliance infrastructure as a competitive moat.
Growth Catalysts
- EU MDR Implementation:The Medical Device Regulation's enhanced clinical evidence requirements are filtering out marginal suppliers and concentrating contract awards among ISO 13485-certified manufacturers with dedicated regulatory affairs teams.
- Ambulatory Surgical Center Expansion:Freestanding orthopedic facilities in Texas and Florida are scaling disposable broach programs to circumvent capital-intensive sterilization infrastructure investments.
- Cobalt-Chrome Alloy Adoption:Revision arthroplasty applications are driving demand for fatigue-resistant broach geometries incorporating cobalt-chrome elements that withstand higher torsional loads during implant extraction procedures.
Market Restraints
- Titanium Feedstock Volatility:Sponge titanium prices fluctuate with aerospace sector demand, squeezing margins for manufacturers of premium reusable broach lines.
- German Supply Concentration:Precision grinding capacity clusters around Solingen and Tuttlingen, creating single-point vulnerability for European OEMs dependent on electrochemical polishing subcontractors.
- Reusable Instrument Liability:Sterilization assurance documentation under FDA guidance documents exposes hospitals to litigation risk when fatigue fractures occur in reprocessed titanium broaches.
Strategic Opportunities
- Indian Orthopedic Device Manufacturing:CDSCO's streamlined Class B device registration pathway and PLI scheme incentives are attracting contract manufacturers seeking cost-advantaged production for export markets.
- Additive Manufacturing Convergence:Hybrid production combining CNC grinding with selective laser melting enables patient-specific broach geometries for complex revision cases without dedicated forging dies.
- Direct Hospital Contracting:IDN procurement officers in Pennsylvania and Ohio are bypassing distributors for high-volume hip and knee reconstruction kits, capturing 12-18 point margin improvements.
Industry Challenges
- Electrochemical Polishing Technician Shortage:Specialized surface finishing expertise for titanium broaches remains concentrated among aging workforces in German and Swiss manufacturing clusters.
- EU MDR Technical Documentation:Legacy broach designs require retroactive clinical evaluation reports, consuming 14-22 month regulatory bandwidth that delays new product introductions.
- Legacy Sterilization Validation:Steam sterilization protocols for reusable broaches must be revalidated against updated ISO 17665 standards, forcing hospital biomedical engineering departments into unplanned capital cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Broaches Market |
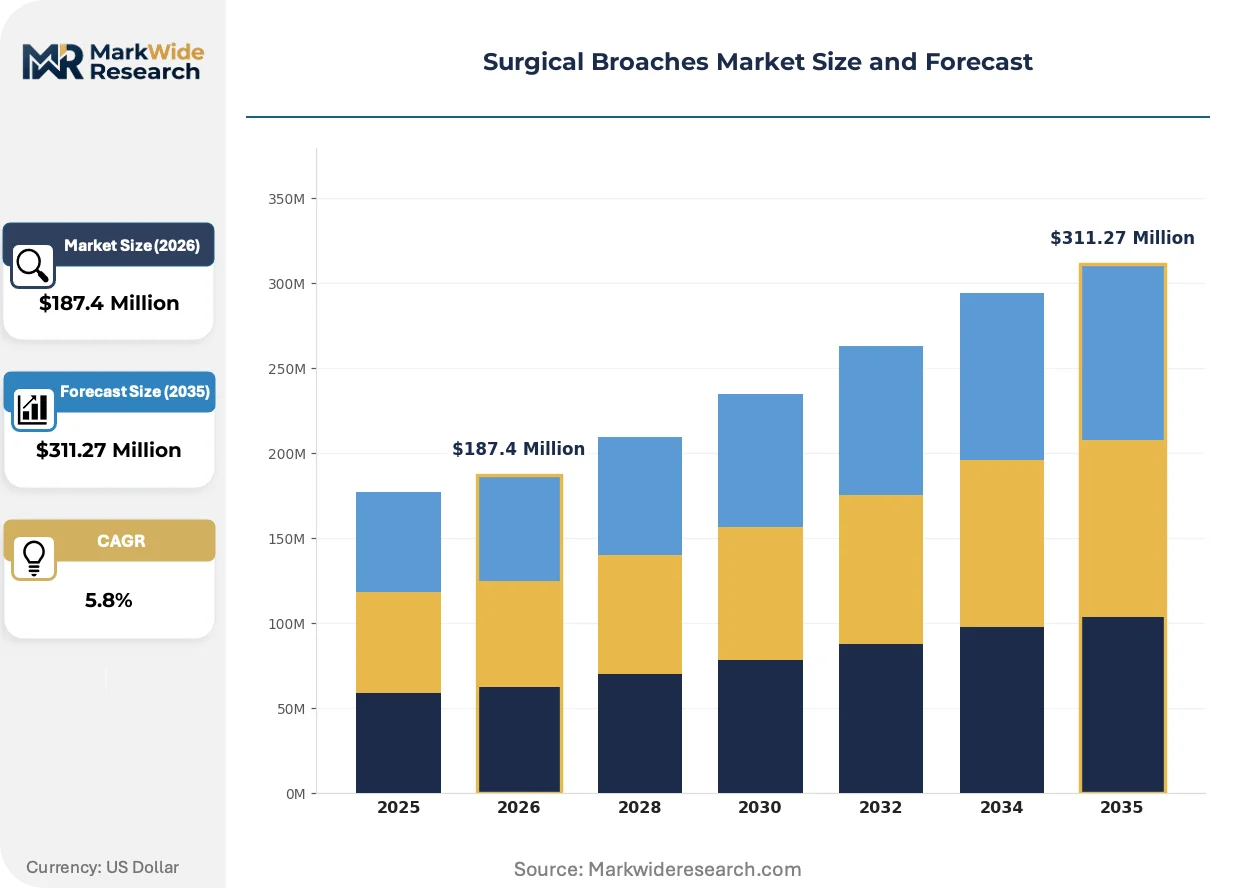
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Purpose, Multi-Purpose, Disposable, Reusable Material: Stainless Steel, Titanium, Alloy, Plastic End User: Hospitals, Ambulatory Surgical Centers, Orthopedic Clinics, Dental Surgeries Functionality: Bone Preparation, Tissue Management, Surgical Fixation, Implantation |
| Companies Covered | Smith & Nephew plc, Zimmer Biomet Holdings, Stryker Corporation, Medtronic, Sandvik, Tecomet Inc, B. Braun SE, CONMED Corporation, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Broaches Market Evolving Landscape
Digital thread integration across design, manufacturing, and post-market surveillance is compressing product development cycles while regulatory data requirements are expanding. Three developments are restructuring competitive positioning.
Robotic-assisted arthroplasty navigation is digitizing broach selection and insertion depth protocols through preoperative planning software that generates patient-specific resection guides. Academic medical centers in Massachusetts and California are deploying these systems for complex primary cases, reducing operative time variability and standardizing implant positioning accuracy across resident training programs.
CE marking under the EU MDR now mandates annual safety update reports and post-market clinical follow-up for Class IIa surgical instruments, extending regulatory maintenance obligations across a product's commercial lifespan. German notified bodies are enforcing stricter biocompatibility testing for nickel-bearing stainless steel alloys, prompting manufacturers to accelerate titanium migration for European market access.
Hospital value analysis committees are unbundling instrument tray sterilization costs from per-procedure pricing, forcing suppliers to disclose lifecycle cost models comparing disposable and reusable broach programs. Integrated delivery networks in North Carolina and Michigan are piloting consignment inventory arrangements where manufacturers retain ownership until point-of-use, transferring working capital burden upstream while capturing consumption data for demand forecasting.
Surgical Broaches Market Segmentation
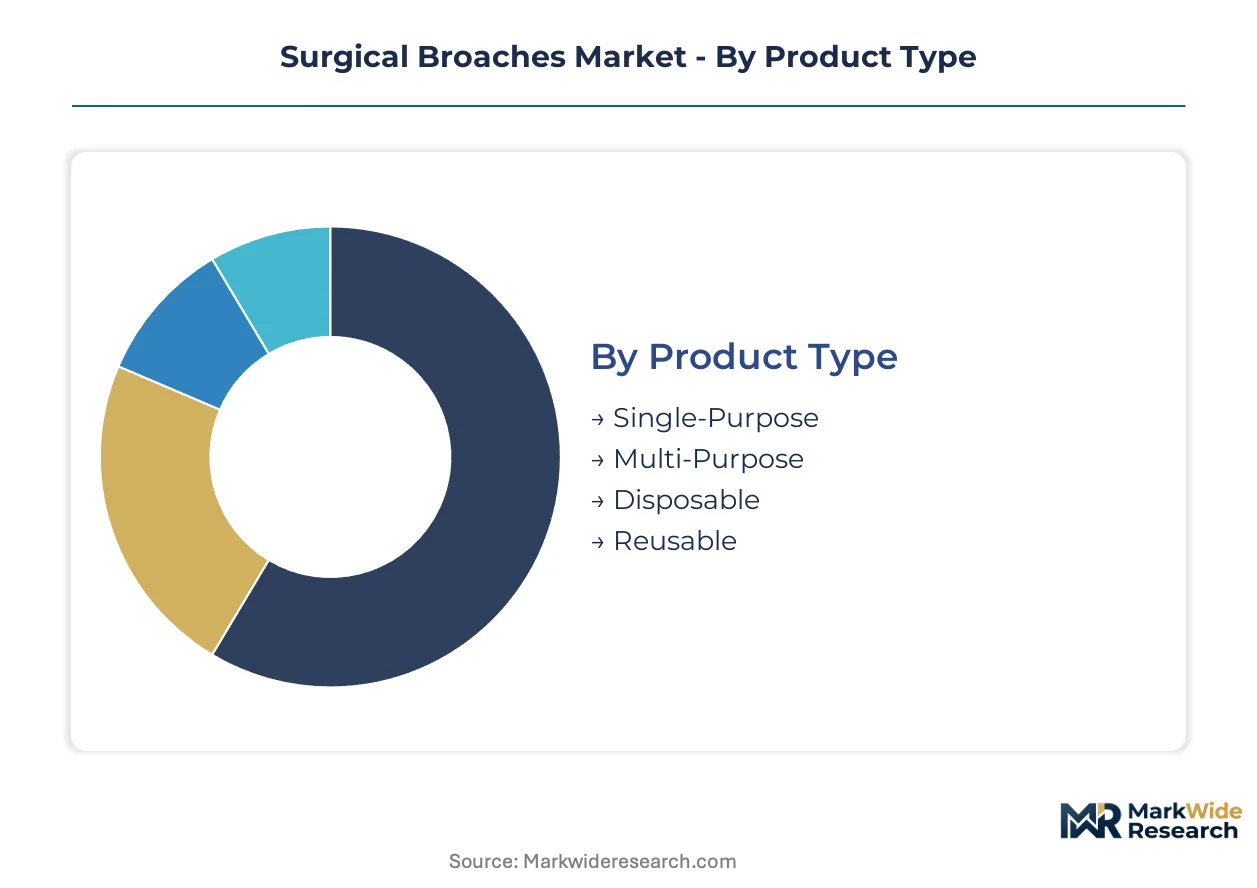
Surgical broaches segment across material science, functional application, and procurement economics. Each dimension shapes vendor positioning and margin architecture differently. Understanding these splits reveals where capital concentrates and where substitution threats emerge.
Product Type:
Cost tier differentiation separates single-use disposables from capital-intensive reusable platforms.
- Disposable:Polymer and coated metal instruments designed for single-procedure use eliminate reprocessing documentation and liability exposure. Freestanding orthopedic facilities in Texas and Florida are scaling these programs to bypass steam sterilization infrastructure investments.
- Reusable:Hardened titanium and stainless steel variants withstand hundreds of autoclave cycles with validated fatigue thresholds. Tertiary hospital orthopedic departments in Germany retain these for revision arthroplasty where instrument customization drives surgical outcomes.
- Single-Purpose:Geometry-specific designs optimized for discrete anatomical sites such as femoral canals or acetabular sockets.
- Multi-Purpose:Modular broach systems with interchangeable heads reducing tray inventory counts.
Reusable broaches command the established base. The steepest expansion runs through Disposable.
Material:
Application severity and sterilization frequency dictate alloy selection and surface finishing requirements.
- Titanium:Biocompatible alpha-beta alloys with superior fatigue resistance and reduced nickel ion release. German notified bodies under EU MDR are accelerating titanium migration as nickel-bearing stainless steel faces stricter biocompatibility scrutiny.
- Stainless Steel:Martensitic grades dominate unit economics across price-sensitive markets through established CNC grinding supply chains.
- Alloy:Cobalt-chrome compositions gaining traction for revision cases requiring enhanced torsional load capacity during implant extraction.
- Plastic:Polymer-based disposable alternatives for low-load applications and emerging markets with limited sterilization infrastructure.
Stainless Steel anchors volume leadership. The most rapid share gains are occurring in Titanium.
End User:
Customer type determines procurement channel structure and lifecycle cost modeling sophistication.
- Hospitals:Integrated delivery networks in Pennsylvania and Ohio are unbundling instrument tray sterilization costs from per-procedure pricing, forcing suppliers into transparent total cost of ownership disclosures.
- Orthopedic Clinics:Specialized procurement teams in Germany's Solingen-Tuttlingen corridor concentrate demand for precision-ground instruments with electrochemical polishing certification.
- Ambulatory Surgical Centers:Freestanding facilities prioritize disposable programs and streamlined instrument kits to minimize biomedical engineering overhead.
- Dental Surgeries:Lower-volume applications with distinct regulatory pathways and reduced fatigue-load requirements.
Hospitals retain procurement volume dominance. Orthopedic Clinics are climbing the fastest as consolidation concentrates buying power.
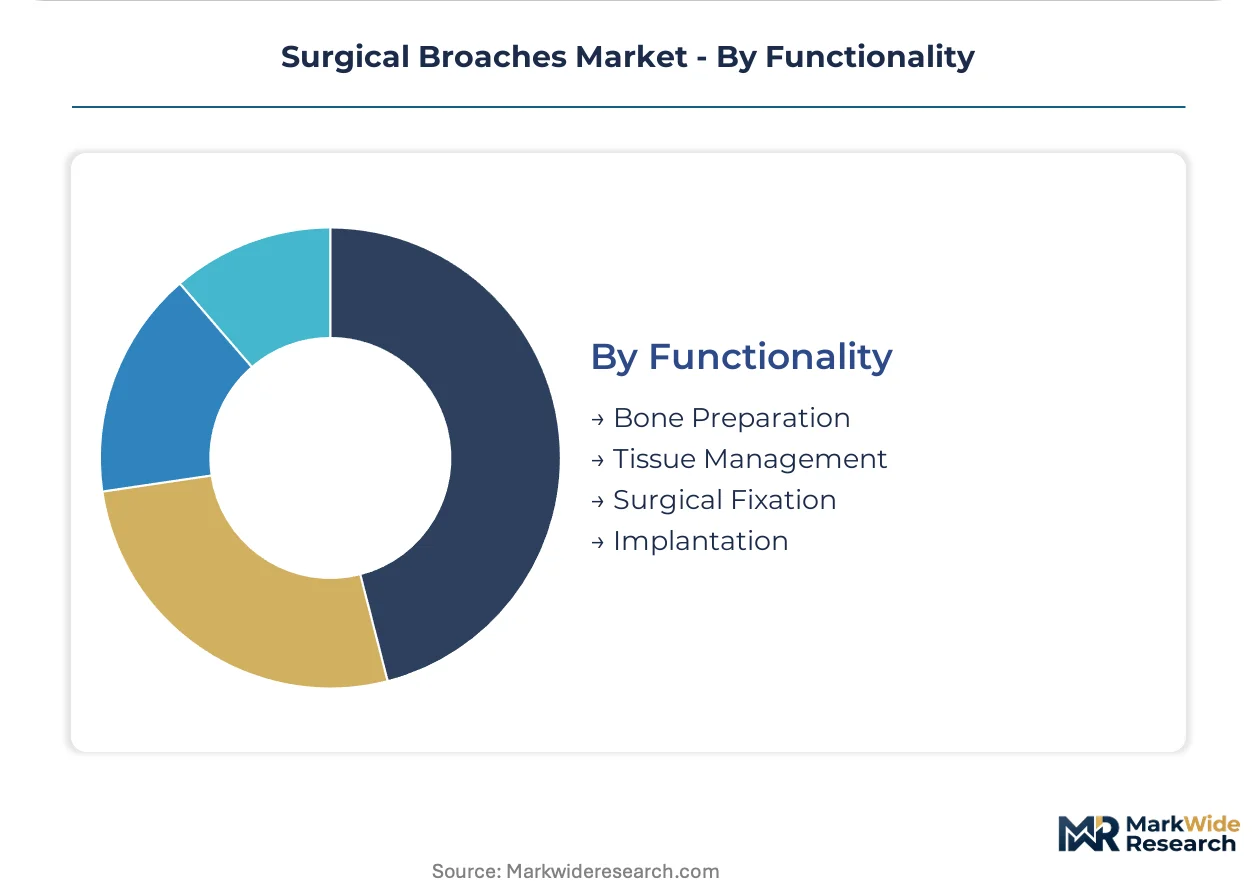
Functionality:
Volume and margin distribution align with procedural complexity and implant category growth.
- Bone Preparation:Fluted, tapered geometries for medullary canal shaping constitute the core application across hip and knee reconstruction.
- Implantation:Broach-assisted implant seating protocols expanding with robotic-assisted arthroplasty navigation systems.
- Tissue Management:Adjunct soft tissue protection features integrated into broach handle designs.
- Surgical Fixation:Complementary stabilization applications in trauma and revision contexts.
Bone Preparation holds the functional core. Implantation is gaining share fastest as navigation technology proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's dominance in precision instrument exports, connecting Solingen grinding workshops to hospital procurement offices across three continents.
United States
Ambulatory surgical centers in Texas and Florida are scaling disposable broach programs to bypass steam sterilization infrastructure. FDA 510(k) clearance pathways mandate biocompatibility testing that extends development timelines for new geometries. Greater Boston academic medical centers are deploying robotic-assisted arthroplasty navigation systems that digitize broach selection protocols.
Germany
Specialized orthopedic device clusters in Solingen and Tuttlingen drive premium instrument adoption through electrochemical polishing certification. EU MDR implementation filters marginal suppliers and concentrates contract awards among ISO 13485-certified manufacturers. The Rhine-Ruhr logistics corridor enables just-in-time delivery to European hospital systems.
India
CDSCO's streamlined Class B device registration pathway and PLI scheme incentives attract contract manufacturers seeking cost-advantaged production. Maharashtra and Gujarat house emerging precision grinding facilities serving export markets. Mumbai-Pune industrial belt suppliers are qualifying for dual FDA-EU certification to access Western procurement channels.
Japan
PMDA regulatory harmonization with ISO standards accelerates approval timelines for titanium alloy instruments. Kansai region manufacturers supply fatigue-resistant broach geometries for revision arthroplasty. Osaka-based precision metalworking clusters maintain captive electrochemical polishing capacity.
United Kingdom
Integrated delivery networks in England are unbundling instrument tray sterilization costs from per-procedure pricing. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical documentation requirements. Midlands manufacturing bases supply NHS orthopedic procurement frameworks.
Surgical Broaches Market Competitive Landscape
On the supply side, the industry is consolidating around dual-certified manufacturers capable of navigating both FDA 510(k) and EU MDR validation timelines. Three strategic archetypes dominate: diversified orthopedic conglomerates with integrated manufacturing networks, precision metalworking specialists with captive surface finishing capacity, and contract manufacturers leveraging cost-advantaged production locations. M&A activity targets regulatory affairs capabilities and electrochemical polishing expertise, while geographic expansion focuses on Indian and Southeast Asian production bases.
Among diversified orthopedic conglomerates, Smith & Nephew plc and Zimmer Biomet Holdings exemplify integrated supply chain control across European hospital systems. Stryker Corporation occupies a position within the ambulatory surgical center segment. These three entities represent distinct competitive vectors: manufacturer-direct hospital contracting, specialized hip and knee reconstruction portfolios, and streamlined instrument kit configurations for freestanding facilities.
| Leading Market Players |
|---|
| Smith & Nephew plc |
| Zimmer Biomet Holdings |
| Stryker Corporation |
| Medtronic |
| Sandvik |
| Tecomet Inc |
| B. Braun SE |
| CONMED Corporation |
| Olympus Corporation |
| Others |
Value Network & Pricing Analysis
The Port of Hamburg's container throughput cost dynamics compress margin buffers for precision instrument exporters while amplifying price differentiation between electrochemical-polished titanium broaches and standard stainless steel variants. German grinding workshops pass logistics premiums downstream, forcing hospital procurement offices into tiered volume negotiations that separate premium certified suppliers from price-competitive alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates surgical broach procurement, with ISO 13485-FDA dual certification commanding substantial premiums over single-certified alternatives. Price differentiation rests on electrochemical polishing certification and validated fatigue-load documentation, while cost compression in the standard tier intensifies as Indian contract manufacturers qualify for Western hospital procurement channels. Ambulatory surgical centers exhibit highest price sensitivity due to disposable program scale requirements, whereas German orthopedic clinics demonstrate lowest sensitivity given outcome-linked procurement criteria.
Supply Chain Analysis
Sponge titanium feedstock draws from aerospace sector demand cycles in the United States, Russia, and Japan, creating margin volatility for premium reusable broach manufacturers. Raw material dependencies center on cobalt-chrome alloys for revision applications, martensitic stainless steel grades for volume production, and specialized grinding abrasives for surface finishing. Single-source vulnerability concentrates around Solingen-Tuttlingen electrochemical polishing subcontractors, with distribution running through manufacturer-direct hospital contracts and specialized orthopedic instrument distributors serving lower-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrochemical polishing expertise functions as the constraining asset in this market, with aging technician workforces in German and Swiss manufacturing clusters limiting output expansion regardless of capital deployment.
For Market Incumbents: Pre-empt regulatory bandwidth exhaustion by accelerating EU MDR technical documentation completion for legacy broach designs before notified body queue times extend further. Capture captive electrochemical polishing capacity through acquisition or exclusive contracting arrangements, neutralizing the emerging threat from Indian contract manufacturers seeking dual certification.
For New Entrants and Emerging Players: Pursue CDSCO Class B registration and PLI scheme qualification in Maharashtra and Gujarat to establish cost-advantaged production for export markets. Target disposable broach programs in Texas and Florida ambulatory surgical centers through streamlined instrument kit configurations that minimize biomedical engineering overhead requirements.
For Investors and Strategic Acquirers: Precision metalworking specialists with captive surface finishing capacity and existing ISO 13485 infrastructure represent the highest-conviction acquisition archetype. Monitor PMDA regulatory harmonization progress as the inflection indicator for Japanese market access timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Completion | Notified body queue management secures market access continuity for Class IIa instruments. |
| Electrochemical Polishing Capacity Acquisition | Captive surface finishing expertise neutralizes single-source subcontractor vulnerability. |
| CDSCO Class B Registration Pathway | Indian regulatory qualification unlocks PLI scheme incentives for export-oriented production. |
| Robotic-Assisted Navigation Integration | Preoperative planning software partnerships standardize broach selection protocols. |
| Consignment Inventory Arrangements | Point-of-use ownership transfer reduces hospital working capital burden while capturing consumption data. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with orthopedic surgeons, hospital procurement committee members, biomedical engineering directors, GPO contracts managers, and precision grinding facility operators. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body documentation, hospital procurement framework records, GPO contract disclosures, and customs trade data for titanium alloy imports. Bottom-up segment sizing and top-down market reconciliation ensured cross-verification of volume and value estimates.
Calibration against historical CAGRs and macroeconomic indicators anchored the projection framework across the analysis window. Segmentation dimensions modeled include material alloy composition, product type tier, end-user facility category, functional application, and regional regulatory cluster. Growth rates derived from procedure volume trends, implant penetration curves, and instrument replacement cycle analysis, with titanium feedstock price volatility and EU MDR implementation pace incorporated as scenario variables.
Macroeconomic conditions sit as an overlay; deviation in aerospace sector titanium demand, healthcare capital expenditure cycles, or sterilization infrastructure investment rates would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timeline adherence and hospital procurement pattern continuity. Cross-checking against orthopedic procedure registry data and implant manufacturer shipment reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Cryosurgical Equipment Market
Surgical Instruments
Germany General Surgical Devices Market
Surgical Instruments
Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Neurosurgical Drills Market
Surgical Instruments
Surgical Lamps Market
Surgical Instruments
US Integrated Operating Rooms Market
Surgical Instruments
Global Hernia Repair Market
Surgical Instruments
United States General Surgical Devices Market
Surgical Instruments
Absorbable Surgical Suture with Needle Market
Surgical Instruments
Cold Disposable Biopsy Forceps Market
Surgical Instruments
Iris Retractors Market
Surgical Instruments
US Surgical Staplers Market
Surgical Instruments
Surgical Drainage Devices Market
Surgical Instruments
Europe Minimally Invasive Surgery Market
Surgical Instruments
Global Laparoscopic Instruments Market
Surgical Instruments
United States Minimally Invasive Surgery Market