
 Diagnostic Electrocardiograph Market | 2026-2036
Diagnostic Electrocardiograph Market Size, Share, and Industry Trends Forecast 2026-2036
Diagnostic Electrocardiograph Market Analysis
India is narrowing the supply gap for affordable diagnostic electrocardiograph systems through domestic manufacturing incentives under the PLI scheme. GE Healthcare leverages its installed base in North American hospitals to sustain recurring revenue from cloud-connected ECG platforms. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. anchors its competitive position through cost-engineered portable ECG units tailored for price-sensitive Asian markets. Nihon Kohden Corporation differentiates via proprietary arrhythmia detection algorithms embedded across its digital device portfolio.
A diagnostic electrocardiograph captures the heart's electrical activity through surface electrodes, typically sampling at 500–1000 Hz with 12-lead configurations to detect ischemia, arrhythmia, and structural abnormalities. The device converts analog myocardial signals into digital waveforms for clinical interpretation, serving as the frontline tool for cardiovascular screening in acute and ambulatory settings. Portable ECG systems are capturing the fastest expansion as point-of-care diagnostics shift toward decentralized settings, while Holter Monitor deployments dominate the recurring revenue pool through extended ambulatory monitoring protocols. Cloud-Based technology segments are restructuring margin profiles by converting capital equipment sales into subscription-based telemetry services.
The FDA governs 510(k) clearances and De Novo classifications for novel ECG algorithms, directly shaping product development timelines and software update architectures for US market entrants. CE marking under the EU MDR and FDA's software-as-medical-device guidance collectively force manufacturers to maintain dual-track quality systems and clinical validation frameworks. Stakeholders must monitor how interoperability mandates from the Office of the National Coordinator for Health IT reshape data exchange requirements across hospital procurement criteria.
Market Dynamics
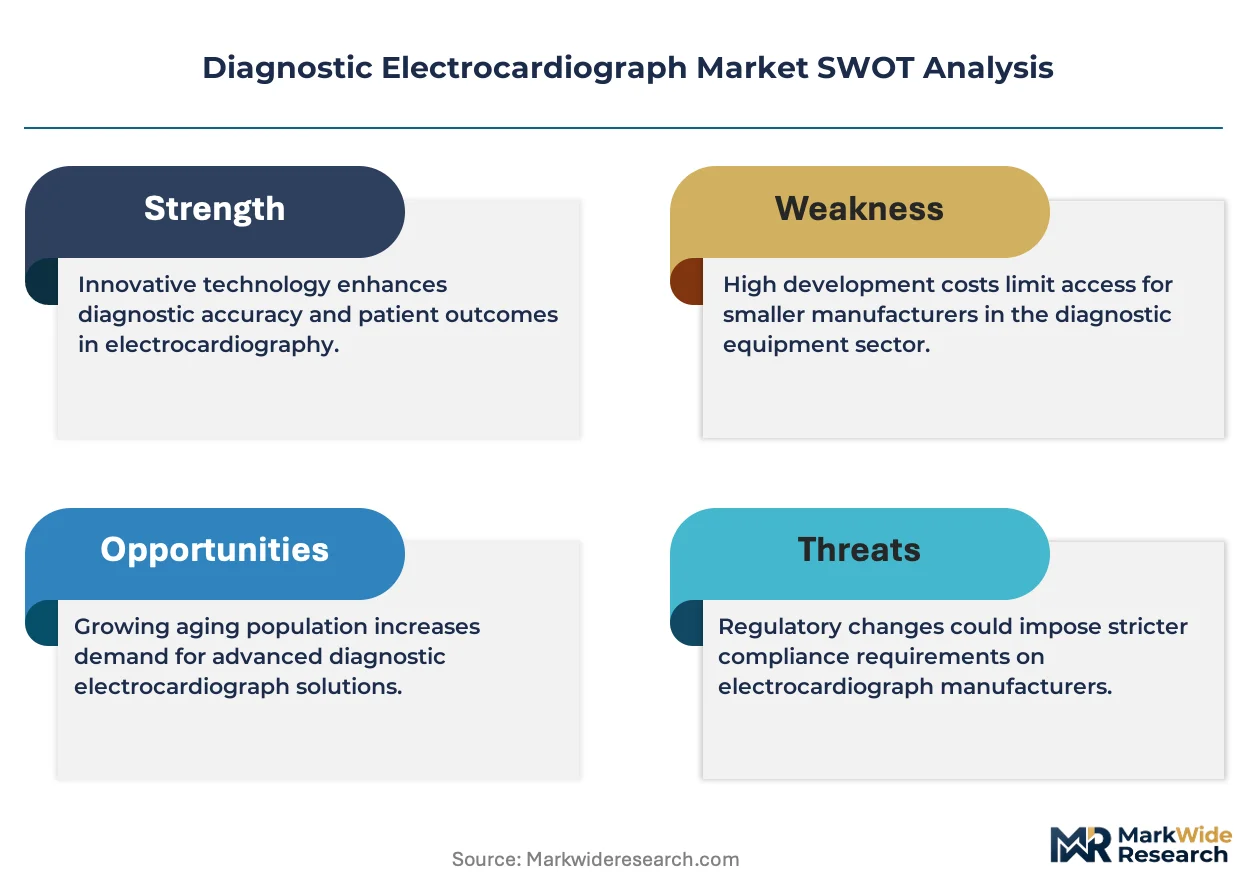
AI-enabled arrhythmia detection algorithms are collapsing the traditional boundary between diagnostic hardware and software-as-medical-device platforms, forcing manufacturers to restructure R&D spend toward cloud-native validation frameworks.
Growth Catalysts
- PLI Manufacturing Incentives:India's production-linked incentive scheme for medical electronics reduces landed costs for domestic ECG assembly, accelerating hospital procurement in tier-2 cities.
- FDA Software-as-Medical-Device Pathways:Streamlined premarket review for AI-enabled ECG algorithms compresses time-to-market for algorithm updates, rewarding continuous learning architectures.
- Portable 12-Lead Miniaturization:Advances in low-power analog front-end circuits enable palm-sized diagnostic-grade acquisition, opening emergency medical services and rural clinics to formal cardiac screening protocols.
Market Restraints
- Electrode Gel Supply Concentration:Silver-silver chloride electrode manufacturing clusters in East Asia create single-source vulnerability for disposable consumables, amplifying cost volatility during logistics disruptions.
- EU MDR Clinical Validation Burden:Expanded post-market surveillance requirements for Class IIa ECG devices extend recertification timelines, freezing product line refreshes for European market entrants.
- Smartwatch Single-Lead Substitution:Consumer-grade PPG-based rhythm monitoring captures low-acuity screening demand, compressing addressable volume for entry-level Holter systems in wellness-oriented demographics.
Strategic Opportunities
- Tele-ICU Integration:Cloud-connected ECG telemetry platforms embed into centralized intensive care monitoring, converting capital equipment sales into recurring per-bed subscription revenue.
- CDSCO Streamlined Registration:India's revised medical device rules create accelerated pathways for domestically manufactured Class B diagnostics, rewarding localized production investments.
- AI-ECG Biomarker Expansion:Deep learning models trained on 12-lead datasets now detect left ventricular dysfunction and hyperkalemia beyond arrhythmia, opening nephrology and heart failure clinic adjacencies.
Industry Challenges
- Interoperability Architecture Fragmentation:Competing data exchange standards between HL7 FHIR, DICOM, and proprietary cloud APIs force manufacturers to maintain multiple integration engineering teams, inflating software maintenance overhead.
- Clinical Validation Talent Scarcity:Shortage of cardiologists with computational training slows ground-truth labeling for FDA 510(k) algorithm submissions, bottlenecking product pipeline velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diagnostic Electrocardiograph Market |
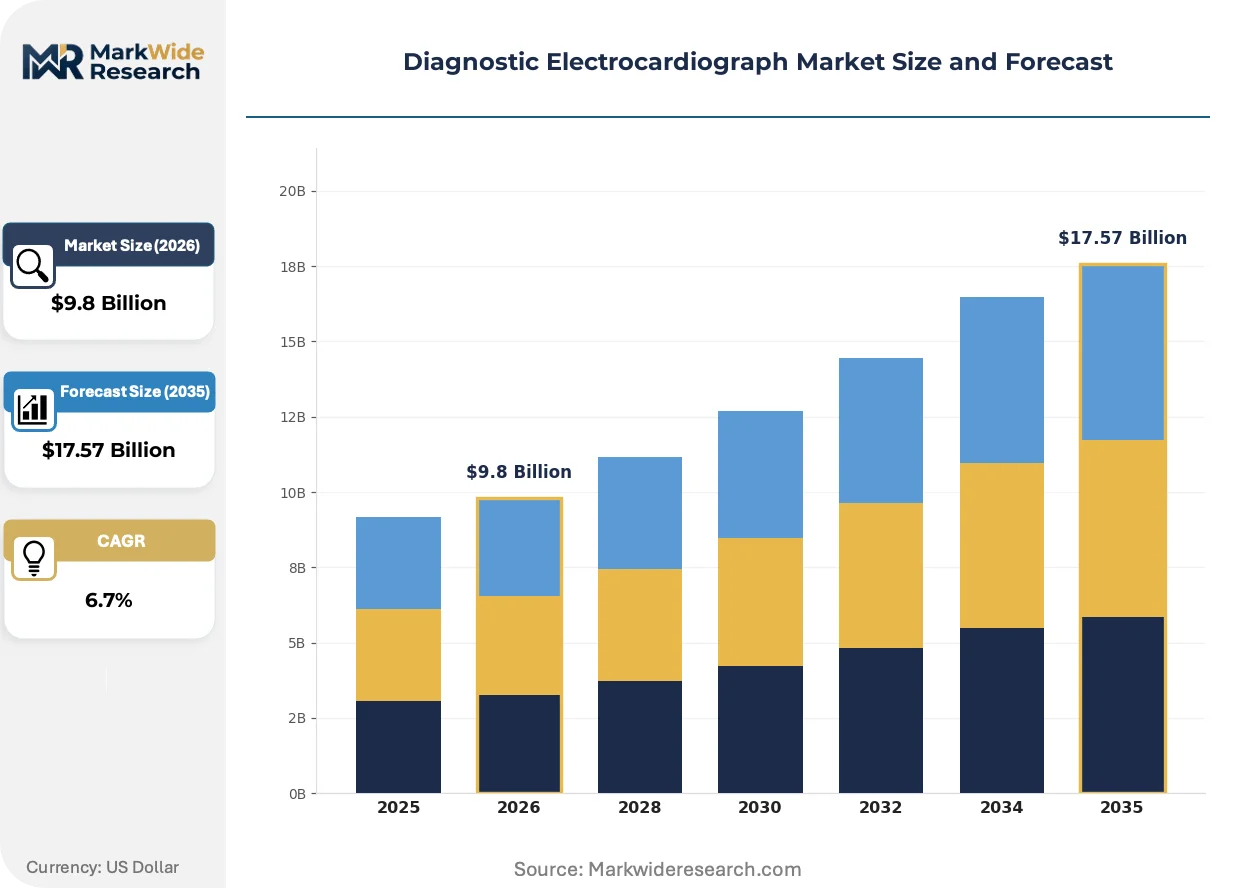
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable ECG, Holter Monitor, Stress ECG, Wireless ECG End User: Cardiology Clinics, Hospitals, Home Care Settings, Emergency Departments Technology: Analog, Digital, Telemedicine, Cloud-Based Delivery Mode: Subscription-Based, One-Time Purchase, Leasing, Bundled Services |
| Companies Covered | Schiller AG, Fukuda Denshi, GE Healthcare, BPL Medical Technologies, Baxter International Inc., Koninklijke Philips N.V., Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Medtronic Plc, Nihon Kohden Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diagnostic Electrocardiograph Market Emerging Trajectories
Edge computing architectures and federated learning frameworks are redistributing where ECG signal processing occurs, compressing latency requirements while amplifying data sovereignty constraints across hospital networks.
Semiconductor integration is collapsing the physical separation between analog acquisition front-ends and digital signal processors, enabling single-chip ECG-on-a-silicon solutions that reduce bill-of-materials costs by half. Emergency departments in the United States are piloting these system-on-chip devices for rapid triage protocols, compressing time-to-diagnosis for acute coronary syndrome presentations from hours to minutes.
EU MDR's Unique Device Identification mandate is forcing ECG manufacturers to embed machine-readable traceability across their entire hardware and software supply chains. The regulation compresses batch recall response times but requires substantial IT infrastructure investment, disproportionately burdening mid-tier device firms serving European hospitals.
Hospital procurement committees are unbundling device acquisition from long-term service contracts, shifting vendor selection criteria toward per-study operational expenditure models. This behavioral pivot favors manufacturers with cloud-native telemetry platforms capable of usage-based billing, most visible in German and French cardiology network tenders where total-cost-of-ownership calculations now dominate capital allocation decisions.
Diagnostic Electrocardiograph Market Segmentation
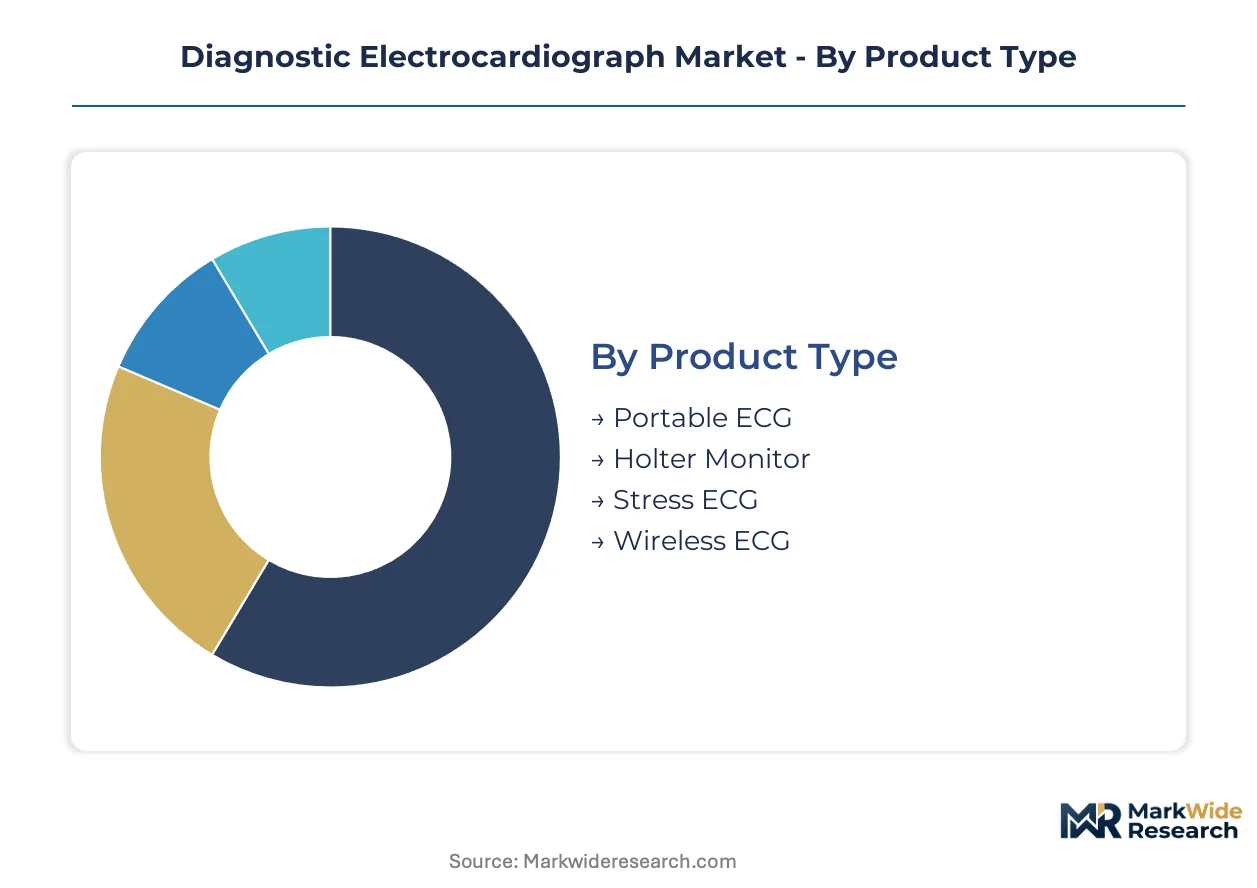
Diagnostic electrocardiograph manufacturers structure product portfolios around four intersecting dimensions: physical form factor, clinical setting, signal processing architecture, and commercial contracting model. These segment boundaries determine R&D allocation, regulatory pathway selection, and pricing strategy.
Product Type:
Mature form factors dominate hospital procurement budgets while emerging miniaturized systems capture ambulatory and emergency expansion.
- Portable ECG:Palm-sized 12-lead acquisition units with integrated thermal printers and lithium-ion power systems. Demand concentrates in Indian tier-2 city clinics where CDSCO's streamlined Class B registration accelerates domestic deployment against import-dependent competitors.
- Holter Monitor:Extended ambulatory recorders sampling at 128–1024 Hz across 24–48 hour protocols with adhesive electrode arrays. German cardiology networks drive recurring revenue concentration as hospital procurement committees unbundle device acquisition from per-study operational expenditure contracts.
- Stress ECG:Treadmill-integrated systems with real-time ST-segment monitoring and automated arrhythmia detection during exercise protocols.
- Wireless ECG:Bluetooth-enabled patch electrodes transmitting to centralized telemetry stations for continuous inpatient monitoring.
Holter Monitor retains volume leadership; Portable ECG holds the steepest expansion curve.
End User:
Customer type segmentation reflects diverging purchasing authority: centralized hospital procurement versus decentralized clinic decision-making versus patient-directed acquisition.
- Cardiology Clinics:Specialist outpatient facilities requiring diagnostic-grade 12-lead interpretation with immediate cardiologist review. Japanese metropolitan clinics anchor premium digital system demand as PMDA's software-as-medical-device guidance rewards cloud-native validation investments.
- Hospitals:Acute care institutions spanning emergency departments, intensive care units, and pre-operative screening wards. India's public-private partnership cardiology network buildouts concentrate procurement volume in government tertiary facilities.
- Home Care Settings:Post-discharge monitoring for heart failure and arrhythmia patients with cellular-connected transmitters.
- Emergency Departments:Rapid triage protocols demanding sub-minute diagnostic output for acute coronary syndrome presentations.
Hospitals command absolute revenue share; Home Care Settings expand most quickly as tele-ICU integration extends monitoring beyond facility walls.
Technology:
Signal processing architecture determines hardware-software margin split and regulatory classification burden.
- Digital:Fully digitized acquisition with 16–24 bit resolution, embedded microprocessors, and USB/Ethernet data export. FDA's evolving 510(k) pathways for AI-enabled algorithms compress time-to-market for deep learning arrhythmia detection models trained on 12-lead datasets.
- Cloud-Based:Edge-acquisition with centralized processing, federated learning model updates, and subscription telemetry services. French hospital procurement tenders increasingly mandate cloud-native platforms capable of usage-based billing under total-cost-of-ownership frameworks.
- Analog:Legacy galvanometer-based systems with thermal stylus output, now confined to lowest-cost emerging market segments.
- Telemedicine:Real-time transmission infrastructure enabling remote cardiologist interpretation for rural and underserved geographies.
Digital systems retain installed base dominance; Cloud-Based architectures gain share fastest as margin profiles shift from capital sales to recurring telemetry subscriptions.
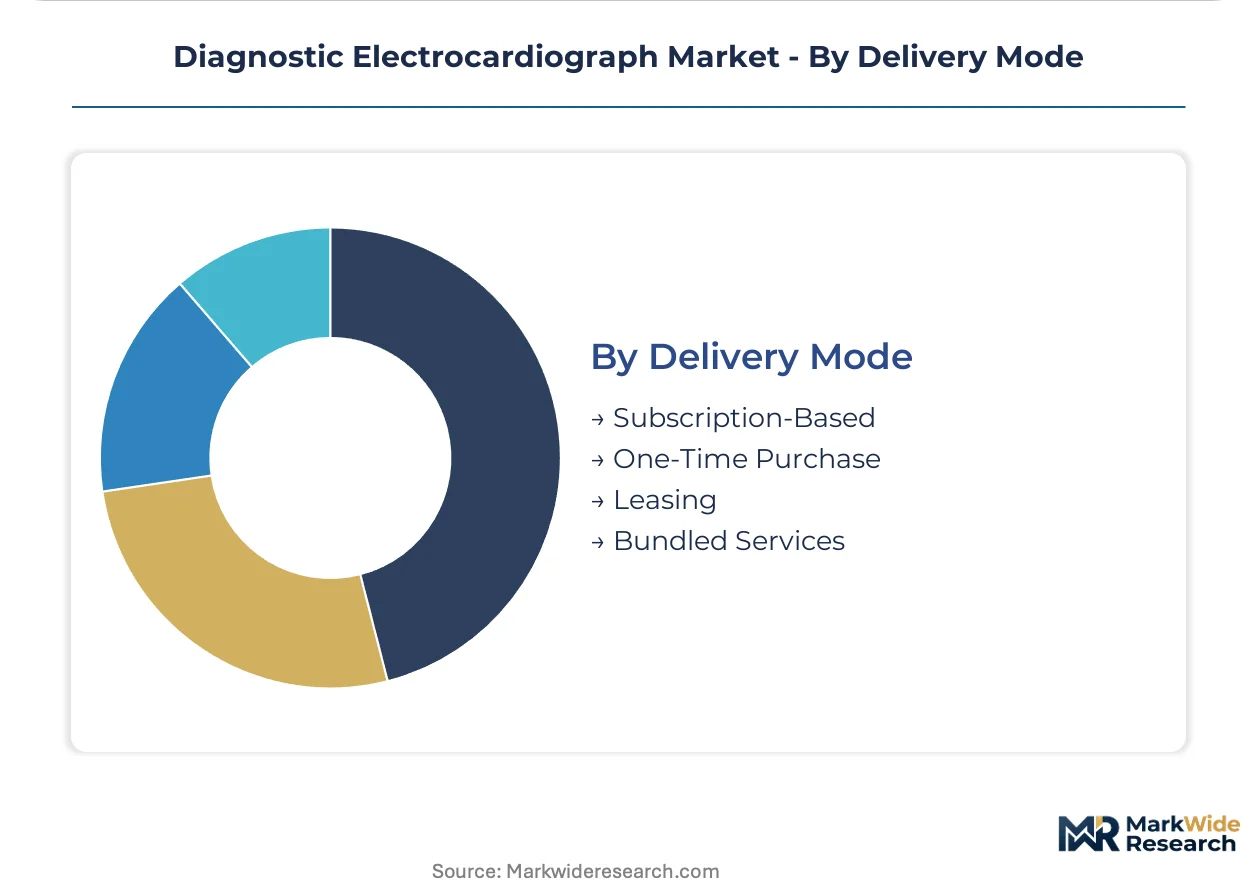
Delivery Mode:
Contracting structure segmentation reflects vendor attempts to capture lifetime value through recurring revenue versus upfront equipment monetization.
- Subscription-Based:Per-bed or per-study recurring fees encompassing hardware, software updates, cloud storage, and clinical support. GE Healthcare leverages North American hospital installed bases to sustain telemetry service revenue against capital budget compression.
- One-Time Purchase:Traditional capital equipment sale with optional extended service contracts, dominant in price-sensitive Asian markets.
- Leasing:Operating lease structures preserving hospital liquidity, prevalent in German and French cardiology network tenders.
- Bundled Services:Device-plus-interpretation contracts where vendors supply remote cardiologist over-read for primary care settings lacking specialist coverage.
One-Time Purchase retains transaction volume leadership; Subscription-Based models claim the steepest expansion trajectory as procurement committees unbundle acquisition from long-term operational expenditure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silver-silver chloride electrode manufacturing concentrates in East Asian industrial clusters, creating single-source vulnerability for disposable consumables while hospital procurement networks in India and Germany restructure contracting models toward operational expenditure frameworks.
United States
Emergency departments pilot system-on-chip ECG devices for acute coronary syndrome triage, compressing diagnostic timelines from hours to minutes. FDA 510(k) pathways for AI-enabled algorithms accelerate software-as-medical-device classifications. Hospital procurement committees in the Northeast Corridor unbundle device acquisition from long-term telemetry service contracts.
Germany
Cardiology network tenders mandate cloud-native platforms capable of usage-based billing under total-cost-of-ownership frameworks. EU MDR's Unique Device Identification mandate forces machine-readable traceability across hardware and software supply chains. Industrial clusters in Baden-Württemberg anchor precision manufacturing for digital acquisition systems.
India
Public-private partnership cardiology network buildouts concentrate procurement volume in government tertiary facilities. CDSCO's streamlined Class B registration accelerates domestic deployment against import-dependent competitors. Tier-2 city clinics in Maharashtra and Gujarat drive portable ECG demand through PLI scheme manufacturing incentives.
Japan
Metropolitan cardiology clinics anchor premium digital system demand as PMDA's software-as-medical-device guidance rewards cloud-native validation investments. PMDA governs premarket approvals for novel arrhythmia detection algorithms. The Kanto region surrounding Tokyo concentrates specialist outpatient facilities requiring diagnostic-grade 12-lead interpretation.
China
Cost-engineered portable ECG units capture price-sensitive Asian market expansion. NMPA regulates medical device registrations under evolving software classification frameworks. Shenzhen anchors electronics manufacturing clusters producing palm-sized diagnostic-grade acquisition systems for emergency medical services deployment.
Diagnostic Electrocardiograph Market Vendor Landscape
Multi-national conglomerates and specialized regional manufacturers split the market along technology-platform versus cost-optimization vectors. Consolidation pressure intensifies as cloud-connected telemetry services convert capital equipment sales into recurring revenue pools. Three archetypes dominate: integrated healthcare technology conglomerates with installed base leverage, Asia-based cost-engineering specialists, and algorithm-focused cardiac monitoring pure-plays. Competitive moves center on strategic partnerships for cloud infrastructure and portfolio diversification into AI-enabled biomarker detection.
Among conglomerate-tier players, GE Healthcare and Koninklijke Philips N.V. occupy positions defined by North American and European hospital installed base leverage. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. exemplifies the Asia-based cost-engineering archetype, while Nihon Kohden Corporation represents algorithm-focused specialization in arrhythmia detection. These three anchors illustrate how geographic origin and corporate structure map to divergent strategic positioning within cloud-native versus hardware-centric value capture models.
| Leading Market Players |
|---|
| Schiller AG |
| Fukuda Denshi |
| GE Healthcare |
| BPL Medical Technologies |
| Baxter International Inc. |
| Koninklijke Philips N.V. |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Medtronic Plc |
| Nihon Kohden Corporation |
| Others |
Supply Flow & Price Mechanics
Shanghai-to-Mumbai container freight corridors transmit East Asian electrode manufacturing cost volatility directly into Indian tier-2 clinic procurement budgets, amplifying price spreads between import-dependent distributors and PLI scheme domestic assemblers while compressing margins for mid-tier portable ECG vendors caught between premium cloud-native platforms and economy analog alternatives.
Pricing Analysis
FDA 510(k) software-as-medical-device pathways dictate the pricing tier structure across US market entrants, separating cloud-connected telemetry subscriptions from capital equipment sales. Three-tier pricing structure across premium AI-enabled, standard digital, and economy analog levels reflects certification burden and after-sales service bundling. Cost compression in entry-level portable units is intensifying because consumer smartwatch substitution erodes addressable volume for basic Holter systems. Price sensitivity concentrates among Indian government tertiary facilities, while Japanese metropolitan cardiology clinics show lowest sensitivity due to PMDA-validated algorithm premiums.
Supply Chain Analysis
Extended payment terms from East Asian silver-silver chloride electrode suppliers now stretch to 90-120 days, straining working capital for mid-tier ECG assemblers. Manufacturing concentrates in China, South Korea, and Japan for analog front-end semiconductors and disposable electrode consumables. Raw material dependencies center on silver chloride pastes, lithium-ion cells, and medical-grade thermoplastics. Single-source vulnerability in East Asian electrode gel clusters amplifies logistics disruption risk. Distribution runs through hospital procurement committees unbundling device acquisition from long-term telemetry service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diagnostic electrocardiograph market is recovering from pandemic-depressed capital equipment cycles as hospital procurement committees restart deferred cardiology infrastructure buildouts and tele-ICU integration accelerates recurring revenue conversion.
For Market Incumbents: Harden cloud-native telemetry architectures against algorithm-focused cardiac monitoring pure-plays by embedding federated learning model updates and per-bed subscription billing. Consolidate backward integration into silver-silver chloride electrode supply through captive manufacturing partnerships in India PLI zones. Lock hospital procurement committees into multi-year operational expenditure contracts before CDSCO streamlined registration floods tier-2 cities with cost-engineered domestic competitors.
For New Entrants and Emerging Players: Build out AI-ECG biomarker detection capabilities targeting nephrology and heart failure clinic adjacencies beyond arrhythmia, where incumbent algorithm portfolios remain underdeveloped. Penetrate Indian tier-2 city public-private partnership cardiology networks through CDSCO-accelerated Class B registration and localized assembly under PLI incentives. Pursue bundled device-plus-interpretation contracts for primary care settings lacking specialist cardiologist coverage.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified healthcare conglomerates seeking to divest non-core cardiac monitoring hardware units amid cloud-native platform consolidation. Five-to-ten year viability favors algorithm-specialist pure-plays with FDA-cleared deep learning models and hospital installed base telemetry conversion. Watch EU MDR Unique Device Identification compliance costs as inflection indicator for mid-tier European market entrant distress.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Software-as-Medical-Device Submission | Accelerates algorithm update deployment and recurring revenue conversion for cloud-connected ECG platforms. |
| CE Marking Pathway under EU MDR | Enables European hospital procurement access while mandating machine-readable traceability infrastructure investment. |
| Hospital System Partnership | Locks in per-bed telemetry subscriptions through tele-ICU integration and usage-based billing frameworks. |
| Software Companion Development | Expands addressable clinical settings beyond cardiology into nephrology and heart failure monitoring adjacencies. |
| Reimbursement Strategy | Secures favorable CMS and private payer codes for AI-enabled ECG biomarker detection protocols. |
Methodological Framework
Desk research of FDA 510(k) clearance databases, CDSCO medical device registration filings, EU MDR notified body certificates, and hospital procurement tender documents preceded structured interviews with biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and cardiology clinic operations directors. Primary fieldwork across US Northeast Corridor emergency departments, German Baden-Württemberg manufacturing clusters, and Indian Maharashtra tier-2 facilities combined with secondary validation from trade customs data and semiconductor import records. Bottom-up unit shipment estimates triangulated against top-down healthcare infrastructure spending allocations.
Assumptions held fixed include prevailing FDA software-as-medical-device guidance timelines, EU MDR post-market surveillance requirements, and PLI scheme manufacturing incentive continuity across the analysis window. Segmentation modeling incorporated product form factor, signal processing architecture, end-user facility type, and commercial contracting structure dimensions. CAGRs derived from curve-fitting historical capital equipment replacement cycles against cloud-native telemetry adoption trajectories, with specific inputs from AI algorithm regulatory clearance velocity and electrode consumables supply concentration metrics.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Asia-based cost-engineering specialists or abrupt FDA guidance shifts would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Visual Field Testing Equipment Market
Diagnostic Instruments
Global Point of Care Ultrasound Market
Diagnostic Instruments
Immunochemistry Analyzer Market
Diagnostic Instruments
Polygraph Instrument (Lie Detector) Market
Diagnostic Instruments
Nasometry Devices Market
Diagnostic Instruments
Genetic Analyzers Market
Diagnostic Instruments
Global Chemiluminescence Immunoassay (CLIA) Analyzers Market
Diagnostic Instruments
Global Blood Coagulation Analyzer Market
Diagnostic Instruments
Blood Flow Measurement Devices Market
Diagnostic Instruments
Point-of-Care Diagnostic Analyzer Accuracy and Interference Test Equipment Market
Diagnostic Instruments
Auto Chemistry Analyzers Market
Diagnostic Instruments
Global Cell Surface Markers Detection Market
Diagnostic Instruments
Tympanometers Market
Diagnostic Instruments
Pachymeter Market
Diagnostic Instruments
Eye Testing Equipment Market
Diagnostic Instruments
Immunoassay Instruments Market