
 Continuous Ambulatory Peritoneal Dialysis Bags Market | 2026-2036
Continuous Ambulatory Peritoneal Dialysis Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Continuous Ambulatory Peritoneal Dialysis Bags Market Outlook
Asset-light leasing arrangements for dialysis supply chains is reconfiguring competitive entry barriers for mid-tier manufacturers. Baxter International Inc. leverages its vertically integrated polymer compounding capacity to control laminate quality from resin to finished bag. Fresenius Medical Care AG & Co. KGaA anchors its position through captive nephrology center networks across Western Europe and North America. Terumo Corporation specializes in precision extrusion for Y-type bag geometries that reduce connection failure rates during home-based exchanges.
Continuous ambulatory peritoneal dialysis bags are sterile, multi-chamber flexible containers fabricated from polyvinyl chloride-free coextruded films or ethylene vinyl acetate laminates, designed to store and deliver dialysis solution into the peritoneal cavity via an indwelling catheter over dwell periods of four to eight hours. Dual chamber bags dominate current production volumes because their separated glucose and buffer compartments extend solution stability prior to mixing. Glucose-based formulations still occupy the largest share of dialysis fluid demand, though icodextrin-based alternatives are gaining traction among diabetic end-stage renal disease patients seeking reduced glucose exposure. Home care patients represent the fastest-growing end user category as payers and nephrology centers push ambulatory treatment models that reduce inpatient dialysis infrastructure costs.
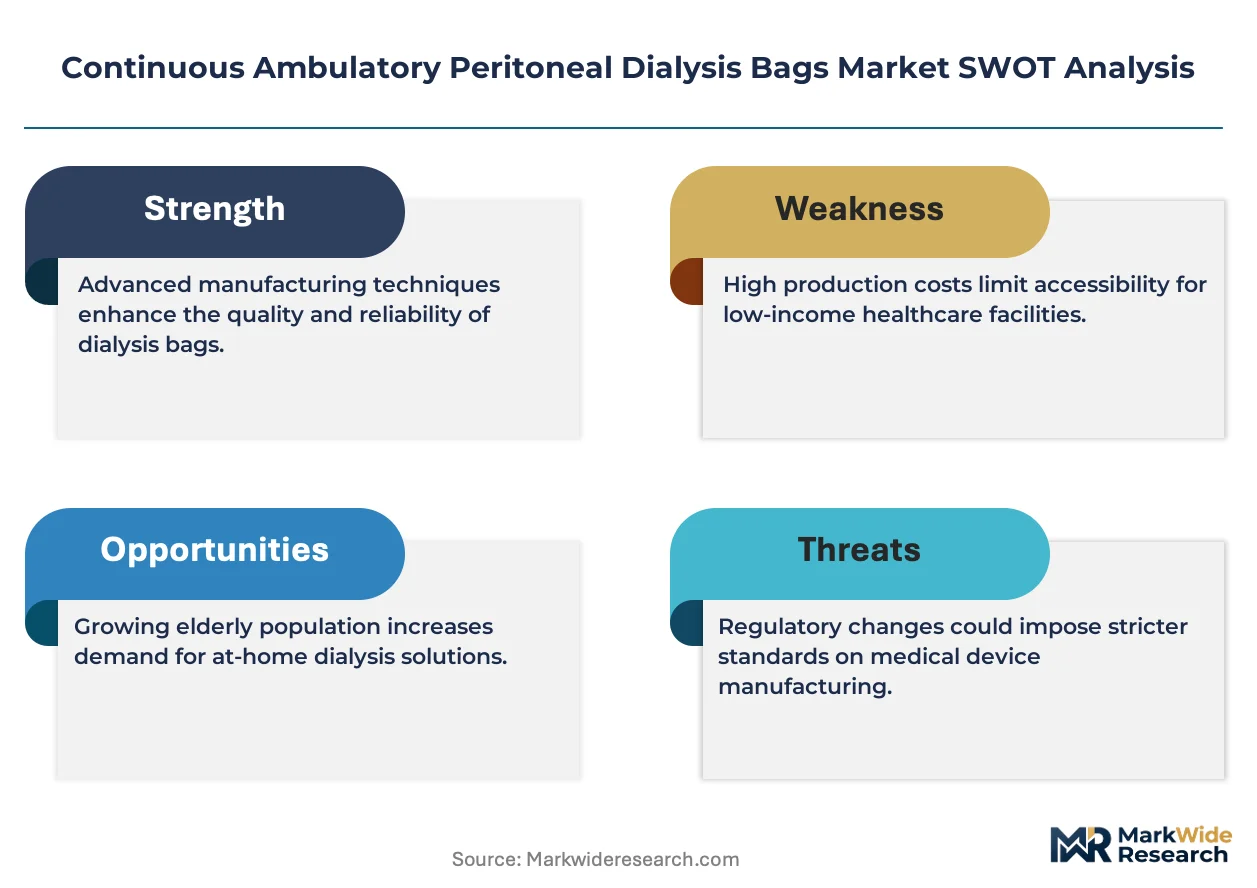
FDA enforces biocompatibility and sterility standards under 21 CFR Part 820 for medical device manufacturing, while the EU Medical Device Regulation requires CE marking with notified body oversight for peritoneal dialysis solution delivery systems. Japan's PMDA maintains distinct JIS T 3232 material specifications that influence laminate selection for bags distributed in that market. Stakeholders must monitor evolving reimbursement coding for home dialysis supplies in the United States and Germany, as these classifications directly determine patient out-of-pocket costs and program enrollment rates.
Market Dynamics
The transition from hospital-based dialysis to home care models is restructuring procurement relationships and forcing manufacturers to redesign bag geometries for patient self-administration rather than clinical handling.
Growth Catalysts
- Home care reimbursement expansion:Payers in the United States and Germany now cover peritoneal dialysis supplies under outpatient durable medical equipment codes, accelerating patient enrollment in domestic treatment programs.
- EMA biocompatibility mandates:The EU Medical Device Regulation's tightened material safety requirements are phasing out legacy PVC formulations and driving adoption of ethylene vinyl acetate laminates across European supply chains.
- Icodextrin formulation uptake:Diabetic end-stage renal disease patients are switching to glucose-sparing dialysis solutions, expanding addressable demand for dual-chamber bags compatible with these alternative chemistries.
Market Restraints
- Resin supply concentration:Medical-grade ethylene vinyl acetate copolymers concentrate among three specialty chemical suppliers, creating input cost volatility when polymer feedstock markets tighten.
- Japan's JIS T 3232 compliance burden:Distinct material specifications for the Japanese market force manufacturers to maintain separate laminate formulations, fragmenting production scale economies.
- Catheter-related peritonitis risk:Connection failure during home exchanges limits patient candidacy for ambulatory models, capping the addressable population despite clinical preference for peritoneal modalities.
Strategic Opportunities
- Rural India penetration:Dialysis infrastructure scarcity in tier-2 and tier-3 cities creates white space for low-cost bag systems paired with telemedicine-supported home training protocols.
- Biodegradable laminate development:Convergence of medical device sterilization standards with circular economy mandates opens pathways for compostable multi-layer films that reduce clinical waste disposal costs.
- Direct-to-patient distribution:E-commerce channels for chronic care supplies are bypassing traditional hospital purchasing committees, enabling margin capture by manufacturers willing to manage last-mile cold chain logistics.
Industry Challenges
- Sterile manufacturing workforce scarcity:Cleanroom technicians with medical device laminating expertise are concentrated in established manufacturing clusters, constraining capacity expansion into emerging markets.
- Multi-jurisdiction certification timelines:Simultaneous FDA 510(k) clearance, CE marking under MDR, and PMDA shonin approval create sequential rather than parallel market entry, delaying revenue recognition across regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuous Ambulatory Peritoneal Dialysis Bags Market |
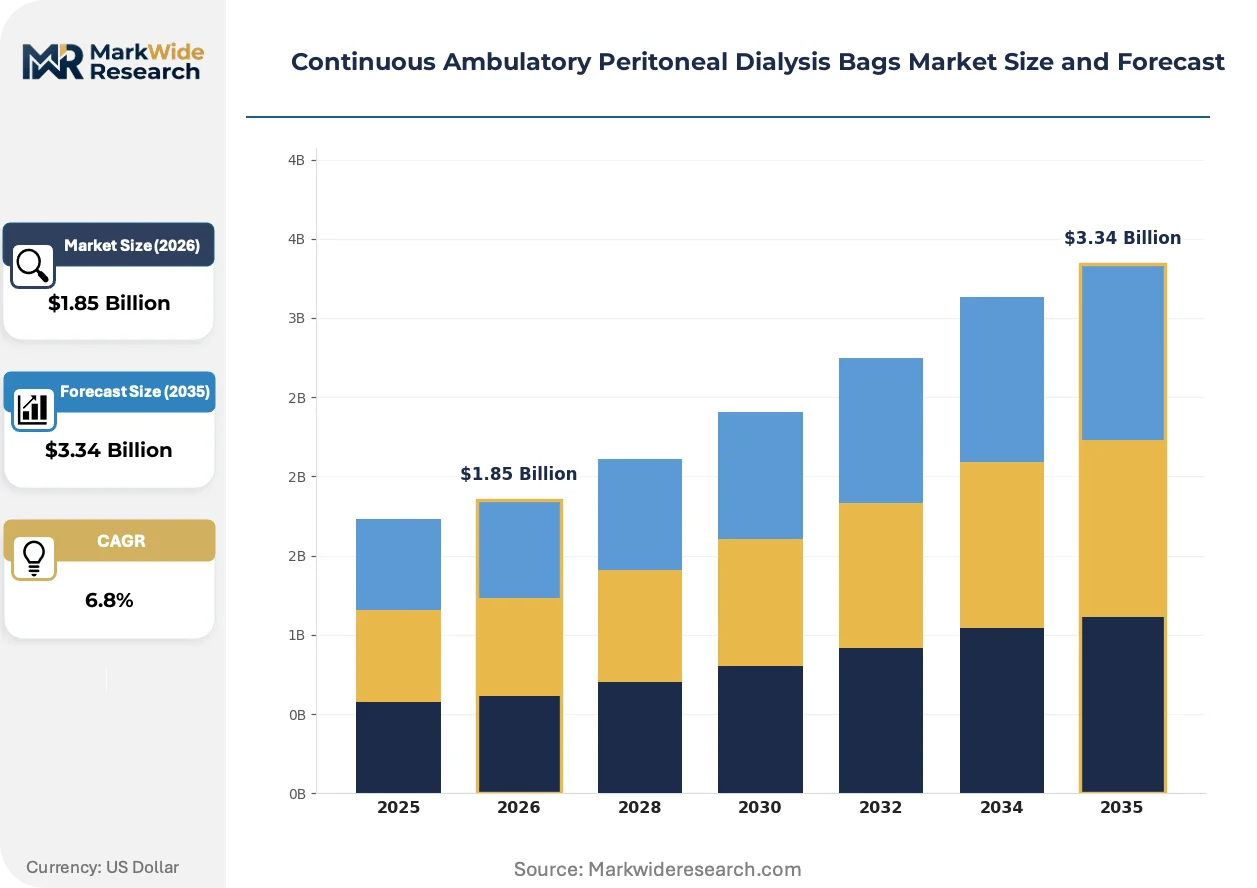
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Solution Bags, Dual Chamber Bags, Triple Chamber Bags, Y-Type Bags Dialysis Fluid Formulation: Glucose-based, Icodextrin-based, Amino Acid-based, Bicarbonate-buffered End User: Nephrology Centers, Home Care Patients, Specialty Clinics, Rehabilitation Facilities Packaging Type: Plastic Bags, Composite Bags, Multi-layer Laminates, Sterile Pouches |
| Companies Covered | Baxter International Inc., Fresenius Medical Care AG & Co. KGaA, Terumo Corporation, Medtronic plc, Utah Medical Products, Inc., Kawasumi Laboratories, Colorplast, Mitra Industries Pvt. Ltd., Maco Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuous Ambulatory Peritoneal Dialysis Bags Market Strategic Shifts
Material science advances and regulatory harmonization pressures are compressing product development cycles while expanding the performance envelope for ambulatory dialysis systems.
Coextruded barrier films with oxygen-scavenging interlayers are collapsing the degradation risk that previously limited glucose solution shelf life. Home care patients in Germany and Japan are adopting these next-generation bags at rates exceeding hospital procurement channels. The technology is collapsing inventory carrying costs for distributors while enabling just-in-time replenishment models that reduce working capital requirements across supply chains.
The EU Medical Device Regulation's post-market surveillance requirements are mandating real-world performance tracking for peritoneal dialysis delivery systems. Manufacturers must now submit periodic safety update reports and maintain vigilance databases that capture adverse events across all member states. Small and mid-tier suppliers without established regulatory affairs infrastructure are outsourcing compliance to specialized consulting firms, altering competitive economics.
Hospital purchasing cooperatives are consolidating procurement for dialysis supplies across multi-site health systems, displacing decentralized ward-level ordering. Integrated delivery networks in the United States are negotiating multi-year sole-source agreements that bundle bags with solution concentrates and connection sets. This concentration is most visible in Medicare Advantage plan territories where capitated reimbursement incentivizes supply standardization to manage total cost of care.
Continuous Ambulatory Peritoneal Dialysis Bags Market Segmentation
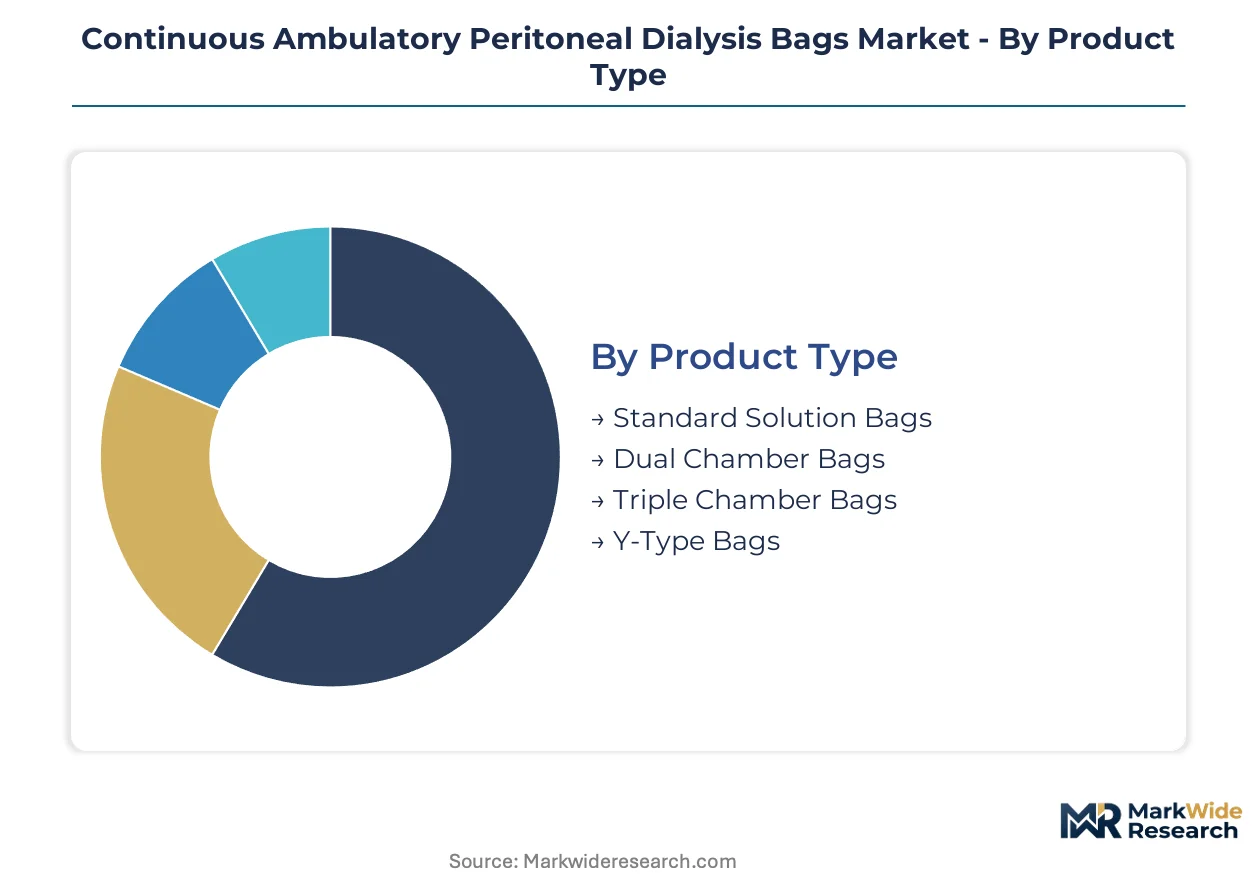
Segmentation in the Continuous Ambulatory Peritoneal Dialysis Bags Market reveals how bag geometry, solution chemistry, and care setting interact to determine procurement patterns. Manufacturers configure production lines around specific segment combinations to capture reimbursement-aligned demand clusters.
Product Type:
After-sales service intensity varies sharply by bag complexity, with multi-chamber systems requiring patient training support and connection failure troubleshooting that single-chamber alternatives do not demand.
- Standard Solution Bags:Single-compartment containers hold pre-mixed dialysis solution for immediate infusion without mixing steps. Demand concentrates in cost-sensitive nephrology centers in India and Southeast Asia where simplified workflows offset clinical flexibility limitations.
- Dual Chamber Bags:Separated glucose and buffer compartments extend chemical stability until point-of-use mixing. Home care patients in Germany and Japan adopt these systems fastest as reimbursement frameworks reward reduced peritonitis rates from fresher solution chemistry.
- Triple Chamber Bags:Additional electrolyte separation enables ultra-customized formulation blending at the bedside. These configurations serve high-acuity patients with complex metabolic requirements in academic medical centers.
- Y-Type Bags:Branching geometry reduces connection steps during self-administered exchanges. Precision extrusion requirements limit supplier base for this segment.
Dual Chamber Bags hold the largest share; momentum sits with Y-Type Bags.
Dialysis Fluid Formulation:
Formulation chemistry dictates laminate compatibility requirements and sterilization protocols that segment manufacturing cost structures.
- Glucose-based:Dextrose monohydrate solutions remain the clinical default for osmotic ultrafiltration. Demand concentrates in established peritoneal dialysis programs across the United States where physician familiarity and formulary inertia sustain volume leadership despite metabolic drawbacks.
- Icodextrin-based:Glucose polymer solutions enable sustained ultrafiltration during long dwells without hyperglycemia exposure. Diabetic end-stage renal disease patients in Western Europe are switching to these alternatives fastest as EMA safety data accumulates.
- Amino Acid-based:Nutritionally supplemented formulations address protein malnutrition in anuric patients. Niche positioning limits production scale.
- Bicarbonate-buffered:Neutral pH chemistry reduces infusion pain and peritoneal membrane irritation. Adoption tracks biocompatibility-conscious prescribing in Japanese nephrology centers.
Glucose-based formulations dominate current volumes; Icodextrin-based alternatives are climbing the fastest.
End User:
Procurement authority and technical support requirements diverge across care settings, reshaping distribution channel economics.
- Nephrology Centers:Institutional purchasers negotiate multi-year supply agreements bundling bags with solutions and connection sets. These facilities in the United States concentrate procurement through integrated delivery networks seeking capitated cost control.
- Home Care Patients:Self-administered exchanges require patient training investment and 24-hour technical hotline support from manufacturers. Payers in Germany now cover home dialysis supplies under outpatient durable medical equipment codes, accelerating enrollment.
- Specialty Clinics:Focused renal practices with limited inpatient capacity favor standardized bag configurations to minimize inventory complexity.
- Rehabilitation Facilities:Transitional care settings use peritoneal dialysis as a bridge modality, creating episodic demand spikes.
Nephrology Centers retain volume leadership; Home Care Patients are gaining share fastest.
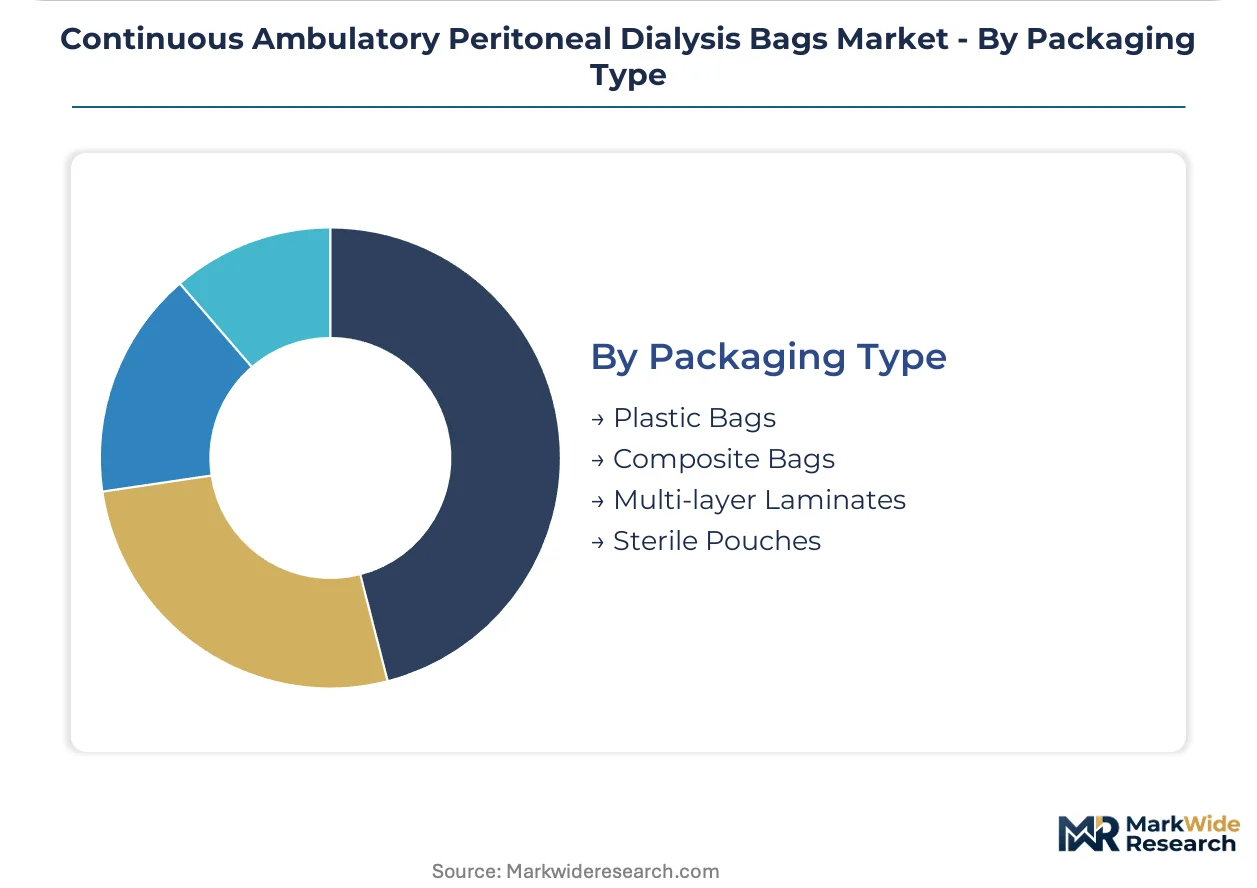
Packaging Type:
Material selection determines sterilization compatibility, shelf life, and waste disposal cost profiles across regulatory jurisdictions.
- Plastic Bags:PVC and PVC-free polyolefin constructions serve cost-optimized markets with shorter distribution chains. These dominate in India where price sensitivity outweighs premium material preferences.
- Composite Bags:Hybrid constructions balance barrier performance with cost. European supply chains are phasing these out under MDR biocompatibility mandates.
- Multi-layer Laminates:Coextruded ethylene vinyl acetate films with oxygen-scavenging interlayers extend solution stability. Baxter International's captive polymer compounding controls quality from resin to finished bag for this premium segment.
- Sterile Pouches:Secondary packaging configurations for aseptic presentation in operating theater environments. Limited to catheter implantation kits rather than routine exchanges.
Multi-layer Laminates command premium positioning; Plastic Bags maintain volume dominance in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement policy redesign is redirecting patient volumes toward home-based peritoneal dialysis across major markets. Government payers in Germany and the United States now classify ambulatory dialysis supplies under durable medical equipment codes, reducing out-of-pocket costs and accelerating enrollment. Material safety mandates from EMA and FDA are simultaneously reshaping manufacturing footprints as manufacturers phase out legacy formulations.
United States
Medicare Advantage capitation models incentivize integrated delivery networks to standardize on peritoneal modalities. FDA 21 CFR Part 820 quality system requirements govern sterile device manufacturing. Manufacturing clusters concentrate in Illinois and California where medical device laminating expertise supports multi-layer film production for premium bag segments.
Germany
Outpatient reimbursement codes now cover home dialysis supplies, accelerating patient migration from hospital wards. EU Medical Device Regulation CE marking mandates biocompatibility testing for ethylene vinyl acetate laminates. Industrial concentration centers on Baden-Württemberg and North Rhine-Westphalia where polymer compounding facilities serve European supply chains.
Japan
Aging demographics sustain peritoneal dialysis program enrollment as nephrology capacity constraints limit hemodialysis expansion. PMDA JIS T 3232 material specifications require distinct laminate formulations for domestic distribution. Manufacturing activity clusters in the Kanto region around Tokyo, where precision extrusion capabilities support Y-type bag geometries.
India
Dialysis infrastructure scarcity in tier-2 and tier-3 cities creates demand for low-cost home treatment systems. CDSCO medical device rules govern sterile container manufacturing quality standards. Industrial activity concentrates in Maharashtra and Gujarat where contract manufacturers assemble plastic bag systems for price-sensitive procurement channels.
United Kingdom
NHS England's renal transformation program promotes ambulatory dialysis to reduce hospital-based treatment costs. MHRA conformity assessment procedures align with EU MDR for market access continuity. Research and development activity clusters in the Southeast around Cambridge and Oxford medical technology corridors.
Continuous Ambulatory Peritoneal Dialysis Bags Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidation characterizes premium segments where captive supply chains and regulatory infrastructure create defensive moats, while fragmentation persists in emerging markets where price-sensitive procurement favors interchangeable suppliers. Three archetypes dominate: vertically integrated polymer compounders, nephrology service network operators, and precision extrusion specialists. Dominant competitive moves include backward integration into resin production and geographic expansion through regulatory certification stacking.
Among vertically integrated manufacturers, Baxter International Inc. exemplifies the polymer-compounding archetype through captive control from resin to finished device. Fresenius Medical Care AG & Co. KGaA represents the service-network model, anchoring competitive position through clinical infrastructure ownership. Terumo Corporation occupies the precision-specialist tier, with Japanese manufacturing heritage informing extrusion capabilities for complex bag geometries.
| Leading Market Players |
|---|
| Baxter International Inc. |
| Fresenius Medical Care AG & Co. KGaA |
| Terumo Corporation |
| Medtronic plc |
| Utah Medical Products, Inc. |
| Kawasumi Laboratories |
| Colorplast |
| Mitra Industries Pvt. Ltd. |
| Maco Pharma |
| Others |
Value Chain & Pricing Dynamics
Medical-grade ethylene vinyl acetate resin production concentrates among three specialty chemical suppliers in Germany and the United States, anchoring margin capture in the upstream polymer compounding tier rather than finished bag assembly. This concentration forces mid-tier manufacturers into price-taker positions on laminate inputs while integrated compounders like Baxter International retain cost visibility from resin through sterilization.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers. FDA-grade and CE-marked multi-layer laminates command substantial premiums over CDSCO-registered plastic bag alternatives in India. Price differentiation rests on biocompatibility testing documentation and sterilization validation depth. Cost compression in standard single-chamber segments is intensifying as contract manufacturers in Maharashtra and Gujarat expand capacity. Home care patients in Germany and Japan exhibit lowest price sensitivity due to comprehensive reimbursement coverage, while nephrology centers in Southeast Asia prioritize procurement cost above material specifications.
Supply Chain Analysis
Tariff exposure between the United States and China disrupts medical device packaging film flows, forcing manufacturers to qualify alternative Asian suppliers. Raw material sourcing draws from ethylene vinyl acetate copolymers in Germany, polyolefin films in the United States, and sterilization-grade adhesives from Japan. Single-source vulnerability concentrates in oxygen-scavenging interlayer technology held by two Japanese specialty chemical firms. Distribution runs through hospital purchasing cooperatives in the United States, integrated delivery networks in Germany, and direct-to-patient e-commerce channels expanding fastest in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Home care reimbursement expansion across Germany and the United States signals early-cycle penetration growth for ambulatory dialysis modalities. This tailwind supports volume acceleration as payers shift financial risk toward outpatient durable medical equipment frameworks.
For Market Incumbents: Harden regulatory certification infrastructure against EMA post-market surveillance mandates and FDA 510(k) pathway tightening. Captive polymer compounding capacity in Illinois and Baden-Württemberg defends margin position against resin cost volatility. Priority investment in sterile manufacturing workforce development addresses technician scarcity constraining capacity expansion into emerging markets.
For New Entrants and Emerging Players: Rural India penetration offers the most accessible white-space opportunity, where dialysis infrastructure scarcity in tier-2 and tier-3 cities outpaces hospital construction timelines. Low-cost plastic bag systems paired with telemedicine-supported home training protocols bypass established procurement relationships. Direct-to-patient e-commerce distribution captures margin otherwise surrendered to hospital purchasing committees.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with precision extrusion specialists serving Japanese Y-type bag geometries and European multi-layer laminate producers. Five-to-ten year viability hinges on biodegradable film development convergence with circular economy mandates. Monitor EMA periodic safety update report submission rates as inflection indicator for regulatory compliance burden sustainability among mid-tier suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Laminate Development | Compostable multi-layer films reduce clinical waste disposal costs under EU circular economy mandates. |
| Direct-to-Patient Distribution | E-commerce channels bypass hospital purchasing committees and capture last-mile cold chain margin. |
| CE Marking Pathway Investment | EU MDR biocompatibility requirements phase out legacy PVC formulations across European supply chains. |
| Hospital System Partnership | Integrated delivery networks bundle bags with solutions under Medicare Advantage capitation models. |
| Reimbursement Strategy | Outpatient durable medical equipment coding in Germany accelerates patient enrollment in home programs. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearances, EMA CE marking databases, and CMS Medicare reimbursement coding. Interviews with nephrologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers informed demand-side validation. Trade data from customs authorities, SEC 10-K filings from medical device manufacturers, and PMDA shonin approval records provided supply-side triangulation. Bottom-up patient volume modeling and top-down reimbursement expenditure analysis converged on segment sizing.
Forecast inputs include bag geometry adoption curves, dialysis fluid formulation switching rates, and home care penetration trajectories across the projection horizon. Segmentation dimensions span product type, solution chemistry, end-user setting, and packaging material tier. CAGRs derive from patient enrollment elasticity to reimbursement policy changes and manufacturing capacity expansion schedules. Sterile manufacturing workforce growth constraints and multi-jurisdiction certification timeline assumptions shape supply-side boundaries.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration into resin production by mid-tier manufacturers would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Port Access Needles Market
Medical Supplies
Disposable Specimen Container Market
Medical Supplies
MENA Syringes and Cannula Market
Medical Supplies
Suture Wire Market
Medical Supplies
Middle East and Africa Surgical Sutures Market
Medical Supplies
North America Intravenous Solutions Market
Medical Supplies
Disposable Masks Market
Medical Supplies
Thermal Printable Wristband Market
Medical Supplies
Global Dried Blood Spot Collection Cards Market
Medical Supplies
Plasma Collection Containers Market
Medical Supplies
Emesis Bag Market
Medical Supplies
Blood Bag Tube Sealer Market
Medical Supplies
Enteral Syringes Market
Medical Supplies
Disposable Medical Gowns Market
Medical Supplies
Smart Face Masks Market
Medical Supplies
Sterile Container Market