
 Intraoperative Aberrometry Market | 2026-2036
Intraoperative Aberrometry Market Size, Share, and Industry Trends Forecast 2026-2036
Intraoperative Aberrometry Market Foresight
Hospital procurement consortia is reconfiguring how intraoperative aberrometry systems reach end users across ambulatory networks. Carl Zeiss Meditec leverages its captive optics manufacturing base in Oberkochen to sustain premium positioning in wavefront-guided cataract workflows. Johnson & Johnson Vision competes through bundled contracts that anchor disposable consumables revenue to system placements. Alcon differentiates by dominating the toric IOL alignment segment where aberrometry validates astigmatic correction in real time.
Intraoperative aberrometry measures refractive power of the eye during live surgery using wavefront sensors operating at infrared wavelengths, typically producing readings within seconds to guide lens selection or laser ablation adjustments. The technology serves primarily to reduce refractive surprise following cataract extraction by verifying aphakic or pseudophakic measurements before wound closure. Aberrometer systems command the largest revenue share due to capital intensity and multi-year service contracts, while software solutions represent the fastest-expanding margin pool as vendors unbundle analytics from hardware. Wavefront aberrometry leads technology adoption in premium cataract channels, whereas intraoperative wavefront sensing captures specialized demand in refractive surgery suites seeking intraoperative confirmation.
The FDA's 510(k) pathway and the EU Medical Device Regulation frame compliance burdens for manufacturers seeking dual-market access, with notified bodies extending review timelines for novel optical algorithms. ISO 10993 biocompatibility standards and IEC 60601-1 electrical safety requirements govern subsystem qualification for devices contacting ocular surfaces or operating in sterile fields. Stakeholders must monitor how CMS reimbursement decisions for computer-assisted cataract surgery reshape hospital capital allocation toward validated aberrometry platforms.
Market Dynamics
Wavefront-guided surgical platforms are consolidating purchasing power across ambulatory surgical networks, forcing device vendors to restructure pricing around multi-year service bundles rather than standalone capital sales.
Growth Catalysts
- Ambulatory surgical center expansion:Freestanding surgical facilities in the United States are outfitting refractive suites with real-time lens verification systems to capture premium cataract volume outside hospital settings.
- EU Medical Device Regulation harmonization:MDR compliance deadlines are accelerating replacement cycles for legacy diagnostic platforms across German and French ophthalmology clinics.
- Toric IOL alignment protocols:Astigmatism-correcting lens workflows now mandate intraoperative confirmation, embedding aberrometry into standard-of-care pathways for premium channel procedures.
Market Restraints
- Capital intensity barriers:Infrared wavefront sensors and precision optics manufacturing concentrate in Oberkochen, creating supply bottleneck vulnerability for non-captive vendors.
- 510(k) pathway friction:FDA premarket notification timelines for novel optical algorithms extend 12-18 months, compressing competitive response windows for algorithm-dependent features.
- Manual keratometry persistence:Low-cost autokeratometers continue serving price-sensitive cataract channels in India and Brazil, limiting aberrometry penetration outside premium tiers.
Strategic Opportunities
- Refractive surgery suite integration:Laser vision correction centers in South Korea are adopting intraoperative wavefront sensing for real-time ablation confirmation, opening adjacent application demand.
- Software unbundling:Analytics platforms are separating from hardware systems, enabling recurring revenue streams through cloud-based surgical planning subscriptions.
- CMS reimbursement tailwinds:Computer-assisted cataract surgery coding decisions in the United States are reshaping hospital capital allocation toward validated measurement platforms.
Industry Challenges
- Optical engineering talent scarcity:Wavefront algorithm development requires specialized computational optics expertise concentrated at select German and Swiss research institutes.
- Legacy EMR integration complexity:Surgical aberrometers must interface with hospital information systems lacking standardized ophthalmology data protocols, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intraoperative Aberrometry Market |
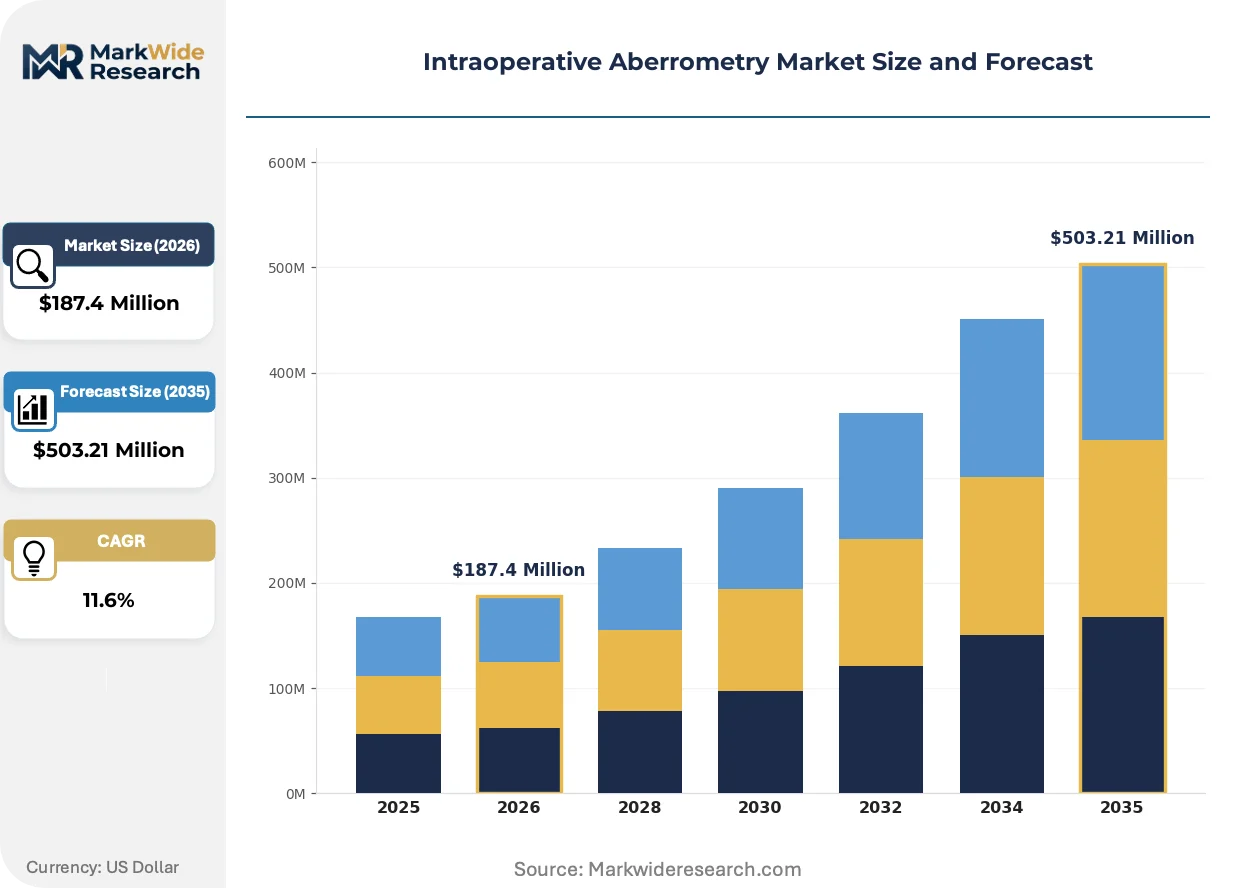
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aberrometer Systems, Software Solutions, Accessories, Consumables Technology: Wavefront Aberrometry, Scheimpflug Imaging, Optical Coherence Tomography, Intraoperative Wavefront Sensing End User: Hospitals, Ambulatory Surgical Centers, Ophthalmology Clinics, Research Institutions Application: Refractive Surgery, Cataract Surgery, Corneal Procedures, Lens Implantation |
| Companies Covered | Carl Zeiss Meditec, ZEISS International, Clarity Medical Systems, Johnson & Johnson Vision, Danaher Corporation, WaveTec Vision, LENSAR, Leica Microsystems, Alcon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intraoperative Aberrometry Market Shifts & Advancements
Digital surgical planning ecosystems are displacing standalone device workflows, compressing the value chain toward integrated platforms that combine preoperative biometry, intraoperative guidance, and postoperative analytics.
Intraoperative wavefront sensing is virtualizing traditional aphakic measurement protocols. Refractive surgery centers in Germany and Japan are adopting these systems for real-time confirmation during laser ablation procedures. This virtualization is compressing the distinction between diagnostic and therapeutic device categories, forcing vendors to restructure R&D around closed-loop surgical ecosystems rather than point solutions.
MDR notified body capacity constraints are extending review timelines for novel optical algorithms across European markets. Manufacturers seeking CE marking for wavefront reconstruction software face 6-9 month delays compared to hardware-only submissions. German ophthalmology clinics are responding by accelerating procurement of MDR-compliant platforms ahead of 2027 renewal deadlines, front-loading capital expenditure into 2025-2026 purchasing cycles.
Hospital procurement consortia are consolidating device purchasing across ambulatory networks, displacing individual surgeon preference in capital allocation decisions. United States health systems are negotiating enterprise-wide contracts that bundle aberrometry hardware with IOL consumables and service agreements. This concentration is most visible in the southeastern United States, where multi-facility surgical groups are standardizing on single-vendor platforms to extract volume discounts and simplify training protocols.
Intraoperative Aberrometry Market Segmentation
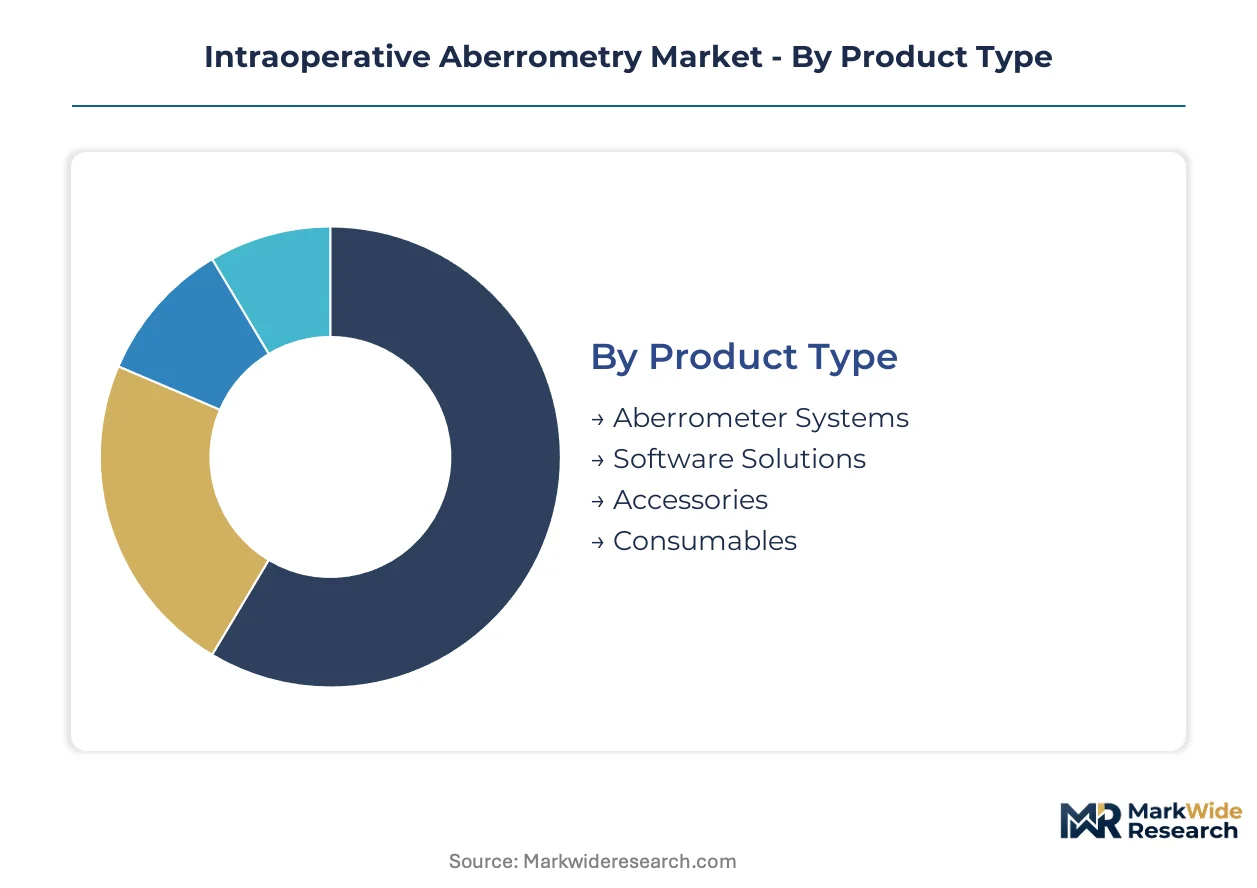
Intraoperative aberrometry vendors structure their commercial strategies around distinct product-service bundles, technology licensing models, and end-user procurement patterns. Each segmentation layer reveals where margin pools concentrate and how competitive positioning shifts across capital equipment versus recurring revenue streams.
Product Type:
After-sales service intensity varies dramatically across this category, with hardware systems demanding multi-year calibration contracts while software solutions shift toward cloud-based subscription models with minimal field engineering requirements.
- Aberrometer Systems:Capital equipment incorporating infrared wavefront sensors and precision optical benches for real-time refractive measurement during live surgery. Hospital procurement consortia in the United States negotiate enterprise-wide service bundles spanning calibration, software updates, and replacement optics. These systems command extended depreciation schedules and captive consumable lock-ins.
- Software Solutions:Analytics platforms for surgical planning, wavefront reconstruction, and postoperative outcome tracking delivered via cloud architecture or on-premise licensing. Ambulatory surgical centers in Germany favor subscription models that unbundle analytics from hardware, enabling faster feature deployment without capital refresh cycles. This segment is expanding most quickly as vendors pivot toward recurring revenue.
- Accessories:Patient interface devices, sterile drapes, and mounting hardware requiring periodic replacement.
- Consumables:Single-use calibration targets, disinfectant solutions, and optical coupling gels tied to procedure volume.
Aberrometer systems hold the largest share; momentum sits with software solutions.
Technology:
Cost tier stratification separates premium wavefront platforms from mid-range alternatives, with reimbursement coding and clinical validation requirements determining which technologies penetrate specific procedure channels.
- Wavefront Aberrometry:Shack-Hartmann sensor arrays measuring total ocular aberrations across Zernike polynomial decompositions for lens power calculation and toric alignment verification. Premium cataract channels in Japan and Germany mandate this technology for astigmatism-correcting lens workflows, embedding it into standard-of-care protocols.
- Intraoperative Wavefront Sensing:Real-time infrared systems capturing aphakic or pseudophakic measurements during wound closure to reduce refractive surprise. Refractive surgery suites in South Korea deploy these for laser ablation confirmation, opening adjacent application demand outside traditional cataract settings.
- Scheimpflug Imaging:Rotating camera systems for corneal tomography and anterior segment analysis.
- Optical Coherence Tomography:Cross-sectional imaging for corneal thickness mapping and intraocular structure visualization.
Wavefront aberrometry dominates revenue concentration; intraoperative wavefront sensing climbs the fastest.
End User:
Customer type determines procurement authority structures, with individual surgeon preference giving way to centralized purchasing decisions as facility networks consolidate.
- Ambulatory Surgical Centers:Freestanding facilities capturing premium cataract volume outside hospital settings through streamlined refractive suites. United States health systems in the Southeast standardize on single-vendor platforms across multi-facility networks to extract volume discounts and simplify training protocols.
- Hospitals:Academic medical centers and community hospitals with capital committees evaluating aberrometry through total cost-of-ownership frameworks. German university hospitals anchor clinical validation networks for novel wavefront-guided platforms, influencing adoption patterns across European markets.
- Ophthalmology Clinics:Independent practices and group practices with limited capital budgets.
- Research Institutions:Academic laboratories and contract research organizations developing next-generation optical algorithms.
Ambulatory surgical centers are gaining share fastest; hospitals retain the largest installed base.
Application:
Procedure volume and reimbursement differentiation separate high-margin premium channels from commoditized standard-care pathways.
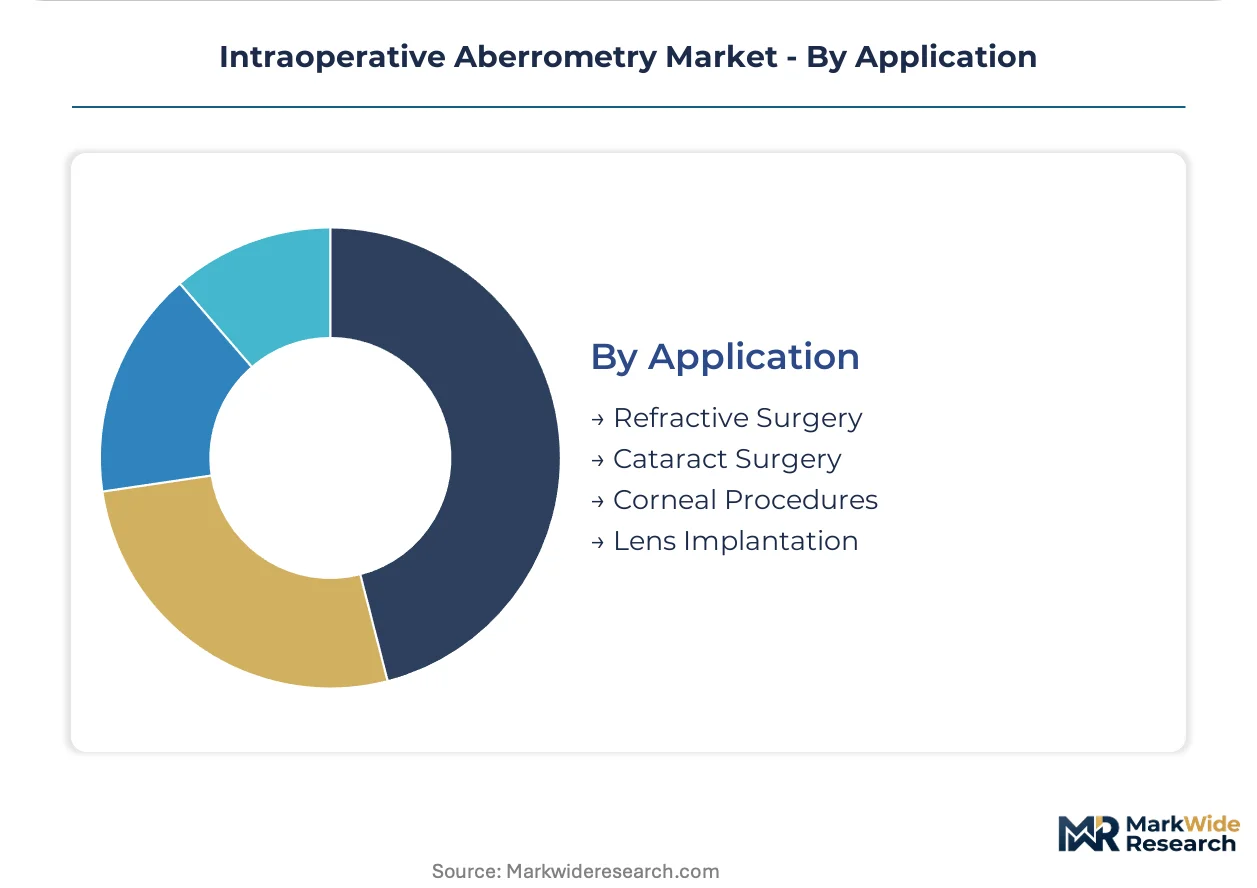
- Cataract Surgery:Lens extraction procedures where intraoperative aberrometry verifies aphakic measurements and guides toric IOL selection. The FDA's 510(k) pathway for computer-assisted cataract surgery coding shapes hospital capital allocation toward validated measurement platforms in the United States.
- Refractive Surgery:Laser vision correction and lens-based procedures requiring real-time ablation confirmation. Centers in Germany and Japan adopt intraoperative wavefront sensing to virtualize traditional diagnostic protocols, compressing the distinction between measurement and treatment device categories.
- Corneal Procedures:Transplantation and reshaping surgeries with specialized aberrometry requirements.
- Lens Implantation:Phakic IOL and premium multifocal lens placements.
Cataract surgery holds the largest share; refractive surgery shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Oberkochen precision optics corridor in southwestern Germany anchors the industry's manufacturing infrastructure, with dedicated rail freight links connecting component suppliers to surgical device assembly facilities across the Rhine-Ruhr industrial belt.
United States
Ambulatory surgical centers in the southeastern states are consolidating refractive suite investments through multi-facility procurement consortia. The FDA's 510(k) premarket notification pathway shapes clearance timelines for wavefront algorithm updates. Nashville and Dallas-Fort Worth surgical networks are standardizing on single-vendor platforms to extract volume discounts and simplify staff training protocols.
Germany
University hospitals in Heidelberg and Tübingen anchor clinical validation networks for next-generation wavefront-guided platforms. The EU Medical Device Regulation's notified body capacity constraints are extending review timelines for optical reconstruction software. The Oberkochen industrial cluster sustains captive precision optics manufacturing for premium cataract workflow systems.
Japan
Refractive surgery centers in Tokyo and Osaka are deploying intraoperative wavefront sensing for real-time laser ablation confirmation. METI's medical device reimbursement frameworks differentiate premium measurement platforms from standard diagnostic equipment. The Kansai region's ophthalmology clinic networks are accelerating MDR-compliant platform procurement ahead of 2027 renewal deadlines.
South Korea
Laser vision correction chains in Seoul and Busan are adopting wavefront verification systems for intraoperative confirmation protocols. The MFDS medical device approval pathway governs software-as-medical-device classifications for cloud-based surgical planning tools. The Pangyo technopolis cluster is hosting digital health startups developing analytics platforms for postoperative outcome tracking.
India
Corporate hospital chains in Mumbai and Delhi-NCR are outfitting premium cataract channels with real-time lens verification systems. CDSCO's medical device rules framework is harmonizing with ISO 13485 quality management standards for imported diagnostic platforms. The Hyderabad medical device manufacturing zone is attracting contract assembly operations for infrared sensor subsystems.
Intraoperative Aberrometry Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated optics manufacturers and diversified surgical device conglomerates with captive ophthalmology divisions. Three strategic archetypes dominate: precision optics specialists with captive manufacturing bases, diversified medtech conglomerates bundling hardware with disposable consumables, and refractive surgery platform vendors integrating diagnostic and therapeutic workflows. Competitive maneuvering concentrates on multi-year service contract structures and software unbundling strategies that shift revenue toward recurring analytics subscriptions.
Among Germany-based precision optics groups, Carl Zeiss Meditec and Leica Microsystems occupy positions anchored by the Oberkochen manufacturing corridor. Johnson & Johnson Vision represents the diversified conglomerate archetype with bundled contract structures. These three exemplify the tension between captive supply chain control and platform ecosystem expansion that defines current competitive positioning.
| Leading Market Players |
|---|
| Carl Zeiss Meditec |
| ZEISS International |
| Clarity Medical Systems |
| Johnson & Johnson Vision |
| Danaher Corporation |
| WaveTec Vision |
| LENSAR |
| Leica Microsystems |
| Alcon |
| Others |
Supply & Pricing Matrix
Oberkochen's precision optics corridor concentrates infrared sensor manufacturing for wavefront-guided surgical platforms, anchoring premium pricing power in German-produced aberrometer systems while compressing margins for non-captive vendors dependent on third-party optical benches. Hospital procurement consortia in the United States exploit this asymmetry through multi-year service bundles that lock in consumable revenue streams alongside capital equipment depreciation schedules.
Pricing Analysis
Volume-discount tiering structures dominate enterprise contract negotiations, with three-tier pricing separating premium wavefront platforms from mid-range alternatives and economy-tier manual keratometry systems. Price differentiation hinges on FDA 510(k) clearance tier and after-sales calibration intensity, with MDR-certified platforms commanding premiums over legacy CE-marked devices. Pricing pressure stems from ambulatory surgical center consolidation demanding standardized single-vendor platforms across multi-facility networks. Independent ophthalmology clinics exhibit highest price sensitivity, while academic medical centers prioritize total cost-of-ownership frameworks over upfront capital expenditure.
Supply Chain Analysis
Supplier-financing facilities extend payment terms for precision optics subsystems, enabling German and Japanese device assemblers to manage working capital through supply-chain finance structures anchored by Oberkochen component suppliers. Geographic supply concentration centers on Germany, Japan, and the United States for Shack-Hartmann sensor arrays, precision optical benches, and infrared detector subsystems. Raw material dependencies include germanium substrates, aluminum-coated mirrors, and specialized epoxy adhesives for sterile field compatibility. Single-source vulnerability concentrates in Oberkochen-based captive optics manufacturing. Distribution runs through hospital procurement consortia and ambulatory surgical center networks with direct field service engineering deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through FDA 510(k) and EU MDR validation creates switching costs that embed incumbent platforms into hospital capital planning cycles. The structural advantage compounds through multi-year service contracts and consumable lock-ins.
For Market Incumbents: Pre-empt software unbundling threats by accelerating cloud-based analytics platform development before ambulatory surgical centers pivot to subscription-only vendors. Capture toric IOL alignment protocol standardization through deeper integration with premium cataract workflow certification. Defend against emerging refractive surgery platform entrants by anchoring clinical validation networks in German university hospitals.
For New Entrants and Emerging Players: Build out intraoperative wavefront sensing capabilities for South Korean laser vision correction chains seeking real-time ablation confirmation outside traditional cataract settings. Target price-sensitive ophthalmology clinics in India and Brazil with mid-range alternatives to premium wavefront platforms. Pursue GPO contract penetration through software-as-medical-device positioning that bypasses capital equipment procurement committees.
For Investors and Strategic Acquirers: Capital is best deployed toward precision optics specialists with captive Oberkochen manufacturing bases and established MDR notified body relationships that accelerate CE marking timelines. Long-term viability over the next decade hinges on software recurring revenue transformation. Monitor CMS reimbursement coding decisions for computer-assisted cataract surgery as the critical inflection signal for hospital capital allocation toward validated measurement platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Pathway Acceleration | Notified body relationships in Germany compress CE marking timelines for optical reconstruction software ahead of 2027 renewal deadlines. |
| Software Companion Development | Cloud-based surgical planning subscriptions unbundle analytics from hardware to capture recurring revenue from ambulatory surgical centers. |
| Hospital System Partnership | Enterprise-wide contracts with southeastern United States health systems standardize training protocols across multi-facility networks. |
| FDA 510(k) Submission Strategy | Premarket notification pathway for novel wavefront algorithms shapes competitive response windows for algorithm-dependent features. |
| Reimbursement Strategy | CMS coding decisions for computer-assisted cataract surgery reshape capital allocation toward validated aberrometry platforms. |
Research Methodology
Initial hypotheses were tested against primary input from cataract surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, EU MDR notified body submissions, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up procedure volume estimates across ambulatory surgical centers and hospitals were triangulated with top-down capital expenditure tracking from health system financial disclosures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling aberrometer system placements against replacement cycles and greenfield ambulatory surgical center construction. Segmentation dimensions included product type, technology tier, end-user facility category, and application procedure volume. CAGRs were derived from installed base evolution and average selling price trajectories. Industry-specific forecast inputs incorporated MDR compliance deadline acceleration and CMS reimbursement coding decision timelines.
Stress conditions across FDA review timeline extensions, notified body capacity constraints, and ambulatory surgical center consolidation velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and procurement consortium negotiation leverage. Macroeconomic contraction, regulatory pathway disruption, or toric IOL protocol abandonment would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Non-Absorbable Sutures Market
Surgical Instruments
Cheilectomy Market
Surgical Instruments
Global Surgical Instrument Tracking System Market
Surgical Instruments
High Flow Needle Sets Market
Surgical Instruments
Minimally Invasive Gastrointestinal Surgical System Market
Surgical Instruments
Global Pain Management and Surgical Devices Market
Surgical Instruments
Brazil General Surgical Devices Market
Surgical Instruments
Endometrial Ablation Market
Surgical Instruments
Disposable Laparoscopic Instruments Market
Surgical Instruments
Global Myomectomy Market
Surgical Instruments
Cystoscopy Needles Market
Surgical Instruments
United States Minimally Invasive Surgery Market
Surgical Instruments
Disposable Ophthalmic Surgical Products Market
Surgical Instruments
Global Surgical Scissors Market
Surgical Instruments
Surgical Visualization Market
Surgical Instruments
Medical Penlights Market