
 Radio Frequency Beauty Equipment Market | 2026-2036
Radio Frequency Beauty Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Radio Frequency Beauty Equipment Market Outlook
Medical-grade certification standards is reorganizing procurement priorities across the Radio Frequency Beauty Equipment industry. Alma Lasers leverages vertical integration into laser and energy-based platform manufacturing to control component quality. Venus Concept sustains channel dominance through subscription-based equipment placement models that lock in clinic loyalty. InMode differentiates by specializing in minimally invasive radio frequency technologies that bridge surgical and non-surgical outcomes.
Radio frequency beauty equipment delivers controlled electromagnetic energy at frequencies typically between 0.3 and 10 MHz to heat dermal collagen and subcutaneous tissue, triggering neocollagenesis and localized fat metabolism. Facial devices command premium placement in dermatology practices due to shorter treatment cycles and higher per-session pricing, while body devices accumulate volume through med-spa chains seeking cellulite reduction and fat reduction service lines. Bipolar and multipolar configurations are displacing monopolar systems in new installations because they offer more predictable energy distribution and reduced epidermal burn risk. Home users represent the fastest-growing end-user category as handheld devices with temperature-limiting sensors enter direct-to-consumer channels.
FDA 510(k) clearance requirements and the EU Medical Device Regulation shape product development timelines and clinical evidence burdens for manufacturers seeking market access. CE marking under MDR Class IIa rules forces companies to maintain post-market surveillance systems and periodic safety update reports. China's NMPA now requires domestic clinical trials for imported radio frequency aesthetic devices, extending registration timelines. Stakeholders must monitor how evolving electromagnetic compatibility standards and tissue heating safety thresholds in major jurisdictions will reshape R&D budgets and geographic launch sequencing.
Market Dynamics
Radio frequency beauty equipment procurement is reorganizing around medical-grade certification hierarchies that separate reimbursable clinical applications from cosmetic wellness services, compressing vendor margins on uncertified devices while elevating premiums for FDA 510(k) cleared systems.
Growth Catalysts
- EU MDR Class IIa pathway:Post-market surveillance mandates under the Medical Device Regulation are accelerating clinic upgrades to compliant hardware, pulling forward replacement cycles across German and French aesthetic practices.
- Med-spa chain consolidation:Scale operators in South Korea and the United States are standardizing device fleets to reduce training costs and enable cross-clinic service menus, concentrating purchase volume with multi-unit contracts.
- Multipolar RF configurations:Predictable energy distribution and reduced epidermal burn risk are displacing monopolar installations in new dermatology suite builds.
Market Restraints
- Copper and semiconductor input volatility:RF generator components face price instability from constrained foundry capacity and refined metal supply disruptions, compressing hardware margins for mid-tier manufacturers.
- NMPA domestic trial requirements:China's National Medical Products Administration now mandates local clinical evidence for imported devices, extending registration timelines and freezing market entry for non-compliant vendors.
- Intense pulsed light substitution:IPL platforms with comparable collagen stimulation profiles compete for capital allocation in budget-constrained clinics, particularly in secondary urban markets.
Strategic Opportunities
- Home-use handheld expansion:Temperature-limiting sensor integration enables direct-to-consumer channels for facial tightening devices, opening volume segments outside clinical procurement.
- Subscription placement models:Equipment-as-service arrangements lock in long-term consumable revenue and reduce upfront capital barriers for independent aesthetic practitioners.
- Cellulite reduction service lines:Body-contouring applications remain underpenetrated relative to facial treatments, offering expansion vectors for med-spa chains seeking differentiated offerings.
Industry Challenges
- Electromagnetic compatibility certification:Evolving IEC 60601-1-2 standards for RF emissions testing extend engineering validation cycles and require specialized compliance expertise that smaller manufacturers struggle to retain.
- Biomedical engineer talent scarcity:The intersection of RF physics and tissue interaction modeling demands specialized expertise that outpaces graduate program output, constraining R&D velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radio Frequency Beauty Equipment Market |
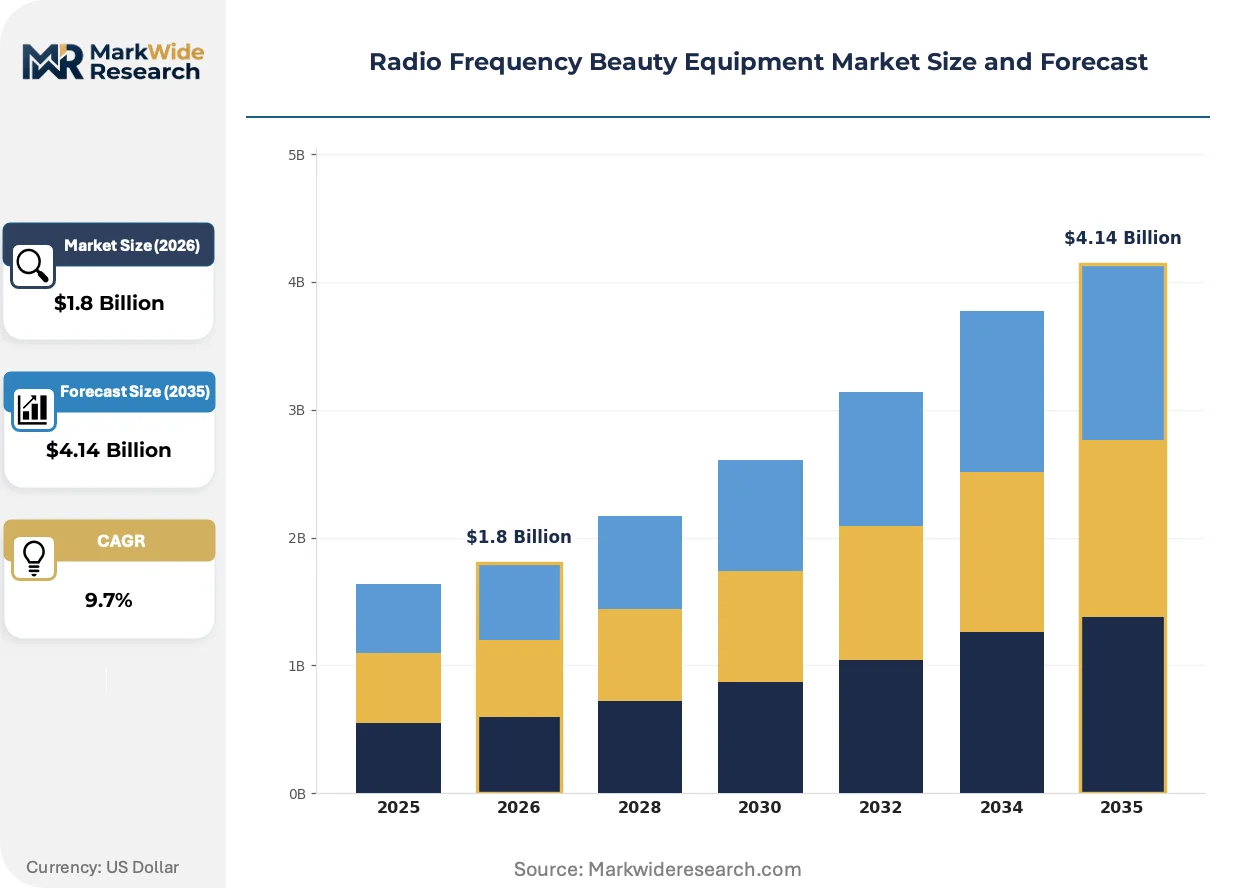
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Facial Devices, Body Devices, Aesthetic Equipment, Handheld Devices Application: Skin Tightening, Cellulite Reduction, Anti-Aging Treatment, Fat Reduction End User: Beauty Clinics, Spas, Cosmetic Hospitals, Home Users Technology: Monopolar, Bipolar, Multipolar, Fractional |
| Companies Covered | Alma Lasers, Venus Concept, Cynosure, Cutera, BTL Industries, Lumenis, InMode, Sharplight Technologies, Syneron Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radio Frequency Beauty Equipment Market Strategic Shifts
Device architecture is splitting between high-power clinical platforms and portable consumer units, while regulatory frameworks in major jurisdictions force concurrent compliance investments that reshape competitive positioning.
Multipolar radio frequency technology is bifurcating the installed base between legacy monopolar systems and newer configurations that distribute energy across multiple electrode pairs. Dermatology practices in Germany and the United States are prioritizing bipolar and multipolar devices for facial applications where epidermal safety margins command premium pricing. This technology split is compressing residual value for monopolar hardware while enabling vendors to segment pricing across safety-performance tiers.
EU Medical Device Regulation post-market surveillance requirements are forcing manufacturers to maintain periodic safety update reports and vigilance systems for RF tissue heating devices. The compliance burden falls heaviest on Class IIa devices, extending product development timelines and elevating clinical evidence costs. Vendors are responding by concentrating launch sequencing on jurisdictions with harmonized standards, delaying secondary market entries until MDR technical documentation matures.
Clinic procurement patterns are fragmenting between capital purchase and operational lease structures, with med-spa chains favoring subscription-based equipment placement that bundles maintenance and consumables. Independent dermatology practices retain preference for outright ownership to preserve balance sheet flexibility and depreciation schedules. This financing split is most pronounced in the United States, where equipment financiers have developed specialized aesthetic device lending products.
Radio Frequency Beauty Equipment Market Segmentation
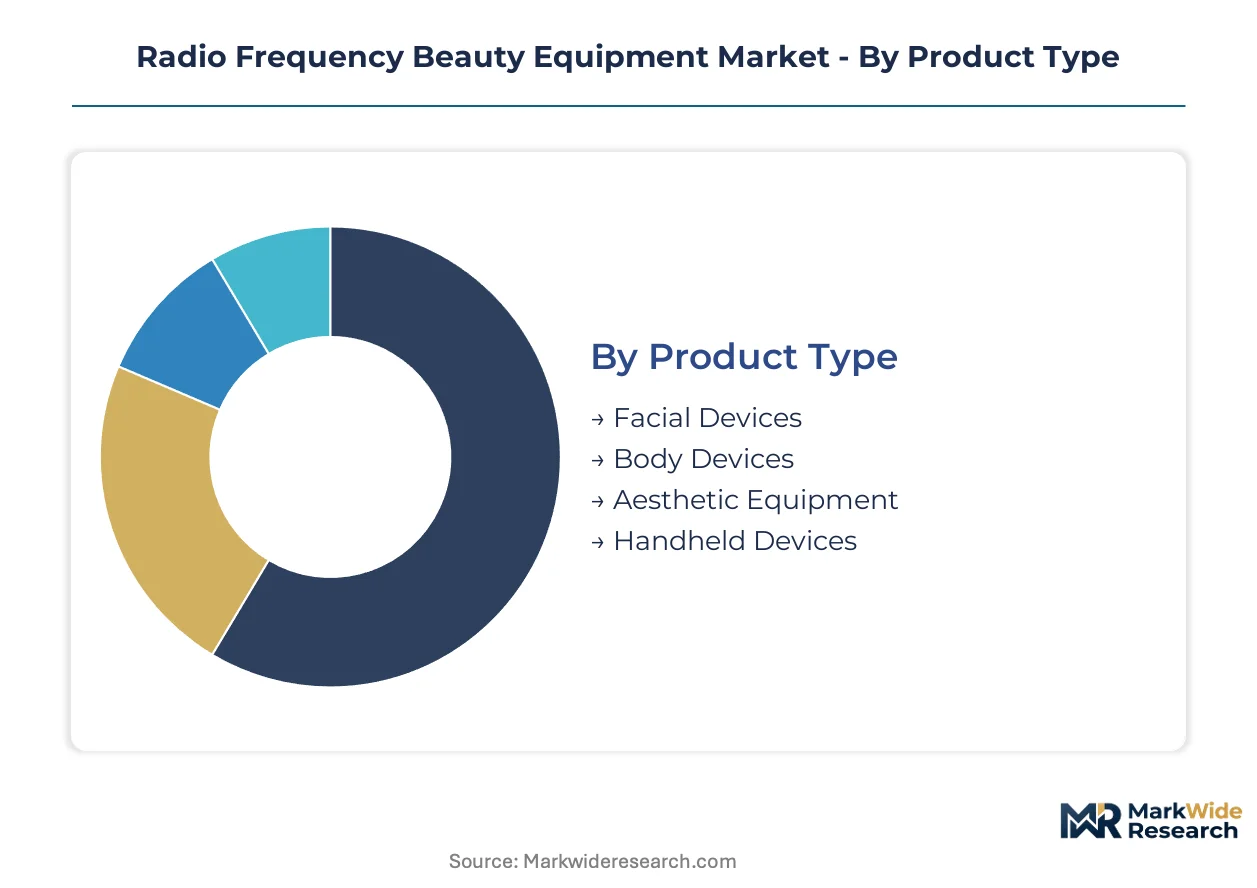
Radio frequency beauty equipment segmentation reveals how technology configuration and use setting determine pricing power and regulatory burden. Understanding these divides clarifies where vendors capture premium returns versus where volume commoditization pressures margins.
Product Type:
Margin pools concentrate in clinical-grade platforms where FDA 510(k) clearance commands substantial price premiums over consumer alternatives.
- Facial Devices:Compact electrode arrays operating at 1-3 MHz target periorbital and jowling applications with shorter treatment protocols. Dermatology practices in Germany and the United States prioritize these systems for their higher per-session pricing and rapid patient turnover.
- Body Devices:Larger applicators with deeper penetration capabilities address abdominal and thigh contours through sustained heating cycles. Med-spa chains in South Korea deploy these for cellulite reduction service lines that differentiate from facial-focused competitors.
- Aesthetic Equipment:Multi-modality platforms combining RF with vacuum or cooling technologies for comprehensive treatment menus.
- Handheld Devices:Battery-powered consumer units with temperature-limiting sensors for direct-to-consumer channels.
The dominant share belongs to Facial Devices, while Handheld Devices are closing the gap fastest.
Application:
Volume distribution tracks procedure reimbursement patterns and consumer willingness to pay for visible outcomes.
- Skin Tightening:Collagen remodeling through controlled dermal heating addresses laxity in facial and neck zones. Cosmetic hospitals in the United States concentrate demand here due to established clinical protocols and predictable patient satisfaction metrics.
- Cellulite Reduction:Subcutaneous tissue heating combined with mechanical manipulation targets fibrous septae. Spas in Germany and South Korea are expanding this service category as body contouring gains preference over invasive alternatives.
- Anti-Aging Treatment:Preventive protocols for fine lines and texture improvement in younger demographics.
- Fat Reduction:Lipolytic heating of adipose tissue for circumferential reduction in targeted zones.
Skin Tightening retains the largest procedure volume, though Cellulite Reduction is expanding most quickly as med-spa chains seek differentiated offerings.
End User:
Procurement patterns fragment sharply between institutional capital budgets and consumer discretionary spending.
- Beauty Clinics:Independent aesthetic practices with mixed service menus prioritize versatile platforms. These operators in the United States favor outright ownership to preserve depreciation schedules and balance sheet flexibility.
- Spas:Wellness-focused operators with lighter medical supervision requirements seek simpler protocols. South Korean spa chains are standardizing device fleets to reduce training costs across multi-unit footprints.
- Cosmetic Hospitals:Surgical facilities integrating non-invasive options for comprehensive patient management.
- Home Users:Individual consumers purchasing handheld devices through direct-to-consumer channels.
Beauty Clinics command the largest installed base, while Home Users are gaining share fastest as temperature-sensor technology enables safer unsupervised operation.
Technology:
Energy delivery architecture determines safety margins, treatment consistency, and regulatory classification complexity.
- Multipolar:Distributed electrode configurations between 0.5-2 MHz provide predictable thermal profiles across treatment zones. New dermatology suite builds in Germany and the United States are prioritizing these systems for reduced epidermal burn risk.
- Bipolar:Paired electrode systems with localized current paths suited for facial precision work. These configurations are displacing monopolar installations where epidermal safety commands premium positioning.
- Monopolar:Single active electrode with return pad requiring higher power settings for equivalent tissue effect.
- Fractional:Micro-needle or pin-based delivery creating discrete thermal zones for accelerated healing.
Multipolar systems hold the leading position in new installations, while Fractional technology is climbing the fastest as manufacturers seek to bridge ablative and non-ablative outcome profiles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in South Korea and Germany exhibit the lowest price elasticity, prioritizing FDA 510(k) clearance and MDR compliance over acquisition cost, while operators in China and secondary US markets remain highly sensitive to upfront capital outlay and financing terms.
United States
Cosmetic hospitals in California and New York Metro drive demand for high-power clinical platforms with shorter treatment protocols. FDA 510(k) clearance timelines shape procurement calendars, with dermatology practices accelerating replacement cycles ahead of anticipated regulatory tightening. Los Angeles and Manhattan host the densest clusters of aesthetic clinics, where multi-device contracts dominate purchasing.
Germany
Dermatology suites in Bavaria and North Rhine-Westphalia prioritize bipolar and multipolar configurations for reduced epidermal burn risk. EU MDR Class IIa post-market surveillance mandates are forcing clinic upgrades to compliant hardware, compressing residual value for legacy systems. Berlin-Brandenburg emerges as a hub for regulatory consulting services supporting CE marking transitions.
South Korea
Med-spa chains in Seoul Capital Area and Busan-Ulsan standardize device fleets to reduce training costs across multi-unit footprints. MFDS registration requirements for radio frequency tissue heating devices enforce rigorous electromagnetic compatibility testing. Gangnam district aesthetic practices command premium placement for facial tightening service lines.
China
Domestic manufacturers in Yangtze River Delta and Pearl River Delta regions capture volume segments as NMPA domestic clinical trial requirements freeze market entry for non-compliant imported vendors. Shanghai and Shenzhen clinics favor multi-modality platforms combining RF with vacuum technologies. Beijing-Tianjin-Hebei corridor shows accelerating preference for subscription-based equipment placement models.
United Kingdom
Independent aesthetic practices in London and Southeast England retain preference for outright ownership to preserve balance sheet flexibility and depreciation schedules. MHRA alignment with EU MDR standards elevates clinical evidence burdens for market access. Harley Street clinic clusters concentrate demand for premium facial devices with established patient satisfaction metrics.
Radio Frequency Beauty Equipment Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Radio Frequency Beauty Equipment industry. Premium-tier vendors capture margin through FDA 510(k) clearance and MDR compliance, while mid-tier manufacturers compete on acquisition cost and financing flexibility. The market structure segments into vertically integrated platform specialists, subscription-based equipment placers, and handheld consumer device entrants. Dominant competitive moves include strategic partnerships with med-spa chains and geographic licensing arrangements to bypass direct registration barriers.
Among vertically integrated platform specialists, Alma Lasers and Lumenis occupy positions emphasizing in-house production of laser and energy-based components. Venus Concept exemplifies the subscription-based equipment placement archetype, with InMode representing specialists in minimally invasive radio frequency configurations. These three anchors demonstrate how vendor strategy diverges across certification hierarchies and financing structures.
| Leading Market Players |
|---|
| Alma Lasers |
| Venus Concept |
| Cynosure |
| Cutera |
| BTL Industries |
| Lumenis |
| InMode |
| Sharplight Technologies |
| Syneron Medical |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day lead times for RF generator assemblies concentrate procurement leverage with German and South Korean component suppliers, compressing margins for mid-tier manufacturers while elevating premiums for vendors with captive supply arrangements. This inventory dynamic bifurcates pricing power between vertically integrated platform specialists and assembly-dependent competitors.
Pricing Analysis
Consumable and service contract revenue streams now drive lifetime value for clinical-grade RF equipment vendors, with subscription-based placement models capturing recurring income that offsets compressed hardware margins. Three-tier pricing structure across FDA-cleared premium, CE-marked standard, and uncertified economy levels segments buyers by risk tolerance and reimbursement access. Cost compression in mid-tier configurations intensifies because copper and semiconductor input volatility erodes assembly margins. Budget-constrained med-spa chains in secondary US markets exhibit highest price sensitivity, while German dermatology practices prioritize MDR compliance over acquisition cost.
Supply Chain Analysis
Ninety-day inventory cycles for RF power amplifiers expose manufacturers to foundry capacity constraints in Taiwan, South Korea, and Japan. RF generator components draw from refined copper suppliers in Chile and semiconductor foundries concentrated in East Asia. Single-source vulnerability for high-frequency power transistors threatens production continuity when foundry allocation tightens. Distribution runs through specialized aesthetic device financiers in the United States and direct manufacturer relationships with med-spa chains in South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radio frequency beauty equipment represents a high-growth disruption as EU MDR Class IIa post-market surveillance mandates force clinic hardware upgrades and pull forward replacement cycles across European aesthetic practices.
For Market Incumbents: Fortify certification moats by accelerating FDA 510(k) submissions for multipolar configurations before regulatory tightening extends clearance timelines. Deepen backward integration into RF power amplifier production to offset semiconductor foundry allocation risk and preserve margin structure against input cost volatility. For New Entrants and Emerging Players: Home-use handheld service gaps where incumbents under-serve direct-to-consumer channels offer the most penetrable entry vector, particularly for temperature-sensor-enabled facial devices. Target independent aesthetic practitioners in the United States with equipment-as-service financing that reduces upfront capital barriers and locks in consumable revenue streams. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device parents with under-optimized aesthetic divisions lacking dedicated RF tissue heating expertise. Long-term viability centers on vendors with harmonized FDA-CE-MDR regulatory dossiers and established post-market surveillance infrastructure. Watch NMPA registration progress for imported devices as the inflection signal for China market access viability.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Buildout | CE marking under EU Class IIa rules forces periodic safety update systems that smaller vendors cannot maintain. |
| Subscription Equipment Placement | Venus Concept's model locks clinic loyalty through bundled maintenance and consumable revenue streams. |
| Multipolar RF Platform Launch | Bipolar and multipolar configurations displace monopolar installations by reducing epidermal burn risk. |
| Handheld Consumer Channel Entry | Temperature-limiting sensors enable direct-to-consumer facial tightening devices outside clinical procurement. |
| NMPA Domestic Trial Investment | China's clinical evidence mandate for imported devices extends registration timelines and freezes non-compliant vendors. |
Study Parameters
A spread of perspectives from biomedical engineers at RF device manufacturers, aesthetic clinic procurement managers, GPO contracts specialists, and regulatory affairs consultants converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, and NMPA registration records. Bottom-up unit economics from device placement models and top-down market sizing from aesthetic procedure volumes were triangulated to constrain estimate ranges.
Segmentation dimensions modeled span product type, application, end user, and technology configuration across the projection horizon. CAGRs were derived from installed base growth, replacement cycle compression, and penetration rate assumptions for home-use categories. Forecast inputs incorporated RF generator component lead times, clinic capital expenditure surveys, and regulatory pathway timeline data.
Underlying assumptions cover stable electromagnetic compatibility standards and continued foundry capacity allocation for RF power semiconductors, with deviation risk concentrated in NMPA registration timeline extensions and copper price volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Carboxy Therapy Market
Aesthetic Medicine
Professional Beauty Services Market
Aesthetic Medicine
Aesthetics Combination Therapy Market
Aesthetic Medicine
Energy-Based Aesthetic Devices Market
Aesthetic Medicine
Body Contouring Market
Aesthetic Medicine
Non-Invasive Fat Reduction Market
Aesthetic Medicine
Chemical Peel Market
Aesthetic Medicine
Dermal Fillers and Botulinum Toxin Market
Aesthetic Medicine
UAE Laser Hair Removal Market
Aesthetic Medicine
Global Stretch Marks Treatment Market
Aesthetic Medicine
Spain Facial Aesthetics Market
Aesthetic Medicine
Facial Rejuvenation Market
Aesthetic Medicine
Asia Pacific Aesthetics Market
Aesthetic Medicine
Global Aesthetic Dermatology Market
Aesthetic Medicine
Europe Aesthetic Dermatology Market
Aesthetic Medicine
Medical Aesthetic Dermal Filler Market