
 Global Surgical Instruments Market | 2026-2036
Global Surgical Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical Instruments Market Outlook
Electrosurgery integration with robotic platforms is fragmenting traditional handheld instrument supply chains. Medtronic leverages its end-to-end surgical ecosystem to anchor high-margin robotics segments. Stryker Corporation competes through specialized orthopedic power tools and navigation systems. Johnson & Johnson differentiates via its Ethicon suturing portfolio and advanced energy device pipeline.
Surgical instruments comprise precision-engineered tools—typically stainless steel, titanium, or polymer composites—manufactured through CNC machining, passivation, and electropolishing to achieve biocompatibility and corrosion resistance for tissue manipulation during operative procedures. Electrosurgery and robotics segments capture expanding margin pools as hospitals prioritize capital-intensive integrated suites, while handheld instruments remain a mature, volume-driven category. Orthopedic and cardiothoracic applications lead procedural demand due to aging demographics and minimally invasive technique diffusion.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and market access costs for manufacturers. ISO 13485 quality management systems and CE marking protocols enforce consistent design controls across production facilities. Stakeholders must monitor reimbursement shifts for robotic-assisted procedures and evolving sterilization validation standards as hospitals consolidate purchasing power.
Market Dynamics
Robotic platform integration is fragmenting traditional handheld instrument supply chains as hospitals consolidate purchasing around capital-intensive integrated surgical suites, forcing mid-tier manufacturers to reposition or exit.
Growth Catalysts
- EU MDR compliance deadlines:Stricter technical documentation requirements under the Medical Device Regulation are accelerating hospital procurement of certified electrosurgical platforms that reduce sterilization cycle complexity.
- Japan's aging surgical workforce:Declining numbers of trained surgeons per capita in Tokyo and Osaka medical clusters are driving demand for robotic-assisted navigation systems that compress learning curves.
- Titanium additive manufacturing:Powder-bed fusion processes are enabling patient-specific orthopedic cutting guides that integrate directly with Stryker and Zimmer Biomet navigation ecosystems.
Market Restraints
- Nickel price volatility:Stainless steel 316L feedstock costs fluctuate with Indonesian and Philippine ore export policies, squeezing margin on disposable retractor and forceps lines.
- Single-source electrosurgical generator dependency:Three German component suppliers control high-frequency power supply modules, creating concentration risk for mid-tier instrument assemblers.
- FDA 510(k) predicate device limitations:Substantial equivalence pathways for novel energy-based instruments face narrowing predicate pools, extending clearance timelines.
Strategic Opportunities
- Outpatient surgical center expansion in India:CDSCO streamlined registration for Class B electrosurgical devices opens ambulatory access beyond tier-1 metros like Mumbai and Delhi.
- AI-powered preoperative planning convergence:Integration of machine learning segmentation with robotic trajectory planning creates white space for instrument manufacturers with software-hardware hybrid capabilities.
- Health Canada priority review vouchers:Expedited pathways for pediatric surgical innovations incentivize development of scaled instrument sets for neonatal cardiothoracic procedures.
Industry Challenges
- ISO 13485 auditor capacity constraints:Notified body backlogs for quality management system recertification delay product launches by 8-14 months.
- Legacy EMR integration complexity:Robotic platform data outputs require custom HL7 FHIR mapping for Epic and Cerner deployments, inflating hospital IT implementation costs.
- Cross-border sterilization validation:Gamma irradiation dose mapping discrepancies between US and EU contract sterilizers create batch release friction for multinational kit suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical Instruments Market |
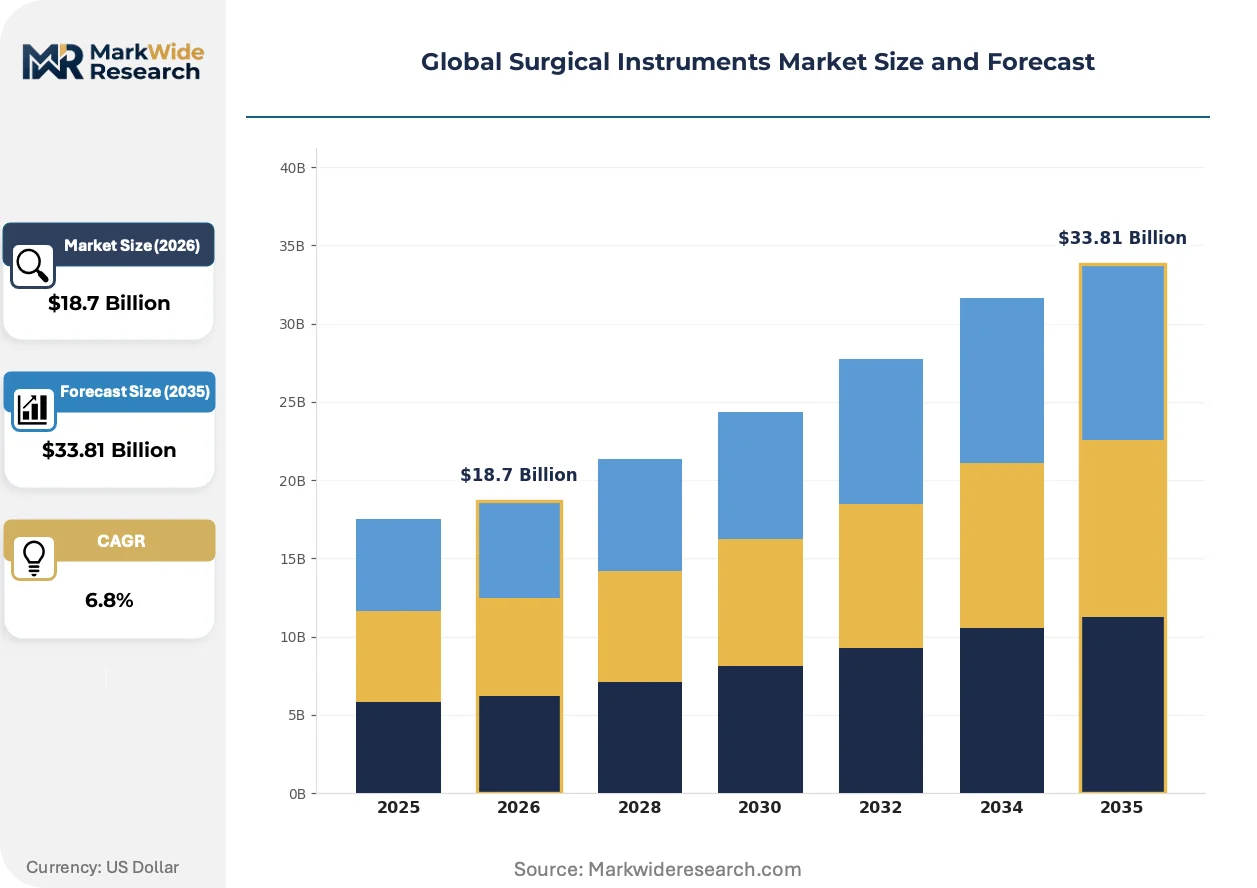
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scalpels, Forceps, Scissors, Sutures Application: Orthopedic, Cardiothoracic, Neurological, General Surgery End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Laboratories Technology: Electrosurgery, Robotics, Laser, Handheld Instruments |
| Companies Covered | Medtronic, Stryker Corporation, Johnson & Johnson, B. Braun SE, Boston Scientific Corporation, Smith & Nephew, Zimmer Biomet Holdings, Olympus Corporation, BD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical Instruments Market Strategic Shifts
Electrosurgical energy delivery and robotic kinematics are converging to redefine operative workflows, while regulatory data requirements and procurement centralization reshape how instruments reach surgical teams.
Single-use polymer-composite retractor systems are collapsing the economic case for traditional stainless steel reprocessing in high-volume orthopedic and spine centers. Ambulatory surgery chains in Florida and Texas are adopting these platforms to eliminate sterilization capital expenditure. The shift is compressing aftermarket service revenue for legacy instrument maintenance providers.
EU MDR Article 10 technical documentation mandates are forcing manufacturers to maintain clinical evidence portfolios for legacy electrosurgical SKUs. German and French notified bodies are rejecting substantial equivalence claims for instruments lacking post-market surveillance data. Class IIa energy device suppliers are responding by consolidating product lines to focus resources on high-volume platforms with defensible clinical histories.
Hospital value analysis committees now dominate capital equipment procurement, displacing individual surgeon preference in robotic instrument selection. Integrated delivery networks in California and Illinois are standardizing across fewer vendor ecosystems to leverage volume pricing. The concentration is most visible in cardiothoracic service lines where da Vinci system lock-in creates captive demand for compatible instrument cartridges.
Global Surgical Instruments Market Segmentation
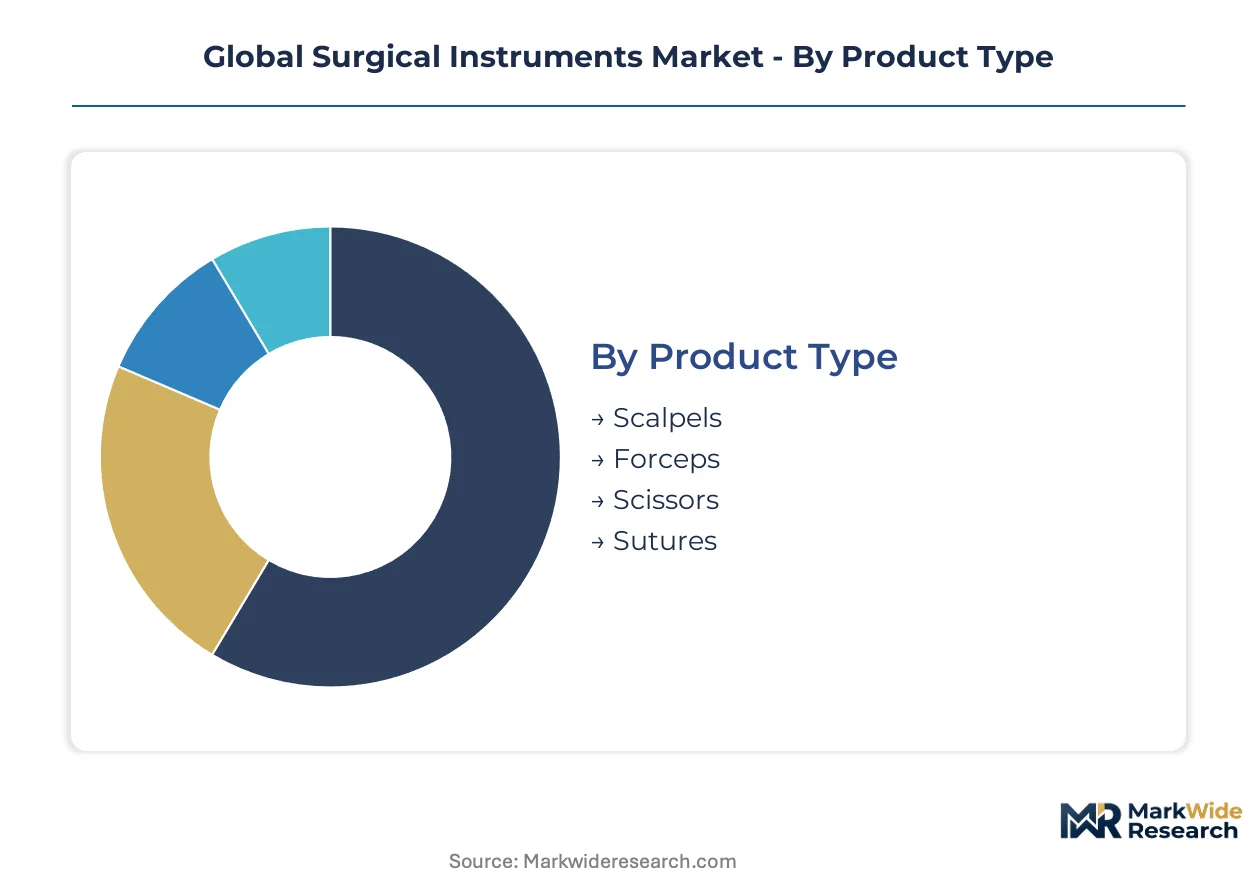
Segmentation in surgical instruments reveals divergent margin structures across technology tiers and care settings. Product type and application dimensions expose where capital intensity concentrates versus where volume commoditization dominates procurement decisions.
Product Type:
Cost tier differentiation separates premium precision-engineered platforms from commodity consumables in surgical instrument portfolios.
- Scalpels:Disposable carbon steel and stainless steel variants dominate high-volume general surgery. Demand clusters in United States ambulatory centers seeking to eliminate reprocessing overhead. Blade geometry standardization under ISO 7740 constrains premium pricing power.
- Forceps:Tungsten carbide inserts and titanium alloys define the premium tier for microsurgical applications. German manufacturers anchor supply through DIN 58298-certified production clusters in Tuttlingen. Grasping jaw design patents differentiate cardiovascular specialty lines.
- Scissors:Supercut and ultrasharp edge technologies target tissue dissection precision in Japan's aging surgical workforce.
- Sutures:Absorbable polymer and natural material portfolios span wound closure applications across Indian tier-2 hospital expansion.
Forceps commands the established base. The steepest expansion runs through Sutures.
Application:
Procedure complexity and reimbursement intensity shape instrument specification requirements across surgical specialties.
- Orthopedic:Power tools, navigation guides, and robotic arm attachments integrate with patient-specific cutting jigs. United States hospital systems prioritize bundled payment compatibility over individual instrument cost. Titanium additive manufacturing enables geometrically complex osteotomy guides.
- Cardiothoracic:Beating-heart stabilizers and endoscopic vein harvesters demand submillimeter precision for coronary bypass procedures. German cardiac surgery centers drive adoption of EU MDR-compliant electrosurgical platforms with integrated smoke evacuation.
- Neurological:Microdissection instruments and ultrasonic aspirators target tumor resection in Japan's neurosurgical clusters.
- General Surgery:Laparoscopic graspers and clip appliers serve high-volume cholecystectomy and hernia repair in Indian outpatient centers.
General Surgery commands the established base. Orthopedic posts the steepest volume climb.
End User:
Capital availability and sterilization infrastructure determine instrument acquisition patterns across care delivery sites.
- Hospitals:Integrated surgical suites with robotic docking stations and centralized sterile processing departments anchor high-value instrument procurement. United States academic medical centers consolidate vendor contracts across service lines to leverage purchasing scale.
- Clinics:Limited procedure rooms and absent autoclave capacity favor single-use disposable instruments. Indian urban clinics adopt CDSCO-registered electrosurgical pencils for minor dermatological procedures.
- Ambulatory Surgical Centers:Procedure-specific instrument kits eliminate cross-contamination risk in high-turnover environments. Texas and Florida chains lead polymer-composite retractor adoption.
- Research Laboratories:Precision microsurgical tools support preclinical device validation and cadaveric training programs.
Hospitals command the established base. Ambulatory Surgical Centers gain share fastest.
Technology:
Energy modality and automation level fragment competitive positioning across price-performance thresholds.
- Electrosurgery:Radiofrequency generators with active electrode monitoring dominate tissue coagulation and cutting. EU MDR technical documentation requirements are consolidating supplier bases around platforms with proven clinical histories.
- Robotics:Articulating instrument wrists and haptic feedback systems enable minimally invasive procedures through 8mm ports. Japanese surgical workforce constraints accelerate da Vinci system penetration in Tokyo metropolitan hospitals.
- Laser:CO2 and fiber-based systems target ophthalmic and dermatological precision applications.
- Handheld Instruments:Stainless steel 316L and titanium alloys persist in cost-sensitive procedures where capital equipment investment is prohibitive.
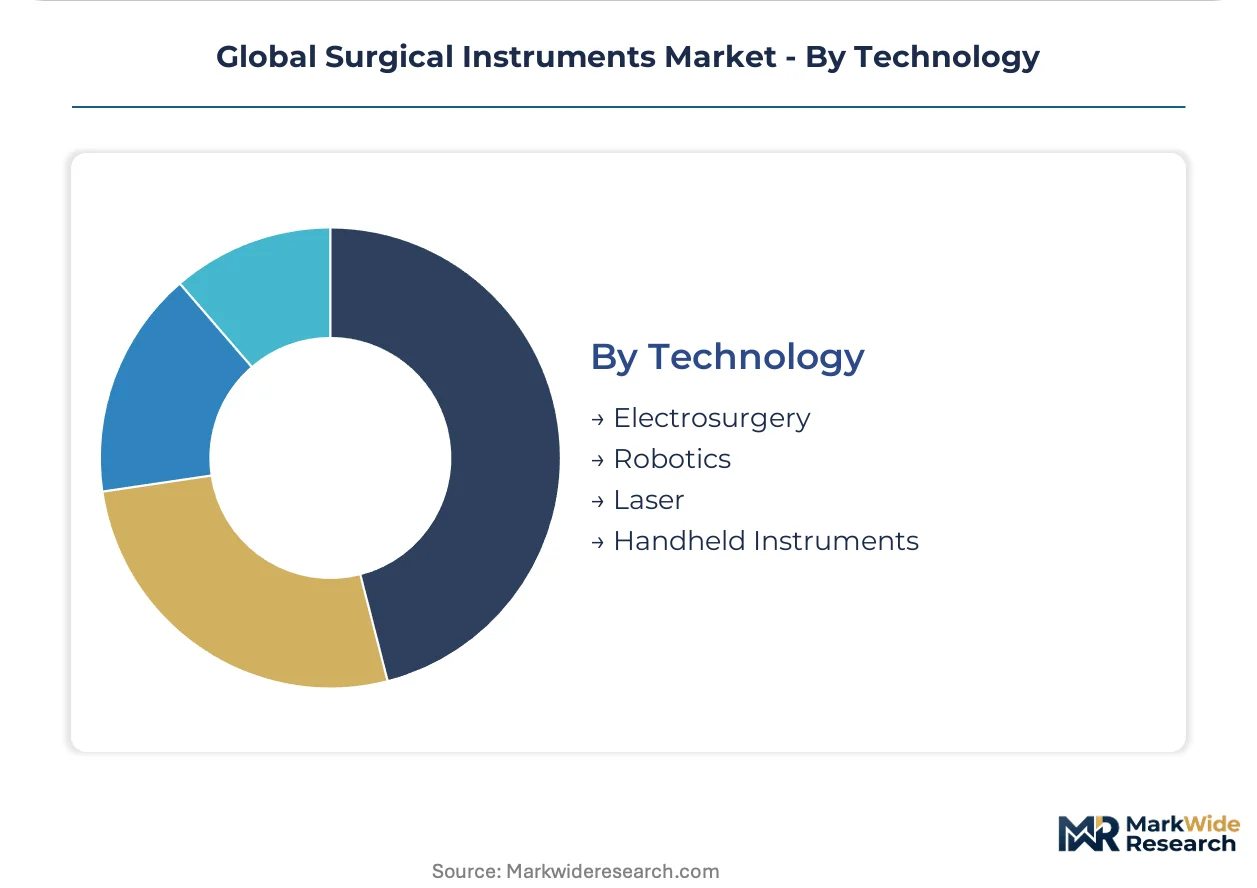
Handheld Instruments command the established base. Robotics shows the steepest trajectory expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in surgical instruments tilt toward surplus positions in German and Japanese manufacturing clusters while the United States absorbs elevated import volumes of electrosurgical platforms. Currency fluctuations against the euro and yen reshape procurement calendars for hospital systems in dollar-denominated markets. Regulatory divergence between FDA 510(k) pathways and EU MDR technical documentation requirements fragments supplier certification strategies across Atlantic trade lanes.
United States
Ambulatory surgery center chains in Florida and Texas drive disposable instrument procurement as sterilization capital avoidance accelerates. FDA 510(k) clearance timelines for novel energy devices extend as predicate device pools narrow. Academic medical centers in California and Illinois consolidate vendor contracts across cardiothoracic service lines to leverage integrated delivery network purchasing scale.
Germany
Tuttlingen manufacturing clusters anchor precision forceps and microsurgical instrument supply through DIN 58298-certified production networks. EU MDR Article 10 technical documentation mandates force clinical evidence portfolio maintenance for legacy electrosurgical SKUs. Frankfurt and Munich hospital systems prioritize EU MDR-compliant platforms with integrated smoke evacuation for cardiac surgery suites.
Japan
Declining trained surgeon counts per capita in Tokyo and Osaka medical clusters compress learning curves through robotic-assisted navigation adoption. PMDA regulatory frameworks align with international standards while maintaining distinct post-market surveillance protocols. Nagoya and Kyoto manufacturing bases supply titanium alloy microdissection tools for domestic neurosurgical demand.
India
Tier-2 hospital expansion beyond Mumbai and Delhi creates ambulatory access points for CDSCO-registered Class B electrosurgical devices. CDSCO streamlined registration pathways reduce market entry friction for mid-tier instrument assemblers. Gujarat and Maharashtra industrial corridors develop polymer-composite retractor manufacturing for domestic outpatient center chains.
China
NMPA medical device classification rules reshape import substitution strategies for domestic electrosurgical generator production. Yangtze River Delta manufacturing zones scale stainless steel 316L instrument forging for cost-sensitive procedural segments. Beijing and Shanghai tertiary hospitals balance NMPA-approved robotic platform adoption against procurement budget constraints.
Global Surgical Instruments Market Competitive Environment
On the supply side, the industry is consolidating around integrated surgical ecosystems that bundle capital equipment, disposable instruments, and software services. Tiered competitive positioning separates end-to-end platform providers from specialized component fabricators and regional instrument assemblers. Three archetypes dominate: diversified medtech conglomerates with robotics portfolios, precision metalworking specialists with DIN-certified production, and emerging polymer-composite disposables manufacturers. M&A activity concentrates on navigation software capabilities and additive manufacturing competencies, while strategic partnerships bridge sterilization validation gaps across multinational kit suppliers.
Among diversified medtech conglomerates, Medtronic, Stryker Corporation, and Johnson & Johnson occupy positions spanning robotics, energy devices, and traditional handheld instruments. Medtronic exemplifies the end-to-end ecosystem archetype through its integrated surgical platform approach. Stryker Corporation represents orthopedic power tool and navigation specialization within the broader competitive set. Johnson & Johnson anchors the suturing and advanced energy device segment through its Ethicon portfolio. These three entities collectively illustrate how scale-driven manufacturers balance capital-intensive robotics segments against volume-driven disposable instrument lines.
| Leading Market Players |
|---|
| Medtronic |
| Stryker Corporation |
| Johnson & Johnson |
| B. Braun SE |
| Boston Scientific Corporation |
| Smith & Nephew |
| Zimmer Biomet Holdings |
| Olympus Corporation |
| BD |
| Others |
Value Chain & Pricing Dynamics
German Tuttlingen manufacturing clusters anchor precision forceps and microsurgical instrument supply, concentrating margin capture in DIN 58298-certified production networks while downstream hospital procurement consolidation erodes pricing power for non-certified assemblers. This upstream concentration funnels value toward quality-validated tiers and squeezes mid-tier competitors dependent on stainless steel 316L commodity feedstock.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with three-tier pricing stratification across premium titanium-alloy platforms, standard stainless steel instruments, and economy polymer-composite disposables. Price differentiation rests on ISO 13485 certification grade and volume scale, with ambulatory surgery centers exhibiting highest price sensitivity against academic medical centers. Cost compression in economy retractor lines intensifies because single-use polymer alternatives eliminate sterilization overhead.
Supply Chain Analysis
Stainless steel 316L feedstock draws from Indonesian and Philippine ore processing, with titanium sponge sourcing concentrated in Japan and Kazakhstan. Nickel price volatility and single-source electrosurgical generator dependency on three German component suppliers create concentration risk for mid-tier instrument assemblers. Distribution runs through integrated delivery network procurement hubs in the United States and hospital system central purchasing in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against single-use polymer-composite retractor platforms collapsing the economic case for traditional stainless steel reprocessing in high-volume orthopedic centers.
For Market Incumbents: Harden quality management system certification moats through accelerated ISO 13485 recertification investments before notified body backlogs extend further. Deepen backward integration into titanium additive manufacturing for patient-specific orthopedic cutting guides, neutralizing powder-bed fusion specialists threatening navigation ecosystem lock-in. For New Entrants and Emerging Players: Build out CDSCO-registered Class B electrosurgical device portfolios targeting Indian tier-2 hospital expansion beyond Mumbai and Delhi. The most penetrable white space sits in polymer-composite retractor manufacturing for Texas and Florida ambulatory surgery chains, with go-to-market execution through GPO contracts managers bypassing consolidated vendor ecosystems. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision metalworking specialists holding DIN 58298-certified Tuttlingen production capacity. Long-term viability over the mid-cycle horizon hinges on navigation software capabilities and additive manufacturing competencies as robotic platform integration fragments traditional handheld instrument supply chains. Watch FDA 510(k) predicate device pool narrowing as inflection signal for clearance timeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Pathway | Article 10 compliance mandates force clinical evidence portfolio consolidation for legacy electrosurgical SKUs. |
| Hospital System Partnership | Integrated delivery networks in California and Illinois standardize vendor contracts to leverage volume pricing. |
| Software Companion Development | AI-powered preoperative planning integration creates white space for instrument manufacturers with hybrid capabilities. |
| Reimbursement Strategy | Robotic-assisted procedure coding shifts determine capital equipment procurement priority in cardiothoracic service lines. |
| CE Marking Pathway | Notified body backlogs for Class IIa energy devices delay product launches by 8-14 months without priority queue access. |
Study Parameters
The analysis maps electrosurgery, robotics, handheld instruments, and laser technology segments, each validated through hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs leads. Primary interview insights triangulate against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up instrument volume modeling reconciles with top-down market sizing across the projection horizon.
Assumptions held fixed include regulatory pathway timelines and nickel feedstock cost trajectories, while robotic adoption rates and outpatient center expansion varied across scenarios. Segmentation dimensions encompass product type, application specialty, end-user facility tier, and energy modality. CAGRs derive from procedural volume elasticity to demographic aging and minimally invasive technique diffusion, with titanium additive manufacturing adoption curves and electrosurgical platform replacement cycles as key inputs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified medtech conglomerates or sudden CDSCO registration pathway shifts would shift outcomes. Cross-checking against hospital capital equipment budget disclosures and GPO contract award databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Global Urology Surgical Instruments Market
Surgical Instruments
Ischemic Stroke Surgery Market
Surgical Instruments
Japan General Surgical Devices Market
Surgical Instruments
Global Laparoscopic Instruments Market
Surgical Instruments
Electrosurgery Market
Surgical Instruments
Cheilectomy Market
Surgical Instruments
Brazil General Surgical Devices Market
Surgical Instruments
Monopolar Electrosurgery Instrument Market
Surgical Instruments
Minimally Invasive Thoracic Surgery Market
Surgical Instruments
Hemostatic Instruments Market
Surgical Instruments
Surgical Pliers Market
Surgical Instruments
Disposable Laparoscopic Instruments Market
Surgical Instruments
Surgical Drains Market
Surgical Instruments
Global Surgical Lasers Market
Surgical Instruments
Asia Pacific Surgical Equipment Market
Surgical Instruments
Surgical Lamps Market