
 Ophthalmic Drug Delivery Systems Market | 2026-2036
Ophthalmic Drug Delivery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmic Drug Delivery Systems Market Intelligence
Hospital formularies and specialty pharmacy networks are rewriting access patterns for advanced ocular therapies. Alcon Inc. leverages its surgical suite presence to anchor implantable delivery platforms within cataract and retinal procedure workflows. Santen Pharmaceutical Co. Ltd. competes through sustained-release innovation in glaucoma management, while EyePoint Pharmaceuticals Inc. specializes in micro-insert technology for posterior segment diseases.
Ophthalmic drug delivery systems encompass engineered platforms that administer therapeutic agents to ocular tissues through controlled release kinetics, achieving intraocular drug concentrations measured in nanograms per milliliter with dosing intervals extending from weeks to years. These systems serve the primary commercial purpose of overcoming physiological barriers such as tear film turnover, corneal epithelial tight junctions, and blood-retinal barrier selectivity that limit conventional topical and systemic administration. Eye drops remain the mature volume base, though margin pools increasingly concentrate in ocular implants where polymer matrix engineering commands premium positioning. Injectable delivery modes are gaining structural share as anti-VEGF biologics and corticosteroid formulations migrate from office-based bolus injection toward depot-based sustained release platforms.
FDA combination product regulations, EMA MDR requirements for active implantable devices, and ISO 10993 biocompatibility standards collectively shape product development timelines, sterilization validation protocols, and clinical evidence thresholds for market authorization. These frameworks elevate capital requirements for new entrants while creating durable competitive moats around established manufacturing quality systems. Stakeholders must monitor evolving FDA guidance on in-situ forming implants and real-world evidence requirements for sustained-release efficacy claims as reimbursement authorities tighten value demonstration standards.
Market Dynamics
Sustained-release polymer engineering is compressing dosing frequency from monthly injections to multi-year implants, forcing manufacturers to rebuild clinical trial infrastructure around long-horizon efficacy endpoints rather than acute pharmacokinetic measures.
Growth Catalysts
- Anti-VEGF biologics:Ranibizumab and aflibercept formulations are migrating toward depot-based platforms, pulling implantable delivery systems into standard-of-care protocols for wet age-related macular degeneration.
- MDR compliance deadlines:The European Medical Device Regulation's 2024-2026 transition window is accelerating hospital procurement of CE-marked active implantable devices ahead of legacy certificate expiration.
- Medicare reimbursement maturation:United States payment pathways for office-based intravitreal procedures now cover sustained-release alternatives, expanding formulary access beyond academic medical centers into community ophthalmology practices.
Market Restraints
- Silicone oil and platinum catalyst costs:Input material volatility for intravitreal tamponade formulations compresses margin pools on vitreoretinal surgical packs.
- Polymer foundry concentration:Specialty PLGA and PCL resin production clusters in Germany and Japan create single-source vulnerability for microsphere and rod implant manufacturers.
- Blood-retinal barrier selectivity:The tight junction architecture of retinal pigment epithelium limits molecular weight thresholds for passive diffusion, excluding large-molecule biologics from certain platform designs.
Strategic Opportunities
- Gene therapy vector delivery:Adeno-associated virus payloads for inherited retinal diseases require precision dosing kinetics that conventional bolus injection cannot achieve, opening white space for programmable release implants.
- Office-based surgical suites:Ambulatory surgery center networks in the United States are expanding capacity for micro-invasive glaucoma surgery, creating channel access for sustained-release trabecular meshwork implants.
- ISO 10993-6 biocompatibility harmonization:Emerging consensus on implant irritation testing protocols is reducing regulatory friction for multi-market submissions, compressing time-to-authorization for polymer matrix platforms.
Industry Challenges
- Sterile manufacturing scale-up:Aseptic filling of preloaded intraocular delivery devices requires ISO 5 cleanroom infrastructure that demands eight-figure capital deployment per production line.
- Long-horizon clinical evidence generation:Five-year safety and efficacy datasets for sustained-release implants extend development timelines beyond typical private-equity holding periods, constraining funding sources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmic Drug Delivery Systems Market |
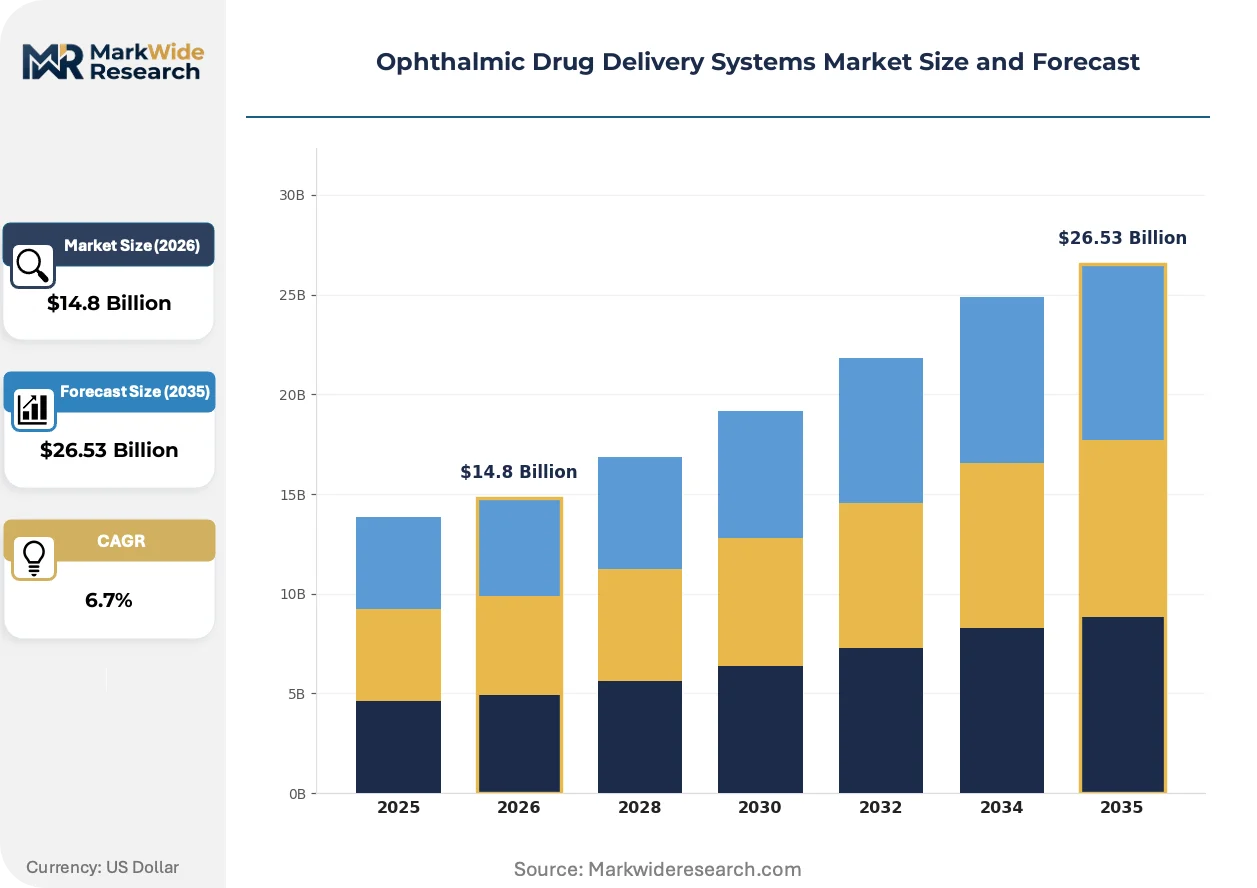
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eye Drops, Ocular Implants, Punctal Plugs, Nanoparticles Delivery Mode: Topical, Injectable, Sustained Release, Iontophoresis Therapy Area: Glaucoma, Inflammation, Infection, Dry Eye End User: Hospitals, Clinics, Pharmacies, Homecare |
| Companies Covered | Ocular Therapeutix Inc., Allergan plc, Santen Pharmaceutical Co. Ltd., Alcon Inc., Bausch + Lomb, Novartis AG, EyePoint Pharmaceuticals Inc., Clearside Biomedical Inc., Envisia Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmic Drug Delivery Systems Market Strategic Shifts & Innovations
Digital twin modeling of ocular pharmacokinetics is compressing formulation development cycles, enabling polymer engineers to simulate drug release profiles before committing to animal studies. This shift is redistributing R&D expenditure from bench work toward computational infrastructure.
Microfluidic manufacturing of polymeric microparticles is virtualizing traditional batch-processing economics. Platform developers in the United States and Switzerland are adopting continuous-flow reactors to achieve tighter particle size distributions for intravitreal suspensions. This technology is virtualizing the scale-up pathway that previously required dedicated pilot plants for each formulation variant.
The FDA's evolving guidance on in-situ forming implants is tightening evidentiary standards for depot formation kinetics and biodegradation byproduct clearance. Manufacturers must now submit real-world pharmacokinetic data from explanted tissue samples, elevating post-market surveillance obligations. Sustained-release corticosteroid formulations for diabetic macular edema face the steepest compliance burden under this framework.
Hospital pharmacy committees are consolidating vendor relationships for implantable ocular devices, displacing the fragmented purchasing patterns that previously allowed multiple sustained-release platforms to coexist within single institutions. This concentration is most visible in United States academic medical centers, where formulary slots for glaucoma drainage devices now require head-to-head cost-effectiveness evidence against established trabeculectomy protocols.
Ophthalmic Drug Delivery Systems Market Segmentation
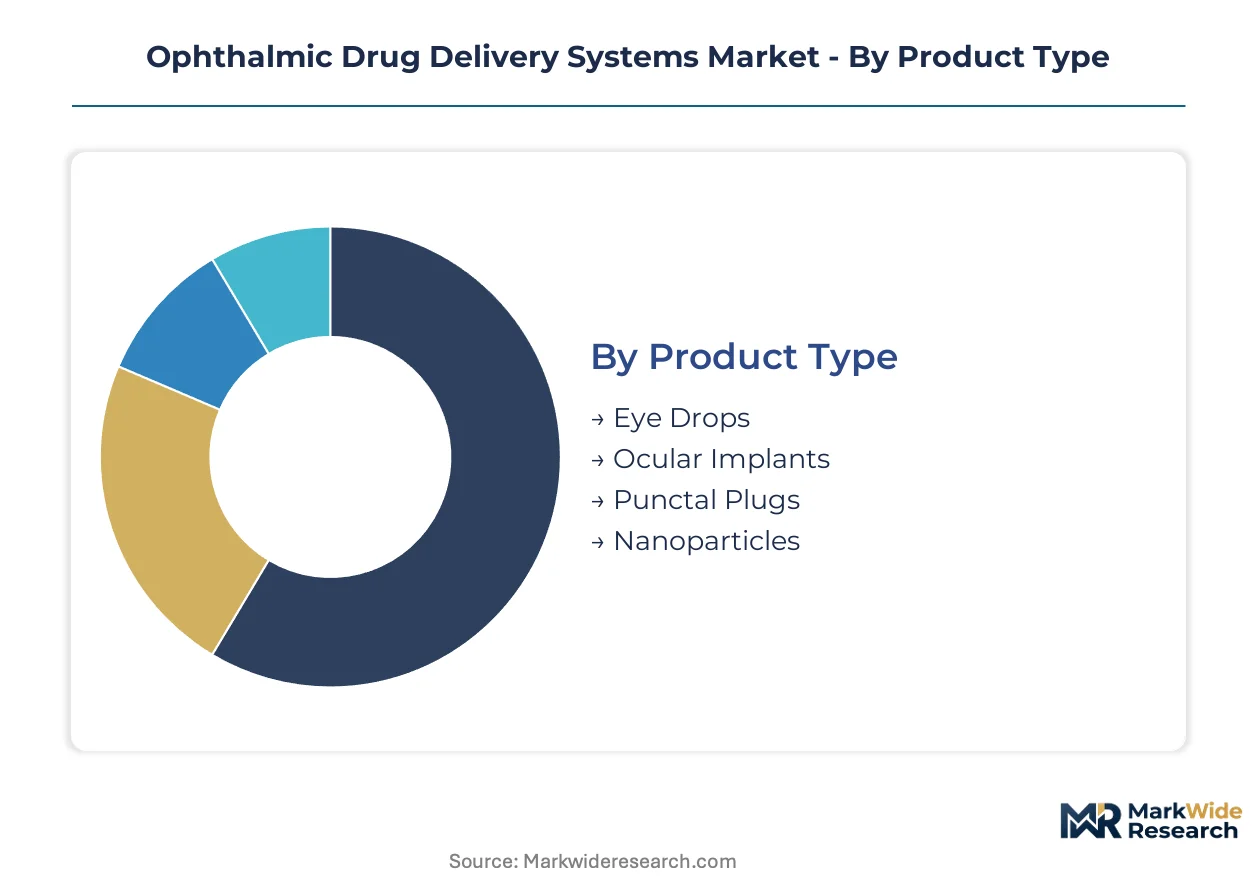
Segmentation in ophthalmic drug delivery reveals how physiological barriers and treatment settings fragment commercial opportunity. Each dimension—product form, administration route, disease target, and care setting—carries distinct regulatory pathways and margin structures that shape manufacturer strategy.
Product Type:
Mature liquid formulations dominate prescription volume while engineered implants capture expanding margin pools through polymer innovation.
- Eye Drops:Aqueous and emulsion-based solutions remain the default first-line therapy across anterior segment diseases. Community ophthalmology practices in the United States prescribe preserved and preservative-free formulations for chronic glaucoma and dry eye management, though tear film drainage limits bioavailability to under 5%.
- Ocular Implants:Biodegradable polymer rods and reservoir devices achieve therapeutic drug levels for months to years through controlled erosion kinetics. Academic medical centers in Germany and Japan are expanding formulary access for intravitreal dexamethasone and fluocinolone acetonide implants as alternatives to repeated anti-VEGF injections.
- Punctal Plugs:Silicone or collagen inserts block nasolacrimal drainage to extend ocular surface drug residence. The devices serve moderate dry eye populations where punctal occlusion augments topical therapy.
- Nanoparticles:Lipid and polymeric carriers under 200 nanometers penetrate corneal epithelial tight junctions for posterior segment targeting. Early-stage formulations are advancing through FDA pre-IND consultation for retinal disease applications.
Eye Drops handles the majority of throughput; Ocular Implants is expanding most quickly on share.
Delivery Mode:
Cost tier separation runs from inexpensive topical administration to capital-intensive sustained-release platforms requiring surgical placement.
- Topical:Direct instillation onto the ocular surface serves anterior segment indications through patient self-administration. The mode dominates glaucoma therapy in United States community practices where reimbursement favors prescription refills over procedural interventions.
- Injectable:Intravitreal and subconjunctival bolus injections deliver therapeutic concentrations to posterior and anterior chambers. Retinal specialists in Switzerland and the United Kingdom perform anti-VEGF injections in office-based settings, driving demand for pre-filled syringe formats.
- Sustained Release:Depot formulations release drug through polymer matrix degradation or osmotic pumping over extended intervals. The category commands premium positioning as Medicare reimbursement pathways mature for intravitreal implant procedures.
- Iontophoresis:Electrically-assisted drug transport across ocular barriers enables non-invasive posterior segment delivery. The technology remains confined to specialist centers in France and Germany pending broader EMA guidance on active device classification.
Topical administration retains the highest prescription count; Sustained Release is climbing the fastest on procedural reimbursement expansion.
Therapy Area:
Application urgency varies from chronic disease management to acute infection control, reshaping pricing power and clinical trial design.
- Glaucoma:Chronic intraocular pressure reduction requires lifelong medication adherence. Sustained-release bimatoprost implants are gaining traction in United States ambulatory surgery centers where micro-invasive glaucoma surgery combines device placement with cataract extraction.
- Inflammation:Uveitis and post-surgical inflammation demand rapid corticosteroid suppression with controlled taper. Intravitreal fluocinolone acetonide implants serve recurrent non-infectious posterior uveitis in academic medical centers across Japan and Germany.
- Infection:Bacterial and fungal keratitis requires high-concentration antimicrobial delivery to avascular corneal tissue. Compounded fortified drops remain standard, though collagen shield delivery is emerging for severe keratitis cases.
- Dry Eye:Chronic ocular surface disease drives cyclosporine and lifitegrast prescription volume. Punctal plugs and lipid-based nanoemulsions compete for moderate-to-severe cases in United States specialty pharmacy networks.
Glaucoma manages the largest chronic patient population; Inflammation is gaining share fastest on biologic implant adoption.
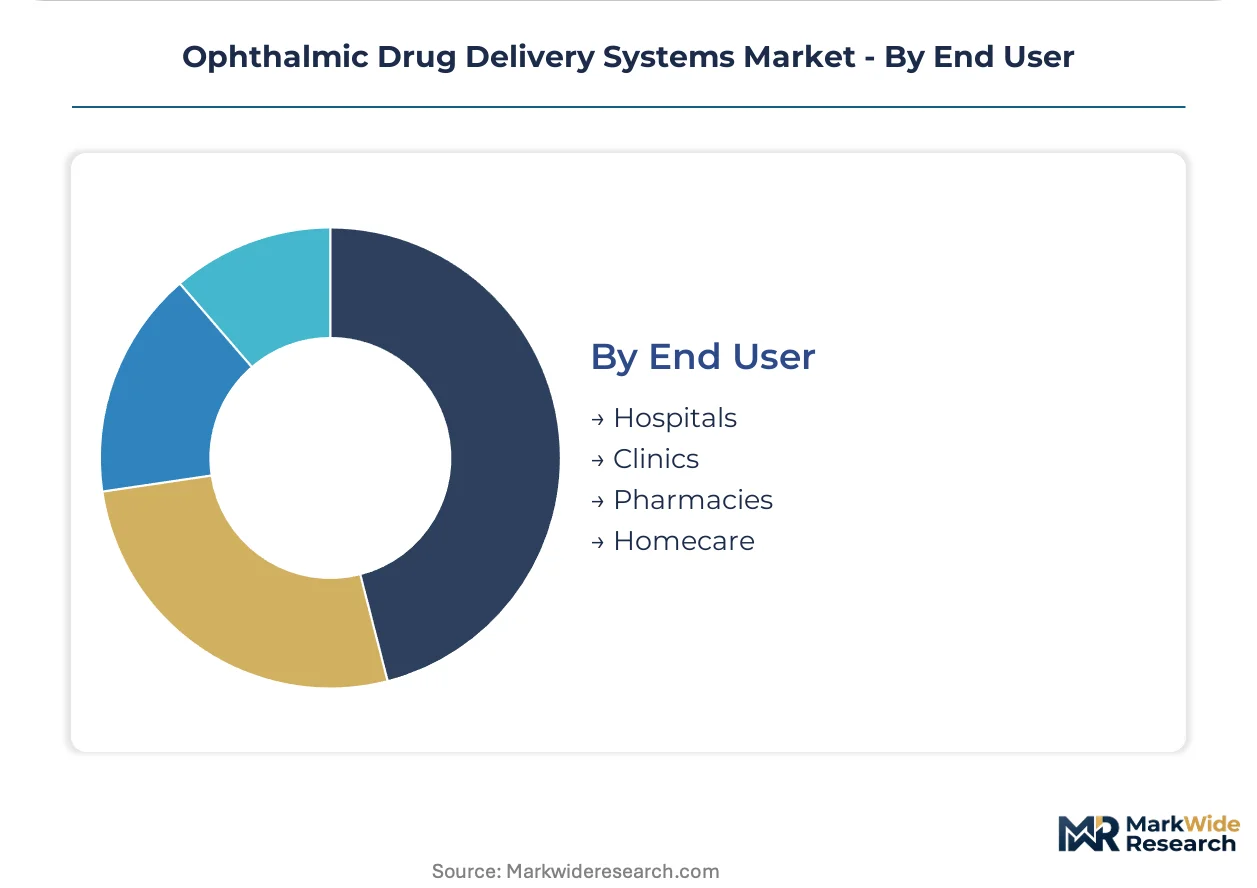
End User:
Customer type determines procurement sophistication, with hospital formularies applying stricter evidence standards than retail channels.
- Hospitals:Inpatient and outpatient surgical departments control access to implantable devices through pharmacy and therapeutics committees. United States academic medical centers are consolidating vendor relationships for sustained-release platforms, requiring head-to-head cost-effectiveness data.
- Clinics:Office-based ophthalmology practices perform the majority of intravitreal injections and glaucoma laser procedures. Medicare reimbursement maturation for sustained-release alternatives is expanding formulary access beyond hospital-owned facilities.
- Pharmacies:Retail and specialty pharmacy channels distribute topical formulations and limited device categories. United States Medicare Part D coverage shapes patient out-of-pocket exposure for chronic glaucoma therapies.
- Homecare:Self-administered drop regimens and punctal plug maintenance extend therapy beyond clinical settings. Patient adherence programs through specialty pharmacies in Germany are improving persistence rates for chronic dry eye management.
Hospitals concentrate the highest-value implant procedures; Clinics are expanding fastest on ambulatory surgical migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure anchors European distribution for temperature-sensitive ocular implants, while direct rail links from Basel to Frankfurt sustain just-in-time resin supply for polymer foundries serving device manufacturers.
United States
Medicare reimbursement maturation for office-based intravitreal procedures drives ambulatory surgery center expansion across Florida and Texas. FDA combination product guidance tightens evidentiary standards for sustained-release depot kinetics. The Research Triangle Park cluster in North Carolina concentrates contract manufacturing for biodegradable polymer rods.
Germany
Hospital pharmacy committees in Bavaria and Baden-Württemberg consolidate vendor relationships for glaucoma drainage devices. EMA MDR transition deadlines accelerate CE-mark procurement ahead of legacy certificate expiration. The Rhine-Main metropolitan region hosts specialty PLGA resin production for microsphere implant manufacturers.
Japan
PMDA priority review vouchers for novel ophthalmic delivery platforms compress approval timelines for sustained-release innovations. Aging demographics expand the addressable patient base for chronic glaucoma and AMD therapies. The Kansai corridor between Osaka and Kobe concentrates precision molding capacity for intraocular delivery devices.
Switzerland
Swissmedic's alignment with EMA MDR requirements streamlines parallel submission pathways for active implantable devices. Geneva-based health technology assessment bodies demand head-to-head cost-effectiveness evidence against standard-of-care injections. The Basel-Zurich axis anchors polymer engineering R&D for extended-release ocular platforms.
India
CDSCO's accelerated approval pathway for orphan ophthalmic indications attracts contract research for inherited retinal disease vectors. Domestic manufacturing incentives under PLI schemes expand sterile filling capacity for preloaded intraocular devices. The Hyderabad-Bengaluru corridor develops active pharmaceutical ingredient supply for corticosteroid implant formulations.
Ophthalmic Drug Delivery Systems Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying polymer matrices, reservoir membranes, and precision-molded delivery hardware. The vendor base stratifies across three tiers: multinational surgical suite anchors with formulary gatekeeper status, mid-cap sustained-release specialists with single-indication depth, and contract development shops offering white-label polymer engineering. Competitive moves concentrate on sterile manufacturing scale-up through dedicated cleanroom infrastructure and long-horizon clinical evidence generation through extended follow-up registries.
Among the named players, Alcon Inc. and Santen Pharmaceutical Co. Ltd. exemplify platform integrators with surgical workflow anchoring capabilities, while EyePoint Pharmaceuticals Inc. occupies a position as a sustained-release specialist with micro-insert technology depth. These three represent distinct archetypes: the capital equipment incumbent leveraging suite presence, the regional pharmaceutical house with polymer innovation focus, and the targeted delivery pure-play with indication-specific platforms.
| Leading Market Players |
|---|
| Ocular Therapeutix Inc. |
| Allergan plc |
| Santen Pharmaceutical Co. Ltd. |
| Alcon Inc. |
| Bausch + Lomb |
| Novartis AG |
| EyePoint Pharmaceuticals Inc. |
| Clearside Biomedical Inc. |
| Envisia Therapeutics |
| Others |
Cost & Logistics Intelligence
The Rhine-Main metropolitan region in Germany anchors specialty PLGA resin production for microsphere implant manufacturers, concentrating polymer foundry capacity that feeds downstream pricing power to device makers serving United States academic medical centers and Japanese hospital pharmacy committees.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates sustained-release implants from pre-filled syringes from conventional eye drops. Price differentiation hinges on ISO 10993-6 biocompatibility certification tier and sterile manufacturing scale. Pricing pressure stems from silicone oil and platinum catalyst input volatility compressing margin pools on vitreoretinal surgical packs. Community ophthalmology practices in the United States exhibit highest price sensitivity; hospital formulary gatekeepers at academic medical centers demonstrate lowest sensitivity due to bundled procedural reimbursement.
Supply Chain Analysis
Tariff exposure between Germany and Japan dominates supply chain risk planning for PLGA and PCL resin procurement. Specialty polymer production clusters in Germany, Japan, and the United States anchor upstream supply. Raw material dependencies include medical-grade silicone oil, platinum catalysts, and biodegradable polyester resins. Single-source vulnerability from concentrated foundry output creates disruption exposure. Distribution runs through hospital pharmacy committees and ambulatory surgery center networks in the United States, with cold chain logistics from Rotterdam sustaining European implant delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation across United States academic medical centers is shifting buyer power toward formulary gatekeepers, compressing vendor slots and demanding head-to-head cost-effectiveness evidence for sustained-release platforms.
For Market Incumbents: Harden sterile manufacturing quality systems against FDA evolving guidance on in-situ forming implants. Deepen backward integration into polymer resin supply through captive production or long-term offtake agreements with Rhine-Main foundries. Defend formulary position by generating five-year safety registries that exceed private-equity holding period constraints facing emerging competitors.
For New Entrants and Emerging Players: Pursue gene therapy vector delivery white space where programmable release kinetics for adeno-associated virus payloads remain underserved. Target ambulatory surgery center networks in Florida and Texas where Medicare reimbursement maturation expands channel access beyond hospital-owned facilities. Lead with microfluidic manufacturing partnerships to bypass dedicated pilot plant capital requirements.
For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because hospital pharmacy committee vendor consolidation favors scale players with sterile ISO 5 cleanroom infrastructure and multi-indication sustained-release portfolios. Acquisition target archetype: mid-cap sustained-release specialists with single-indication depth and explant tissue pharmacokinetic datasets. Watch FDA real-world evidence requirements for sustained-release efficacy claims as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR transition deadlines accelerate procurement of active implantable devices ahead of legacy certificate expiration. |
| Hospital System Partnership | Academic medical center formulary consolidation demands head-to-head cost-effectiveness evidence against trabeculectomy protocols. |
| Manufacturing Scale-Up | ISO 5 cleanroom infrastructure requires eight-figure capital deployment per aseptic filling production line. |
| Reimbursement Strategy | Medicare pathway maturation for office-based intravitreal procedures expands formulary access into community ophthalmology. |
| Software Companion Development | Digital twin modeling of ocular pharmacokinetics redistributes R&D expenditure toward computational infrastructure. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with regulatory affairs leads, formulary directors, hospital procurement managers, and biomedical engineers; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up segmentation modeling triangulated against top-down market sizing from trade flow analysis and CMS Medicare reimbursement data.
Forecast inputs span product type, delivery mode, therapy area, and end user segments across the projection horizon. CAGRs derive from patient population epidemiology, procedure volume trajectories, and pricing elasticity assumptions for sustained-release platforms versus conventional bolus injection alternatives. The analytical framework incorporates anti-VEGF biologic migration patterns and MDR compliance deadline impacts.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement policy, polymer resin commodity pricing, or FDA combination product guidance would shift the trajectory. Material shifts in blood-retinal barrier penetration technology or gene therapy regulatory pathways would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Oral Contraceptive Pills Market
Pharmaceuticals
Latin America Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Hydroxychloroquine Market
Pharmaceuticals
Seropositive Rheumatoid Arthritis Drug Market
Pharmaceuticals
Osteoarthritis Drugs Market
Pharmaceuticals
Global Azithromycin Market
Pharmaceuticals
Global Fibrinogen Concentrates Market
Pharmaceuticals
Hard Empty HPMC Capsule Market
Pharmaceuticals
Indonesia Oral Anti-Diabetic Drug Market
Pharmaceuticals
Stye Drug Market
Pharmaceuticals
Ocular Excipients Market
Pharmaceuticals
Leukotriene Inhibitors Market
Pharmaceuticals
Anticonvulsants Market
Pharmaceuticals
Global Varicella Vaccine Market
Pharmaceuticals
India Pharmaceutical Market
Pharmaceuticals
Nefopam Hydrochloride Injection Market