
 Global Azithromycin Market | 2026-2036
Global Azithromycin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Azithromycin Market Foresight
Hospital procurement concentration is hardening as health systems in Brazil, Nigeria, and Vietnam consolidate antibiotic purchasing under centralized tenders. Pfizer leverages its branded Zithromax heritage to sustain premium positioning in markets where originator recognition still commands formulary access. Sandoz anchors European generic substitution through its vertically integrated cephalosporin and macrolide manufacturing network. Teva Pharmaceutical Industries Ltd. competes aggressively on price in North American retail channels where pharmacy benefit managers drive macrolide tier placement.
Azithromycin is a semisynthetic 15-membered macrolide antibiotic with a methyl-substituted nitrogen in the lactone ring, formulated as dihydrate or trihydrate salts for oral and parenteral administration. It inhibits bacterial protein synthesis by binding to the 50S ribosomal subunit, delivering tissue-penetrating concentrations for respiratory, skin, and sexually transmitted infection therapy. Tablet formulations dominate volume due to stability advantages and patient compliance in outpatient settings, while injection presentations capture higher per-unit margins in hospitalized sepsis and pneumonia protocols. Suspension demand accelerates in pediatric populations where swallowing barriers limit solid-dose adoption. Eye drops remain a niche segment constrained by ophthalmic formulation complexity and preservative compatibility requirements.
FDA bioequivalence standards and EMA Good Manufacturing Practice inspections shape API sourcing decisions, with non-compliance triggering import alerts that disrupt supply continuity. WHO Prequalification Programme criteria increasingly determine eligibility for government procurement tenders across sub-Saharan Africa and Southeast Asia. India's CDSCO manufacturing licensing and China's NMPA environmental compliance enforcement add further regulatory layers that filter supplier participation. Stakeholders must monitor evolving antimicrobial stewardship protocols that restrict empirical macrolide prescribing and assess how resistance surveillance data reshape reimbursement and formulary access for azithromycin relative to respiratory fluoroquinolones and tetracyclines.
Market Dynamics
Hospital formulary consolidation across emerging markets is compressing supplier margins while amplifying volume concentration, as centralized antibiotic tenders in Brazil, Nigeria, and Vietnam favor manufacturers with integrated API-to-finished-dose capabilities and multi-site regulatory approvals.
Growth Catalysts
- WHO Prequalification Programme:Expanded eligibility criteria for government procurement tenders across sub-Saharan Africa and Southeast Asia are opening access channels for qualified generic manufacturers.
- Pediatric suspension formulations:Rising demand for liquid dosage forms in low- and middle-income countries addresses swallowing barriers and expands addressable patient populations.
- India:CDSCO manufacturing licensing reforms and domestic API production scale are strengthening cost-competitive export positions into regulated markets.
Market Restraints
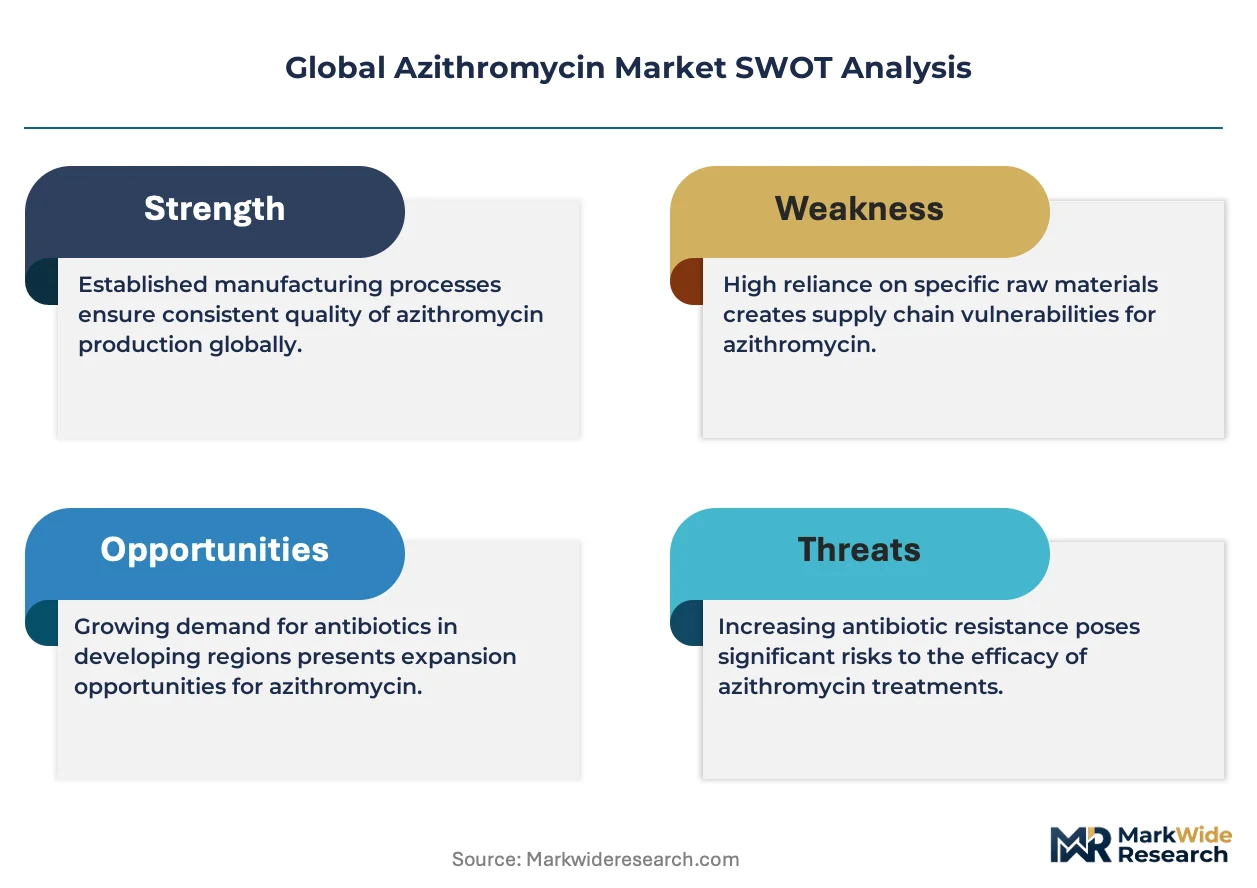
- Azalide resistance surveillance:Expanding macrolide resistance in Streptococcus pneumoniae populations is triggering antimicrobial stewardship protocols that restrict empirical prescribing.
- FDA bioequivalence requirements:Stringent dissolution and pharmacokinetic standards for generic azithromycin dihydrate tablets are extending ANDA approval timelines and raising development costs.
- China NMPA environmental enforcement:Tightened wastewater discharge standards for antibiotic API fermentation are forcing facility upgrades and production rationalization among bulk manufacturers.
Strategic Opportunities
- Vietnam:Underpenetrated hospital procurement systems and rising respiratory infection burden create first-mover advantages for vertically integrated suppliers establishing local distribution.
- Ophthalmic azithromycin:Preservative-compatible aqueous formulations for bacterial conjunctivitis represent a margin-accretive niche with limited current competition.
- EU F-Gas Regulation:Phase-down of hydrofluorocarbon propellants in metered-dose inhalers is redirecting respiratory antibiotic development resources toward dry-powder and nebulized macrolide alternatives.
Industry Challenges
- EMA GMP inspection backlog:Extended lead times for on-site manufacturing audits are delaying market authorizations and freezing supply expansion plans for European entry.
- Legacy quality management system upgrades:Transition from paper-based batch records to electronic data integrity platforms requires substantial validation expenditure and temporary productivity losses.
- API supply requalification:Forced switches between azithromycin base suppliers due to import alerts trigger costly stability studies and bioequivalence bridging trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Azithromycin Market |
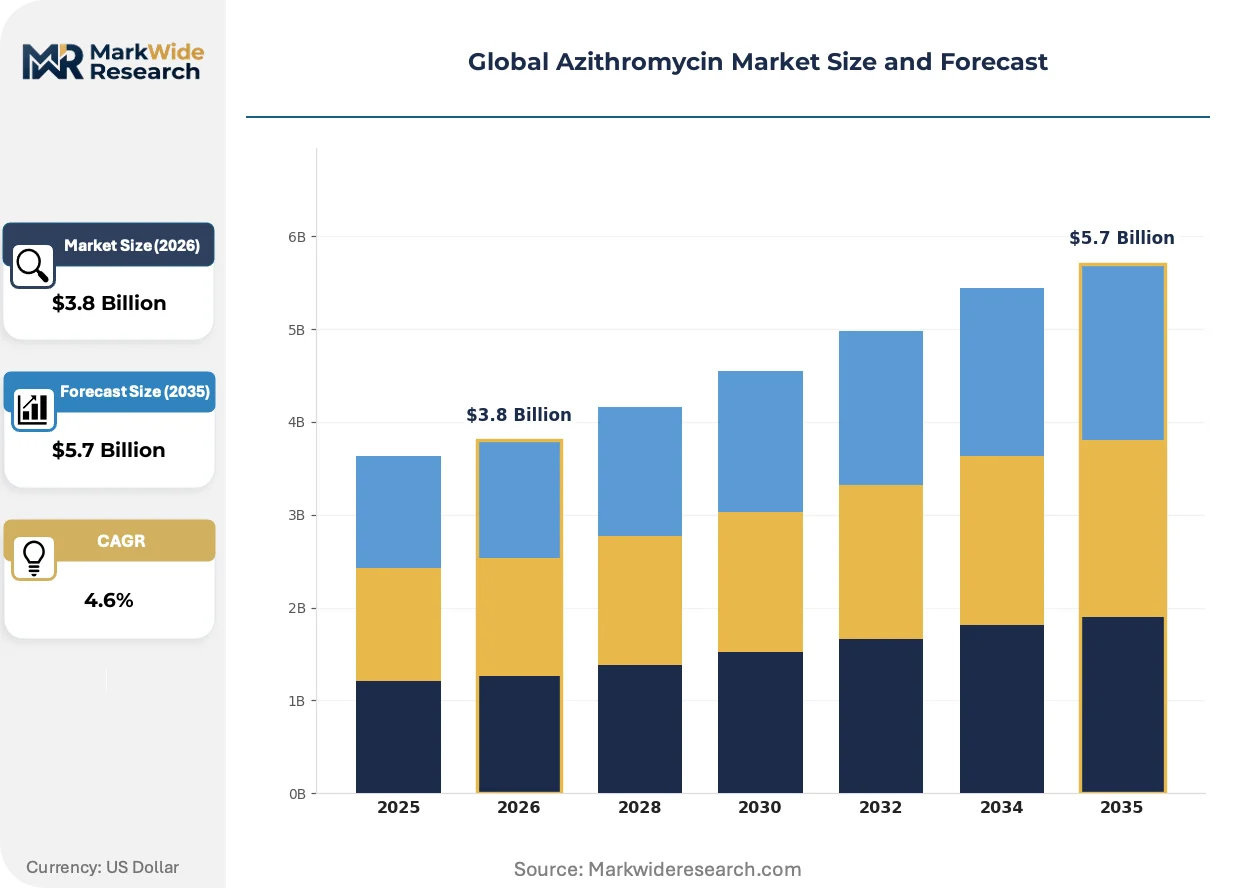
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Suspension, Injection, Capsule, Eye Drops Therapy Area: Respiratory Tract Infection, Skin Infection, Ear Infection, Sexually Transmitted Diseases, Gastrointestinal Infection End User: Hospitals, Clinics, Ambulatory Surgical Centers, Diagnostic Laboratories Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Sales |
| Companies Covered | Pfizer, Sandoz, Teva Pharmaceutical Industries Ltd., Alembic Pharmaceuticals, Aurobindo Pharma, Lupin, Wockhardt, CSPC Pharmaceutical Group Ltd., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Azithromycin Market Shifts & Advancements
Continuous manufacturing technologies and real-time release testing are compressing batch cycle times while antimicrobial stewardship protocols are reshaping prescribing algorithms across inpatient and outpatient settings.
Hot-melt extrusion is unifying amorphous solid dispersion production for enhanced azithromycin bioavailability in fixed-dose combination therapies. European generic manufacturers are adopting this platform to differentiate against commodity tablet suppliers. The technology is unifying process analytical technology with quality-by-design frameworks, collapsing traditional separate-unit operations into single continuous lines.
EMA's revised GMP Annex 1 for sterile medicinal products is mandating barrier isolation technology and single-use systems in parenteral azithromycin manufacturing. Facility retrofit costs are concentrating intravenous production among capitalized multinationals. Hospital purchasers in Germany and France are prioritizing suppliers with certified containment infrastructure, shifting tender evaluation weights toward manufacturing quality scores.
Centralized hospital procurement is displacing fragmented distributor networks in Brazil's public health system. State-level consortiums are aggregating antibiotic demand into multi-year framework agreements with price-volume mechanisms. São Paulo and Minas Gerais health secretariats are piloting direct manufacturer contracting, bypassing traditional wholesale markups and forcing logistics providers to unbundle distribution from commercial representation.
Global Azithromycin Market Segmentation
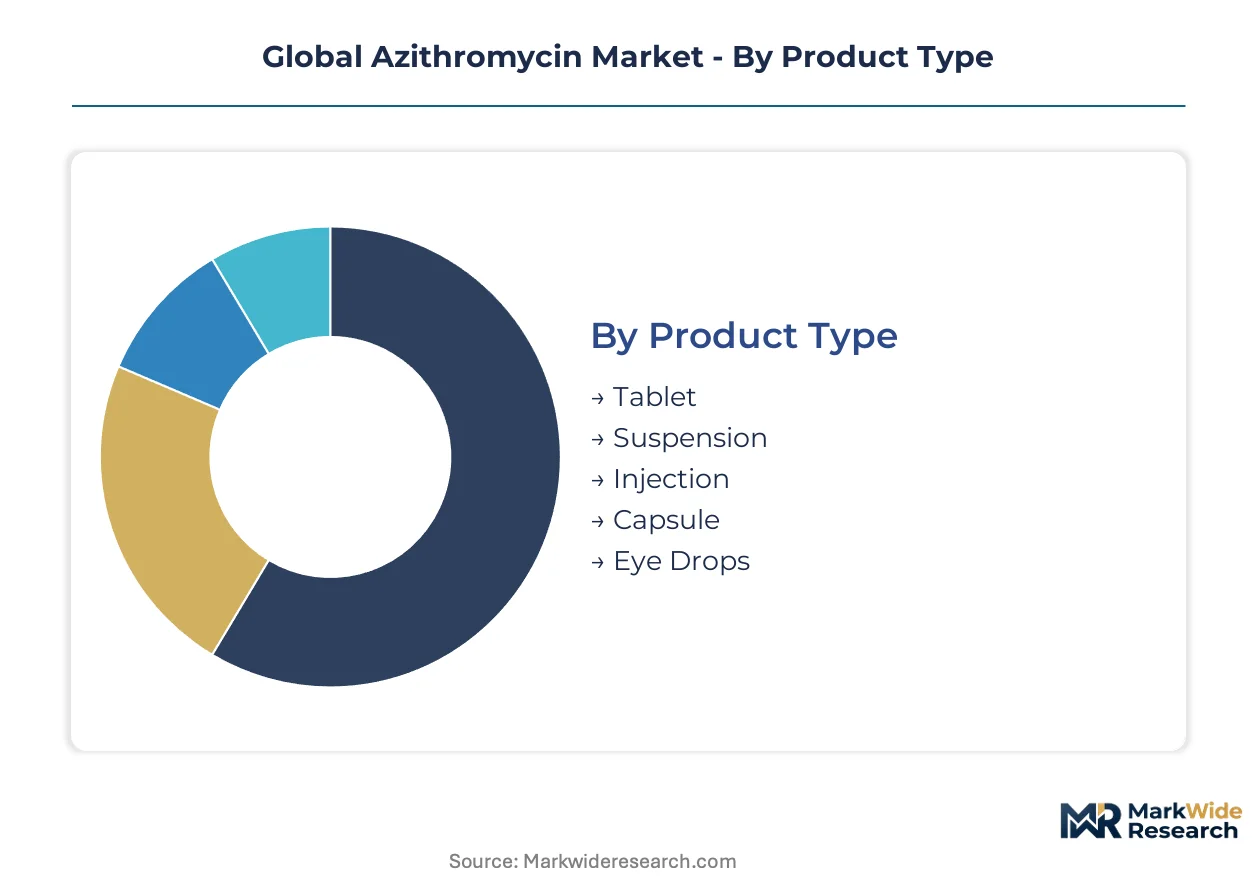
Azithromycin market segmentation reveals divergent margin structures across dosage forms and therapy areas. Supply-side capabilities and regulatory positioning vary sharply by channel, creating distinct competitive battlegrounds for manufacturers seeking volume versus premium positioning.
Product Type:
Manufacturing complexity and stability requirements concentrate API supply for high-volume solid doses among Indian and Chinese producers with integrated fermentation-to-finish capabilities.
- Tablet:Dihydrate and trihydrate salt formulations dominate outpatient prescribing for respiratory and skin infections. Hospital procurement tenders in Brazil and Vietnam favor tablet suppliers with FDA-approved ANDAs and multi-year stability data packages.
- Suspension:Liquid pediatric formulations address swallowing barriers in low- and middle-income countries. CDSCO-licensed Indian manufacturers are expanding suspension output for WHO Prequalification Programme eligibility across sub-Saharan Africa.
- Injection:Parenteral presentations command hospital formulary placement for severe pneumonia and sepsis protocols.
- Capsule:Alternative solid-dose option with limited differentiation from tablet equivalents.
- Eye Drops:Ophthalmic formulations face preservative compatibility constraints and specialized GMP requirements.
Today's leader: Tablet. Tomorrow's challenger: Suspension.
Therapy Area:
Antimicrobial stewardship protocols are reshaping empirical prescribing patterns differently across infection sites, with respiratory applications facing the steepest restriction pressure.
- Respiratory Tract Infection:Community-acquired pneumonia and acute bacterial sinusitis represent the largest addressable patient populations. Rising macrolide resistance in Streptococcus pneumoniae is triggering stewardship restrictions in Germany and France.
- Skin Infection:Cellulitis and impetigo applications benefit from azithromycin's tissue-penetrating pharmacokinetics. Outpatient dermatology clinics in the US drive retail pharmacy volume for short-course regimens.
- Ear Infection:Pediatric otitis media prescribing concentrates in primary care settings with high generic substitution rates.
- Sexually Transmitted Diseases:Chlamydia and gonorrhea combination protocols face protocol competition from cephalosporins.
- Gastrointestinal Infection:Traveler's diarrhea applications are declining due to fluoroquinolone and rifaximin alternatives.
Respiratory Tract Infection maintains volume dominance. Skin Infection is gaining share fastest as stewardship spares dermatology prescribing.
End User:
Procurement centralization is hardening price-volume mechanisms across institutional channels while retail and direct channels preserve margin for differentiated formulations.
- Hospitals:Centralized antibiotic tenders in São Paulo and Minas Gerais aggregate demand under multi-year framework agreements. EMA GMP inspection backlogs are freezing European hospital supply expansion for new entrants.
- Clinics:Outpatient facilities in Nigeria and Vietnam drive suspension demand for pediatric populations with limited cold-chain requirements.
- Ambulatory Surgical Centers:Prophylactic dosing protocols favor single-dose azithromycin for surgical site infection prevention.
- Diagnostic Laboratories:Limited direct procurement role; primarily influences prescribing through resistance surveillance data.
Hospitals anchor institutional volume. Clinics represent the steepest expansion trajectory as primary care networks densify in emerging markets.
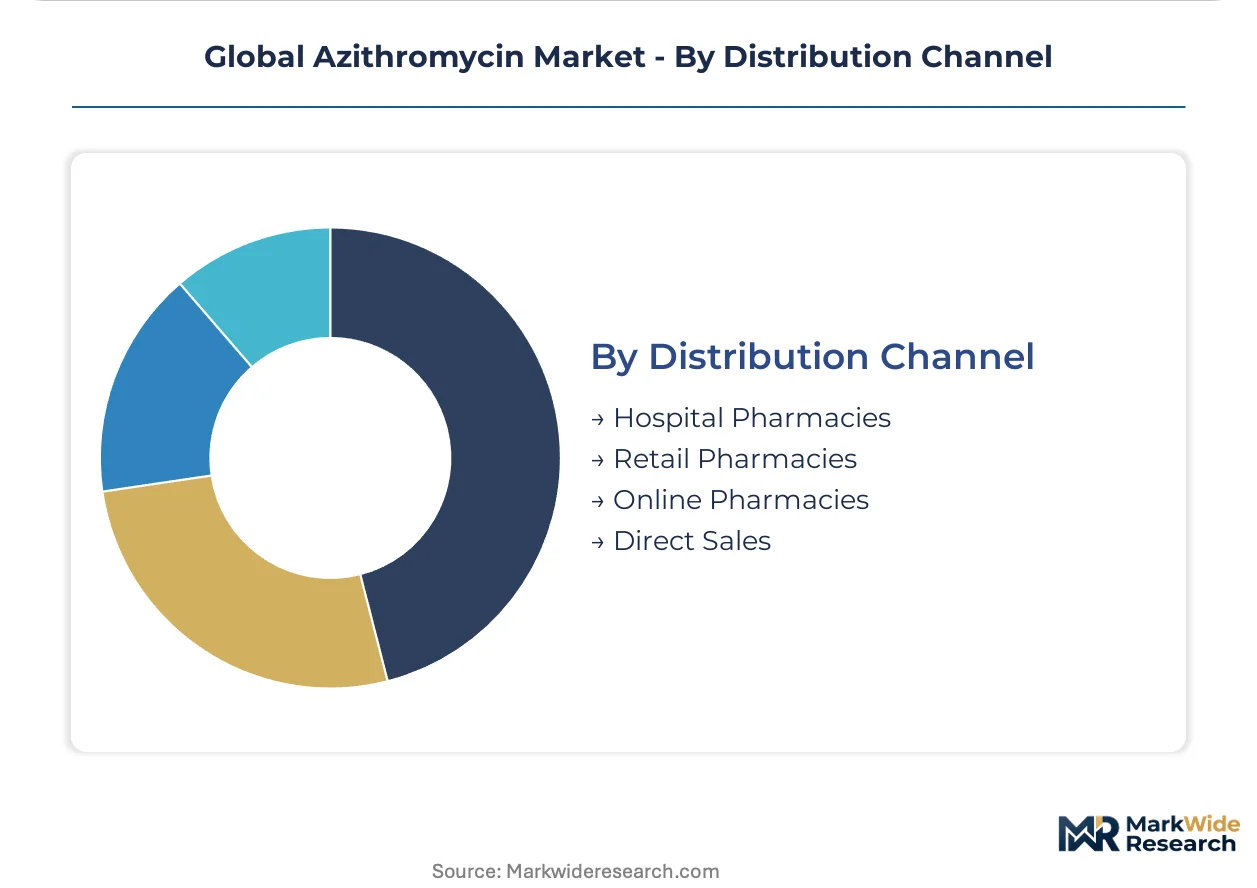
Distribution Channel:
Channel margin structures reflect regulatory burden and logistics complexity, with hospital pharmacies capturing volume concentration and online channels penetrating price-sensitive retail segments.
- Hospital Pharmacies:State-level consortiums in Brazil bypass wholesale markups through direct manufacturer contracting. Suppliers with certified barrier isolation technology score higher in German and French tender evaluations.
- Retail Pharmacies:Pharmacy benefit managers in North America drive macrolide tier placement through formulary exclusion lists.
- Online Pharmacies:E-commerce penetration accelerates in India where CDSCO track-and-trace requirements are tightening.
- Direct Sales:Limited to tender-based institutional procurement with specialized logistics requirements.
Hospital Pharmacies dominate value capture. Online Pharmacies are reshaping competitive positioning in price-transparent retail environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical formulation chemists and API fermentation specialists cluster in manufacturing hubs across India, China, and select European markets. Regulatory compliance expertise concentrates in jurisdictions with stringent GMP enforcement, creating talent scarcity in emerging production centers.
India
Domestic API-to-finished-dose integration strengthens export competitiveness into regulated markets. CDSCO manufacturing licensing reforms compress approval timelines for WHO Prequalification Programme eligibility. Hyderabad and Ahmedabad clusters expand suspension formulation capacity for pediatric supply contracts across sub-Saharan Africa.
China
Environmental compliance enforcement at antibiotic API fermentation facilities drives production rationalization among bulk manufacturers. NMPA wastewater discharge standards force facility upgrades that filter supplier participation. Shijiazhuang and Zhejiang manufacturing bases consolidate output among capitalized producers with captive environmental treatment infrastructure.
Germany
Hospital procurement prioritizes suppliers with certified barrier isolation technology for parenteral presentations. EMA GMP inspection backlogs delay market authorizations for new entrants seeking European hospital formulary placement. Frankfurt and Munich distribution hubs anchor centralized tender fulfillment for state-level consortiums.
Brazil
State-level health secretariats pilot direct manufacturer contracting to bypass traditional wholesale markups. ANVISA regulatory alignment with FDA bioequivalence standards shapes generic substitution protocols. São Paulo and Minas Gerais health systems aggregate antibiotic demand under multi-year framework agreements with price-volume mechanisms.
Vietnam
Underpenetrated hospital procurement systems and rising respiratory infection burden create first-mover opportunities. Local distribution partnerships determine tender access as centralized purchasing displaces fragmented networks. Ho Chi Minh City and Hanoi medical centers drive suspension demand for pediatric populations in primary care expansion zones.
Global Azithromycin Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation and API supply tiers. Market structure concentrates among vertically integrated manufacturers with multi-site regulatory approvals and captive fermentation capacity. Three archetypes dominate: originator heritage players leveraging brand recognition, generic volume suppliers competing on tender pricing, and API-forward integrators controlling upstream cost positions. Competitive moves center on regulatory filing acceleration and geographic expansion through distribution partnerships.
Among originator-heritage players, Pfizer occupies a position exemplifying premium formulary access through brand equity retention. Sandoz and Teva Pharmaceutical Industries Ltd. represent the generic volume tier, with Sandoz anchoring European substitution networks and Teva competing aggressively in North American retail channels where pharmacy benefit managers drive tier placement. These three companies illustrate the strategic divergence between brand-premium and price-volume positioning.
| Leading Market Players |
|---|
| Pfizer |
| Sandoz |
| Teva Pharmaceutical Industries Ltd. |
| Alembic Pharmaceuticals |
| Aurobindo Pharma |
| Lupin |
| Wockhardt |
| CSPC Pharmaceutical Group Ltd. |
| Novartis AG |
| Others |
Supply & Pricing Matrix
NMPA wastewater discharge standards gate qualified supply and premium-tier pricing access, as Chinese API manufacturers bearing facility upgrade costs pass through environmental compliance premiums while Indian CDSCO-licensed competitors capture standard-tier volume through lower regulatory overhead.
Pricing Analysis
Bundled logistics-unbundled tender participation splits the pricing architecture. Hospital procurement in Brazil and Vietnam runs on contract-based long-term offtake with price-volume mechanisms, where WHO Prequalification Programme certification and FDA-approved ANDAs command premium positioning against CDSCO-standard supply. Cost compression in the economy tier intensifies as centralized tenders aggregate demand and force wholesale markup elimination. Retail pharmacy benefit managers in North America exhibit highest price sensitivity, while hospital formulary directors in Germany and France prioritize barrier isolation certification over unit cost.
Supply Chain Analysis
Workforce availability constraints in Hyderabad and Ahmedabad fermentation clusters, alongside Shijiazhuang chemical engineering talent scarcity, concentrate API production among capitalized manufacturers with captive training pipelines. India and China anchor global azithromycin base supply, drawing from erythromycin thiocyanate fermentation feedstocks and organic solvent recovery systems. Single-source vulnerability runs through environmental enforcement actions that trigger forced supplier switches. Distribution runs through state-level health secretariats in Brazil and direct manufacturer contracting networks in Vietnam, displacing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between India's CDSCO licensing cost structure and China's NMPA environmental compliance burden, with regulatory differential widening qualified supplier margins in Hyderabad and Ahmedabad clusters.
For Market Incumbents: To counter antimicrobial stewardship protocols restricting empirical macrolide prescribing, Sandoz and Teva Pharmaceutical Industries Ltd. should deepen backward integration into API fermentation capacity in India while accelerating EMA GMP certification for barrier isolation infrastructure. Channel control through direct state-level contracting in Brazil's São Paulo and Minas Gerais health systems preserves pricing power against distributor disintermediation. For New Entrants and Emerging Players: Capture ophthalmic azithromycin aqueous formulations as the most penetrable segment, where preservative compatibility requirements filter competition and margin structures exceed commodity tablet tiers. Vietnam's underpenetrated hospital procurement systems offer white-space expansion for pediatric suspension supply through local distribution partnerships in Ho Chi Minh City and Hanoi primary care zones. For Investors and Strategic Acquirers: Valuations sit cheapest among CDSCO-licensed Indian manufacturers with WHO Prequalification Programme eligibility but incomplete FDA ANDA portfolios. Long-term viability hinges on antimicrobial resistance surveillance trajectories and stewardship protocol expansion. Watch EMA GMP inspection backlog resolution as inflection signal for European hospital formulary access normalization.| Strategic Initiative | Industry Significance |
|---|---|
| EMA GMP Certification Pathway | Barrier isolation technology investment unlocks German and French hospital tender scoring premiums. |
| Backward Integration into API Fermentation | Captive erythromycin thiocyanate supply hedges NMPA environmental enforcement disruption risk. |
| WHO Prequalification Programme Submission | Eligibility gates sub-Saharan Africa government procurement tenders for pediatric suspension volume. |
| Direct Manufacturer Contracting | Bypassing wholesale markups in Brazil's state-level health secretariats compresses landed cost. |
| Ophthalmic Formulation Development | Preservative-compatible aqueous azithromycin addresses bacterial conjunctivitis with limited competitor presence. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up dosage form demand modeling and top-down therapeutic area sizing were triangulated to anchor volume estimates.
Comparable-period anchoring linked projection assumptions to historical regulatory approval timelines and tender participation patterns across the analysis window. Segmentation dimensions included dosage form, therapy area, end-user institution type, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating antimicrobial stewardship protocol penetration rates and pediatric population growth trajectories.
EMA inspection backlog duration, NMPA environmental enforcement intensity, and macrolide resistance surveillance thresholds are the dominant revision risks to forecast assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Photophobia Drug Market
Pharmaceuticals
Acetylspiramycin Market
Pharmaceuticals
Global Doxorubicin Market
Pharmaceuticals
Alprazolam Powder Market
Pharmaceuticals
Candidiasis Therapeutics Market
Pharmaceuticals
Valsartan Market
Pharmaceuticals
Asia-Pacific Adenomyosis Drugs Market
Pharmaceuticals
4-Valent HPV Vaccine (4vHPV) Market
Pharmaceuticals
New Zealand Diabetes Drugs Market
Pharmaceuticals
Peptide Therapeutics Market
Pharmaceuticals
Global Systemic Lupus Erythematosus Drugs Market
Pharmaceuticals
Buprenorphine and Naloxone Market
Pharmaceuticals
Emedastine Difumarate Market
Pharmaceuticals
Hard Empty HPMC Capsule Market
Pharmaceuticals
Vaginal Ring Market
Pharmaceuticals
Generic Pharmaceuticals Contract Manufacturing Market