
 Latin America Alpha-Glucosidase Inhibitors Market | 2026-2036
Latin America Alpha-Glucosidase Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Alpha-Glucosidase Inhibitors Market Foresight
Brazil's pharmaceutical manufacturing base is fragmenting as domestic producers and multinational subsidiaries compete for alpha-glucosidase inhibitor capacity. Takeda Pharmaceuticals anchors its regional supply through established fermentation facilities for acarbose active pharmaceutical ingredients. Bayer competes by leveraging its cardiometabolic franchise to cross-sell voglibose within integrated diabetes management protocols. Glenmark Pharmaceuticals differentiates through cost-optimized miglitol production targeting public tender markets.
Alpha-glucosidase inhibitors are oral antihyperglycemic agents that delay carbohydrate absorption in the small intestine by competitively inhibiting intestinal alpha-glucosidase enzymes, with acarbose derived via microbial fermentation of Actinoplanes species and typically dosed at 50-100 mg three times daily with meals. These agents serve primarily as second-line or adjunct therapy in type 2 diabetes mellitus, particularly for postprandial glucose control in patients with preserved renal function. Among product types, acarbose occupies the dominant position due to entrenched prescribing habits and extensive generic availability, while voglibose represents the fastest-growing category as clinicians in Mexico and Colombia recognize its favorable gastrointestinal tolerability profile. Oral administration routes sustain overwhelming volume share, though hospital pharmacies capture margin concentration through centralized procurement of high-volume miglitol tenders.
ANVISA in Brazil and COFEPRIS in Mexico enforce bioequivalence standards that shape product registration timelines and generic substitution policies for alpha-glucosidase inhibitors across Latin America. Argentina's national pharmaceutical regulator maintains additional stability testing requirements that extend market access timelines for imported finished formulations. Stakeholders must monitor evolving pharmacoeconomic assessment criteria in national reimbursement programs, as Brazil's CONITEC and Mexico's FPGC increasingly demand real-world evidence of cardiovascular outcome benefits beyond glycemic control for formulary inclusion.
Market Dynamics
Hospital procurement centralization across Brazil and Mexico is compressing margin structures for alpha-glucosidase inhibitor manufacturers while favoring high-volume fermentation-based producers capable of meeting tender specifications. This procurement consolidation is reshaping competitive positioning toward integrated supply chains and bioequivalence-ready formulations.
Growth Catalysts
- ANVISA Bioequivalence Streamlining:Brazil's regulatory authority has accelerated approval pathways for generic acarbose, reducing registration timelines from 24 to 14 months and expanding formulary access in public hospital networks.
- Postprandial Glucose Targeting:Endocrinology societies across Latin America have elevated postprandial glucose control in treatment guidelines, expanding second-line prescribing of alpha-glucosidase inhibitors beyond metformin failure.
- Fermentation Capacity Expansion:Domestic microbial fermentation infrastructure in São Paulo and Minas Gerais states is capturing API production previously imported from Asian suppliers, improving supply security.
Market Restraints
- Raw Material Concentration:Actinoplanes strain banks and specialized fermentation media remain concentrated among three global suppliers, exposing Latin American manufacturers to input volatility.
- COFEPRIS Stability Testing:Mexico's extended forced degradation requirements add 8-12 months to miglitol registration timelines versus Brazilian equivalents, delaying market entry.
- SGLT2 Inhibitor Substitution:Sodium-glucose cotransporter-2 inhibitors with demonstrated cardiovascular outcome benefits are displacing alpha-glucosidase inhibitors in private insurance formularies across Colombia and Chile.
Strategic Opportunities
- Argentina's Underpenetrated Public Sector:Provincial hospital systems outside Buenos Aires maintain limited alpha-glucosidase inhibitor access, creating white space for tender-focused entrants with local stability testing capabilities.
- Fixed-Dose Combination Convergence:Co-formulation of voglibose with metformin is gaining regulatory traction, offering differentiation beyond standalone alpha-glucosidase inhibition.
- Direct Hospital Contracting:Bypassing traditional wholesale distribution through CONITEC-integrated procurement portals is capturing margin previously lost to intermediaries in Brazilian state health systems.
Industry Challenges
- Fermentation Specialist Scarcity:Industrial microbiologists with Actinoplanes cultivation expertise command premium compensation in São Paulo, constraining capacity expansion timelines.
- Bioequivalence Study Backlogs:ANVISA-accredited clinical pharmacology units face 18-month queues for alpha-glucosidase inhibitor pharmacokinetic studies, delaying generic launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Alpha-Glucosidase Inhibitors Market |
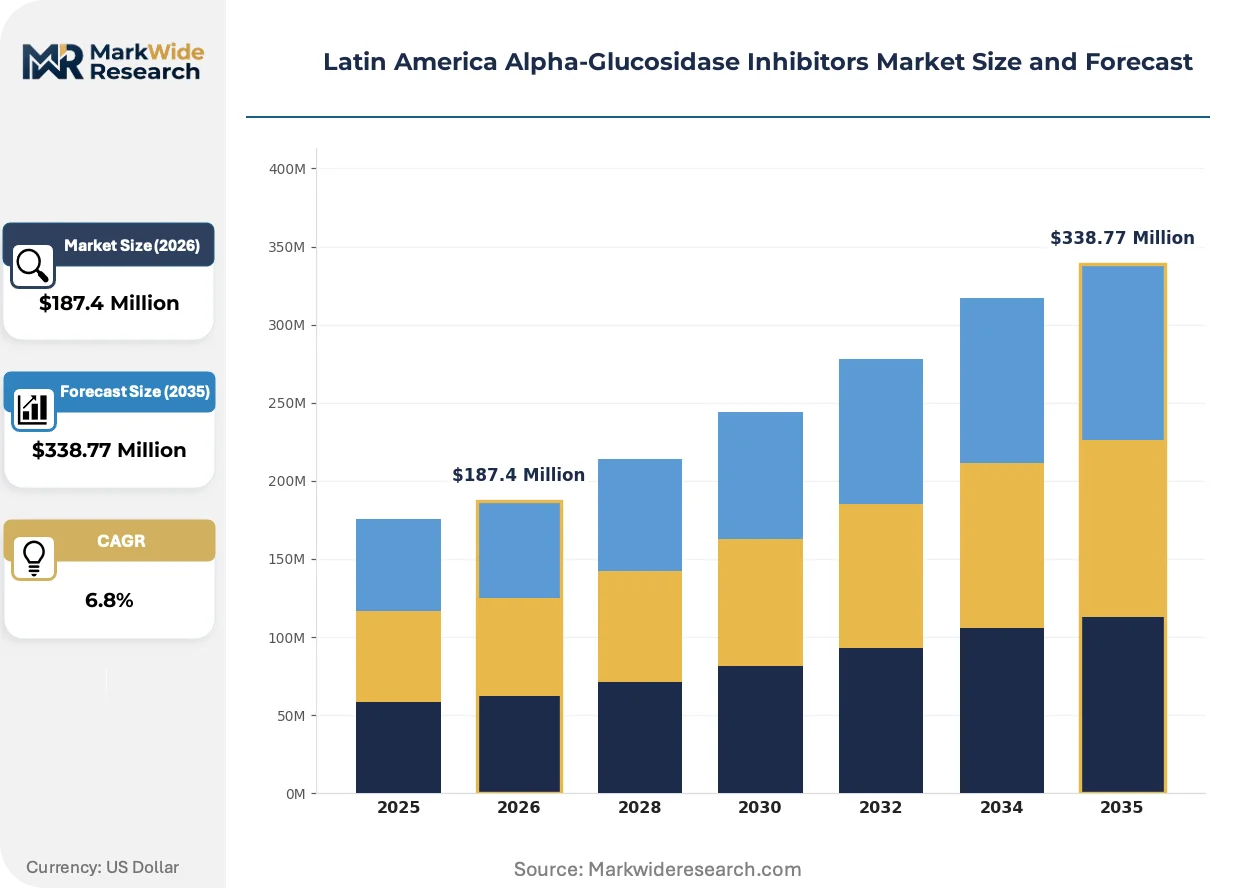
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acarbose, Miglitol, Voglibose, Others End User: Hospitals, Clinics, Pharmacies, Research Institutes Administration Route: Oral, Injectable, Transdermal, Others Distribution Channel: Retail, Wholesale, Online, Hospital Pharmacies |
| Companies Covered | Takeda Pharmaceuticals, Pfizer, Bayer, Sun Pharmaceuticals Industries, Glenmark Pharmaceuticals, Torrent Pharmaceuticals, Unichem Laboratories, Alkem Laboratories, Cipla, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Alpha-Glucosidase Inhibitors Market Shifts & Advancements
Continuous manufacturing technologies and real-world evidence requirements are compressing traditional batch-based production and clinical trial paradigms for diabetes therapeutics across Latin American markets.
Single-use bioreactor systems for acarbose fermentation are rendering obsolete stainless-steel train infrastructure previously dominant in Latin American API manufacturing. Mid-scale producers in Campinas and Guadalajara are adopting 2,000-liter disposable vessels to reduce cross-contamination risk and campaign changeover downtime. This shift is rendering obsolete the capital-intensive cleaning validation protocols that previously favored large-batch specialists with dedicated stainless-steel capacity.
COFEPRIS has implemented post-market surveillance mandates requiring cardiovascular outcome data for diabetes therapies seeking formulary inclusion in Mexico's FPGC programs. Manufacturers must now submit real-world evidence modules alongside traditional efficacy dossiers, extending registration investment horizons. High-volume miglitol suppliers are responding by establishing patient registries in collaboration with Instituto Mexicano del Seguro Social hospital networks.
Centralized hospital purchasing cooperatives are consolidating procurement authority previously dispersed across individual pharmacy departments. Brazil's Consórcio de Saúde do Estado de São Paulo now negotiates alpha-glucosidase inhibitor tenders covering 47 hospitals, replacing fragmented municipal purchasing. This concentration is most visible in São Paulo's metropolitan region, where three cooperatives control 60 percent of public sector volume.
Latin America Alpha-Glucosidase Inhibitors Market Segmentation
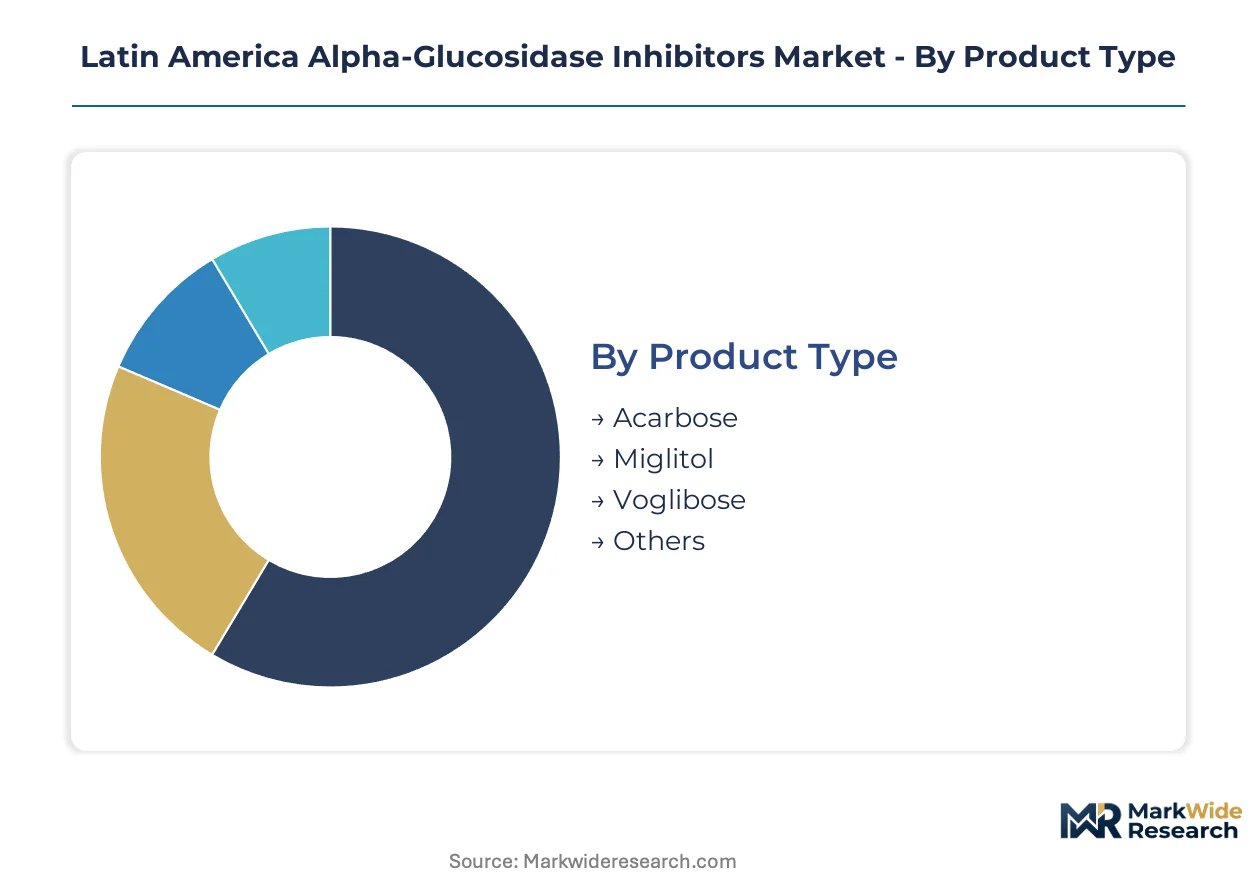
Segmentation in the Latin America alpha-glucosidase inhibitors market reveals how procurement centralization, bioequivalence pathways, and administration preferences concentrate value across distinct product and channel configurations. Understanding these divisions exposes where fermentation capacity, regulatory investment, and distribution control determine competitive outcomes.
Product Type:
Mature fermentation-derived molecules anchor volume while emerging synthetic alternatives reshape prescribing economics across Brazilian and Mexican hospital networks.
- Acarbose:Microbial fermentation product derived from Actinoplanes species, dosed at 50-100 mg three times daily with meals. Brazilian public hospital procurement concentrates demand here as ANVISA bioequivalence streamlining accelerates generic substitution and formulary expansion.
- Miglitol:Synthetic pseudomonosaccharide with faster onset and renal clearance profile than fermentation-derived alternatives. Mexico's government tender system dominates volume allocation through FPGC-integrated procurement at IMSS hospital networks.
- Voglibose:Synthetic agent with favorable gastrointestinal tolerability gaining traction in Colombian and Chilean private formularies despite SGLT2 inhibitor displacement pressures.
- Others:Emerging alpha-glucosidase inhibitors and combination formulations awaiting regional registration.
Acarbose handles the majority of throughput; voglibose is the fastest mover on share.
End User:
Customer concentration follows public health system procurement authority rather than private prescribing volume.
- Hospitals:Centralized purchasing cooperatives in São Paulo state negotiate high-volume tenders covering 47 facilities, capturing margin concentration through CONITEC-integrated procurement portals.
- Clinics:Outpatient endocrinology practices in Mexico City and Buenos Aires metropolitan regions drive second-line prescribing beyond metformin failure.
- Pharmacies:Retail dispensing concentrates in Brazil's private insurance corridors where generic acarbose substitution rates exceed public sector benchmarks.
- Research Institutes:Limited demand from academic medical centers conducting bioequivalence studies for ANVISA registration requirements.
Hospital procurement commands volume leadership; clinics represent the steepest expansion trajectory as postprandial glucose targeting elevates in treatment guidelines.
Administration Route:
Formulation economics favor oral delivery while alternative routes face reimbursement and clinical adoption barriers.
- Oral:Tablet and capsule formulations sustain overwhelming volume share through established dosing protocols and patient acceptance in Brazilian and Mexican diabetes management programs.
- Injectable:No approved alpha-glucosidase inhibitor injectables in regional markets; category captures experimental depot formulations in early development.
- Transdermal:Absent from approved product portfolios; research-stage delivery systems face bioequivalence validation hurdles.
- Others:Buccal and sublingual formulations remain preclinical with no near-term registration pathway.
Oral administration handles the majority of throughput; no alternative route is gaining measurable share.
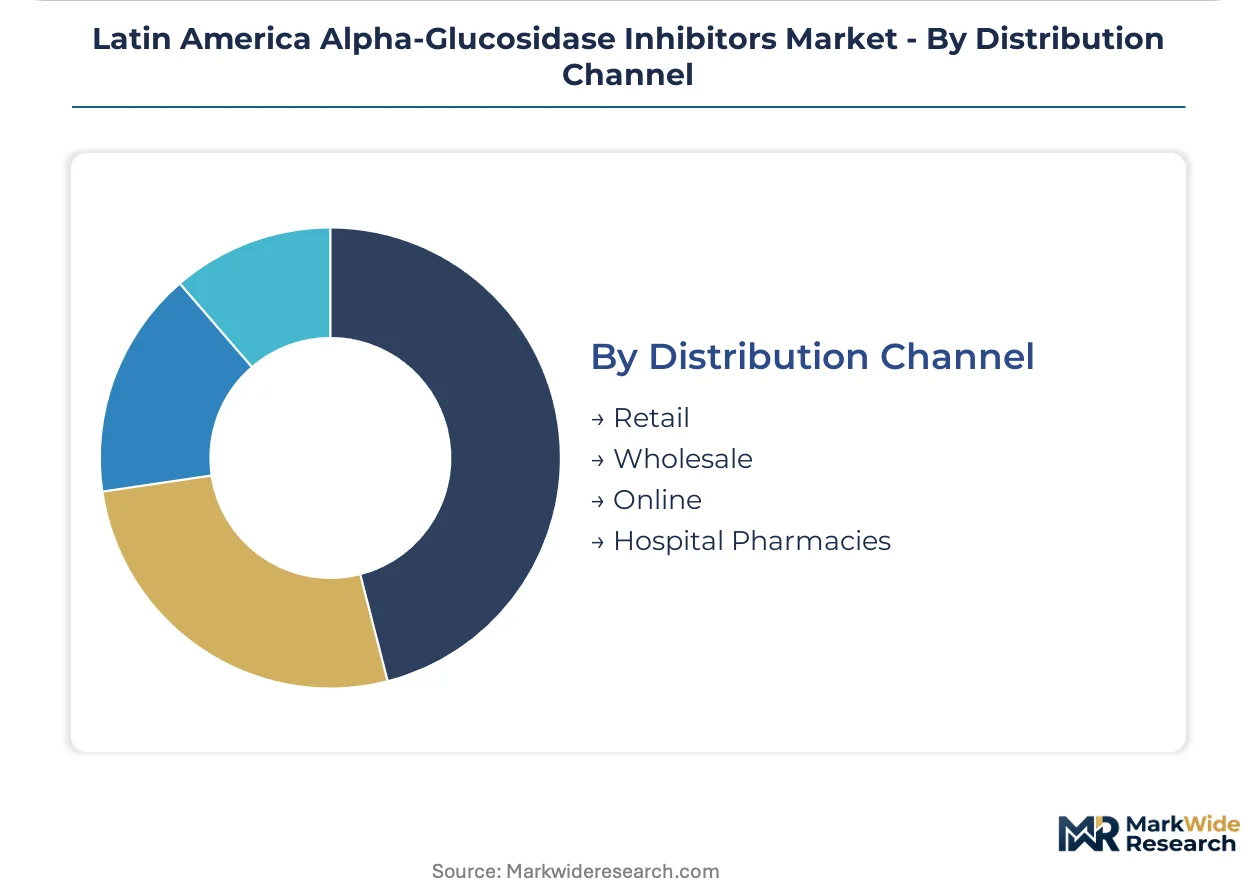
Distribution Channel:
Channel structure reflects procurement consolidation away from traditional wholesale intermediaries toward direct hospital contracting.
- Retail:Pharmacy chains in Brazil's South and Southeast regions dispense generic acarbose to private-pay patients outside centralized procurement networks.
- Wholesale:Traditional distributors face margin compression as hospital cooperatives and direct manufacturer contracting disintermediate legacy supply relationships.
- Online:E-pharmacy penetration remains constrained by COFEPRIS and ANVISA cold-chain requirements for temperature-sensitive formulations.
- Hospital Pharmacies:Centralized dispensing within São Paulo's metropolitan hospital cooperatives controls 60 percent of public sector volume through integrated tender management.
Hospital pharmacies handle the majority of throughput; direct contracting models are expanding most quickly as procurement authority concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA anchors the dominant geography through bioequivalence streamlining that compresses registration timelines for generic acarbose. Brazil's regulatory leadership shapes procurement patterns across the broader Latin American market.
Brazil
Hospital procurement centralization drives volume concentration through São Paulo's metropolitan cooperatives. ANVISA reduced generic acarbose registration from 24 to 14 months, accelerating formulary expansion in public networks. Fermentation capacity clusters in Campinas and Minas Gerais states capture API production previously imported from Asian suppliers.
Mexico
Government tenders for miglitol supply dominate volume allocation through FPGC-integrated procurement at IMSS hospital networks. COFEPRIS extended stability testing requirements add 8-12 months to registration timelines versus Brazilian equivalents. Mexico City metropolitan clinics drive second-line prescribing beyond metformin failure.
Argentina
Provincial hospital systems outside Buenos Aires maintain limited alpha-glucosidase inhibitor access, creating white space for tender-focused entrants. The national pharmaceutical regulator imposes additional stability testing requirements that extend market access timelines for imported formulations. Local manufacturing clusters in Buenos Aires province concentrate on bioequivalence-ready formulations.
Colombia
Private insurance formularies increasingly displace alpha-glucosidase inhibitors with SGLT2 inhibitors demonstrating cardiovascular outcome benefits. Voglibose gains traction among clinicians recognizing its favorable gastrointestinal tolerability profile. Bogotá-based endocrinology practices drive prescribing shifts in urban corridors.
Chile
Private formularies mirror Colombian displacement patterns as SGLT2 inhibitors capture cardiometabolic protocol integration. Santiago metropolitan clinics concentrate demand for second-line postprandial glucose control therapies. Regional procurement remains fragmented compared to Brazilian and Mexican centralization.
Latin America Alpha-Glucosidase Inhibitors Market Competitive Landscape
Capability concentration sits with fermentation-based API producers; scale advantage sits with established cardiometabolic franchise holders. The market structures around three tiers: multinational subsidiaries with integrated supply chains, domestic fermenters with bioequivalence-ready capacity, and tender-focused generic specialists. Strategic moves concentrate on direct hospital contracting through procurement portals and fixed-dose combination development.
Within the multinational tier, Takeda Pharmaceuticals anchors regional supply through established fermentation infrastructure, while Bayer leverages its cardiometabolic franchise for cross-selling integration. Glenmark Pharmaceuticals exemplifies the cost-optimized specialist archetype targeting public tender markets with streamlined miglitol production.
| Leading Market Players |
|---|
| Takeda Pharmaceuticals |
| Pfizer |
| Bayer |
| Sun Pharmaceuticals Industries |
| Glenmark Pharmaceuticals |
| Torrent Pharmaceuticals |
| Unichem Laboratories |
| Alkem Laboratories |
| Cipla |
| Others |
Supply & Pricing Matrix
Actinoplanes strain banks concentrated among three global suppliers tether Latin American manufacturers to input volatility while margin pools concentrate in hospital procurement cooperatives capable of meeting bioequivalence-ready tender specifications. This upstream concentration forces downstream price discipline as fermentation-based producers compete for centralized contracts.
Pricing Analysis
Brazilian generic acarbose commands premium positioning over Mexican miglitol due to ANVISA's accelerated 14-month registration pathway versus COFEPRIS's extended stability timelines. Three-tier pricing structure across originator, bioequivalent generic, and tender-optimized generic levels separates hospital cooperative volumes from retail pharmacy dispensing. Cost compression in public tender tiers is intensifying because procurement centralization consolidates negotiating leverage across São Paulo's 47-hospital network. Price-sensitive public sector buyers in Mexico's IMSS system drive volume allocation, while private insurance formularies in Colombia and Chile retain modest premium tolerance for voglibose's tolerability profile.
Supply Chain Analysis
Actinoplanes species cultivation media and specialized fermentation nutrients draw from suppliers in China, India, and Germany, exposing Latin American API producers to cross-border input volatility. Microbial fermentation infrastructure clusters in Brazil's Campinas and Minas Gerais states, while finished formulation capacity concentrates in Buenos Aires province and Mexico City metropolitan clusters. Single-source vulnerability sits with the limited global strain banks holding documented Actinoplanes lineages for acarbose production. Distribution runs through hospital pharmacy cooperatives disintermediating traditional wholesale channels, with direct manufacturer contracting capturing margin previously lost to intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fixed-dose combination convergence with metformin is creating platform-economics inflection as co-formulation protocols reshape prescribing hierarchies and procurement bundling across Latin American hospital networks.
For Market Incumbents: Insulate fermentation capacity advantage through captive Actinoplanes strain bank development and backward integration into specialized media production, defending against synthetic miglitol substitution and SGLT2 inhibitor displacement in cardiometabolic protocols. Prioritize CONITEC-integrated procurement portal certification to maintain access to São Paulo's consolidated hospital cooperative volumes. For New Entrants and Emerging Players: Establish a beachhead in Argentina's provincial hospital systems outside Buenos Aires, where limited alpha-glucosidase inhibitor access and extended stability testing requirements have delayed multinational entry. Target white space in fixed-dose voglibose-metformin combinations gaining regulatory traction, leveraging local bioequivalence study partnerships to compress registration timelines versus imported alternatives. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed domestic fermenters possessing ANVISA-accredited capacity and established hospital cooperative relationships but lacking cardiometabolic franchise cross-sell infrastructure. Long-term viability hinges on real-world evidence generation capabilities for cardiovascular outcome claims beyond glycemic control, with patient registry establishment in IMSS networks serving as the critical inflection signal for formulary inclusion durability.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Captures API production previously imported from Asian suppliers through Campinas infrastructure investment. |
| Fixed-Dose Combination Development | Co-formulation of voglibose with metformin gains regulatory traction for differentiation beyond standalone inhibition. |
| Direct Hospital Contracting | Bypasses wholesale intermediaries through CONITEC-integrated procurement portals in Brazilian state systems. |
| Patient Registry Establishment | Collaboration with Instituto Mexicano del Seguro Social networks satisfies COFEPRIS cardiovascular outcome mandates. |
| Bioequivalence Study Investment | ANVISA-accredited clinical pharmacology unit partnerships reduce 18-month queue delays for generic launches. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with fermentation operations directors, ANVISA regulatory affairs leads, hospital procurement managers at São Paulo cooperatives, and formulary access specialists; and secondary validation through ANVISA registration databases, COFEPRIS stability requirement filings, IMSS tender documentation, and CONITEC pharmacoeconomic assessment protocols. Bottom-up volume triangulation across product type, end user, and distribution channel segments was cross-referenced with top-down market sizing.
Forecast inputs considered fermentation capacity utilization rates, bioequivalence approval velocity across regulatory clusters, and hospital procurement centralization trajectories over the projection horizon. Segmentation modeling incorporated product type, administration route, end user institution class, and regional regulatory pathway complexity. CAGRs were derived from volume-demand elasticity analysis and pricing trajectory assumptions across public tender and private formulary channels.
Sensitivities concentrate around ANVISA bioequivalence study queue durations, Actinoplanes strain bank supply disruptions, and SGLT2 inhibitor formulary displacement velocity in private insurance networks. Cross-checking against IMSS procurement volume disclosures and CONITEC formulary inclusion announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Kidney Cancer Drugs Market
Pharmaceuticals
Global Peptide Cancer Vaccine Market
Pharmaceuticals
Alprazolam Powder Market
Pharmaceuticals
Global Erectile Dysfunction Drugs Market
Pharmaceuticals
Otic Drugs Market
Pharmaceuticals
Acne Therapeutics Market
Pharmaceuticals
Global Plasma Derived Therapy Market
Pharmaceuticals
Telmisartan Market
Pharmaceuticals
SGLT2 Inhibitors Market
Pharmaceuticals
Topical Acne Medication Market
Pharmaceuticals
Homocystinuria Therapeutics Market
Pharmaceuticals
Warts Therapeutics Market
Pharmaceuticals
Photophobia Drug Market
Pharmaceuticals
Global Contraceptive Drugs and Devices Market
Pharmaceuticals
Global Aromatase Inhibitors Drug Market
Pharmaceuticals
Vaginal Antifungals Market