
 Indonesia Oral Anti-Diabetic Drug Market | 2026-2036
Indonesia Oral Anti-Diabetic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Oral Anti-Diabetic Drug Market Insights
Fixed-dose combination packaging is realigning prescribing behavior among Indonesian endocrinologists and primary care physicians. Takeda leverages its established metabolic portfolio to sustain hospital formulary presence across Java and Sumatra. Novo Nordisk anchors the premium GLP-1 segment through specialist channel control in tier-one cities. Pfizer competes on manufacturing scale for mature biguanide and sulfonylurea volumes distributed through government tenders.
Oral anti-diabetic drugs comprise synthetic or semi-synthetic chemical entities formulated as immediate-release or modified-release solid dosage forms, designed to reduce blood glucose through mechanisms including hepatic glucose suppression, pancreatic insulin secretion enhancement, or incretin pathway modulation. The primary commercial purpose centers on chronic outpatient management of hyperglycemia in type 2 diabetes patients who do not require or tolerate injectable therapy. Biguanides occupy the largest volume tier due to decades of generic availability and first-line positioning in national treatment guidelines. DPP-4 inhibitors command the fastest-growing revenue pool as prescribers shift toward gliptin-based regimens with lower hypoglycemia risk. GLP-1 receptor agonists in oral form concentrate margin in urban specialist clinics where patients demonstrate higher out-of-pocket payment capacity.
Indonesia's Ministry of Health and the national food and drug regulatory agency govern pharmaceutical registration, GMP certification, and post-market surveillance for oral anti-diabetic products. The BPJS Kesehatan national insurance scheme determines reimbursement tiers and formulary inclusion, directly shaping manufacturer pricing negotiations and volume allocation. Manufacturers must monitor JKN formulary revisions and local production incentives under the Ministry of Industry's pharmaceutical sector roadmap to align portfolio investment with evolving access dynamics.
Market Dynamics
Fixed-dose combination packaging is rewriting prescribing protocols across Indonesia's tier-one hospital networks, compressing the traditional step-therapy sequence and accelerating formulary updates in Java's endocrinology departments.
Growth Catalysts
- JKN Formulary Expansion:BPJS Kesehatan's reimbursement tier revisions are pulling combination therapies into subsidized channels, expanding patient access beyond Jakarta's specialist corridors.
- Endocrinology Clustering:Specialist service concentration in Surabaya and Bandung is generating referral density that amplifies prescription volume for newer therapeutic classes.
- Modified-Release Formulation Adoption:Once-daily dosing technologies are improving adherence metrics in primary care settings across Central Java.
Market Restraints
- API Import Dependency:Active pharmaceutical ingredient supply concentrates on Chinese and Indian manufacturers, exposing formulators to currency volatility and shipping disruptions.
- GMP Certification Bottleneck:Indonesia's national pharmaceutical regulator maintains stringent facility inspection queues that delay new product launches by 18-24 months.
- Generics Substitution Pressure:Government tender mechanisms for mature biguanides and sulfonylureas compress margin pools available for novel mechanism investments.
Strategic Opportunities
- Eastern Indonesia Penetration:Sulawesi and Papua remain underserved by specialist diabetes care, creating first-mover potential for telemedicine-integrated distribution models.
- Local Production Incentives:Ministry of Industry pharmaceutical sector roadmaps offer tax relief and accelerated approval pathways for domestic manufacturing investments.
- DPP-4/SGLT-2 Convergence:Dual-mechanism fixed-dose combinations align with emerging international treatment guidelines and command premium positioning in private hospital channels.
Industry Challenges
- Specialist Workforce Scarcity:Endocrinologist density in Indonesia lags regional benchmarks, constraining patient throughput for complex oral therapy initiation.
- Cold Chain Fragmentation:Temperature-sensitive biologic oral formulations face last-mile integrity risks in archipelago logistics spanning 17,000 islands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Oral Anti-Diabetic Drug Market |
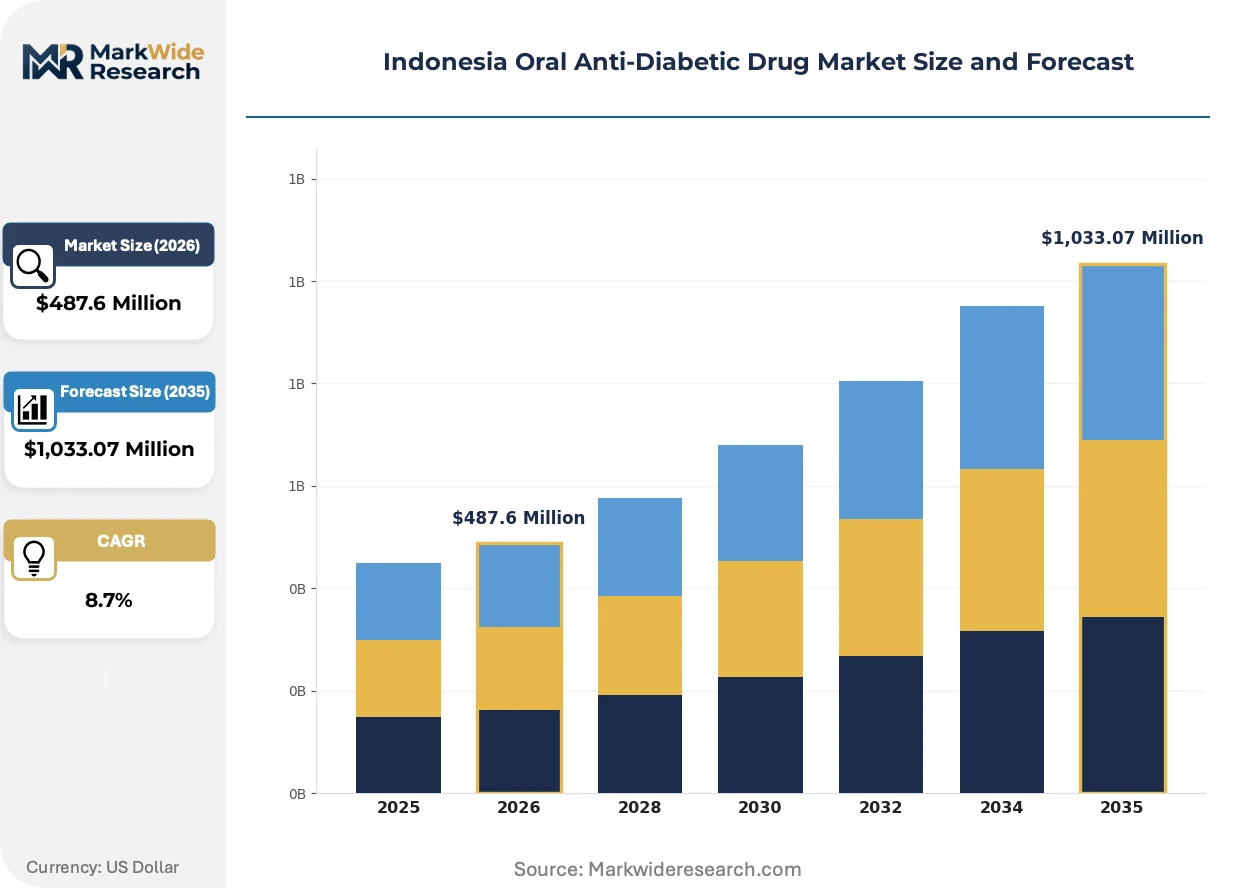
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biguanides, Sulfonylureas, DPP-4 Inhibitors, GLP-1 Receptor Agonists Delivery Mode: Tablets, Capsules, Liquids, Granules End User: Hospitals, Clinics, Homecare, Pharmacies Therapy Area: Type 2 Diabetes, Metabolic Syndrome, Gestational Diabetes, Prediabetes |
| Companies Covered | Takeda, Novo Nordisk, Pfizer, Eli Lilly, Janssen Pharmaceuticals, Astellas, Boehringer Ingelheim, Merck And Co, AstraZeneca, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Oral Anti-Diabetic Drug Market Trends and Innovations
Digital therapeutics integration and precision dosing platforms are disrupting Indonesia's traditional chronic disease management protocols, creating new interface points between pharmaceutical manufacturers and patient monitoring ecosystems.
Oral GLP-1 receptor agonist formulations are rewriting the injectable-to-oral transition pathway for type 2 diabetes patients. Urban specialist clinics in Jakarta and Surabaya are adopting these agents for patients demonstrating higher out-of-pocket payment capacity. The technology is compressing the historical dominance of parenteral incretin therapy in premium segments.
BPJS Kesehatan's outcome-based reimbursement pilots are reshaping manufacturer-hospital contracting structures. Volume guarantees now tie to HbA1c reduction metrics rather than simple prescription counts. Private hospital chains in Java are restructuring procurement committees to incorporate clinical pharmacy cost-effectiveness analyses.
Patient self-monitoring application adoption is altering the prescriber-patient information asymmetry in diabetes management. Primary care physicians in tier-two cities are encountering patients arriving with continuous glucose monitor data and therapy adjustment requests. This behavioral shift concentrates in Bandung and Yogyakarta where smartphone penetration intersects with rising health literacy.
Indonesia Oral Anti-Diabetic Drug Market Segmentation
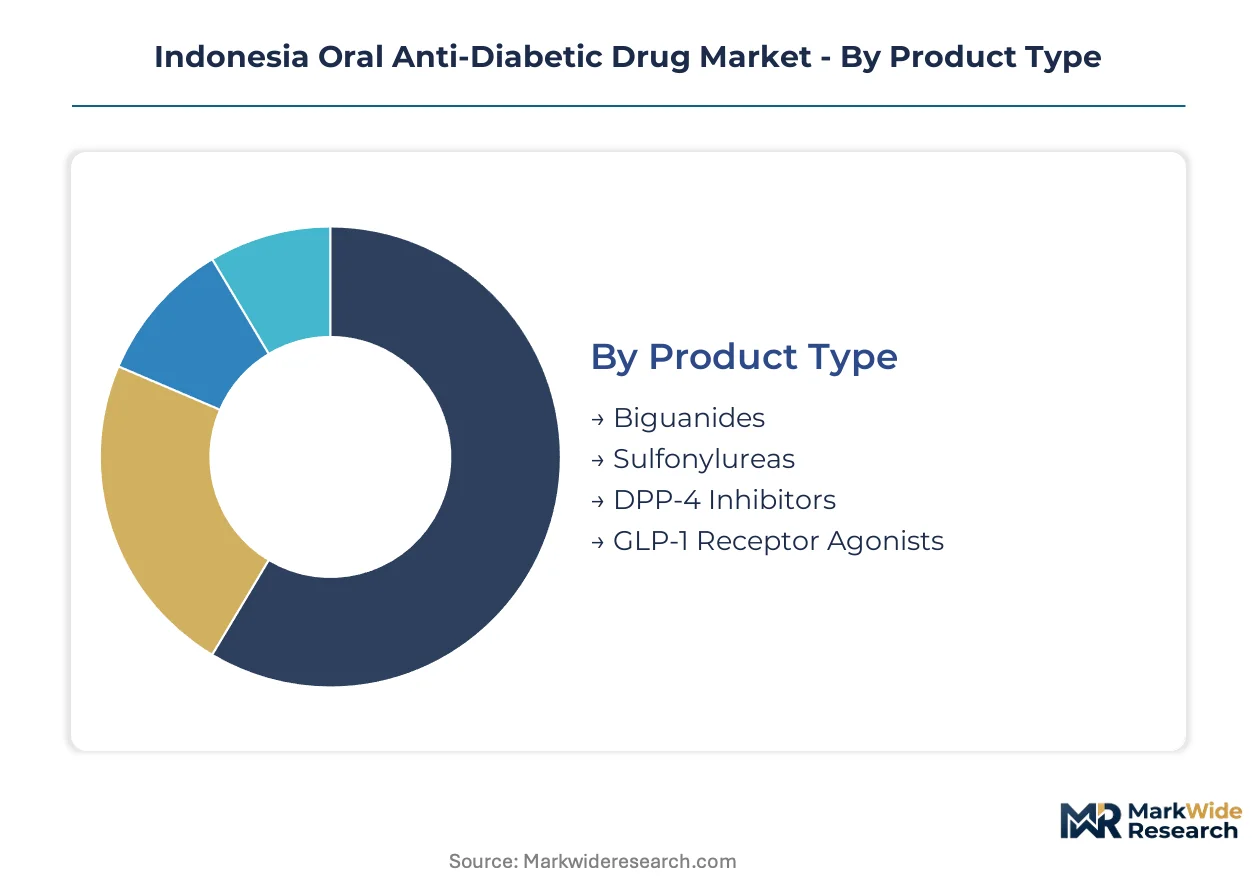
Segmentation of Indonesia's oral anti-diabetic drug market reveals how regulatory pathways, reimbursement tiers, and patient access channels fragment commercial opportunity across distinct product and delivery categories. Understanding these divides enables manufacturers to align portfolio investment with the specific approval burdens and volume dynamics governing each segment.
Product Type:
BPJS Kesehatan formulary tiers and Ministry of Health registration requirements vary sharply across mechanism classes, with newer molecular entities facing extended GMP certification queues and outcome-based contracting pilots.
- Biguanides:Metformin-based formulations dominate procurement volumes through government tenders, with immediate-release and modified-release variants both commanding formulary inclusion. Demand concentrates in primary care networks across Central and East Java where first-line therapy initiation rates run highest, though margin compression from multi-source generic competition constrains manufacturer investment in novel formulations.
- DPP-4 Inhibitors:Gliptin-class agents require specialist prescription in most private hospital channels and carry premium reimbursement positioning. Prescription volume clusters in Jakarta and Surabaya endocrinology departments where lower hypoglycemia risk drives physician preference, with sitagliptin and vildagliptin variants leading hospital formulary adoption.
- Sulfonylureas:Mature agents face intensifying generic substitution pressure under JKN procurement mechanisms.
- GLP-1 Receptor Agonists:Oral incretin formulations concentrate in urban specialist clinics with higher out-of-pocket payment capacity.
Biguanides sit at the top of the volume ranking, with DPP-4 inhibitors climbing the fastest.
Delivery Mode:
Packaging format selection directly shapes distribution economics and patient adherence profiles across Indonesia's archipelago logistics network, with solid dosage forms benefiting from established cold-chain exemptions.
- Tablets:Immediate-release and modified-release solid dosage forms constitute the dominant delivery format for chronic outpatient therapy. Manufacturing scale concentrates among domestic formulators serving government tender volumes, with blister and strip packaging configurations optimized for tropical climate stability.
- Capsules:Hard-shell and soft-gel formulations occupy niche positioning for combination therapies and modified-release applications. Demand localizes in private hospital pharmacies across Java where patient co-payment capacity supports premium pricing.
- Liquids:Oral solutions and suspensions serve pediatric and geriatric populations with swallowing difficulties.
- Granules:Sachet-based formulations target rural dispensing practices with limited pill-counting infrastructure.
Tablets capture the largest production volume, with capsules expanding most quickly in premium channels.
End User:
Channel selection determines pricing architecture and procurement committee influence, with hospital networks demanding outcome guarantees and retail pharmacies operating on wholesale margin structures.
- Hospitals:Tertiary and secondary care facilities govern initiation of complex combination therapies and newer mechanism classes. Procurement committees in Java's tier-one hospital networks are restructuring to incorporate clinical pharmacy cost-effectiveness analyses, with volume guarantees increasingly tied to HbA1c reduction metrics.
- Clinics:Primary care and specialist outpatient settings manage stable patients on established regimens. Patient throughput concentrates in Surabaya and Bandung where endocrinology clustering generates referral density for therapy escalation.
- Homecare:Direct-to-patient dispensing models remain underdeveloped outside Jakarta.
- Pharmacies:Community and hospital outpatient dispensaries handle the majority of prescription fulfillment.
Hospitals anchor the value chain for novel agents, with clinics generating the steepest prescription volume expansion.
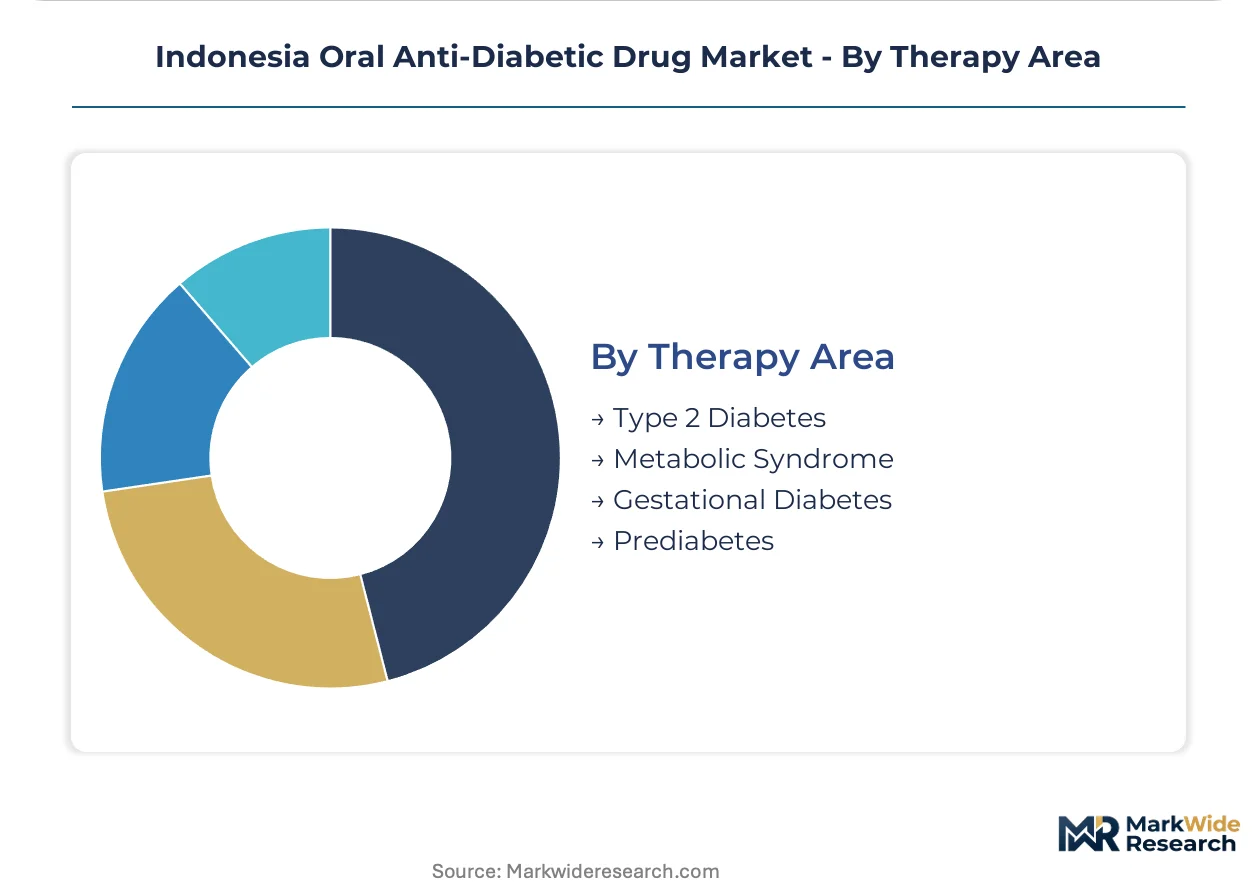
Therapy Area:
Indication-specific treatment guidelines and risk stratification protocols segment prescriber behavior, with type 2 diabetes commanding dedicated formulary attention while metabolic syndrome remains underaddressed.
- Type 2 Diabetes:The core indication drives national treatment guideline development and BPJS Kesehatan reimbursement prioritization. Patient volume concentrates in urban corridors where diagnostic screening penetration intersects with specialist access, though rural detection gaps persist in Eastern Indonesia.
- Metabolic Syndrome:Polypharmacy requirements for dyslipidemia, hypertension, and glycemic control create combination therapy opportunities. Prescription patterns cluster in Jakarta's integrated diabetes centers where multi-morbidity management protocols are most established.
- Gestational Diabetes:Maternal health programs in Java's provincial hospitals drive screening and intervention.
- Prediabetes:Lifestyle intervention prioritization limits pharmaceutical penetration in this category.
Type 2 diabetes holds the largest patient pool, with metabolic syndrome gaining share fastest as multi-morbidity recognition expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's pharmaceutical sector traces its modern foundations to Dutch colonial-era laboratories in Batavia, with post-independence state enterprises scaling domestic production from the 1960s onward. The oral anti-diabetic drug market now distributes across an archipelago where Java's industrial corridor dominates manufacturing and procurement.
Java
Java generates the majority of oral anti-diabetic prescription volume through Jakarta's specialist hospital networks and Surabaya's endocrinology referral clusters. BPJS Kesehatan formulary negotiations concentrate in the capital, where procurement committees increasingly demand HbA1c outcome guarantees. Bandung's pharmaceutical manufacturing belt supplies modified-release formulations to Central Java primary care networks.
Sumatra
Sumatra's patient access expands through Medan's growing private hospital sector and Palembang's provincial health system integration with JKN reimbursement tiers. The island's logistics infrastructure struggles with last-mile distribution to rural districts, concentrating volume in urban corridors. Domestic formulators leverage Batam's free trade zone status for API import processing.
Sulawesi
Sulawesi remains underserved by specialist diabetes care, with Makassar's tertiary facilities serving as the primary escalation point for Eastern Indonesia referrals. Telemedicine-integrated distribution models are testing patient adherence protocols in remote highland communities. The provincial health office coordinates with Jakarta on JKN formulary implementation delays.
Kalimantan
Kalimantan's oil and gas industry workforce drives employer-sponsored health coverage for oral anti-diabetic therapies in Balikpapan and Samarinda. Mining company clinics generate concentrated demand for combination therapies among shift workers with metabolic syndrome. Pontianak's border location creates cross-border pharmaceutical trade monitoring challenges for Indonesia's national drug regulator.
Bali and Nusa Tenggara
Bali's tourism economy supports private pharmacy channels for premium DPP-4 inhibitor access among affluent retirees and expatriate populations. Denpasar's hospitals anchor diabetes screening programs that feed into specialist referral pathways. Eastern Nusa Tenggara faces diagnostic penetration gaps that limit pharmaceutical market development outside Kupang's provincial hospital network.
Indonesia Oral Anti-Diabetic Drug Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the mechanism-class and channel-access dimensions of Indonesia's oral anti-diabetic market. The competitive structure fragments between multinational innovators controlling specialist hospital formulary positions and domestic formulators capturing government tender volumes for mature agents. Three archetypes dominate: patent-protected molecular specialists, high-volume generic manufacturers, and hybrid players bridging private premium and public procurement channels. Capacity expansion into local production facilities and strategic partnerships with regional distributors constitute the primary competitive moves reshaping market access.
Among the multinational innovators referenced in this analysis, Takeda and Novo Nordisk occupy distinct positioning archetypes. Takeda leverages its metabolic portfolio heritage to sustain hospital formulary presence across Java and Sumatra. Novo Nordisk anchors the premium GLP-1 segment through specialist channel concentration in tier-one cities. Pfizer competes on manufacturing scale for mature biguanide volumes distributed through government tenders, representing the hybrid archetype that spans both premium and procurement channels.
| Leading Market Players |
|---|
| Takeda |
| Novo Nordisk |
| Pfizer |
| Eli Lilly |
| Janssen Pharmaceuticals |
| Astellas |
| Boehringer Ingelheim |
| Merck And Co |
| AstraZeneca |
| Others |
Pricing and Supply Chain Analysis
Modified-release formulation adoption is compressing manufacturing cost curves while concentrating production scale among domestic formulators serving BPJS Kesehatan tender volumes. This technology shift simultaneously elevates quality premiums for hospital formulary positioning and deepens dependency on imported active pharmaceutical ingredients from Chinese and Indian suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs Indonesia's oral anti-diabetic market, with DPP-4 inhibitors and oral GLP-1 formulations commanding specialist-channel premiums while generic biguanides face government procurement compression. Price differentiation hinges on BPJS Kesehatan formulary tier placement and GMP certification status. Margins are tightening due to generics substitution pressure under JKN procurement mechanisms. Primary care networks in Central Java exhibit highest price sensitivity; urban specialist clinics in Jakarta demonstrate lowest.
Supply Chain Analysis
Active pharmaceutical ingredient supply rests on Chinese and Indian specialty chemical manufacturers, with metformin and gliptin intermediates drawing from concentrated coastal production zones. Key inputs span synthetic organic compounds, specialized catalysts, and modified-release polymers. Single-source vulnerability runs through API import channels exposed to currency volatility and shipping disruptions. Distribution runs through Java's pharmaceutical manufacturing belt to hospital procurement committees and provincial health system warehouses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's oral anti-diabetic market represents a late-cycle quality story as patient self-monitoring applications and outcome-based reimbursement pilots shift demand toward HbA1c-demonstrated efficacy. Prescriber expectations for combination therapy convenience are elevating premium specifications.
For Market Incumbents: To counter specialist workforce scarcity constraining patient throughput, Takeda and Novo Nordisk should deepen hospital formulary control through clinical pharmacy cost-effectiveness partnerships while accelerating local production investments under Ministry of Industry tax relief programs to defend margin position against generic encroachment. For New Entrants and Emerging Players: Telemedicine-integrated distribution models offer first-mover positioning in Sulawesi and Papua where specialist diabetes care remains underserved. Eastern Indonesia penetration leverages JKN formulary implementation delays to establish patient adherence protocols before incumbent footprint expansion. For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid players bridging private premium and public procurement channels. Long-term viability centers on portfolio breadth spanning DPP-4/SGLT-2 convergence combinations. Watch BPJS Kesehatan outcome-based reimbursement pilot expansion as inflection signal for contracting structure transformation.| Strategic Initiative | Industry Significance |
|---|---|
| Local Manufacturing Investment | Ministry of Industry tax relief accelerates GMP certification timelines for domestic facilities. |
| Telemedicine Distribution Partnership | Makassar tertiary referrals enable remote highland community adherence monitoring in Sulawesi. |
| Outcome-Based Contracting | Volume guarantees tied to HbA1c metrics reshape Jakarta hospital procurement committee structures. |
| Fixed-Dose Combination Development | DPP-4/SGLT-2 dual-mechanism alignment with international guidelines commands private hospital premium. |
| Specialist Channel Concentration | Surabaya and Bandung endocrinology clustering generates referral density for therapy escalation. |
Research Methodology
Direct dialogue with drug development executives, formulary directors at Java's tier-one hospitals, BPJS Kesehatan reimbursement specialists, and pharmaceutical distribution channel partners grounded qualitative insights. Secondary validation drew from BPJS Kesehatan formulary databases, Ministry of Health GMP certification records, ClinicalTrials.gov registration data, and national pharmaceutical import statistics. Bottom-up prescription volume modeling and top-down healthcare expenditure triangulation ensured analytical robustness.
Bottom-up demand modeling segmented by mechanism class, delivery mode, end-user channel, and therapy indication across the analysis window. Top-down validation cross-referenced national health insurance reimbursement trends and diabetes prevalence epidemiology. CAGRs derived from patient volume projections, pricing trajectory assumptions, and formulary expansion timelines. Forecast inputs incorporated JKN penetration rates and specialist workforce growth patterns.
The model holds under stable BPJS Kesehatan reimbursement tiers and continued API import channel functionality; deviation in currency volatility or GMP certification queue extensions would shift volume allocation assumptions. A small set of named triggers warrants ongoing watch: JKN formulary revision timing, Ministry of Industry local production incentive adjustments, and Eastern Indonesia telemedicine infrastructure deployment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Malaysia Oral Anti-Diabetic Drug Market
Pharmaceuticals
Brazil Diabetes Drugs Market
Pharmaceuticals
Global Prophylactic HIV Drugs Market
Pharmaceuticals
Nephrology Drugs Market
Pharmaceuticals
Global Primary Biliary Cirrhosis Drug Market
Pharmaceuticals
Empty Capsules Market
Pharmaceuticals
Europe Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
Italy Pharmaceutical Market
Pharmaceuticals
Global Anticoagulant Reversal Drugs Market
Pharmaceuticals
Global Respiratory Drug Market
Pharmaceuticals
3D Printing Drug Market
Pharmaceuticals
Global Corticosteroids Market
Pharmaceuticals
Carbapenem Antibiotics Market
Pharmaceuticals
H2-Receptor Antagonists Market
Pharmaceuticals
Global Zika Vaccines Market
Pharmaceuticals
Myocardial Infarction Drugs Market