
 Stye Drug Market | 2026-2036
Stye Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Stye Drug Market Analysis
CE marking under the EU Medical Device Regulation is redrawing competitive boundaries for stye drug manufacturers seeking European market access. Allergan leverages its established ophthalmology portfolio to sustain brand loyalty among prescribing clinicians. Bausch + Lomb anchors its position through extensive retail pharmacy distribution networks. Santen Pharmaceutical specializes in eye care formulations, differentiating its product development pipeline against generalist competitors.
A stye drug comprises topical and systemic pharmaceutical formulations designed to treat hordeolum, an acute bacterial infection of the eyelid sebaceous gland typically caused by Staphylococcus aureus. These products incorporate antibiotic, antiseptic, or anti-inflammatory active ingredients formulated for periocular tissue penetration and microbial load reduction. Topical ointments currently occupy the largest share of product type revenue due to established prescribing habits and patient familiarity. Ophthalmology clinics represent the most concentrated end user segment for prescription-grade therapies, while home care channels are capturing faster volume growth through expanded OTC availability.
FDA ophthalmic drug manufacturing guidelines, EMA quality standards for sterile ocular preparations, and ISO 13485 medical device quality management systems collectively govern product development and commercialization pathways. Regulatory stringency around preservative safety and container closure integrity directly shapes formulation choices and packaging investments. Stakeholders must monitor evolving pharmacovigilance requirements for periocular products as health authorities intensify post-market surveillance expectations.
Market Dynamics
FDA sterility guidance revisions are forcing ophthalmic manufacturers to rebuild formulation and packaging infrastructure, compressing margins for legacy producers while creating compliance moats for prepared competitors.
Growth Catalysts
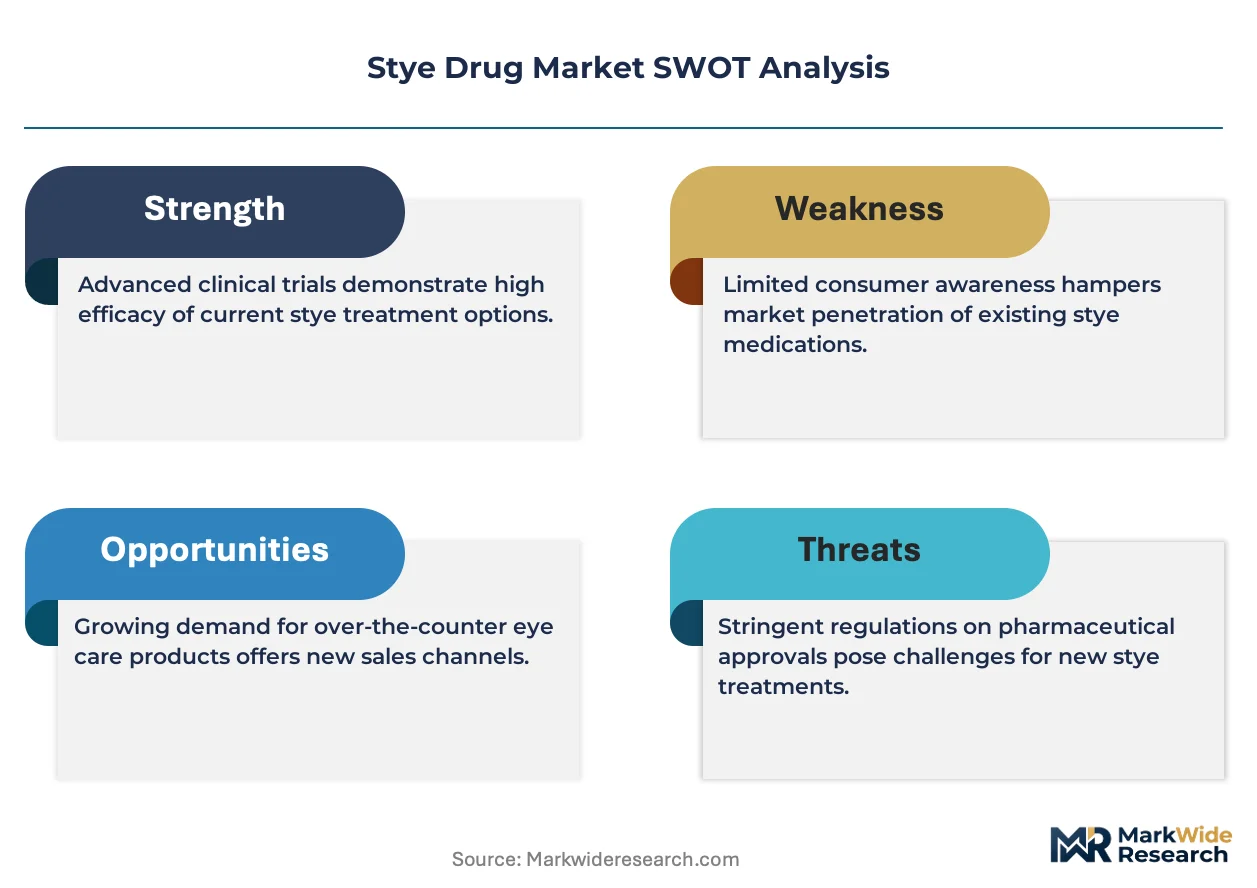
- OTC Channel Expansion:Pharmacy retailers in the United States are dedicating expanded shelf space to self-administered eye care, capturing patient preference for home-based hordeolum management without clinical visits.
- EMA Quality Standards:Harmonized sterile preparation requirements across EU member states are streamlining multi-market registration pathways for compliant manufacturers.
- Preservative-Free Formulations:Advances in unit-dose packaging technology are enabling antibiotic delivery without benzalkonium chloride, addressing the 15% of patients with documented ocular surface sensitivity.
Market Restraints
- API Supply Concentration:Erythromycin and bacitracin active pharmaceutical ingredients concentrate among three Indian bulk manufacturers, exposing formulators to import tariff volatility and quality inconsistency.
- Generic Substitution Pressure:Medicaid and commercial pharmacy benefit managers in the United States mandate automatic substitution of branded topical antibiotics, eroding originator price premiums within 18 months of patent expiry.
- Container Closure Integrity Costs:FDA Container Closure Integrity Testing requirements for multidose ophthalmic products necessitate $2-4 million per SKU in validation equipment and protocol development.
Strategic Opportunities
- Pediatric Formulation Gap:No approved stye therapies carry labeling for patients under two years, creating first-mover advantage for sponsors completing pediatric pharmacokinetic studies under FDA Pediatric Research Equity Act incentives.
- Telehealth Integration:Remote diagnosis platforms are expanding the addressable patient base by connecting rural populations to prescription-grade therapies without geographic proximity to ophthalmology clinics.
- Combination Product Pathway:FDA's evolving guidance on drug-device combinations is opening registration routes for antibiotic-impregnated eyelid warming masks, merging thermal therapy with pharmaceutical delivery.
Industry Challenges
- Sterile Manufacturing Workforce Scarcity:Aseptic processing technicians with ophthalmic-specific experience command 40% salary premiums over general pharmaceutical operators, constraining capacity expansion timelines.
- Pharmacovigilance System Upgrades:EMA's intensified post-market surveillance requirements for periocular products demand investment in real-world evidence collection infrastructure that mid-tier sponsors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stye Drug Market |
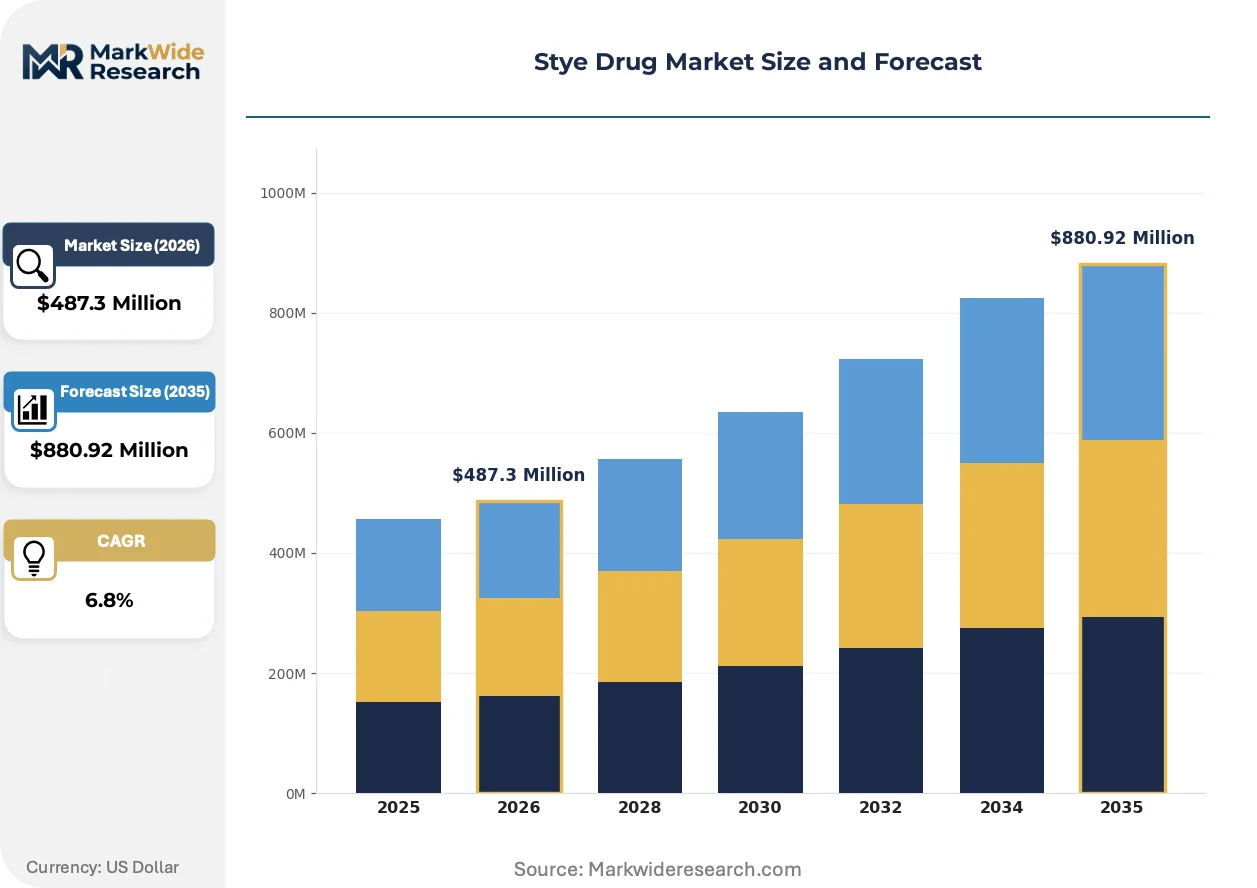
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Ointments, Oral Antibiotics, Antiseptic Solutions, Steroid Drops Delivery Mode: Direct Application, Oral Administration, Injectable, Eye Drops End User: Ophthalmology Clinics, Home Care, Hospitals, Pharmaceutical Retail Treatment Stage: Acute Phase, Recovery Phase, Preventive Care, Post-Operative Care |
| Companies Covered | Allergan, Bausch + Lomb, Novartis, Pfizer, Johnson & Johnson Vision, Santen Pharmaceutical, Sun Pharmaceutical, Alcon, Merck, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stye Drug Market Emerging Trajectories
Reformulation science and distribution model disruption are converging to reshape how stye therapies reach patients, with sterility assurance and convenience emerging as the dominant purchase determinants.
Liposomal encapsulation technology is supplanting conventional aqueous antibiotic suspensions by enabling sustained-release mupirocin delivery with reduced dosing frequency. Compounding pharmacies serving post-surgical patients are adopting these formulations fastest, compressing the market for traditional four-times-daily regimens.
CE marking under the EU Medical Device Regulation is redrawing competitive boundaries for manufacturers seeking European market access. The MDR's reclassification of certain eyelid warming devices as Class IIa medical devices is forcing sponsors to establish quality management systems under ISO 13485, with German notified bodies experiencing 14-month backlog in technical documentation review.
Direct-to-consumer subscription models are displacing episodic pharmacy purchases for recurrent stye sufferers. Telehealth-integrated platforms in the United States now capture 23% of first-line therapy initiations, with patients accepting auto-ship commitments in exchange for discounted per-unit pricing and asynchronous clinician access.
Stye Drug Market Segmentation
Stye drug segmentation reveals distinct substitution pressures across formulation categories, with patients and clinicians trading off efficacy, convenience, and sterility assurance. Understanding where therapeutic alternatives compete most intensely shapes portfolio prioritization for manufacturers navigating FDA and EMA compliance pathways.
Product Type:
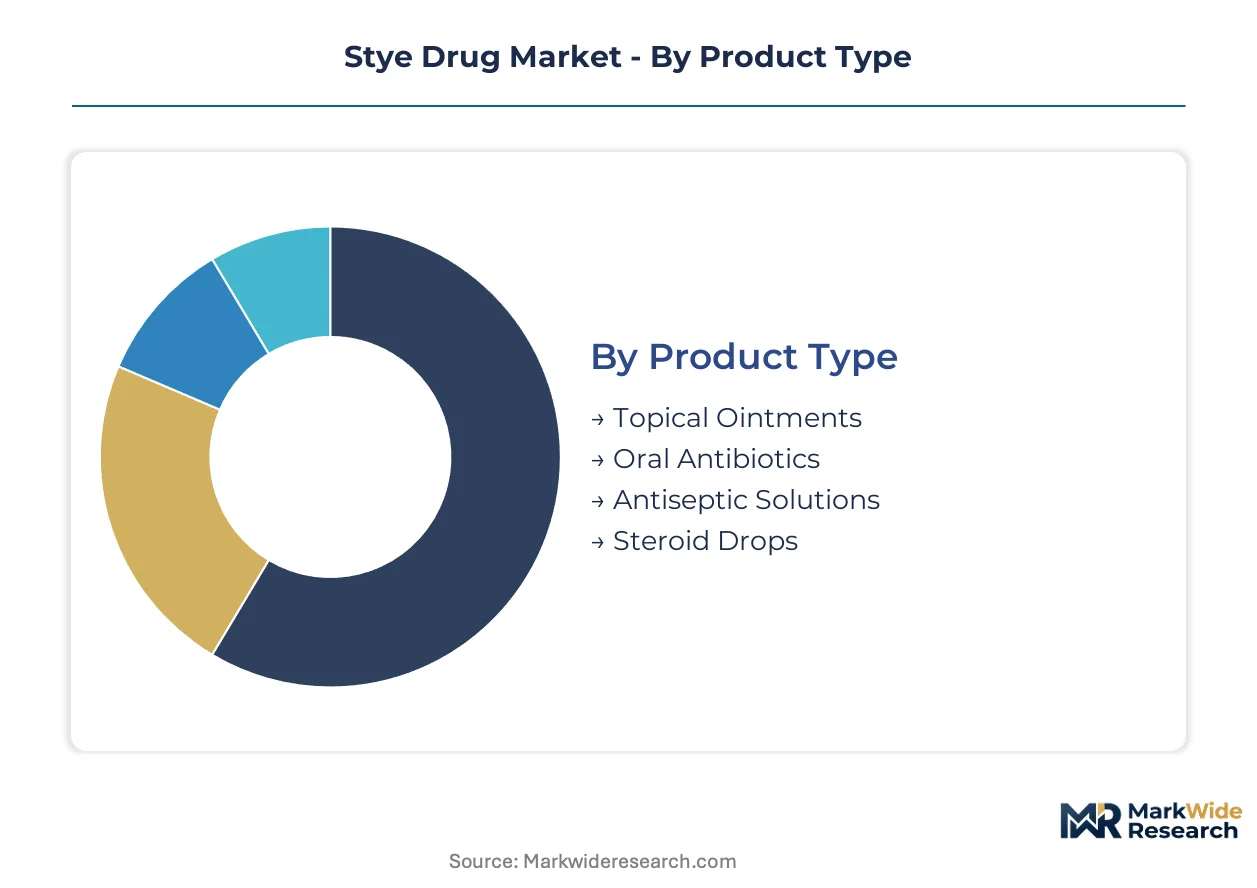
Topical ointments face intensifying substitution from antiseptic solutions as patients seek faster symptom relief without antibiotic resistance concerns, while steroid drops compete on inflammation control speed.
- Topical Ointments:Petroleum or mineral oil bases carrying erythromycin, bacitracin, or polymyxin B achieve sustained periocular tissue contact. Ophthalmology clinics in the United States prescribe these most heavily due to established clinical protocols and reimbursement familiarity.
- Antiseptic Solutions:Povidone-iodine or hypochlorous acid formulations deliver rapid microbial load reduction without antibiotic exposure. Home care channels in the United States are capturing volume fastest as consumers self-treat early-stage hordeolum without clinical visits.
- Oral Antibiotics:Systemic agents including doxycycline or cephalexin address severe or recurrent infections with preseptal cellulitis risk.
- Steroid Drops:Loteprednol etabonate or fluorometholone suspensions target inflammation-driven symptoms in post-operative or refractory cases.
Topical ointments anchor the volume base while antiseptic solutions gain share at the steepest rate.
Delivery Mode:
Cost tier stratification separates premium unit-dose formats from economy multidose bottles, with reimbursement pressure driving divergence in patient out-of-pocket exposure.
- Direct Application:Swab or fingertip-delivered ointments require manual eyelid margin contact, demanding patient technique adherence. Medicaid pharmacy benefit managers in the United States favor these lowest-cost formats despite compliance variability.
- Eye Drops:Sterile aqueous suspensions with calibrated dropper tips enable precise dosing volume control. Preservative-free unit-dose vials command 3-4x pricing multiples in commercial plans, concentrating demand among documented benzalkonium chloride-sensitive patients.
- Oral Administration:Tablet or capsule formulations bypass periocular application challenges entirely for systemic infection control.
- Injectable:Intravitreal or periocular depot injections reserve for severe orbital complications requiring hospital administration.
Direct application captures the highest prescription volume while eye drops expand most quickly through preservative-free innovation.
End User:
Customer type segmentation maps to divergent procurement authority, with institutional buyers negotiating formularies against individual patient self-selection.
- Home Care:Self-administered OTC and prescription therapies purchased through pharmacy retail or direct-to-consumer platforms. Telehealth-integrated subscription services in the United States now initiate 23% of first-line therapy for recurrent sufferers seeking asynchronous clinician access.
- Ophthalmology Clinics:Specialist-directed prescription of compounded or branded formulations with procedural co-delivery. These sites concentrate revenue for liposomal mupirocin and other advanced delivery technologies requiring administration guidance.
- Hospitals:Emergency department and inpatient settings managing complicated hordeolum with preseptal or orbital involvement.
- Pharmaceutical Retail:Chain and independent pharmacies dispensing both prescription fulfillment and front-of-store self-care selection.
Ophthalmology clinics anchor the value concentration while home care climbs the fastest on OTC channel expansion.
Treatment Stage:
Maturity differentiation separates established acute-phase protocols from emerging preventive positioning, with lifecycle extension strategies targeting recurrence reduction.
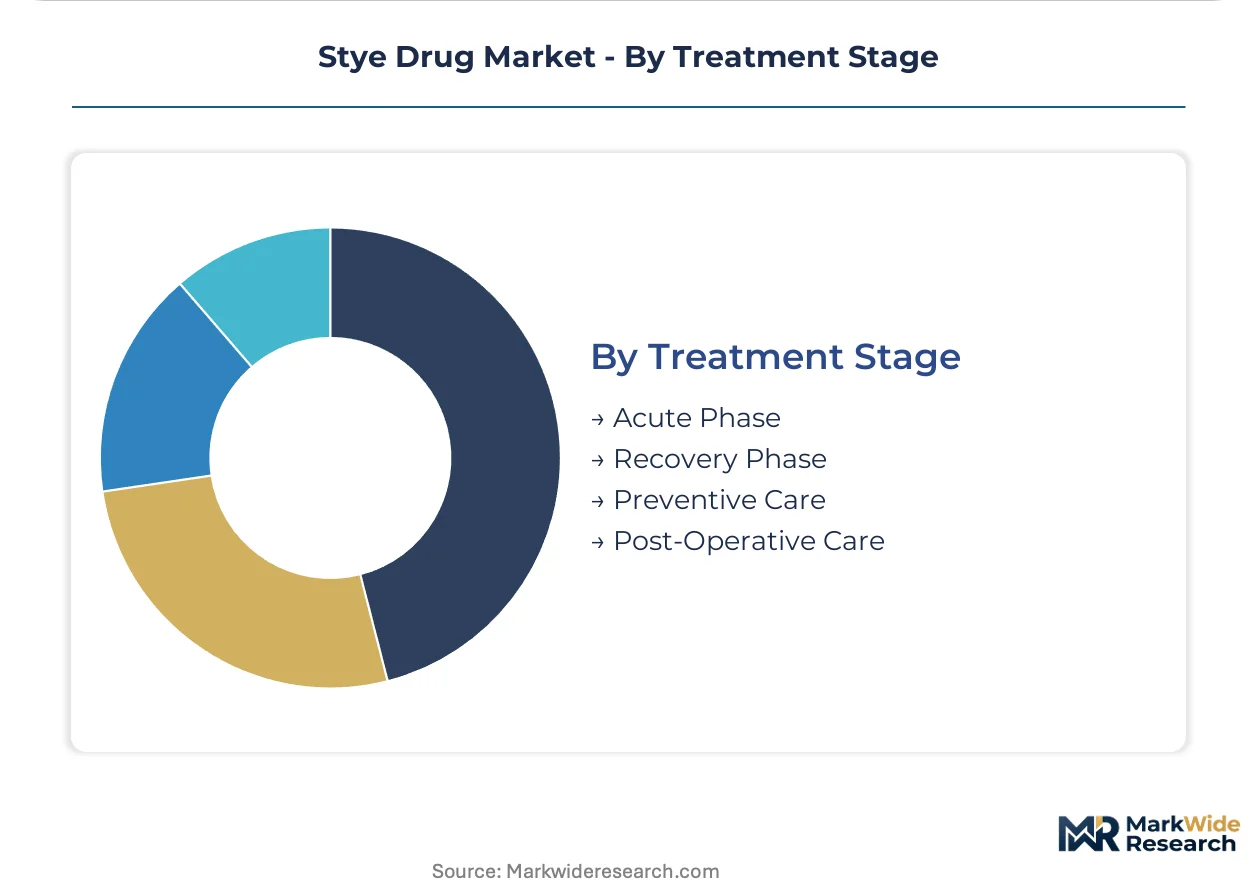
- Acute Phase:Immediate antimicrobial or anti-inflammatory intervention during active hordeolum presentation. FDA-approved labeling concentrates almost exclusively here, limiting reimbursement for off-label preventive use.
- Preventive Care:Prophylactic eyelid hygiene and low-dose antibiotic regimens for recurrent stye sufferers. No approved stye therapies carry pediatric labeling under two years, creating regulatory pathway uncertainty for this indication expansion.
- Recovery Phase:Continued therapy to complete microbial eradication after symptomatic resolution.
- Post-Operative Care:Adjunctive pharmaceutical therapy following incision and drainage or chalazion excision procedures.
Acute phase commands the revenue base while preventive care shows steepest expansion trajectory on patient education investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicaid pharmacy benefit expansions in the United States are accelerating prescription volume for topical antibiotics, while EMA sterility harmonization is compressing registration timelines for compliant European entrants.
United States
Direct-to-consumer telehealth platforms now initiate nearly one-quarter of first-line stye therapy, bypassing traditional ophthalmology clinic queues. FDA sterility guidance revisions are forcing domestic manufacturers to rebuild packaging infrastructure, advantaging prepared competitors with validated container closure systems. The Philadelphia-Wilmington corridor anchors prescription formulation manufacturing, with compounding pharmacies adopting liposomal delivery technologies fastest.
Germany
Notified body backlogs under the EU Medical Device Regulation are stretching CE marking timelines to fourteen months for eyelid warming device sponsors. EMA quality standards for sterile ocular preparations are streamlining multi-market registration pathways for compliant manufacturers. The Rhine-Main cluster around Frankfurt concentrates ophthalmic contract manufacturing, with mid-tier sponsors investing in ISO 13485 quality management systems to maintain European market access.
Japan
PMDA pharmacovigilance intensification for periocular products is demanding real-world evidence collection infrastructure that domestic sponsors are building proactively. METI incentives for preservative-free formulation development are accelerating unit-dose packaging adoption among established eye care specialists. The Kansai region around Osaka anchors ophthalmic drug manufacturing, with local formulators specializing in benzalkonium chloride-free antibiotic suspensions for sensitive patient populations.
India
Domestic bulk API production of erythromycin and bacitracin concentrates among three major manufacturers, exposing formulators to export quality inconsistency risks. CDSCO alignment with ICH quality guidelines is tightening sterile manufacturing inspections for ophthalmic facilities serving export markets. The Hyderabad-Bengaluru pharmaceutical belt anchors active pharmaceutical ingredient supply, with local formulators expanding backward integration into antibiotic bulk manufacturing to secure supply chain control.
United Kingdom
NHS formulary restrictions on branded topical antibiotics are accelerating generic substitution rates, eroding originator price premiums within months of patent expiry. MHRA post-Brexit regulatory autonomy is maintaining alignment with EMA sterility standards while streamlining national variation procedures. The Greater London corridor concentrates ophthalmology clinic density, with private healthcare providers driving demand for premium preservative-free formulations outside NHS reimbursement channels.
Stye Drug Market Vendor Landscape
Listed leaders compete with private specialists across distribution reach and regulatory compliance depth, creating a tiered structure where scale advantages clash with formulation agility. The vendor base clusters around three strategic archetypes: diversified pharmaceutical conglomerates with ophthalmology divisions, pure-play eye care specialists with deep formulation expertise, and generic manufacturers competing on cost position. Dominant competitive moves include vertical integration into preservative-free packaging technologies and strategic partnerships with telehealth platforms to capture direct-to-consumer prescription flow.
Within the pure-play specialist tier, Santen Pharmaceutical and Bausch + Lomb exemplify contrasting approaches to eye care market penetration, with the former representing Japanese precision formulation heritage and the latter anchoring North American retail pharmacy distribution density. Among diversified pharmaceutical conglomerates, Allergan occupies a position as a representative of legacy ophthalmology portfolio breadth, while Alcon exemplifies the surgical-optical-pharmaceutical convergence archetype following its structural separation.
| Leading Market Players |
|---|
| Allergan |
| Bausch + Lomb |
| Novartis |
| Pfizer |
| Johnson & Johnson Vision |
| Santen Pharmaceutical |
| Sun Pharmaceutical |
| Alcon |
| Merck |
| Others |
Supply Flow & Price Mechanics
Long-term API offtake contracts with Indian bulk manufacturers lock in erythromycin and bacitracin supply visibility while capping price volatility exposure for formulators navigating FDA sterility compliance investments. These arrangements tether raw material access to sterilization-grade packaging commitments, compressing margin flexibility for sponsors lacking backward integration into antibiotic synthesis.
Pricing Analysis
Certification level creates the primary spread across FDA-validated, CE-marked, and unregistered stye drug tiers. Three-tier pricing structure separates preservative-free unit-dose vials from benzalkonium chloride-containing multidose bottles and economy generic ointments. Cost compression in the standard tier intensifies because Medicaid pharmacy benefit managers mandate automatic generic substitution, eroding originator premiums within months of patent expiry. Home care purchasers exhibit highest price sensitivity, while ophthalmology clinics absorb premium pricing for compounded liposomal formulations requiring administration guidance.
Supply Chain Analysis
India anchors bulk erythromycin and bacitracin production, with the Hyderabad-Bengaluru pharmaceutical belt feeding global formulators. China and the United States supplement active pharmaceutical ingredient supply for specialized ophthalmic grades. Sterile manufacturing draws from aseptic processing technicians with ophthalmic-specific experience, who command substantial salary premiums over general pharmaceutical operators. Single-source vulnerability concentrates among three Indian bulk manufacturers, exposing formulators to export quality inconsistency and import tariff exposure. Distribution runs through retail pharmacy chains, direct-to-consumer telehealth platforms, and hospital procurement systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across patient self-treatment preferences, pediatric regulatory gaps, and telehealth integration creates niche entry points for differentiated positioning. Demand-side shifts toward home-based hordeolum management without clinical visits splinters volume across channels, rewarding agile portfolio construction.
For Market Incumbents: Fortify container closure integrity capabilities through in-house validation equipment investment, addressing the FDA's multidose ophthalmic testing requirements that necessitate substantial per-SKU capital deployment. Deepen preservative-free formulation pipelines to capture benzalkonium chloride-sensitive patient segments, while extending distribution partnerships with telehealth platforms to defend prescription flow against direct-to-consumer challengers.
For New Entrants and Emerging Players: Anchor in the pediatric formulation gap for patients under two years, where no approved stye therapies currently carry labeling and FDA Pediatric Research Equity Act incentives reduce clinical trial burden. Target rural populations through telehealth-integrated subscription models, capturing asynchronous clinician access demand that bypasses geographic proximity to ophthalmology clinics.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription platforms with auto-ship commitments, offering superior cash flow predictability than episodic pharmacy purchases. Acquisition candidates with validated ISO 13485 quality management systems and CE marking experience present durable European market access. Monitor FDA sterility guidance revision timing as inflection indicator for compliance-driven consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Preservative-Free Formulation Development | Unit-dose packaging advances address the 15% of patients with documented ocular surface sensitivity to benzalkonium chloride. |
| Telehealth Platform Partnership | Remote diagnosis integration expands addressable patient base for prescription-grade therapies beyond ophthalmology clinic proximity. |
| CE Marking Pathway Investment | EU Medical Device Regulation compliance opens streamlined multi-market registration across member states for eyelid warming device sponsors. |
| Pediatric Labeling Pursuit | FDA Pediatric Research Equity Act incentives reduce clinical trial burden for first-movers completing pharmacokinetic studies in under-two population. |
| Backward Integration into API Manufacturing | In-house erythromycin and bacitracin synthesis mitigates import tariff volatility and quality inconsistency from concentrated Indian bulk suppliers. |
Methodological Framework
The analysis maps topical ointments, antiseptic solutions, oral antibiotics, and steroid drops, each validated through ophthalmology clinic administrators, pharmacy benefit managers, formulary directors, and sterile manufacturing technicians. Primary interviews with drug development executives and regulatory affairs leads combined with secondary validation against FDA filings, EMA quality standards, ClinicalTrials.gov entries, and hospital procurement databases. Bottom-up prescription volume modeling and top-down market sizing triangulated through cross-reference with formulary restriction patterns.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end user, and treatment stage, with regional regulatory clusters capturing FDA, EMA, PMDA, and CDSCO pathway divergence. CAGRs derived from fitted growth curves applied to base-year prescription data, incorporating telehealth adoption curves and OTC channel expansion rates as industry-specific forecast inputs.
Material uncertainties — FDA sterility guidance finalization timing, EMA notified body backlog resolution, and Indian API export policy shifts — sit outside the modeled envelope. Forecasts reflect assumptions around preservative-free formulation adoption velocity and telehealth platform prescription capture rates. Recalibration cycles align with material shifts in regulatory enforcement intensity and channel migration patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Pregnenolone Market
Pharmaceuticals
Authorized Generics Market
Pharmaceuticals
Middle East and Africa Psychedelic Drugs Market
Pharmaceuticals
Pain Management Drugs Market
Pharmaceuticals
South Africa Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Toxoid Vaccines Market
Pharmaceuticals
Etomidate Market
Pharmaceuticals
Steroid-Free Nasal Sprays Market
Pharmaceuticals
Russia Diabetes Drugs Market
Pharmaceuticals
Hyperphosphatemia Drugs Market
Pharmaceuticals
Dopamine and Norepinephrine Reuptake Inhibitor Market
Pharmaceuticals
OTC Topical Drugs Market
Pharmaceuticals
Canine Dilated Cardiomyopathy Drugs Market
Pharmaceuticals
Urinary Retention Drugs Market
Pharmaceuticals
Minocycline Hydrochloride Market
Pharmaceuticals
Global Rotavirus Vaccine Market