
 Leukotriene Inhibitors Market | 2026-2036
Leukotriene Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Leukotriene Inhibitors Market Foresight
Active pharmaceutical ingredient production in India is repositioning supply chains for generic leukotriene inhibitors. Merck & Co. sustains brand recognition through original montelukast chemistry expertise. AstraZeneca differentiates via respiratory portfolio breadth spanning biologics and small molecules. Teva Pharmaceutical Industries leverages vertical manufacturing scale to compete on zafirlukast supply.
Leukotriene inhibitors are selective antagonists of cysteinyl leukotriene receptors or 5-lipoxygenase pathway blockers, formulated as tablets, oral granules, or inhalation devices to interrupt bronchoconstriction and eosinophilic inflammation in asthma and allergic rhinitis. Montelukast dominates prescription volume across pediatric and adult maintenance protocols, while oral granule demand accelerates in age groups below six years where tablet administration fails. The therapeutic area segmentation reveals asthma as the mature revenue base, with allergic rhinitis representing the faster-expanding indication as seasonal prescription patterns lengthen.
FDA bioequivalence requirements and EMA quality guidelines govern generic substitution and cross-border API sourcing for this drug class. The EPA and national environmental regulators impose solvent emission limits on 5-lipoxygenase inhibitor synthesis facilities, raising compliance costs for batch manufacturers. Stakeholders must monitor evolving pharmacovigilance signals around neuropsychiatric side effects, as label restrictions would reshape prescribing behavior across hospital and homecare channels without warning.
Market Dynamics
Hospital procurement of oral granule formulations is tightening pediatric asthma protocols while FDA and EMA bioequivalence standards for generic montelukast reshape manufacturer qualification requirements across supply chains.
Growth Catalysts
- EMA Quality Guidelines:Cross-border API sourcing rules for generic substitution are accelerating qualified supplier consolidation across European manufacturing networks.
- Pediatric Formulation Demand:Oral granule protocols for patients below six years are expanding hospital pharmacy procurement volumes where tablet administration fails.
- Specialty Pharmacy Networks:United States distribution infrastructure for maintenance therapy dispensing is concentrating prescription fulfillment into high-efficiency channels.
Market Restraints
- 5-Lipoxygenase Synthesis Costs:EPA solvent emission limits on batch manufacturing facilities are raising environmental compliance expenditures for API producers.
- Indian API Concentration:Active pharmaceutical ingredient production repositioning has created geographic supply vulnerability for generic leukotriene inhibitor feedstocks.
- Neuropsychiatric Label Risk:Evolving FDA pharmacovigilance signals around montelukast behavioral side effects threaten prescriber confidence without warning.
Strategic Opportunities
- Allergic Rhinitis Indication:Seasonal prescription pattern lengthening is creating faster-expanding revenue potential beyond mature asthma maintenance protocols.
- Inhalation Device Convergence:Dry powder inhaler technology integration with leukotriene pathway blockers is opening combination therapy positioning against biologics.
- Environmental Regulatory Tailwinds:EU Green Deal solvent reduction mandates are favoring manufacturers with green chemistry capabilities in 5-lipoxygenase inhibitor synthesis.
Industry Challenges
- Bioequivalence Study Talent:FDA statistical reviewer capacity constraints are extending generic montelukast approval timelines for ANDA filers.
- Cross-Border Qualification Complexity:EMA-FDA mutual recognition agreement gaps are forcing duplicate facility inspections for multinational API suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leukotriene Inhibitors Market |
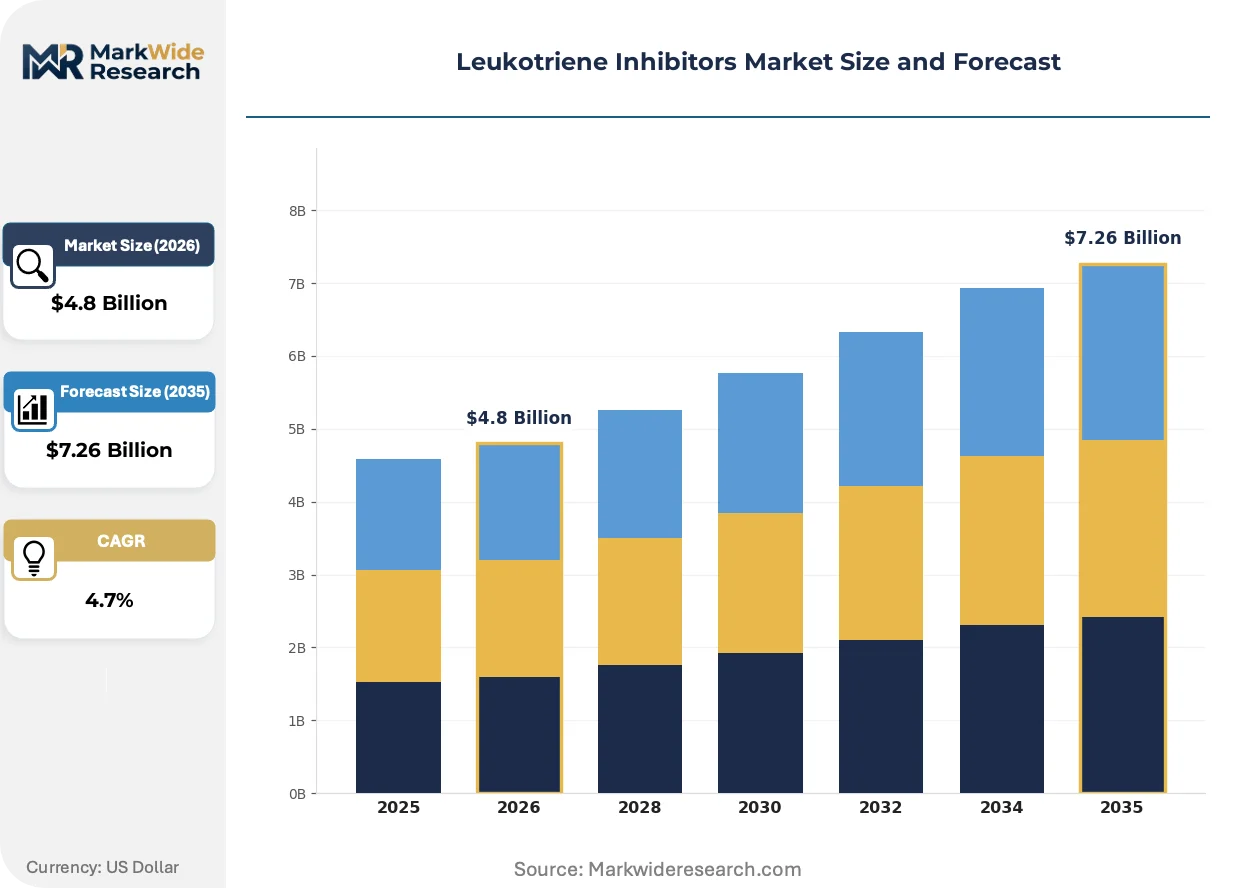
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Montelukast, Zafirlukast, Pranlukast, Other End User: Hospitals, Clinics, Pharmacies, Homecare Formulation: Tablets, Oral Granules, Liquid, Inhalation Therapeutic Area: Asthma, Allergic Rhinitis, Chronic Obstructive Pulmonary Disease, Others |
| Companies Covered | Merck & Co., AstraZeneca, GlaxoSmithKline, Teva Pharmaceutical Industries, Novartis AG, Cipla, Sun Pharmaceutical Industries, Viatris, Dr. Reddy's Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leukotriene Inhibitors Market Shifts & Advancements
Formulation science advances and regulatory harmonization pressures are compressing development cycles while reshaping competitive differentiation around pediatric delivery systems and environmental manufacturing credentials.
Continuous manufacturing technology for oral granule production is unifying powder processing and packaging operations into single-line configurations. Pediatric-focused contract manufacturers in the United States are adopting these systems to meet hospital pharmacy just-in-time delivery requirements. The technology is unifying quality control and release testing into real-time monitoring, collapsing batch release timelines from weeks to hours.
REACH authorization requirements for residual solvents in pharmaceutical intermediates are tightening supply chain documentation standards for European API importers. Manufacturers must now demonstrate full substance volume tracking from synthesis through formulation. Generic montelukast suppliers sourcing from Indian facilities face the steepest compliance adaptation costs under these expanded obligations.
Hospital formularies are consolidating maintenance therapy purchasing into single-source contracts with specialty pharmacy distributors. Independent retail channels are losing asthma protocol prescription volume to integrated health system pharmacies with 90-day dispensing capabilities. This concentration is most visible in United States metropolitan markets where accountable care organization pharmacy networks dominate pediatric chronic disease management.
Leukotriene Inhibitors Market Segmentation
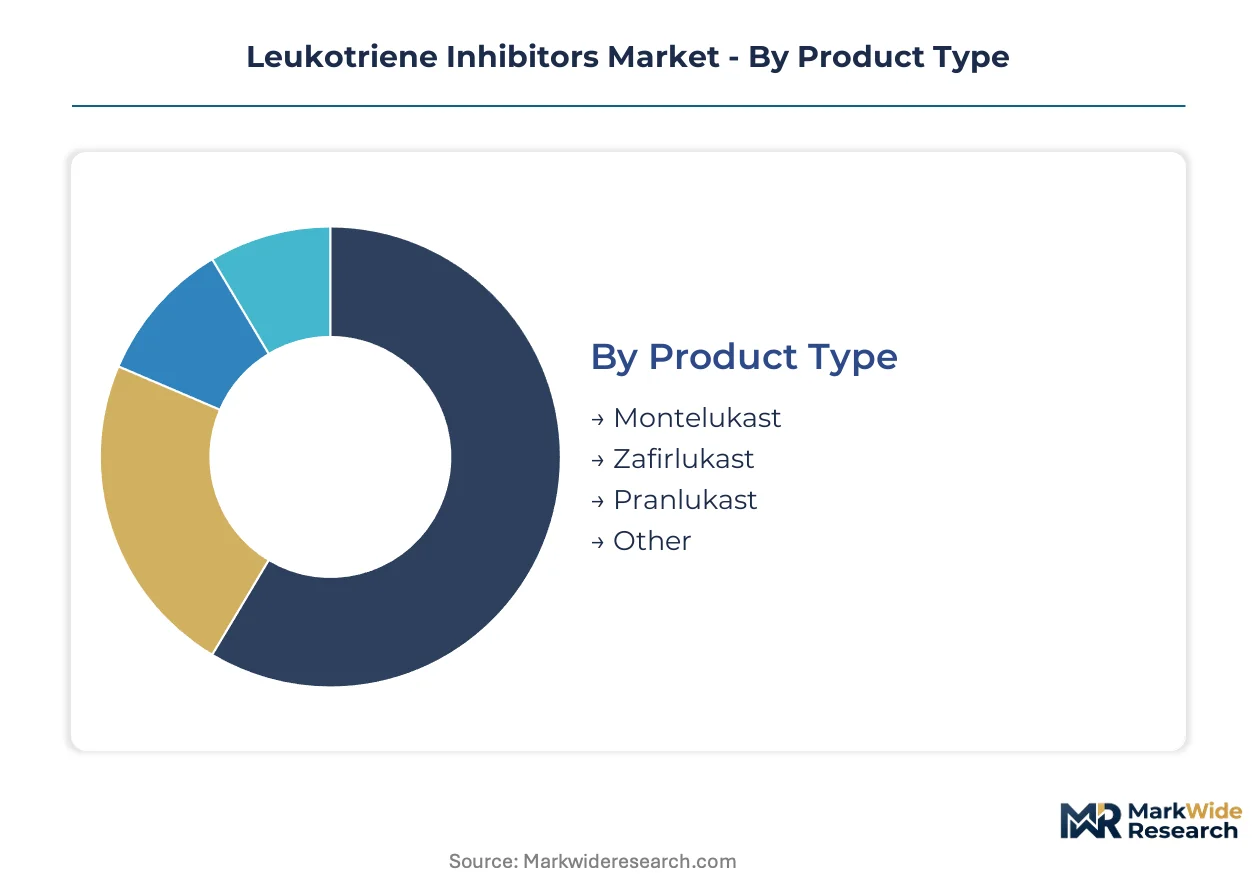
Leukotriene inhibitor segmentation reveals how formulation technology, patient age demographics, and care setting economics split prescription volume across distinct commercial battlegrounds. Each axis carries unique regulatory, reimbursement, and manufacturing implications that reshape competitive strategy.
Product Type:
Receptor selectivity and 5-lipoxygenase pathway targeting define the pharmacological differentiation between agents.
- Montelukast:Cysteinyl leukotriene receptor antagonist with once-daily oral dosing and established pediatric labeling. Hospital formularies in the United States prioritize this agent for maintenance therapy protocols due to comprehensive age-range approvals and generic availability.
- Zafirlukast:Competitive receptor antagonist requiring twice-daily administration with narrower therapeutic window considerations. Demand concentrates in specialty clinics managing adult patients with specific comorbidity profiles where montelukast tolerability concerns arise.
- Pranlukast:Japanese-developed receptor antagonist with regional regulatory approvals limiting commercial footprint. Prescription volume remains concentrated in East Asian markets where original regulatory pathways established clinical precedent.
- Other:5-lipoxygenase inhibitors including zileuton and experimental pipeline compounds with hepatotoxicity monitoring requirements.
Montelukast leads on scale; Other agents lead on momentum through pipeline 5-lipoxygenase inhibitors addressing unmet efficacy needs.
End User:
Care setting infrastructure determines reimbursement mechanics, prescription duration, and patient monitoring intensity.
- Hospitals:Integrated health system pharmacies with 90-day dispensing capabilities and specialty pharmacy distribution contracts. Pediatric asthma protocol centralization in United States metropolitan accountable care organization networks drives procurement consolidation.
- Clinics:Outpatient respiratory specialty centers with biologic co-prescription patterns and step-therapy authorization workflows.
- Pharmacies:Independent retail channels losing maintenance therapy volume to integrated systems, though seasonal allergic rhinitis demand sustains counter-prescription relevance.
- Homecare:Pediatric oral granule administration support services and chronic disease management programs with nurse educator deployment.
Hospitals command procurement volume concentration; Homecare represents the steepest expansion trajectory through pediatric chronic disease management program growth.
Formulation:
Delivery system engineering directly addresses age-specific administration barriers and bioavailability optimization.
- Tablets:Standard oral solid dosage with established bioequivalence testing frameworks and mature generic substitution pathways. Adult maintenance protocols and older pediatric patients drive prescription volume in United States specialty pharmacy networks.
- Oral Granules:Powder-in-packet formulation enabling administration to patients below six years where tablet swallowing fails. Continuous manufacturing technology adoption by United States contract manufacturers supports hospital pharmacy just-in-time delivery requirements.
- Liquid:Suspension formulations for patients with dysphagia or specific palatability requirements in younger age brackets.
- Inhalation:Dry powder and metered-dose device integration with leukotriene pathway blockers, currently experimental but positioning for combination therapy against biologics.
Tablets dominate manufacturing scale; Oral Granules gain share fastest through pediatric protocol tightening.
Therapeutic Area:
Indication-specific clinical endpoints and seasonal prescription patterns reshape revenue stability and marketing investment returns.
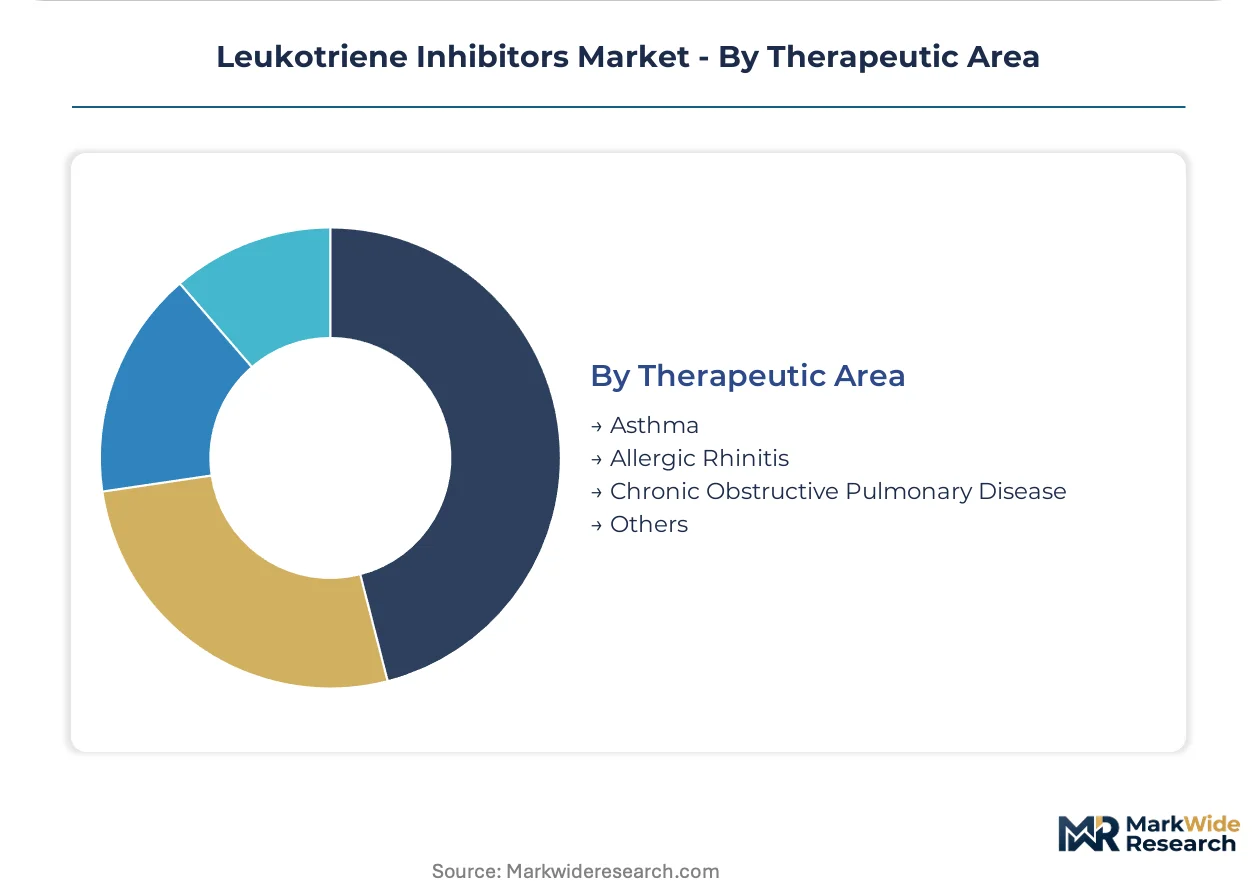
- Asthma:Mature maintenance therapy indication with established step-care guidelines and biologic escalation pathways. Hospital formularies treat this as foundational chronic respiratory management with long prescription duration economics.
- Allergic Rhinitis:Seasonal and perennial nasal inflammation indication with expanding prescription pattern lengthening as climate change extends pollen seasons. Faster-expanding revenue potential compared to asthma maintenance protocols.
- Chronic Obstructive Pulmonary Disease:Off-label and investigational use with limited regulatory approval, though some health systems explore leukotriene modulation in specific phenotypes.
- Others:Urticaria, exercise-induced bronchoconstriction, and emerging inflammatory indications with small commercial footprint.
Asthma anchors revenue stability; Allergic Rhinitis climbs the fastest through seasonal pattern extension and indication awareness expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing active pharmaceutical ingredient production toward jurisdictions with streamlined environmental compliance frameworks, while finished formulation manufacturing clusters in higher-regulation markets capture value-added margins through pediatric specialization.
United States
Specialty pharmacy networks in metropolitan accountable care organizations concentrate maintenance therapy dispensing for pediatric asthma protocols. FDA bioequivalence standards for generic montelukast reshape manufacturer qualification timelines for ANDA filers. Greater Boston and Research Triangle Park host contract manufacturing organizations adopting continuous oral granule production for hospital just-in-time delivery.
Germany
REACH authorization requirements for residual solvents in pharmaceutical intermediates tighten supply chain documentation for API importers. EMA quality guidelines accelerate qualified supplier consolidation across European manufacturing networks. The Rhine-Ruhr industrial corridor maintains formulation packaging operations serving hospital pharmacy networks across the continent.
India
Active pharmaceutical ingredient production for generic leukotriene inhibitors repositioning has created geographic supply vulnerability for global feedstock security. CDSCO manufacturing facility inspections align with FDA and EMA mutual recognition frameworks for export qualification. Gujarat and Telangana pharmaceutical clusters dominate 5-lipoxygenase inhibitor intermediate synthesis for international generic suppliers.
Japan
Pranlukast prescription volume remains concentrated in domestic markets where original regulatory pathways established clinical precedent decades prior. PMDA pharmacovigilance monitoring tracks neuropsychiatric signal evolution for leukotriene receptor antagonists. The Kansai region maintains regional formulation manufacturing serving East Asian distribution networks.
United Kingdom
Seasonal allergic rhinitis prescription pattern lengthening drives faster-expanding demand as climate change extends pollen seasons. MHRA post-Brexit regulatory divergence creates parallel approval pathways for generic substitution frameworks. The Southeast England pharmaceutical corridor specializes in pediatric oral granule packaging for hospital formulary contracts.
Leukotriene Inhibitors Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue green chemistry credentials and pediatric formulation specialization. The market structure reflects moderate consolidation around original chemistry expertise and vertical manufacturing scale, with generic suppliers competing on bioequivalence approval velocity. Three archetypes dominate: originators with brand recognition, integrated generic manufacturers with API-to-formulation control, and pediatric-focused contract specialists. Competitive moves center on environmental manufacturing certification acquisition and continuous processing technology licensing.
Within the originator tier, Merck & Co. and AstraZeneca exemplify distinct strategic positioning—Merck sustaining brand recognition through original montelukast chemistry expertise, AstraZeneca differentiating via respiratory portfolio breadth spanning biologics and small molecules. Among integrated generic manufacturers, Teva Pharmaceutical Industries occupies a position leveraging vertical manufacturing scale to compete on zafirlukast supply. Indian-origin specialists including Cipla and Sun Pharmaceutical Industries represent the API-to-formulation archetype with repositioned supply chain footprints.
| Leading Market Players |
|---|
| Merck & Co. |
| AstraZeneca |
| GlaxoSmithKline |
| Teva Pharmaceutical Industries |
| Novartis AG |
| Cipla |
| Sun Pharmaceutical Industries |
| Viatris |
| Dr. Reddy's Laboratories |
| Others |
Supply & Pricing Matrix
Hospital pharmacy procurement consolidation into specialty pharmacy networks anchors pricing power for oral granule formulations, compressing distributor margins while rewarding manufacturers with pediatric FDA labeling and continuous manufacturing certification.
Pricing Analysis
Distributor margin compression in United States specialty pharmacy channels is intensifying as hospital formularies consolidate into single-source contracts with 90-day dispensing capabilities. Generic montelukast pricing stratifies across originator brand premiums, FDA bioequivalence-certified generics, and economy-tier Indian API-sourced alternatives. Cost compression in the economy tier reflects EMA and FDA inspection backlogs delaying ANDA approvals. Pediatric hospitals demonstrate lowest price sensitivity due to protocol rigidity, while independent retail pharmacies face highest sensitivity as maintenance therapy volume migrates to integrated health systems.
Supply Chain Analysis
Freight cost volatility for temperature-controlled 5-lipoxygenase inhibitor intermediates is elevating landed costs for European formulators sourcing from Indian API clusters. Active pharmaceutical ingredient production concentrates in India, China, and the United States, with Gujarat and Telangana pharmaceutical corridors dominating generic leukotriene inhibitor feedstock synthesis. Formulation manufacturing draws from acetone and dichloromethane solvent supplies subject to REACH authorization documentation requirements. Single-source vulnerability in Indian API concentration threatens supply continuity during CDSCO-FDA mutual recognition inspection delays. Distribution runs through specialty pharmacy distributors with hospital system integration in metropolitan accountable care organization networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on continuous manufacturing adoption reducing oral granule production costs and allergic rhinitis indication premium positioning extending seasonal prescription capture.
For Market Incumbents:Acquire continuous manufacturing technology licenses to collapse batch release timelines from weeks to hours and defend against pediatric-focused contract manufacturers. Secure backward integration into 5-lipoxygenase inhibitor intermediate synthesis to offset EPA solvent emission compliance cost inflation. Prioritize EMA quality guideline certification to maintain European hospital formulary positioning against Indian API competitors facing REACH documentation adaptation costs.
For New Entrants and Emerging Players:The mid-tier pricing gap between originator montelukast and economy generic alternatives creates entry space for bioequivalence-certified suppliers with green chemistry credentials. Target United States metropolitan accountable care organization pharmacy networks with just-in-time oral granule delivery capabilities. Pursue FDA bioequivalence approval velocity advantage over Indian competitors constrained by statistical reviewer capacity bottlenecks.
For Investors and Strategic Acquirers:Specialty pharmaceutical manufacturers with respiratory portfolio breadth are the most active acquirer in this space, seeking pediatric formulation capabilities to complement biologic pipelines. The five-to-ten year viability window favors targets with environmental regulatory certification ahead of EU Green Deal solvent reduction mandates. Acquisition target archetype: contract manufacturers with continuous oral granule production installed in Greater Boston or Research Triangle Park. Monitor FDA pharmacovigilance signal evolution around neuropsychiatric side effects as inflection indicator for prescriber confidence shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Adoption | Collapses oral granule batch release timelines from weeks to hours for hospital just-in-time contracts. |
| Green Chemistry Certification | Positions API suppliers favorably under EU Green Deal solvent reduction mandates for 5-lipoxygenase synthesis. |
| Pediatric Formulation Specialization | Captures oral granule demand growth in patients below six years where tablet administration fails. |
| Allergic Rhinitis Indication Expansion | Extends revenue capture as climate change lengthens seasonal prescription patterns beyond asthma maintenance. |
| Specialty Pharmacy Network Integration | Secures 90-day dispensing contracts with United States accountable care organization hospital systems. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down API production tracking forms the analytical core of this study. Primary interviews with formulary directors, regulatory affairs leads at generic manufacturers, pediatric pulmonologists, and specialty pharmacy distribution executives combined with secondary validation from FDA ANDA filings, EMA quality guideline documentation, ClinicalTrials.gov protocol registries, and hospital procurement databases. Cross-referencing prescription volume data against manufacturing capacity disclosures enables supply-demand reconciliation across the analysis window.
Input-output matrices map montelukast, zafirlukast, and pranlukast demand flows through formulation type, therapeutic area indication, patient age demographic, and care setting infrastructure dimensions across the projection horizon. CAGRs derive from segmented volume trajectory modeling incorporating pediatric protocol adoption rates, generic substitution elasticity, and seasonal prescription pattern extension. Forecast inputs include EPA solvent emission compliance cost projections and CDSCO inspection capacity assumptions for Indian API export qualification.
Caveats apply where FDA pharmacovigilance label restrictions, EMA-FDA mutual recognition agreement gaps, or Indian API supply disruptions could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Antiemetics Market
Pharmaceuticals
Bisphosphonates Market
Pharmaceuticals
Opioid Induced Constipation Drug Market
Pharmaceuticals
Global Acyclovir Market
Pharmaceuticals
Estonia Pharmaceutical Market
Pharmaceuticals
Anticonvulsants Market
Pharmaceuticals
Blood Coagulants Market
Pharmaceuticals
Bipolar Disorder Drugs and Treatment Market
Pharmaceuticals
Direct Oral Anticoagulants Market
Pharmaceuticals
Pantoprazole Market
Pharmaceuticals
Long-Acting Insulin Market
Pharmaceuticals
Global Fibrinogen Concentrates Market
Pharmaceuticals
Global DNA Repair Drugs Market
Pharmaceuticals
Ceftriaxone Sodium (API) Market
Pharmaceuticals
Guanethidine Market
Pharmaceuticals
Otic Drugs Market