
 Anticonvulsants Market | 2026-2036
Anticonvulsants Market Size, Share, and Industry Trends Forecast 2026-2036
Anticonvulsants Market Outlook
Levetiracetam formulations is pivoting away from older hydantoin chemistry toward broader-spectrum mechanisms with improved tolerability profiles. Pfizer Inc. leverages its established hospital formulary relationships to sustain high-volume injectable distribution. Novartis AG anchors its position through deep expertise in neurology therapeutic development. UCB S.A. dominates the European epilepsy prescription landscape with a focused anticonvulsant portfolio.
Anticonvulsants comprise pharmacological compounds that modulate neuronal excitability through sodium channel blockade, GABA receptor potentiation, or calcium channel inhibition, manufactured via multi-step organic synthesis with stringent purity controls exceeding 99.5% active pharmaceutical ingredient content, primarily prescribed for seizure suppression and increasingly for neuropathic pain and mood stabilization. The epilepsy therapeutic area generates the largest revenue pool due to chronic maintenance dosing requirements, while the neuropathic pain segment commands premium pricing as off-label utilization expands in outpatient settings. Oral delivery mode retains the dominant volume share, though intravenous formulations capture disproportionate margin in acute hospital episodes.
The FDA maintains stringent bioequivalence standards for generic anticonvulsant substitutions, while the EMA's orphan drug incentives accelerate development for rare epilepsy syndromes, and Japan's PMDA imposes additional pharmacovigilance requirements that extend product lifecycle management obligations. Regulatory divergence across these jurisdictions compels manufacturers to maintain separate clinical data packages and manufacturing compliance systems. Stakeholders must monitor evolving pharmacogenomic guidance that promises to reshape patient stratification and trial design requirements.
Market Dynamics
The anticonvulsants sector faces intensifying pressure from pharmacogenomic stratification, which fragments addressable populations and demands tailored clinical trial architectures across sodium channel blockers, GABA modulators, and calcium channel inhibitors.
Growth Catalysts
- FDA Accelerated Approval:The FDA's orphan drug designation pathway compresses development timelines for rare epilepsy syndromes, drawing venture funding toward Dravet and Lennox-Gastaut indications.
- Pediatric Neurology Expansion:Rising seizure diagnosis rates in children under five drive chronic maintenance prescribing, establishing durable revenue streams for extended-release formulations.
- Neuropathic Pain Off-Label:Diabetic peripheral neuropathy and post-herpetic neuralgia applications expand outpatient utilization beyond epilepsy, capturing premium reimbursement in pain management clinics.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for levetiracetam and lamotrigine concentrates in Chinese and Indian chemical synthesis clusters, exposing formulators to tariff volatility and shipping disruptions.
- Bioequivalence Stringency:The FDA's narrow therapeutic index requirements for generic substitution create regulatory friction that protects originator pricing but delays patient access to lower-cost alternatives.
- Central Nervous System Side-Effect Burden:Cognitive slowing, mood disturbance, and teratogenicity limit patient adherence, driving discontinuation rates that compress lifetime value per prescription.
Strategic Opportunities
- Japan's Pharmacovigilance Extension:PMDA post-market surveillance obligations extend product lifecycle management service contracts, creating recurring revenue streams for safety database maintenance and signal detection.
- Intravenous Hospital Formulary:Status epilepticus protocols in emergency departments favor injectable levetiracetam over fosphenytoin, opening acute-care channels with disproportionate margin capture.
- Gene Therapy Convergence:Antisense oligonucleotide platforms paired with anticonvulsant maintenance regimens promise combination protocols for genetic epilepsy subtypes.
Industry Challenges
- Specialized Neurology Talent Scarcity:Pediatric epileptologist training programs produce insufficient fellowship graduates to staff expanding clinics, creating patient access bottlenecks that limit prescription volume growth.
- Legacy Formulation Integration:Hydantoin chemistry manufacturing lines require costly retooling to accommodate broader-spectrum mechanism production, straining capital allocation for mid-tier generic manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anticonvulsants Market |
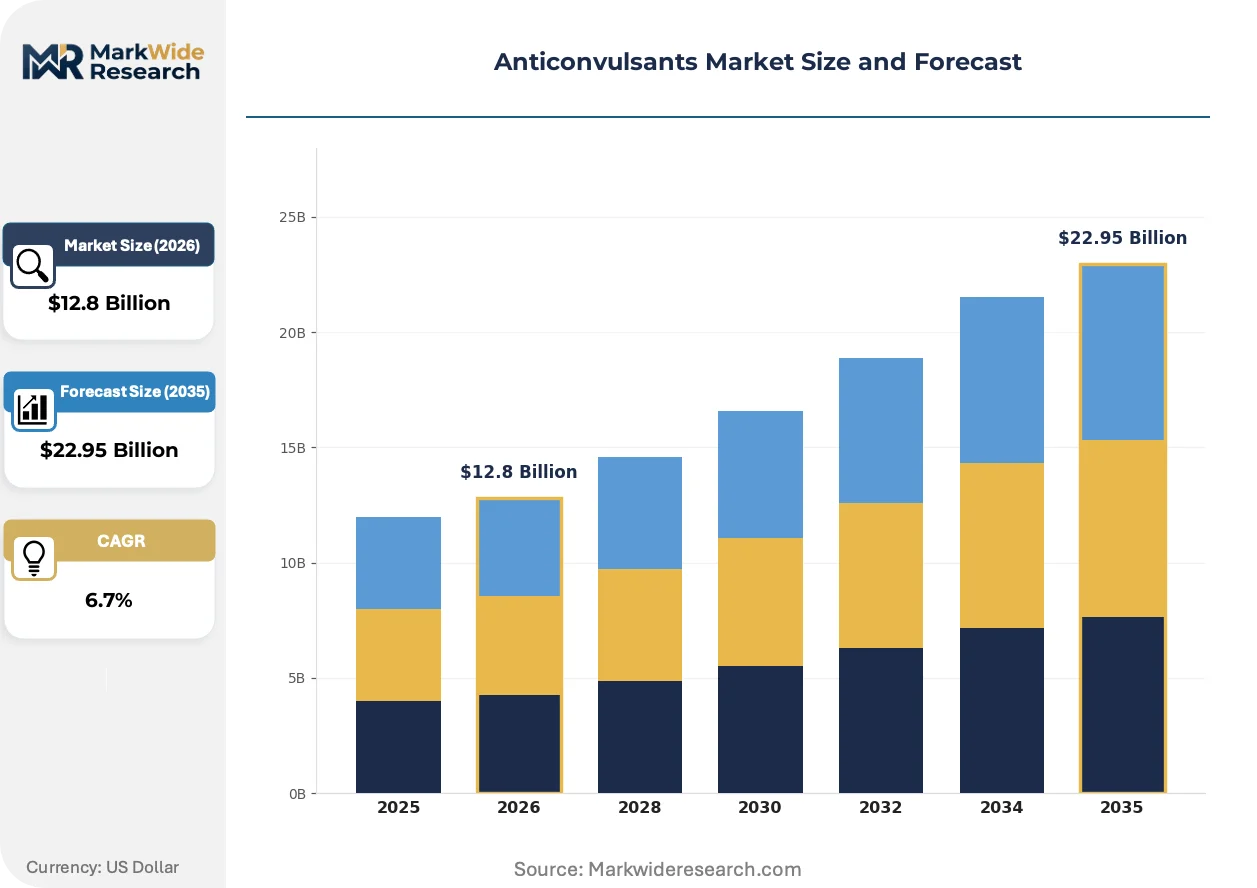
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Benzodiazepines, Barbiturates, Hydantoins, Succinimides Therapeutic Area: Epilepsy, Neuropathic Pain, Anxiety Disorders, Bipolar Disorder Delivery Mode: Oral, Injectable, Intravenous, Topical End User: Hospitals, Clinics, Homecare Settings, Rehabilitation Centers |
| Companies Covered | Pfizer Inc., Novartis AG, UCB S.A., Johnson & Johnson, GSK plc, Sanofi, AstraZeneca, Abbott Laboratories, Takeda Pharmaceutical Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anticonvulsants Market Strategic Shifts
Neuropharmacology is pivoting from empirical dosing toward biomarker-guided patient selection, compressing trial failure rates and reshaping competitive positioning around predictive diagnostic partnerships.
Continuous subcutaneous delivery systems are decentralizing seizure management from hospital-based emergency intervention toward ambulatory prevention. Epilepsy monitoring units at Cleveland Clinic and Mayo Clinic are piloting closed-loop neurostimulation paired with real-time drug delivery. This convergence is decentralizing acute-care revenue toward outpatient device-pharmaceutical bundles that capture margin from emergency department bypass.
The EMA's orphan drug incentives are accelerating rare epilepsy syndrome development by mandating pediatric investigation plans and offering protocol assistance. Manufacturers now face binding commitments to generate post-authorization efficacy data in ultra-rare populations. This regulatory architecture most affects biotech entrants targeting SCN1A or CDKL5 mutations, who must build European regulatory capabilities before US commercialization.
Hospital procurement committees are consolidating anticonvulsant purchasing through therapeutic class carve-outs that favor sole-source contracts for intravenous formulations. Academic medical centers in Texas, Pennsylvania, and Massachusetts have shifted from multi-source generics to single-supplier agreements with 90-day inventory guarantees. This concentration is most visible in Level 1 trauma centers where formulary switches cascade to affiliated community hospitals within integrated delivery networks.
Anticonvulsants Market Segmentation
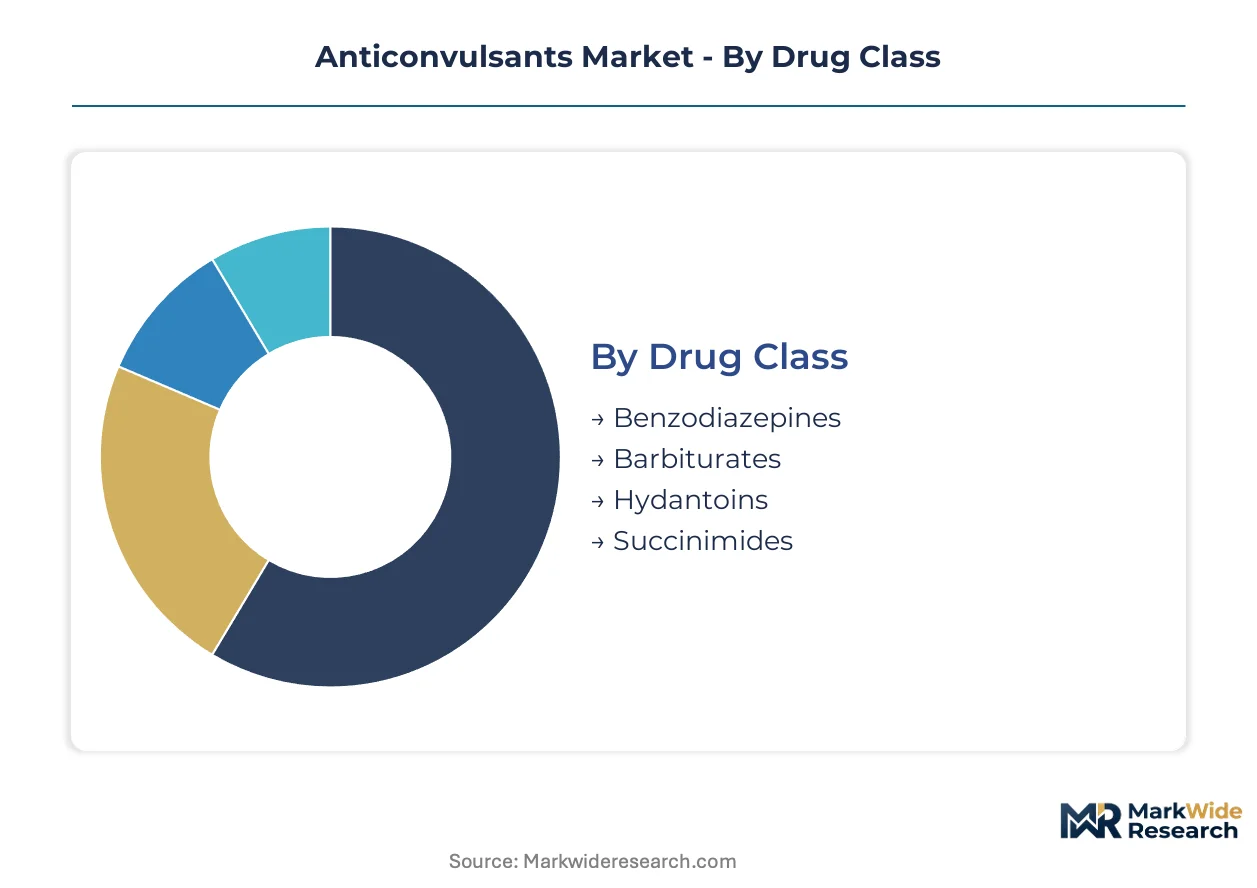
Anticonvulsant prescribing patterns fragment sharply across clinical settings and pharmacological mechanisms. Manufacturers align formulation strategies to specific therapeutic contexts rather than pursuing universal blockbusters.
Drug Class:
Standalone oral maintenance regimens dominate chronic epilepsy management, while embedded intravenous protocols integrate into hospital emergency workflows for status epilepticus intervention.
- Benzodiazepines:GABA-A receptor agonists with rapid onset characteristics. Demand clusters in acute seizure termination protocols across United States emergency departments, where lorazepam and diazepam remain first-line for convulsive emergencies despite respiratory depression liabilities.
- Hydantoins:Sodium channel blockers derived from 1908 phenytoin chemistry. German and Japanese hospital formularies retain substantial phenytoin volumes for prophylactic neurosurgical applications, though therapeutic drug monitoring requirements constrain outpatient expansion.
- Barbiturates:Older GABAergic compounds with narrow therapeutic indices.
- Succinimides:T-type calcium channel inhibitors primarily reserved for absence seizure subtypes.
Volume placements concentrate in Benzodiazepines; the faster expansion belongs to Hydantoins.
Therapeutic Area:
Cost tier stratification separates chronic maintenance indications from premium-priced off-label neuropathic pain applications.
- Epilepsy:Chronic seizure suppression requiring daily dosing across decades. United States pediatric neurology clinics generate concentrated prescription volumes for extended-release formulations, with FDA orphan drug pathways accelerating development for Dravet and Lennox-Gastaut syndromes.
- Neuropathic Pain:Diabetic peripheral neuropathy and post-herpetic neuralgia applications command reimbursement premiums in outpatient pain management settings. German statutory health insurance funds increasingly cover pregabalin and gabapentin for polyneuropathy with documented nerve conduction deficits.
- Anxiety Disorders:Off-label benzodiazepine utilization for panic and generalized anxiety.
- Bipolar Disorder:Mood stabilization applications for valproate and lamotrigine derivatives.
Prescription volumes peak in Epilepsy; Neuropathic Pain captures the steepest margin expansion trajectory.
Delivery Mode:
Application context determines route selection, with acute hospital episodes favoring parenteral administration over chronic outpatient oral regimens.
- Oral:Tablet and capsule formulations for maintenance therapy. Japanese community pharmacies dispense substantial volumes of levetiracetam and lamotrigine for ambulatory epilepsy management, with PMDA pharmacovigilance obligations extending manufacturer service contracts.
- Intravenous:Hospital-based emergency administration for breakthrough seizures. Level 1 trauma centers in Texas and Massachusetts have consolidated purchasing through sole-source agreements for injectable levetiracetam, displacing fosphenytoin in status epilepticus protocols.
- Injectable:Intramuscular depot formulations for adherence-challenged patients.
- Topical:Peripheral nerve applications with limited systemic absorption.
Unit volumes concentrate in Oral; Intravenous formulations deliver disproportionate revenue per dose.
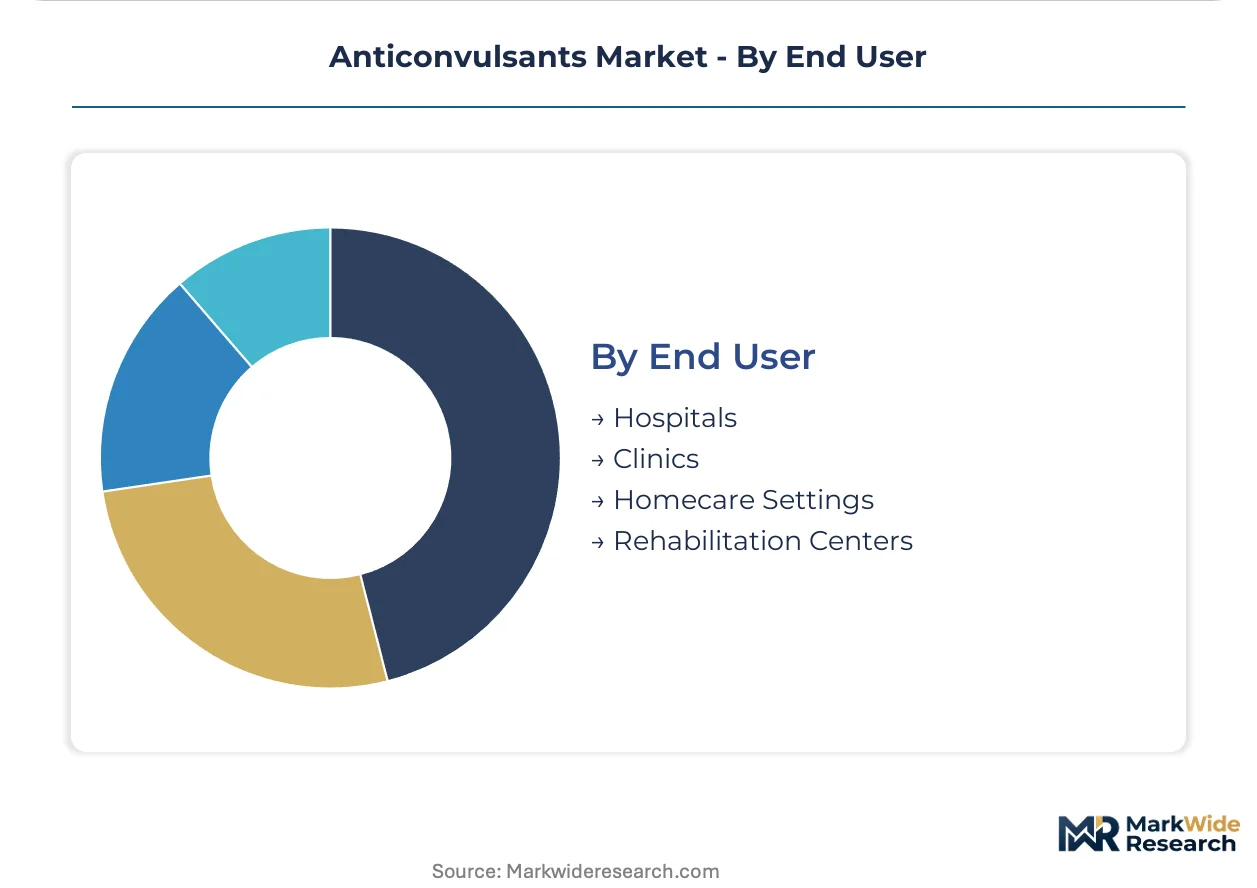
End User:
Customer type segmentation reflects care setting reimbursement structures and prescribing authority distributions.
- Hospitals:Acute-care institutions with formulary committees controlling intravenous anticonvulsant access. Academic medical centers in Pennsylvania anchor regional purchasing consortia that cascade formulary decisions to affiliated community facilities.
- Clinics:Outpatient neurology and pain management practices. Pediatric epileptologist scarcity in United States fellowship programs creates access bottlenecks that limit prescription volume growth despite rising diagnosis rates.
- Homecare Settings:Long-term residential and hospice applications.
- Rehabilitation Centers:Post-acute seizure management during neurological recovery.
Revenue concentration sits with Hospitals; Clinics represent the most contested channel for manufacturer access investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India and tariff-advantaged manufacturing corridors in China concentrate active pharmaceutical ingredient synthesis for levetiracetam and lamotrigine. These zones attract pharmaceutical chemical investment through accelerated customs clearance and reduced corporate tax rates.
United States
Pediatric neurology clinics in Texas and Massachusetts generate concentrated prescription volumes for extended-release anticonvulsant formulations. The FDA maintains stringent bioequivalence standards for generic substitutions that protect originator pricing structures. Academic medical centers in Pennsylvania anchor regional purchasing consortia that cascade formulary decisions to affiliated community hospitals.
Germany
Statutory health insurance funds drive reimbursement for pregabalin and gabapentin in diabetic peripheral neuropathy with documented nerve conduction deficits. The EMA's orphan drug incentives accelerate development timelines for rare epilepsy syndromes through protocol assistance mandates. Hospital formularies in Bavaria and North Rhine-Westphalia retain substantial phenytoin volumes for prophylactic neurosurgical applications.
Japan
Community pharmacies dispense substantial levetiracetam and lamotrigine volumes for ambulatory epilepsy management. The PMDA imposes extended pharmacovigilance obligations that lengthen product lifecycle management service contracts. Manufacturing clusters in the Kanto region around Tokyo supply domestic formulation facilities with high-purity active pharmaceutical ingredients.
India
API manufacturing for generic anticonvulsants concentrates in chemical synthesis clusters around Hyderabad and Ahmedabad. The CDSCO aligns bioequivalence requirements with FDA standards to facilitate export-oriented production. Contract research organizations in Maharashtra and Gujarat support bioanalytical studies for ANDA submissions to regulated markets.
Anticonvulsants Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with originators defending hospital formulary positions through injectable portfolios while generic houses compete on oral maintenance therapy pricing. The vendor base organizes into three tiers: multinational pharmaceutical corporations with neurology franchises, mid-cap generic specialists with concentrated anticonvulsant portfolios, and API-to-formulation integrated manufacturers. Consolidation pressure intensifies as hospital procurement committees shift toward sole-source contracts for intravenous products. Geographic expansion and portfolio diversification represent the dominant competitive moves, with manufacturers acquiring regional generic assets to secure distribution infrastructure.
Within the branded pharmaceutical tier, Pfizer Inc. and Novartis AG exemplify established hospital formulary relationships that sustain high-volume injectable distribution. UCB S.A. occupies a focused position in European epilepsy prescription landscapes through concentrated anticonvulsant development expertise. These three companies represent contrasting archetypes: diversified pharmaceutical conglomerates leveraging cross-therapeutic infrastructure versus neurology-specialized developers with concentrated mechanism expertise.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| UCB S.A. |
| Johnson & Johnson |
| GSK plc |
| Sanofi |
| AstraZeneca |
| Abbott Laboratories |
| Takeda Pharmaceutical Company Limited |
| Others |
Value Chain & Pricing Dynamics
EMA orphan drug incentives and FDA accelerated approval pathways gate qualified supply access and premium-tier pricing power, as manufacturers must maintain separate clinical data packages and pharmacovigilance systems across jurisdictions to capture orphan indication premiums.
Pricing Analysis
Short lead-time premiums for intravenous hospital formulary contracts command substantial markups over oral maintenance therapy, while spot inventory in oral generics trades at compressed margins. Three-tier pricing structure across originator injectables, authorized generics, and commodity tablets separates emergency department procurement from chronic outpatient dispensing. Cost compression in oral levetiracetam intensifies because Indian and Chinese API oversupply feeds aggressive generic tendering. Pediatric neurology clinics show least price sensitivity due to formulary loyalty and therapeutic drug monitoring requirements, while retail pharmacy chains exhibit highest sensitivity to per-tablet differentials.
Supply Chain Analysis
ICH Q7 GMP certification and FDA active pharmaceutical ingredient facility inspections gate entry for levetiracetam and lamotrigine suppliers, disqualifying uncertified chemical synthesis operations from regulated market participation. API manufacturing concentrates in India, China, and Japan, with formulation finishing distributed across Germany, the United States, and domestic Japanese facilities. Raw material dependencies center on acetic anhydride derivatives, chiral resolution agents, and high-purity solvents. Single-source vulnerability runs through Hyderabad chemical clusters where flood and regulatory inspection disruptions have previously constrained global lamotrigine availability. Distribution runs through hospital GPO contracts in the United States, statutory health insurance tendering in Germany, and regional wholesaler consignment in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anticonvulsant market participation functions as a cost-of-compliance story where FDA bioequivalence stringency for narrow therapeutic index drugs creates a barrier-to-entry moat protecting compliant manufacturers from price-erosion by undercapitalized generic entrants.
For Market Incumbents: To counter pharmacogenomic stratification fragmenting addressable populations, deploy backward integration into Indian API synthesis clusters to secure lamotrigine and levetiracetam supply continuity, while investing in closed-loop neurostimulation partnerships to capture device-pharmaceutical bundle margins from emergency department bypass.
For New Entrants and Emerging Players: Enter via Japan's extended pharmacovigilance service contracts, where PMDA post-market surveillance obligations create recurring revenue streams for safety database maintenance that incumbent pharma conglomerates undervalue relative to molecule development.
For Investors and Strategic Acquirers: FDA accelerated approval pathway utilization for Dravet and Lennox-Gastaut syndromes is the leading indicator that orphan epilepsy subtypes will command sustained premium pricing, positioning concentrated anticonvulsant developers with European regulatory capabilities as attractive acquisition targets over a multi-year viability window.
| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA accelerated approval compresses development timelines for rare epilepsy syndromes. |
| Injectable Formulary Consolidation | Sole-source hospital contracts in Texas and Massachusetts displace multi-source generic purchasing. |
| API Manufacturing Integration | Captive supply of levetiracetam intermediates insulates against tariff volatility in Chinese chemical clusters. |
| Pharmacovigilance Service Expansion | PMDA post-market obligations in Japan extend product lifecycle management contract durations. |
| Neurostimulation Partnership Development | Cleveland Clinic and Mayo Clinic pilot programs signal device-drug convergence revenue capture. |
Study Parameters
FDA Orange Book filings, EMA EPAR assessments, and ClinicalTrials.gov protocol records formed the secondary backbone, cross-referenced with primary interviews involving pediatric epileptologists, hospital formulary directors, pharmaceutical regulatory affairs leads, and API procurement managers at Indian contract manufacturers. Bottom-up prescription volume modeling across oral and intravenous delivery modes triangulated against top-down therapeutic area spending estimates from statutory health insurance funds and Medicare claims data.
Bottom-up patient-flow analysis segmented by drug class, therapeutic indication, and regional regulatory cluster anchored the analytical lens, with value outputs calibrated across the projection horizon through indication-specific pricing tiers and volume assumptions. CAGRs derived from longitudinal prescription audit data and hospital purchasing consortium contract disclosures, incorporating pharmacogenomic biomarker adoption curves and orphan drug incentive utilization rates as epilepsy-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under API supply disruption scenarios or sudden FDA bioequivalence standard revisions. A model refresh is warranted upon material change in pediatric neurology fellowship graduation rates or EMA pediatric investigation plan enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Veterinary Pain Management Drugs Market
Pharmaceuticals
Smoking Cessation Drugs Market
Pharmaceuticals
Global Anticoagulant Reversal Drugs Market
Pharmaceuticals
Vaginal Antifungals Market
Pharmaceuticals
Contract Pharmaceutical Fermentation Services Market
Pharmaceuticals
Smart Pills Market
Pharmaceuticals
North America Over the Counter Drugs Market
Pharmaceuticals
Influenza Antiviral Market
Pharmaceuticals
Hyperphosphatemia Drugs Market
Pharmaceuticals
North America Biguanide Market
Pharmaceuticals
Sarcoma Drugs Market
Pharmaceuticals
Tissue Plasminogen Activator Market
Pharmaceuticals
Urinary Retention Drugs Market
Pharmaceuticals
Candidiasis Therapeutics Market
Pharmaceuticals
Global Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
Global Liposome Drug Delivery Market