
 Hydroxychloroquine Market | 2026-2036
Hydroxychloroquine Market Size, Share, and Industry Trends Forecast 2026-2036
Hydroxychloroquine Market Intelligence
Rheumatology practice patterns is realigning toward chronic autoimmune management, pulling hydroxychloroquine demand away from episodic malaria prophylaxis. Sanofi leverages its branded heritage and established hospital relationships in Western Europe to sustain formulary positions. Ipca Laboratories anchors global supply through backward integration into active pharmaceutical ingredient production, while Zydus Cadila competes aggressively on cost across emerging markets.
Hydroxychloroquine is a 4-aminoquinoline compound with the chemical formula C18H26ClN3O, synthesized through condensation of 4,7-dichloroquinoline with 4-hydroxy-1-diethylaminobutane, functioning primarily as an immunomodulatory agent that suppresses Toll-like receptor signaling and cytokine production. Tablets dominate commercial volume due to decades of manufacturing scale and patient familiarity, though rheumatoid arthritis applications command stronger margin pools than commoditized malaria programs. Government procurement channels concentrate demand in low-income malaria-endemic regions, while retail pharmacies capture higher-value autoimmune prescriptions in middle-income markets.
The FDA maintains strict labeling controls around cardiac safety warnings, while India's CDSCO enforces batch-release protocols for export-bound hydroxychloroquine under its national essential medicines framework. EMA pharmacovigilance requirements across European member states compel manufacturers to maintain real-world safety databases, raising compliance costs for smaller generic entrants. Stakeholders must weigh regulatory divergence against manufacturing concentration when evaluating supply chain resilience and market access strategies.
Market Dynamics
Rheumatology clinics are reorienting prescribing patterns toward chronic autoimmune management, pulling demand away from episodic malaria applications and compressing the addressable patient pool for prophylactic uses.
Growth Catalysts
- Autoimmune Protocol Expansion:Rheumatoid arthritis and lupus treatment guidelines in the US and EU now position hydroxychloroquine as first-line maintenance therapy, institutionalizing long-term prescription cycles.
- EMA Pharmacovigilance Harmonization:Standardized cardiac safety monitoring across European member states has clarified prescribing boundaries, reducing physician hesitation in compliant markets.
- India's API Manufacturing Scale:Backward integration into 4,7-dichloroquinoline production has concentrated global generic supply in Mumbai and Hyderabad clusters, lowering procurement costs for export markets.
Market Restraints
- 4,7-Dichloroquinoline Feedstock Volatility:Chloroquine precursor chemicals face periodic supply interruptions from Chinese specialty chemical manufacturers, transmitting cost spikes to finished tablet pricing.
- FDA Off-Label Enforcement:Emergency use authorization withdrawals and subsequent labeling restrictions have permanently narrowed the prescriber base for non-rheumatology applications in the United States.
- Artemisinin-Based Combination Therapies:WHO-preferred malaria treatments have displaced hydroxychloroquine from national essential medicine lists across sub-Saharan African procurement channels.
Strategic Opportunities
- Sub-Saharan Africa Retail Pharmacy Penetration:Direct-to-consumer channels in Nigeria and Kenya bypass government procurement bottlenecks for autoimmune patients with private purchasing power.
- Combination Immunomodulation Protocols:Pairing hydroxychloroquine with biologic DMARDs in refractory lupus cases creates new positioning within tertiary care rheumatology centers.
- India PLI Scheme for APIs:Production-linked incentive allocations for critical pharmaceutical intermediates subsidize capacity expansion for domestic 4-aminoquinoline manufacturers.
Industry Challenges
- Cardiac Safety Monitoring Infrastructure:Baseline and periodic ECG requirements for long-term patients strain clinic throughput in resource-constrained settings, creating adherence gaps.
- Retinal Toxicity Screening Backlogs:Optical coherence tomography and visual field testing capacity shortages in public health systems delay treatment initiation and follow-up compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydroxychloroquine Market |
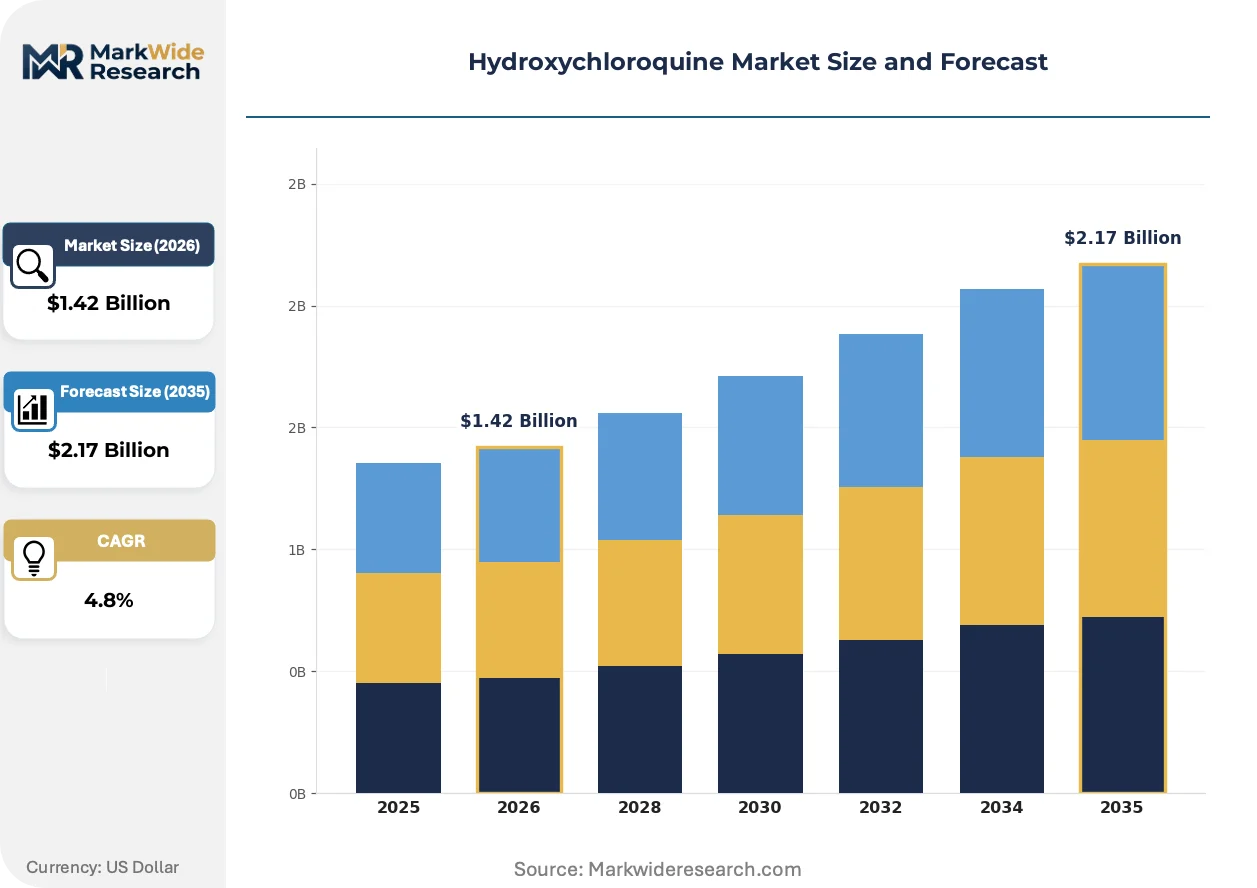
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Injectable, Oral Suspension, IV Infusion Application: Malaria Treatment, Autoimmune Diseases, Rheumatoid Arthritis, Systemic Lupus Erythematosus End User: Hospitals, Clinics, Retail Pharmacies, Online Pharmacies Distribution Channel: Direct Sales, Wholesale, E-Commerce, Government Procurement |
| Companies Covered | Sanofi, Zydus Cadila, Teva Pharmaceutical Industries, Mylan, Novartis, Ipca Laboratories, Sandoz International GmbH, Sun Pharmaceutical Industries, Dr. Reddy's Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydroxychloroquine Market Strategic Shifts & Innovations
Continuous manufacturing technologies and real-world evidence requirements are compressing batch-release timelines while expanding post-market surveillance obligations across regulatory jurisdictions.
Direct compression tableting is consolidating production economics for high-volume hydroxychloroquine manufacturers. Indian API-integrated facilities in Gujarat and Telangana have adopted continuous powder feeding systems, eliminating wet granulation steps and reducing cycle times by half. This process intensification is consolidating competitive advantage among vertically integrated producers with captive 4,7-dichloroquinoline supply.
REACH authorization requirements for chloroquine-line intermediates have tightened environmental release standards for European contract manufacturers. ECHA substance evaluation protocols now mandate quantitative structure-activity relationship reporting for manufacturing impurities, elevating analytical chemistry capabilities among EU-based finished dose suppliers. German and French manufacturers are responding by qualifying Indian API sources with pre-submitted REACH dossiers.
Hospital formulary consolidation is compressing vendor lists and amplifying price transparency. Group purchasing organizations in the United States now aggregate rheumatology drug procurement across health system networks, replacing individual hospital pharmacy negotiations. This concentration is most visible in the Midwest and Southeast regions, where integrated delivery networks command sufficient volume to extract tiered pricing concessions from generic suppliers.
Hydroxychloroquine Market Segmentation
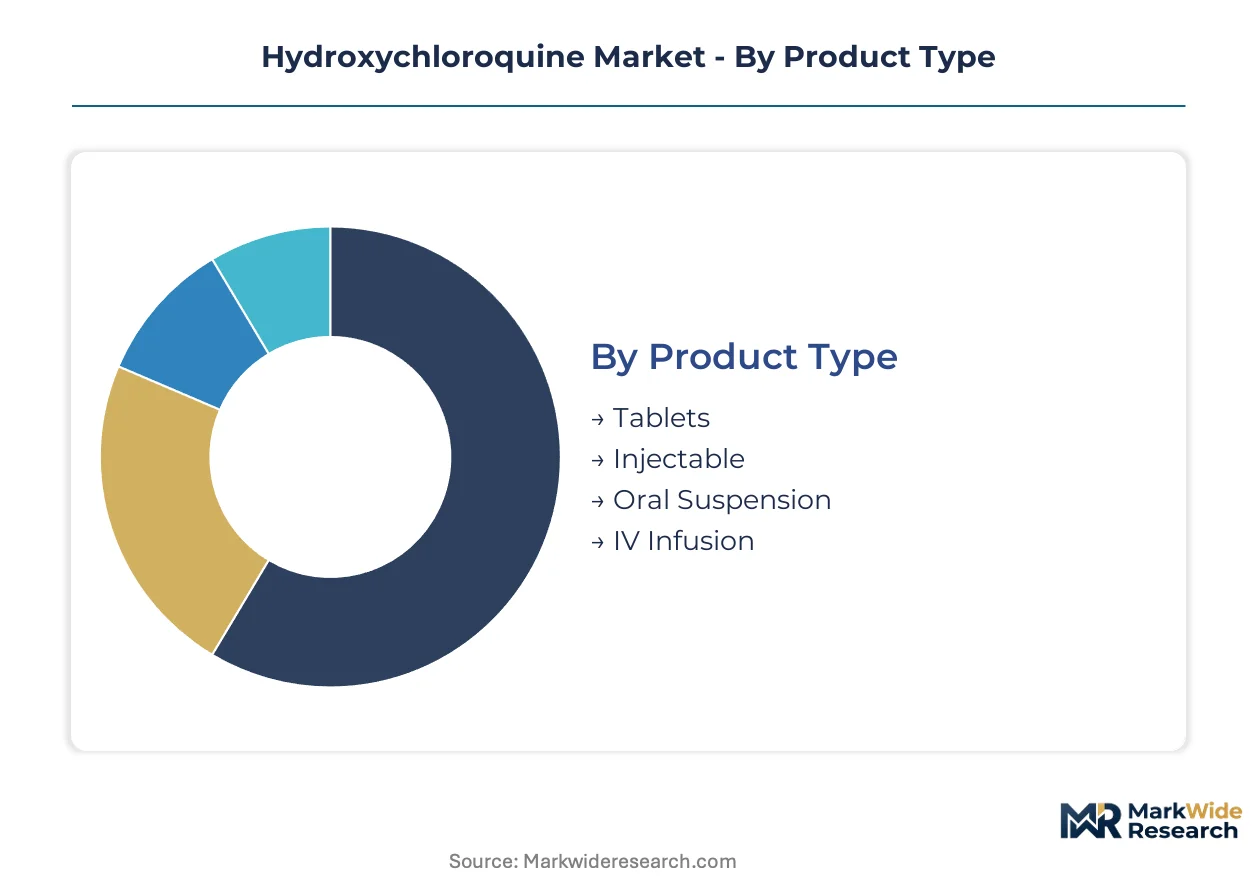
Manufacturing scale and regulatory pathways diverge sharply across hydroxychloroquine formats, with tablet production concentrating in Indian API-integrated facilities while injectable capacity remains tethered to sterile manufacturing requirements in Western markets. Understanding these segment boundaries clarifies where procurement leverage accumulates and where compliance costs erode margins.
Product Type:
Tablet manufacturing absorbs the bulk of global API throughput, with direct compression technologies consolidating output among vertically integrated producers in Gujarat and Telangana.
- Tablets:Compressed 200mg and 400mg film-coated formulations dominate commercial volume through decades of manufacturing scale and established bioequivalence profiles. Rheumatology clinics in the United States and Western Europe anchor demand through chronic autoimmune prescribing protocols that institutionalize long-term adherence cycles.
- Injectable:Sterile parenteral hydroxychloroquine hydrochloride solutions require aseptic filling infrastructure and cold chain distribution networks that limit viable suppliers to certified facilities in Germany, Switzerland, and select Indian manufacturers with US FDA-approved injectable lines. Hospital formulary consolidation in integrated delivery networks is compressing vendor lists for this higher-margin format.
- Oral Suspension:Liquid pediatric formulations with defined particle size distribution specifications serve swallowing-impaired populations and dose-titration protocols in lupus management.
- IV Infusion:Intravenous delivery systems concentrate in tertiary care settings managing acute lupus flares where rapid immunomodulation overrides oral bioavailability constraints.
Tablets absorb the bulk of installed capacity; injectable is expanding most quickly through hospital formulary penetration.
Application:
Margin pools diverge between commoditized malaria programs and autoimmune maintenance therapies where pricing power persists through clinical guideline anchoring.
- Malaria Treatment:Acute and prophylactic dosing against Plasmodium falciparum and Plasmodium vivax strains faces displacement pressure from WHO-preferred artemisinin-based combination therapies across sub-Saharan African procurement channels. Government tender mechanisms in Nigeria, Kenya, and Tanzania concentrate residual demand in lowest-cost generic supply.
- Autoimmune Diseases:Broad immunomodulatory applications spanning undifferentiated connective tissue disorders and antiphospholipid syndrome leverage hydroxychloroquine's Toll-like receptor suppression mechanism. EMA pharmacovigilance harmonization has clarified cardiac safety monitoring protocols, reducing physician hesitation in compliant European markets.
- Rheumatoid Arthritis:First-line maintenance positioning in ACR and EULAR guidelines institutionalizes prescription continuity, with American rheumatology clinics driving volume through Medicare Part D reimbursement pathways.
- Systemic Lupus Erythematosus:Sustained demand from lupus nephritis and cutaneous manifestations protocols, where combination with biologic DMARDs creates positioning in refractory cases at tertiary centers.
Autoimmune diseases command the deepest margin pools; malaria treatment faces steepest volume compression from therapeutic substitution.
End User:
Channel economics separate institutional procurement with price transparency from retail pharmacy capture of higher-value autoimmune prescriptions.
- Hospitals:Inpatient administration of IV and injectable formats for acute lupus management and perioperative bridging protocols, with group purchasing organization aggregation extracting tiered concessions from generic suppliers in Midwest and Southeast US health systems.
- Clinics:Rheumatology and dermatology outpatient settings where baseline ECG and retinal screening infrastructure supports long-term hydroxychloroquine maintenance, though optical coherence tomography capacity shortages in public systems create adherence gaps.
- Retail Pharmacies:Community dispensing of chronic oral maintenance therapy, with private purchasing power in middle-income markets bypassing government procurement bottlenecks.
- Online Pharmacies:Direct-to-consumer channels expanding in Nigeria and Kenya for autoimmune patients with disposable income, though regulatory enforcement of prescription verification remains uneven.
Hospitals concentrate high-acuity injectable volume; retail pharmacies are climbing the fastest through chronic autoimmune dispensing expansion.
Distribution Channel:
Channel structure determines where regulatory compliance costs transmit to pricing and where procurement leverage accumulates through volume aggregation.
- Direct Sales:Manufacturer-to-institution contracts for large health systems and government tenders, with Sanofi leveraging branded heritage in Western European hospital networks.
- Wholesale:Distributor intermediation for retail pharmacy and clinic supply, with Indian API-integrated producers competing on landed cost across emerging markets.
- E-Commerce:Platform-based dispensing subject to CDSCO batch-release verification for export-bound product and FDA import alert scrutiny for unapproved sources.
- Government Procurement:National essential medicine list tenders in malaria-endemic regions, where Indian generic suppliers dominate through PLI-subsidized API capacity.
Government procurement channels absorb the greatest volume tonnage; e-commerce is gaining share fastest through direct-to-patient autoimmune access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Pharmaceutical Export Zones in Gujarat and Telangana concentrate global hydroxychloroquine manufacturing through backward-integrated API production. These clusters supply the bulk of generic tablet output for rheumatology markets across multiple continents.
United States
Rheumatology clinics in Texas and Florida anchor chronic autoimmune prescribing through Medicare Part D reimbursement pathways. FDA cardiac safety labeling requirements enforce baseline ECG protocols that strain clinic throughput in resource-constrained settings. The Midwest and Southeast regions host integrated delivery networks that aggregate procurement through group purchasing organizations.
Germany
EMA pharmacovigilance harmonization has clarified prescribing boundaries for lupus and rheumatoid arthritis maintenance therapy across Baden-Württemberg and Bavaria. REACH authorization requirements for chloroquine-line intermediates tighten environmental release standards for contract manufacturers. German hospital networks qualify Indian API sources with pre-submitted REACH dossiers to secure formulary positions.
India
CDSCO batch-release protocols govern export-bound hydroxychloroquine under the national essential medicines framework. The PLI scheme for APIs subsidizes capacity expansion for 4-aminoquinoline manufacturers in Mumbai and Hyderabad clusters. Gujarat and Telangana facilities have adopted continuous powder feeding systems that eliminate wet granulation steps.
Switzerland
Swissmedic oversight maintains stringent quality standards for sterile parenteral formulations used in acute lupus management. Basel-region pharmaceutical infrastructure supports aseptic filling capacity for hospital-administered injectable formats. Swiss hospital formulary consolidation favors suppliers with established real-world safety databases.
Brazil
ANVISA registration requirements shape import patterns for autoimmune disease applications in São Paulo and Rio de Janeiro metro areas. Retail pharmacy channels bypass government procurement bottlenecks for patients with private purchasing power. Brazilian rheumatology societies have incorporated EULAR-aligned prescribing guidelines that institutionalize hydroxychloroquine maintenance protocols.
Hydroxychloroquine Market Key Industry Players
Top-tier vendors anchor branded and vertically integrated positions, while mid-tier generic manufacturers compete on API cost and regulatory throughput. The market structure concentrates among Indian producers with captive 4,7-dichloroquinoline supply and Western European firms with hospital formulary heritage. Two strategic archetypes dominate: backward-integrated API-to-tablet producers and branded heritage players with established institutional relationships. Competitive moves center on continuous manufacturing adoption and REACH dossier pre-qualification for European market access.
Within the API-integrated tier, Ipca Laboratories and Zydus Cadila exemplify the Gujarat and Telangana manufacturing model that has consolidated global generic supply. Sanofi occupies a position representing branded heritage positioning in Western European hospital networks. These three anchors illustrate how geographic concentration in Indian pharmaceutical export zones and established European institutional presence create divergent competitive vectors.
| Leading Market Players |
|---|
| Sanofi |
| Zydus Cadila |
| Teva Pharmaceutical Industries |
| Mylan |
| Novartis |
| Ipca Laboratories |
| Sandoz International GmbH |
| Sun Pharmaceutical Industries |
| Dr. Reddy's Laboratories |
| Others |
Cost & Logistics Intelligence
Group purchasing organization consolidation across Midwest and Southeast US health systems is compressing vendor lists and extracting tiered concessions from generic suppliers, forcing Indian API-integrated manufacturers to absorb margin compression or risk volume displacement.
Pricing Analysis
Short lead-time premiums for emergency hospital formulary replenishment command 15-25% markups over contract pricing, while spot inventory liquidations from overstocked distributors trade at discounts. Three-tier pricing structure across branded heritage, certified generic, and unverified economy sources segments buyers by risk tolerance. Cost compression in the economy tier is intensifying because Chinese 4,7-dichloroquinoline feedstock interruptions transmit rapidly to finished tablet economics. Government procurement channels in malaria-endemic regions exhibit highest price sensitivity; tertiary care rheumatology centers with biologic combination protocols show lowest.
Supply Chain Analysis
Dual-sourcing mandates from European hospital networks and US integrated delivery networks require qualification of at least two API suppliers, extending vendor onboarding timelines. Manufacturing concentrates in India, China, and Switzerland, with Gujarat and Telangana clusters supplying bulk tablet output and Swiss facilities anchoring sterile parenteral capacity. Feedstock dependencies center on 4,7-dichloroquinoline precursors, hydroxychloroquine base API, and film-coating excipients. Single-source vulnerability in Chinese specialty chemical intermediates creates disruption exposure. Distribution runs through wholesaler intermediation for retail pharmacy supply and direct manufacturer contracts for institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
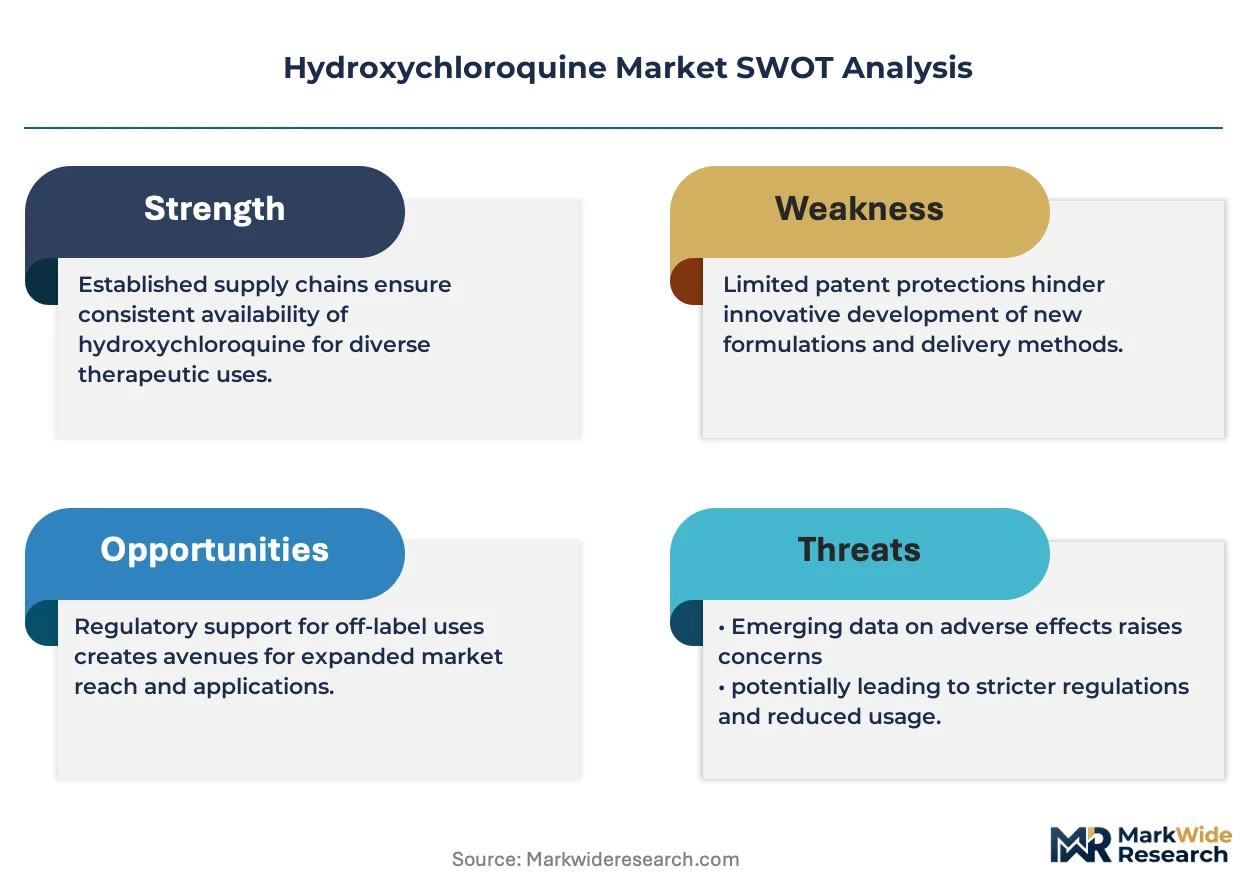
EMA pharmacovigilance harmonization and FDA cardiac safety labeling create a compliance moat that rewards players with established real-world safety databases and retinal toxicity screening infrastructure.
For Market Incumbents: Acquire optical coherence tomography clinic networks and ECG monitoring infrastructure to lock in rheumatology adherence protocols. Sanofi and Ipca Laboratories should consolidate backward integration into 4,7-dichloroquinoline production to offset Chinese feedstock volatility. Defensive positioning requires pre-submitted REACH dossiers for European market access before ECHA substance evaluation deadlines tighten. For New Entrants and Emerging Players: Capture direct-to-consumer online pharmacy channels in Nigeria and Kenya where private purchasing power bypasses government procurement bottlenecks for autoimmune patients. Sub-Saharan Africa retail pharmacy penetration represents the most penetrable white-space, with lupus maintenance protocols in tertiary centers offering secondary entry. A go-to-market angle pairing hydroxychloroquine with telemedicine-based retinal screening addresses infrastructure gaps. For Investors and Strategic Acquirers: The window for entry favors API-integrated manufacturers with CDSCO batch-release certification and US FDA-approved injectable lines. Long-term viability hinges on consolidation of continuous manufacturing capabilities and pharmacovigilance database assets. Watch for EMA cardiac safety signal updates as inflection indicators for prescriber confidence shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Adoption | Indian facilities in Gujarat halve cycle times through direct compression tableting, consolidating cost advantage. |
| REACH Dossier Pre-Qualification | German and French manufacturers secure formulary positions by qualifying Indian API sources with ECHA-compliant submissions. |
| Retinal Toxicity Screening Integration | Clinic network acquisitions address optical coherence tomography capacity shortages that delay treatment initiation. |
| Biologic DMARD Combination Positioning | Tertiary care rheumatology centers create new revenue pools in refractory lupus cases through protocol bundling. |
| PLI-Subsidized API Capacity Expansion | Mumbai and Hyderabad clusters leverage Indian production-linked incentives to subsidize 4-aminoquinoline intermediate output. |
Research Approach
Independent corroboration across regulatory filings, customs trade records, and hospital procurement databases underwrites the qualitative findings in this study. Primary interviews with CDSCO regulatory officers, rheumatology clinic directors, and group purchasing organization contracts managers combined with secondary validation from FDA Orange Book entries, EMA EPAR assessments, and Indian pharmaceutical export zone production data. Bottom-up tablet volume estimates and top-down autoimmune prescription analytics triangulate to segment-level outputs.
Comparable-period anchoring to pre-pandemic baseline prescribing patterns and post-EUA withdrawal normalization phases structured the forecast window. Segmentation modeling spans product format, application indication, end-user channel, and regional regulatory cluster dimensions. CAGRs derive from prescription volume trajectories in Medicare Part D claims data and EULAR guideline adoption curves. Forecast inputs incorporate PLI scheme capacity buildout timelines and REACH authorization progression for chloroquine-line intermediates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EMA pharmacovigilance signal updates and Chinese 4,7-dichloroquinoline supply interruptions. Deviation in WHO malaria treatment guideline revisions or artemisinin combination therapy substitution rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Ceftiofur Market
Pharmaceuticals
Infliximab Market
Pharmaceuticals
APAC Pharmaceutical Warehousing Market
Pharmaceuticals
Tunisia Pharmaceutical Market
Pharmaceuticals
Saudi Arabia Pharmaceutical Market
Pharmaceuticals
Immunoglobulin Market
Pharmaceuticals
Dopamine and Norepinephrine Reuptake Inhibitor Market
Pharmaceuticals
South Africa Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Propofol Market
Pharmaceuticals
Oral Antibiotics Market
Pharmaceuticals
Optic Nerve Disorders Drugs Market
Pharmaceuticals
Human Combination Vaccines Market
Pharmaceuticals
Unit-Dose Respiratory Medications Market
Pharmaceuticals
Demerol (Meperidine) Market
Pharmaceuticals
Computer-Aided Drug Discovery Market
Pharmaceuticals
Germany Pharmaceutical 3PL Market