
 Chronic Liver Diseases Therapeutics Market | 2026-2036
Chronic Liver Diseases Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Liver Diseases Therapeutics Market Insights
FDA breakthrough therapy designation is pivoting the cost-of-entry calculus for developers of novel liver disease agents, requiring earlier investment in biomarker strategies and adaptive trial infrastructure. Gilead Sciences, Inc. leverages its nucleotide analog expertise to sustain dominance in hepatitis B and D portfolios. AbbVie Inc. anchors its position through immunology platforms targeting autoimmune hepatitis and emerging fibrotic indications. Bristol-Myers Squibb Company differentiates via checkpoint inhibitor applications in hepatocellular carcinoma combinations.
Chronic liver diseases therapeutics encompass pharmacological interventions designed to modify disease progression, manage complications, and improve survival across viral, metabolic, autoimmune, and neoplastic hepatic conditions; these agents typically require hepatic metabolism profiling and dose adjustment protocols due to altered first-pass kinetics in cirrhotic patients. Antivirals retain the largest value share given curative hepatitis C regimens and long-term hepatitis B suppression requirements, though immunotherapies represent the fastest-expanding margin pool as combination protocols for liver cancer multiply. Oral delivery modes command volume leadership in outpatient chronic management, while injectables capture premium pricing in hospital-based acute decompensation and oncology settings.
FDA, EMA, and WHO prequalification standards collectively shape clinical endpoint requirements, manufacturing compliance burdens, and market access sequencing across developed and emerging markets. The FDA's hepatic impairment guidance mandates dedicated pharmacokinetic studies, while EMA's MDR transition imposes strengthened post-market surveillance on device-drug combinations used in portal hypertension management. Stakeholders must monitor evolving non-invasive fibrosis staging criteria from regulators, as these diagnostic thresholds directly determine reimbursable treatment populations and trial eligibility criteria.
Market Dynamics
FDA breakthrough therapy designations are compressing development timelines for novel liver disease agents, forcing developers to front-load biomarker validation and adaptive trial infrastructure investments before Phase II data matures.
Growth Catalysts
- Medicare reimbursement protocols:United States outpatient chronic disease management policies now favor ambulatory care models over hospitalization for compensated cirrhosis, expanding addressable patient populations for oral antiviral regimens.
- Non-invasive fibrosis staging:Magnetic resonance elastography and enhanced transient elastography are replacing biopsy-dependent protocols, accelerating treatment initiation decisions and expanding reimbursable candidate pools.
- Japan hepatology infrastructure:METI-supported precision medicine initiatives in liver cancer are creating demand for companion diagnostic-linked immunotherapy combinations.
Market Restraints
- EMA MDR transition costs:Strengthened post-market surveillance requirements for device-drug combinations in portal hypertension management are extending compliance timelines and elevating regulatory overhead for European market entry.
- API supply concentration:Active pharmaceutical ingredient manufacturing for nucleotide analogs clusters in specific Asian manufacturing zones, creating single-source vulnerability for hepatitis B maintenance therapies.
- Hepatic impairment pharmacokinetics:FDA guidance mandates dedicated PK studies in Child-Pugh Class B and C populations, adding 12-18 months to development timelines for agents metabolized through CYP450 pathways.
Strategic Opportunities
- India CDSCO fast-track pathways:Accelerated approval mechanisms for orphan hepatology indications are opening access to the world's second-largest hepatitis B patient population with compressed regulatory timelines.
- AI-integrated drug discovery:Machine learning platforms for fibrosis mechanism modeling are converging with organoid-based hepatotoxicity screening, compressing preclinical candidate selection cycles.
- Direct-to-specialist distribution:Hepatology-focused digital therapeutics platforms are bypassing traditional hospital pharmacy procurement, capturing margin through subscription-based adherence monitoring.
Industry Challenges
- Adaptive trial design expertise:Scarcity of biostatisticians experienced in Bayesian response-adaptive randomization is bottlenecking sponsor ability to exploit FDA breakthrough pathway efficiencies.
- Legacy EHR integration:Fibrosis staging algorithm deployment requires harmonization with disparate hospital IT systems, delaying real-world evidence collection for payer negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Liver Diseases Therapeutics Market |
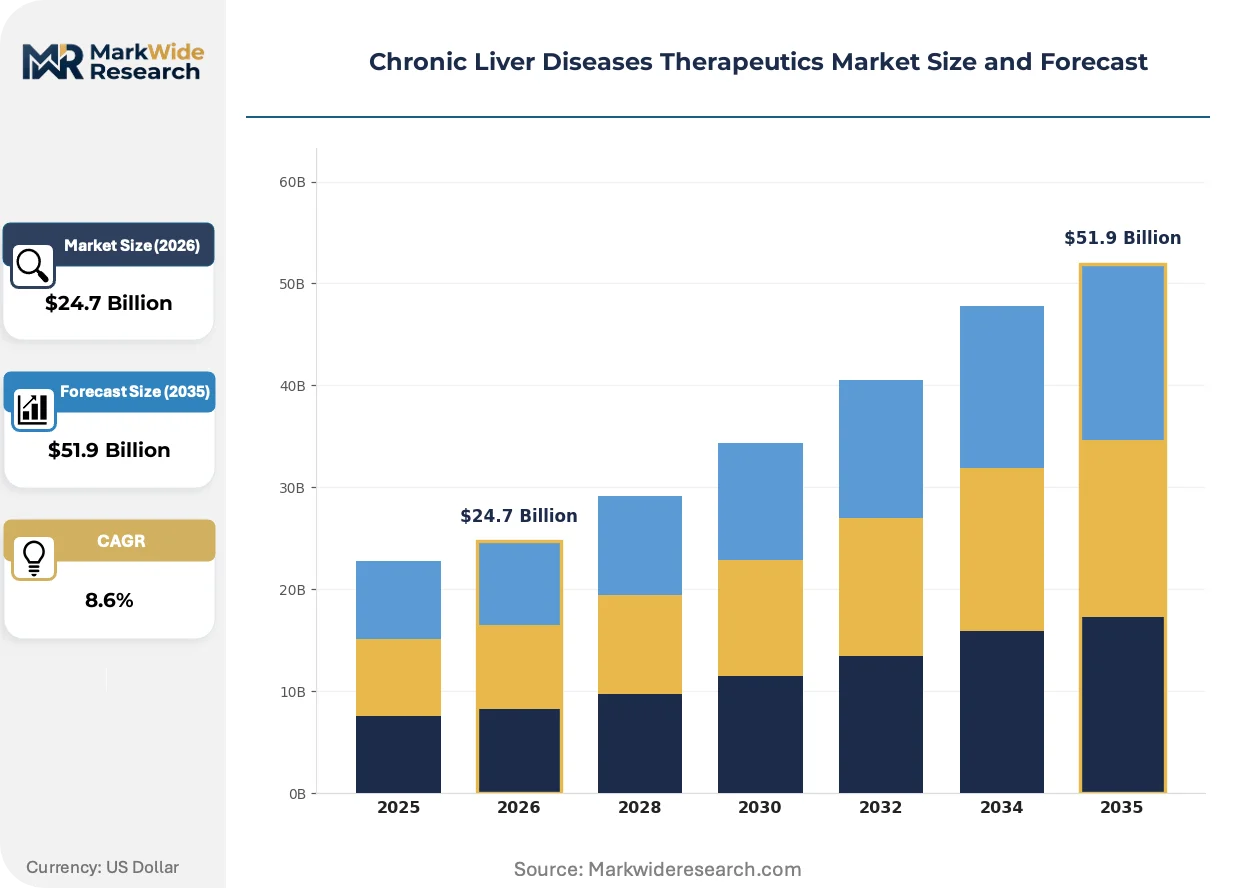
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $51.9 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antivirals, Enzymes, Immunotherapies, Compounds Application: Cirrhosis, Hepatitis, Fatty Liver Disease, Liver Cancer End User: Hospitals, Clinics, Research Institutes, Homecare Settings Delivery Mode: Injectables, Oral, Infusions, Topicals |
| Companies Covered | Gilead Sciences, Inc., AbbVie Inc., Bristol-Myers Squibb Company, F. Hoffmann-La Roche Ltd, Merck & Co., Inc., Novartis AG, Pfizer Inc., Sanofi S.A., GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Liver Diseases Therapeutics Market Trends and Innovations
Three convergent forces are restructuring how liver disease therapies reach patients: point-of-care diagnostic integration, regulatory pathway compression, and ambulatory care model expansion. Each trend is altering competitive positioning without requiring incumbent pipeline overhaul.
Non-invasive fibrosis assessment technology is decentralizing diagnostic authority from academic medical centers to community hepatology practices. Point-of-care elastography devices now deliver liver stiffness measurements comparable to magnetic resonance protocols at one-fifth the capital cost. Community gastroenterology groups in the United States are adopting these platforms to retain patients who would otherwise transfer to tertiary centers for staging, compressing referral leakage and capturing therapy initiation revenue.
EMA's MDR transition for device-drug combinations is forcing hepatology device manufacturers to restructure quality management systems around strengthened post-market clinical follow-up obligations. The regulation requires systematic collection of real-world performance data for transjugular intrahepatic portosystemic shunt delivery systems and pressure monitoring sensors. German and French hospital procurement consortia are now conditioning tender awards on demonstrated MDR technical documentation completeness, favoring established suppliers with regulatory affairs scale.
Specialty pharmacy distribution is displacing traditional hospital outpatient dispensing for oral antiviral maintenance regimens. United States payers are mandating 90-day fill requirements through limited network specialty pharmacies to capture manufacturer rebate structures and enforce adherence monitoring. This channel consolidation is visible most acutely in Medicare Part D hepatitis C curative therapy administration, where mail-order penetration now exceeds two-thirds of new prescriptions.
Chronic Liver Diseases Therapeutics Market Segmentation
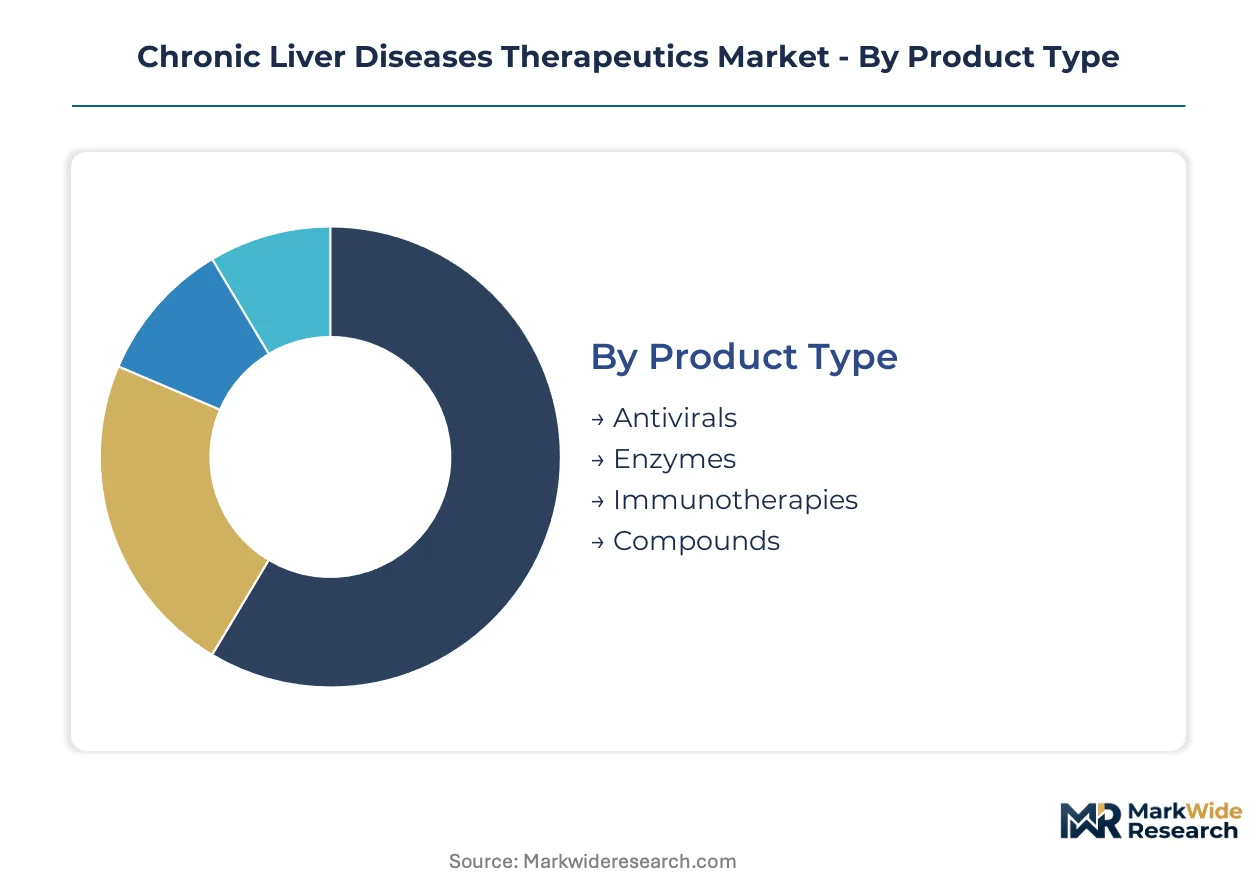
Segmentation in chronic liver diseases therapeutics reveals distinct capital allocation patterns across molecular platforms and care settings. Manufacturers must align R&D investment intensity with reimbursement velocity and patient access infrastructure.
Product Type:
Capital intensity varies sharply across molecular platforms, with biologics manufacturing requiring substantially higher upfront facility investment than small-molecule synthesis.
- Antivirals:Nucleotide and nucleoside analogs dominate hepatitis B suppression and hepatitis C curative regimens through direct-acting viral polymerase inhibition. Demand concentrates in Medicare Part D outpatient channels across the United States, where 90-day maintenance fills drive volume economics and adherence monitoring investments.
- Immunotherapies:Checkpoint inhibitors and engineered cytokines target hepatocellular carcinoma through PD-1/PD-L1 axis modulation and tumor microenvironment reprogramming. Japanese METI-supported precision medicine initiatives are accelerating companion diagnostic-linked combination protocols, requiring parallel diagnostic infrastructure investment.
- Enzymes:Replacement therapies address rare metabolic deficiencies such as urea cycle disorders and lysosomal storage diseases with recombinant protein platforms.
- Compounds:Small-molecule fibrosis modulators and metabolic regulators target non-alcoholic steatohepatitis progression through FXR and PPAR pathway agonism.
Antivirals absorb the bulk of installed manufacturing capacity; immunotherapies are expanding most quickly.
Application:
Clinical endpoint requirements and trial complexity create divergent development cost structures across disease indications.
- Hepatitis:Viral hepatitis B and C represent the most mature therapeutic areas with established surrogate endpoints and accelerated approval pathways. The United States accounts for the majority of reimbursed curative therapy initiations, though India CDSCO fast-track mechanisms are opening access to the world's second-largest hepatitis B population.
- Liver Cancer:Hepatocellular carcinoma and cholangiocarcinoma drive oncology platform expansion through combination immunotherapy protocols. Japanese hepatology infrastructure investments are creating demand for biomarker-stratified trial designs requiring substantial biostatistical capability.
- Fatty Liver Disease:Non-alcoholic steatohepatitis and metabolic dysfunction-associated steatotic liver disease represent emerging indications with evolving diagnostic criteria and payer uncertainty.
- Cirrhosis:Decompensated cirrhosis management focuses on complication prevention through portal hypertension control and hepatic encephalopathy prophylaxis.
Hepatitis captures the largest share of commercialized assets; liver cancer is climbing the fastest.
End User:
Channel economics and procurement concentration determine margin capture and distribution infrastructure requirements.
- Hospitals:Tertiary academic medical centers manage acute decompensation, hepatocellular carcinoma protocols, and transplant evaluation through inpatient and infusion-based delivery. German and French hospital procurement consortia are conditioning tender awards on MDR technical documentation completeness for device-drug combinations.
- Homecare Settings:Oral antiviral maintenance and subcutaneous immunotherapy administration shift care from institutional to ambulatory environments. United States specialty pharmacy networks now capture over two-thirds of hepatitis C curative therapy prescriptions through mail-order distribution.
- Clinics:Community gastroenterology practices are adopting point-of-care elastography to retain patients who would otherwise transfer to tertiary centers.
- Research Institutes:Academic medical centers conduct Phase I-III trials and real-world evidence generation for payer negotiations.
Hospitals retain the highest absolute therapy value; homecare settings are gaining share fastest.
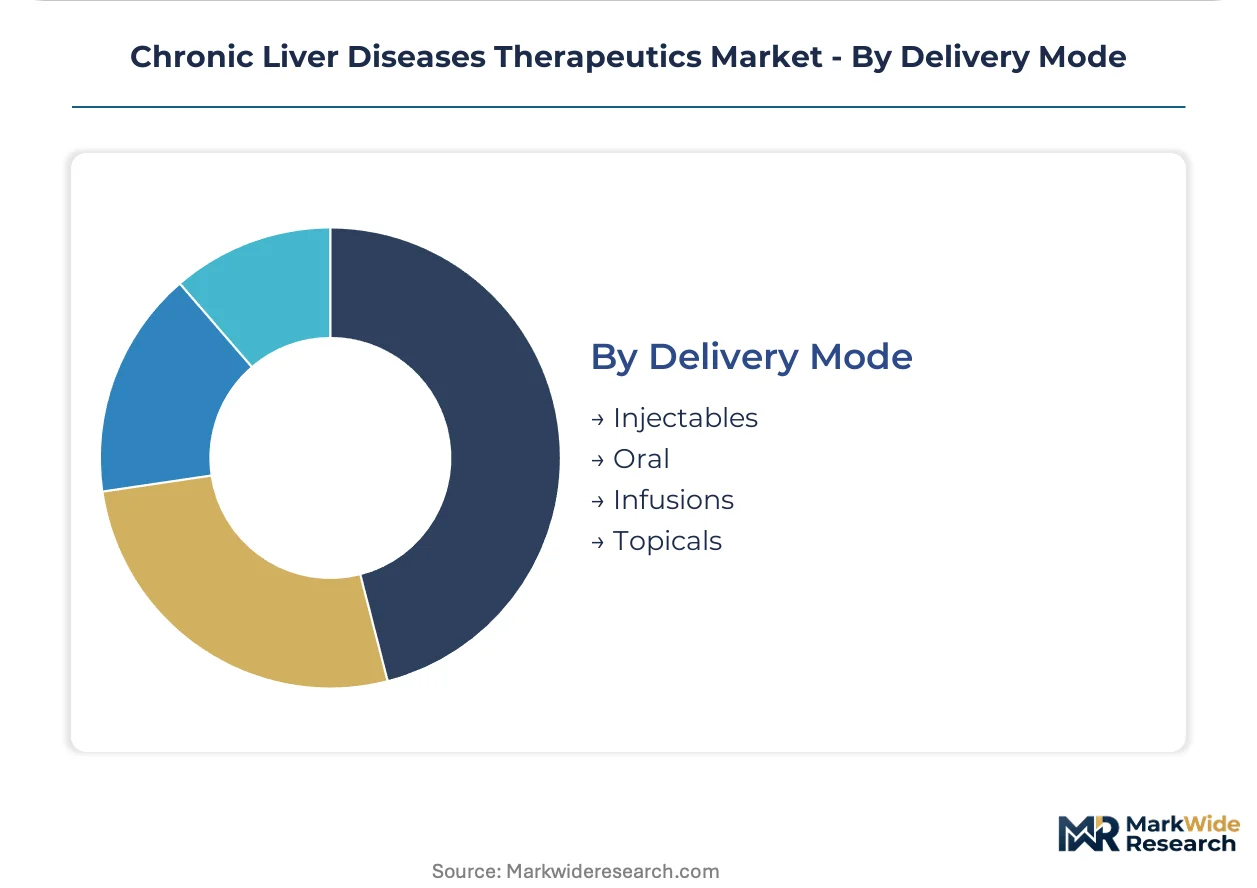
Delivery Mode:
Formulation development costs and manufacturing complexity create distinct competitive barriers across administration routes.
- Oral:Small-molecule tablets and capsules enable outpatient chronic disease management with patient-administered dosing flexibility. Medicare reimbursement protocols increasingly favor ambulatory oral regimens over hospitalization for compensated cirrhosis.
- Injectables:Subcutaneous and intravenous biologics command premium pricing in oncology and acute decompensation settings through hospital-based administration and cold-chain logistics.
- Infusions:Extended-duration intravenous delivery supports checkpoint inhibitor combinations and critical care hepatology interventions.
- Topicals:Transdermal and localized delivery systems address pruritus and cutaneous manifestations of cholestatic liver disease.
Oral formulations dominate prescription volume; injectables capture the steepest pricing premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in India and China's biomedical industrial parks are accelerating API manufacturing concentration. Japan's METI-designated innovation clusters concentrate precision medicine infrastructure. Germany's MedTech hubs anchor European device-drug combination development.
United States
Medicare Part D outpatient reimbursement protocols and specialty pharmacy networks drive oral antiviral volume. FDA breakthrough therapy designations compress development timelines for novel agents. Boston and San Francisco biotech clusters concentrate adaptive trial infrastructure and biomarker validation capabilities.
Germany
Hospital procurement consortia in North Rhine-Westphalia and Bavaria condition tender awards on MDR technical documentation completeness. EMA post-market surveillance requirements elevate compliance overhead for portal hypertension device-drug combinations. Frankfurt and Munich regulatory affairs hubs support pan-European market access sequencing.
Japan
METI-supported precision medicine initiatives in liver cancer create demand for companion diagnostic-linked immunotherapy combinations. PMDA accelerated approval pathways favor biomarker-stratified trial designs. Osaka and Tokyo hepatology infrastructure investments concentrate biostatistical capability for oncology protocols.
India
CDSCO fast-track pathways for orphan hepatology indications open access to the world's second-largest hepatitis B patient population. BIS manufacturing standards govern API production for nucleotide analogs. Hyderabad and Ahmedabad pharmaceutical clusters concentrate hepatitis B maintenance therapy supply.
China
NMPA priority review channels for innovative biologics shorten hepatocellular carcinoma combination timelines. Dual carbon goals reshape energy-intensive API manufacturing compliance. Shanghai and Suzhou biomedical zones integrate AI-driven drug discovery with organoid-based hepatotoxicity screening.
Chronic Liver Diseases Therapeutics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across molecular platform categories. The market structure tiers between nucleotide analog incumbents with established manufacturing scale and immunotherapy entrants building oncology combination portfolios. Three archetypes dominate: large-cap diversified pharmaceuticals with hepatology as one vertical among many, mid-cap specialists concentrating on viral hepatitis or liver cancer exclusively, and emerging biotechs leveraging FDA breakthrough pathways for fibrosis mechanisms. Competitive moves center on adaptive trial infrastructure acquisition and companion diagnostic partnership structures.
Within the large-cap diversified tier, Gilead Sciences, Inc. and AbbVie Inc. occupy positions sustained by nucleotide analog expertise and immunology platform breadth respectively. Bristol-Myers Squibb Company anchors the checkpoint inhibitor application segment for hepatocellular carcinoma combinations. These three entities exemplify how incumbents defend position through portfolio breadth rather than single-molecule concentration.
| Leading Market Players |
|---|
| Gilead Sciences, Inc. |
| AbbVie Inc. |
| Bristol-Myers Squibb Company |
| F. Hoffmann-La Roche Ltd |
| Merck & Co., Inc. |
| Novartis AG |
| Pfizer Inc. |
| Sanofi S.A. |
| GlaxoSmithKline plc |
| Others |
Pricing and Supply Chain Analysis
Captive API manufacturing for nucleotide analogs in Hyderabad and Ahmedabad pharmaceutical clusters anchors both hepatitis B therapy supply security and premium pricing power for maintenance regimens. This backward integration shields incumbents from raw material volatility while enabling tiered pricing stratification across branded, authorized generic, and economy formulations.
Pricing Analysis
Short lead-time premiums command substantial markups in hepatitis C curative therapy procurement, where hospital systems pay 15-25% above contract rates for emergency stock replenishment. Three-tier pricing structure across originator, licensed generic, and compulsory-licensed economy levels reflects FDA bioequivalence tiering and volume scale. Cost compression in standard-tier oral antivirals is intensifying because Medicare Part D rebate aggregation concentrates purchasing leverage with specialty pharmacy networks. Community gastroenterology practices exhibit highest price sensitivity due to cash-pay patient exposure, while tertiary academic medical centers absorb premium pricing for checkpoint inhibitor combinations.
Supply Chain Analysis
Direct-to-specialty-pharmacy distribution handles the majority of oral antiviral volume, bypassing traditional hospital outpatient pharmacy procurement. Active pharmaceutical ingredient production draws from India, China, and South Korea, with nucleoside precursor synthesis concentrated in Zhejiang province chemical parks. Supply chain vulnerability centers on single-source dependence for tenofovir alafenamide intermediates, where environmental compliance shutdowns in specific manufacturing zones trigger allocation protocols. Cold-chain logistics for checkpoint inhibitor infusions feed from regional distribution hubs in Frankfurt, Singapore, and Memphis.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chronic liver diseases therapeutics sector sits at a technology-transition inflection, with non-invasive fibrosis staging via magnetic resonance elastography and transient elastography displacing biopsy-dependent protocols across reimbursement pathways.
For Market Incumbents: To counter biosimilar erosion in hepatitis B nucleotide analog portfolios, anchor position through backward integration into API precursor manufacturing and companion diagnostic co-development for immunotherapy combinations. Priority investment targets adaptive trial infrastructure to exploit FDA breakthrough therapy designation efficiencies before Phase II data matures. For New Entrants and Emerging Players: Direct-to-specialist digital therapeutics platforms offer the most penetrable white-space entry vector, bypassing consolidated specialty pharmacy networks through subscription-based adherence monitoring and point-of-care diagnostic integration. Target community gastroenterology practices in United States Medicare Advantage markets with AI-integrated fibrosis staging algorithms that compress referral leakage to tertiary centers. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap specialists with validated biomarker strategies and adaptive trial infrastructure. Long-term viability over the coming decade hinges on regulatory approval velocity rather than manufacturing scale alone. Watch FDA hepatic impairment guidance revisions as the critical inflection signal for development timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Trial Infrastructure Investment | Bayesian response-adaptive randomization capabilities compress FDA breakthrough pathway timelines for novel agents. |
| Companion Diagnostic Partnership | PMDA-accelerated biomarker-stratified protocols in Japan create first-mover advantage in hepatocellular carcinoma combinations. |
| API Manufacturing Scale-Up | CDSCO fast-track access to India's hepatitis B patient population requires BIS-compliant nucleotide analog production capacity. |
| Specialty Pharmacy Network Integration | Medicare Part D 90-day fill mandates concentrate volume through limited distribution channels capturing manufacturer rebates. |
| Non-Invasive Diagnostic Platform Deployment | Point-of-care elastography adoption in United States community practices retains patients who would transfer to tertiary staging centers. |
Research Methodology
Document review covered FDA hepatic impairment guidance documents, EMA MDR technical documentation requirements, and ClinicalTrials.gov protocol registrations, complemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from formulary databases, CMS Medicare Part D utilization data, and SEC 10-K pipeline disclosures. Bottom-up patient-flow modeling and top-down revenue triangulation anchored market size estimation.
Cross-referencing historical approval velocity against expert panel input on breakthrough designation probability shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include molecular platform, disease indication, delivery mode, and regional regulatory cluster. CAGRs were derived from patient population epidemiology, treatment penetration curves, and pricing trajectory assumptions specific to Medicare reimbursement protocols and EMA market access sequencing.
The model holds under stable FDA breakthrough therapy designation criteria and continued Medicare outpatient reimbursement favorability; deviation in hepatic impairment guidance stringency or specialty pharmacy network consolidation would shift volume and value trajectories. Periodic stress-testing of base assumptions against real-world evidence collection rates and MDR compliance cost escalation is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Gastroesophageal Junction Adenocarcinoma Therapeutics Market
Gastroenterology
Malabsorption Syndrome Treatment Market
Gastroenterology
Gluten Intolerance Treatment Market
Gastroenterology
Ultrasound Gastroscopes Market
Gastroenterology
Gallstone Market
Gastroenterology
Chile Gastric Cancer Treatment Market
Gastroenterology
Diverticular Disease Therapeutics Market
Gastroenterology
Helicobacter Pylori Infections Treatment Market
Gastroenterology
Malignant Ascites Market
Gastroenterology
High Definition Ultrasound Gastroscope Market
Gastroenterology
Gastroesophageal Reflux Disease Therapeutics Market
Gastroenterology
Intestinal Pseudo-Obstruction Treatment Market
Gastroenterology
Peptic Ulcer Market
Gastroenterology
Necrotic Enteritis Treatment Market
Gastroenterology
US Gastroenterology Ambulatory Surgery Center Market
Gastroenterology
Global Gastrointestinal Bleeding Treatment Market