
 Non-Infectious Uveitis Treatment Market | 2026-2036
Non-Infectious Uveitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Infectious Uveitis Treatment Market Analytics
Biologic agents are pivoting treatment economics away from chronic corticosteroid dependence in posterior uveitis. AbbVie Inc. leverages its immunology platform to sustain dominance in TNF-inhibitor segments for refractory cases. Novartis AG anchors European biologics access through specialized ophthalmology hospital contracts. Regeneron Pharmaceuticals differentiates via IL-6 pathway inhibition with intravitreal delivery systems.
Non-infectious uveitis treatment encompasses pharmacological management of sterile intraocular inflammation through corticosteroids, immunosuppressants, biologics, and NSAIDs, typically administered via intravitreal injection, oral, topical, or subcutaneous routes to preserve visual acuity and prevent structural complications such as macular edema or retinal detachment. Biologics command the fastest expansion within product type categories, driven by steroid-sparing protocols in hospital settings. Intravitreal injection leads delivery mode preference among retina specialists, while ambulatory surgical centers capture growing procedure volumes as site-of-care shifts away from inpatient settings.
FDA ophthalmology division and EMA's Committee for Medicinal Products for Human Use govern biologic approval standards, with both agencies tightening post-market surveillance for sustained-release ocular implants. The European Union's Medical Device Regulation and ISO 13485 quality management standards shape manufacturing compliance for combination drug-device products. Stakeholders must monitor evolving reimbursement thresholds for biologic switching protocols and site-of-care authorization changes affecting ambulatory surgical center eligibility.
Market Dynamics
Sustained-release intravitreal implants are compressing treatment frequency and shifting site-of-care economics from hospital wards to ambulatory surgical centers, forcing reimbursement recalibration across major health systems.
Growth Catalysts
- IL-6 pathway inhibition:Steroid-sparing biologic protocols in posterior uveitis are reducing chronic corticosteroid exposure and associated adverse events in tertiary retina centers.
- FDA accelerated approval pathways:Expedited biologics review timelines are compressing competitive entry windows and expanding therapeutic options for refractory cases.
- Japan's metropolitan hospital networks:Specialist retina center clustering around Tokyo and Osaka is concentrating procedure volumes and driving implant adoption.
Market Restraints
- Biologics manufacturing concentration:Limited contract development and manufacturing organization capacity for monoclonal antibodies creates supply vulnerability for intravitreal formulations.
- EMA post-market surveillance tightening:Enhanced pharmacovigilance requirements for sustained-release ocular implants extend regulatory compliance timelines and increase documentation burden.
- Topical corticosteroid substitution:Anterior segment cases retain access to low-cost generic drops, limiting biologic penetration in mild-to-moderate presentations.
Strategic Opportunities
- German outpatient clinic expansion:Ambulatory surgical center eligibility broadening under statutory health insurance reforms is redirecting intravitreal procedure volumes from inpatient settings.
- Combination drug-device convergence:Integration of biologic payloads with biodegradable polymer matrices enables programmable release kinetics and extends dosing intervals.
- United States site-of-care authorization changes:Medicare reimbursement adjustments favoring office-based surgical suites create channel expansion potential for sustained-release implants.
Industry Challenges
- Ocular immunology fellowship scarcity:Limited subspecialty training pipeline constrains retina specialist availability to manage complex biologic protocols.
- ISO 13485 quality system implementation:Combination product manufacturers face dual compliance burden spanning pharmaceutical and medical device quality frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Infectious Uveitis Treatment Market |
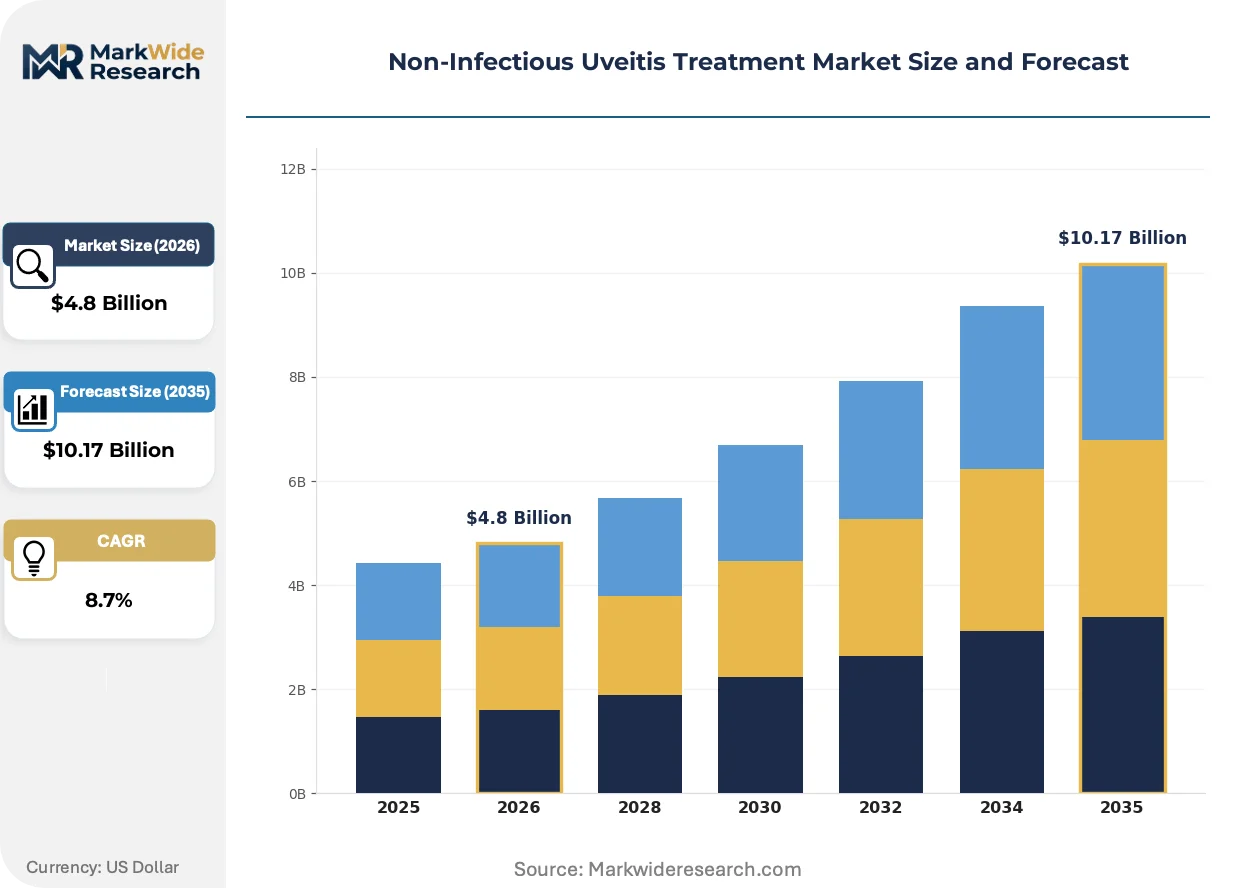
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Immunosuppressants, Biologics, NSAIDs Delivery Mode: Intravitreal Injection, Oral, Topical, Subcutaneous End User: Hospitals, Ambulatory Surgical Centers, Ophthalmology Clinics, Homecare Indication: Intermediate Uveitis, Posterior Uveitis, Anterior Uveitis, Panuveitis |
| Companies Covered | AbbVie Inc., Novartis AG, Bausch + Lomb, EyePoint Pharmaceuticals, Santen Pharmaceutical Co., Ltd., Regeneron Pharmaceuticals, Clearside Biomedical, Alimera Sciences, Ocular Therapeutix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Infectious Uveitis Treatment Market Evolving Landscape
Biologic delivery systems are compressing the treatment paradigm from chronic medication dependence toward interval-based intervention, with formulation science and regulatory science advancing in parallel.
Biodegradable polymer matrices for intravitreal drug release are rewriting the chronic disease management model in posterior uveitis. Retina specialists in academic medical centers are transitioning patients from monthly anti-inflammatory injections to six-month implant cycles. This interval extension is compressing clinic capacity constraints while improving adherence metrics in patient populations with transportation barriers.
EMA's Medical Device Regulation implementation is restructuring combination product classification and conformity assessment pathways for sustained-release ocular implants. Manufacturers must now navigate notified body involvement alongside centralized marketing authorization, extending pre-market timelines. German and French health technology assessment bodies are responding with parallel scientific advice programs to synchronize evidence generation requirements.
Hospital purchasing committees are consolidating biologic procurement through specialty pharmacy carve-outs and exclusive distribution agreements. Group purchasing organizations are displacing traditional wholesaler relationships for high-cost ophthalmology therapeutics. This concentration is most visible in United States integrated delivery networks, where formulary placement decisions now precede individual physician prescribing autonomy.
Non-Infectious Uveitis Treatment Market Segmentation
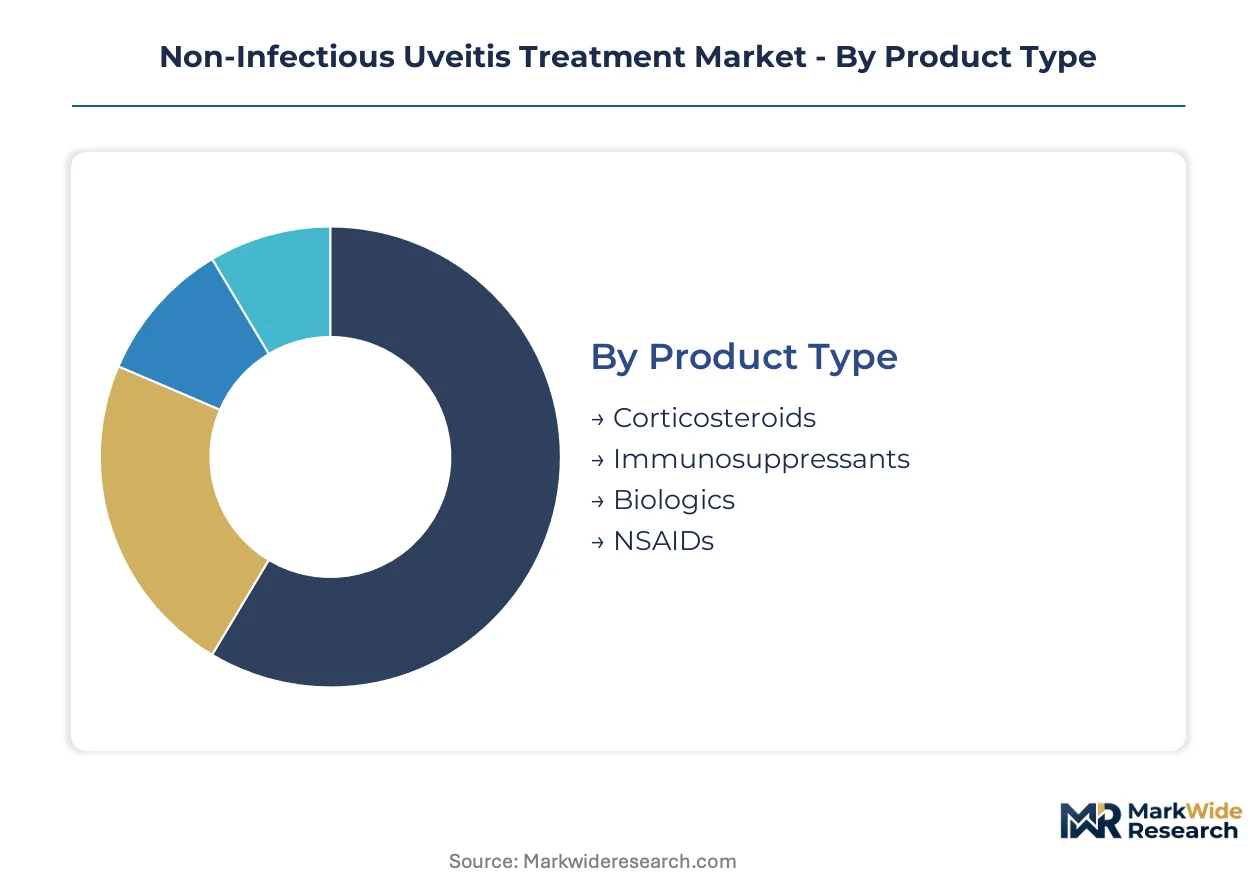
Segmentation in non-infectious uveitis treatment reveals divergent capital requirements across therapeutic modalities. Hospital procurement committees and ambulatory surgical center operators allocate budgets differently based on reimbursement pathways and site-of-care economics.
Product Type:
Biologics demand the heaviest upfront manufacturing investment due to monoclonal antibody production facilities and cold-chain infrastructure requirements.
- Biologics:Recombinant monoclonal antibodies targeting IL-6, TNF-alpha, and interferon pathways require mammalian cell culture bioreactors and sterile fill-finish capabilities. Tertiary retina centers in the United States and Germany concentrate demand for steroid-sparing protocols in refractory posterior uveitis, though manufacturing concentration limits contract development organization capacity.
- Corticosteroids:Synthetic glucocorticoid formulations span intravitreal implants, periocular depots, and topical preparations with established generic competition. Academic medical centers in Japan favor sustained-release intravitreal implants for chronic management, while anterior segment cases retain access to low-cost generic drops.
- Immunosuppressants:Calcineurin inhibitors and antimetabolites require less specialized production infrastructure than biologics.
- NSAIDs:Topical formulations serve mild anterior presentations with minimal manufacturing complexity.
Corticosteroids absorb the bulk of installed capacity; biologics are expanding most quickly.
Delivery Mode:
Route selection determines facility certification requirements and reimbursement coding complexity across care settings.
- Intravitreal Injection:Direct vitreous cavity administration via pars plana puncture demands sterile compounding pharmacies and retina specialist availability. Ambulatory surgical centers in Germany and the United States capture growing procedure volumes as site-of-care shifts accelerate under reimbursement reforms.
- Oral:Systemic corticosteroids and immunosuppressants distribute through retail pharmacy channels with lower per-dose costs but higher systemic adverse event profiles.
- Topical:Eye drop formulations target anterior segment inflammation with minimal procedural overhead.
- Subcutaneous:Biologic self-administration enables home-based therapy for maintenance protocols.
Intravitreal injection commands the steepest expansion trajectory; oral administration retains the largest patient volume base.
End User:
Capital deployment varies sharply between inpatient infrastructure and outpatient facility buildouts.
- Hospitals:Academic medical centers maintain sterile compounding capabilities, retina specialist staffing, and emergency infrastructure for acute complications. Major metropolitan networks in Tokyo, Osaka, and selected United States cities concentrate complex case referrals and biologic infusion protocols.
- Ambulatory Surgical Centers:Standalone facilities optimize throughput for scheduled intravitreal procedures with lower overhead than hospital-based settings.
- Ophthalmology Clinics:Private practice settings handle anterior segment presentations and post-implant monitoring.
- Homecare:Subcutaneous biologic administration and oral medication management extend care beyond facility walls.
Hospitals retain the dominant share of complex procedure revenue; ambulatory surgical centers are gaining share fastest.
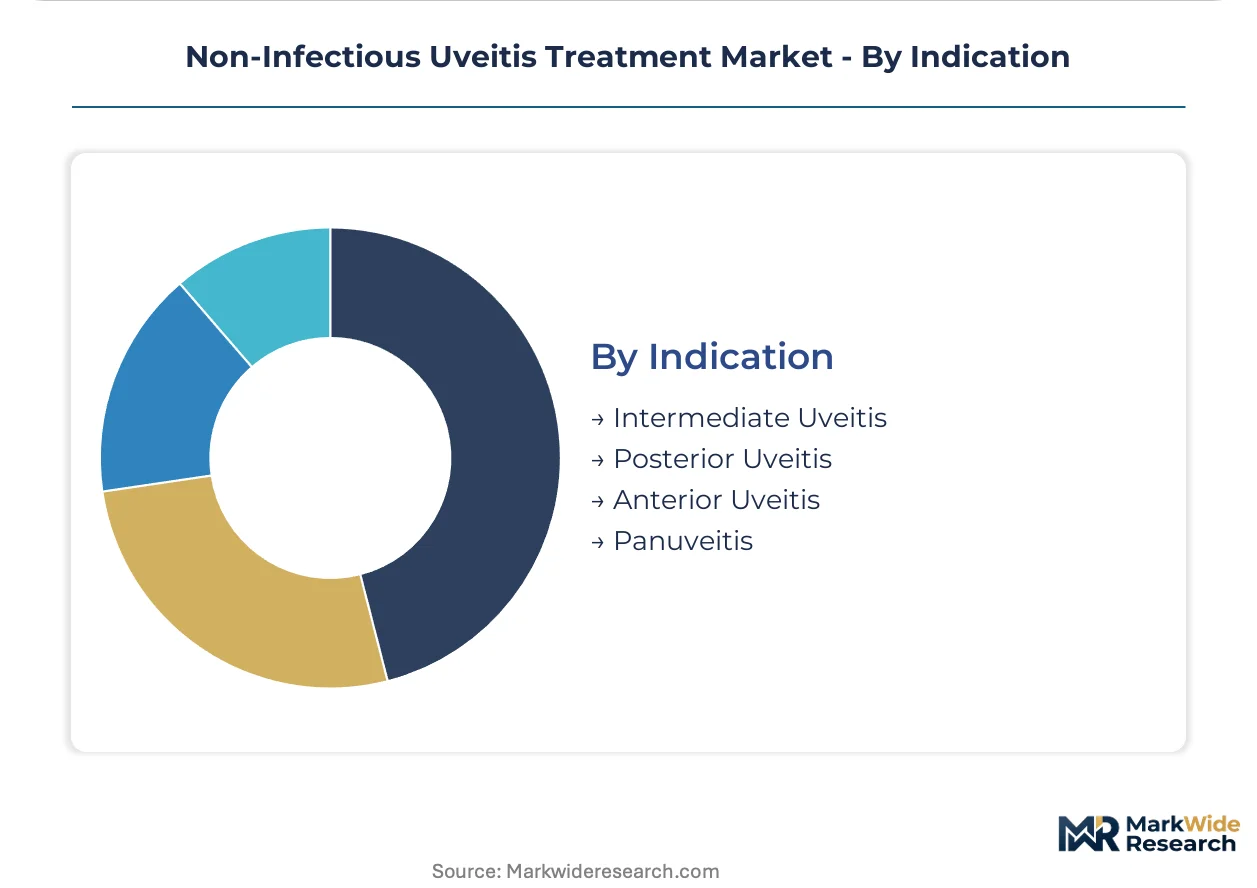
Indication:
Disease anatomical location dictates treatment intensity and specialist referral patterns.
- Posterior Uveitis:Retinal and choroidal inflammation requires intravitreal or systemic therapy to preserve visual acuity. Retina specialists in the United States and Germany prioritize biologic protocols for macular edema prevention.
- Anterior Uveitis:Iris and ciliary body inflammation responds to topical corticosteroids in most cases.
- Intermediate Uveitis:Pars plana and peripheral retinal inflammation occupies a therapeutic middle ground.
- Panuveitis:Diffuse inflammation demands aggressive systemic or combined local therapy.
Anterior uveitis generates the highest case volume; posterior uveitis drives the majority of biologic expenditure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand clusters around metropolitan retina centers in the United States, Germany, and Japan, where specialist density and reimbursement infrastructure concentrate complex case volumes. Hospital networks in these markets anchor biologic adoption curves.
United States
Integrated delivery networks in Boston, Baltimore, and San Francisco concentrate retina specialist staffing and biologic infusion capacity. FDA accelerated approval pathways compress competitive entry timelines for IL-6 pathway inhibitors. Medicare site-of-care authorization changes redirect intravitreal procedures from inpatient wards to office-based surgical suites in major metropolitan hospital networks.
Germany
Statutory health insurance reforms broaden ambulatory surgical center eligibility, shifting procedure volumes from university hospitals to standalone facilities. EMA post-market surveillance tightening extends regulatory compliance timelines for sustained-release ocular implants. Retina centers in Munich and Heidelberg anchor biologic protocol adoption for refractory posterior uveitis.
Japan
PMDA ophthalmology division prioritizes reviews for steroid-sparing biologics in posterior segment disease. Specialist retina centers cluster around Tokyo and Osaka metropolitan hospital networks, concentrating implant adoption. METI funding for combination drug-device manufacturing infrastructure addresses domestic production gaps for biodegradable polymer matrices.
United Kingdom
NICE technology appraisals determine biologic access thresholds in National Health Service specialist centers. London and Manchester academic medical centers maintain sterile compounding capabilities for intravitreal biologic protocols. MHRA post-Brexit regulatory autonomy enables accelerated assessment pathways for novel ocular delivery systems.
Switzerland
Swissmedic marketing authorization requirements align with EMA standards while permitting earlier access for academic medical center protocols. Basel and Zurich hospital networks concentrate biologic procurement through specialty pharmacy carve-outs. ISO 13485 quality system implementation supports domestic contract manufacturing for European combination product developers.
Non-Infectious Uveitis Treatment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with biologic developers commanding premium positioning against generic corticosteroid incumbents. The vendor base organizes around three strategic archetypes: immunology platform extenders, ophthalmology-focused delivery system innovators, and regional hospital contract specialists. Consolidation pressures concentrate among biologics manufacturers seeking mammalian cell culture capacity. Portfolio diversification into sustained-release formats represents the dominant competitive move alongside geographic expansion through European hospital purchasing committee relationships.
Within the immunology platform extender tier, AbbVie Inc. and Novartis AG exemplify archetypes leveraging systemic therapeutic expertise into ophthalmology-specific indications. Regeneron Pharmaceuticals occupies a distinct position among IL-6 pathway specialists with intravitreal delivery capabilities. These three entities anchor competitive dynamics through contrasting approaches to retina specialist engagement and hospital formulary placement strategy.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Novartis AG |
| Bausch + Lomb |
| EyePoint Pharmaceuticals |
| Santen Pharmaceutical Co., Ltd. |
| Regeneron Pharmaceuticals |
| Clearside Biomedical |
| Alimera Sciences |
| Ocular Therapeutix |
| Others |
Value Network & Pricing Analysis
Hospital formulary consolidation across United States integrated delivery networks is compressing supplier margins and forcing biologics manufacturers toward exclusive distribution agreements with specialty pharmacy carve-outs.
Pricing Analysis
Volume concentration in tertiary retina centers splits the market between premium biologic protocols and commoditized corticosteroid tiers. Three-tier pricing structure across premium biologic, sustained-release implant, and generic topical levels reflects certification grade and cold-chain infrastructure requirements. Pricing pressure stems from statutory health insurance reimbursement recalibration in Germany favoring ambulatory surgical center site-of-care shifts. Academic medical centers exhibit lowest price sensitivity due to formulary placement priority, while private ophthalmology clinics face acute cost compression from generic corticosteroid substitution.
Supply Chain Analysis
Specialized workforce scarcity in mammalian cell culture bioreactor operations constrains monoclonal antibody output in United States, Switzerland, and Ireland manufacturing hubs. Raw material dependencies center on recombinant protein media, biodegradable polymer matrices, and sterile fill-finish components. Single-source vulnerability for contract development and manufacturing organization capacity creates supply interruption exposure for intravitreal biologic formulations. Distribution runs through hospital specialty pharmacy channels and group purchasing organization networks rather than traditional wholesale relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biologics manufacturing concentration and EMA post-market surveillance tightening are accelerating consolidation, eliminating sub-scale players lacking mammalian cell culture infrastructure or dual ISO 13485 quality system capabilities.
For Market Incumbents: Lock in exclusive supply agreements with contract development and manufacturing organizations possessing sterile fill-finish capabilities for intravitreal formulations. Deepen backward integration into biodegradable polymer matrix production to secure programmable release kinetics technology. Defend against emerging IL-6 pathway competitors by accelerating FDA submission timelines for next-generation implant cycles.
For New Entrants and Emerging Players: Novel sustained-release delivery platforms offer the most penetrable wedge for market entry, specifically targeting six-month dosing interval extension as the unmet need. Focus initial commercialization on German ambulatory surgical centers where statutory health insurance reforms have broadened site-of-care eligibility. Pursue hospital purchasing committee relationships through value-based contracting models demonstrating reduced clinic capacity utilization.
For Investors and Strategic Acquirers: The window for entry favors contract manufacturers with ISO 13485 certification and existing ophthalmology combination product experience. Long-term viability hinges on captive supply of biodegradable polymer matrices and sterile compounding infrastructure. Watch for inflection in Medicare site-of-care authorization changes affecting office-based surgical suite reimbursement eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Accelerated Approval Pathway | Compresses competitive entry timelines for IL-6 pathway inhibitors in refractory posterior uveitis. |
| CE Marking Pathway | Enables European hospital purchasing committee access under EMA Medical Device Regulation convergence. |
| Hospital System Partnership | Secures formulary placement through specialty pharmacy carve-outs in United States integrated delivery networks. |
| Manufacturing Scale-Up | Addresses contract development and manufacturing organization capacity constraints for monoclonal antibody production. |
| Reimbursement Strategy | Aligns with Medicare site-of-care authorization changes favoring ambulatory surgical center eligibility. |
Research Methodology
Multi-period observation of FDA approval timelines, EMA post-market surveillance requirements, and hospital procurement database trends anchored the trend analysis, supplemented by interviews with retina specialists, hospital formulary directors, biologics manufacturing executives, and group purchasing organization contract managers. Secondary validation drew from FDA filings, EMA centralized marketing authorization records, ClinicalTrials.gov ophthalmology trial registries, and CMS Medicare reimbursement policy documents. Bottom-up procedure volume estimates across United States, German, and Japanese metropolitan hospital networks triangulated against top-down biologics expenditure projections.
Segment-weighting across product type, delivery mode, end user, and indication dimensions structured the analytical framework across the projection horizon. CAGRs were derived from modeled adoption curves for sustained-release intravitreal implants and biologic penetration rates in steroid-sparing protocols. Treatment line positioning, regional regulatory cluster dynamics, and site-of-care shift velocity served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including PMDA regulatory timeline acceleration beyond current ophthalmology division prioritization and unforeseen generic corticosteroid formulation disruptions. Forecasts reflect assumptions regarding continued IL-6 pathway clinical validation and stable contract manufacturing capacity expansion. Material deviation in Medicare site-of-care authorization triggers or EMA Medical Device Regulation implementation delays warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Glaucoma Treatment Market
Ophthalmology
Ocular Pain Market
Ophthalmology
Pediatric Vitrectomy Market
Ophthalmology
Ophthalmic Operating Room Microscope Market
Ophthalmology
Retinal Disease Therapeutics Market
Ophthalmology
Allergy Relieving Eye Drops Market
Ophthalmology
Ophthalmic Clinical Trials Market
Ophthalmology
Ophthalmic Ultrasound Systems Market
Ophthalmology
Eye Allergy Treatment Market
Ophthalmology
South Africa Ophthalmic Devices Market
Ophthalmology
Corneal Pachymetry Market
Ophthalmology
Trachoma Treatment Market
Ophthalmology
Panuveitis Treatment Market
Ophthalmology
Ophthalmic Eye Shield Market
Ophthalmology
Global Vitreous Tamponades Market
Ophthalmology
Inherited Retinal Diseases Treatment Market