
 Drug Delivery Systems Market | 2026-2036
Drug Delivery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Drug Delivery Systems Market Intelligence
Biodegradable polymers are decoupling implantable drug delivery from permanent foreign-body risks, cutting revision-surgery burdens for chronic therapies. Johnson & Johnson Services, Inc. leverages its DePuy Synthes orthopedic network to anchor surgical implant distribution. Novartis AG competes through its Sandoz generics unit with complex injectable capacity. Pfizer Inc. dominates parenteral manufacturing scale across multiple continental hubs.
Drug delivery systems integrate formulation science, device engineering, and biocompatible materials to achieve targeted, controlled, or sustained release of therapeutic agents at specified anatomical sites. These systems employ specifications such as zero-order release kinetics, particle sizes below 200 nanometers for cellular uptake, and polymer degradation rates calibrated to therapeutic windows spanning weeks to months. Injectable devices and infusion pumps lead product-type revenue due to biologics volume, while microneedles and nanoparticles represent the fastest-expanding delivery-technology categories as dermatology and oncology applications mature. Home healthcare providers anchor end-user demand growth as self-administration protocols expand beyond diabetes into multiple sclerosis and rheumatoid arthritis.
The FDA enforces Current Good Manufacturing Practice under 21 CFR Parts 210-211, while the EMA applies Annex 1 sterile manufacturing revisions; both frameworks elevate barrier-isolation and single-use system requirements for aseptic processing. ISO 13485 quality management standards and the EU Medical Device Regulation (MDR) reshape market access timelines and clinical-evidence burdens for combination products. Stakeholders must monitor whether FDA draft guidance on continuous manufacturing accelerates capital redeployment from batch-based sterile fill-finish lines.
Market Dynamics
Biologics manufacturers are consolidating fill-finish capacity around single-use isolator lines to meet FDA sterility expectations while cutting batch-changeover downtime. This capital redeployment is compressing the supplier base for aseptic processing equipment.
Growth Catalysts
- Wearable injector adoption:Rheumatology clinics in Germany are replacing infusion-chair protocols with patient-worn bolus devices, cutting facility overhead.
- EMA Annex 1 revision:The 2022 sterile manufacturing update mandates barrier isolation for all new aseptic lines, forcing facility upgrades that expand equipment replacement cycles.
- Microneedle dermatology:Cosmetic peptide delivery in Japan is shifting from topical creams to dissolvable microarray patches, opening formulation partnerships between device and API specialists.
Market Restraints
- Stainless steel supply concentration:Pharmaceutical-grade 316L sourcing clusters in Swedish and Finnish mills, exposing fill-finish equipment builders to alloy price volatility.
- Polymer degradation calibration:PLGA molecular-weight variability forces extended stability testing for depot formulations, stretching development timelines.
- Biologic cold-chain dependency:mRNA lipid nanoparticles require uninterrupted -70°C logistics, limiting distribution to markets with validated cryogenic infrastructure.
Strategic Opportunities
- Home infusion in Brazil:ANVISA's 2023 remote-monitoring guidance enables reimbursement for ambulatory pump therapy, opening Latin America's largest pharma market to wearable device entrants.
- Continuous manufacturing transition:FDA draft guidance on real-time release testing invites capital-light modular lines that slash sterile suite footprints.
- Implantable oncology:Biodegradable wafers for glioblastoma are crossing from preclinical to Phase III, creating polymer synthesis partnerships between device and API manufacturers.
Industry Challenges
- Isolator engineering talent:Aseptic containment design expertise concentrates among retirees from 1990s-era barrier technology programs, constraining vendor expansion.
- EU MDR combination-product recertification:Prefilled syringes with integrated needles face dual technical file submissions, stretching regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug Delivery Systems Market |
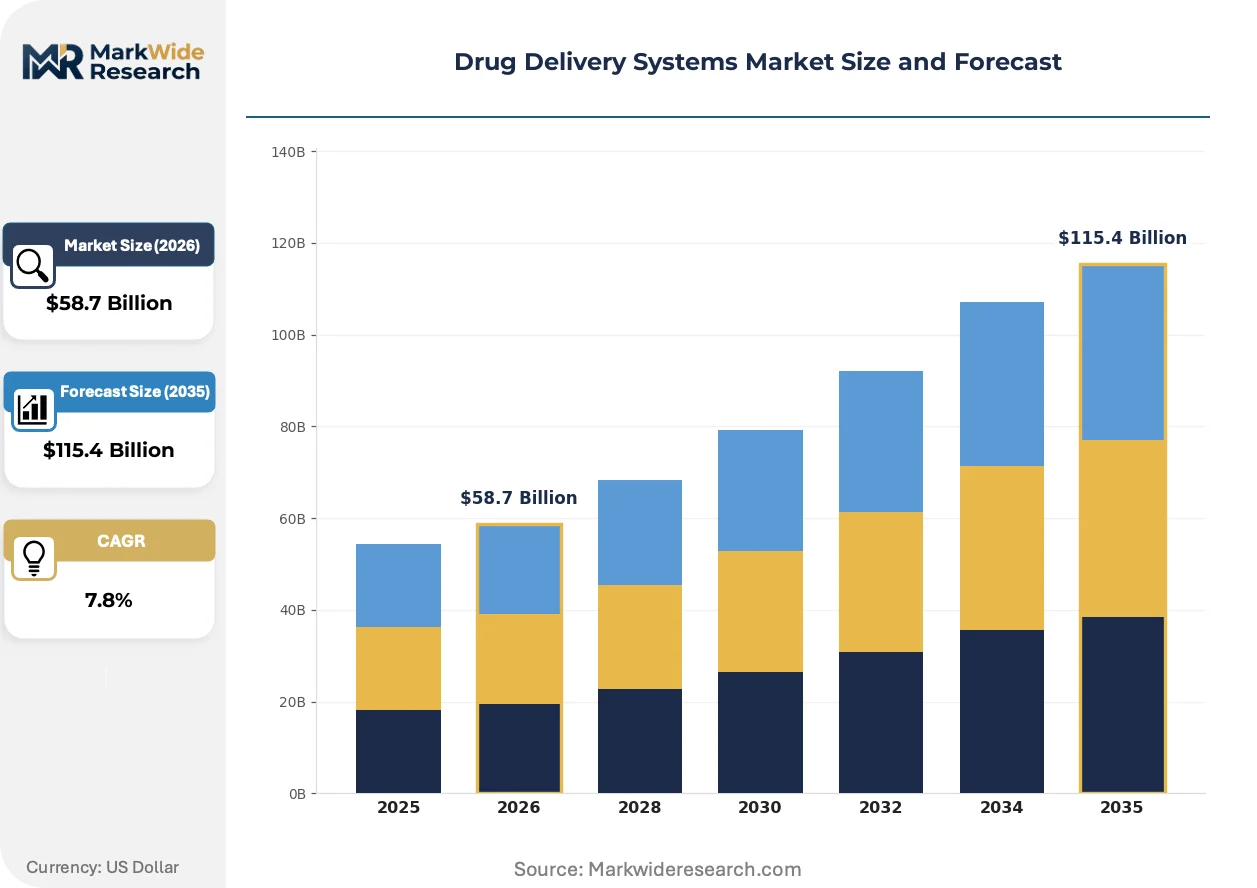
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $115.4 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Transdermal Patches, Injectable Devices, Oral Disintegrating Tablets, Infusion Pumps Therapy Area: Oncology, Cardiovascular, Neurological, Respiratory, Diabetes End User: Pharmacies, Research Laboratories, Specialty Clinics, Home Healthcare Providers, Long-term Care Facilities Delivery Technology: Microneedles, Liposomal, Nanoparticles, Polymer-based Systems, Biodegradable Implants |
| Companies Covered | Johnson & Johnson Services, Inc., Novartis AG, Pfizer Inc., Becton, Dickinson and Company, Baxter International Inc., West Pharmaceutical Services Inc., Amgen Inc., Gerresheimer AG, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug Delivery Systems Market Strategic Shifts & Innovations
Digital integration is collapsing the distinction between drug delivery hardware and patient monitoring software, creating subscription revenue models that compete with capital equipment sales.
Smart autoinjectors with embedded sensors are unifying dose administration with adherence tracking. Multiple sclerosis clinics in the United States are piloting Bluetooth-enabled platforms that transmit injection timestamps to electronic health records. This connectivity is unifying reimbursement negotiations around outcomes verification rather than device procurement alone.
REACH polymer registration is tightening supply chains for implantable-grade polycaprolactone. European compounders now face substance volume thresholds that exclude small-batch medical grades from simplified notification pathways. German orthopedic device manufacturers are responding by qualifying alternative polyester suppliers from Switzerland and Austria.
Self-administration training is compressing the traditional nurse-education model for biologic therapy. Rheumatology practices in Japan are replacing in-clinic injection tutorials with augmented-reality smartphone applications that guide patients through subcutaneous technique. Osaka-area specialty pharmacies report reduced callback volumes as visual instruction replaces paper leaflets.
Drug Delivery Systems Market Segmentation
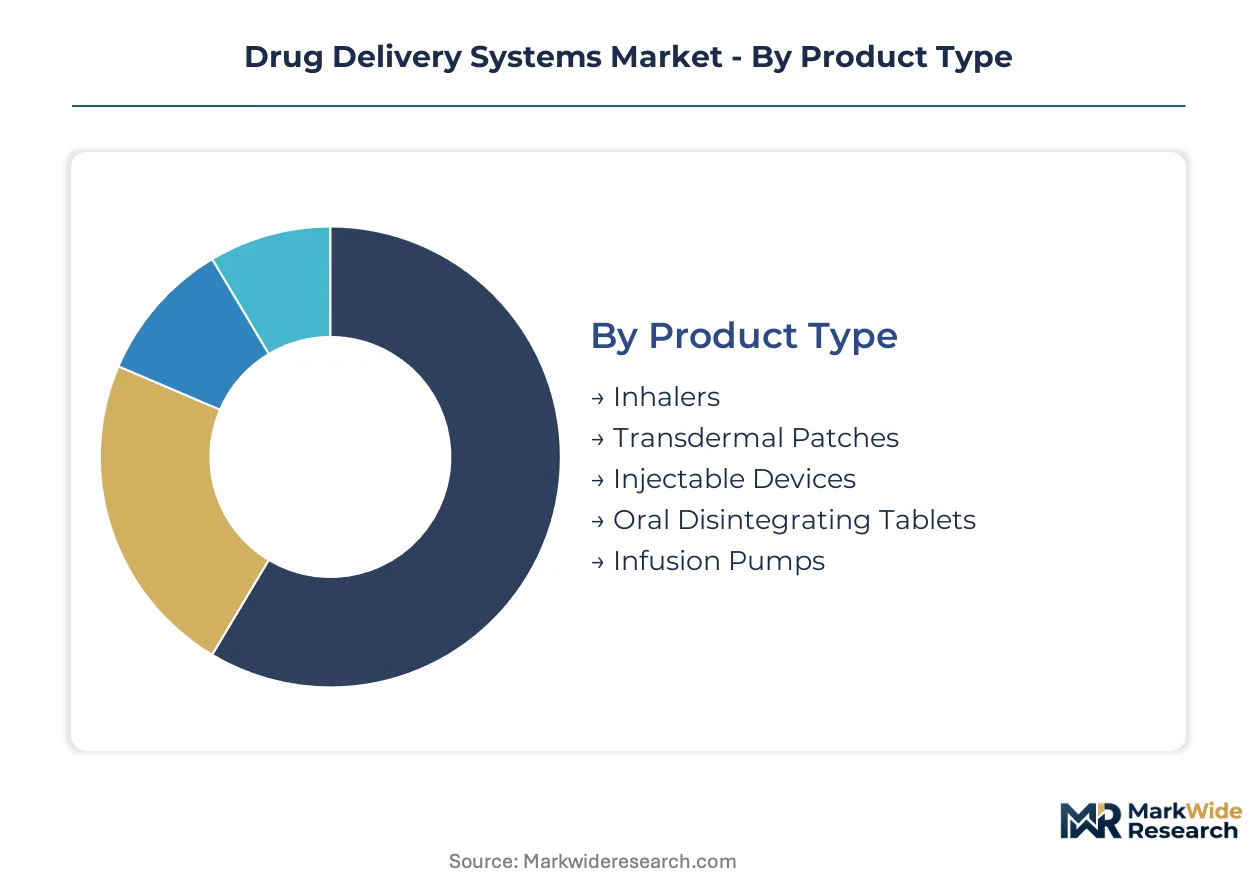
Drug delivery segmentation reveals how regulatory pathways and manufacturing complexity fragment commercial opportunity. Each category carries distinct certification burdens, supply chain configurations, and customer access patterns that reshape competitive positioning across therapeutic domains.
Product Type:
Injectable Devices and Infusion Pumps face FDA 21 CFR Part 820 quality system requirements plus EMA MDR combination-product rules, while Inhalers navigate EPA propellant regulations alongside medical device standards.
- Injectable Devices:Prefilled syringes and autoinjectors incorporate glass-barrel or polymer-barrel construction with staked-needle or luer-lock interfaces. Rheumatology clinics in Germany are replacing infusion-chair protocols with patient-worn bolus devices, cutting facility overhead while expanding self-administration eligibility.
- Infusion Pumps:Ambulatory and implantable variants deliver programmable basal-bolus profiles through peristaltic or syringe-drive mechanisms. Home healthcare providers in the United States anchor demand growth as multiple sclerosis and rheumatoid arthritis protocols shift from clinical to residential settings.
- Inhalers:Pressurized metered-dose and dry-powder formats serve asthma and COPD maintenance therapy.
- Transdermal Patches:Reservoir and matrix designs enable nicotine cessation and hormone replacement through stratum corneum penetration.
- Oral Disintegrating Tablets:Lyophilized wafer and compressed tablet formats dissolve on the tongue for pediatric and geriatric compliance.
Injectable Devices sit at the top of the volume ranking, with Infusion Pumps climbing the fastest as home-care protocols expand beyond diabetes into neurology and immunology.
Therapy Area:
Oncology and Diabetes command the steepest R&D investment curves, while Cardiovascular and Neurological applications face diverging reimbursement density across national health systems.
- Oncology:Liposomal doxorubicin and antibody-drug conjugates require cold-chain integrity through distribution. Research laboratories in Boston cluster around Phase I-III trials for biodegradable wafer implants targeting glioblastoma, with polymer synthesis partnerships bridging device and API manufacturers.
- Diabetes:Insulin pens, pumps, and continuous glucose monitor-integrated closed-loop systems dominate unit volumes. Osaka-area specialty pharmacies report reduced callback volumes as augmented-reality smartphone applications replace paper leaflets for subcutaneous technique training.
- Cardiovascular:Anticoagulant depot formulations and implantable sensors address post-stroke medication adherence.
- Respiratory:Inhaled corticosteroid-long-acting beta-agonist combinations serve asthma and COPD maintenance.
- Neurological:Intrathecal pumps and intranasal delivery target multiple sclerosis and Parkinson's disease symptom management.
Diabetes captures the highest absolute unit volume, with Oncology gaining share fastest as lipid nanoparticle and biodegradable implant platforms mature.
End User:
Home Healthcare Providers and Specialty Clinics operate on diverging procurement rhythms, with the former emphasizing disposable cost-per-dose and the latter prioritizing device durability and staff training efficiency.
- Home Healthcare Providers:Skilled nursing agencies and durable medical equipment suppliers coordinate patient training, device provisioning, and remote monitoring. ANVISA's remote-monitoring guidance in Brazil enables reimbursement for ambulatory pump therapy, opening Latin America's largest pharma market to wearable device entrants.
- Specialty Clinics:Rheumatology, endocrinology, and oncology infusion centers manage biologic administration protocols. Frankfurt-area dermatology practices are piloting microneedle peptide delivery, shifting from topical creams to dissolvable microarray patches.
- Pharmacies:Retail and specialty pharmacy networks handle prescription fulfillment and patient counseling for self-administered therapies.
- Research Laboratories:Academic and contract research organizations conduct preclinical and clinical formulation studies.
- Long-term Care Facilities:Nursing homes and assisted-living centers manage polypharmacy regimens for geriatric populations.
Home Healthcare Providers dominate current procurement volumes, with Specialty Clinics expanding most quickly as infusion-chair protocols convert to ambulatory alternatives.
Delivery Technology:
Microneedles and Nanoparticles occupy the innovation frontier with abbreviated regulatory precedents, while Liposomal and Polymer-based Systems leverage decades of toxicology dossiers.
- Nanoparticles:Lipid and polymeric carriers below 200 nanometers enable cellular uptake and tumor targeting through enhanced permeability and retention effects. mRNA lipid nanoparticles require uninterrupted -70°C logistics, limiting distribution to markets with validated cryogenic infrastructure.
- Microneedles:Dissolvable, hydrogel-forming, and hollow variants pierce the stratum corneum without dermal nerve activation. Cosmetic peptide delivery in Japan is shifting from topical creams to dissolvable microarray patches, opening formulation partnerships between device and API specialists.
- Liposomal:Phospholipid bilayer encapsulation improves solubility and reduces toxicity for chemotherapeutic agents.
- Polymer-based Systems:PLGA and polycaprolactone matrices enable sustained release through bulk or surface erosion mechanisms.
- Biodegradable Implants:Rod, wafer, and depot formulations eliminate retrieval surgery for chronic therapies.
Nanoparticles lead current technology investment, with Microneedles following the steepest expansion trajectory as dermatology and vaccine applications mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's biotech corridor anchors North American drug delivery innovation, with specialty pharmaceutical production clustering around Frankfurt and Osaka driving European and Asian demand respectively.
United States
FDA's Quality by Design framework and 21 CFR Parts 210-211 sterile manufacturing rules are tightening barrier-isolation requirements for aseptic processing. Massachusetts-based research laboratories cluster around Phase I-III trials for biodegradable wafer implants targeting glioblastoma. Multiple sclerosis clinics across the country pilot Bluetooth-enabled autoinjector platforms that transmit injection timestamps to electronic health records.
Germany
Rheumatology clinics in Frankfurt and surrounding regions are replacing infusion-chair protocols with patient-worn bolus devices, cutting facility overhead while expanding self-administration eligibility. EMA Annex 1 revisions mandate barrier isolation for all new aseptic lines, forcing facility upgrades that expand equipment replacement cycles. Bavarian orthopedic device manufacturers are qualifying alternative polyester suppliers from Switzerland and Austria as REACH polymer registration tightens supply chains.
Japan
Osaka-area specialty pharmacies report reduced callback volumes as augmented-reality smartphone applications replace paper leaflets for subcutaneous technique training. METI standards and PMDA oversight shape combination-product approval timelines for microneedle peptide delivery systems. Cosmetic peptide delivery in Tokyo and surrounding markets is shifting from topical creams to dissolvable microarray patches, opening formulation partnerships between device and API specialists.
Brazil
ANVISA's 2023 remote-monitoring guidance enables reimbursement for ambulatory pump therapy, opening Latin America's largest pharma market to wearable device entrants. São Paulo-based home healthcare providers are consolidating procurement around disposable cost-per-dose metrics as self-administration protocols expand beyond diabetes. The country's national pharmaceutical regulator is aligning sterile manufacturing standards with international norms to accelerate biologics licensing.
Switzerland
Swissmedic oversight of combination products creates a regulatory gateway for European market access. Basel and Zurich host polymer synthesis partnerships bridging device and API manufacturers for implantable oncology applications. German orthopedic manufacturers source pharmaceutical-grade 316L stainless steel and implantable-grade polycaprolactone through Swiss compounders as REACH volume thresholds exclude small-batch medical grades from simplified notification pathways.
Drug Delivery Systems Market Key Industry Players
Global majors compete with regional champions across fill-finish capacity and combination-product certification. The supplier base compresses around single-use isolator lines as biologics manufacturers consolidate aseptic processing equipment procurement. Three archetypes dominate: diversified healthcare conglomerates with orthopedic networks, specialized parenteral manufacturers with continental hub scale, and generic injectable specialists with complex formulation capacity. Competitive moves center on polymer synthesis partnerships for biodegradable implants and continuous manufacturing technology licensing.
Within the diversified healthcare tier, Johnson & Johnson Services, Inc. and Pfizer Inc. exemplify contrasting scale strategies. Novartis AG occupies a position bridging proprietary and generic portfolios through its Sandoz unit. These three entities represent the dominant competitive archetypes: network-anchored distribution, multi-continental manufacturing scale, and complex injectable specialization respectively.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Novartis AG |
| Pfizer Inc. |
| Becton, Dickinson and Company |
| Baxter International Inc. |
| West Pharmaceutical Services Inc. |
| Amgen Inc. |
| Gerresheimer AG |
| Medtronic |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up aseptic equipment specialists are consolidating fill-finish component suppliers across Sweden and Finland, tightening pharmaceutical-grade 316L stainless steel availability while compressing procurement leverage for mid-tier device manufacturers. This ownership concentration feeds directly into pricing discipline for barrier-isolation systems and single-use assemblies.
Pricing Analysis
Input-cost pass-through from pharmaceutical-grade polymer and alloy markets dominates pricing dynamics for implantable-grade polycaprolactone and 316L stainless steel components. Pricing stratifies across FDA-certified barrier systems, CE-marked standard lines, and economy-grade non-isolated equipment tiers. Cost compression in economy-grade autoinjectors is intensifying as Brazilian and Indian home healthcare providers consolidate procurement around disposable cost-per-dose metrics. Specialty clinics in Germany and Japan exhibit the lowest price sensitivity due to EMA Annex 1 compliance mandates and METI quality benchmarks.
Supply Chain Analysis
Dual-sourcing requirements for aseptic processing equipment mandate qualification of both Swedish and Finnish mills for pharmaceutical-grade 316L stainless steel, plus Swiss and Austrian compounders for implantable-grade polycaprolactone. Raw material dependencies center on PLGA polymers, phospholipid excipients, and cryogenic-grade insulation foams. Single-source vulnerability concentrates in barrier-isolation engineering talent pools retiring from 1990s-era containment programs. Distribution runs through regional equipment distributors serving Frankfurt-area rheumatology clinics and Osaka-area specialty pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EMA Annex 1 sterile manufacturing revisions and FDA Quality by Design frameworks are accelerating equipment replacement cycles and polymer qualification timelines.
For Market Incumbents: Anticipate margin pressure from continuous manufacturing modular lines by securing polymer synthesis partnerships for biodegradable oncology implants before Phase III trials complete. Anchor defensive positioning through backward integration into pharmaceutical-grade 316L sourcing networks across Scandinavian mills. Prioritize certification investment for EU MDR combination-product technical files to stretch regulatory affairs bandwidth among mid-tier competitors.
For New Entrants and Emerging Players: Capture white-space in Brazil's home infusion segment where ANVISA remote-monitoring guidance enables reimbursement for ambulatory pump therapy. Target microneedle peptide delivery partnerships between device specialists and cosmetic API manufacturers in Japan's dermatology market. Lead with augmented-reality patient training platforms that compress traditional nurse-education models for subcutaneous biologic administration.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional aseptic equipment specialists lacking single-use isolator line portfolios. Long-term viability across the analysis window hinges on exposure to biologics fill-finish capacity expansion rather than small-molecule batch processing. Signal to monitor: FDA draft guidance finalization on real-time release testing and continuous manufacturing adoption rates among top-ten biologics manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Polymer Synthesis Partnership | Biodegradable wafer implants for glioblastoma bridge device and API manufacturers across Boston and Basel clusters. |
| Continuous Manufacturing Licensing | Modular sterile lines slash facility footprints while meeting FDA draft guidance on real-time release testing protocols. |
| Barrier-Isolation Certification | EMA Annex 1 compliance mandates drive equipment replacement cycles for single-use isolator line installations. |
| Home Infusion Reimbursement Strategy | ANVISA remote-monitoring guidance opens Latin America's largest pharma market to wearable pump device entrants. |
| Augmented-Reality Training Platform | Osaka-area specialty pharmacies reduce callback volumes through smartphone-guided subcutaneous technique instruction. |
Research Approach
Direct dialogue with aseptic processing equipment engineers, regulatory affairs leads at combination-product manufacturers, hospital procurement managers, and polymer synthesis R&D directors grounded qualitative findings. Secondary validation drew from FDA 21 CFR filings, EMA Annex 1 revision documents, ISO 13485 certification databases, and ClinicalTrials.gov biodegradable implant records. Bottom-up demand modeling for prefilled syringe and wearable injector volumes triangulated against top-down biologics production capacity estimates across Massachusetts, Frankfurt, and Osaka manufacturing clusters.
Market sizing outputs reflect segment-level projections across product type, therapy area, end user, and delivery technology dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical biologics fill-finish capacity expansion correlated with regulatory compliance investment cycles. Industry-specific inputs incorporated PLGA degradation rate variability, microneedle dermatology adoption curves, and cold-chain infrastructure penetration by regional market.
Regulatory timeline delays, polymer supply concentration shocks, and continuous manufacturing technology adoption rates are the dominant revision risks to demand forecasts. Deviation in FDA draft guidance finalization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Acne Treatment Devices Market
Medical Devices
Craniomaxillofacial Devices Market
Medical Devices
Luer Lock Connector Market
Medical Devices
Global Cardiac Holter Monitor Market
Medical Devices
Deaver Retractor Market
Medical Devices
Saudi Arabia Minimally Invasive Surgery Devices Market
Medical Devices
Europe 3D Printing in Healthcare Market
Medical Devices
Inferior Vena Cava Filters Market
Medical Devices
Large Volume Nebulizers Market
Medical Devices
Organ Preservation Market
Medical Devices
Pen Needles Market
Medical Devices
Global Tracheal Tube and Airway Products Market
Medical Devices
Global Semiconductor in Healthcare Market
Medical Devices
Global Mobile ECG Devices Market
Medical Devices
Global Mucosal Atomization Devices Market
Medical Devices
Syringe Scale Magnifiers Market