
 France Ophthalmic Devices Market | 2026-2036
France Ophthalmic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
France Ophthalmic Devices Market Foresight
Hospital procurement is rotating toward ambulatory surgery centers as cataract and refractive procedures migrate to outpatient settings. EssilorLuxottica SA dominates the contact lens and spectacle lens segment through its vertically integrated optical supply chain. Alcon Inc. competes across surgical instruments and intraocular lenses with sustained investment in phacoemulsification platforms. Carl Zeiss Meditec AG leads diagnostic imaging through its optical coherence tomography systems, which occupy premium positions in French university hospital networks.
Ophthalmic devices encompass precision instruments, implants, and diagnostic systems engineered to specifications such as biocompatible acrylic intraocular lenses with 6-millimeter optic diameters and swept-source OCT platforms achieving 3-micrometer axial resolution, all designed to restore, preserve, or measure visual function. Diagnostic devices anchor the product mix as glaucoma and retinal disease screening expands under France's national diabetic retinopathy surveillance program, while surgical instruments capture concentrated margin pools tied to single-use phacoemulsification consumables. Laser systems within the technology dimension sustain above-average growth as excimer and femtosecond platforms displace mechanical microkeratomes in refractive surgery workflows.
ANSM enforces pre-market conformity assessment for Class III implantable ophthalmic devices under EU MDR transition timelines, while CNIL governs patient imaging data flows from connected diagnostic equipment. CE marking and ISO 13485 quality system certification shape market access thresholds for both domestic manufacturers and importers serving French healthcare providers. Stakeholders must monitor MDR notified body capacity constraints and evolving reimbursement tariffs from France's Haute Autorité de Santé as determinants of commercial viability for novel surgical platforms.
Market Dynamics
France's ophthalmic device sector pivots on the EU MDR transition, which compresses notified body capacity and elongates conformity assessment timelines for Class III implantable lenses. Surgical volume migration toward outpatient settings simultaneously reconfigures procurement authority away from centralized hospital purchasing.
Growth Catalysts
- ANSM CE marking enforcement:Stricter pre-market scrutiny under EU MDR elevates barriers for low-quality imports, protecting established suppliers with robust quality systems.
- Ambulatory surgery center expansion:Cataract and refractive procedure volumes are migrating to outpatient facilities, creating dedicated equipment demand for streamlined surgical platforms.
- Île-de-France teaching hospital networks:Paris-based academic medical centers drive procurement of premium diagnostic and surgical systems, concentrating high-value demand in the capital region.
Market Restraints
- Notified body capacity constraints:EU MDR transition has thinned certifier availability, extending time-to-market for novel implantable devices by 12-18 months.
- Single-use consumable cost inflation:Phacoemulsification tubing and irrigation sets face polymer supply volatility, pressuring per-procedure margins in high-volume cataract workflows.
- Technical limitation in femtosecond adoption:Laser-assisted cataract surgery platforms require substantial facility investment and surgeon retraining, slowing penetration outside major urban centers.
Strategic Opportunities
- Connected diagnostic platforms:OCT systems with cloud-based image storage align with CNIL data governance frameworks and enable remote screening for diabetic retinopathy.
- Provincial clinic networks:Underpenetrated regions beyond Île-de-France present whitespace for mobile diagnostic units and distributed surgical capacity.
- Reimbursement tariff optimization:HAS periodic review of procedure codes creates windows for premium IOL technologies to secure favorable coverage.
Industry Challenges
- ISO 13485 certification timelines:Quality system audits face backlogs, delaying market access for emerging manufacturers and contract sterilization providers.
- Surgeon training pipeline constraints:Femtosecond laser and advanced IOL implantation techniques require specialized fellowship programs, creating adoption bottlenecks.
- Legacy equipment integration:New diagnostic platforms must interface with hospital information systems using heterogeneous data standards, complicating deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Ophthalmic Devices Market |
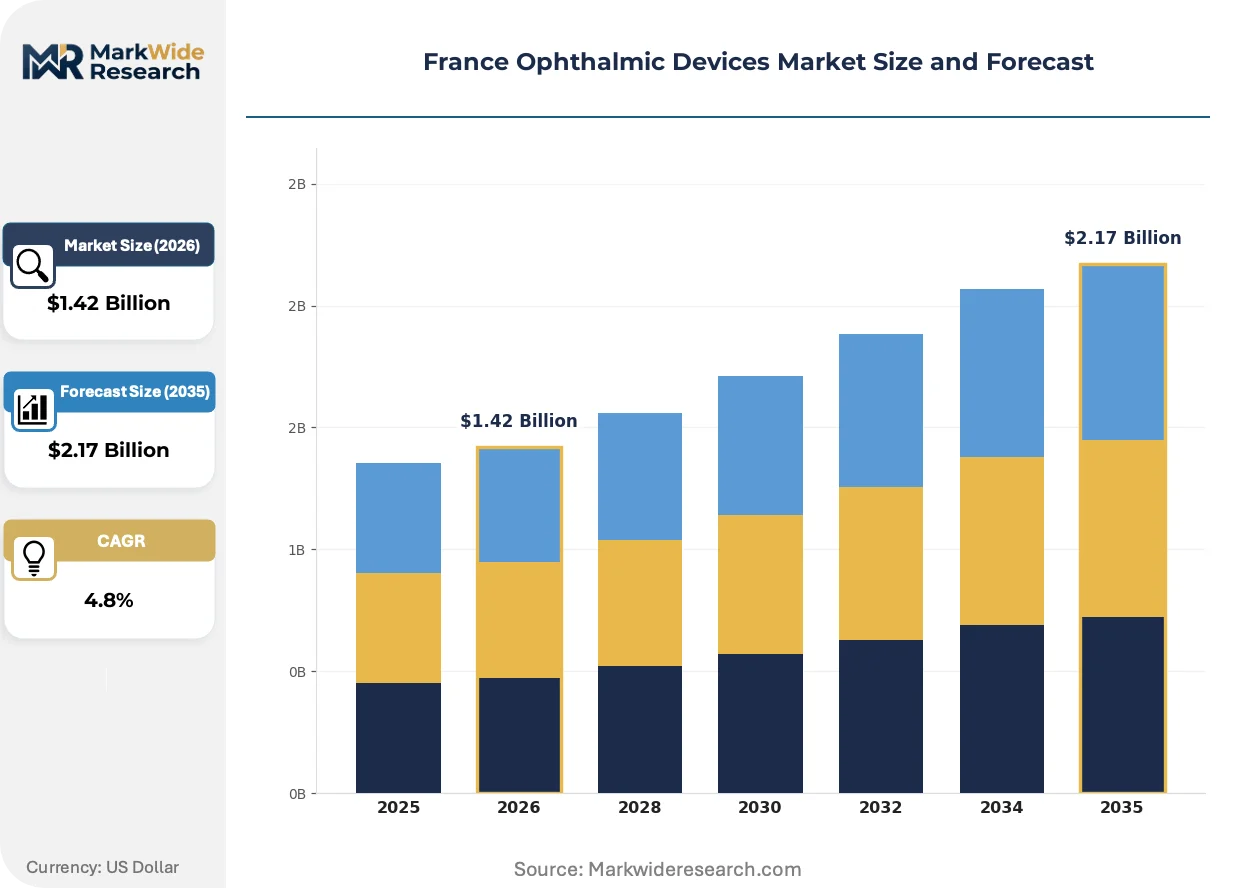
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraocular Lenses, Diagnostic Devices, Surgical Instruments, Contact Lenses, Imaging Systems Application: Cataract Surgery, Glaucoma Management, Retinal Treatment, Refractive Surgery, Corneal Therapy End User: Hospitals, Eye Care Clinics, Specialty Centers, Ambulatory Surgery Centers, Ophthalmologists Technology: Laser Systems, Optical Coherence Tomography, Digital Imaging, Phacoemulsification, Ultrasonography |
| Companies Covered | EssilorLuxottica SA, Alcon Inc., Carl Zeiss Meditec AG, Johnson & Johnson Vision Care, Topcon Corporation, Bausch Health Companies Inc., Hoya Corporation, HAAG-Streit Group, Nidek Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Ophthalmic Devices Market Shifts & Advancements
Technological substitution and regulatory compression are actively restructuring competitive positioning in French ophthalmic care. Device portfolios are splitting between premium platforms for academic centers and streamlined systems for high-volume outpatient settings.
Swept-source optical coherence tomography is bifurcating the diagnostic imaging landscape. These systems achieve sub-3-micrometer axial resolution for glaucoma and retinal disease detection. University hospital networks in Paris and Lyon are adopting them rapidly, while regional clinics retain older spectral-domain platforms. The technology split is compressing mid-tier equipment margins and concentrating premium value in top-tier academic purchasers.
EU MDR transition timelines are reshaping product lifecycle planning for implantable devices. ANSM now requires updated clinical evidence packages for legacy intraocular lenses seeking certificate renewal. Manufacturers with pre-MDR approvals face parallel regulatory maintenance and new product development, diverting R&D resources toward compliance rather than innovation. Surgical implant segments bear the heaviest documentation burden, accelerating consolidation among suppliers with dedicated regulatory affairs capacity.
Hospital purchasing consortia are fragmenting authority across regional health agencies and independent surgery centers. Centralized tenders at AP-HP and other Paris hospital groups once dominated procurement; now autonomous ambulatory centers negotiate directly with manufacturers for phacoemulsification platforms. This diffusion is most visible in the Provence-Alpes-Côte d'Azur and Occitanie regions, where private ophthalmology chains have captured substantial surgical volume from public hospitals.
France Ophthalmic Devices Market Segmentation
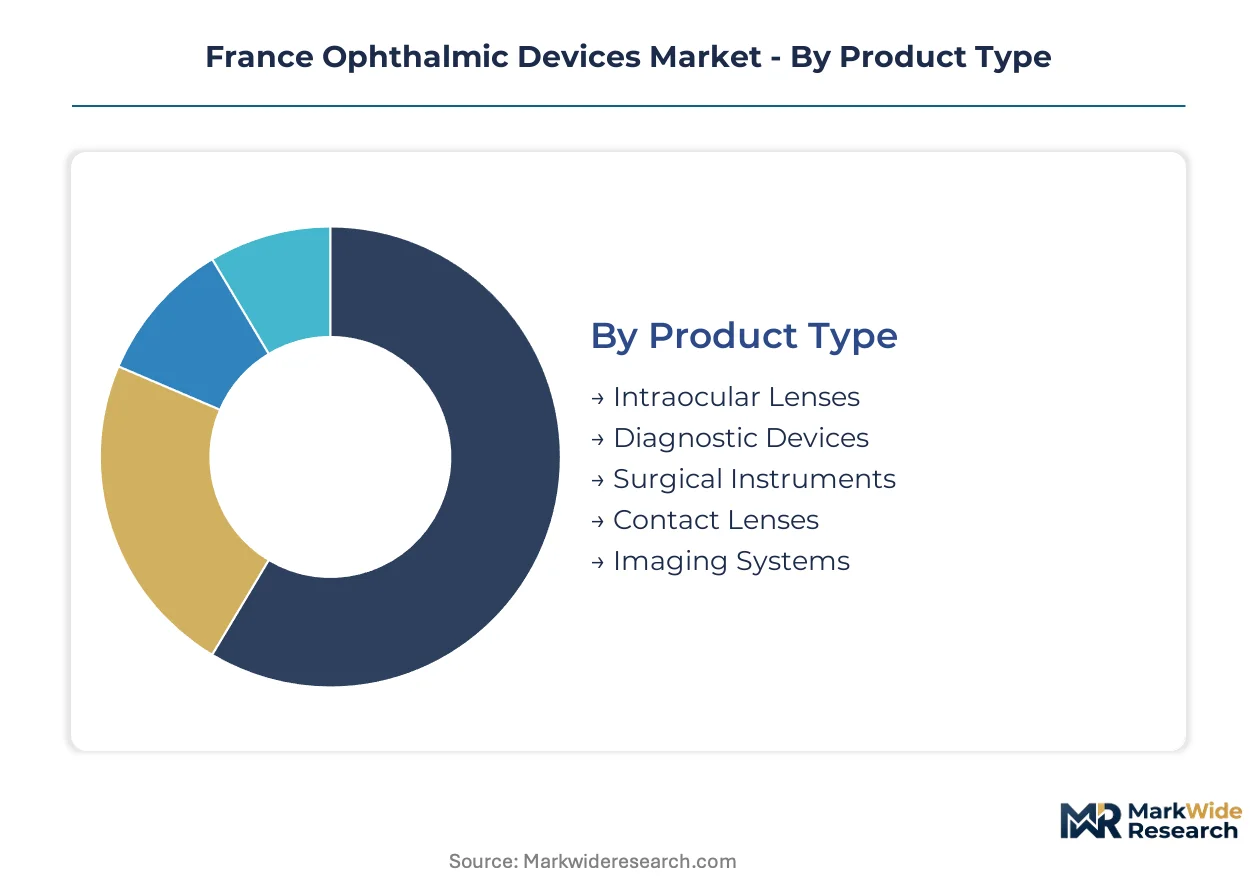
Segmentation in the France ophthalmic devices market reveals how procurement authority, clinical workflow, and regulatory burden distribute across distinct product and customer categories. Understanding these splits enables suppliers to align R&D investment with reimbursement pathways and facility-level purchasing power.
Product Type:
Domestic manufacturing concentrates in diagnostic and surgical platforms around Paris and Lyon, while intraocular lenses and contact lenses flow through import channels dominated by multinational supply chains.
- Intraocular Lenses:Biocompatible acrylic and silicone optics with 6-millimeter diameters and toric or multifocal corrections. Demand clusters in Île-de-France teaching hospitals where premium IOLs command favorable HAS reimbursement tariffs for complex cataract cases.
- Diagnostic Devices:Optical coherence tomography systems, perimetry units, and slit-lamp biomicroscopes for glaucoma and retinal screening. Adoption accelerates under France's national diabetic retinopathy surveillance program, with swept-source OCT platforms replacing spectral-domain units in university hospital networks.
- Surgical Instruments:Phacoemulsification handpieces, irrigation-aspiration sets, and microsurgical forceps engineered for single-use or limited reprocessing cycles.
- Contact Lenses:Daily disposable silicone hydrogel and rigid gas-permeable designs for refractive correction and therapeutic applications.
- Imaging Systems:Fundus cameras and angiography platforms integrating with hospital information systems for centralized image archiving under CNIL data governance.
Intraocular lenses hold the largest share; momentum sits with diagnostic devices as screening protocols expand.
Application:
Cost tier stratification separates premium academic procedures from high-volume outpatient workflows, with reimbursement differentials driving technology selection.
- Cataract Surgery:Phacoemulsification with IOL implantation represents the highest procedural volume in French ophthalmology. Ambulatory surgery centers in Provence-Alpes-Côte d'Azur and Occitanie capture growing case volumes from public hospital networks.
- Glaucoma Management:Minimally invasive glaucoma surgery devices and sustained-release drug delivery implants. Paris-based academic centers drive adoption of advanced surgical alternatives to topical therapy regimens.
- Retinal Treatment:Vitrectomy platforms and laser photocoagulation systems for diabetic retinopathy and age-related macular degeneration.
- Refractive Surgery:Excimer and femtosecond laser platforms for corneal reshaping procedures, concentrated in private clinic chains with direct-to-consumer marketing capacity.
- Corneal Therapy:Cross-linking systems and endothelial keratoplasty instruments for corneal dystrophy and ectasia management.
Cataract surgery commands the greatest revenue concentration; glaucoma management is climbing fastest as surgical alternatives displace pharmaceutical first-line therapy.
End User:
Customer type fragmentation splits purchasing authority between centralized hospital consortia and autonomous outpatient facilities with divergent equipment specifications.
- Hospitals:Public hospital groups such as AP-HP maintain bulk procurement leverage for multi-system diagnostic platforms and surgical suites serving mixed inpatient-outpatient volumes.
- Eye Care Clinics:Independent and chain-affiliated practices requiring compact diagnostic equipment with streamlined maintenance contracts.
- Specialty Centers:Dedicated retinal or glaucoma institutes with concentrated case volumes justifying premium technology investment.
- Ambulatory Surgery Centers:Streamlined cataract and refractory procedure facilities negotiating directly with manufacturers for phacoemulsification platforms, bypassing traditional hospital supply chains.
- Ophthalmologists:Solo practitioners and small group practices selecting portable diagnostic devices and consumable surgical supplies through distributor networks.
Hospitals retain the largest installed base; ambulatory surgery centers are expanding most quickly as surgical volume migrates outpatient.
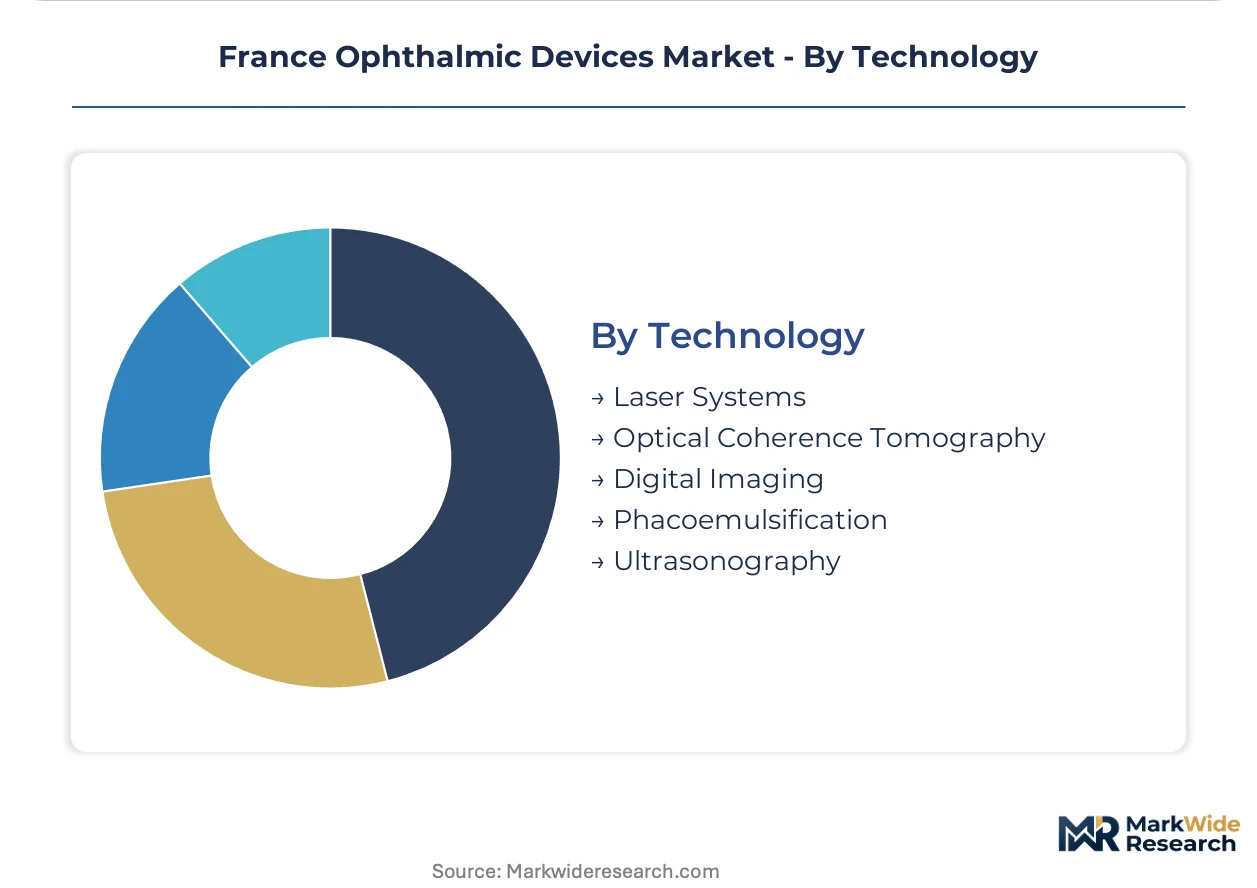
Technology:
Maturity curves separate established modalities from emerging platforms facing adoption barriers tied to capital intensity and surgeon training requirements.
- Laser Systems:Excimer platforms for refractive correction and femtosecond systems for flap creation and lens fragmentation. Femtosecond adoption for cataract surgery stalls outside major urban centers due to facility investment thresholds and retraining requirements.
- Optical Coherence Tomography:Spectral-domain and swept-source platforms achieving sub-3-micrometer axial resolution for retinal layer imaging. Swept-source systems gain share in Paris and Lyon university hospitals while regional clinics retain older spectral-domain units.
- Digital Imaging:Connected fundus photography and angiography with cloud-based storage architectures compliant with CNIL patient data regulations.
- Phacoemulsification:Ultrasound-based lens fragmentation systems with peristaltic or venturi fluidics, the workhorse technology for cataract surgery across all French facility types.
- Ultrasonography:A-scan and B-scan ocular biometry for axial length measurement and posterior segment imaging when optical media opacity limits light-based diagnostics.
Phacoemulsification anchors current procedural volume; optical coherence tomography shows steepest expansion trajectory as screening protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision surgical platforms to French hospital networks through established EU trade corridors. Swiss optical component suppliers feed diagnostic imaging supply chains serving Paris-based academic centers. Italian lens fabricators maintain secondary sourcing relationships with French distributors.
Île-de-France
AP-HP hospital group procurement concentrates demand for premium phacoemulsification systems and swept-source OCT platforms. ANSM's CE marking enforcement under EU MDR timelines shapes pre-market access for implantable devices seeking entry through Paris teaching hospitals. Paris and surrounding suburbs host the densest cluster of ophthalmology residency programs, driving early adoption of femtosecond laser platforms.
Auvergne-Rhône-Alpes
Lyon-based university hospital networks sustain demand for advanced glaucoma surgical devices and diagnostic imaging systems. CNIL data governance frameworks govern cloud-connected retinal screening programs expanding across the region's diabetic patient population. The Lyon-Saint-Étienne corridor supports a growing chain of private ambulatory surgery centers capturing cataract volumes from public hospital networks.
Provence-Alpes-Côte d'Azur
Private ophthalmology clinic chains in Marseille and Nice negotiate directly with manufacturers for streamlined surgical platforms, bypassing traditional hospital supply chains. HAS reimbursement tariff reviews create periodic windows for premium IOL technologies to secure favorable coverage in this high-margin outpatient market. The Côte d'Azur's aging demographic profile sustains above-average cataract procedure density per capita.
Occitanie
Toulouse and Montpellier anchor distributed surgical capacity serving underscreened rural populations for diabetic retinopathy. Mobile diagnostic units equipped with portable OCT systems extend reach into Pyrenees-adjacent territories lacking permanent ophthalmology infrastructure. Regional health agencies here fragment procurement authority away from the centralized AP-HP model dominant in Paris.
Hauts-de-France
Lille's university hospital network maintains secondary-tier demand for spectral-domain OCT platforms as newer swept-source systems concentrate in Paris and Lyon. Cross-border patient flows from Belgium influence equipment specifications at clinics near the frontier. The region's industrial optics heritage supports specialized contract manufacturers serving domestic diagnostic device assembly.
France Ophthalmic Devices Market Competitive Landscape
Player mix skews toward diversified multinational health conglomerates with dedicated ophthalmology divisions. Market structure concentrates around three to four integrated suppliers controlling implantable lens, surgical platform, and diagnostic imaging segments simultaneously. Strategic archetypes split between vertically integrated optical conglomerates, precision surgical instrument specialists, and diagnostic imaging technology developers. Competitive moves emphasize M&A consolidation of niche IOL technologies and strategic partnerships with ambulatory surgery center chains.
Among the diversified multinational tier, EssilorLuxottica SA exemplifies vertical integration across spectacle lens, contact lens, and retail optical distribution. Alcon Inc. and Carl Zeiss Meditec AG occupy positions spanning surgical instrumentation and diagnostic platforms. These three anchors represent distinct strategic vectors: optical supply chain control, surgical consumable recurring revenue, and premium imaging technology premiumization.
| Leading Market Players |
|---|
| EssilorLuxottica SA |
| Alcon Inc. |
| Carl Zeiss Meditec AG |
| Johnson & Johnson Vision Care |
| Topcon Corporation |
| Bausch Health Companies Inc. |
| Hoya Corporation |
| HAAG-Streit Group |
| Nidek Co. Ltd |
| Others |
Supply & Pricing Matrix
Swept-source optical coherence tomography displacing spectral-domain platforms concentrates procurement power in Paris and Lyon teaching hospitals while compressing margins for mid-tier diagnostic equipment elsewhere. This substitution dynamic simultaneously reshapes supply geography toward German precision optics manufacturers and elevates pricing premiums for sub-3-micrometer resolution systems serving academic networks.
Pricing Analysis
Technology-generation pricing gaps separate swept-source OCT platforms commanding premium positioning from spectral-domain units facing depreciation pressure and next-generation femtosecond cataract systems awaiting reimbursement clarity. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking tier under EU MDR, brand equity in phacoemulsification platforms, and bundled service contracts. Pricing pressure stems from ambulatory surgery center procurement consolidation demanding streamlined platform economics. Independent ophthalmology chains in Provence-Alpes-Côte d'Azur exhibit highest price sensitivity; Île-de-France teaching hospitals remain least sensitive due to HAS reimbursement favoring premium IOL technologies.
Supply Chain Analysis
Just-in-time inventory strategies dominate phacoemulsification consumables given single-use tubing and irrigation set requirements, while strategic stockpiling of optical-grade polymers buffers polymer supply volatility affecting per-procedure economics. Manufacturing concentrates in Germany for precision surgical platforms, Switzerland for optical components, and Ireland for intraocular lens fabrication. Raw material dependencies include biocompatible acrylic polymers, high-purity silicone for optics, and rare-earth elements for laser systems. Single-source vulnerability concentrates in swept-source laser componentry from specialized German suppliers. Distribution runs through hospital purchasing consortia in Île-de-France and direct manufacturer negotiations with ambulatory chains in southern regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR regulatory capacity constraints have created a bottleneck where notified body audit slots and ISO 13485 certification timelines outstrip available specialist regulatory affairs talent, compressing commercialization windows for novel implantable devices.
For Market Incumbents: Consolidate regulatory affairs capacity through dedicated MDR transition teams and captive notified body relationships to defend certificate renewal timelines for legacy intraocular lenses against emerging entrants lacking compliance infrastructure. Acquire niche toric and multifocal IOL technologies to fill premium portfolio gaps ahead of HAS reimbursement reviews. Channel control through exclusive ambulatory surgery center partnerships in Occitanie and Provence-Alpes-Côte d'Azur offsets margin pressure from polymer cost inflation in phacoemulsification consumables. For New Entrants and Emerging Players: Cloud-connected diagnostic platforms with CNIL-compliant data architectures represent a service-layer gap where incumbents under-serve provincial clinic networks lacking hospital information system integration expertise. Mobile OCT units for diabetic retinopathy screening in Occitanie's rural Pyrenees-adjacent territories offer the most penetrable geography given permanent ophthalmology infrastructure shortages. Go-to-market angle should emphasize turnkey deployment with embedded technician training rather than equipment-only sales. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed ophthalmology clinic chains in southern France seeking platform standardization across distributed ambulatory networks. Long-term viability hinges on reimbursement durability through HAS periodic reviews and MDR certificate maintenance capacity rather than technology differentiation alone. Acquisition targets should demonstrate installed base density in underpenetrated regions beyond Île-de-France. Signal to watch is femtosecond cataract surgery platform utilization rates crossing threshold for manufacturer financing program eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR transition timelines compress commercialization windows for Class III implantable lenses requiring ANSM scrutiny. |
| Hospital System Partnership | AP-HP procurement concentration in Île-de-France creates anchor demand for premium diagnostic and surgical platforms. |
| Software Companion Development | CNIL-compliant cloud architectures for OCT image storage enable remote diabetic retinopathy screening in underserved regions. |
| Reimbursement Strategy | HAS tariff optimization for premium IOL technologies determines commercial viability in high-volume cataract workflows. |
| Backward Integration | In-house polymer compounding for intraocular lenses buffers supply volatility and protects per-procedure margins. |
Research Methodology
Operator-level perspectives from ophthalmology department heads, ambulatory surgery center medical directors, biomedical equipment procurement managers, and ANSM regulatory affairs specialists anchored the qualitative base for this study. Primary interview findings combined with secondary validation from hospital procurement databases, GPO contracts, CE marking notifications under EU MDR, and HAS reimbursement tariff documentation. Bottom-up equipment shipment analysis and top-down healthcare expenditure triangulation cross-verified market sizing across product and regional segments.
Sensitivity analysis tested forecast robustness against notified body capacity constraints, polymer supply volatility, and femtosecond platform adoption trajectories across the analysis window. Segmentation dimensions modeled include product type, application, end user, and technology generation with regional procurement authority fragmentation as an ophthalmology-specific overlay. CAGRs derived from equipment replacement cycles, screening protocol expansion rates, and surgical volume migration patterns toward outpatient settings.
Underlying assumptions cover EU MDR transition completion, HAS reimbursement stability for premium IOL tiers, and polymer supply normalization, with deviation risk concentrated in notified body audit backlogs extending beyond current timelines. Forecasts reflect these conditions without scenario-weighting. Revision becomes warranted when femtosecond cataract surgery platform reimbursement crosses threshold for favorable coverage or when ANSM enforcement intensity shifts materially from current baselines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Bathroom and Toilet Assist Devices Market
Medical Devices
Bone Fixation Plates Market
Medical Devices
Battery-Operated Lactate Meter Market
Medical Devices
DLIF and XLIF Implants Market
Medical Devices
Medical Device Manufacturing Outsourcing Market
Medical Devices
Condylar Plate Fixation System Market
Medical Devices
Intra-Abdominal Pressure Measurement Devices (IPMD) Market
Medical Devices
North America Renal Denervation Devices Market
Medical Devices
Global Vaginal Sling Market
Medical Devices
Bariatric Beds Market
Medical Devices
Embolization Coils Market
Medical Devices
Brazil Aesthetic Devices Market
Medical Devices
Pelvic Floor Electrical Stimulation Devices Market
Medical Devices
MRI Safe Defibrillator Market
Medical Devices
Submucosal Injections Market
Medical Devices
Drug and Gene Delivery Devices Market