
 India Pharmaceutical Market | 2026-2036
India Pharmaceutical Market Size, Share, and Industry Trends Forecast 2026-2036
India Pharmaceutical Market Outlook
Active pharmaceutical ingredient production in Gujarat and Telangana is expanding, with dedicated bulk drug parks receiving central government backing under the PLI scheme. Sun Pharmaceutical Industries leverages backward integration into complex generics to sustain margin resilience across regulated export markets. Dr. Reddy's Laboratories anchors its competitive position through biosimilar development programs targeting oncology and immunology segments. Cipla Limited differentiates via respiratory delivery platforms and deep channel control across emerging markets.
India pharmaceuticals encompass chemically synthesized or biologically derived medicinal products formulated for therapeutic, prophylactic, or diagnostic use, with specifications governed by pharmacopeial standards for purity, potency, and bioequivalence. These products serve industrial purposes spanning chronic disease management, acute care intervention, and preventive healthcare delivery across institutional and retail channels. Generic drugs occupy the dominant volume position, while biosimilars represent the fastest-expanding margin pool as patent cliffs open reference biologic pathways. Oncology and cardiovascular therapy areas concentrate reimbursement attention and specialist prescriber access, creating structural advantages for firms with dedicated therapeutic franchises.
CDSCO mandates bioequivalence documentation and manufacturing facility inspections under Schedule M and WHO-GMP frameworks, while the PLI scheme for active pharmaceutical ingredients conditions subsidy disbursement on domestic value addition thresholds. FSSAI parallel oversight of nutraceutical-pharma hybrids creates dual compliance exposure for OTC product portfolios. Stakeholders must monitor evolving CDSCO data integrity requirements and state-level environmental clearance timelines for greenfield capacity.
Market Dynamics
CDSCO's accelerated approval pathways for novel therapies are compressing product registration timelines, while the PLI scheme for active pharmaceutical ingredients is redrawing domestic manufacturing economics across Maharashtra, Telangana, and Gujarat.
Growth Catalysts
- PLI scheme for bulk drugs:Central government subsidy disbursement tied to domestic value addition thresholds is incentivizing greenfield API capacity in dedicated parks.
- Domestic hospital procurement expansion:Institutional buying consolidation is creating volume anchors for local formulation manufacturers serving acute care and chronic disease segments.
- Patent cliff openings in biologics:Expiring reference product protections are unlocking biosimilar development pathways across oncology and immunology therapy areas.
Market Restraints
- Import dependence for KSMs:Key starting material supply chains remain concentrated in Chinese chemical intermediates, exposing margin volatility to cross-border tariff and logistics disruptions.
- Environmental clearance timelines:State-level pollution control board approvals for greenfield bulk drug facilities in Andhra Pradesh and Gujarat extend project commissioning schedules.
- WHO-GMP inspection backlogs:CDSCO's facility certification queue creates bottlenecks for export-oriented manufacturers seeking regulated market access.
Strategic Opportunities
- Eastern India manufacturing corridors:Underdeveloped API and formulation capacity in Odisha and West Bengal offers land and labor cost arbitrage for PLI scheme beneficiaries.
- Respiratory delivery platform extension:Metered-dose and dry-powder inhaler technology convergence with connected device ecosystems opens chronic obstructive pulmonary disease management segments.
- FSSAI nutraceutical-pharma hybrid channel:Dual regulatory overlap creates OTC shelf space expansion for preventive healthcare portfolios targeting urban retail pharmacy networks.
Industry Challenges
- Data integrity compliance:CDSCO's evolving ALCOA+ documentation standards for manufacturing records demand legacy facility upgrades and staff retraining investments.
- Specialist prescriber access concentration:Oncology and cardiovascular therapy areas face restricted hospital formulary entry controlled by centralized pharmacy and therapeutics committees.
- Biologics cold chain infrastructure:Biosimilar distribution requires temperature-controlled logistics networks that remain fragmented beyond tier-one cities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Pharmaceutical Market |
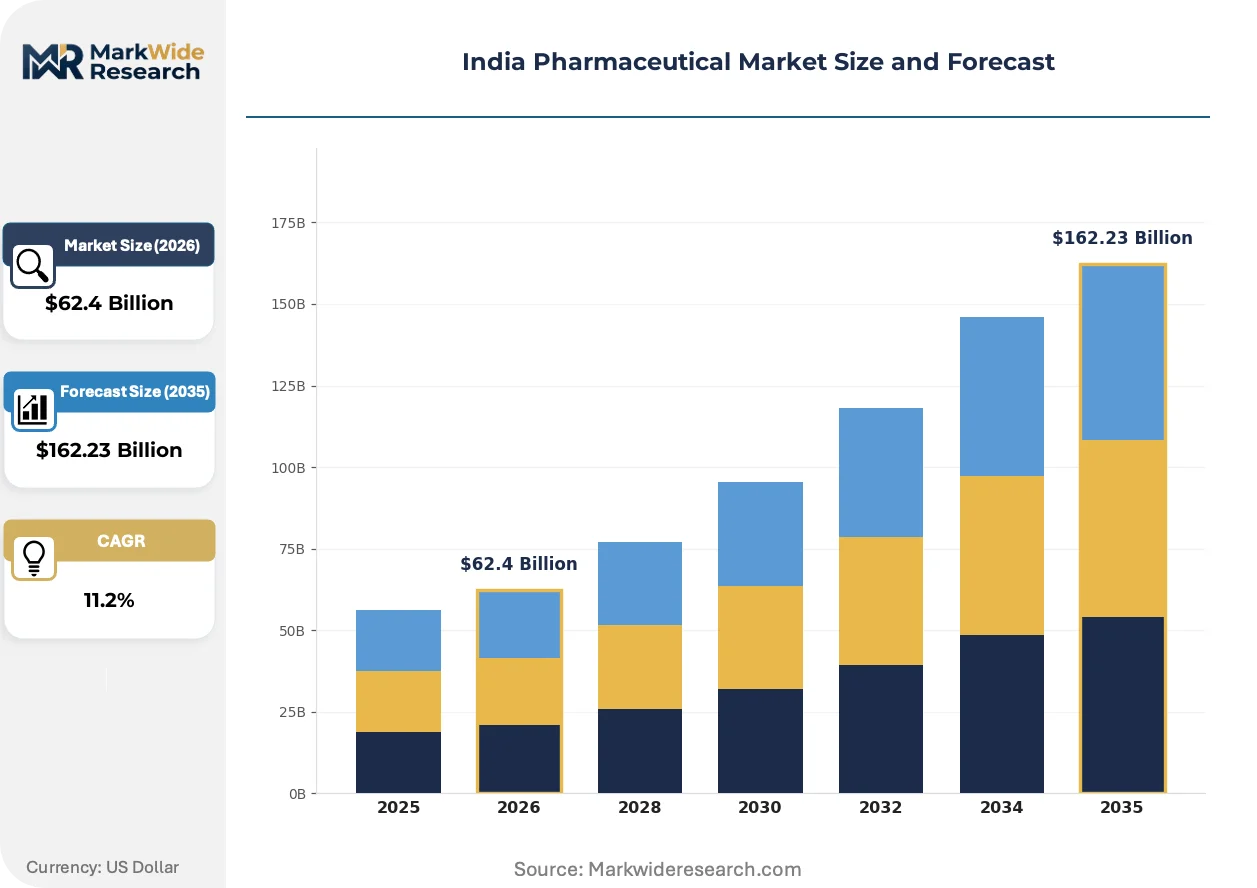
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $162.23 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Generic Drugs, OTC Products, Biosimilars, Branded Medicines End User: Hospitals, Retail Pharmacies, Clinics, Distributors Therapy Area: Cardiovascular, Oncology, Neurology, Infectious Diseases Delivery Mode: Injectables, Oral Tablets, Topical, Inhalers |
| Companies Covered | Sun Pharmaceutical Industries Ltd, Cipla Limited, Dr. Reddy’s Laboratories Ltd, Divi's Laboratories Limited, Zydus Lifesciences, Torrent Pharmaceuticals Ltd, Lupin Limited, Aurobindo Pharma Limited, Alkem Laboratories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Pharmaceutical Market Strategic Shifts
Continuous manufacturing platforms and digital batch records are displacing traditional pharmaceutical production economics, while CDSCO's quality management system mandates are accelerating technology adoption timelines across domestic facilities.
Continuous processing technology is decentralizing active pharmaceutical ingredient production from large-batch facilities to modular, smaller-footprint units. Mid-size formulation manufacturers in Hyderabad and Vadodara are piloting these systems to reduce solvent waste and compression cycle times. The shift is enabling distributed manufacturing networks that shorten supply chains to domestic hospital procurement hubs.
CDSCO's revised Schedule M guidelines for good manufacturing practices now mandate electronic batch recording and environmental monitoring systems for all new facility approvals. Domestic manufacturers seeking export registrations must demonstrate real-time data capture capabilities during WHO-GMP inspections. The requirement is compressing technology upgrade timelines for legacy plants in Mumbai and Chennai industrial clusters.
Hospital pharmacy consolidation is compressing supplier bases as centralized procurement committees replace individual physician prescribing autonomy. Institutional buyers in Delhi and Bengaluru are implementing tender-based annual contracts that favor manufacturers with dedicated therapeutic franchises and local inventory stocking. The shift is visible across oncology injectables and cardiovascular fixed-dose combinations where volume commitments determine formulary placement.
India Pharmaceutical Market Segmentation
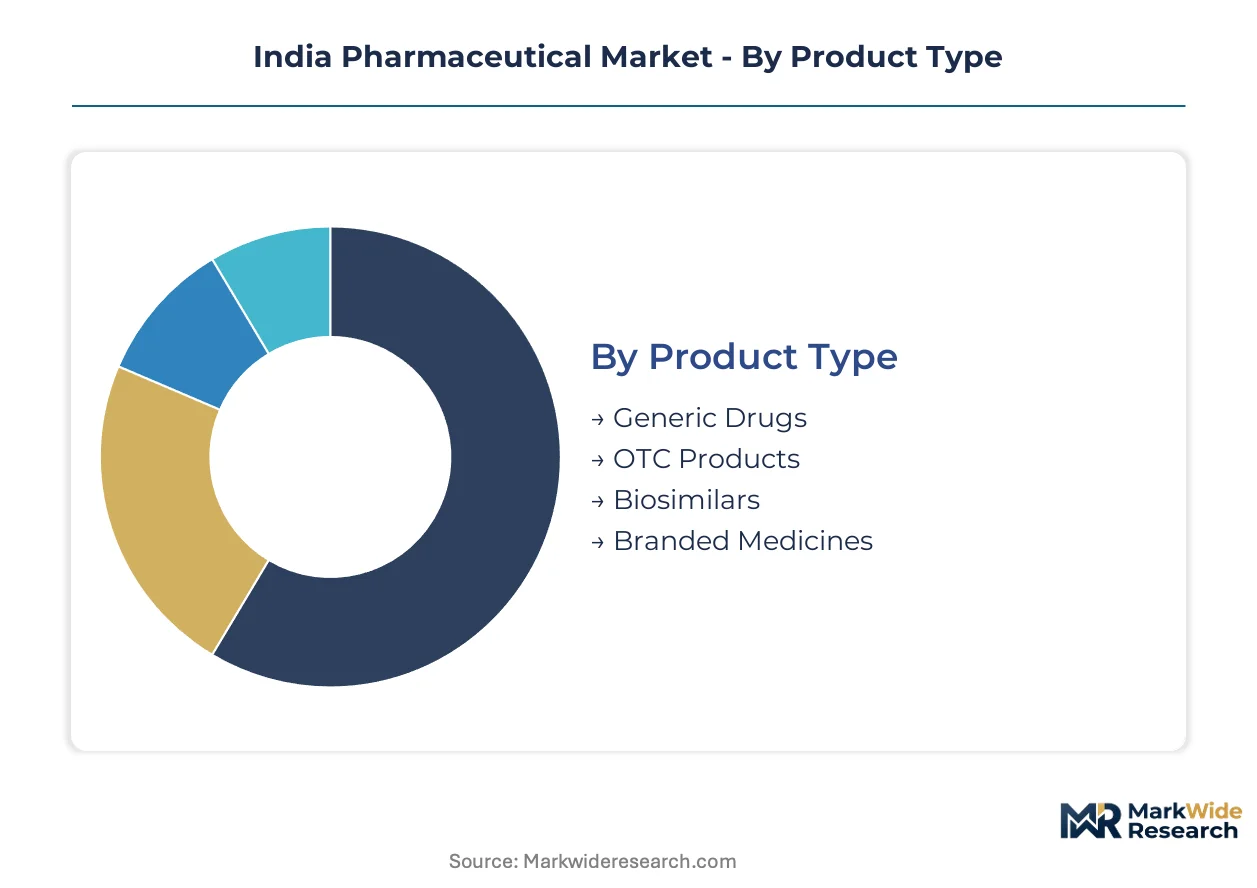
Segmentation reveals how procurement authority and reimbursement pathways concentrate demand across India's pharmaceutical value chain. Understanding these divides exposes where margin pools accumulate and which access channels reward specialized capabilities.
Product Type:
Cost tier separates manufacturers serving price-sensitive institutional tenders from those capturing premium biosimilar margins.
- Generic Drugs:Chemically equivalent formulations produced after patent expiry dominate hospital procurement volumes. Maharashtra and Telangana manufacturers leverage PLI scheme subsidies to undercut import prices in government tenders.
- Biosimilars:Recombinant protein therapies referencing off-patent biologics command the steepest margin expansion. CDSCO's abbreviated approval pathways for oncology and immunology biosimilars are accelerating developer pipelines.
- OTC Products:Self-medication categories span analgesics, antacids, and cough-cold combinations distributed through retail pharmacy networks.
- Branded Medicines:Patent-protected originator compounds retain specialist prescriber loyalty in metro hospital formularies.
Generic drugs lead volumes today; biosimilars are climbing the fastest.
End User:
Customer type determines whether relationships hinge on tender compliance, formulary access, or last-mile distribution density.
- Hospitals:Centralized pharmacy and therapeutics committees in Delhi and Bengaluru consolidate annual contracts for oncology injectables and cardiovascular combinations. Inventory stocking commitments determine supplier selection.
- Retail Pharmacies:Fragmented independent and chain outlets across tier-two cities drive OTC and chronic disease prescription refill volumes.
- Clinics:Specialist outpatient centers in Mumbai and Chennai concentrate high-value biologic prescribing.
- Distributors:Stockist networks bridge manufacturer warehouses to pharmacy shelves, with credit terms and cold chain capabilities as differentiators.
Hospitals anchor institutional procurement; retail pharmacies capture the greatest prescription volume expansion.
Therapy Area:
Application urgency shapes whether reimbursement coverage, specialist density, or preventive screening programs drive demand.
- Cardiovascular:Hypertension and dyslipidemia fixed-dose combinations dominate chronic prescription volumes. State government insurance schemes in Tamil Nadu and Kerala expand patient access.
- Oncology:Cytotoxic injectables and targeted small molecules concentrate in tertiary care centers. CDSCO's accelerated approval pathways for novel therapies are compressing registration timelines for domestic developers.
- Neurology:Epilepsy and Parkinson's disease formulations require long-term adherence support through patient assistance programs.
- Infectious Diseases:Antibiotic and antiviral demand fluctuates with seasonal disease burden and hospital-acquired infection protocols.
Cardiovascular therapies lead prescription volumes today; oncology is expanding most quickly on biosimilar penetration.
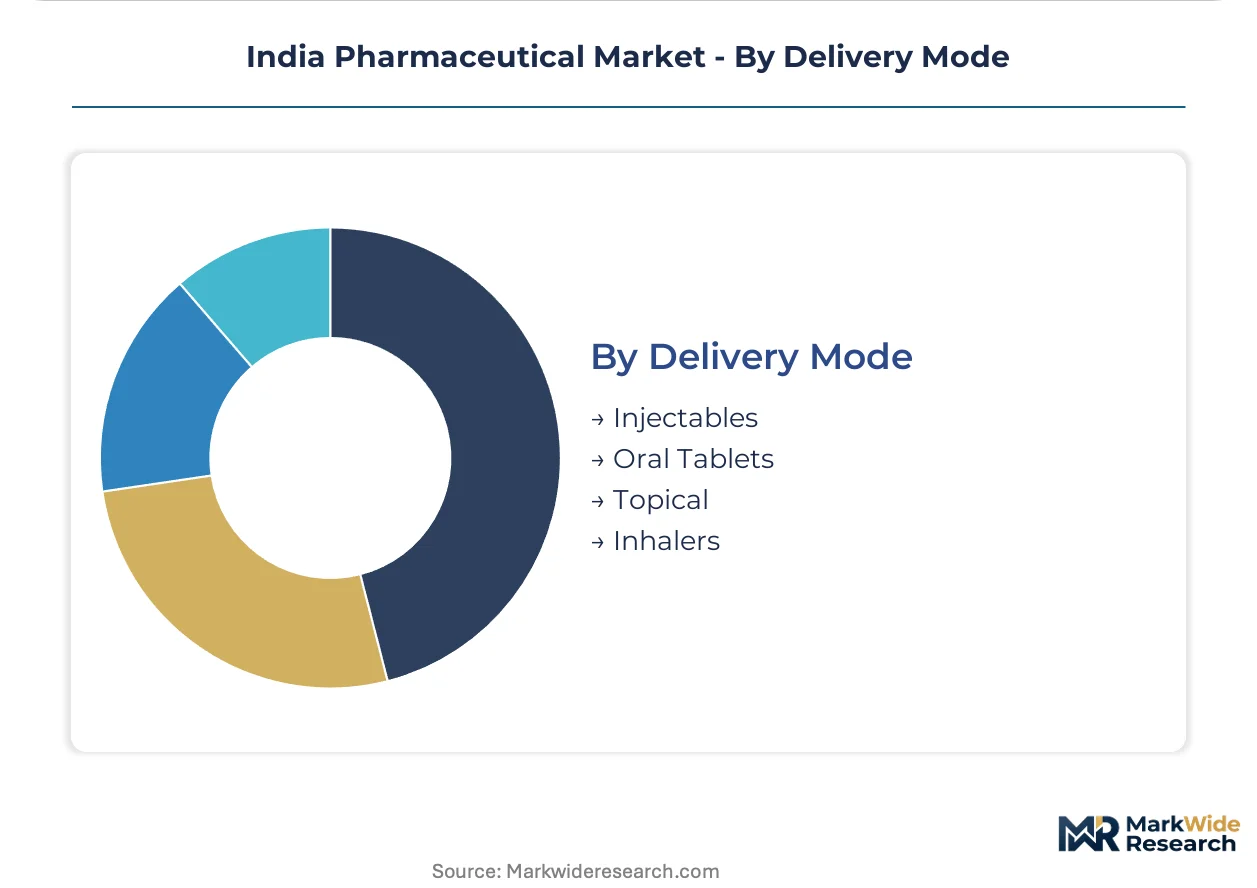
Delivery Mode:
Supply concentration in manufacturing technology determines which modes achieve cost leadership versus premium positioning.
- Oral Tablets:Solid dosage forms dominate volume manufacturing in Hyderabad and Vadodara clusters. Continuous processing technology adoption is reducing solvent waste and compression cycle times.
- Injectables:Sterile fill-finish capabilities for oncology and biologics command facility investment premiums. WHO-GMP inspection backlogs create bottlenecks for export-oriented manufacturers.
- Inhalers:Metered-dose and dry-powder devices require respiratory delivery platform expertise. Connected device ecosystem integration is opening chronic obstructive pulmonary disease management segments.
- Topical:Creams, ointments, and transdermal patches serve dermatology and pain management with lower regulatory barriers.
Oral tablets lead manufacturing volumes today; inhalers are gaining share fastest on respiratory platform investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost arbitrage is redirecting pharmaceutical production toward states with streamlined environmental clearances and PLI scheme disbursement efficiency. CDSCO's centralized approval frameworks reduce compliance friction relative to fragmented state-level oversight elsewhere. This geographic sorting concentrates API and formulation capacity in jurisdictions that balance subsidy access with infrastructure maturity.
Maharashtra
Hospital procurement consolidation in Mumbai and Pune drives demand for oncology injectables and cardiovascular fixed-dose combinations. CDSCO's WHO-GMP inspection protocols govern export-oriented facilities in the Baddi-Nalagarh corridor spillover. The Mumbai-Pune industrial belt hosts sterile fill-finish operations serving institutional tenders across western India.
Telangana
Biosimilar development programs targeting immunology segments concentrate specialist prescriber access in Hyderabad's tertiary care network. The PLI scheme for bulk drugs channels central subsidy disbursement into dedicated API parks near the city. Genome Valley anchors recombinant protein manufacturing with cold chain infrastructure extending to tier-two distribution nodes.
Gujarat
Ankleshwar and Vadodara clusters leverage continuous processing technology adoption to reduce solvent waste in oral tablet manufacturing. State pollution control board timelines for greenfield approvals remain shorter than Andhra Pradesh equivalents. Dahej and Jhagadia industrial zones concentrate KSM-to-API backward integration under PLI scheme thresholds.
Karnataka
Bengaluru's hospital pharmacy and therapeutics committees implement tender-based annual contracts favoring manufacturers with local inventory stocking. CDSCO's accelerated approval pathways for novel therapies compress registration timelines for domestic developers headquartered in the city. The Electronic City corridor hosts digital batch record system providers serving nationwide GMP upgrade cycles.
Tamil Nadu
State government insurance schemes in Chennai and Coimbatore expand patient access to chronic disease formulations. FSSAI parallel oversight of nutraceutical-pharma hybrids creates dual compliance exposure for OTC portfolios targeting urban retail networks. The Sriperumbudur-Oragadam belt attracts formulation packaging investments serving Southeast Asian export markets.
India Pharmaceutical Market Competitive Environment
Maharashtra and Gujarat producers anchor the scale-driven tier; Telangana specialists hold biosimilar development capabilities. The market structure tiers across integrated API-formulation conglomerates, pure-play bulk drug manufacturers, and respiratory delivery platform owners. Strategic archetypes include backward-integrated generic exporters, biologics developers with cold chain networks, and OTC brand builders with pharmacy channel control. Dominant competitive moves encompass greenfield API capacity expansion under PLI subsidies and hospital formulary access consolidation through inventory stocking commitments.
Within the integrated pharmaceutical tier, Sun Pharmaceutical Industries Ltd, Dr. Reddy's Laboratories Ltd, and Cipla Limited exemplify distinct strategic positioning. Sun Pharmaceutical Industries Ltd represents backward integration into complex generics for regulated export markets. Dr. Reddy's Laboratories Ltd occupies a position anchored to biosimilar development programs across oncology and immunology segments. Cipla Limited exemplifies respiratory delivery platform differentiation and emerging market channel depth. These three entities collectively illustrate how geographic concentration in Maharashtra, Telangana, and Gujarat translates into divergent capability specializations.
| Leading Market Players |
|---|
| Sun Pharmaceutical Industries Ltd |
| Cipla Limited |
| Dr. Reddy's Laboratories Ltd |
| Divi's Laboratories Limited |
| Zydus Lifesciences |
| Torrent Pharmaceuticals Ltd |
| Lupin Limited |
| Aurobindo Pharma Limited |
| Alkem Laboratories |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap manufacturers with multi-generational control over Maharashtra and Gujarat production clusters anchor supply discipline through captive API capacity, translating into pricing power that resists tender-driven erosion in institutional procurement channels. CDSCO's PLI scheme disbursement mechanics reward domestic value addition thresholds, reinforcing margin buffers against Chinese KSM import volatility.
Pricing Analysis
Distributor margin compression in government hospital tenders now defines the dominant pricing structure, with three-tier pricing stratification across premium biosimilars, standard generics, and economy institutional packs. Price differentiation hinges on WHO-GMP certification tier and volume scale commitments to centralized pharmacy committees. Cost compression in economy-tier oral solids is intensifying because of PLI scheme subsidy competition among Maharashtra and Telangana producers. Retail pharmacy channels show least price sensitivity for respiratory delivery platforms, while government tenders exhibit maximum sensitivity for cardiovascular fixed-dose combinations.
Supply Chain Analysis
Key starting material supply rests on Chinese chemical intermediate producers for antibiotic and oncology API synthesis, with Indian bulk drug parks in Telangana and Gujarat providing partial backward integration relief. Raw material dependencies span fermentation-derived intermediates, petrochemical solvents, and chromatography resins. Single-source vulnerability concentrates in penicillin and cephalosporin KSM streams subject to cross-border tariff disruptions. Distribution runs through stockist networks with credit-term differentiation, bridging manufacturer warehouses to fragmented retail pharmacy outlets across tier-two cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India pharmaceuticals constitute a late-cycle quality story as hospital formulary access consolidates around manufacturers with demonstrated biosimilar development capabilities and cold chain infrastructure. The demand-shift toward premium specifications in oncology and immunology segments rewards firms with specialist prescriber relationships and CDSCO accelerated approval track records.
For Market Incumbents: Hedge against biosimilar margin compression by deepening backward integration into complex generic APIs under PLI scheme thresholds, while securing inventory stocking commitments from Delhi and Bengaluru hospital pharmacy committees. CDSCO's evolving data integrity requirements threaten legacy facility compliance costs; prioritize electronic batch recording upgrades in Mumbai and Chennai clusters to defend WHO-GMP export registrations. For New Entrants and Emerging Players: Direct-to-hospital digital procurement platforms offer the lowest-friction entry vector into institutional tender participation, bypassing entrenched stockist credit relationships. Eastern India manufacturing corridors in Odisha and West Bengal present the most penetrable geography for greenfield API capacity with land and labor cost arbitrage. Target respiratory delivery platform partnerships with connected device ecosystem providers to access chronic obstructive pulmonary disease management segments. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play bulk drug manufacturers lacking formulation forward integration, as PLI scheme subsidies compress return thresholds for standalone API producers. The five-to-ten year viability window favors biologics developers with demonstrated CDSCO approval pathways and cold chain networks extending beyond tier-one cities. Watch CDSCO's WHO-GMP inspection queue clearance rates as the inflection signal for export-oriented capacity utilization recovery.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Accelerated Approval Pathway | Compresses novel therapy registration timelines for oncology and immunology developers. |
| PLI Scheme Capacity Expansion | Central subsidy disbursement anchors greenfield API investment in Telangana bulk drug parks. |
| Backward Integration Program | Captive KSM-to-API production insulates margin volatility from Chinese intermediate supply. |
| Respiratory Platform Extension | Metered-dose inhaler convergence with connected devices opens COPD management segments. |
| Hospital Formulary Consolidation | Inventory stocking commitments secure annual tender contracts in Delhi and Bengaluru institutions. |
Study Parameters
Multiple input streams — primary interviews with drug development executives, regulatory affairs leads, and hospital procurement managers; secondary validation against CDSCO filings, ClinicalTrials.gov records, and formulary databases; plus customs trade data — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured perspective from Maharashtra, Telangana, and Gujarat manufacturing clusters alongside Delhi and Bengaluru institutional buying centers.
Data-stream reconciliation across product type, therapy area, delivery mode, and regional regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume and value buildups, with biosimilar penetration curves and PLI scheme disbursement schedules serving as key pharmaceutical-specific forecast inputs.
The model assumes a particular technology adoption path for continuous manufacturing platforms; alternative pathways for modular distributed production would alter the outlook for solvent waste reduction and compression cycle economics. Forecasts reflect assumptions regarding CDSCO inspection queue clearance rates, environmental approval timelines in Andhra Pradesh and Gujarat, and KSM import tariff stability. A small set of triggers — WHO-GMP certification backlogs, state pollution control board clearance delays, and biologics cold chain fragmentation — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Iron Deficiency Injectables Market
Pharmaceuticals
Global Cholera Vaccines Market
Pharmaceuticals
Czech Republic Pharmaceutical Market
Pharmaceuticals
Narcotic Analgesics Market
Pharmaceuticals
Australia Pharmaceuticals Market
Pharmaceuticals
Amylin Analogs Market
Pharmaceuticals
Global Zika Vaccines Market
Pharmaceuticals
Nefopam Hydrochloride Injection Market
Pharmaceuticals
Wujibaifeng Pills Market
Pharmaceuticals
Asia-Pacific Contraceptives Market
Pharmaceuticals
GLP-1 Receptor Agonist Market
Pharmaceuticals
GCC Generic Injectables Market
Pharmaceuticals
Global Orphan Drugs Market
Pharmaceuticals
Antidiuretic Drugs Market
Pharmaceuticals
Global Diphtheria Vaccine Market
Pharmaceuticals
Motilium Market