
 Osteoarthritis Drugs Market | 2026-2036
Osteoarthritis Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Osteoarthritis Drugs Market Intelligence
The capability gap in developing novel disease-modifying therapies is bifurcating the competitive landscape. Large-scale pharmaceutical firms like Pfizer Inc. leverage extensive clinical trial infrastructure for new biologics. In contrast, companies such as Anika Therapeutics specialize in targeted hyaluronic acid-based treatments. Sanofi competes through a broad portfolio spanning both innovative and established drug classes, addressing multiple patient needs.
Osteoarthritis drugs are pharmacological agents designed to manage symptoms of degenerative joint disease, primarily by reducing inflammation and alleviating pain. These therapies function by inhibiting pathways like cyclooxygenase (COX) or by replenishing synovial fluid viscosity. NSAIDs and analgesics form the foundational treatment volume, while corticosteroids and hyaluronic acid injections represent higher-value interventions. Oral tablets and capsules dominate the market by formulation, though topical creams are gaining traction for localized pain management.
The US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) set stringent requirements for clinical trial data and drug efficacy. These regulatory hurdles shape development timelines and market entry strategies for new therapies, including novel DMOADs. Stakeholder focus now centers on navigating the complex reimbursement pathways for higher-cost biologic and cell-based therapies.
Market Dynamics
The central dynamic is the collision between escalating demand from aging global populations and the formidable scientific and financial barriers to developing true disease-modifying osteoarthritis drugs, creating a market defined by this therapeutic gap.
Growth Catalysts
- DMOAD Development:Advances in understanding disease pathophysiology are accelerating the pipeline for disease-modifying osteoarthritis drugs, which target the underlying causes of cartilage degradation rather than just symptoms.
- Aging Demographics:Countries with rapidly aging populations, such as Japan, exhibit concentrated and sustained demand for both symptomatic and advanced osteoarthritis therapies, supporting market volume and value.
- Regulatory Pathways:The FDA's provision for Breakthrough Therapy designation creates an expedited development and review pathway for drugs treating serious conditions with preliminary evidence of substantial improvement.
Market Restraints
- Clinical Trial Failure:The high attrition rate for DMOAD candidates in late-stage clinical trials, particularly Phase III, represents a major financial and scientific impediment to innovation.
- Stringent Endpoints:Regulatory bodies like the EMA require developers to demonstrate not just symptomatic relief but structural joint improvement, a notoriously difficult clinical endpoint to achieve.
- Generic Competition:The widespread availability and low cost of generic nonsteroidal anti-inflammatory drugs creates significant pricing pressure and limits the market for incrementally innovative but higher-priced therapies.
Strategic Opportunities
- Companion Diagnostics:Developing biomarkers to identify patient subsets who will respond best to specific targeted therapies presents an opportunity to improve clinical trial success rates and personalize treatment.
- Targeted Formulations:Long-acting intra-articular injectables offer a pathway to improve patient compliance and provide sustained local drug delivery, bypassing systemic side effects associated with oral medications.
- Geographic Expansion:Markets in Latin America, such as Brazil, represent significant growth potential due to expanding healthcare access, rising disposable incomes, and an increasing elderly population.
Industry Challenges
- Reimbursement Hurdles:Securing favorable reimbursement status from payers and health technology assessment bodies for high-cost biologic therapies requires extensive evidence of long-term cost-effectiveness, a major operational challenge.
- Specialized Talent Gaps:A shortage of experienced clinical researchers and specialized trial sites equipped for long-term musculoskeletal studies can create bottlenecks in the development of novel osteoarthritis treatments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Osteoarthritis Drugs Market |
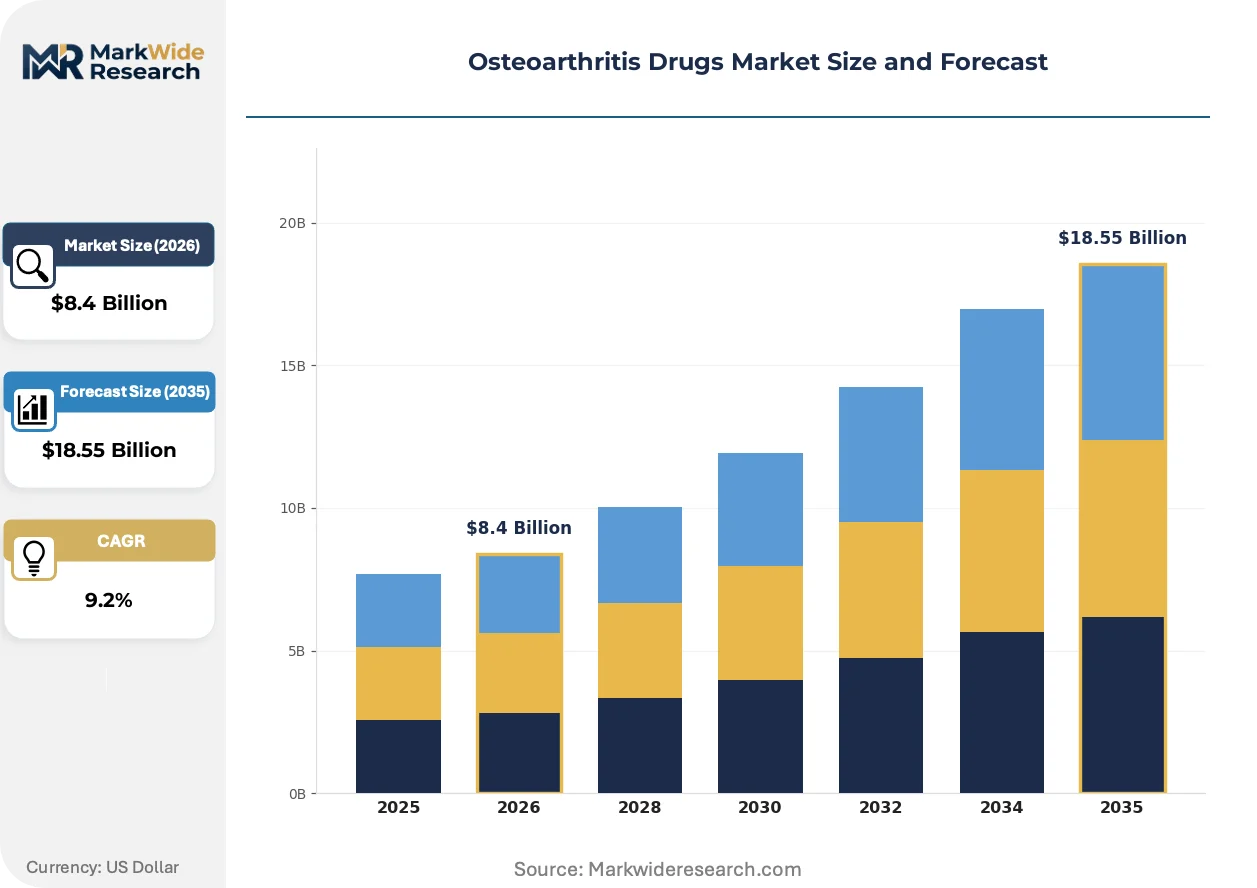
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $18.55 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: NSAIDs, Analgesics, Corticosteroids, Hyaluronic Acid, Glucosamine Formulation: Oral Tablets, Topical Creams, Injections, Capsules, Patches Patient Demographic: Elderly, Middle-aged Adults, Postmenopausal Women, Athletes, Sedentary Individuals Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Clinic Pharmacies, Specialty Stores |
| Companies Covered | Pfizer Inc., Sanofi, GlaxoSmithKline plc, Bayer AG, Novartis AG, Johnson & Johnson, Eli Lilly and Company, Anika Therapeutics, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Osteoarthritis Drugs Market Strategic Shifts & Innovations
The therapeutic paradigm is shifting from chronic symptom management toward disease modification and potential tissue regeneration. This evolution influences research priorities, clinical trial design, and the long-term definition of treatment success for osteoarthritis.
Cell-based therapies, including those using mesenchymal stem cells, aim to regenerate damaged cartilage and modulate the inflammatory joint environment. Adoption is currently focused within specialized research hospitals conducting late-stage clinical trials. This regenerative approach is supplanting the traditional pharmacological model focused solely on chronic symptom management.
Regulatory frameworks like the FDA's Regenerative Medicine Advanced Therapy designation are critical. This status provides intensive guidance and eligibility for accelerated approval for cell and gene therapies that address serious unmet medical needs. The designation most impacts developers of next-generation biologics and regenerative medicines, streamlining their path to market.
A transition toward value-based healthcare models is altering how therapies are procured and reimbursed. The conventional fee-for-service payment system is being challenged by arrangements that tie payment to patient-reported outcomes and long-term efficacy. This shift is most pronounced in integrated health systems within the United States and through HTA evaluations in European countries like Germany.
Osteoarthritis Drugs Market Segmentation
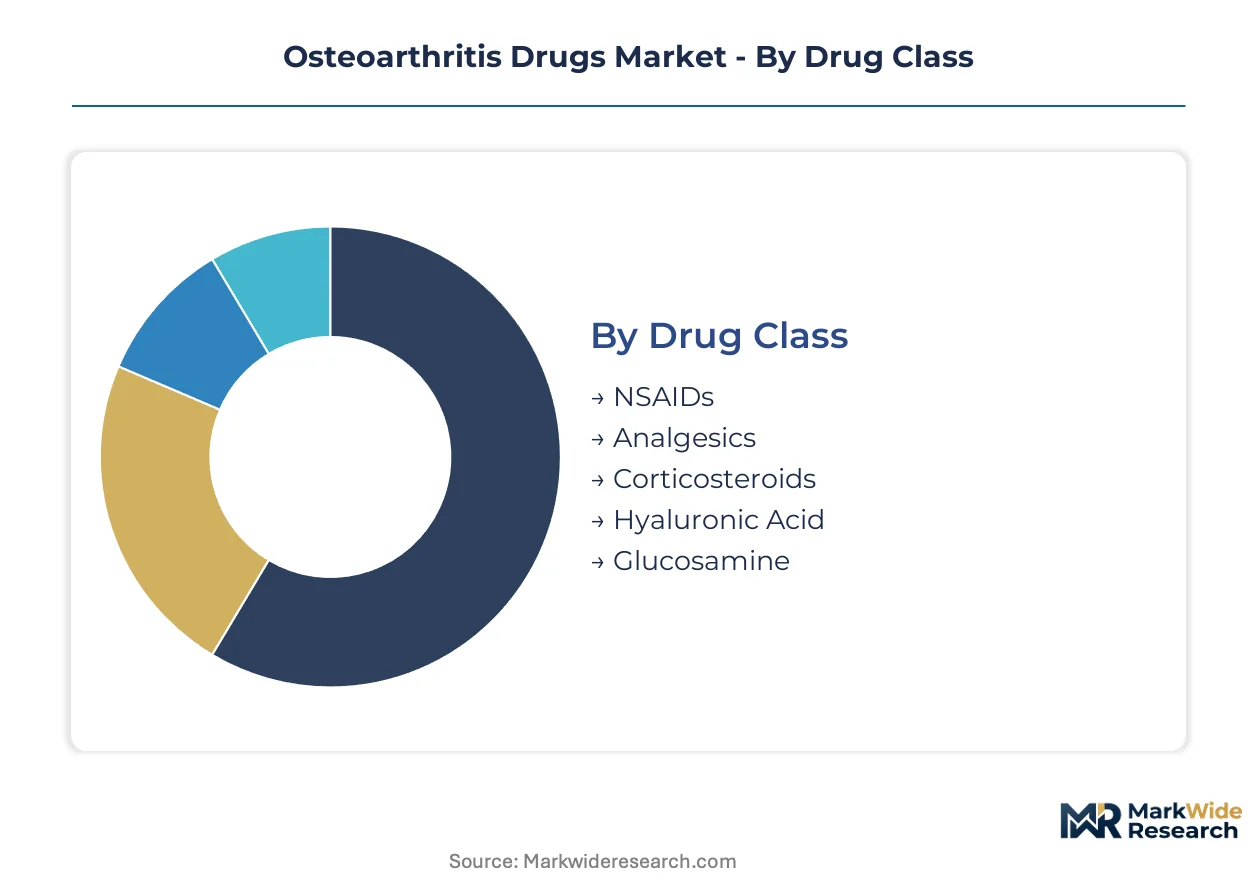
The osteoarthritis drugs market segments into distinct categories, each reflecting varied therapeutic approaches and patient needs. Understanding these divisions is crucial for identifying areas of concentrated demand and emerging treatment modalities. Strategic targeting within these segments allows for optimized product development and market penetration.
Drug Class:
The geographic spread of drug classes varies, with established treatments like NSAIDs holding strong in most regions, while advanced therapies see concentrated adoption in developed markets like Germany and Japan.
- NSAIDs:Nonsteroidal anti-inflammatory drugs reduce pain and inflammation by inhibiting cyclooxygenase enzymes. Demand for these foundational treatments is widespread across all major economies.
- Hyaluronic Acid:These therapies replenish synovial fluid viscosity, providing lubrication and shock absorption. Adoption is concentrated in countries with advanced healthcare infrastructure and higher reimbursement for injections.
- Analgesics:Pain-relieving medications target symptomatic relief without addressing inflammation, forming a core part of early-stage management.
- Corticosteroids:Potent anti-inflammatory agents administered via injection, corticosteroids offer rapid, temporary relief for acute flare-ups.
- Glucosamine:A dietary supplement for joint health, glucosamine's role in disease modification remains under clinical investigation.
NSAIDs command the established base. The steepest expansion runs through Hyaluronic Acid.
Formulation:
Formulations are tailored to specific application requirements, ranging from systemic relief via oral medications to localized treatment through topical creams and intra-articular injections for targeted delivery.
- Oral Tablets:These solid dosage forms offer systemic drug delivery and patient convenience, making them a primary choice for chronic pain management. Demand is consistently high globally due to ease of administration and broad availability.
- Injections:Administered directly into the joint, injections provide localized and often rapid relief, bypassing systemic side effects. Their application is crucial for higher-value interventions like hyaluronic acid and corticosteroids.
- Topical Creams:Applied directly to the skin over affected joints, topical creams deliver localized pain relief with minimal systemic exposure.
- Capsules:Encapsulated oral medications offer an alternative to tablets, often used for specific drug release profiles or patient preference.
- Patches:Transdermal patches deliver medication through the skin, providing sustained local or systemic relief for osteoarthritis symptoms.
The market remains anchored by Oral Tablets, while Injections show significant promise.
Patient Demographic:
Patient demographics drive treatment volume, with the elderly population representing the largest and most consistent demand, while other groups present specialized requirements for osteoarthritis management.
- Elderly:This demographic experiences the highest prevalence of osteoarthritis due to age-related cartilage degeneration. Global demand concentrates here, particularly in aging societies such as Japan and Germany.
- Postmenopausal Women:Hormonal changes post-menopause contribute to increased osteoarthritis risk and progression. Specific therapeutic needs arise from estrogen decline and joint health.
- Middle-aged Adults:This group often experiences early-onset osteoarthritis due to lifestyle factors and prior joint injuries.
- Athletes:High-impact sports and repetitive joint stress increase osteoarthritis risk, requiring targeted preventative and treatment strategies.
- Sedentary Individuals:Lack of physical activity contributes to joint stiffness and muscle weakness, exacerbating osteoarthritis symptoms.
The Elderly represent the largest patient cohort, with Postmenopausal Women demonstrating specific therapeutic needs.
Distribution Channel:
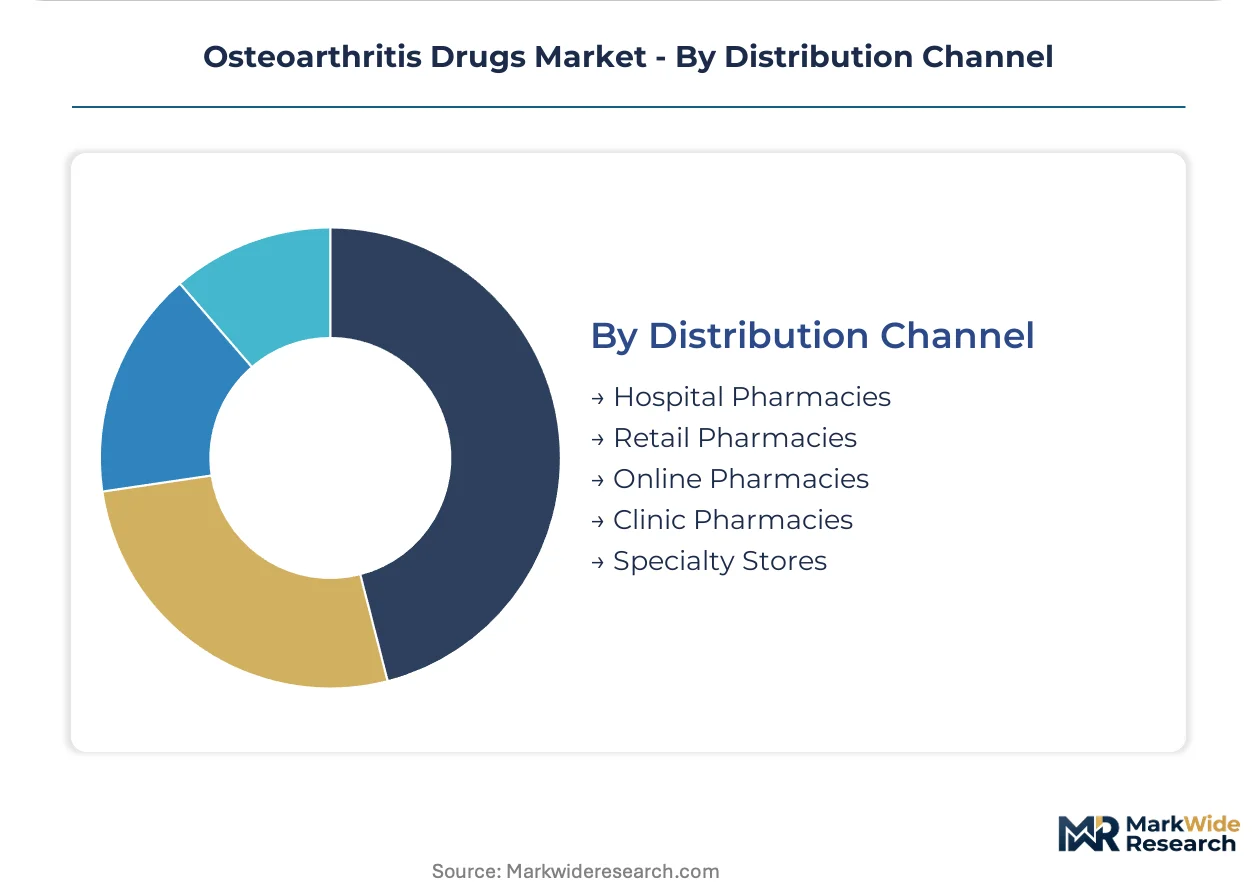
The maturity of distribution channels varies, with established retail and hospital pharmacies forming the backbone, while online platforms represent an emerging, rapidly expanding segment for drug access.
- Retail Pharmacies:These accessible outlets serve as the primary point of sale for over-the-counter and prescription osteoarthritis medications. Their broad geographic reach drives significant market volume.
- Hospital Pharmacies:Integrated within healthcare facilities, these pharmacies manage inpatient medication needs and often dispense specialized injectable therapies. Demand is high for advanced treatments.
- Online Pharmacies:Digital platforms offer convenience and wider product selection, gaining traction for prescription refills and over-the-counter pain management.
- Clinic Pharmacies:Located within clinics, these pharmacies provide immediate access to medications prescribed during patient consultations.
- Specialty Stores:These outlets may focus on specific health products, including certain supplements or medical devices related to joint health.
Traditional channels like Retail Pharmacies maintain dominance, but digital platforms such as Online Pharmacies are gaining influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global osteoarthritis drugs market exhibits varied demand elasticity across regions. Developed economies with robust healthcare systems often show lower price sensitivity for advanced therapies. Conversely, emerging markets prioritize cost-effective symptomatic relief.
United States
The United States market demonstrates strong demand for novel osteoarthritis therapies, driven by an aging population and high healthcare expenditure. The FDA's provision for Breakthrough Therapy designation accelerates the review of new drugs. Boston's biotech hub remains a critical center for the development of next-generation disease-modifying osteoarthritis drugs.
Germany
Germany's market for osteoarthritis drugs benefits from an aging demographic and a well-developed healthcare infrastructure. The EMA requires developers to demonstrate structural joint improvement, influencing clinical trial design. Frankfurt's pharmaceutical cluster focuses on research and development for advanced biologic therapies.
Japan
Japan exhibits concentrated demand for both symptomatic and advanced osteoarthritis therapies due to its rapidly aging population. The PMDA ensures rigorous evaluation of new drug candidates before market entry. Osaka's life science park is a hub for regenerative medicine research, including cell-based osteoarthritis treatments.
Brazil
Brazil presents significant growth potential for osteoarthritis drugs, fueled by expanding healthcare access and rising disposable incomes. ANVISA establishes strict guidelines for the registration and commercialization of new therapies. São Paulo's medical technology sector sees increasing investment in joint health solutions and localized drug delivery systems.
United Kingdom
United Kingdom's market is shaped by the increasing prevalence of osteoarthritis and a shift towards value-based healthcare models. The MHRA provides regulatory oversight for the approval and monitoring of pharmaceutical products. Cambridge's biomedical campus hosts numerous clinical trials for novel disease-modifying osteoarthritis drugs.
Osteoarthritis Drugs Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the osteoarthritis drugs market. This structure combines large pharmaceutical firms with extensive R&D capabilities and smaller, focused innovators, creating a dynamic competitive environment. Strategic archetypes include diversified pharmaceutical giants, specialized biologics developers, and targeted drug delivery solution providers. Companies frequently engage in strategic partnerships to access novel technologies, expand their geographic reach, and navigate complex regulatory landscapes.
Within the diversified pharmaceutical giants, Pfizer Inc. and Sanofi exemplify broad portfolio strategies, leveraging their extensive clinical trial infrastructure across various drug classes and global markets. Anika Therapeutics, a specialist in targeted hyaluronic acid-based treatments, occupies a distinct position focusing on specific therapeutic modalities and localized delivery. These companies collectively represent the market's dual nature, balancing established symptomatic relief with the pursuit of innovative disease-modifying solutions, reflecting the varied approaches to managing osteoarthritis.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Sanofi |
| GlaxoSmithKline plc |
| Bayer AG |
| Novartis AG |
| Johnson & Johnson |
| Eli Lilly and Company |
| Anika Therapeutics |
| Abbott Laboratories |
| Others |
Cost & Logistics Intelligence
The 18-month lead time for clinical trial data submission underpins the concentrated supply chain for novel DMOADs, enabling premium pricing for breakthrough therapies. This extended development cycle creates significant barriers to market entry, influencing the overall cost structure of advanced osteoarthritis treatments.
Pricing Analysis
The long-term patient adherence to therapy drives the value proposition for novel osteoarthritis drugs. Value-based pricing models are increasingly applied to high-cost biologics, contrasting with the per-unit transactional pricing for generic NSAIDs. Clinical efficacy and regulatory designations like FDA Breakthrough Therapy status drive significant price differentiation. Pricing softness reflects the widespread availability of generic nonsteroidal anti-inflammatory drugs. Payers demonstrate high price sensitivity for advanced therapies, while patients are sensitive to out-of-pocket costs for chronic symptom management.
Supply Chain Analysis
The stringent cold chain requirements for biologic DMOADs create a logistics chokepoint in last-mile delivery. Active pharmaceutical ingredient production for many osteoarthritis drugs draws from India and China. Advanced biologics manufacturing centers on the United States and Europe. Specialized bioreactors and complex chemical precursors are critical inputs. Single-source vulnerability for novel DMOAD components poses a structural risk. Distribution runs through retail pharmacies for oral medications and hospital pharmacies for injectable therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The osteoarthritis drugs market is undergoing a buyer-power shift as health technology assessment bodies consolidate procurement decisions. This consolidation forces manufacturers to demonstrate clear long-term cost-effectiveness for novel therapies.
For Market Incumbents:Compound investment in next-generation disease-modifying osteoarthritis drugs to counter the threat of generic competition for established therapies. Leverage existing extensive clinical trial infrastructure to accelerate biologic development. Pursue strategic partnerships with specialized biotech firms to access novel regenerative medicine platforms. Consolidate market share in high-value segments through portfolio diversification.
For New Entrants and Emerging Players:Breakthrough Therapy designation creates an expedited path for novel DMOADs, allowing new entrants to target unmet needs. Focus on developing targeted intra-articular injectables for localized delivery in early-stage osteoarthritis patients. Identify and commercialize companion diagnostics to personalize treatment selection. A personalized medicine approach offers a potent go-to-market angle against broad-spectrum therapies.
For Investors and Strategic Acquirers:Long-term, this sits as a high-value innovation play because of the significant unmet medical need for disease-modifying therapies. Investors should target specialized DMOAD developers with late-stage pipeline assets and robust clinical data. The successful navigation of reimbursement pathways for novel biologics serves as a critical inflection indicator. Watch for positive Phase III clinical trial readouts for cartilage regeneration therapies.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerate DMOAD development for market leadership in advanced therapies. |
| Regulatory Approval Pathway | Expedite market entry for novel biologics targeting disease modification. |
| Licensing Agreement | Access innovative regenerative medicine technologies for cartilage repair. |
| Manufacturing Scale-Up | Ensure supply for high-demand DMOADs and cell-based treatments. |
| Pipeline Diversification | Mitigate clinical trial failure risks across various drug classes. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary validation. Primary research involved discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists across key geographies. Secondary data sources included FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. This approach enabled comprehensive bottom-up and top-down triangulation.
The forecast period analysis employed a quantitative modeling framework integrating historical data with projected market dynamics. Segmentation dimensions modeled included drug class, formulation, patient demographic, distribution channel, and regional regulatory clusters. Compound annual growth rates were derived through regression analysis and expert consensus. Key industry-specific forecast inputs included disease prevalence rates and DMOAD pipeline progression.
Decision-makers should treat outputs as directional under current regulatory approval timelines and DMOAD clinical trial success rate assumptions; material deviation would warrant model refresh. Unforeseen clinical trial failures or shifts in reimbursement policies represent significant risk factors. Practitioners should keep alternative scenarios live as DMOAD development and payer policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Osteoporosis Drugs Market
Pharmaceuticals
Europe Meglitinide Market
Pharmaceuticals
SGLT2 Inhibitors Market
Pharmaceuticals
Beta Blockers Market
Pharmaceuticals
India Plasma Fractionation Market
Pharmaceuticals
Saudi Arabia Diabetes Drugs Market
Pharmaceuticals
Xerostomia Therapeutics Market
Pharmaceuticals
Global Chickenpox Vaccine Market
Pharmaceuticals
OTC Cough, Cold & Allergy Medicine Market
Pharmaceuticals
3D Printing Drug Market
Pharmaceuticals
North America SGLT2 Inhibitors Market
Pharmaceuticals
Hyperphosphatemia Drugs Market
Pharmaceuticals
Sodium Aescinate Market
Pharmaceuticals
Global Gastroparesis Drug Market
Pharmaceuticals
Azathioprine API Market
Pharmaceuticals
Hypertriglyceridemia Therapeutics Market