
 Global Varicella Vaccine Market | 2026-2036
Global Varicella Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Varicella Vaccine Market Foresight
Asset-light manufacturing partnerships and contract development models are reshaping competitive entry in varicella vaccine production. Merck & Co. leverages decades of live-attenuated expertise to dominate pediatric supply chains across North America. GlaxoSmithKline anchors European distribution through integrated public health tenders. Sanofi specializes in combination formulations that bundle varicella with measles-mumps-rubella coverage, reducing clinic visit burdens.
Varicella vaccine comprises live attenuated Oka-strain varicella-zoster virus preparations formulated to induce cell-mediated immunity against primary infection, typically administered in two-dose regimens at 12-15 months and 4-6 years. The product prevents chickenpox and reduces subsequent herpes zoster incidence by establishing durable VZV-specific T-cell memory. Live attenuated products retain the largest installed manufacturing base and lowest per-dose production costs, though recombinant platforms are gaining traction for immunocompromised populations where contraindications limit live virus use. Combination vaccines capture premium positioning by consolidating antigens into single injections, while monovalent formulations persist in niche settings requiring flexible scheduling.
The FDA's potency testing requirements and EMA's Guideline on Clinical Evaluation of Vaccines shape formulation stability benchmarks and Phase III endpoint design. WHO prequalification standards govern access to UNICEF procurement channels, creating a dual-track compliance burden for manufacturers targeting emerging economies. Stakeholders must monitor mRNA platform migration timelines and evolving national immunization schedule expansions to align capacity investments with demand trajectories.
Market Dynamics
Live-attenuated manufacturing concentration and tightening potency standards from FDA and EMA are compressing supplier margins while accelerating qualification timelines for new entrants seeking WHO prequalification.
Growth Catalysts
- Universal immunization mandates:India's expansion of varicella coverage through public health centers is generating sustained volume commitments from state procurement agencies.
- Combination formulation adoption:Bundled measles-mumps-rubella-varicella schedules reduce clinic visit burdens and improve completion rates in pediatric populations.
- EMA stability guideline harmonization:Standardized potency testing protocols reduce regulatory friction for manufacturers seeking parallel US-European market entry.
Market Restraints
- Live virus cold chain dependence:Attenuated formulations require uninterrupted 2-8°C distribution infrastructure, limiting reach in regions with intermittent electricity.
- Single-source strain lineage:The Oka-strain patent estate concentrates upstream biological material access with legacy Japanese and US holders.
- Recombinant platform cost premiums:Subunit alternatives for immunocompromised populations carry manufacturing costs exceeding live-attenuated benchmarks.
Strategic Opportunities
- Brazilian pediatric program scale-up:ANVISA's expanded immunization schedule creates tender volume for qualified suppliers with local fill-finish partnerships.
- Public-private partnership models:UNICEF procurement channels reward manufacturers achieving WHO prequalification with multi-year offtake guarantees.
- mRNA platform migration:Nucleic acid delivery systems for VZV antigens may bypass live virus manufacturing constraints entirely.
Industry Challenges
- Cell culture specialist scarcity:MRC-5 and WI-38 diploid cell propagation expertise has contracted as biologics manufacturing gravitated toward CHO and HEK293 platforms.
- Stability validation timelines:FDA's accelerated potency degradation testing protocols extend submission-to-approval intervals for new formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Varicella Vaccine Market |
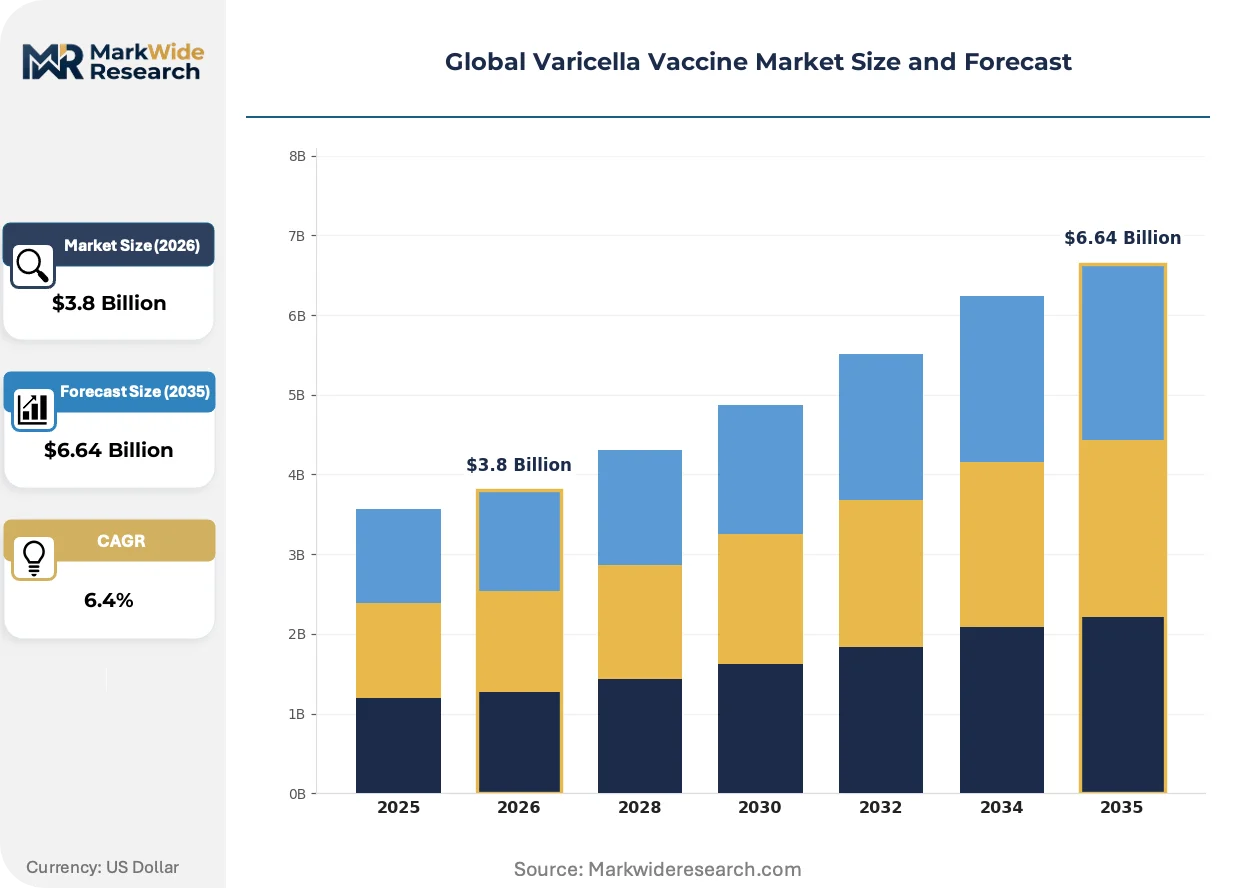
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Attenuated, Recombinant, Combination, Monovalent Application: Children Immunization, Adult Immunization, Healthcare Workers, Travelers, Immunocompromised Patients End User: Hospitals, Clinics, Public Health Centers, Pharmacies, Research Institutes Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Government Supply, Private Clinics |
| Companies Covered | Merck & Co., GlaxoSmithKline, Sanofi, Pfizer, Seqirus, GC Biopharma, Takeda Pharmaceutical Company, Mitsubishi Tanabe Pharma, Bharat Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Varicella Vaccine Market Shifts & Advancements
Digital supply chain tracking and recombinant manufacturing platforms are disrupting traditional live-attenuated production economics while regulatory agencies tighten release specifications.
Recombinant varicella-zoster glycoprotein E subunit vaccines are virtualizing the immunocompromised patient segment that contraindicates live virus exposure. Oncology centers and transplant units in Germany and Japan have adopted these formulations for prophylaxis protocols. The technology is virtualizing the historical trade-off between efficacy and safety that constrained live-attenuated use in specialized populations.
REACH's updated pharmaceutical manufacturing waste protocols are mandating closed-system bioreactor adoption for European production facilities. The regulation eliminates open-vessel cell culture processes for new manufacturing licenses. Contract manufacturers in Switzerland and Ireland are retrofitting capacity to comply with the 2025 enforcement deadline.
Direct government contracting is displacing distributor-mediated procurement in emerging economies. Brazil's Ministry of Health and India's Universal Immunization Programme now negotiate price and volume directly with qualified manufacturers. This pattern concentrates purchasing power with national regulators while compressing intermediary margins in São Paulo and Mumbai distribution channels.
Global Varicella Vaccine Market Segmentation
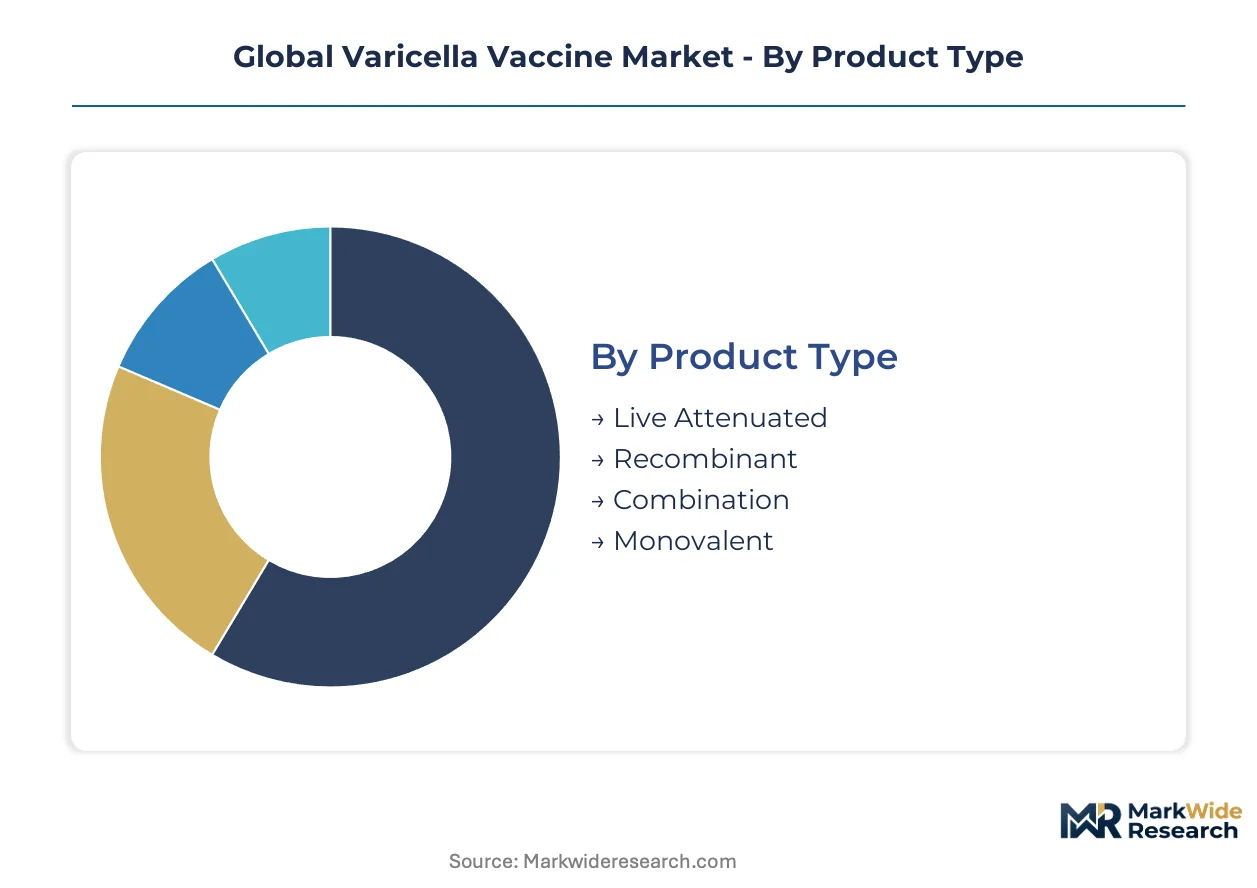
Varicella vaccine demand fragments across formulation technologies, patient risk profiles, and procurement channels. Manufacturers configure production lines and regulatory submissions around these divisions to capture volume commitments from distinct buyer archetypes.
Product Type:
Cost tier determines manufacturing complexity and cold chain infrastructure requirements across formulation categories.
- Live Attenuated:Oka-strain varicella-zoster virus propagated in MRC-5 or WI-38 diploid cell cultures retains the lowest per-dose production economics. Demand concentrates in India's Universal Immunization Programme and Brazil's expanded pediatric schedules where procurement agencies prioritize cost efficiency over storage complexity.
- Combination:Measles-mumps-rubella-varicella antigen bundling reduces clinic visit frequency and improves series completion rates in pediatric populations. European public health tenders in Germany and France specify combination formulations to streamline national immunization logistics.
- Recombinant:Glycoprotein E subunit platforms bypass live virus manufacturing constraints for immunocompromised populations.
- Monovalent:Single-antigen formulations persist in niche settings requiring flexible dosing intervals or contraindication management.
Live Attenuated commands the established base. The steepest expansion runs through Combination.
Application:
Patient risk stratification and age-based immunization schedules create divergent volume and margin profiles.
- Children Immunization:Two-dose regimens at 12-15 months and 4-6 years generate the largest absolute volume. National program scale-ups in India and Brazil concentrate procurement power with ministry-level negotiators seeking multi-year offtake guarantees.
- Immunocompromised Patients:Oncology centers and transplant units in Japan and Germany have adopted recombinant formulations for prophylaxis protocols where live virus exposure is contraindicated. This segment commands premium pricing but requires specialized distribution partnerships with hospital pharmacy networks.
- Adult Immunization:Catch-up vaccination and herpes zoster prevention drives demand in aging populations.
- Healthcare Workers:Occupational exposure protocols mandate seronegative staff completion.
- Travelers:Pre-departure immunization for VZV-naive individuals visiting endemic regions.
Children Immunization anchors procurement volume. Immunocompromised Patients delivers the fastest margin expansion.
End User:
Facility type determines cold chain capability, reimbursement pathway, and regulatory documentation burden.
- Public Health Centers:Government-operated clinics in India and Brazil administer universal immunization program doses through direct manufacturer contracting. These facilities manage 2-8°C storage with generator backup but lack ultra-low capacity.
- Hospitals:Tertiary care centers in Germany and Japan handle immunocompromised patient segments requiring recombinant formulations and specialized adverse event monitoring protocols.
- Clinics:Private pediatric practices in the US and France deliver combination vaccines to insured populations.
- Pharmacies:Retail vaccination sites expanding in US and UK markets.
- Research Institutes:Clinical trial sites and post-marketing surveillance centers.
Public Health Centers dominate volume throughput. Hospitals capture the highest per-dose revenue.
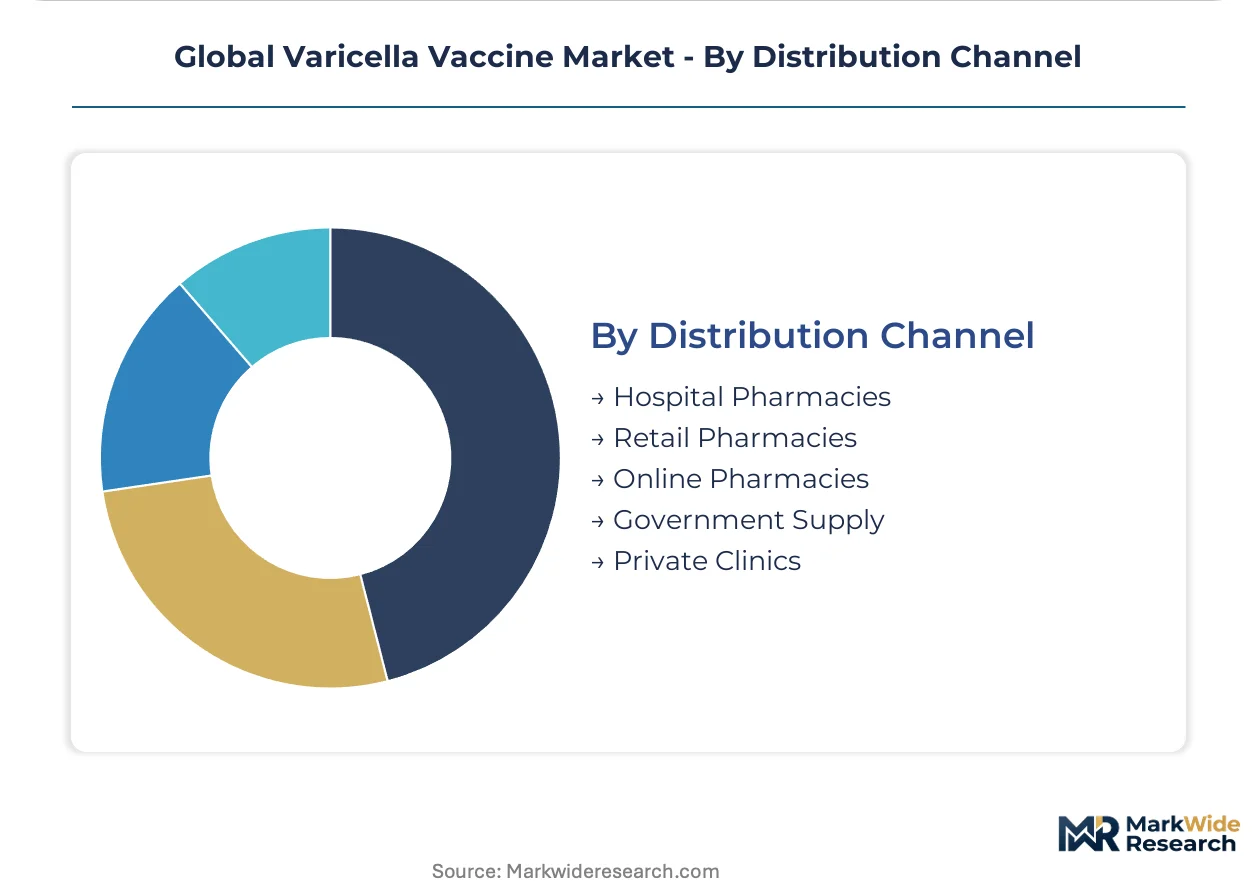
Distribution Channel:
Channel structure reflects procurement centralization trends and intermediary margin compression in emerging economies.
- Government Supply:Direct ministry contracting in India, Brazil, and Saudi Arabia eliminates distributor layers. UNICEF procurement channels reward WHO prequalification with multi-year volume commitments for qualified manufacturers.
- Hospital Pharmacies:Integrated health systems in the US and Germany manage formulary placement and cold chain custody for recombinant and combination products.
- Retail Pharmacies:Community-based vaccination in US, UK, and Australian markets.
- Online Pharmacies:Direct-to-patient delivery expanding in markets with established cold chain logistics.
- Private Clinics:Fee-for-service vaccination in urban centers.
Government Supply concentrates purchasing power. Hospital Pharmacies sustain premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Universal Immunization Programme expansion and Brazil's ANVISA schedule updates are redirecting procurement flows toward direct government contracting. Germany's EMA-aligned stability protocols and Japan's PMDA recombinant adoption create divergent regulatory compliance burdens. The United States maintains FDA potency testing as the benchmark for new formulation approvals.
United States
FDA accelerated potency degradation testing protocols extend submission timelines for new varicella formulations. The CDC's Advisory Committee on Immunization Practices maintains two-dose pediatric scheduling at 12-15 months and 4-6 years. Maryland-based manufacturing clusters near the FDA headquarters district concentrate legacy live-attenuated production expertise.
Germany
REACH pharmaceutical manufacturing waste protocols mandate closed-system bioreactor adoption by 2025. EMA stability guideline harmonization reduces regulatory friction for manufacturers seeking parallel US-European market entry. The Rhine-Main biotech corridor around Frankfurt hosts contract manufacturing organizations retrofitting capacity for compliance.
India
The Universal Immunization Programme generates sustained volume commitments from state procurement agencies scaling varicella coverage. CDSCO tightened cold chain documentation requirements for public health center distribution. Hyderabad and Pune vaccine manufacturing clusters expand fill-finish partnerships to meet tender volumes.
Brazil
ANVISA's expanded pediatric immunization schedule creates tender volume for qualified suppliers with local partnerships. The Ministry of Health negotiates price and volume directly with manufacturers, compressing distributor margins. São Paulo state health secretariats anchor regional distribution infrastructure with generator-backed 2-8°C storage capacity.
Japan
PMDA approval pathways for recombinant varicella-zoster glycoprotein E subunit vaccines serve immunocompromised patient segments. METI funding supports nucleic acid delivery platform research for VZV antigens. The Kansai region's Osaka-based hospital pharmacy networks specialize in oncology and transplant unit prophylaxis protocols.
Global Varicella Vaccine Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent procurement pathways. Consolidation concentrates around legacy live-attenuated manufacturers with WHO prequalification status and established UNICEF supply relationships. Three archetypes dominate: integrated pharmaceutical conglomerates with pediatric vaccine portfolios, contract development specialists with asset-light manufacturing partnerships, and regional biotech firms with localized fill-finish capabilities. Capacity expansion and strategic licensing agreements constitute the primary competitive moves as new entrants seek accelerated qualification timelines.
Within the integrated conglomerate tier, Merck & Co. and GlaxoSmithKline occupy positions defined by decades of live-attenuated expertise and established distribution infrastructure. Sanofi exemplifies the combination formulation specialist archetype, bundling varicella with measles-mumps-rubella coverage to reduce clinic visit burdens. These three anchors represent distinct strategic postures: Merck & Co. with North American pediatric supply chain dominance, GlaxoSmithKline with European public health tender integration, and Sanofi with premium positioning through antigen consolidation.
| Leading Market Players |
|---|
| Merck & Co. |
| GlaxoSmithKline |
| Sanofi |
| Pfizer |
| Seqirus |
| GC Biopharma |
| Takeda Pharmaceutical Company |
| Mitsubishi Tanabe Pharma |
| Bharat Biotech |
| Others |
Supply & Pricing Matrix
Undercapacity in Indian fill-finish facilities drives aggressive tender bidding from qualified manufacturers while compressing margins for European suppliers facing REACH compliance costs. Live-attenuated production economics hinge on this utilization asymmetry between emerging market expansion and mature market regulatory burden.
Pricing Analysis
Certification level (WHO prequalification versus national-only registration) creates the primary spread between contract tiers. Contract-based long-term offtake agreements dominate government procurement in India and Brazil, where volume scale determines price positioning. Cost compression in live-attenuated formulations is intensifying because MRC-5 cell culture specialist scarcity elevates production premiums. Public health centers exhibit highest price sensitivity; hospital pharmacies for immunocompromised recombinant segments show lowest.
Supply Chain Analysis
Extended payment terms from Brazilian state health secretariats and supply-chain finance facilities through UNICEF channels shape working capital requirements for qualified suppliers. Manufacturing concentrates in India, the United States, and Belgium for legacy live-attenuated capacity. Oka-strain viral seeds and MRC-5 diploid cell banks constitute critical biological inputs. Single-source strain lineage creates vulnerability to patent estate enforcement. Distribution runs through direct government contracting in emerging economies and hospital pharmacy networks in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. WHO prequalification timelines and FDA potency validation protocols create switching costs that protect incumbent positions against rapid displacement.
For Market Incumbents: Pre-empt recombinant platform migration by securing nucleic acid delivery partnerships before mRNA VZV candidates advance. Lock in MRC-5 cell culture specialist talent pools through captive training programs. Capacity addition in Hyderabad and Pune fortifies position against emerging Indian contract manufacturers seeking accelerated WHO prequalification. For New Entrants and Emerging Players: Immunocompromised patient segments in German oncology centers represent the most penetrable entry point for recombinant specialists lacking live-attenuated heritage. Brazilian state tender participation through local fill-finish joint ventures offers volume access without full manufacturing qualification. Partner with established CDMOs for EMA stability protocol compliance rather than greenfield facility investment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among WHO-prequalified manufacturers with UNICEF multi-year offtake guarantees. Five-to-ten-year viability favors contract development specialists with asset-light models and regulatory affairs depth over capital-intensive manufacturing plays. Watch FDA accelerated potency degradation testing protocol expansion as signal for extended approval timelines that favor incumbents with validated stability data.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA stability guideline harmonization reduces parallel US-European submission friction for qualified applicants. |
| Manufacturing Scale-Up | Closed-system bioreactor retrofitting ahead of REACH deadlines secures European production licenses. |
| Licensing Agreement | Oka-strain patent estate access through Japanese legacy holders unlocks upstream biological material supply. |
| Pipeline Diversification | mRNA platform migration for VZV antigens bypasses live virus cold chain constraints entirely. |
| Long-term Supply Agreement | UNICEF procurement channel qualification delivers multi-year volume commitments from emerging economy tenders. |
Research Methodology
A spread of perspectives from regulatory affairs directors, formulary managers at German hospital pharmacies, CDSCO compliance officers, and Brazilian state procurement leads converged on the working assumptions. Primary interviews combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and WHO prequalification status databases. Bottom-up tender volume aggregation and top-down immunization schedule expansion trajectories were triangulated.
Demand-supply balance modeling anchored the analytical framework across the analysis window. Segmentation dimensions included formulation technology, patient risk profile, procurement channel, and regional regulatory cluster. CAGRs derived from volume trajectory alignment with national immunization program expansion timelines and potency stability validation intervals. Forecast inputs incorporated cold chain infrastructure buildout rates and MRC-5 cell culture specialist pipeline constraints.
Macroeconomic conditions sit as an overlay; deviation in emerging market currency stability or vaccine procurement budget allocation would shift the trajectory. Forecasts reflect assumptions around regulatory timeline adherence and biological material supply continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Antidotes Market
Pharmaceuticals
Iceland Pharmaceutical Market
Pharmaceuticals
Global Hedgehog Pathway Inhibitors Market
Pharmaceuticals
Global Oxytocic Pharmaceuticals Market
Pharmaceuticals
Global Esketamine Market
Pharmaceuticals
Herbal Drugs Market
Pharmaceuticals
Global Liver Diseases Therapeutics Market
Pharmaceuticals
Hard Empty HPMC Capsule Market
Pharmaceuticals
Global Plasma Derived Therapy Market
Pharmaceuticals
Computer-Aided Drug Discovery Market
Pharmaceuticals
Global Prefilled Syringes Drug Molecules Market
Pharmaceuticals
Latin America Meglitinide Market
Pharmaceuticals
Celiac Disease Drugs Market
Pharmaceuticals
Pharmacy and Drug Store Franchises Market
Pharmaceuticals
Bladder Cancer Treatment Drugs Market
Pharmaceuticals
Telmisartan Market