
 Hard Empty HPMC Capsule Market | 2026-2036
Hard Empty HPMC Capsule Market Size, Share, and Industry Trends Forecast 2026-2036
Hard Empty HPMC Capsule Market Insights
Pharmaceutical companies are bifurcating their capsule procurement between traditional gelatin and HPMC alternatives as clean-label pressure intensifies. Lonza Group leverages its vertically integrated excipient platform to sustain supply security for European and North American drug makers. ACG Worldwide anchors production scale across India, competing on cost-adjusted output for global generics clients. Suheung Co., Ltd. differentiates through specialized coating technologies that extend functional release profiles for modified-delivery formulations.
Hard empty HPMC capsules consist of hydroxypropyl methylcellulose shells manufactured via dip-molding of aqueous polymer solutions, with standard moisture content ranging from 4% to 6% and dissolution profiles tunable through varying polymer viscosity grades. The primary commercial purpose centers on oral dosage delivery for moisture-sensitive or hygroscopic actives where gelatin cross-linking risks stability failure. Size 0 and Size 1 SKUs dominate volume throughput across pharmaceutical applications, while nutraceutical buyers increasingly specify Size 00 for high-fill-density botanical extracts. Contract manufacturers occupy the fastest-growing end-user channel as outsourcing consolidates capsule-filling operations away from in-house pharmaceutical lines.
US FDA guidance on BSE-TSE compliance and EMA certification requirements for animal-free excipients shape product standards and market access across developed markets. India's CDSCO aligns with USP-NF monographs for HPMC capsule shell testing, enabling export qualification for domestic manufacturers. China's NMPA maintains GB standards for vegetable-origin capsules that diverge from pharmacopeial harmonization, creating dual-registration burdens for multinational suppliers. Stakeholders must monitor regulatory divergence between pharmacopeias as a determinant of manufacturing location and certification investment.
Market Dynamics
Pharmaceutical procurement bifurcation between gelatin and HPMC shell materials intensifies as US FDA and EMA documentation mandates for animal-origin-free excipients harden compliance thresholds across developed markets.
Growth Catalysts
- EMA Certification Requirements:European pharmaceutical manufacturers accelerate HPMC adoption to satisfy animal-free excipient documentation protocols for cross-border drug approvals.
- Moisture-Sensitive Actives:Formulators of hygroscopic APIs specify HPMC shells to circumvent gelatin cross-linking failures that compromise shelf stability.
- India:ACG Worldwide and domestic contract manufacturers anchor export-scale production hubs serving North American and European generics clients.
Market Restraints
- HPMC Polymer Feedstock Volatility:Purified cellulose derivative costs fluctuate with pulp commodity markets and specialty chemical purification capacity constraints.
- Chinese Supplier Concentration:A subset of mid-tier HPMC shell producers cluster in Shandong and Jiangsu provinces, creating single-source vulnerability for non-vertically integrated buyers.
- Gelatin Cost Competitiveness:Bovine and porcine gelatin retains 30-40% price advantage for non-BSE-sensitive applications, slowing substitution in cost-pressured markets.
Strategic Opportunities
- Brazil:ANVISA's alignment with USP-NF HPMC monographs opens registration pathways for Indian and European suppliers in Latin America's largest pharma market.
- Modified-Release Formulations:Enteric-coated HPMC capsules with tunable dissolution profiles capture share from tablet-based delayed-release technologies in proton pump inhibitor and enzyme delivery.
- CDSCO Export Harmonization:India's convergence with USP-NF testing standards reduces dual-certification burdens for domestic manufacturers targeting FDA-regulated buyers.
Industry Challenges
- Dip-Molding Process Expertise:Thin-shell HPMC production requires aqueous polymer viscosity control that few contract manufacturers outside India and Korea have mastered at commercial scale.
- Dual Pharmacopeia Registration:China's GB standards for vegetable-origin capsules diverge from USP-NF and EP monographs, forcing multinational suppliers to maintain separate quality systems.
- Legacy Gelatin Filling Line Retrofit:Pharmaceutical capsule-filling equipment optimized for gelatin shell elasticity requires tooling and humidity-control modifications to handle HPMC's distinct mechanical properties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hard Empty HPMC Capsule Market |
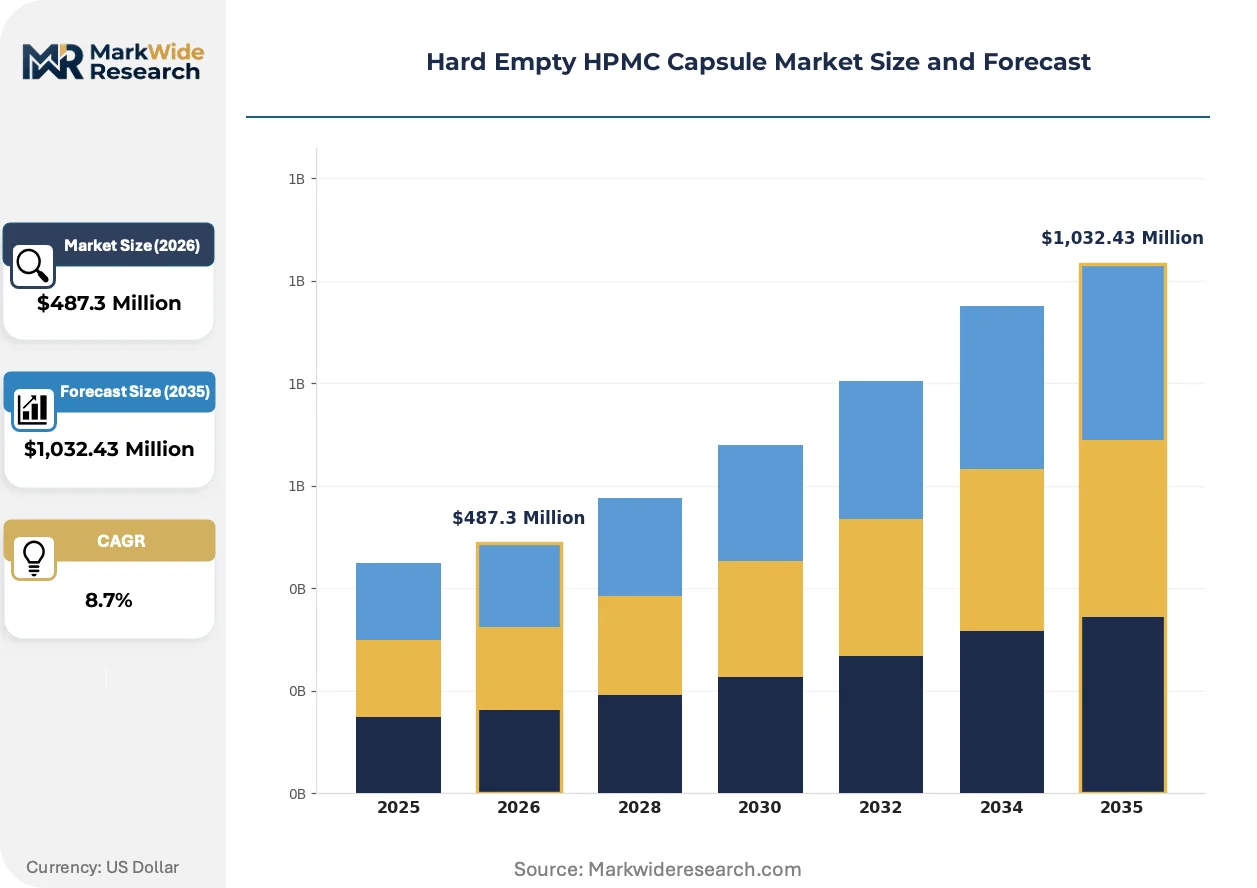
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Size 00, Size 0, Size 1, Size 2 Application: Pharmaceuticals, Nutraceuticals, Dietary Supplements, Veterinary Medicine End User: Contract Manufacturers, Pharmaceutical Companies, Research Institutions, Health Food Manufacturers Distribution Channel: Online Retail, Distributors, Wholesalers, Direct Sales |
| Companies Covered | Lonza Group, ACG Worldwide, Qualicaps, Suheung Co., Ltd., Anhui Huangshan Capsule Co., Ltd., Shanxi Guangsheng Medicinal Capsule Co. Ltd., Sunil Healthcare Ltd., Baotou Capstech Co., Ltd., Zhejiang Yuexi Capsule Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hard Empty HPMC Capsule Market Trends and Innovations
Shell material innovation, regulatory documentation automation, and procurement channel restructuring are compressing traditional supply relationships while opening technical differentiation pathways for specialized manufacturers.
Low-viscosity HPMC polymer grades with accelerated dissolution profiles are supplanting standard-tier shells in fast-dissolving nutraceutical applications. Sports nutrition and botanical extract formulators in North America specify these grades to meet 15-minute disintegration benchmarks. This substitution is compressing demand for conventional HPMC SKUs in high-volume supplement channels.
REACH compliance automation tools now integrate excipient origin documentation into supplier qualification workflows. European drug makers deploy blockchain-anchored certification trails to satisfy EMA audit requirements for animal-free supply chains. Small and mid-cap generics manufacturers in Germany and Italy lag in this digitization, creating compliance vulnerability relative to larger competitors.
Direct procurement from shell manufacturers is displacing distributor-mediated purchasing for volume capsule buyers. Large contract manufacturers in the United States and Germany negotiate multi-year supply agreements with ACG Worldwide and Lonza Group, bypassing regional chemical distributors. This channel consolidation is most pronounced among CDMOs filling more than 500 million units annually.
Hard Empty HPMC Capsule Market Segmentation
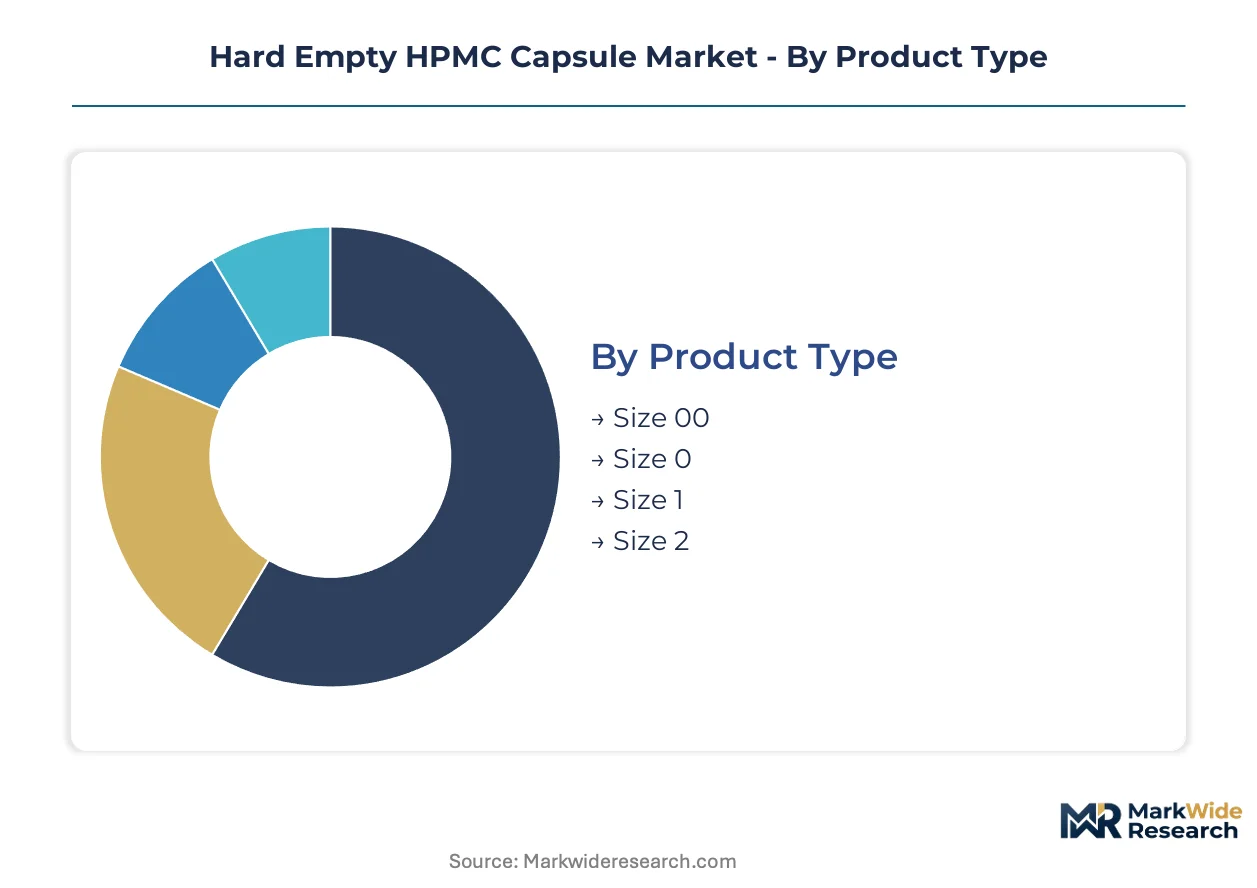
Hard empty HPMC capsule procurement patterns diverge sharply across capsule dimensions, therapeutic categories, and buyer sophistication tiers. Formulators select shell specifications based on fill density requirements, active ingredient sensitivity profiles, and downstream regulatory filing geographies.
Product Type:
Margin pools concentrate in high-volume Size 0 and Size 1 SKUs where pharmaceutical contract manufacturers consolidate procurement at scale.
- Size 00:These oversized shells accommodate high-density botanical extracts and sports nutrition formulations prevalent in North American nutraceutical channels. Nutraceutical buyers in the United States specify Size 00 for green powder and protein formulations where gelatin-free positioning commands shelf price premiums.
- Size 0:Standard-size HPMC shells dominate pharmaceutical throughput for oral solid dosage forms across European and Indian generics markets. ACG Worldwide and Lonza Group anchor production capacity for Size 0 SKUs serving FDA and EMA filing pathways.
- Size 1:Mid-range capsules capture pediatric and geriatric formulations where swallowability constraints limit fill volume.
- Size 2:Compact shells serve veterinary medicine and niche research applications with limited volume throughput.
Size 0 holds installed capacity. Size 00 is rotating up the share rankings.
Application:
Cost tier stratification separates pharmaceutical-grade certification requirements from nutraceutical label claims.
- Pharmaceuticals:Drug manufacturers specify HPMC shells for moisture-sensitive APIs where gelatin cross-linking risks ICH stability failures. EMA certification requirements and US FDA BSE-TSE documentation mandates accelerate substitution from animal-origin gelatin in European and North American filing pathways.
- Nutraceuticals:Sports nutrition and botanical extract formulators in Germany and Italy specify low-viscosity HPMC grades to meet accelerated disintegration benchmarks for clean-label positioning.
- Dietary Supplements:Vitamin and mineral compounders prioritize cost-adjusted sourcing from Indian contract manufacturers for private-label retail distribution.
- Veterinary Medicine:Companion animal pharmaceutical developers specify HPMC for palatability-masked formulations where shell integrity resists gastric degradation.
Pharmaceuticals maintains certification infrastructure. Nutraceuticals is expanding most quickly.
End User:
Customer type determines procurement channel sophistication and specification stringency.
- Contract Manufacturers:CDMOs filling more than 500 million units annually negotiate direct supply agreements with ACG Worldwide and Lonza Group, bypassing regional distributors. These buyers specify enteric-coated and modified-release HPMC variants for proton pump inhibitor and enzyme delivery portfolios.
- Pharmaceutical Companies:Multinational drug makers maintain dual-sourcing strategies across gelatin and HPMC shell materials to mitigate supply continuity risks.
- Research Institutions:Clinical trial material procurement favors standardized Size 0 HPMC shells for bioequivalence studies requiring batch-to-batch dissolution consistency.
- Health Food Manufacturers:Supplement brand owners specify Size 00 HPMC for high-fill-density botanical extracts targeting vegan positioning claims.
Contract Manufacturers command volume leverage. Health Food Manufacturers are climbing the fastest.
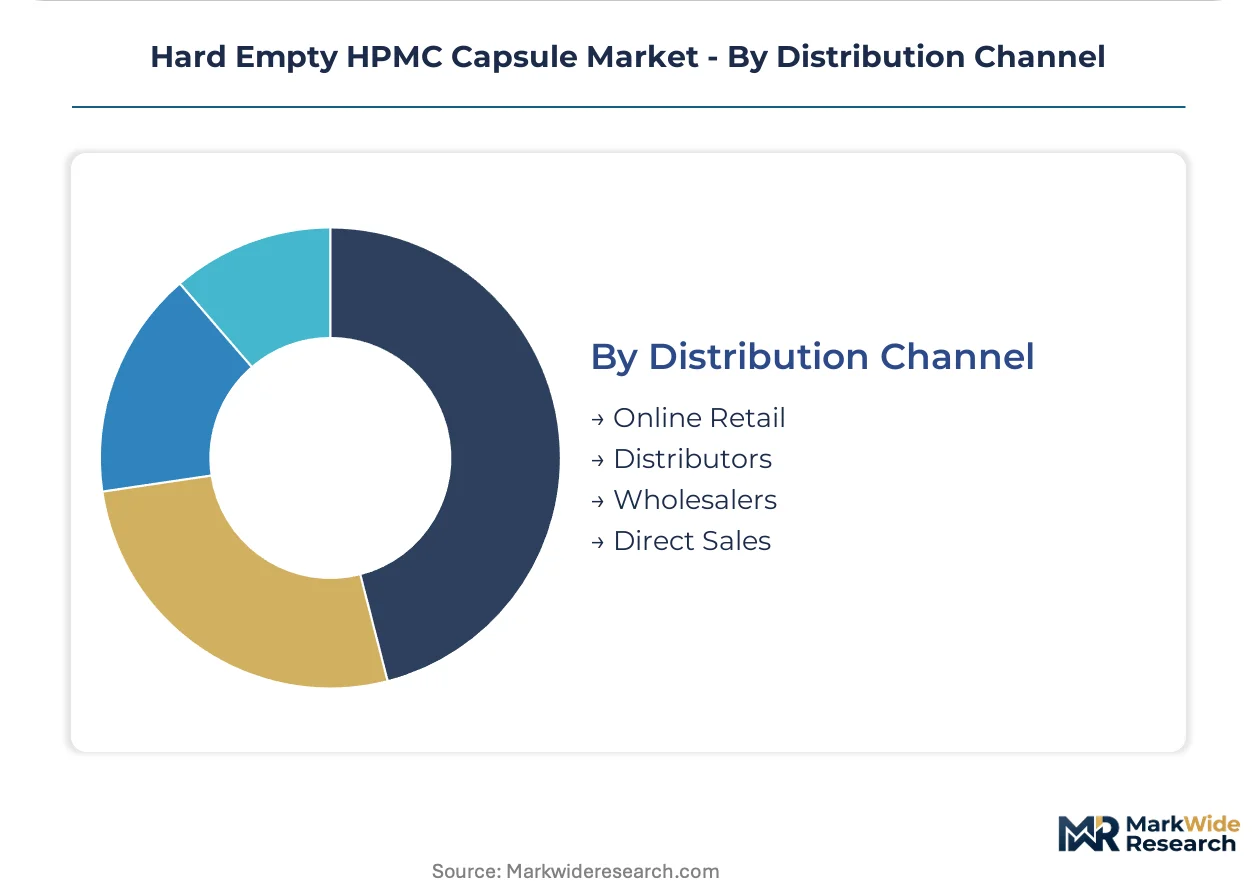
Distribution Channel:
Volume concentration dictates channel economics and supplier relationship structures.
- Direct Sales:Large pharmaceutical and nutraceutical formulators in the United States and Germany execute multi-year supply agreements with shell manufacturers. These arrangements lock in capacity allocation and simplify EMA audit trail documentation.
- Distributors:Regional chemical distributors serve mid-tier generics manufacturers and smaller supplement brands lacking procurement scale for direct manufacturer negotiation.
- Wholesalers:Pharmaceutical wholesalers aggregate HPMC capsule procurement for hospital and retail pharmacy chains with standardized SKU requirements.
- Online Retail:E-commerce channels serve research institutions and small health food manufacturers with low-volume, specification-flexible purchasing patterns.
Direct Sales anchors contractual volume. Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian contract manufacturers ship hard empty HPMC capsules to North American and European pharmaceutical buyers seeking animal-origin-free excipient documentation. This trade corridor anchors export-scale production capacity for global generics supply chains.
United States
Pharmaceutical formulators specify HPMC shells for moisture-sensitive APIs to avoid gelatin cross-linking failures during ICH stability studies. FDA documentation mandates for BSE-TSE compliance accelerate substitution from animal-origin gelatin in drug filing pathways. New Jersey and North Carolina host contract manufacturing clusters where CDMOs negotiate direct supply agreements with Indian and European shell producers.
Germany
REACH compliance automation tools integrate excipient origin documentation into supplier qualification workflows for domestic drug makers. EMA certification requirements for animal-free excipients harden procurement standards across cross-border pharmaceutical approvals. The Rhine-Ruhr industrial region concentrates capsule-filling operations for European generics clients.
India
CDSCO alignment with USP-NF monographs enables export qualification for domestic HPMC capsule manufacturers serving FDA-regulated buyers. ACG Worldwide anchors production scale across Mumbai and Hyderabad production hubs. These facilities process purified cellulose derivatives into Size 0 and Size 1 shells for North American and European pharmaceutical procurement.
China
NMPA maintains GB standards for vegetable-origin capsules that diverge from USP-NF and EP monographs, creating dual-registration burdens for multinational suppliers. Shandong and Jiangsu provinces cluster mid-tier HPMC shell producers serving domestic pharmaceutical formulators. These manufacturing centers supply standardized shells for local generics companies.
Brazil
ANVISA alignment with USP-NF HPMC monographs opens registration pathways for Indian and European suppliers in Latin America's largest pharmaceutical market. São Paulo state concentrates import distribution and capsule-filling operations for regional generics distribution. Local contract manufacturers specify HPMC shells to meet documentation requirements for export-oriented production.
Hard Empty HPMC Capsule Market Competitive Landscape
Listed leaders compete with private specialists across shell manufacturing and coating technologies in a market structure that concentrates capacity among vertically integrated excipient platforms and regional fabrication clusters. Tiered competitive positioning separates premium-grade pharmaceutical certification holders from cost-optimized nutraceutical suppliers. Three archetypes dominate: integrated polymer-to-shell manufacturers, specialized coating technology providers, and regional contract fabrication hubs. Capacity expansion and direct procurement channel development represent the dominant competitive moves as large buyers bypass distributor intermediaries.
Within the integrated manufacturing tier, Lonza Group and ACG Worldwide exemplify scale-driven positions anchored in European and Indian production bases respectively. Suheung Co., Ltd. occupies a specialization position among coating technology providers. These three entities represent distinct strategic archetypes: the Swiss-German integrated excipient platform, the Indian export-scale fabrication hub, and the Korean functional-release specialist.
| Leading Market Players |
|---|
| Lonza Group |
| ACG Worldwide |
| Qualicaps |
| Suheung Co., Ltd. |
| Anhui Huangshan Capsule Co., Ltd. |
| Shanxi Guangsheng Medicinal Capsule Co. Ltd. |
| Sunil Healthcare Ltd. |
| Baotou Capstech Co., Ltd. |
| Zhejiang Yuexi Capsule Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day inventory buffers at European pharmaceutical buyers concentrate pricing leverage with Indian and Korean shell manufacturers who control dip-molding capacity. This lead-time compression rewards vertically integrated suppliers while squeezing distributor margins across non-direct procurement channels.
Pricing Analysis
Standard-viscosity HPMC polymer grades command 15-25% premiums over low-viscosity alternatives used in fast-dissolving nutraceutical applications. Pricing stratifies across pharmaceutical certification tiers, enteric-coated functional variants, and uncoated commodity shells. Cost compression in Size 00 nutraceutical SKUs intensifies as Indian contract manufacturers scale aqueous polymer processing. Pharmaceutical buyers exhibit lowest price sensitivity due to regulatory filing dependencies, while dietary supplement brand owners prioritize cost-adjusted sourcing.
Supply Chain Analysis
Purified cellulose derivative purification capacity in Shandong province anchors global HPMC polymer feedstock availability. Manufacturing draws from Indian excipient fabrication hubs, Korean coating technology specialists, and Chinese mid-tier shell producers. Single-source vulnerability concentrates in specialty polymer viscosity grades required for modified-release formulations. Distribution runs through direct manufacturer agreements for volume buyers and regional chemical distributors for mid-tier accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hard empty HPMC capsule demand sits in early-cycle expansion as FDA and EMA documentation mandates for animal-origin-free excipients accelerate substitution from gelatin across developed-market drug filings.
For Market Incumbents: Compound certification advantages by deepening backward integration into purified cellulose derivatives and expanding Size 0 capacity at Mumbai and Hyderabad production hubs. Defend against emerging Korean coating technology specialists by locking multi-year direct supply agreements with North American CDMOs filling proton pump inhibitor portfolios. Prioritize REACH compliance automation to maintain EMA audit trail advantages over digitization-lagging European generics competitors. For New Entrants and Emerging Players: Anchor in Brazilian and Mexican contract manufacturing corridors where ANVISA alignment with USP-NF monographs opens registration pathways for Indian and European suppliers. Target mid-tier nutraceutical distributors in Germany and Italy lacking procurement scale for direct manufacturer negotiation. Pursue white-label coating technology licensing from Korean specialists to differentiate on functional-release capabilities without captive polymer processing investment. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized excipient shell manufacturing divisions. Long-term viability hinges on regulatory documentation automation capabilities and direct procurement channel control rather than distributor-mediated volume. Monitor CDSCO export harmonization progress as inflection signal for Indian manufacturer valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Purified Cellulose | Captive polymer supply insulates Lonza and ACG from pulp commodity volatility and Chinese feedstock concentration. |
| REACH Compliance Automation | Blockchain-anchored certification trails satisfy EMA audit requirements for animal-free supply chain documentation. |
| Direct Procurement Channel Development | Multi-year agreements with CDMOs filling 500M+ units annually bypass distributor intermediaries and lock capacity allocation. |
| Modified-Release Coating Technology Licensing | Suheung's enteric-coated HPMC variants capture share from tablet-based delayed-release technologies in enzyme delivery. |
| CDSCO Export Harmonization Investment | USP-NF testing standard alignment reduces dual-certification burdens for Indian manufacturers targeting FDA-regulated buyers. |
Research Methodology
Operator-level perspectives from pharmaceutical procurement directors, CDMO operations heads, excipient regulatory affairs leads, and nutraceutical brand managers anchored the qualitative base. Primary fieldwork combined structured interviews across these stakeholder roles with secondary validation from FDA BSE-TSE guidance documents, EMA certification requirement filings, USP-NF monograph updates, and CDSCO export standard notifications. Bottom-up volume modeling by capsule size, coating type, and end-user channel triangulated against top-down excipient market sizing from customs trade data and pharmaceutical import records.
Sensitivity analysis tested forecast outputs across polymer feedstock cost scenarios, regulatory harmonization timing variations, and substitution elasticity assumptions. The analytical framework segmented by product type (Size 00, 0, 1, 2), application (pharmaceutical, nutraceutical, dietary supplement, veterinary), end user (contract manufacturer, pharmaceutical company, research institution, health food manufacturer), and distribution channel (direct sales, distributor, wholesaler, online retail). CAGRs derived from regression against pharmaceutical outsourcing trends, clean-label supplement growth patterns, and regional regulatory adoption curves.
Decision-makers should treat outputs as directional under base assumptions of sustained FDA-EMA documentation mandate enforcement and stable cellulose derivative purification capacity; material deviation in regulatory alignment timing or polymer feedstock availability would warrant model refresh. Practitioners should keep alternative scenarios live as NMPA GB standard harmonization progress and Brazilian ANVISA implementation pace evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Adenosine Market
Pharmaceuticals
RNA-Targeted Small Molecules Market
Pharmaceuticals
Male Hypogonadism Market
Pharmaceuticals
Dextromethorphan Market
Pharmaceuticals
Calcitriol Capsules Market
Pharmaceuticals
North America SGLT2 Inhibitors Market
Pharmaceuticals
Europe Heparin Market
Pharmaceuticals
Cancer Immunotherapy Drug Discovery Outsourcing Market
Pharmaceuticals
India Plasma Fractionation Market
Pharmaceuticals
Cough Oral Solution Market
Pharmaceuticals
Europe Diabetes Drugs Market
Pharmaceuticals
Vasopressin Antagonists Market
Pharmaceuticals
Bacterial Vaginosis Treatment Market
Pharmaceuticals
Soft Capsules Drugs Market
Pharmaceuticals
Adrenocorticotropic Hormone [ACTH] Market
Pharmaceuticals
India Pharmaceutical Market