
 United Kingdom Ophthalmology Devices Market | 2026-2036
United Kingdom Ophthalmology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Ophthalmology Devices Market Analytics
Silicone hydrogel is pivoting away from traditional hydrogel in contact lens formulations, improving oxygen permeability and extending comfortable wear time for patients. Alcon Inc. leverages its vertically integrated supply chain to dominate premium intraocular lens production. Johnson & Johnson Vision Care anchors the daily disposable segment through sustained R&D investment in moisture-retention technologies. Carl Zeiss Meditec AG specializes in optical coherence tomography platforms that occupy the high-resolution diagnostic tier.
Ophthalmology devices comprise precision-engineered instruments, diagnostic imaging systems, surgical tools, and vision correction products designed for the examination, treatment, and management of ocular conditions. Phacoemulsification systems utilize ultrasonic frequency handpieces operating at 40–60 kHz to emulsify cataractous lenses through a sub-3 mm incision. Diagnostic Devices command the largest revenue share as NHS procurement concentrates capital expenditure on OCT and retinal imaging platforms. Vision Care Products represent the fastest-expanding segment driven by subscription-based daily disposable lens models. Cataract Surgery applications generate the deepest margin pools due to procedure volume and premium IOL upsell potential.
The Medicines and Healthcare products Regulatory Agency enforces UK Medical Devices Regulation requirements, mandating enhanced clinical evidence for Class III implantable devices and strengthening post-market vigilance obligations. The Care Quality Commission inspects eye care centers against national standards, directly influencing procurement decisions for diagnostic equipment upgrades. The National Institute for Health and Care Excellence shapes adoption velocity through technology appraisal guidance that determines NHS reimbursement for novel surgical interventions. Stakeholders must monitor MHRA divergence from EU MDR alignment timelines and prepare supply chain documentation for independent UK conformity assessment routes.
Market Dynamics
The UK ophthalmology devices sector is experiencing concentrated pressure from NHS procurement centralization, which is compressing vendor margins while simultaneously accelerating platform consolidation across hospital trusts.
Growth Catalysts
- UK Medical Devices Regulation:The MHRA's enhanced post-market surveillance requirements are driving replacement cycles for legacy diagnostic equipment as trusts seek compliant platforms.
- Phacoemulsification technology:Sub-3 mm incision capabilities are expanding day-case cataract surgery eligibility, increasing throughput at NHS foundation trusts.
- London and South East England:Specialist eye hospital clusters concentrate demand for premium intraocular lenses and advanced OCT systems.
Market Restraints
- Premium IOL input costs:Specialized hydrophobic acrylic materials and diffractive optic designs carry elevated raw material exposure.
- Vendor concentration:Optical coherence tomography platform supply concentrates among German and Japanese precision optics manufacturers.
- MHRA divergence timeline:Uncertainty around UK-EU MDR alignment is extending conformity assessment durations for Class III implantable devices.
Strategic Opportunities
- Subscription-based daily disposable models:Direct-to-patient lens delivery platforms bypass traditional optical retail channels.
- Tele-ophthalmology integration:Remote diagnostic workflows combining smartphone-based visual acuity testing with AI-assisted image screening.
- NICE technology appraisal pathways:Expedited reimbursement determinations for novel surgical interventions meeting clinical efficacy thresholds.
Industry Challenges
- Vitreoretinal surgeon training pipelines:Fellowship positions are failing to match procedural volume growth at tertiary referral centers.
- Legacy PACS integration:New OCT platforms require costly interoperability workarounds with entrenched hospital imaging archives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Ophthalmology Devices Market |
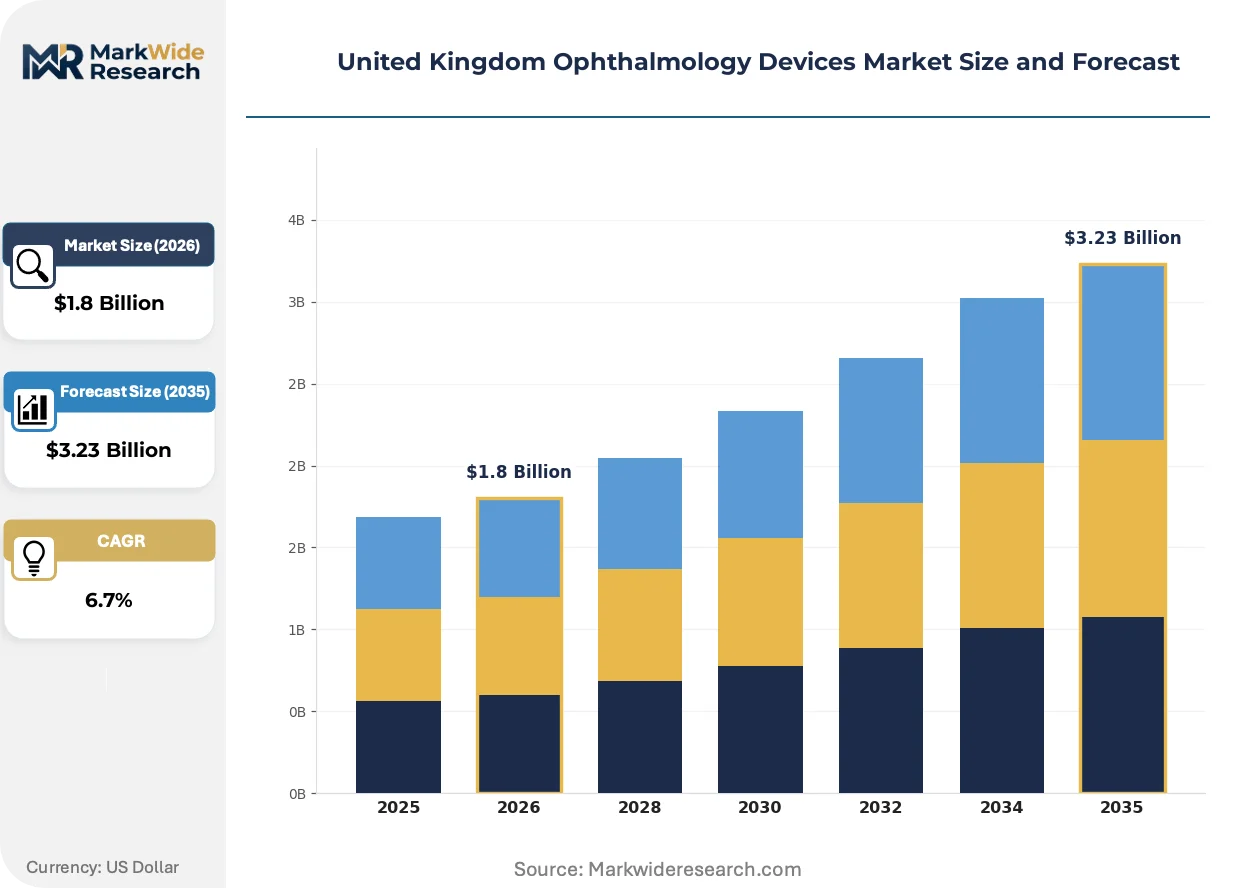
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Devices, Surgical Instruments, Therapeutic Devices, Vision Care Products End User: Hospitals, Clinics, Eye Care Centers, Research Institutions Technology: Laser Technology, Optical Coherence Tomography, Retinal Imaging, Phacoemulsification Application: Cataract Surgery, Glaucoma Treatment, Retinal Disease Management, Refractive Surgery |
| Companies Covered | Alcon Inc., Johnson & Johnson Vision Care, Carl Zeiss Meditec AG, Bausch + Lomb Corp., CooperVision Inc., Topcon Corporation, HAAG-Streit Group, Rayner Intraocular Lenses Ltd., Nidek Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Ophthalmology Devices Market Evolving Landscape
Artificial intelligence is penetrating diagnostic workflows at an accelerating pace, compressing image interpretation timelines while raising new questions about clinical liability and validation standards.
Swept-source optical coherence tomography is automating volumetric retinal scanning at speeds exceeding conventional spectral-domain systems. NHS hospital trusts in Manchester and Birmingham are piloting these platforms for glaucoma progression monitoring. The technology is automating detection of subclinical structural changes, reducing specialist referral burdens.
The UK Medical Devices Regulation is tightening clinical evidence requirements for software-as-a-medical-device applications. Manufacturers must now submit prospective validation studies for AI-assisted diagnostic algorithms. Ophthalmic imaging platforms with embedded screening tools face the steepest compliance ramps.
Hospital procurement teams are consolidating vendor relationships through framework agreements that bundle diagnostic equipment, maintenance, and consumables. Single-source contracts are displacing fragmented purchasing across individual departments. This concentration is most visible in England's NHS Supply Chain ophthalmology category tower.
United Kingdom Ophthalmology Devices Market Segmentation
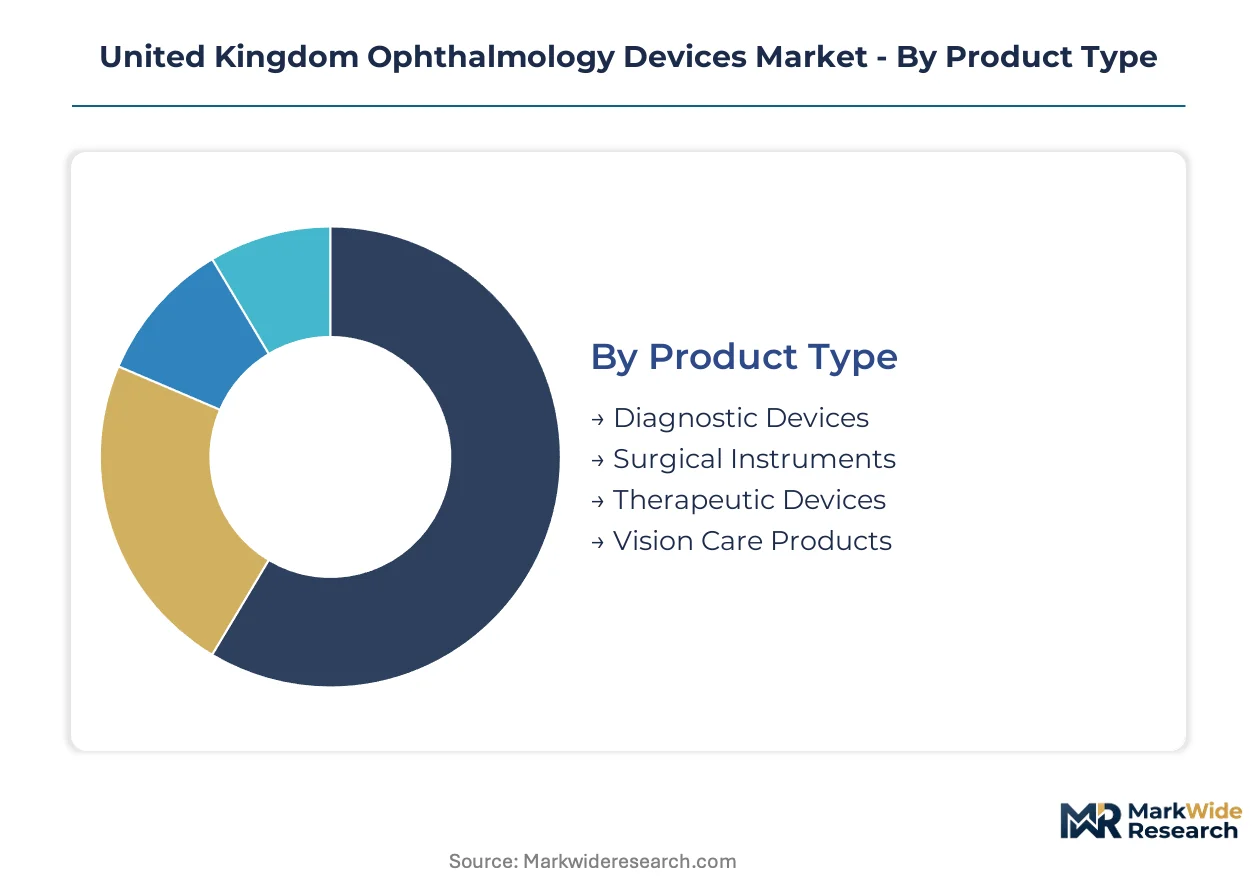
Segmentation in UK ophthalmology devices reveals how regulatory burden, procurement concentration, and clinical workflow specialization shape vendor strategy. Understanding these divisions exposes where MHRA compliance costs concentrate and where NHS capital expenditure flows.
Product Type:
MHRA classification tiers determine conformity assessment intensity across this category, with Class III implantables facing the steepest clinical evidence requirements.
- Diagnostic Devices:Optical coherence tomography platforms and retinal imaging systems dominate NHS capital procurement. London teaching hospitals concentrate demand for high-resolution spectral-domain and swept-source configurations. MHRA post-market surveillance obligations accelerate replacement cycles for legacy equipment.
- Vision Care Products:Daily disposable contact lenses and lens care solutions operate under lighter regulatory burden than implantable devices. Subscription-based direct-to-patient delivery models are bypassing traditional optical retail channels across South East England.
- Surgical Instruments:Precision-engineered phacoemulsification handpieces and microsurgical tools require sterile supply chain integrity.
- Therapeutic Devices:Ocular drug delivery systems and sustained-release implants face extended MHRA approval timelines.
Diagnostic Devices sits at the top of the volume ranking, with Vision Care Products climbing the fastest.
End User:
Procurement authority and reimbursement pathway sophistication vary sharply across this dimension, shaping vendor sales cycle length and contract structure.
- Hospitals:NHS foundation trusts and specialist eye hospitals command centralized procurement budgets for multi-million-pound diagnostic platform acquisitions. Framework agreements bundle equipment, maintenance, and consumables into multi-year contracts.
- Eye Care Centers:Independent optometry practices and high-street chains drive volume in vision care products. These operators lack capital for surgical equipment but concentrate demand for refraction devices and contact lens fitting tools.
- Clinics:Private ophthalmology clinics in London and Manchester perform elective refractive procedures outside NHS reimbursement.
- Research Institutions:University hospitals and clinical trial centers pilot novel diagnostic algorithms and AI-assisted screening tools.
Hospitals capture the deepest revenue pools, while Eye Care Centers are expanding most quickly through subscription lens models.
Technology:
Intellectual property concentration and component supply geography create divergent competitive dynamics across these platforms.
- Optical Coherence Tomography:Swept-source configurations automate volumetric retinal scanning at speeds exceeding spectral-domain predecessors. Manchester and Birmingham NHS trusts are piloting these platforms for glaucoma progression monitoring.
- Phacoemulsification:Ultrasonic handpieces operating at 40–60 kHz enable sub-3 mm incision cataract surgery. Day-case eligibility expansion at NHS foundation trusts is driving throughput growth.
- Laser Technology:Femtosecond and excimer platforms serve refractive correction and capsulotomy applications.
- Retinal Imaging:Wide-field fundus photography and angiography systems support diabetic retinopathy screening programs.
Optical Coherence Tomography leads installed base, with Phacoemulsification gaining share fastest through day-case surgery expansion.
Application:
Procedure reimbursement rates and clinical outcome visibility determine where premium technology upgrades achieve NHS adoption.
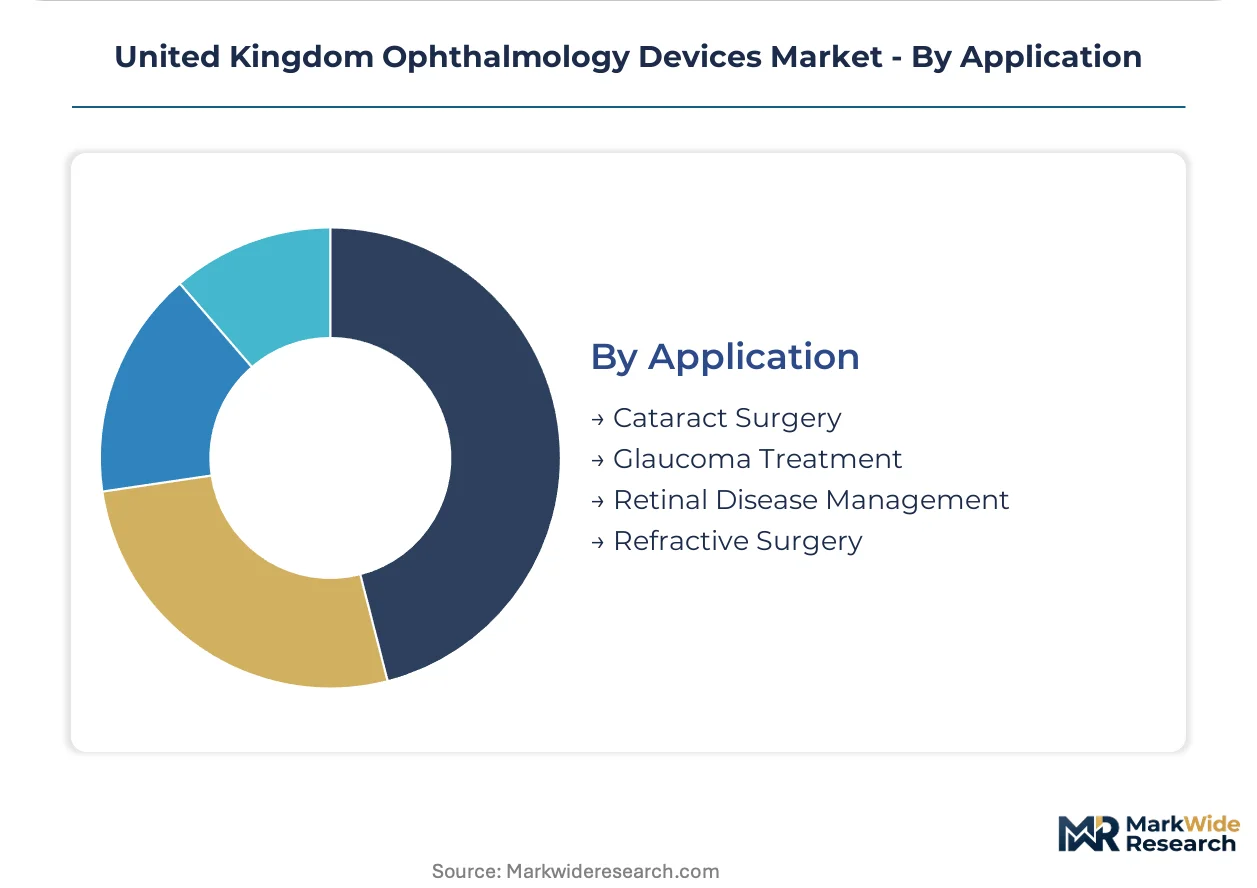
- Cataract Surgery:High procedural volume and premium intraocular lens upsell potential generate the deepest margin pools. NICE technology appraisal guidance shapes adoption velocity for novel surgical interventions.
- Retinal Disease Management:Age-related macular degeneration and diabetic retinopathy drive demand for intravitreal injection delivery systems and sustained-release implants. Treatment burden is rising with population aging.
- Glaucoma Treatment:Minimally invasive surgical devices and sustained-release drug delivery are displacing filtration surgery in early disease.
- Refractive Surgery:Elective laser vision correction operates outside NHS reimbursement, concentrating in private London clinics.
Cataract Surgery commands the largest procedure volume, with Retinal Disease Management showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London and South East England specialist eye hospitals concentrate procurement authority for premium diagnostic platforms and intraocular lenses. NHS foundation trusts in these clusters drive multi-million-pound capital expenditure on optical coherence tomography systems. The Medicines and Healthcare products Regulatory Agency shapes equipment replacement cycles through enhanced post-market surveillance mandates.
London and South East England
Moorfields Eye Hospital and St Thomas' Hospital anchor demand for swept-source OCT and premium IOL platforms. The MHRA's UK Medical Devices Regulation accelerates legacy equipment decommissioning at these tertiary centers. Westminster and Southwark hospital trusts pilot AI-assisted diagnostic workflows for glaucoma progression monitoring.
Midlands
Birmingham's Queen Elizabeth Hospital and University Hospitals Birmingham NHS Foundation Trust concentrate vitreoretinal surgery volume. The Care Quality Commission inspects these centers against national standards, directly influencing diagnostic equipment upgrade timelines. Manchester Royal Eye Hospital collaborates with Birmingham trusts on tele-ophthalmology pilots combining smartphone-based screening with remote specialist review.
North England
Manchester Royal Eye Hospital and Sheffield Teaching Hospitals anchor northern demand for phacoemulsification systems and day-case cataract surgery expansion. NHS Supply Chain framework agreements bundle equipment procurement across these trusts, compressing vendor margins while consolidating vendor relationships. Leeds Teaching Hospitals NHS Trust participates in multi-site trials for minimally invasive glaucoma surgical devices.
Scotland
NHS Scotland's Golden Jubilee National Hospital and Glasgow's Queen Elizabeth University Hospital concentrate elective ophthalmic surgery capacity. The Scottish Health Technologies Group issues parallel technology appraisal guidance that influences adoption velocity for novel surgical interventions. Edinburgh's Princess Alexandra Eye Pavilion maintains research partnerships with University of Edinburgh for AI-assisted retinal imaging validation studies.
Wales
Cardiff and Vale University Health Board and Swansea Bay University Health Board manage ophthalmic service delivery across south Wales. Welsh Government health technology assessment processes determine reimbursement for premium intraocular lenses outside standard NHS tariff. Singleton Hospital in Swansea participates in UK-wide diabetic retinopathy screening program expansion.
United Kingdom Ophthalmology Devices Market Competitive Landscape
Framework agreement consolidation dominates the current landscape as NHS Supply Chain ophthalmology category towers displace fragmented departmental purchasing. The vendor base organizes around three strategic archetypes: diversified multinational healthcare conglomerates with vertically integrated ophthalmology divisions, German and Japanese precision optics specialists controlling high-resolution diagnostic tiers, and mid-cap contact lens manufacturers exploiting direct-to-patient subscription models. M&A activity concentrates among vision care product portfolios, while strategic partnerships between diagnostic platform vendors and AI software developers accelerate regulatory approval pathways for embedded screening algorithms.
Within the diversified healthcare conglomerate tier, Alcon Inc., Johnson & Johnson Vision Care, and Bausch + Lomb Corp. occupy positions spanning surgical devices through vision care products. These entities exemplify scale-driven competitive positioning through captive supply chains and sustained R&D investment in moisture-retention and oxygen-permeability technologies. Carl Zeiss Meditec AG anchors the precision optics specialist archetype, representing German engineering concentration in spectral-domain and swept-source OCT platforms. CooperVision Inc. sits within the subscription-model contact lens segment, exemplifying direct-to-patient delivery strategies that bypass traditional optical retail channels across South East England.
| Leading Market Players |
|---|
| Alcon Inc. |
| Johnson & Johnson Vision Care |
| Carl Zeiss Meditec AG |
| Bausch + Lomb Corp. |
| CooperVision Inc. |
| Topcon Corporation |
| HAAG-Streit Group |
| Rayner Intraocular Lenses Ltd. |
| Nidek Co. Ltd. |
| Others |
Value Network & Pricing Analysis
NHS Supply Chain framework agreements concentrate procurement authority among a handful of hospital trusts, locking vendors into multi-year bundled contracts that compress margins while standardizing equipment tiers across England's ophthalmology category tower.
Pricing Analysis
Specialized hydrophobic acrylic materials and diffractive optic designs for premium intraocular lenses carry elevated raw material exposure that manufacturers pass through to hospital procurement teams. Pricing stratifies across premium, standard, and economy tiers based on optical performance specifications and MHRA conformity assessment depth. Cost compression in diagnostic platforms is intensifying because NHS capital budgets face competing demands from digital transformation mandates. High-street optometry chains exhibit greatest price sensitivity due to thin contact lens retail margins, while tertiary eye hospitals prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Freight costs for precision optical components from Germany and Japan elevate landed costs for spectral-domain and swept-source OCT platforms serving UK hospital trusts. Manufacturing concentration in Germany, Japan, and Switzerland feeds the high-resolution diagnostic tier with specialized precision optics and ultrasonic handpiece assemblies. Single-source vulnerability persists for swept-source laser sources and hydrophobic acrylic polymer feedstocks. Distribution runs through NHS Supply Chain category towers and GPO contracts that bundle equipment, maintenance, and consumables into consolidated framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK ophthalmology devices market represents a late-cycle quality story where NHS procurement teams increasingly specify premium diagnostic performance and embedded AI screening capabilities over legacy platform replacements.
For Market Incumbents: To counter vendor consolidation pressure from NHS framework agreements, Alcon and Johnson & Johnson Vision Care should deepen backward integration into silicone hydrogel polymer production and secure captive supply of hydrophobic acrylic materials for premium IOL lines. Channel control through direct-to-patient subscription platforms offers defensive moats against optical retail disintermediation. For New Entrants and Emerging Players: Enter via tele-ophthalmology software stacks that combine smartphone-based visual acuity testing with AI-assisted image screening, targeting underpenetrated community optometry networks in North England and Wales. White-space concentration exists in minimally invasive glaucoma surgical devices where NICE appraisal pathways remain unsettled. A go-to-market angle anchored to MHRA software-as-a-medical-device pre-certification accelerates hospital pilot adoption. For Investors and Strategic Acquirers: Diversified healthcare conglomerates with ophthalmology divisions are the most active acquirer in this space, seeking vision care product portfolios with direct-to-patient subscription infrastructure. Long-term viability hinges on regulatory navigation capabilities across UK-EU MDR divergence timelines. Acquisition targets should exhibit embedded AI diagnostic validation studies and established NHS framework contract relationships. The signal to watch is MHRA publication of independent conformity assessment route timelines for Class III implantables.| Strategic Initiative | Industry Significance |
|---|---|
| MHRA Software-as-a-Medical-Device Pre-Certification | Accelerates hospital pilot adoption for AI-assisted diagnostic algorithms before full UK MDR compliance. |
| NHS Framework Agreement Consolidation | Bundles diagnostic equipment, maintenance, and consumables into multi-year contracts that displace fragmented purchasing. |
| Direct-to-Patient Subscription Platform Launch | Bypasses traditional optical retail channels across South East England through automated lens delivery logistics. |
| Swept-Source OCT Platform Integration | Automates volumetric retinal scanning at Manchester and Birmingham trusts for glaucoma progression monitoring. |
| Premium IOL Reimbursement Strategy | Navigates NICE technology appraisal pathways to secure NHS tariff coverage for novel surgical interventions. |
Research Methodology
Direct dialogue with NHS procurement managers, biomedical engineers at Moorfields Eye Hospital, GPO contracts specialists, and MHRA regulatory affairs leads grounded the qualitative foundation of this study. Secondary validation drew from NHS Supply Chain ophthalmology category tower disclosures, MHRA post-market surveillance bulletins, NICE technology appraisal guidance documents, and hospital trust capital expenditure reports. Bottom-up equipment installation data and top-down procurement budget analysis were triangulated against vendor revenue disclosures.
Segmented outputs across product type, end user, technology, and application dimensions were generated over the projection horizon. CAGRs were derived from procedural volume trajectories, replacement cycle acceleration under UK MDR mandates, and premium IOL penetration assumptions. Forecast inputs incorporated day-case cataract surgery expansion rates at NHS foundation trusts and subscription-based daily disposable lens adoption curves in South East England.
The model holds under stable NHS capital allocation and continued MHRA-EU MDR divergence; deviation in reimbursement policy shifts or regulatory alignment timelines would revise equipment replacement velocity assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Retinal Disease Therapeutics Market
Ophthalmology
Nystagmus Market
Ophthalmology
Synoptophore Market
Ophthalmology
Thyroid Eye Disease Treatment Market
Ophthalmology
North America Ophthalmic Devices and Drugs Market
Ophthalmology
Epidemic Keratoconjunctivitis Treatment Market
Ophthalmology
Light Therapy Glasses Market
Ophthalmology
India Ophthalmology Devices Market
Ophthalmology
Neurotrophic Keratitis Market
Ophthalmology
Global Anterior Uveitis Treatment Market
Ophthalmology
Keratoconus Treatment Market
Ophthalmology
Global Vitreous Tamponades Market
Ophthalmology
Europe Primary Angle-Closure Glaucoma Market
Ophthalmology
Intraocular Lymphoma Treatment Market
Ophthalmology
Extended and Continuous Wear Lenses Market
Ophthalmology
Optometry/Eye Exam Equipment Market