
 Onion Powder Market | 2026-2036
Onion Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Onion Powder Market Intelligence
Buyer concentration across restaurant chains is pivoting toward centralized procurement of standardized dehydrated ingredients, replacing fragmented spot-market purchases. Olam Food Ingredients leverages its integrated supply chain from farm to dehydrated flake to secure multi-year contracts with multinational quick-service operators. McCormick & Company, Inc. anchors North American shelf-stable seasoning demand through proprietary grinding and blending technologies. BCFoods Europe B.V. specializes in low-moisture granulation formats tailored to industrial soup and sauce manufacturers.
Onion powder consists of dehydrated Allium cepa bulbs that undergo washing, peeling, slicing, drying, and milling to achieve moisture content below six percent, yielding a free-flowing concentrate with intensified sulfur compound flavor. Dehydrated onion powder dominates commercial volumes due to its extended shelf stability and uniform dispersibility in dry seasoning blends, while granulated variants command premium positioning within foodservice channels for visible texture applications. The food processing end-user segment concentrates the largest procurement volumes, though restaurant chains represent the fastest-growing demand pool as operators reduce fresh-prep labor.
FDA enforcement of the Food Safety Modernization Act's preventive controls for human food shapes dehydration facility compliance costs and import documentation burdens. FSSAI standards in India and EFSA mycotoxin thresholds in Europe further constrain supplier eligibility, favoring processors with certified laboratory testing and HACCP-validated drying systems. Stakeholders must evaluate backward integration into bulb cultivation or captive dehydration capacity to secure supply continuity under tightening multi-jurisdiction safety mandates.
Market Dynamics
Centralized procurement by multinational quick-service operators is compressing supplier margins while rewarding dehydration processors with captive bulb sourcing and multi-jurisdiction food safety certifications.
Growth Catalysts
- FSMA Preventive Controls:FDA enforcement mandates HACCP-validated drying systems, disqualifying small processors and consolidating volume among certified facilities with laboratory testing capabilities.
- Foodservice Labor Reduction:Restaurant chains are eliminating fresh-prep stations, substituting dehydrated onion powder for sliced bulbs to standardize flavor and reduce kitchen headcount.
- Spray Drying Advancement:Low-temperature atomization technology preserves volatile sulfur compounds, expanding application into premium seasoning blends previously requiring fresh ingredients.
Market Restraints
- Bulb Price Volatility:Onion crop yields fluctuate with monsoon patterns in Maharashtra and Nile Delta irrigation constraints, creating input cost instability for non-integrated processors.
- EFSA Mycotoxin Thresholds:European aflatoxin limits for dried vegetables block entry for dehydration facilities lacking in-house chromatography testing, restricting supplier pool expansion.
- Fresh Substitute Preference:High-end culinary channels and farm-to-table restaurant concepts reject dehydrated formats, capping penetration in visible-texture applications.
Strategic Opportunities
- India Export Infrastructure:Gujarat and Maharashtra dehydration clusters are expanding cold storage and containerized shipping capacity to capture European buyers diversifying from Egyptian sourcing.
- Clean-Label Positioning:Single-ingredient onion powder without anti-caking agents commands shelf-space premiums in North American natural retail channels.
- PLI Scheme Alignment:India's production-linked incentive scheme for food processing subsidizes capital equipment for dehydration capacity expansion, reducing payback periods for compliant investors.
Industry Challenges
- Traceability System Integration:Multi-jurisdiction lot-tracking requirements from farm to flake demand ERP upgrades that mid-tier processors struggle to fund.
- Moisture Specification Calibration:Divergent customer standards ranging from four to seven percent moisture content force production line reconfiguration and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Onion Powder Market |
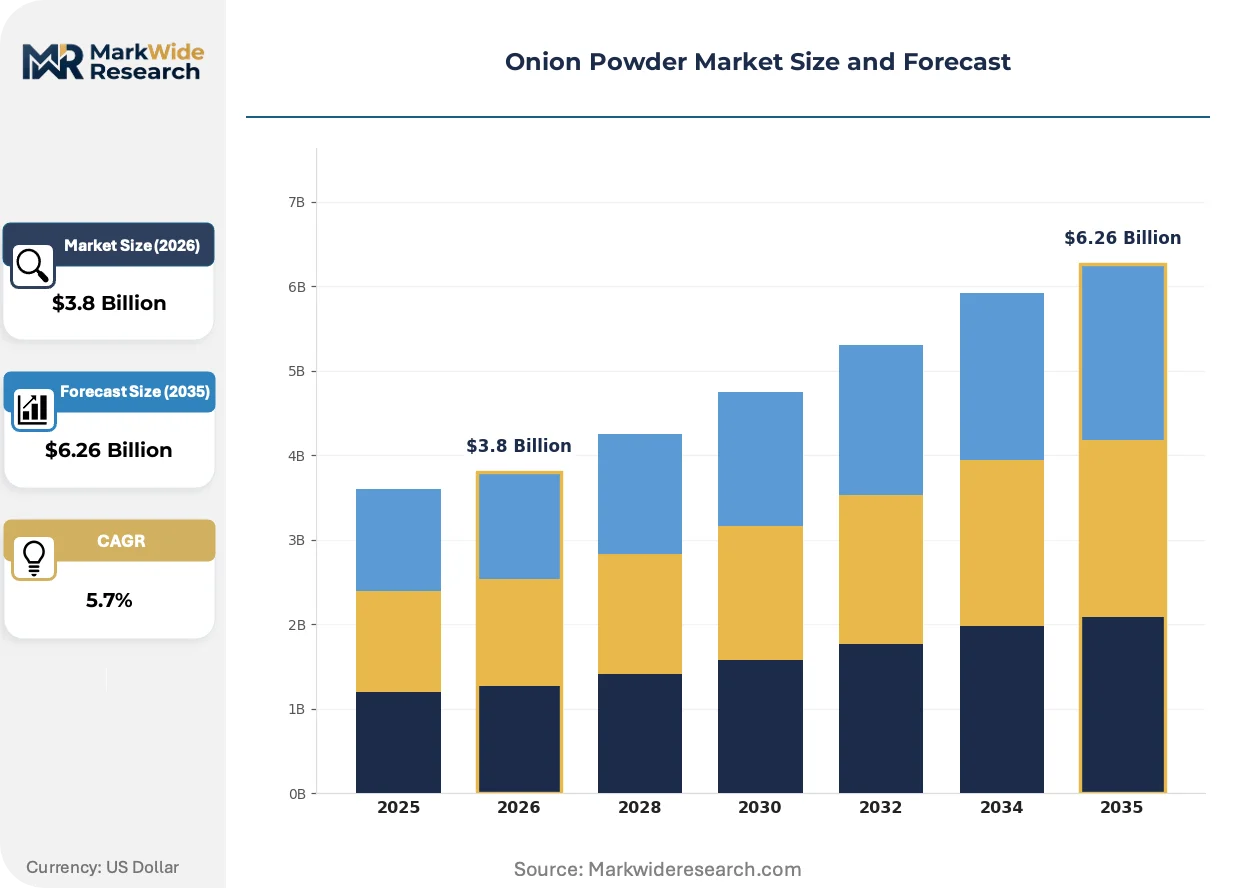
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granulated Onion Powder, Dehydrated Onion Powder, Onion Flakes, Onion Granules End User: Food Processing, Restaurant Chains, Retail, Households Packaging Type: Bags, Pouches, Jars, Bulk Containers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Jain Farm Fresh Foods Ltd., BCFoods Europe B.V., Olam Food Ingredients, Real Dehydrates Pvt. Ltd., Silva, McCormick & Company, Inc., ShunDi Foods, Adegermex S.A. de C.V., Natural Dehydrated Vegetables Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Onion Powder Market Strategic Shifts & Innovations
Dehydration technology and procurement centralization are reshaping competitive advantage toward integrated supply chains with certified food safety infrastructure and flexible format capabilities.
Near-infrared spectroscopy is automating real-time moisture monitoring during drying cycles. Industrial soup manufacturers deploying this technology reduce batch rejection rates and compress quality assurance labor. The standardization of inline testing is automating compliance documentation for export shipments to multiple regulatory jurisdictions.
REACH registration requirements for imported food contact substances are tightening documentation burdens on European dehydration facilities sourcing processing aids from Asian chemical suppliers. The regulation forces reformulation of anti-caking coatings and accelerates substitution toward mineral-based alternatives. German and Dutch industrial seasoning blenders are most affected, consolidating supplier qualification lists to pre-registered chemical vendors.
Annual contracting with fixed-volume commitments is displacing spot-market purchasing among North American quick-service chains. Procurement departments negotiate eighteen-month supply agreements with penalty clauses for specification deviation, transferring inventory risk to dehydration processors. This shift is most visible in contract structures governing supply to centralized distribution centers serving franchise networks across the United States and Canada.
Onion Powder Market Segmentation
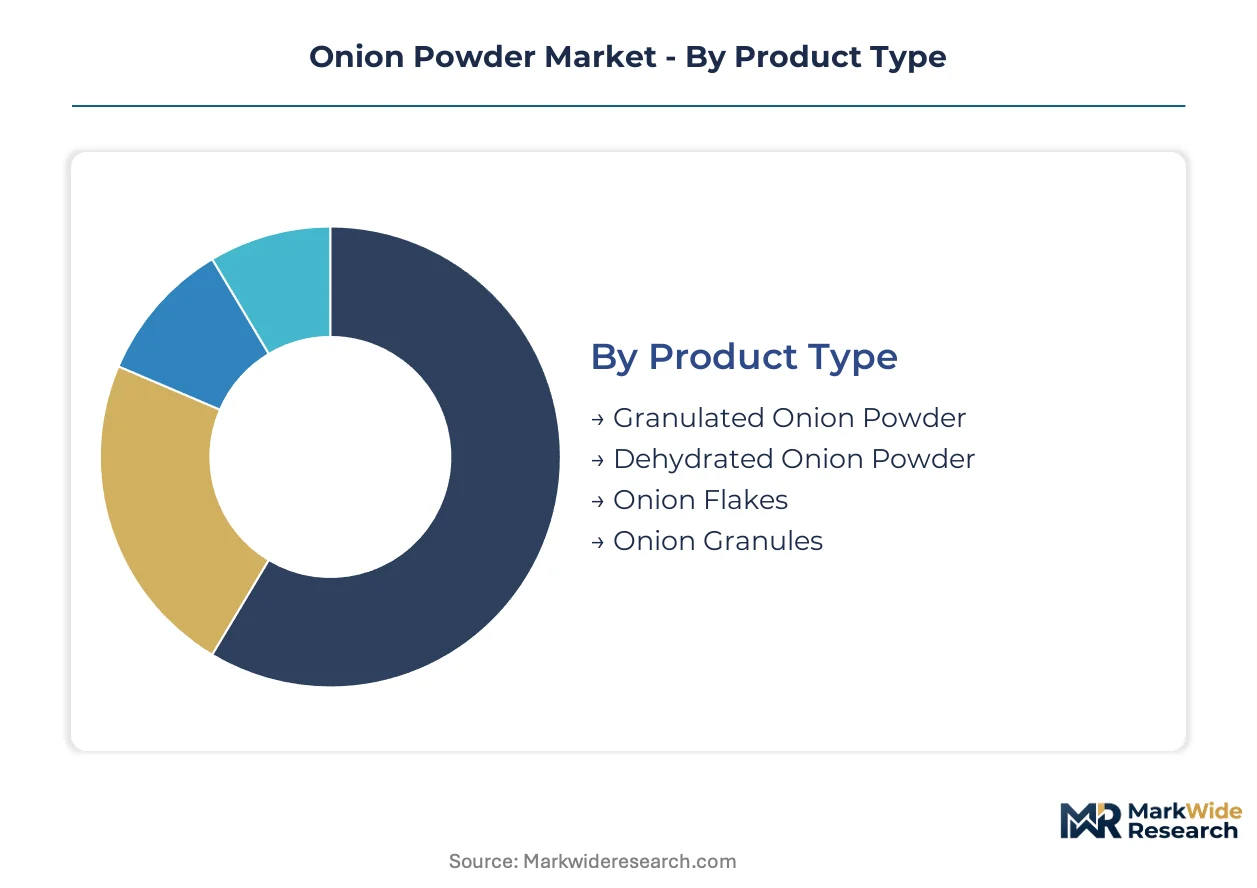
Onion powder procurement patterns diverge sharply across product formats and end-use channels, with industrial buyers prioritizing moisture specifications and traceability certifications while retail channels emphasize packaging shelf appeal and clean-label positioning.
Product Type:
FDA and FSSAI preventive controls apply uniformly across all formats, though granulated variants face additional particle-size validation for foodservice texture requirements.
- Dehydrated Onion Powder:Finely milled concentrate with moisture content below six percent achieves uniform dispersibility in dry seasoning blends. Food processing facilities in the United States and India concentrate procurement volumes here, driven by extended shelf stability mandates and centralized manufacturing of packaged meals.
- Granulated Onion Powder:Coarse-cut particles retain visible texture for foodservice applications. Quick-service operators specify this format for burger toppings and sandwich builds, substituting fresh-prep labor with standardized flavor delivery.
- Onion Flakes:Larger dehydrated pieces command premium positioning in European retail channels for visible-ingredient applications.
- Onion Granules:Intermediate particle size bridges powder and flake categories for soup manufacturers requiring rapid rehydration.
Dehydrated onion powder sits at the top of the volume ranking, with granulated onion powder climbing the fastest.
End User:
Cost tier separation drives procurement centralization, with multinational chains negotiating multi-year contracts while household buyers remain price-sensitive and fragmented.
- Food Processing:Industrial soup, sauce, and seasoning manufacturers dominate procurement volumes, specifying moisture tolerances within narrow bands and demanding HACCP-validated supplier certifications. EFSA mycotoxin thresholds constrain European sourcing eligibility.
- Restaurant Chains:Quick-service and fast-casual operators are eliminating fresh-prep stations, converting to dehydrated formats for flavor standardization across franchise networks. This segment expands most quickly as labor costs rise.
- Retail:North American natural and conventional grocery channels stock clean-label single-ingredient powders without anti-caking agents.
- Households:Small-format pouch purchases concentrate in price-sensitive emerging markets with limited cold-chain infrastructure.
Food processing commands the largest procurement scale, with restaurant chains gaining share fastest.
Packaging Type:
Application context dictates format selection, with moisture barrier properties and dispensing convenience determining industrial versus retail suitability.
- Bulk Containers:Food-grade totes and drums serve industrial dehydration processors shipping to centralized distribution centers. Gujarat and Maharashtra export clusters favor containerized bulk for European buyers.
- Bags:Multi-wall paper sacks with polyethylene liners balance cost and moisture protection for mid-volume foodservice procurement.
- Pouches:Stand-up flexible packaging dominates North American retail shelf placement with resealability features.
- Jars:Glass containers command premium positioning in specialty retail and gift segments with visibility marketing.
Bulk containers lead industrial volume, with pouches expanding most quickly in retail channels.
Distribution Channel:
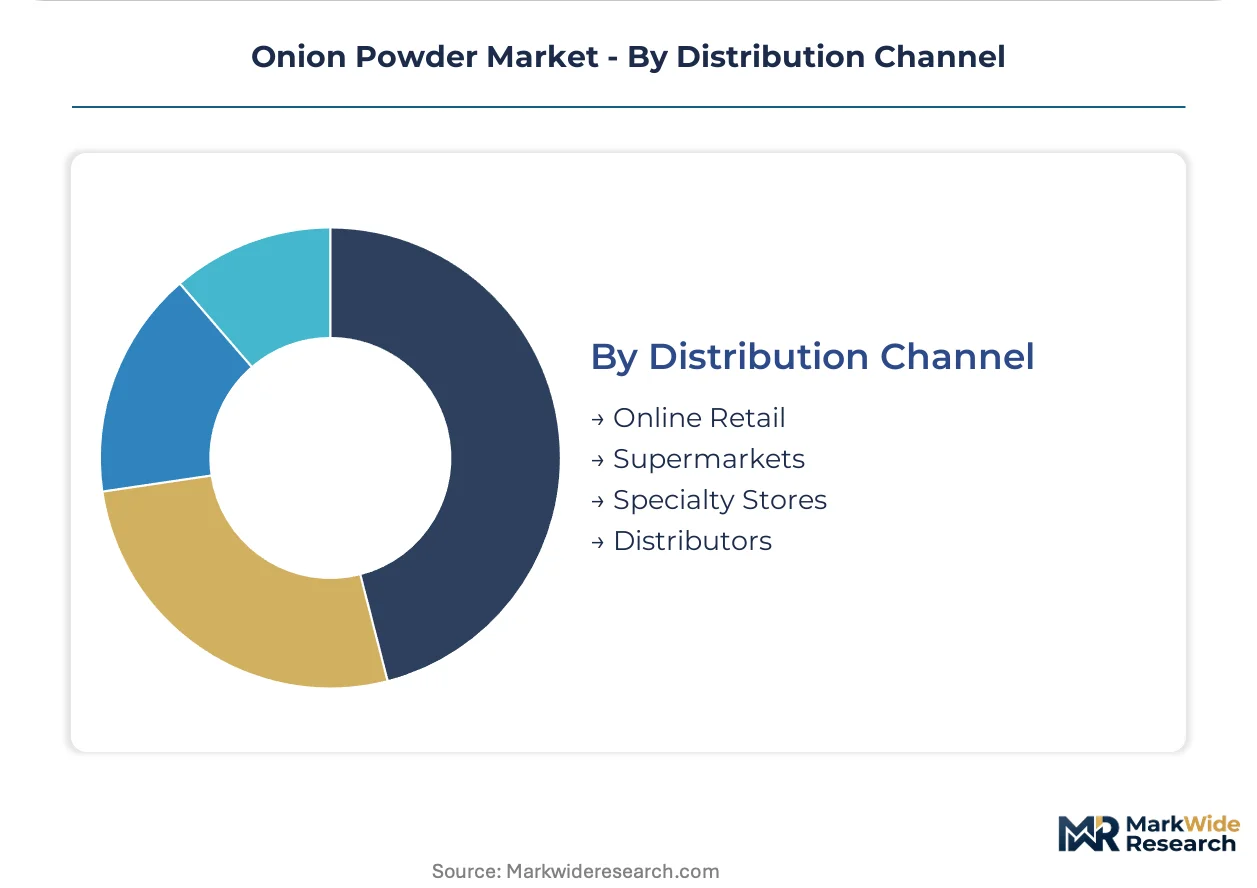
Customer scale and specification complexity determine channel selection, with large processors bypassing intermediaries while smaller buyers rely on distributor technical support.
- Distributors:Industrial ingredient distributors consolidate shipments from India and Egypt to European and North American food manufacturers, managing documentation for multi-jurisdiction traceability requirements.
- Online Retail:Direct-to-consumer platforms capture household and small-restaurant demand for specialty formats, accelerating in North American metropolitan markets.
- Supermarkets:Mass retail chains in the United States and Canada stock national-brand and private-label jars and pouches.
- Specialty Stores:Natural and organic retailers emphasize clean-label single-ingredient positioning with transparent supply chain claims.
Distributors handle the largest procurement volumes, with online retail climbing fastest among emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized dehydration engineers and food safety compliance officers cluster in Gujarat and Maharashtra, anchoring India's export capacity expansion while European processors recruit talent for mycotoxin laboratory validation.
United States
Quick-service restaurant chains drive procurement centralization through eighteen-month fixed-volume contracts. FDA enforcement of FSMA preventive controls mandates HACCP-validated drying systems for import eligibility. Chicago and Dallas distribution centers consolidate shipments from Indian and Egyptian suppliers to franchise networks.
India
Gujarat and Maharashtra dehydration clusters scale containerized shipping capacity to capture European buyers diversifying sourcing. FSSAI traceability protocols tighten documentation burdens on mid-tier processors lacking ERP integration. The PLI scheme for food processing subsidizes capital equipment, reducing payback periods for compliant dehydration investors.
Germany
Industrial seasoning blenders face REACH registration requirements for processing aids sourced from Asian chemical suppliers. EFSA mycotoxin thresholds for dried vegetables block entry for facilities lacking in-house chromatography testing. Hamburg and Rotterdam ports manage consolidated ingredient shipments from India and Egypt.
Egypt
Nile Delta irrigation constraints create input cost instability for non-integrated onion processors. The country's national food safety regulator tightens export certification requirements for European market access. Cairo and Alexandria dehydration facilities compete with Indian clusters for contract volumes.
Netherlands
Rotterdam serves as the primary European entry point for containerized dehydrated vegetable imports from India and Egypt. EFSA aflatoxin limits constrain supplier pool expansion to certified facilities with laboratory testing capabilities. Dutch industrial soup manufacturers specify low-moisture granulation formats from validated dehydration processors.
Onion Powder Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across procurement tiers. The vendor base separates into three layers: multinational ingredient platforms with captive farm networks, regional dehydration processors with certified laboratory infrastructure, and commodity traders lacking backward integration. Two strategic archetypes dominate—integrated supply chain operators securing multi-year contracts, and format-specialized processors serving industrial texture requirements. Competitive moves concentrate on capacity expansion in Gujarat and Maharashtra, and strategic partnerships with quick-service distribution centers.
Within the integrated supply chain tier, Olam Food Ingredients and Jain Farm Fresh Foods Ltd. exemplify archetypes combining farm-level sourcing with dehydration capacity. BCFoods Europe B.V. occupies a position among format-specialized European processors. McCormick & Company, Inc. anchors North American shelf-stable seasoning demand through proprietary processing infrastructure.
| Leading Market Players |
|---|
| Jain Farm Fresh Foods Ltd. |
| BCFoods Europe B.V. |
| Olam Food Ingredients |
| Real Dehydrates Pvt. Ltd. |
| Silva |
| McCormick & Company, Inc. |
| ShunDi Foods |
| Adegermex S.A. de C.V. |
| Natural Dehydrated Vegetables Pvt. Ltd. |
| Others |
Cost & Logistics Intelligence
Centralized procurement by multinational quick-service operators is compressing supplier margins and forcing dehydration processors to reconfigure production lines for multi-format output, which in turn hardens price floors for smaller buyers lacking volume leverage.
Pricing Analysis
Capacity additions in Gujarat and Maharashtra are reshaping price floors across export tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation anchored in HACCP certification status and moisture specification precision. Price differentiation reflects FSSAI traceability compliance and captive bulb sourcing depth. Cost compression in economy-grade powder is intensifying because Egyptian processors compete aggressively on Nile Delta harvest volumes. Quick-service chains show least price sensitivity due to fixed-volume contract structures, while emerging market households remain most vulnerable to pass-through volatility.
Supply Chain Analysis
Reverse-logistics flows for rejected moisture-specification batches return to Gujarat dehydration clusters for reprocessing into animal feed or lower-grade industrial inputs, reducing waste recovery costs. Supply concentrates in India, Egypt, and the Netherlands, with raw material flows drawing from Maharashtra onion cultivation, Nile Delta bulb harvests, and European re-export processing. The chain rests on sulfur compound volatility, irrigation water availability, and containerized shipping slot access. Single-source vulnerability concentrates in monsoon-dependent Maharashtra harvests. Distribution runs through Rotterdam and Hamburg port consolidation to European industrial seasoning blenders, with Chicago and Dallas distribution centers serving North American quick-service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where restaurant chain procurement departments now mandate HACCP-validated drying systems and sub-six-percent moisture guarantees, elevating certified processors above commodity suppliers.
For Market Incumbents: Cement multi-year contract renewals with quick-service distribution centers before Gujarat capacity expansions reach full output. Lock in backward integration into Maharashtra bulb cultivation to insulate input costs from monsoon volatility. Invest in near-infrared spectroscopy inline testing to reduce batch rejection penalties under tightening FDA preventive controls. For New Entrants and Emerging Players: Specialty natural retailers seeking clean-label single-ingredient powders without anti-caking agents represent an underserved buyer archetype with shelf-space premiums available. Target North American metropolitan online retail channels for direct-to-consumer stand-up pouch formats. Pursue white-label manufacturing partnerships with established dehydration processors lacking retail packaging capabilities. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier Indian dehydration processors holding FSSAI certifications and PLI scheme equipment subsidies but lacking ERP traceability integration for European export eligibility. Five-to-ten-year viability favors facilities with laboratory mycotoxin testing and captive cold storage. Monitor EFSA aflatoxin threshold enforcement actions as inflection indicator for supplier pool consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bulb Cultivation | Maharashtra farm acquisitions reduce input cost volatility from monsoon yield fluctuations. |
| HACCP Certification Investment | FDA preventive controls disqualify uncertified processors, consolidating volume among compliant facilities. |
| Near-Infrared Spectroscopy Deployment | Inline moisture monitoring reduces batch rejection rates for industrial soup manufacturers. |
| Clean-Label Format Development | Single-ingredient powders without anti-caking agents command shelf-space premiums in natural retail. |
| ERP Traceability Integration | Multi-jurisdiction lot-tracking compliance opens European export eligibility beyond commodity traders. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dehydration plant managers, quick-service procurement directors, FSSAI compliance officers, and European industrial seasoning blenders with secondary validation from FDA enforcement records, EFSA mycotoxin threshold documentation, Indian customs export data, and SEC filings from listed ingredient processors. Bottom-up volume estimates from Gujarat and Maharashtra capacity utilization triangulated against top-down demand segmentation from food processing facility procurement surveys.
Historical reference periods anchored the forecast window to pre-pandemic baseline volumes and post-FSMA implementation compliance cost structures across the analysis window. Segmentation dimensions modeled include product format granularity, moisture specification tier, end-use channel concentration, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand projections incorporating spray drying technology diffusion rates and quick-service labor substitution trajectories.
Underlying measurement precision varies by segment; food processing procurement volumes carry tighter precision than household retail consumption estimates. Forecasts reflect assumptions regarding FSSAI traceability enforcement intensity and EFSA mycotoxin threshold stability. Practitioners should monitor PLI scheme subsidy disbursement rates and Rotterdam port container slot availability for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Mullein Leaf Market
Spices and Seasonings
Global Oregano Essential Oil Market
Spices and Seasonings
Europe Seasoning Market
Spices and Seasonings
Boutique Salt Market
Spices and Seasonings
North America Seasonings Market
Spices and Seasonings
Kosher Salt Market
Spices and Seasonings
Smoked Black Pepper Market
Spices and Seasonings
Organic Spices and Herbs Market
Spices and Seasonings
Organic Saffron Market
Spices and Seasonings
Paprika Powder Market
Spices and Seasonings
Lemon Salt Market
Spices and Seasonings
Vanilla Salt Market
Spices and Seasonings
Cinnamon Market
Spices and Seasonings
Chipotle Salt Market
Spices and Seasonings
North American Seasonings and Spices Market
Spices and Seasonings
Turmeric Oleoresin Market