
 Vanilla Salt Market | 2026-2036
Vanilla Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Vanilla Salt Market Analytics
Gourmet restaurants and artisan bakeries is rotating toward vanilla salt as a signature finishing ingredient, displacing conventional table salt in premium plating applications. McCormick leverages its retail distribution network to sustain shelf presence across mainstream supermarkets. SaltWorks, Inc. anchors the North American specialty salt segment through direct sourcing relationships with Pacific Northwest vanilla bean suppliers. Cargill competes on manufacturing scale, operating integrated evaporation facilities that control bulk supply costs.
Vanilla salt is a flavored crystalline seasoning produced by infusing natural or synthetic vanilla compounds with sodium chloride, typically achieving particle sizes between 0.3 mm and 3 mm depending on intended application. The product serves commercial kitchens and retail consumers seeking aromatic enhancement without liquid extract handling. Fine grain formulations lead household penetration due to uniform dissolution in baking applications, while coarse variants command margin premiums in garnishing channels where visual texture drives plate presentation. The food service distribution channel represents the fastest-growing structural segment as independent restaurants build direct supplier relationships bypassing traditional wholesale intermediaries.
The FDA maintains food additive safety standards governing vanilla-derived flavoring compounds in salt-based products, while USDA organic certification requirements constrain sourcing for premium tier suppliers. ISO 22000 food safety management systems increasingly function as baseline market access credentials for export-oriented producers. Stakeholders must monitor evolving clean-label definitions and vanilla bean origin traceability mandates as procurement criteria harden across European and North American buyer bases.
Market Dynamics
Clean-label certification requirements and vanilla bean origin traceability mandates are compressing supplier margins while reshaping procurement criteria across premium food service channels. These compliance pressures are accelerating consolidation among specialty salt producers who lack direct sourcing relationships with Pacific Northwest vanilla bean suppliers.
Growth Catalysts
- USDA Organic Certification:Premium tier suppliers leverage organic credentials to command shelf price premiums in California's specialty food corridor, where direct-to-chef distribution channels favor credentialed producers.
- Artisan Bakery Expansion:Independent bakeries in urban food hubs are building direct supplier relationships that bypass traditional wholesale intermediaries, creating pull-through demand for coarse-grain garnishing formulations.
- Fine Grain Formulation:Uniform dissolution properties in baking applications are driving household penetration, particularly among home bakers seeking aromatic enhancement without liquid extract handling complexity.
Market Restraints
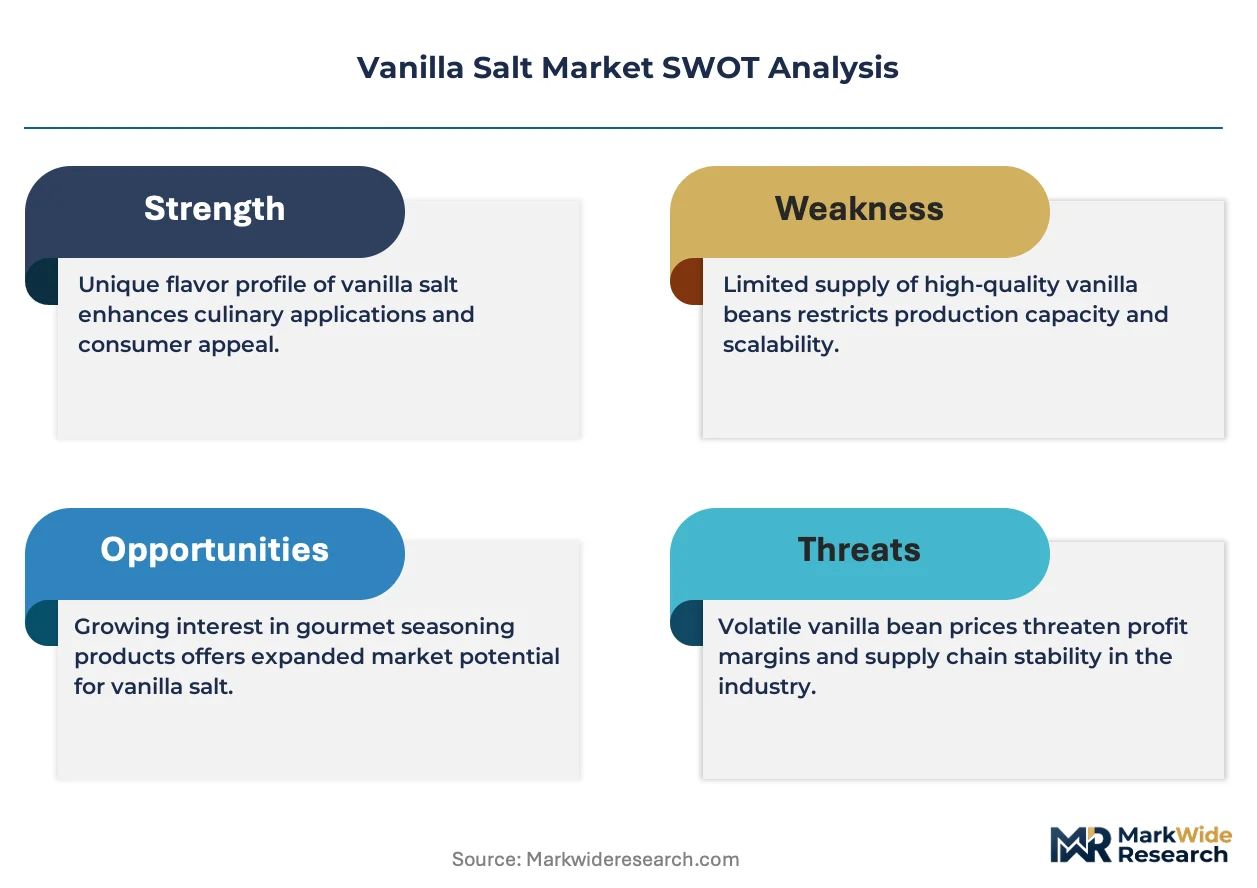
- Vanilla Bean Price Volatility:Madagascar and Indonesia supply concentration exposes processors to cyclical crop failures and speculative commodity swings that compress blending margins.
- FDA Food Additive Scrutiny:Synthetic vanillin compound restrictions in salt-based products force reformulation investments that disadvantage smaller producers lacking in-house regulatory affairs capacity.
- Sea Salt Substitution:Himalayan and Celtic salt variants with inherent mineral complexity are capturing premium positioning without flavor additive compliance burdens.
Strategic Opportunities
- Direct-to-Consumer Subscription:Specialty food e-commerce platforms enable bypass of retail slotting fees while capturing recurring revenue from enthusiast home cooks seeking limited-batch releases.
- ISO 22000 Export Credentialing:Food safety management certification opens European Union and Japanese market access where origin traceability mandates exceed domestic requirements.
- Coarse-Grain Food Service Partnerships:Visual texture-driven plate presentation demand in independent restaurants creates margin expansion potential for garnishing-channel specialists.
Industry Challenges
- Vanilla Bean Authentication Expertise:Shortage of analytical chemists capable of distinguishing natural from synthetic compounds slows clean-label verification timelines and extends product launch cycles.
- Evaporation Facility Capex:Integrated sodium chloride production requires significant capital deployment for solar evaporation infrastructure that smaller flavor houses cannot finance independently.
- Multi-Jurisdiction Label Harmonization:Divergent FDA, EFSA, and FSSAI additive definitions force SKU proliferation that fragments production runs and elevates inventory carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vanilla Salt Market |
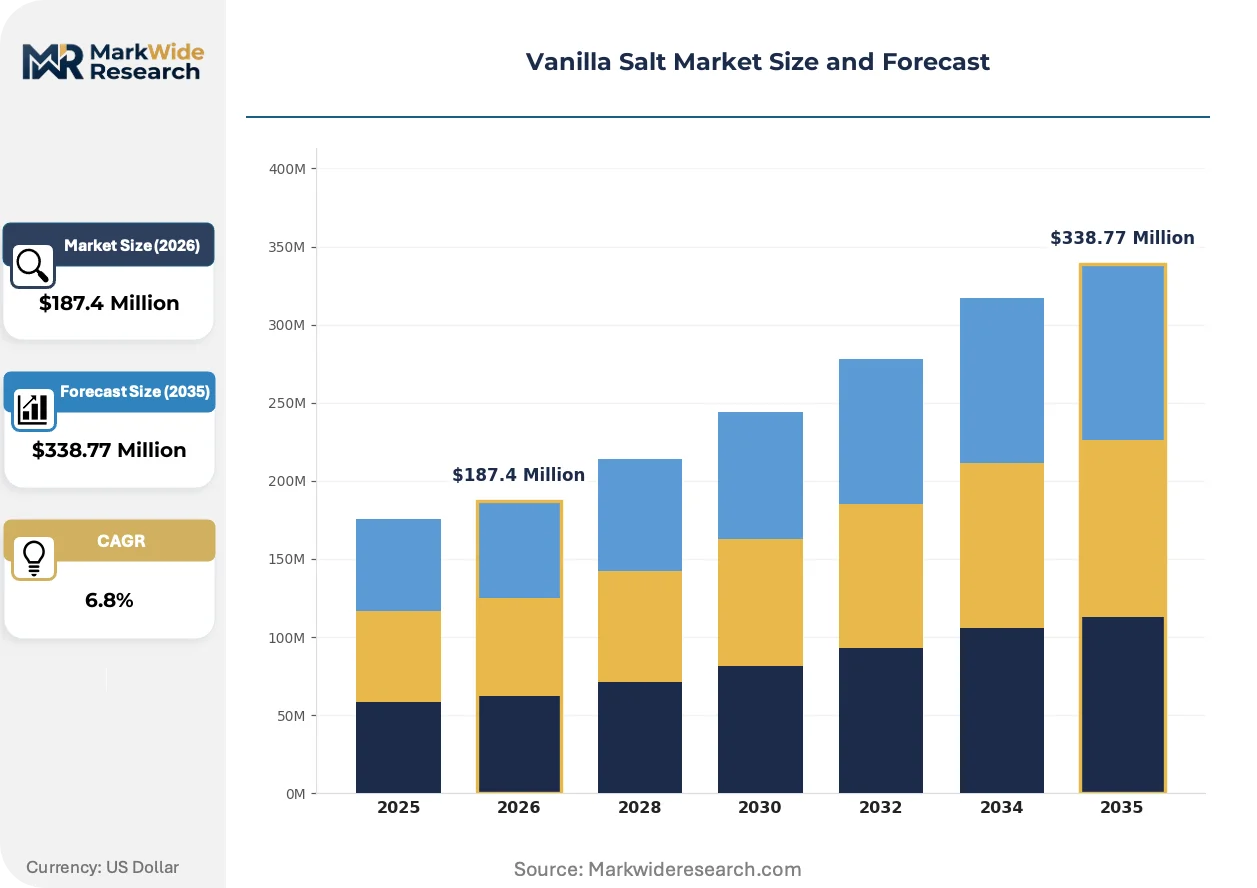
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coarse, Fine, Flavored, Organic Application: Baking, Cooking, Seasoning, Garnishing Distribution Channel: Online, Supermarkets, Specialty Stores, Food Service End User: Households, Restaurants, Bakeries, Gourmet Shops |
| Companies Covered | Artisan Salt Company, McCormick, SaltWorks, Inc., Compass Minerals, Cargill, The Spice Lab, San Francisco Salt Co., K+S Aktiengesellschaft, Hepp’s Salt Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vanilla Salt Market Evolving Landscape
Spray-dried vanilla infusion technology is reshaping production economics by enabling precise compound distribution across variable crystal geometries. These process innovations are compressing the traditional maceration timeline while expanding formulation flexibility for industrial-scale blenders.
Cryogenic grinding of whole vanilla pods is supplanting liquid extract absorption methods in premium product lines. Gourmet restaurant kitchens in New York and San Francisco are adopting these aromatically intact formulations for finishing applications where heat degradation previously compromised flavor intensity. The technology is enabling shorter production cycles that align with just-in-chef procurement patterns.
EFSA clean-label guidance on natural flavoring definitions is tightening compound disclosure requirements for European Union market entry. Blenders must now substantiate extraction method claims through third-party laboratory verification, elevating documentation costs for export-oriented North American producers. Small-batch specialists are responding by pursuing Protected Geographical Indication partnerships with vanilla cooperatives.
Chef-driven specification is displacing distributor-mediated procurement in high-end food service channels. Independent restaurants in California's specialty food corridor are contracting directly with Pacific Northwest vanilla bean suppliers for custom salt co-development. This disintermediation is most visible in Los Angeles and San Francisco, where tasting-menu establishments publish sourcing provenance as menu narrative.
Vanilla Salt Market Segmentation
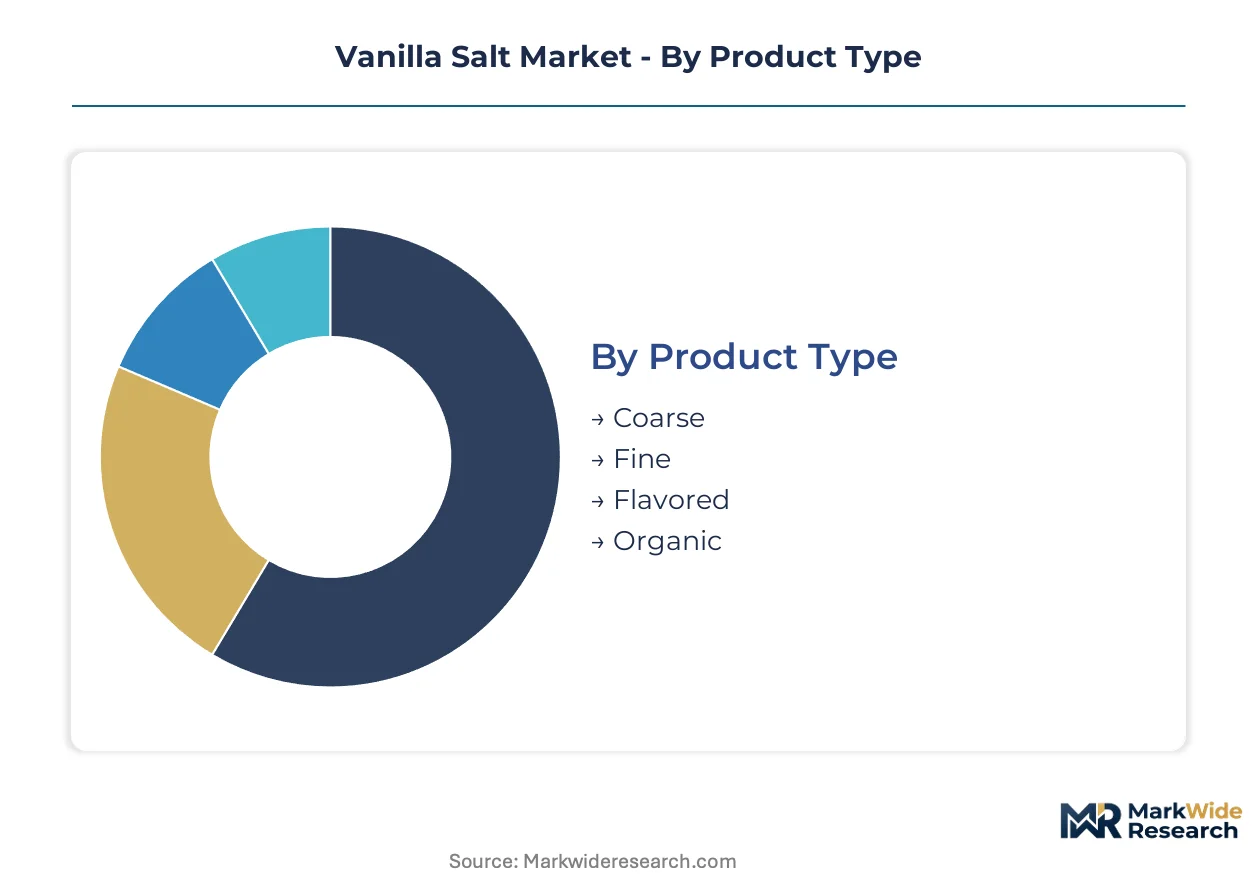
Segmentation in vanilla salt reveals how substitution pressures from unflavored premium salts and extract-based flavoring systems concentrate risk in specific product tiers. Each dimension exposes different vulnerability points to Himalayan salt displacement and synthetic vanillin cost competition.
Product Type:
Coarse and fine grain formulations face the strongest substitution threat from mineral-complex sea salts that deliver visual or textural differentiation without flavor additive compliance burdens.
- Coarse:Crystalline structures ranging 2-3 mm retain aromatic compounds through lower surface-area exposure. Gourmet restaurants in California's specialty food corridor specify these formulations for finishing applications where plate presentation drives procurement decisions.
- Fine:Particles below 0.5 mm achieve rapid dissolution in baking batters and doughs. Household penetration concentrates among home bakers seeking aromatic enhancement without liquid extract handling complexity.
- Flavored:Compound-infused variants beyond pure vanilla face direct competition from liquid extract systems that offer dosing flexibility.
- Organic:USDA-certified production carries traceability documentation requirements that constrain sourcing to specific vanilla bean cooperatives.
Fine grain anchors the volume base while coarse formulations gain share at the steepest rate.
Application:
Margin structures diverge sharply across use cases, with heat-exposed applications demanding more stable compound formulations than ambient finishing uses.
- Baking:Thermal degradation of volatile vanilla compounds during oven exposure requires encapsulated or spray-dried formulations. Artisan bakeries in urban food hubs drive specification for uniform dissolution properties.
- Cooking:Stovetop applications expose salt to moisture and temperature gradients that accelerate flavor compound loss. Restaurant kitchens prioritize batch-to-batch consistency over intensity peaks.
- Seasoning:Tabletop use competes directly with grinder-based whole bean systems that offer perceived freshness.
- Garnishing:Visual texture requirements favor coarse crystals with intact pod flecking visible to diners.
Seasoning maintains the broadest installed base while garnishing climbs fastest among premium food service channels.
Distribution Channel:
Channel selection determines compliance burden intensity, with food service bypassing retail label requirements while assuming chef-driven specification risk.
- Online:Direct-to-consumer subscription models enable limited-batch releases without slotting fee structures. Specialty food e-commerce platforms capture recurring revenue from enthusiast home cooks.
- Supermarkets:McCormick-scale retail networks demand standardized packaging and extended shelf stability that constrain formulation innovation.
- Specialty Stores:Curated assortments favor provenance storytelling and origin traceability documentation.
- Food Service:Direct supplier relationships bypass wholesale intermediaries, compressing lead times for independent restaurants.
Supermarkets dominate absolute volume throughput while food service expands most quickly.
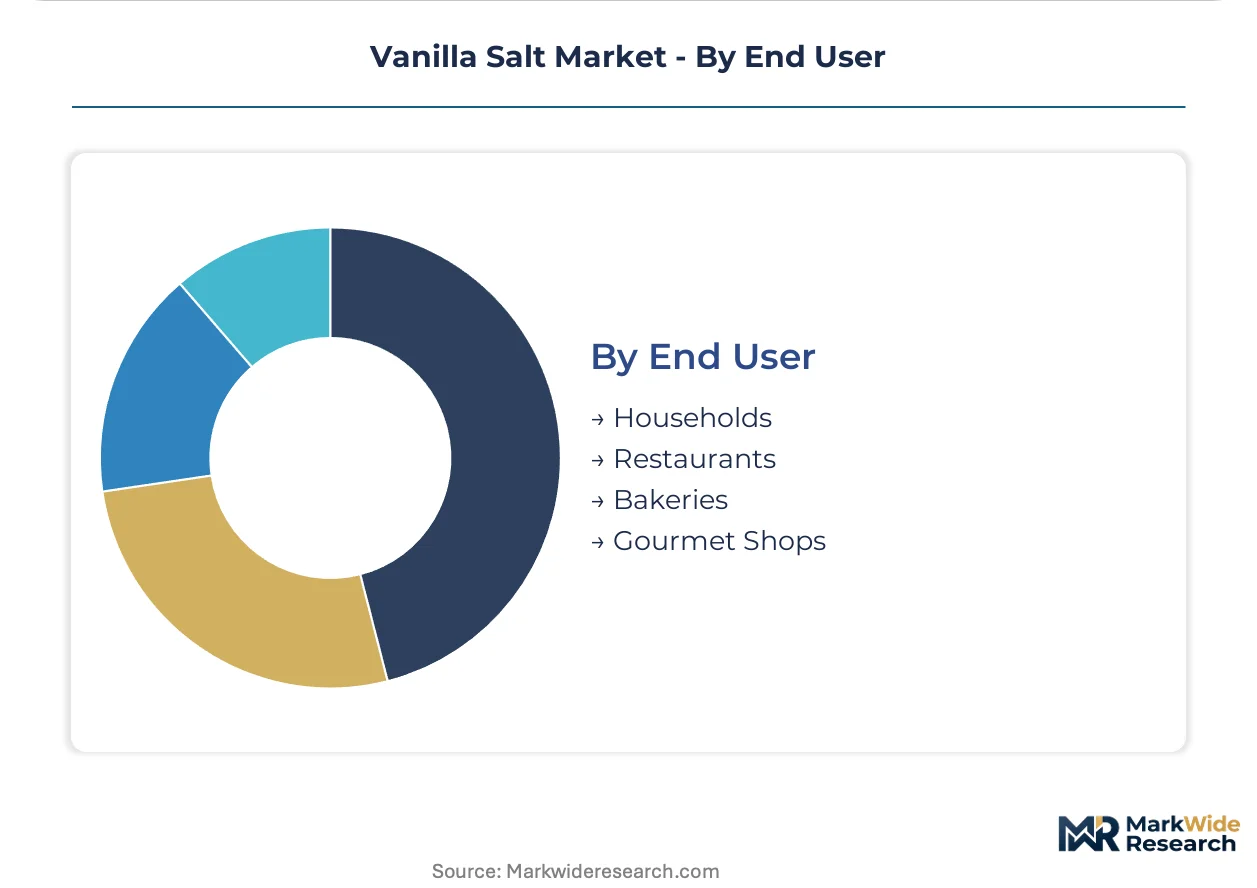
End User:
Procurement sophistication varies dramatically, with commercial kitchens conducting organoleptic validation that household purchasers cannot replicate.
- Households:Price-sensitive occasional use concentrates in fine grain formats for baking applications. Clean-label certification influences purchase decisions less than convenience positioning.
- Restaurants:Independent tasting-menu establishments in Los Angeles and San Francisco contract directly with Pacific Northwest vanilla bean suppliers for custom co-development.
- Bakeries:Production-scale procurement favors consistent granulation for automated dosing equipment.
- Gourmet Shops:Curated retail assortments command margin premiums through exclusive sourcing relationships.
Households provide the volume foundation while restaurants drive specification innovation at the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Oakland's cold-chain infrastructure underwrites California's dominance in specialty food distribution, connecting Pacific Northwest vanilla bean suppliers to Los Angeles and San Francisco tasting-menu establishments through direct-to-chef logistics channels.
United States
California's specialty food corridor concentrates procurement from independent restaurants building direct supplier relationships. FDA food additive regulations govern vanilla-derived flavoring compounds in salt-based products. Los Angeles and San Francisco tasting-menu establishments publish sourcing provenance as menu narrative, driving specification innovation.
Germany
Artisan bakeries in urban food hubs create pull-through demand for coarse-grain garnishing formulations with traceable origin documentation. EFSA clean-label guidance tightens compound disclosure requirements for natural flavoring definitions. Hamburg's specialty food import clusters coordinate Pacific Northwest vanilla bean sourcing for premium tier distribution.
France
Gourmet restaurants specify coarse crystalline structures for finishing applications where plate presentation drives procurement decisions. ANSM and DGCCRF enforce additive safety standards parallel to FDA frameworks. Parisian tasting-menu establishments contract directly with vanilla cooperatives for Protected Geographical Indication partnerships.
Japan
Household penetration concentrates among home bakers seeking aromatic enhancement without liquid extract handling complexity. METI and PMDA coordinate food safety management requirements exceeding domestic U.S. standards. Tokyo's specialty retail corridors curate provenance storytelling for enthusiast consumer segments.
United Kingdom
Specialty food e-commerce platforms capture recurring revenue from enthusiast home cooks seeking limited-batch releases. FSA maintains additive regulations aligned with evolving EFSA guidance. London's restaurant procurement clusters disintermediate wholesale intermediaries through direct supplier contracting.
Vanilla Salt Market Competitive Landscape
Concentration sits with diversified food ingredient conglomerates and specialty salt specialists. The vendor base spans three tiers: multinational agricultural processors with integrated evaporation infrastructure, mid-cap regional blenders with direct vanilla bean sourcing relationships, and artisan micro-producers serving chef-driven channels. Competitive positioning hardens around backward integration into Pacific Northwest vanilla supply, ISO 22000 credentialing for export access, and direct-to-chef distribution bypassing wholesale intermediaries. M&A activity targets specialty salt producers lacking regulatory affairs capacity, while capacity expansion concentrates in solar evaporation facilities controlling bulk sodium chloride costs.
Among U.S.-based specialists, SaltWorks, Inc. and San Francisco Salt Co. occupy positions within the premium-tier direct-sourcing archetype, exemplifying the direct-to-chef distribution model that bypasses traditional wholesale channels. McCormick represents the diversified conglomerate tier with retail network scale, anchoring mainstream supermarket penetration through standardized shelf presence. These three entities illustrate the competitive tension between specialty provenance positioning and mass-market volume throughput.
| Leading Market Players |
|---|
| Artisan Salt Company |
| McCormick |
| SaltWorks, Inc. |
| Compass Minerals |
| Cargill |
| The Spice Lab |
| San Francisco Salt Co. |
| K+S Aktiengesellschaft |
| Hepp's Salt Co. |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day vanilla bean curing cycles compress procurement windows and amplify spot-market exposure for North American blenders, concentrating pricing power among Pacific Northwest suppliers with direct cooperative relationships while forcing secondary processors into cost-pass-through structures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates USDA-certified organic formulations from conventional blends and synthetic-vanillin economy grades. Price differentiation rests on origin traceability documentation and ISO 22000 credential status. Cost compression in the standard tier is intensifying because Madagascar supply volatility forces hedging premiums. Household purchasers exhibit highest price sensitivity, while Los Angeles tasting-menu establishments absorb premiums for provenance-verified coarse crystals.
Supply Chain Analysis
Madagascar vanilla bean export licensing functions as the primary chokepoint, constraining annual flow volumes and amplifying spot-price volatility for processors lacking forward-contract coverage. Raw material sourcing draws from Madagascar, Indonesia, and Papua New Guinea pod harvests. Sodium chloride feedstock relies on Utah solar evaporation facilities and Chilean coastal operations. Single-source vulnerability in Madagascar bourbon vanilla exposes blenders to cyclical crop failure. Distribution runs through direct-to-chef channels in California's specialty food corridor alongside conventional food service wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as vanilla bean harvests normalize following Madagascar drought stress, with procurement patterns adjusting to rebuilt inventory positions across Pacific Northwest supplier networks.
For Market Incumbents: Consolidate backward integration into Pacific Northwest vanilla cooperatives to secure origin-traceable supply ahead of tightening EFSA disclosure requirements. Expand ISO 22000-credentialed capacity for Japanese and EU export qualification. Defensive positioning against Himalayan salt substitution demands amplified provenance storytelling through chef partnership programs. For New Entrants and Emerging Players: Anchor in direct-to-consumer subscription channels where retail slotting fees do not barrier entry, targeting enthusiast home bakers in urban food hubs. Cryogenic grinding technology differentiation offers white-space positioning against maceration-based incumbents. Food service bypass models in secondary cities present underexploited procurement relationships. For Investors and Strategic Acquirers: Long-term, this sits as a specialty-ingredient consolidation play because clean-label compliance burdens favor scaled regulatory affairs capacity over artisan micro-producers. Acquisition targets should display direct vanilla bean sourcing relationships and existing chef-channel contracts. Monitor vanilla bean futures spread compression as inflection signal for margin recovery timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vanilla Cooperatives | Pacific Northwest direct sourcing secures traceability documentation required by EFSA disclosure mandates. |
| Cryogenic Grinding Technology Deployment | Aromatically intact formulations command chef premiums in Los Angeles and San Francisco tasting-menu establishments. |
| ISO 22000 Certification Investment | Food safety management credentials unlock Japanese and European Union market access beyond domestic channels. |
| Direct-to-Consumer Subscription Launch | Specialty food e-commerce platforms bypass supermarket slotting fees while capturing recurring enthusiast revenue. |
| Coarse-Grain Food Service Partnerships | Visual texture-driven plate presentation demand in independent restaurants creates margin expansion potential. |
Research Methodology
Initial hypotheses were tested against primary input from vanilla bean procurement managers, specialty salt blenders, chef-owners of tasting-menu restaurants, and food service distribution executives, and refined through secondary validation against FDA additive guidance filings, USDA organic certification databases, customs import records, and Pacific Northwest cooperative harvest reports. Bottom-up volume estimates from processor capacity utilization were triangulated against top-down category spending data.
Variance decomposition across product type, application method, distribution channel, and end-user sophistication tiers shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate synthesis. Forecast inputs incorporated vanilla bean futures curve positioning and solar evaporation facility capacity expansion timelines.
Decision-makers should treat outputs as directional under assumptions of normalized Madagascar harvest recovery and stable FDA additive definitions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EFSA clean-label guidance evolution and vanilla bean authentication technology disruption unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Saffron Market
Spices and Seasonings
Savoury Seasoning Market
Spices and Seasonings
Seasonings Market
Spices and Seasonings
Tamarind Extract Market
Spices and Seasonings
South America Spice and Herb Extracts Market
Spices and Seasonings
Peppermint Extract Market
Spices and Seasonings
Turkey Flavors Market
Spices and Seasonings
Serrata Extract Market
Spices and Seasonings
Moringa Leaves Powder Market
Spices and Seasonings
Oregano Oil Market
Spices and Seasonings
Low Sodium Sea Salt Market
Spices and Seasonings
Africa Seasoning and Spices Market
Spices and Seasonings
Chipotle Salt Market
Spices and Seasonings
Smoked Salt Market
Spices and Seasonings
Incense Sticks (Agarbatti) Market
Spices and Seasonings
Pepper Market