
 Seafood Powders Market | 2026-2036
Seafood Powders Market Size, Share, and Industry Trends Forecast 2026-2036
Seafood Powders Market Analytics
A capital-intensity divergence between integrated fishing conglomerates and specialized ingredient refiners is reorganizing competitive dynamics in seafood powders. Austevoll Seafood ASA leverages its fleet-to-factory pipeline to control raw material quality from catch to dried concentrate. Croda International Plc anchors its position through pharmaceutical-grade refinement capabilities that command premium positioning in nutritional applications. Omega Protein Corporation dominates menhaden-derived fishmeal supply chains across the Gulf of Mexico processing belt.
Seafood powders comprise dehydrated, milled, or extracted marine biomass processed to standardized protein, lipid, or mineral concentrations for industrial incorporation. Spray-drying at controlled inlet temperatures preserves thermolabile omega-3 fatty acids in fish oil powders destined for encapsulation. Fish powder leads volume throughput due to established supply chains from reduction fisheries, while shrimp powder commands margin premiums in savory flavor applications. Nutritional supplements represent the fastest-expanding application segment as clinical validation of marine bioactives deepens consumer willingness to pay for functional ingredients.
FDA oversees GRAS self-affirmation pathways for novel seafood-derived ingredients entering U.S. food and supplement channels, while EFSA mandates novel food authorization for non-traditional marine species in European applications. REACH compliance requirements govern residual solvent thresholds in extracted powder forms traded across EU member states. Stakeholders must monitor evolving maximum residue limits for heavy metals and histamine as regulatory science tightens safety benchmarks for marine-origin ingredients.
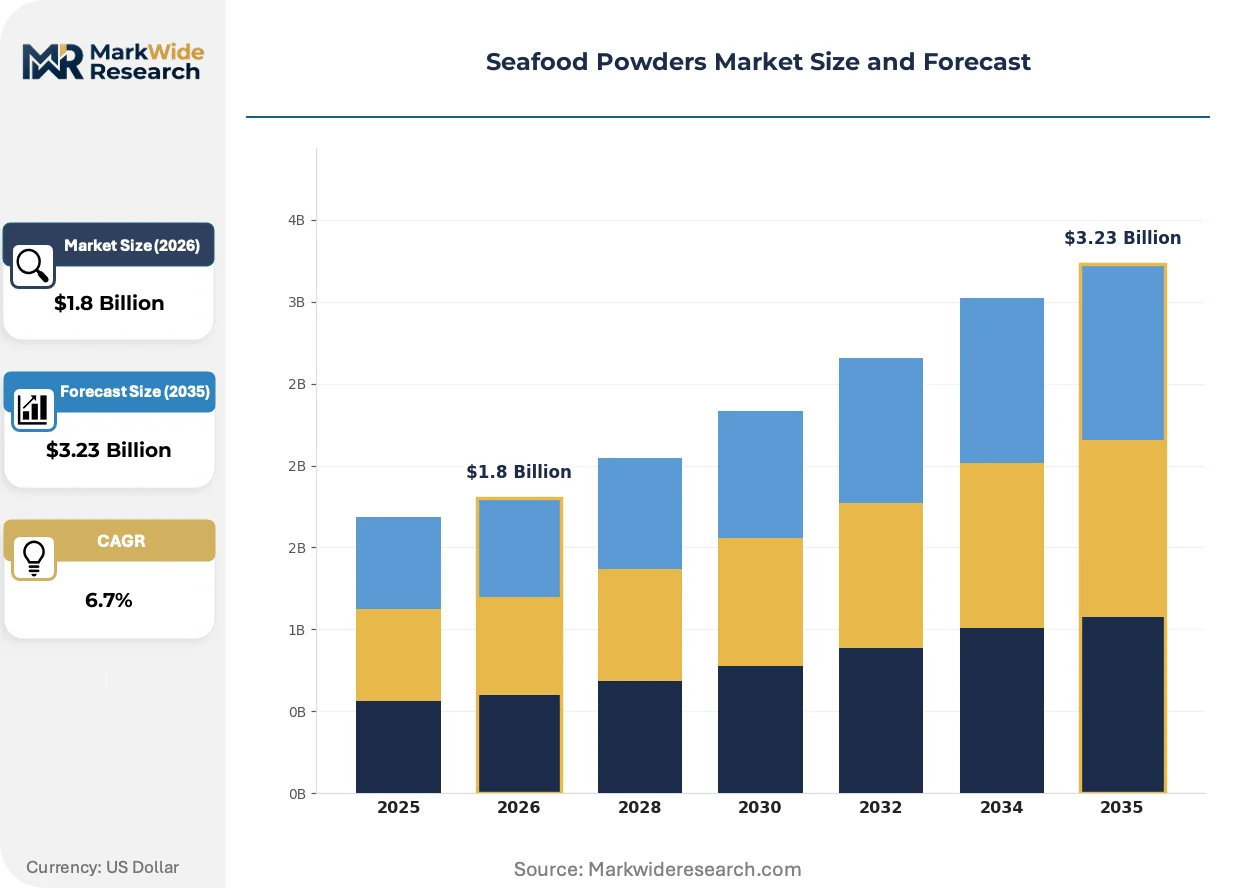
Market Dynamics
EU Green Deal sustainability mandates are forcing processors to revalidate entire supply chains for carbon footprint traceability, while spray-drying energy costs and menhaden stock volatility squeeze margin structures simultaneously.
Growth Catalysts
- Clinical validation of marine bioactives:Nutraceutical formulators are expanding omega-3 encapsulation programs as peer-reviewed studies on cardiovascular outcomes accumulate in PubMed-indexed journals.
- Norway's integrated fisheries infrastructure:Coastal processing corridors from Bergen to Ålesund enable same-day catch-to-concentrate workflows that preserve thermolabile lipid profiles.
- REACH compliance automation:European ingredient suppliers deploying solvent-tracking software are accelerating novel food dossier preparation for EFSA authorization pathways.
Market Restraints
- Menhaden stock concentration:Gulf of Mexico reduction fisheries supply over 70% of North Atlantic fishmeal precursor, creating single-basin biological risk exposure.
- Spray-drying energy intensity:Natural gas-fired inlet temperature control consumes 340-400 kWh per ton of dried powder, locking processors into volatile hydrocarbon cost curves.
- Plant protein substitution:Pea and fava protein isolates achieving 85% PDCAAS scores are displacing fish powder in mid-tier savory applications.
Strategic Opportunities
- Algae-derived DHA convergence:Fermentation platforms combining CRISPR strain optimization with continuous harvesting are opening non-fishery lipid sources for vegan supplement positioning.
- Direct-to-brand e-commerce channels:Sports nutrition startups in California and Texas are bypassing traditional ingredient distributors to source traceable marine collagen directly.
- EU Green Deal carbon border adjustments:Norwegian processors with electrified drying infrastructure qualify for preferential tariff treatment under emerging CBAM marine product classifications.
Industry Challenges
- Novel food dossier preparation timelines:EFSA scientific opinion cycles extending 18-24 months are delaying market entry for Antarctic krill and mesopelagic species powders.
- Cross-contamination control in shared facilities:Shellfish powder processors operating on multi-species lines face histamine monitoring protocols that add 12-15% to quality assurance labor costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seafood Powders Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Powder, Crab Powder, Shrimp Powder, Squid Powder Application: Food Industry, Nutritional Supplements, Pet Food, Pharmaceuticals Form: Powdered, Granulated, Flaked, Extracted Distribution Channel: Online Retail, Direct Sales, Specialty Stores, Wholesalers |
| Companies Covered | Austevoll Seafood ASA, Oceana Group Limited, Croda International Plc, FMC Corporation, Omega Protein Corporation, Biomega AS, Aker BioMarine ASA, Marvesa, Ocean's Flavor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seafood Powders Market Evolving Landscape
Marine ingredient processing is pivoting toward precision fermentation and carbon-accounted supply chains as buyers demand molecular specificity and scope-three emissions documentation.
Microencapsulation technology using modified starch and gum arabic wall systems is miniaturizing lipid droplet diameters below 50 microns, enabling pharmaceutical-grade bioavailability in omega-3 powders. Nutraceutical contract manufacturers in Switzerland and New Jersey are retrofitting spray towers with two-fluid nozzle atomizers at 15-20% annual capex allocation. This particle size compression is collapsing the traditional distinction between food-grade and pharmaceutical-grade fish oil powders.
EFSA's 2023 updated guidance on marine contaminant maximum levels is tightening cadmium and methylmercury thresholds for fish powder destined for infant formula applications. Dutch and Danish processors are investing in ion-exchange resin purification to meet the sub-0.1 ppm cadmium specifications. The regulatory squeeze is segmenting the European market into contaminant-tested premium streams and commodity-grade animal feed channels.
Brand procurement teams are consolidating supplier panels from 12-15 vendors to 3-4 strategic partners with full-chain carbon accounting. This vendor compression is eliminating spot-market traders and favoring vertically integrated Norwegian and Peruvian operations with Marine Stewardship Council chain-of-custody certification. The shift is most pronounced in German and Dutch sports nutrition contract manufacturing, where scope-three disclosure requirements are hardening into purchase order clauses.
Seafood Powders Market Segmentation
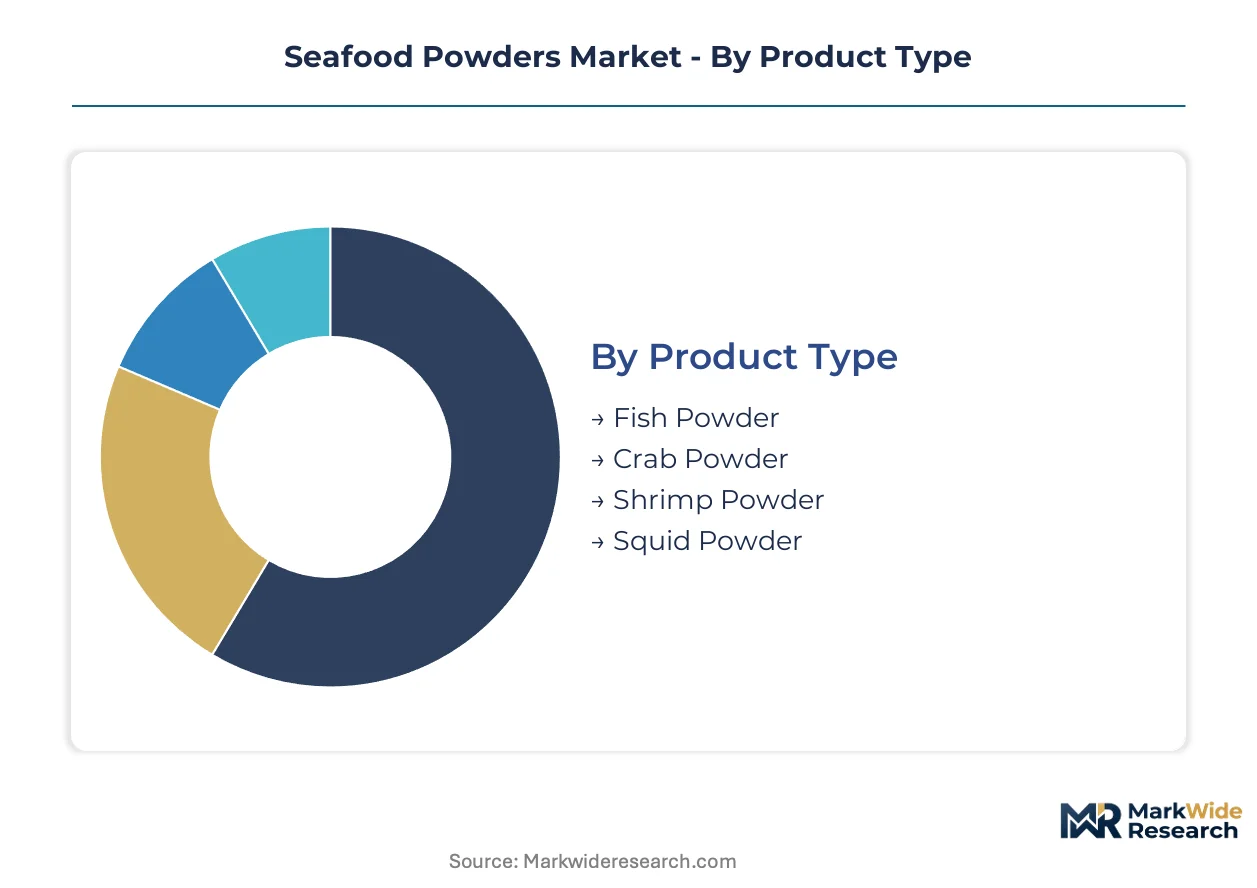
Seafood powder processors configure production lines around regulatory thresholds that vary sharply by end-use channel. FDA GRAS pathways for food-grade powders diverge from EMA pharmaceutical-grade validation requirements, forcing capital allocation decisions that lock facilities into single-channel output.
Product Type:
FDA and EFSA maintain divergent maximum residue limits for heavy metals and histamine across marine species categories, with infant formula applications facing the strictest cadmium thresholds under EFSA's updated guidance.
- Fish Powder:Reduction fisheries in the Gulf of Mexico and Norwegian coastal corridors supply menhaden, anchovy, and cod precursors standardized to 60-72% crude protein. Demand concentrates in aquaculture feed mills and mid-tier savory flavor houses where cost-per-protein-unit drives procurement decisions.
- Shrimp Powder:Penaeid and caridina species processing yields umami-intense powders with 2-4% natural chitin content prized in Asian sauce formulations. Premium positioning in Japanese and Korean instant noodle seasoning packets commands margin multiples over commodity fish powder.
- Crab Powder:Chionoecetes and portunus species-derived powders serve niche savory applications in Chesapeake Bay regional seasoning blends.
- Squid Powder:Dosidicus gigas and loligo species concentrates supply Japanese takoyaki flavoring and Korean seafood snack coatings.
Established volume favors fish powder; emerging adoption favors shrimp powder.
Application:
Cost tier stratification separates pharmaceutical-grade refinement investments from commodity feed-channel spray-drying infrastructure.
- Nutritional Supplements:Omega-3 encapsulation and marine collagen peptide programs demand microencapsulation at sub-50-micron particle sizes. Swiss and New Jersey contract manufacturers retrofit spray towers with two-fluid nozzle atomizers to serve sports nutrition startups sourcing traceable biomass directly.
- Food Industry:Savory flavor houses in Germany and the Netherlands consolidate supplier panels to 3-4 strategic partners with Marine Stewardship Council chain-of-custody certification and scope-three emissions documentation.
- Pet Food:Premium companion animal formulations incorporate salmon and whitefish powders for palatability enhancement in superpremium kibble segments.
- Pharmaceuticals:EMA pharmaceutical-grade refinement capabilities command premium positioning for lipid-based drug delivery systems and wound healing matrices.
Pharmaceutical-grade margins concentrate capability investment; supplement-channel volume scales fastest.
Form:
Processing energy intensity varies 3-4x across form categories, with spray-drying thermal loads locking processors into natural gas cost curves.
- Powdered:Standardized 80-200 mesh particle sizes dominate bulk industrial incorporation where dispersibility in aqueous systems determines functional performance.
- Granulated:Agglomerated structures improve flowability in high-speed tableting operations for supplement contract manufacturers.
- Flaked:Visual texture differentiation serves premium pet food and specialty culinary applications.
- Extracted:Solvent-based lipid concentration and ion-exchange resin purification meet sub-0.1 ppm cadmium specifications for infant formula channels under EFSA tightening.
Powdered forms capture commodity throughput; extracted forms concentrate regulatory-compliant premium streams.
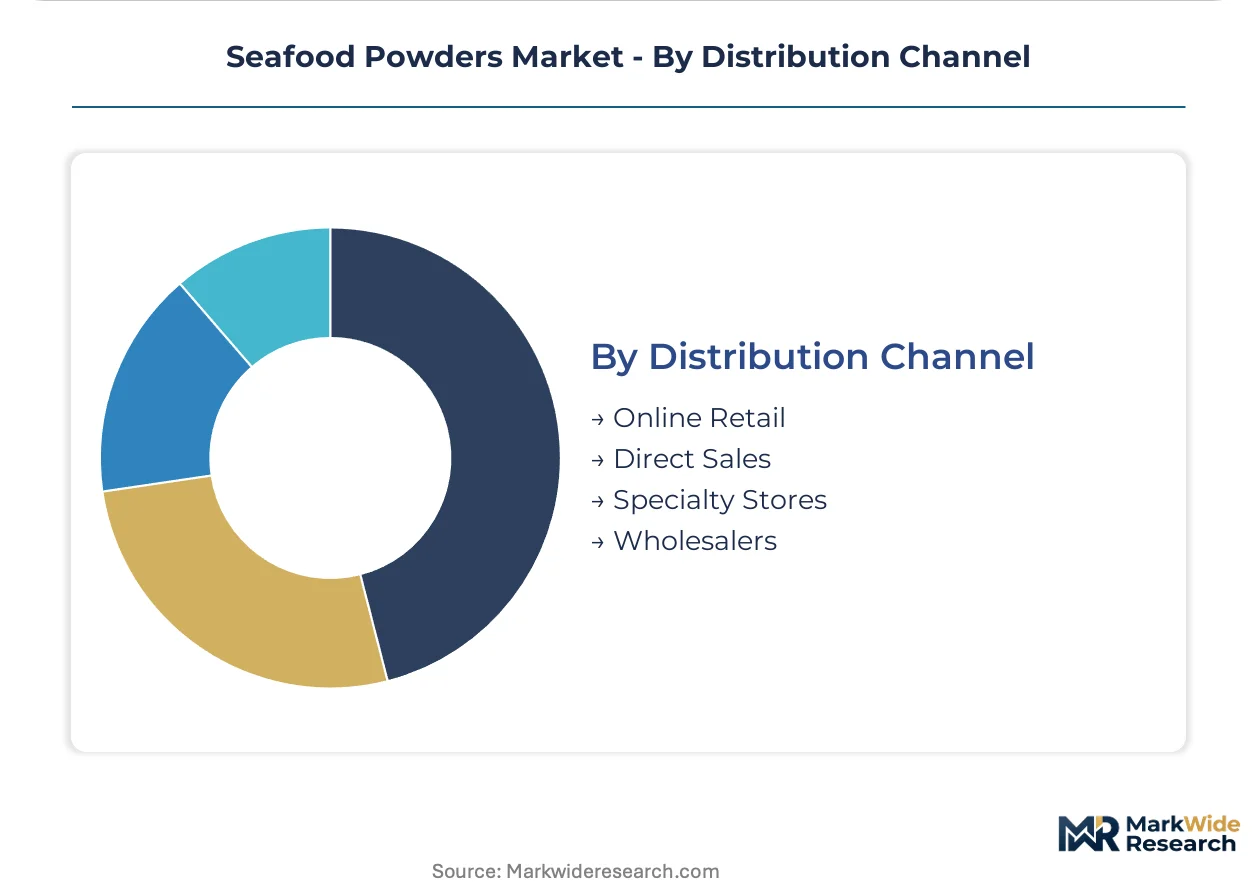
Distribution Channel:
Customer type fragmentation separates spot-market traders from vertically integrated direct relationships with carbon-accounting capabilities.
- Direct Sales:California and Texas sports nutrition startups bypass traditional ingredient distributors to source traceable marine collagen with batch-level heavy metal certificates.
- Online Retail:E-commerce platforms enable small-batch artisanal seafood powder brands to reach direct-to-consumer channels with origin storytelling.
- Specialty Stores:Gourmet and health food retail in urban coastal markets curate premium-positioned single-species powders.
- Wholesalers:Traditional bulk distributors serve mid-tier food manufacturers without captive sourcing infrastructure.
Direct sales deepen supply chain transparency; wholesale channels retain commodity volume liquidity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the Netherlands demonstrate the highest price elasticity for certified-sustainable powders, while Japanese and Norwegian procurement teams absorb 15-20% premiums for documented catch-to-concentrate traceability. This demand-elasticity contrast shapes regional investment patterns.
Norway
Austevoll Seafood ASA's fleet-to-factory pipeline anchors demand for same-day catch processing along the Bergen-Ålesund corridor. EU Green Deal carbon border adjustments favor Norwegian processors with electrified drying infrastructure. The coastal processing corridor preserves thermolabile lipid profiles that command premium positioning in Swiss and German supplement channels.
United States
Omega Protein Corporation dominates menhaden-derived supply across the Gulf of Mexico reduction fisheries belt. FDA GRAS self-affirmation pathways enable faster novel ingredient entry compared to EFSA timelines. Sports nutrition startups in California and Texas bypass distributors to source traceable marine collagen with batch-level heavy metal certificates.
Germany
Savory flavor houses in Hamburg and Frankfurt consolidate supplier panels to 3-4 strategic partners with Marine Stewardship Council chain-of-custody certification. REACH compliance automation through solvent-tracking software accelerates novel food dossier preparation. The Dutch-German border region concentrates scope-three emissions documentation capabilities for EU Green Deal procurement.
Japan
Penaeid and caridina shrimp powder demand concentrates in instant noodle seasoning and takoyaki flavoring applications. METI guidelines on marine resource traceability tighten documentation requirements for imported powders. Osaka and Nagoya processing clusters specialize in umami-intense formulations for premium export channels.
Netherlands
Dutch processors invest in ion-exchange resin purification to meet EFSA's sub-0.1 ppm cadmium specifications for infant formula channels. Rotterdam's port infrastructure enables bulk menhaden and anchovy concentrate imports from Peruvian and Gulf of Mexico origins. The Randstad region hosts the highest concentration of EFSA-authorized novel food dossier consultants.
Seafood Powders Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the seafood powders value chain. The market structures around three tiers: integrated fishing conglomerates with captive fleet assets, pharmaceutical-grade refiners with EMA-validated capabilities, and regional reduction-fishery operators serving commodity feed channels. Strategic moves concentrate on backward integration into reduction fisheries and certification-driven supplier panel consolidation by brand procurement teams.
Within the integrated conglomerate tier, Austevoll Seafood ASA and Omega Protein Corporation exemplify fleet-to-factory control architectures. Aker BioMarine ASA occupies a position representing Antarctic krill extraction specialization. Croda International Plc anchors the pharmaceutical-grade refinement segment. These three archetypes—Nordic integrated fisheries, North American reduction-fishery operators, and British specialty chemical refiners—capture distinct margin pools based on certification grade and end-use channel.
| Leading Market Players |
|---|
| Austevoll Seafood ASA |
| Oceana Group Limited |
| Croda International Plc |
| FMC Corporation |
| Omega Protein Corporation |
| Biomega AS |
| Aker BioMarine ASA |
| Marvesa |
| Ocean's Flavor |
| Others |
Value Network & Pricing Analysis
Fleet-scale economies in Norwegian reduction fisheries establish minimum efficient scale thresholds that lock smaller Gulf of Mexico operators into commodity price bands while electrified drying infrastructure in Bergen-Ålesund corridors commands carbon-accounted premiums from German and Dutch buyers.
Pricing Analysis
After-sales certification and traceability documentation drives lifetime value capture across seafood powder tiers. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade levels separates EMA-validated lipid refiners from FDA GRAS-affirmed food channels and commodity menhaden meal. Pricing pressure stems from pea and fava protein isolates achieving functional parity in mid-tier savory applications. Feed-grade buyers exhibit highest price sensitivity; pharmaceutical-grade nutraceutical formulators absorb 15-20% premiums for sub-0.1 ppm cadmium specifications.
Supply Chain Analysis
Just-in-time catch-to-concentrate workflows dominate Norwegian coastal processing where same-day fleet-to-factory pipelines preserve thermolabile omega-3 profiles, while strategic stockpiling of menhaden precursors buffers Gulf of Mexico operators against biological volatility. Supply concentrates in Norway, the United States, and Peru. Raw material dependencies rest on menhaden, anchovy, and Antarctic krill biomass. Single-basin biological risk in the Gulf of Mexico reduction fisheries creates supply vulnerability. Distribution runs through vertically integrated direct sales to sports nutrition startups and consolidated supplier panels serving German savory flavor houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seafood powders track a cyclical recovery as menhaden stock assessments rebound from recent biological lows and EU Green Deal procurement premiums reactivate Norwegian capacity utilization.
For Market Incumbents: Secure backward integration into electrified drying infrastructure to qualify for EU carbon border adjustment preferences. Defend market position by accelerating EFSA novel food dossiers for Antarctic krill and mesopelagic species ahead of 18-24 month regulatory cycles. Counter plant protein substitution threats with marine bioactive clinical validation programs that deepen pharmaceutical-grade differentiation. For New Entrants and Emerging Players: Traceability-as-a-service gaps in batch-level heavy metal certification and scope-three emissions documentation expose incumbent underservice to California and Texas sports nutrition startups. Target direct-to-brand e-commerce channels where artisanal positioning commands premium-mid pricing. Pursue algae-derived DHA fermentation platforms as the most penetrable white-space for vegan supplement positioning. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pharmaceutical-grade refiners with EMA-validated capabilities over commodity feed-channel operators. Long-term viability across the analysis window hinges on regulatory compliance automation and carbon-accounted supply chain infrastructure. The acquisition archetype to prioritize: integrated Norwegian operators with Marine Stewardship Council certification and electrified processing assets. Revision becomes warranted when EFSA contaminant thresholds tighten beyond ion-exchange resin purification economics or when menhaden stock assessments trigger quota reductions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrified Drying Infrastructure | Norwegian processors with renewable-powered spray towers capture EU Green Deal tariff preferences under emerging CBAM classifications. |
| EFSA Novel Food Dossier Acceleration | Early submission for Antarctic krill and mesopelagic species powders secures 18-24 month regulatory lead time advantage. |
| Direct-to-Brand E-Commerce Channel Development | California and Texas sports nutrition startups bypass traditional distributors for traceable marine collagen with batch certificates. |
| Algae-Derived DHA Fermentation Scale-Up | CRISPR-optimized strain platforms open non-fishery lipid sources for vegan supplement positioning against fish oil powders. |
| Ion-Exchange Resin Purification Investment | Dutch and Danish processors meet EFSA sub-0.1 ppm cadmium specifications for infant formula premium channel access. |
Research Methodology
A standing panel of seafood powder plant managers, procurement leads at German savory flavor houses, Norwegian fleet operations directors, and Swiss nutraceutical contract manufacturers provided ongoing calibration across primary fieldwork. Secondary validation drew from EFSA novel food registers, FDA GRAS notification databases, Marine Stewardship Council chain-of-custody records, and customs trade data on menhaden and anchovy concentrate flows. Bottom-up volume modeling triangulated against top-down expenditure analysis across nutritional supplement, food industry, and pharmaceutical end-use channels.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type tier, application channel, form category, and distribution structure. CAGRs were derived from slope analysis of normalized growth trajectories. Forecast inputs incorporated menhaden stock assessment cycles, EU Green Deal carbon border adjustment implementation timelines, and EFSA contaminant threshold evolution.
Forecasts assume regulatory continuity in EFSA, FDA, and REACH regimes; material policy shifts would require re-modeling. Biological volatility in Gulf of Mexico reduction fisheries and plant protein substitution acceleration in mid-tier savory applications constitute primary revision triggers. Revision becomes warranted when menhaden biomass assessments cross quota threshold levels or when EFSA cadmium specifications tighten beyond ion-exchange purification economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Organic Salmon Market
Seafood
South America Canned Seafood Market
Seafood
Middle East Seafood Market
Seafood
Processed Seafood and Seafood Processing Equipment Market
Seafood
United Arab Emirates Seafood Market
Seafood
Salmon Fish Market
Seafood
Europe Shrimp Market
Seafood
Canned Seafood Market
Seafood
Surimi by-Product Market
Seafood
Canned Tuna Market
Seafood
United States Frozen and Canned Seafood Market
Seafood
Global Smoked Fish Market
Seafood
Canned Fishery Product Market
Seafood
Shellfish Extract Market
Seafood
Fish Hydrolysate Market
Seafood
Edible Seaweed Market