
 North America Anti-Caking Market | 2026-2036
North America Anti-Caking Market Size, Share, and Industry Trends Forecast 2026-2036
North America Anti-Caking Market Analytics
Food-grade specification upgrades is rotating demand toward higher-purity silica and magnesium stearate grades that meet stricter flow-performance thresholds. BASF SE leverages its integrated silica manufacturing network to supply pharmaceutical and food-tier customers with consistent particle-size control. Cargill Incorporated anchors the agricultural channel through its fertilizer distribution partnerships across the Corn Belt. Evonik Industries AG specializes in precipitated silica technologies that differentiate performance in hygroscopic chemical formulations.
Anti-caking agents are powdered or granulated additives, typically composed of silica, calcium carbonate, or magnesium stearate, that prevent particle agglomeration by absorbing moisture or creating physical barriers between crystals; manufacturers produce these materials through precipitation, milling, or surface-coating processes to achieve specified particle sizes between 5 and 50 microns for optimal dispersibility. The food additives application segment leads volume consumption due to widespread use in salt, cheese powders, and seasoning blends, while pharmaceutical-grade silica commands premium margins driven by USP-NF certification requirements. Powder form dominates current shipments, though granule formats are gaining share in automated fertilizer blending operations across the Great Plains.
The FDA governs food-contact anti-caking agents through GRAS determinations and 21 CFR direct food additive regulations, while Health Canada's PMRA and Food Directorate jointly oversee agricultural and food-grade material approvals, creating a dual-compliance burden for cross-border suppliers. EPA registration requirements for silica-based materials used in pesticide formulations add another layer of technical documentation. Stakeholders must monitor pending FDA guidance on nanoscale silica characterization, as particle-size thresholds could redefine acceptable specifications for food and pharmaceutical applications without warning.
Market Dynamics
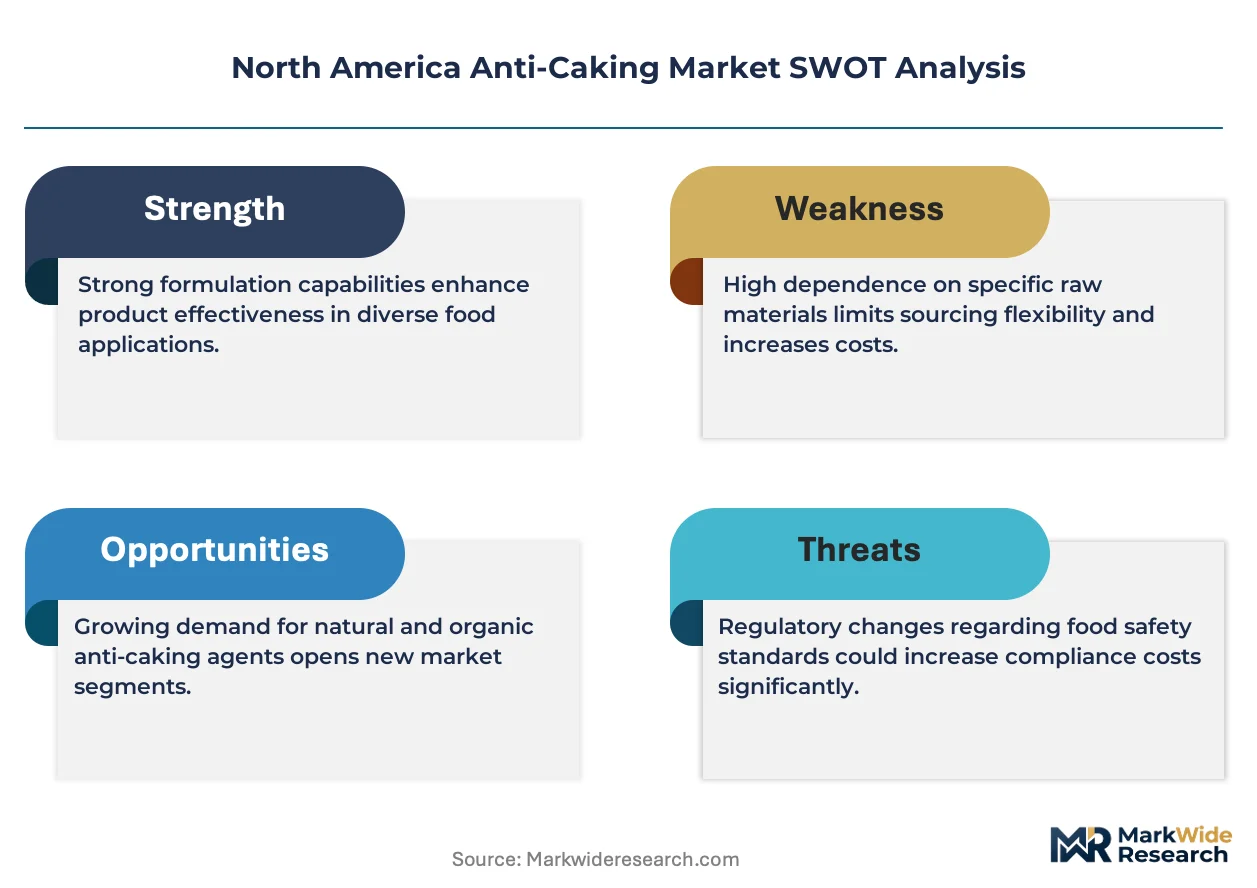
Clean-label formulation mandates from U.S. and Canadian regulators are forcing processors to retire traditional talc-based flow agents in favor of mineral-derived alternatives that satisfy transparency requirements without sacrificing anti-caking performance.
Growth Catalysts
- GRAS Notification Streamlining:The FDA's accelerated GRAS determination process for silica and calcium carbonate variants reduces time-to-market for reformulated food additives by 8-12 months compared to full food additive petitions.
- Fertilizer Corridor Expansion:Automated blending operations across Iowa, Illinois, and Indiana drive granule-format silica demand as cooperatives upgrade from bagged to bulk-handling infrastructure.
- Pharmaceutical USP-NF Certification:Stringent particle-size and purity specifications for excipient-grade silica create premium-tier pricing power for qualified suppliers serving generic drug manufacturers.
Market Restraints
- Soda Ash Price Volatility:Synthetic silica production depends on sodium carbonate feedstock subject to energy-cost fluctuations and North American supply disruptions from Wyoming trona mine maintenance cycles.
- Dual-Jurisdiction Compliance Burden:Cross-border suppliers face overlapping FDA direct food additive rules and Health Canada Food Directorate novel food assessments, doubling regulatory documentation costs.
- Organic Anti-Caking Substitution:Rice hull ash and cellulose-based alternatives capture niche share in certified-organic seasoning applications where mineral additives face exclusion.
Strategic Opportunities
- Mexican Food Processing Expansion:Querétaro and Guanajuato industrial corridors attract U.S. seasoning blend manufacturers seeking nearshored production with NAFTA-compliant material sourcing.
- Nanoscale Silica Characterization:Pending FDA guidance on sub-100nm particle thresholds creates first-mover advantage for suppliers with existing electron-microscopy quality systems.
- Direct-to-Cooperative Distribution:Bypassing traditional agrichemical distributors, silica suppliers establish direct technical service relationships with Great Plains fertilizer blenders for customized granule sizing.
Industry Challenges
- Particle Engineering Talent Scarcity:Precipitated silica manufacturing requires specialized colloid chemistry expertise concentrated at legacy production sites, constraining new facility staffing.
- Legacy Equipment Retrofit Costs:Food-grade pneumatic conveying systems demand stainless-steel construction and HEPA filtration upgrades incompatible with existing mineral-handling infrastructure at mid-tier processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Anti-Caking Market |
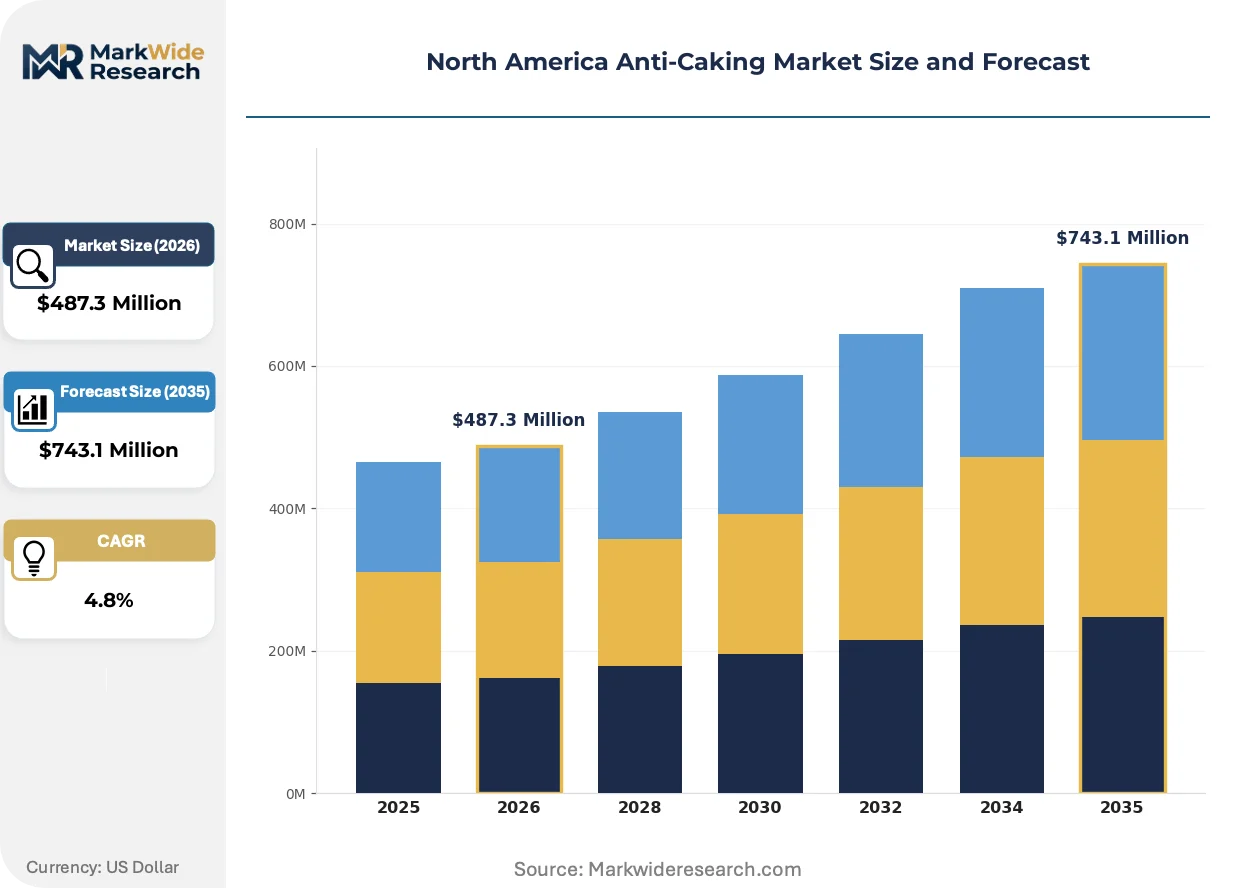
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Sodium Bicarbonate, Calcium Carbonate, Silica, Magnesium Stearate Application: Food Additives, Chemical Formulations, Pharmaceuticals, Agricultural Products End User: Food Industry, Cosmetics Manufacturers, Chemical Producers, Fertilizer Companies Form: Powder, Granule, Liquid, Tablets |
| Companies Covered | BASF SE, Cargill Incorporated, Evonik Industries AG, J.M. Huber Corporation, ArrMaz Products, PPG Industries, W. R. Grace & Co.-Conn, Solvay, Huber Engineered Materials, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Anti-Caking Market Evolving Landscape
Surface-modified silica technologies and regulatory pre-certification strategies are compressing traditional competitive advantages while opening new specification tiers across food, pharmaceutical, and agricultural channels.
Surface-functionalized precipitated silica with hydrophobic silane treatments is decomposing the historical trade-off between moisture resistance and dispersibility in hygroscopic seasoning applications. Midwest seasoning blenders are adopting these grades at 15-20% volume premiums to eliminate caking failures in high-humidity distribution environments. The technology is decomposing commodity silica margins by enabling performance-based specification lock-in with fewer qualified alternative suppliers.
Health Canada's pending alignment with FDA nanomaterial characterization protocols will force dual-submission strategies for cross-border food additive approvals. Silica suppliers must harmonize electron-microscopy batch documentation and dissolution testing protocols to satisfy both regulators without duplicate testing. Agricultural chemical formulators face the steepest adaptation burden as PMRA pesticide inert ingredient reviews incorporate particle-size distribution thresholds previously absent from Canadian requirements.
Seasoning manufacturers are consolidating supplier relationships from 4-6 anti-caking vendors to 2-3 strategic partners capable of integrated technical service and regulatory documentation support. This concentration displaces spot-market purchasing in favor of multi-year supply agreements with built-in specification evolution clauses. The shift is most visible in California and Texas seasoning clusters where private-label contract manufacturers face retailer mandates for single-source traceability from mine to finished blend.
North America Anti-Caking Market Segmentation
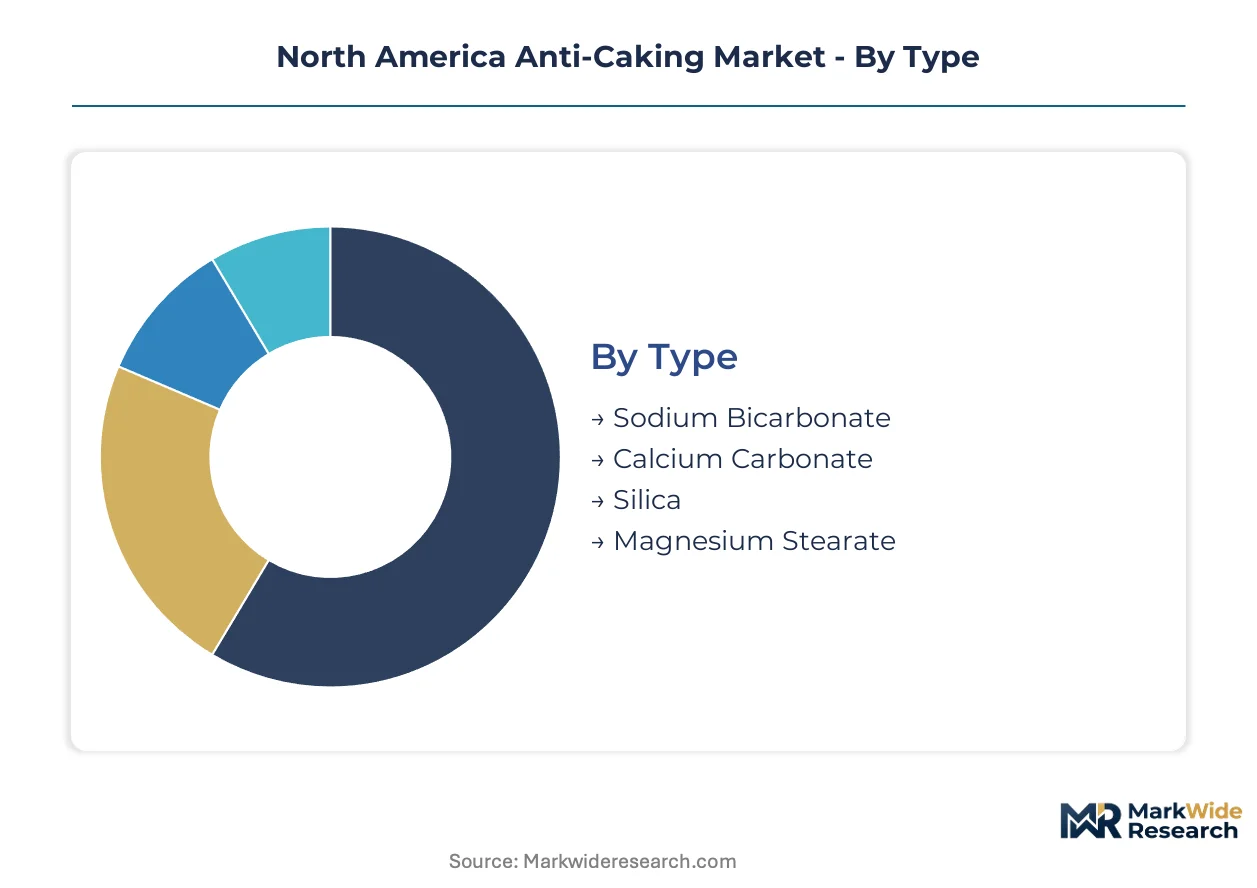
Anti-caking specification tiers diverge sharply between domestic North American consumption and export-oriented production, with regulatory compliance requirements driving material selection across each channel. Understanding segment boundaries enables suppliers to align manufacturing investments with the distinct technical documentation and purity thresholds demanded by food, pharmaceutical, and agricultural end-uses.
Type:
Silica and calcium carbonate variants dominate domestic formulation demand, while magnesium stearate and sodium bicarbonate grades serve specialized export channels requiring USP-NF or FCC certification documentation.
- Silica:Precipitated and fumed silica variants absorb moisture through high surface-area particle structures engineered to 5-50 micron specifications. Demand concentrates in Great Lakes chemical manufacturing corridors where pharmaceutical and food-grade precipitated silica commands premium positioning against commodity alternatives. FDA GRAS notification requirements for synthetic amorphous silica create specification barriers that favor established North American producers with validated electron-microscopy quality systems.
- Calcium Carbonate:Ground and precipitated grades function as both anti-caking agents and nutritional fortifiers in seasoning blends and baking applications. Midwest food processors favor domestically sourced calcium carbonate from Ohio and Pennsylvania limestone deposits to satisfy retailer traceability mandates and reduce cross-border documentation burdens. Surface-coated variants with stearic acid treatments gain share in high-humidity distribution environments.
- Magnesium Stearate:Hydrophobic lubricant-grade material serves pharmaceutical tablet manufacturing and select food applications requiring exceptional flow properties. USP-NF certification requirements limit qualified supplier pools.
- Sodium Bicarbonate:Dual-function leavening and flow agent deployed primarily in baking mixes and prepared flour blends. Sodium content labeling trends constrain expansion in clean-label seasoning segments.
Silica holds the largest share; momentum sits with surface-modified calcium carbonate grades penetrating pharmaceutical excipient applications.
Application:
Cost tier differentiation separates commodity agricultural applications from premium pharmaceutical and food-grade segments, with certification requirements determining margin capture potential.
- Food Additives:Salt, cheese powders, and seasoning blends represent volume concentration points where anti-caking performance directly impacts shelf stability and consumer acceptance. FDA 21 CFR direct food additive regulations and Health Canada Food Directorate approvals create dual-compliance documentation requirements for cross-border seasoning manufacturers operating in California, Texas, and Ontario processing clusters. Clean-label formulation mandates accelerate substitution of talc-based legacy agents with mineral-derived alternatives.
- Pharmaceuticals:Excipient-grade silica and magnesium stearate enable tablet compression and powder flow in generic drug manufacturing. USP-NF certification, ICH Q3D elemental impurity guidelines, and FDA drug master file requirements create qualification barriers that sustain 40-60% price premiums over food-grade equivalents. Indianapolis and Research Triangle Park pharmaceutical corridors anchor domestic demand.
- Chemical Formulations:Hygroscopic powder stabilization in industrial catalysts, pigments, and polymer additives. EPA registration requirements for silica-based pesticide inert ingredients add regulatory complexity.
- Agricultural Products:Fertilizer anti-caking prevents clumping in bulk-handled urea, ammonium nitrate, and compound fertilizers. Iowa-Illinois-Indiana fertilizer corridor drives granule-format adoption for automated blending infrastructure.
Food additives command volume leadership; pharmaceuticals deliver the steepest margin expansion trajectory.
End User:
Customer procurement sophistication varies dramatically across end-use segments, with food industry buyers demanding integrated technical service and fertilizer companies prioritizing bulk logistics efficiency.
- Food Industry:Seasoning blenders, salt processors, and dairy powder manufacturers require lot-to-lot consistency documentation and rapid specification evolution support. California and Texas seasoning clusters consolidate supplier relationships toward 2-3 strategic partners capable of integrated regulatory documentation and single-source traceability from mine to finished blend. Private-label contract manufacturers face retailer mandates for transparency that disqualify multi-source spot purchasing.
- Fertilizer Companies:Agricultural cooperatives and integrated nitrogen producers across the Corn Belt upgrade from bagged to bulk-handling infrastructure, driving granule-format silica demand with customized particle sizing for pneumatic conveying systems. Direct technical service relationships with blenders displace traditional agrichemical distribution channels.
- Chemical Producers:Industrial powder formulators in pigments, catalysts, and polymer additives. Performance specifications prioritize moisture absorption capacity over regulatory certification.
- Cosmetics Manufacturers:Talc-free powder formulations and pressed powder compacts. Clean beauty trends accelerate mineral-derived anti-caking adoption in color cosmetics.
The food industry anchors volume consumption; fertilizer companies generate the fastest procurement pattern transformation.
Form:
Supply chain configuration determines format selection, with powder dominating established processing infrastructure and granule formats requiring capital-intensive blending system upgrades.
- Powder:Standard 5-50 micron particle sizes serve existing pneumatic conveying and mixing equipment across food, pharmaceutical, and chemical processing facilities. Powder dominates current shipments due to compatibility with legacy infrastructure and lower per-unit handling costs. Dust generation and flowability limitations drive evaluation of alternatives in high-volume fertilizer applications.
- Granule:Agglomerated formats engineered for automated fertilizer blending operations reduce dust emissions and improve metering precision in bulk-handling systems. Great Plains cooperatives adopt granule silica at volume premiums to eliminate caking failures in outdoor storage and high-humidity distribution environments. Granule production requires specialized compaction and spheronization equipment concentrated at legacy manufacturing sites.
- Liquid:Suspension and dispersion formats for specialized coating applications and continuous processing systems. Limited adoption due to shipping weight penalties and stability concerns.
- Tablets:Pre-measured solid doses for laboratory and small-batch pharmaceutical processing. Niche positioning in R&D and clinical trial material supply.
Powder maintains format dominance; granule adoption climbs fastest in agricultural channel infrastructure upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silica manufacturing clusters concentrate around the Great Lakes chemical corridor and the U.S. Midwest fertilizer belt, with regulatory divergence between FDA and Health Canada creating distinct compliance zones for cross-border suppliers.
United States
The Corn Belt fertilizer corridor across Iowa, Illinois, and Indiana drives granule-format silica consumption as agricultural cooperatives automate bulk-handling infrastructure. FDA GRAS notifications for synthetic amorphous silica shape food-grade formulation standards, with pending guidance on nanoscale particle thresholds creating specification uncertainty. Indianapolis and Research Triangle Park pharmaceutical clusters anchor excipient-grade demand for USP-NF certified materials.
Canada
Health Canada's dual oversight through PMRA and the Food Directorate imposes documentation burdens on agricultural and food-grade material approvals that exceed U.S. requirements alone. The Great Lakes chemical manufacturing belt extends into southern Ontario, where cross-border seasoning processors face retailer mandates for single-source traceability. Toronto and Montreal food processing hubs consolidate supplier relationships toward integrated technical service partners capable of dual-jurisdiction compliance.
Mexico
Querétaro and Guanajuato industrial corridors attract U.S. seasoning blend manufacturers seeking nearshored production with NAFTA-compliant material sourcing. Mexican food processors adopt mineral-derived anti-caking agents as clean-label mandates from U.S. and Canadian retail customers cascade southward. Monterrey chemical distributors serve as regional hubs for silica and calcium carbonate supply to northern Mexico's expanding dairy powder sector.
North America Anti-Caking Market Competitive Landscape
Concentration sits with diversified chemical conglomerates possessing integrated silica manufacturing networks and validated quality systems for pharmaceutical certification. The vendor base stratifies between premium-tier suppliers with USP-NF capabilities and commodity-grade producers serving agricultural channels. Strategic archetypes include precipitation technology specialists, agricultural distribution integrators, and surface-modification innovators. Competitive moves center on direct-to-cooperative distribution bypassing traditional agrichemical channels and regulatory pre-certification investments ahead of pending nanomaterial guidance.
Among Germany-based chemical conglomerates, BASF SE and Evonik Industries AG occupy positions spanning pharmaceutical and food-tier supply with precipitated silica expertise. Cargill Incorporated anchors the agricultural channel through its Corn Belt distribution infrastructure. These three exemplify the tiered structure: technology-driven specialists command premium positioning in regulated applications, while agricultural integrators leverage logistics scale in commodity fertilizer markets.
| Leading Market Players |
|---|
| BASF SE |
| Cargill Incorporated |
| Evonik Industries AG |
| J.M. Huber Corporation |
| ArrMaz Products |
| PPG Industries |
| W. R. Grace & Co.-Conn |
| Solvay |
| Huber Engineered Materials |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day inventory cycles at Great Lakes silica processors concentrate pricing power with domestic precipitated silica manufacturers possessing validated electron-microscopy quality systems. This lead-time band tightens during Wyoming trona mine maintenance windows, forcing cross-border buyers toward premium-tier contracts with built-in specification evolution clauses.
Pricing Analysis
FDA GRAS notification requirements dictate the pricing tier structure across food-grade and pharmaceutical-grade silica segments. Three-tier pricing separates USP-NF certified excipient grades from food-grade precipitated variants and agricultural commodity silica, with certification-driven premiums widening during Health Canada dual-jurisdiction review backlogs. Cost compression in agricultural-grade material intensifies because fertilizer cooperatives consolidate purchasing toward direct technical service relationships. Food processors exhibit lowest price sensitivity due to retailer traceability mandates, while bulk fertilizer blenders drive hardest bargain negotiations.
Supply Chain Analysis
Strategic stockpile preferences dominate pharmaceutical and food-grade channels, while just-in-time procurement prevails in agricultural fertilizer applications subject to seasonal demand spikes. Manufacturing concentrates in the United States Great Lakes corridor, Germany, and Belgium, with sodium carbonate feedstock drawn from Wyoming trona deposits and European synthetic soda ash operations. Supply chain risk centers on single-source vulnerability for electron-microscopy validated quality systems. Distribution runs through integrated chemical conglomerate networks for regulated grades and direct-to-cooperative channels for agricultural silica.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label formulation mandates across North American food processing represent an early-cycle expansion story, with surface-modified silica technologies penetrating hygroscopic seasoning applications at volume premiums.
For Market Incumbents: Consolidate supplier relationships with California and Texas seasoning clusters facing retailer single-source traceability mandates. Deepen backward integration into Wyoming trona supply through long-term offtake agreements to defend margin position against soda ash price volatility. Lock in electron-microscopy batch documentation capabilities ahead of pending FDA nanoscale silica guidance.
For New Entrants and Emerging Players: Technical service gaps in dual-jurisdiction regulatory documentation present white-space entry points for cross-border seasoning manufacturers operating in Ontario and Quebec. Target Mexican food processors in Querétaro and Guanajuato corridors adopting clean-label mineral alternatives under U.S. retail customer pressure. Lead with integrated regulatory submission support bundled with surface-modified calcium carbonate grades.
For Investors and Strategic Acquirers: Long-term, this sits as a specialty-chemical consolidation play because precipitated silica manufacturing expertise concentrates at legacy production sites with colloid chemistry talent scarcity. Acquisition candidates include mid-tier surface-modification specialists with existing silane treatment capabilities. Watch for FDA nanomaterial characterization guidance finalization as inflection signal for premium-tier supplier valuation expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Certification Investment | Electron-microscopy quality systems capture first-mover advantage ahead of FDA nanoscale guidance thresholds. |
| Direct-to-Cooperative Distribution | Bypassing agrichemical distributors locks in Great Plains fertilizer blender relationships with customized granule sizing. |
| Surface Modification Technology | Hydrophobic silane treatments decompose commodity silica margins through performance-based specification lock-in. |
| Backward Integration into Feedstock | Captive soda ash supply from Wyoming trona operations insulates against energy-cost-driven price volatility. |
| Mexican Manufacturing Footprint | Querétaro and Guanajuato facilities capture NAFTA-compliant nearshoring demand from U.S. seasoning blenders. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with anti-caking ingredient procurement managers, regulatory affairs directors at seasoning manufacturers, fertilizer cooperative technical service leads, and pharmaceutical excipient quality managers; alongside secondary validation through FDA GRAS notification databases, Health Canada Food Directorate approval records, U.S. Geological Survey mineral commodity summaries, and American Chemistry Council silica market reports. Bottom-up volume modeling triangulated against top-down value estimates derived from trade flow analysis.
Across the analysis window, forecasts employed multi-dimensional segmentation by grade tier, end-use industry, form factor, and regional regulatory cluster. CAGRs were computed from annualized growth trajectories fitted to historical shipment data and projected adoption curves for surface-modified technologies. Key inputs included Wyoming trona production schedules, FDA guidance publication timelines, and Great Plains fertilizer infrastructure investment pipelines.
Underlying assumptions cover sustained clean-label formulation momentum and stable dual-jurisdiction regulatory frameworks, with deviation risk concentrated in nanomaterial characterization threshold changes and organic anti-caking substitution acceleration. Revision becomes warranted when FDA nanoscale silica guidance crosses implementation thresholds triggering specification recertification waves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Canada Food Additives Market
Food Additives and Ingredients
China Emulsifiers Market
Food Additives and Ingredients
Argentina Food Additives Market
Food Additives and Ingredients
Africa Food Emulsifiers Market
Food Additives and Ingredients
France Adjuvants Market
Food Additives and Ingredients
Leavening Agents Market
Food Additives and Ingredients
Natural Ferulic Acid Market
Food Additives and Ingredients
Asia Food Emulsifiers Market
Food Additives and Ingredients
Fermented Chymosin Market
Food Additives and Ingredients
Natural Food Preservatives Market
Food Additives and Ingredients
Egypt Food Preservatives Market
Food Additives and Ingredients
Food Stabilizer Systems Market
Food Additives and Ingredients
India Food Emulsifiers Market
Food Additives and Ingredients
South America Food Acidulants Market
Food Additives and Ingredients
Food Fungal Enzyme Market
Food Additives and Ingredients
South America Anti Caking Market