
 Lemon Salt Market | 2026-2036
Lemon Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Lemon Salt Market Foresight
The capital-intensity gap between artisanal producers and industrial salt manufacturers is collapsing as shared co-packing infrastructure lowers entry barriers for premium lemon salt brands. McCormick & Company leverages its global spice distribution network to secure shelf space across mainstream retail channels. SaltWorks, Inc. sustains its position through direct sourcing relationships with Mediterranean citrus suppliers and proprietary dehydration technology. Jacobsen Salt Co. anchors its brand identity around hand-harvested sea salt infused with regional lemon varieties from the Oregon coast.
Lemon salt denotes a flavored finishing salt produced by combining evaporated sea salt or rock salt with dried lemon peel, lemon juice concentrate, or essential oil extracts, typically containing 85-95% sodium chloride with 2-8% citrus-derived compounds by weight, used to enhance acidity and brightness in finished dishes without adding liquid. Flaked lemon salt commands premium positioning in gourmet retail due to its delicate texture and visual appeal on plated presentations, while lemon salt blends are expanding fastest among food manufacturers seeking ready-to-use seasoning solutions. Coarse lemon salt occupies a mature niche within traditional European markets where tableside grinding remains customary.
EFSA purity standards and FDA Good Manufacturing Practices shape ingredient sourcing protocols and labeling claims for lemon salt sold across European and American retail channels. REACH compliance requirements govern citrus extract handling within EU-based processing facilities, influencing supplier qualification procedures. Stakeholders must monitor evolving clean-label certification schemes and regional citrus crop yields to secure supply continuity as climate variability intensifies across Mediterranean growing regions.
Market Dynamics
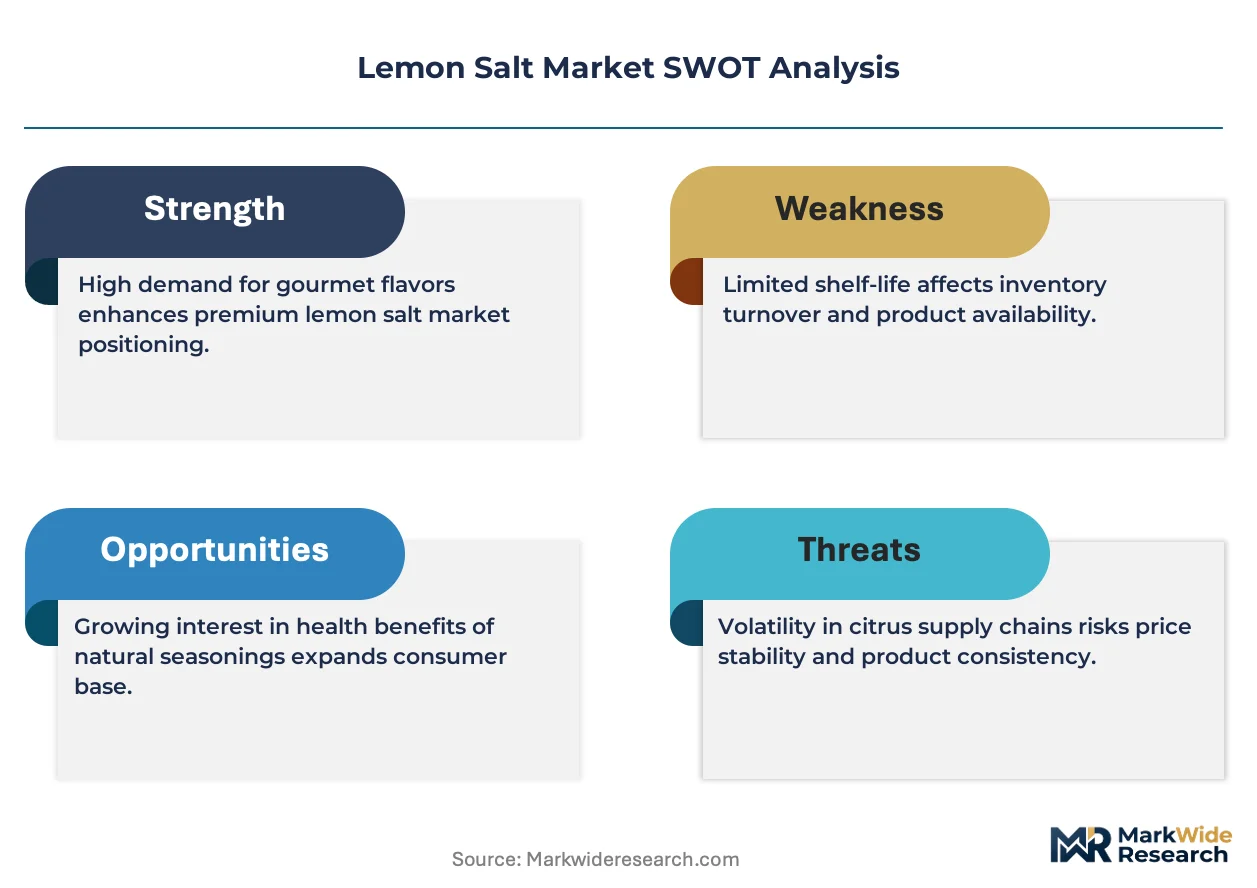
Shared co-packing infrastructure is collapsing the capital-intensity gap between artisanal lemon salt producers and industrial salt manufacturers, enabling premium brands to access dehydration and packaging capabilities without building captive facilities.
Growth Catalysts
- EFSA Clean-Label Standards:European Union purity requirements under EFSA are forcing ingredient transparency upgrades across retail channels, accelerating replacement of synthetic flavor enhancers with dried citrus peel formulations in food manufacturing applications.
- Finishing Salt Adoption:Gourmet restaurants in California, Provence, and Sicily are expanding tableside presentation of flaked lemon salt, creating pull-through demand into home cooking segments through chef-endorsed retail placement.
- Dehydration Technology:Proprietary low-temperature citrus dehydration systems are preserving volatile aromatic compounds previously lost in conventional heat processing, enabling flavor intensity parity with fresh lemon zest in shelf-stable formats.
Market Restraints
- Mediterranean Crop Concentration:Over 70% of premium lemon varieties suitable for salt infusion originate in coastal Sicily and Calabria, exposing supply chains to climate-induced yield variability and irrigation restrictions.
- REACH Compliance Friction:European Chemicals Agency registration requirements for citrus essential oil extracts create 18-24 month qualification timelines for new suppliers, limiting formulation flexibility for EU-based processors.
- Rock Salt Substitution:Unflaked Himalayan pink salt and smoked sea salts are capturing similar price positioning in gift and specialty retail, compressing incremental trial rates for lemon-infused variants.
Strategic Opportunities
- Indian Food Processing Expansion:FSSAI-standardized food manufacturers in Maharashtra and Karnataka are integrating lemon salt into ready-to-cook spice blends for export and domestic urban markets.
- Direct-to-Restaurant Distribution:Bypassing traditional spice distributors, artisanal producers are building chef relationships through vineyard-style harvest tours and co-creation programs in Oregon and Sicily.
- Biodegradable Packaging Mandates:EU Green Deal packaging regulations are accelerating demand for compostable film structures, favoring mid-size brands with flexible supplier relationships over rigid multinational supply chains.
Industry Challenges
- Sensory Evaluation Talent Scarcity:Qualified flavor chemists with citrus-specific volatile compound expertise command premium compensation, constraining R&D throughput for emerging brands.
- Organic Certification Timelines:USDA and EU organic equivalency audits require 36-month transition periods for citrus orchards, locking in supply commitments before demand materializes.
- Moisture Migration Control:Hygroscopic salt-citrus interfaces demand nitrogen-flush packaging investments that strain working capital for producers scaling beyond artisanal batch sizes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lemon Salt Market |
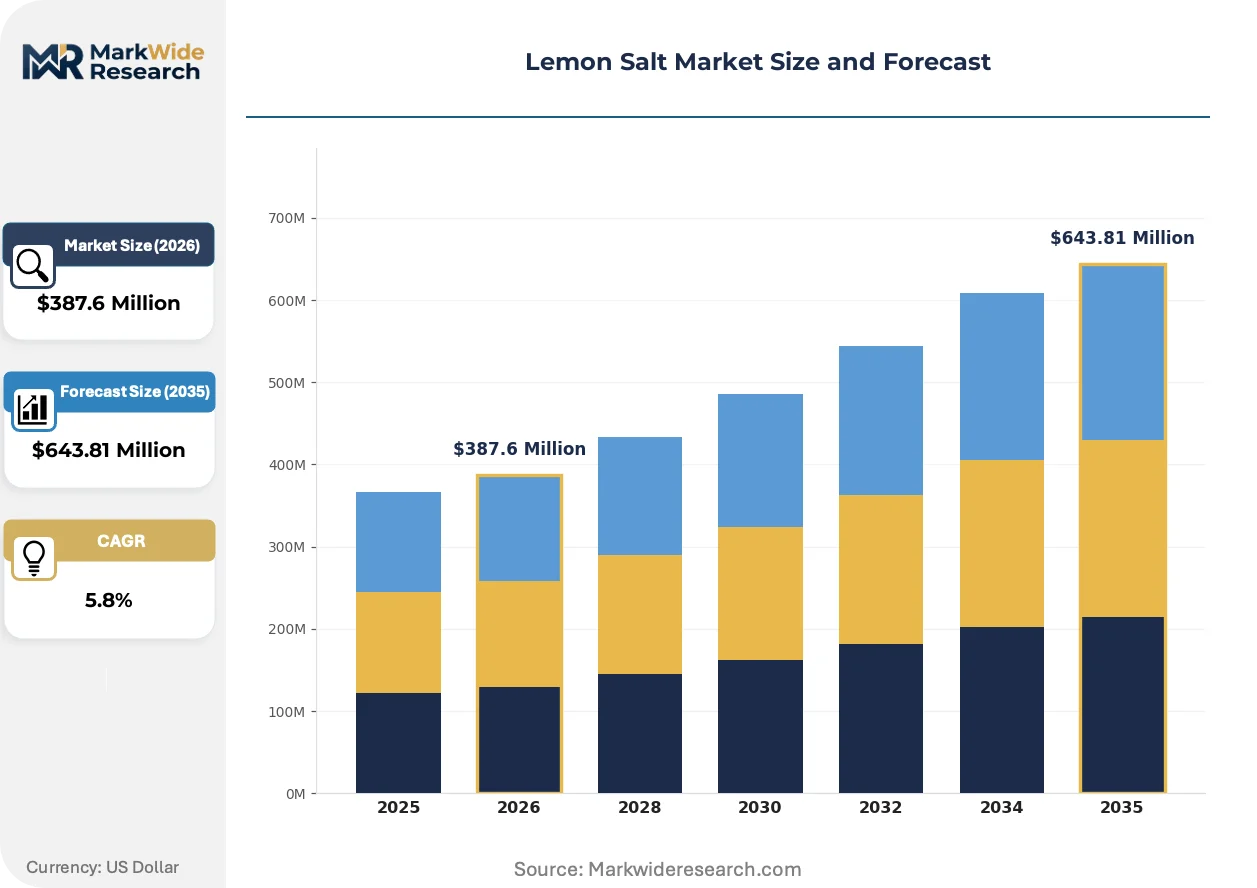
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flaked Lemon Salt, Coarse Lemon Salt, Fine Lemon Salt, Lemon Salt Blend Packaging Type: Glass Jars, Plastic Bags, Pouches, Metal Tins Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale End User: Household, Restaurants, Catering Services, Food Manufacturers |
| Companies Covered | McCormick & Company, Inc., SaltWorks, Inc., Morton Salt, Inc., Cargill, Incorporated, The Spice Lab, Jacobsen Salt Co., Redmond Real Salt, Tata Chemicals Limited, Unilever PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lemon Salt Market Shifts & Advancements
Active modifications in dehydration technology, regulatory labeling frameworks, and procurement channel structures are restructuring how lemon salt reaches end-users. These shifts favor agile mid-tier producers over legacy mass-market suppliers.
Spray-dried lemon juice concentrate is supplanting sun-dried peel infusions in food manufacturing applications. Large-scale seasoning blenders in the United States and Germany are adopting this format for batch consistency and microbial stability. The technology is compressing traditional seasonal procurement windows into year-round contracting structures.
REACH registration requirements for citrus-derived substances are tightening supplier qualification protocols across EU processing facilities. Industrial consequence includes forced dual-sourcing mandates and extended vendor audit cycles. Small-scale Mediterranean extract producers are consolidating to share regulatory compliance costs.
Chef procurement through specialty food distributors is fragmenting into direct farm relationships and subscription-based harvest allocations. This pattern disrupts traditional spice house intermediaries in California and Provence. Oregon-based sea salt producers report 40% of volume now moving outside conventional wholesale channels.
Lemon Salt Market Segmentation
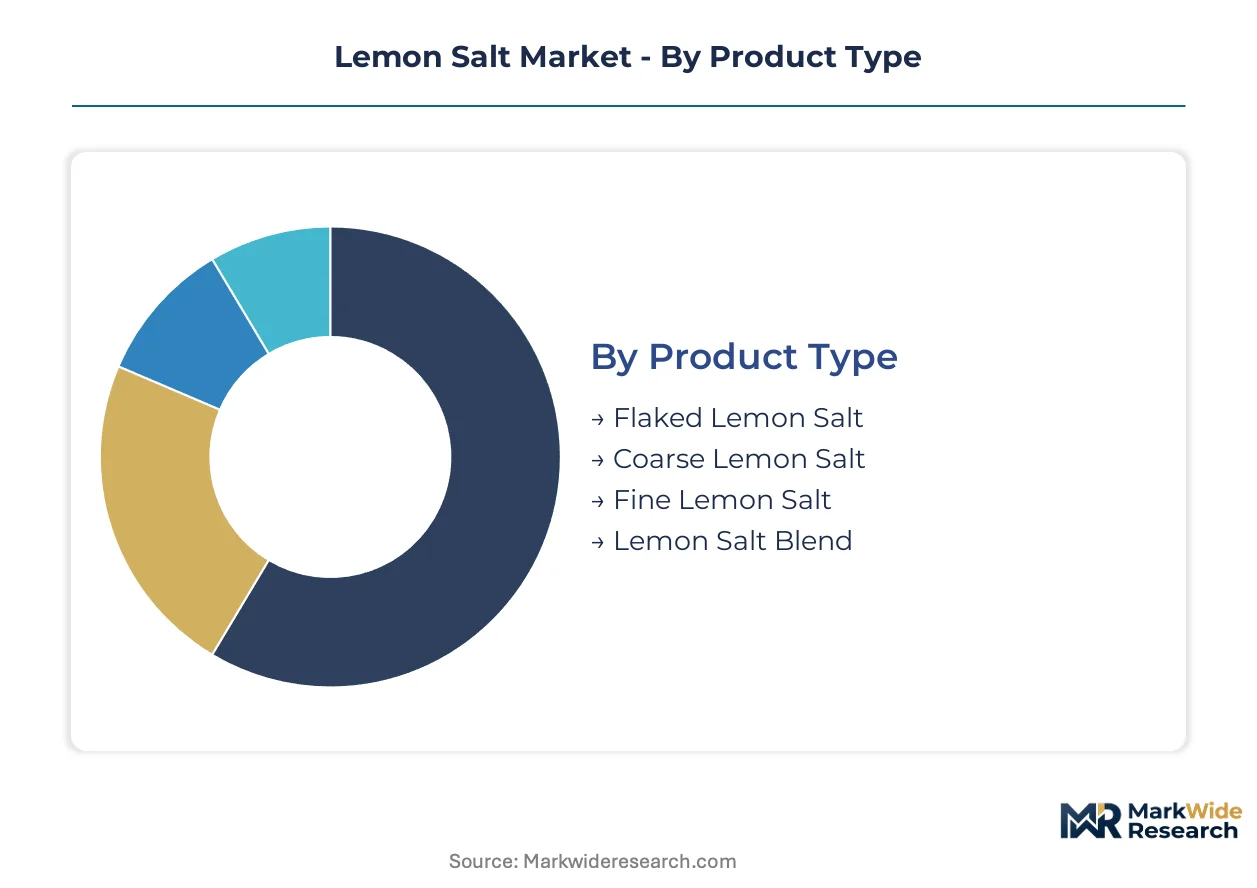
Lemon salt's positioning across premium and mass-market tiers demands precise channel alignment. Product texture and packaging format determine whether brands reach Michelin-starred kitchens or supermarket spice aisles.
Product Type:
Channel-mix patterns separate finishing salts destined for direct restaurant procurement from commodity blends flowing through food manufacturing supply chains.
- Flaked Lemon Salt:Delicate, pyramid-shaped crystals containing 2-8% citrus-derived compounds by weight deliver visual impact on plated presentations. Demand concentrates in California's Napa Valley and Provence's artisanal food clusters where chef-endorsed retail placement drives home cooking adoption.
- Lemon Salt Blend:Pre-mixed formulations with standardized particle distribution enable batch consistency for industrial seasoning applications. Food manufacturers in Germany and the United States are expanding procurement of spray-dried concentrate formats for ready-to-use solutions.
- Coarse Lemon Salt:Large-grain crystals suitable for tableside grinding occupy mature positioning in traditional European markets.
- Fine Lemon Salt:Uniform particle size supports even dispersion in baking and sauce applications.
Flaked lemon salt dominates installed base in premium channels. Lemon salt blends are where expansion concentrates most steeply.
Packaging Type:
Cost tier alignment separates gift-positioned formats from operational packaging designed for high-volume food service rotation.
- Glass Jars:Airtight sealing with nitrogen-flush capability preserves volatile aromatic compounds in hygroscopic salt-citrus interfaces. Gourmet retailers in Oregon and Sicily favor this format for vineyard-style harvest tour merchandise and direct-to-consumer subscription allocations.
- Pouches:Flexible film structures accommodate compostable materials mandated under EU Green Deal packaging regulations. Mid-size brands with agile supplier relationships are capturing share from rigid multinational supply chains.
- Metal Tins:Vintage aesthetic positioning supports premium gift retail placement.
- Plastic Bags:Economy-grade barrier properties serve bulk food manufacturing procurement.
Glass jars dominate installed base in specialty retail. Pouches are where expansion concentrates fastest.
Distribution Channel:
Volume concentration patterns reveal divergent growth trajectories between fragmented direct procurement and consolidated wholesale structures.
- Specialty Stores:Curated assortment and staff expertise support premium positioning for hand-harvested regional varieties. Oregon-based sea salt producers report 40% of volume now moving outside conventional wholesale channels through this route.
- Online Retail:Subscription-based harvest allocations and direct farm relationships enable artisanal producers to bypass traditional spice house intermediaries. Chef procurement through digital platforms is fragmenting established distributor relationships in California and Provence.
- Supermarkets:Mainstream shelf space requires compliance with FDA labeling standards and EFSA purity requirements.
- Wholesale:Traditional spice distributor networks retain scale advantages for mass-market penetration.
Specialty stores dominate installed base in premium segments. Online retail is where expansion concentrates most rapidly.
End User:
Application maturity separates established household consumption from emerging industrial integration patterns.
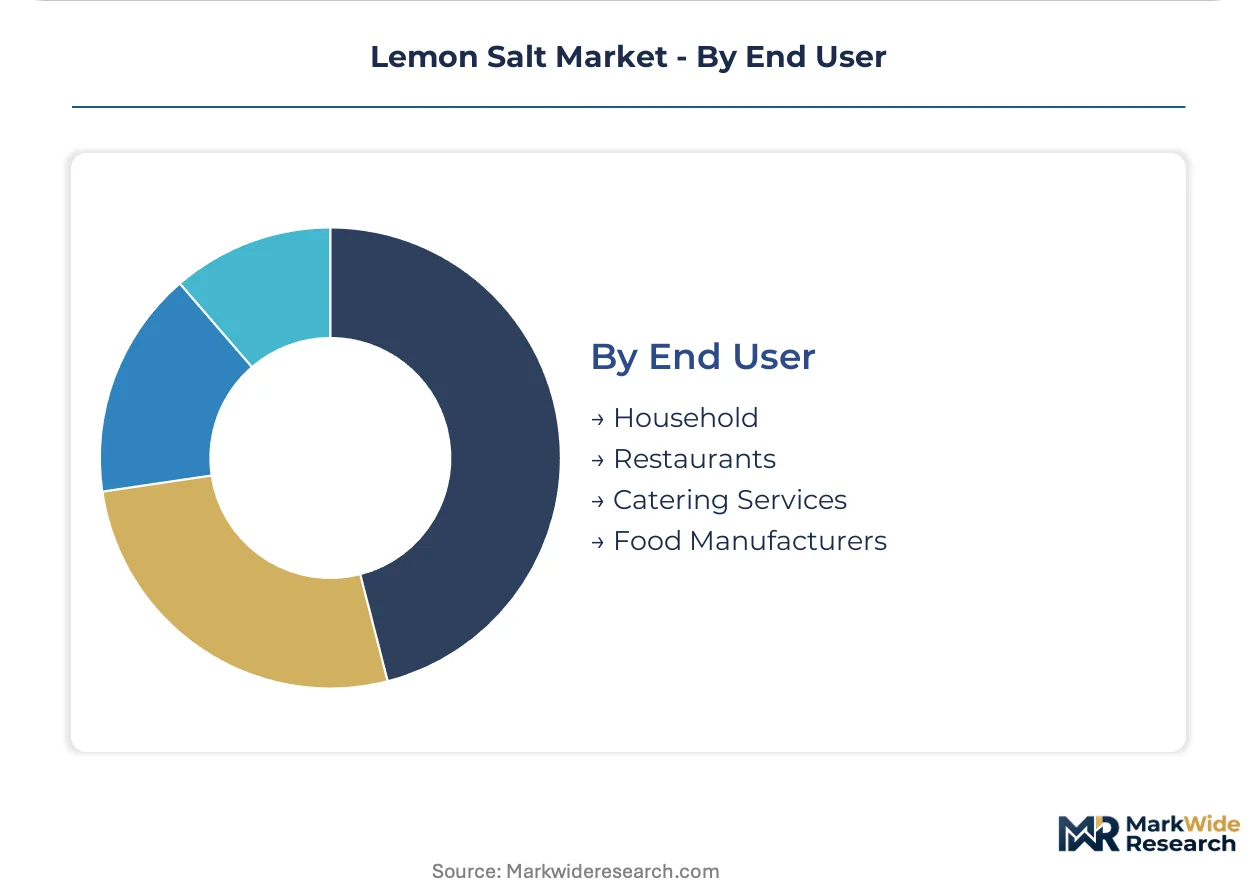
- Restaurants:Tableside presentation of flaked lemon salt in Michelin-tier establishments creates pull-through demand into adjacent retail channels. Direct-to-restaurant distribution bypassing traditional spice distributors is accelerating through co-creation programs.
- Food Manufacturers:FSSAI-standardized processors in Maharashtra and Karnataka are integrating lemon salt into ready-to-cook spice blends for export and domestic urban markets. Spray-dried lemon juice concentrate is supplanting sun-dried peel infusions for microbial stability.
- Household:Home cooking segments respond to chef-endorsed placement and recipe media integration.
- Catering Services:Operational efficiency demands drive preference for pre-blended, consistent-format procurement.
Restaurants dominate installed base in value terms. Food manufacturers are where expansion concentrates most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in lemon salt track Mediterranean citrus surplus against North American and European gourmet demand. Italy and Spain generate raw material surpluses while the United States and Germany absorb finished product volumes. Processing capacity expansion in India is redirecting some intra-Asian trade patterns.
United States
California's artisanal food clusters in Napa Valley and the Central Coast drive premium flaked lemon salt consumption. FDA Good Manufacturing Practices and evolving labeling standards shape ingredient transparency requirements for retail channels. Oregon-based sea salt producers now report 40% of volume moving outside conventional wholesale distribution through direct chef relationships.
Italy
Coastal Sicily and Calabria supply over 70% of premium lemon varieties suitable for salt infusion, anchoring European raw material sourcing. EFSA purity standards under EU regulation enforce ingredient transparency upgrades across processing facilities. Artisanal producers in Provence-Alpes-Côte d'Azur maintain traditional tableside grinding customs that sustain coarse lemon salt demand.
Germany
Industrial seasoning blenders in Bavaria and North Rhine-Westphalia expand procurement of spray-dried lemon juice concentrate for batch consistency. REACH compliance requirements for citrus essential oil extracts create extended supplier qualification timelines. Food manufacturers in the Stuttgart region integrate lemon salt into ready-to-use seasoning solutions for export markets.
India
FSSAI-standardized processors in Maharashtra and Karnataka integrate lemon salt into ready-to-cook spice blends for domestic urban markets and export. The country's food safety regulator mandates standardized manufacturing protocols that accelerate formal sector adoption. Mumbai-Pune industrial corridor hosts expanding co-packing infrastructure serving mid-tier brands.
Japan
Specialty retailers in Tokyo and Osaka curate premium finishing salts for Michelin-tier restaurant procurement. METI guidelines on processed food labeling influence import sourcing decisions for citrus-infused products. Kyushu-based citrus processors are developing dehydration technology partnerships with domestic salt refiners.
Lemon Salt Market Competitive Landscape
Concentration sits with diversified spice houses and specialized salt refiners rather than pure-play lemon salt producers. The competitive terrain splits between mass-market seasoning conglomerates with retail shelf space dominance and artisanal coastal producers with chef-direct relationships. Strategic archetypes include global spice distributors leveraging existing grocery networks, Mediterranean-focused specialists with captive citrus sourcing, and regional sea salt harvesters building terroir-based brand identity. Capacity expansion through shared co-packing infrastructure and backward integration into citrus orchard partnerships represent the dominant competitive moves.
Within the diversified spice house tier, McCormick & Company, Inc. exemplifies mass-market penetration through established retail channel relationships. Among specialized salt refiners, SaltWorks, Inc. and Jacobsen Salt Co. occupy positions that emphasize direct sourcing and regional terroir narratives respectively. These three entities represent the structural poles of the competitive landscape: scale-driven distribution, Mediterranean supply chain control, and coastal harvester authenticity.
| Leading Market Players |
|---|
| McCormick & Company, Inc. |
| SaltWorks, Inc. |
| Morton Salt, Inc. |
| Cargill, Incorporated |
| The Spice Lab |
| Jacobsen Salt Co. |
| Redmond Real Salt |
| Tata Chemicals Limited |
| Unilever PLC |
| Others |
Supply & Pricing Matrix
Spray-dried lemon juice concentrate replacing sun-dried peel infusions is redrawing procurement geography toward industrial dehydration hubs in Germany and the United States while compressing seasonal price premiums previously commanded by Mediterranean peel suppliers. This input substitution simultaneously weakens Sicilian raw material bargaining power and rewards processors with year-round contracting leverage.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in this market. Flaked finishing salts command substantial brand premiums tied to chef endorsement and regional terroir narratives, while spray-dried concentrates trade on volume scale and batch consistency. Price differentiation hinges on certification grade—USDA Organic and EU organic equivalency tiers extract meaningful premiums—and vertical integration into captive citrus sourcing. Cost compression in standard-grade blends is intensifying because shared co-packing infrastructure erodes scale advantages of legacy salt refiners. Food manufacturers exhibit highest price sensitivity due to formulation cost targets, whereas Michelin-tier restaurants prioritize sensory performance over unit economics.
Supply Chain Analysis
Strategic stockpiling of dried citrus inputs dominates inventory strategy given Mediterranean harvest seasonality and climate-induced yield volatility. Raw material sourcing draws from coastal Sicily and Calabra for premium lemon varieties, Oregon for regional sea salt harvests, and Gujarat for industrial-grade rock salt feedstock. Processing capacity concentrates in Germany, the United States, and emerging Maharashtra-Karnataka corridor facilities. Single-source vulnerability pervades the premium tier where over 70% of suitable citrus originates in Italian coastal zones exposed to irrigation restrictions. Distribution runs through fragmented specialty food distributors, direct-to-restaurant channels, and consolidating online retail platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Proprietary low-temperature dehydration technology is disrupting flavor preservation economics, creating asymmetric opportunity for agile mid-tier producers against mass-market incumbents locked into conventional heat processing infrastructure.
For Market Incumbents: Compound defensive positioning through backward integration into Sicilian and Calabrian orchard partnerships that lock in premium citrus supply before organic certification timelines mature. Accelerate R&D investment in nitrogen-flush packaging capabilities to control moisture migration in scaled production runs. Threat from chef-direct procurement models outside conventional wholesale channels demands parallel channel development through vineyard-style harvest tours and co-creation programs. For New Entrants and Emerging Players: Lead with biodegradable packaging compliance as a wedge against rigid multinational supply chains constrained by EU Green Deal mandates. Target FSSAI-standardized food manufacturers in Maharashtra and Karnataka as the most penetrable segment given rapid formal sector adoption and limited incumbent saturation. Deploy subscription-based harvest allocation models that bypass traditional spice house intermediaries and capture chef relationships through digital platforms. For Investors and Strategic Acquirers: The market sits at a technology-adoption phase that favors specialized dehydration technology holders and direct-sourcing specialists over undifferentiated commodity processors. Long-term viability across the analysis window rests on captive supply relationships and proprietary flavor preservation IP rather than brand equity alone. Acquisition target archetype encompasses Mediterranean-focused specialists with REACH-compliant citrus extract capabilities and scalable co-packing relationships. Signal to monitor: regulatory acceleration of clean-label certification schemes that would obsolete synthetic flavor enhancer alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citrus Orchards | Captive supply from Sicilian and Calabrian growing regions secures premium raw material access ahead of organic certification queues. |
| Proprietary Dehydration Technology Deployment | Low-temperature systems preserving volatile aromatic compounds enable flavor parity with fresh zest in shelf-stable formats. |
| Direct-to-Restaurant Distribution Buildout | Chef relationships through co-creation programs and harvest tours capture volume outside traditional spice distributor networks. |
| Biodegradable Packaging Transition | Compostable film structures satisfy EU Green Deal mandates and favor agile mid-size brands over rigid multinational supply chains. |
| FSSAI Compliance Investment | Standardized manufacturing protocols unlock ready-to-cook spice blend integration in Maharashtra and Karnataka processing corridors. |
Research Methodology
Initial hypotheses were tested against primary input from specialty salt procurement managers at gourmet restaurant groups, citrus orchard operations directors in Sicily and Calabria, dehydration technology engineers, and specialty food retail category buyers, then refined through secondary validation. Primary fieldwork combined structured interviews with supply chain stakeholders and facility observations at co-packing infrastructure sites. Secondary sources encompassed EFSA purity standard filings, FDA Good Manufacturing Practice guidance documents, FSSAI standardized protocol disclosures, and trade flow records from customs databases. Bottom-up volume estimates from processor capacity and utilization rates were triangulated against top-down demand segmentation derived from channel shipment data.
Variance decomposition across the projection horizon isolates drivers by product texture tier, packaging format compliance requirements, distribution channel concentration patterns, and end-user application maturity. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic consumption indicators and regulatory adoption curves. Industry-specific forecast inputs include Mediterranean citrus crop yield variability models and REACH registration timeline assumptions for citrus-derived substances.
Underlying assumptions cover sustained EFSA and FDA clean-label enforcement trajectories, with deviation risk concentrated in climate-induced supply disruptions across Italian coastal growing regions and accelerated synthetic flavor replacement timelines. Revision becomes warranted when organic certification backlog durations or biodegradable packaging cost parity thresholds cross materiality boundaries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Garlic Oleoresin Market
Spices and Seasonings
Dill Oil Market
Spices and Seasonings
Sichuan Peppercorn Market
Spices and Seasonings
Pink Himalayan Salt Market
Spices and Seasonings
Chipotle Salt Market
Spices and Seasonings
Thyme Extract Market
Spices and Seasonings
Spice Grinders Market
Spices and Seasonings
Asia-Pacific Seasoning and Spices Market
Spices and Seasonings
Basil Essential Oil Market
Spices and Seasonings
Global Clove Market
Spices and Seasonings
North America Spice and Herb Extracts Market
Spices and Seasonings
Oregano Oil Market
Spices and Seasonings
Blended Spices Market
Spices and Seasonings
Asia-Pacific Spice and Herb Extracts Market
Spices and Seasonings
Spice Oils and Oleoresins Market
Spices and Seasonings
Africa Spice and Herb Extracts Market