
 Paprika Powder Market | 2026-2036
Paprika Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Paprika Powder Market Insights
Commodity-grade bulk sales revenue is narrowing toward value-added extract and oleoresin production. Kalsec Natural Ingredients leverages vertical integration from seed breeding to extraction in the United States. Botanic Healthcare anchors its position through specialized nutraceutical-grade paprika oleoresin supply to European pharmaceutical formulators. Qingdao Fumanxin Foods Co., Ltd. competes on manufacturing scale, operating integrated drying and grinding facilities across China's Xinjiang growing belt.
Paprika powder consists of dried and ground fruits from Capsicum annuum cultivars, typically measuring 500–2,000 Scoville Heat Units for sweet varieties and processed through controlled dehydration below 60°C to preserve carotenoid stability; its primary commercial purpose centers on natural food coloring, flavoring, and antioxidant applications across processed food and cosmetic formulations. Sweet Paprika dominates volume flows into mass-market food manufacturing, where color consistency drives procurement specifications. Smoked Paprika commands premium positioning within specialty retail and culinary arts channels, reflecting consumer preference for authentic wood-fired flavor profiles. Hot Paprika sustains niche growth within ethnic food processing and artisanal condiment production.
EU REACH and EFSA frameworks govern maximum residue limits and additive classifications for paprika-derived colorants entering European food and cosmetic supply chains. FDA color additive regulations in the United States require batch certification for certain carotenoid extracts, shaping importer documentation requirements and testing protocols. Stakeholders must monitor evolving clean-label certification standards and regional organic equivalence agreements to secure sustained market access across jurisdictions.
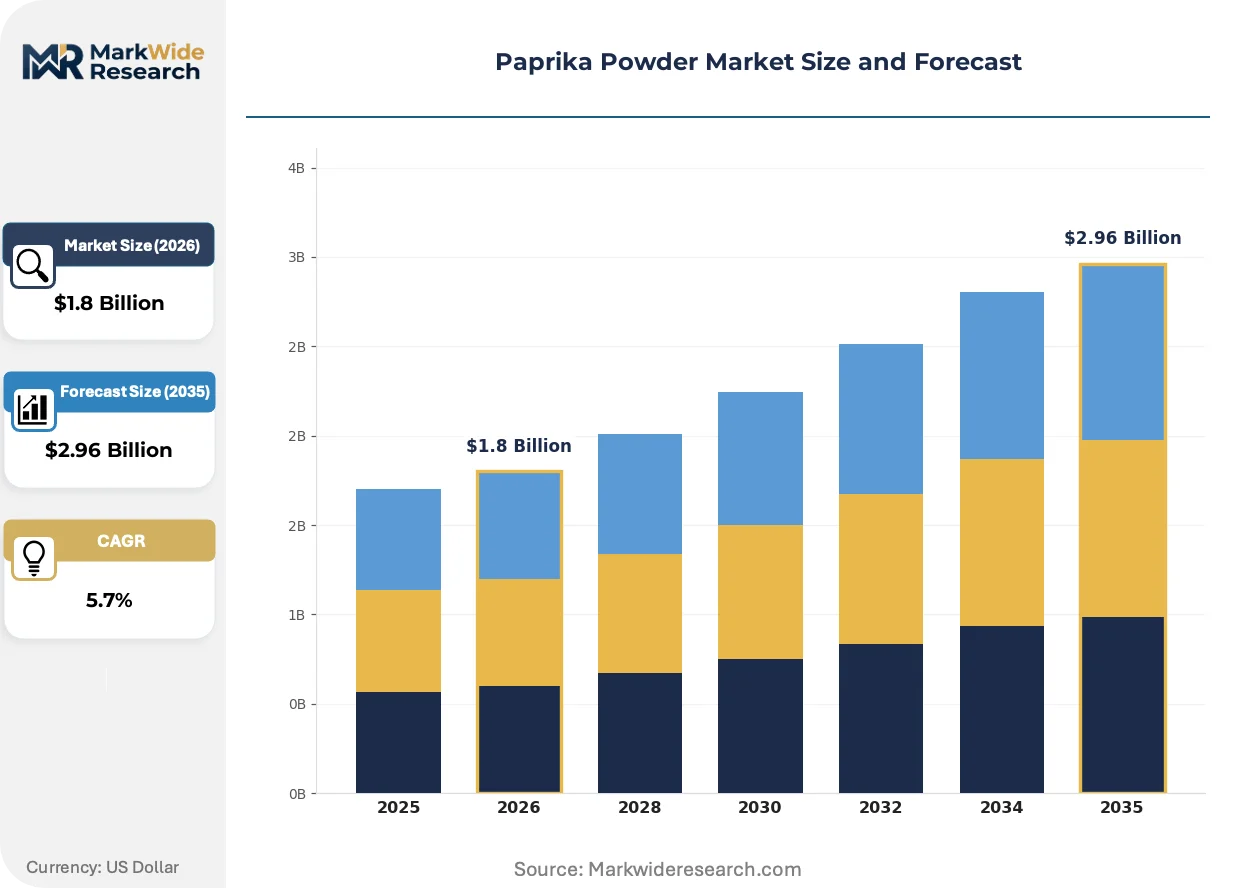
Market Dynamics
EU REACH restrictions on synthetic azo dyes are redirecting food manufacturer procurement toward botanical colorants, concentrating purchasing power among buyers with certified clean-label supply chains and backward integration into controlled cultivation regions.
Growth Catalysts
- REACH Annex XVII dye restrictions:ECHA's tightened limits on Tartrazine and Sunset Yellow FCF are forcing European food processors to reformulate with paprika-derived carotenoids for bakery and confectionery applications.
- Capsicum annuum breeding programs:Seed-to-extract pipeline investments in Spain's Cáceres province are yielding cultivars with stabilized capsanthin content above 3,500 CU for industrial colorant buyers.
- Clean-label retail mandates:North American private-label grocery chains now require third-party verified natural colorant documentation for shelf placement in sauce and snack categories.
Market Restraints
- Climate volatility in concentrated growing belts:Hungary's Szeged-Tomato zone and Spain's Extremadura region face recurring drought stress that compresses harvest yields and amplifies price volatility for oleoresin processors.
- Carotenoid stability limitations:Degradation rates of capsorubin and capsanthin above 60°C processing temperatures constrain high-heat food applications without microencapsulation investments.
- Turmeric and annatto substitution:Lower-cost natural colorants from competing botanical sources capture share in yellow-orange hue segments where paprika's red specificity is not required.
Strategic Opportunities
- Nutraceutical-grade oleoresin expansion:Pharmaceutical formulators in Germany and Switzerland are sourcing high-purity carotenoid extracts for antioxidant supplement capsules, commanding premium pricing over food-grade specifications.
- Cosmetic colorant regulatory tailwinds:EU Cosmetics Regulation (EC) No 1223/2009 permits paprika-derived pigments in rinse-off products, opening formulation pipelines for natural makeup and personal care brands.
- Direct-to-manufacturer digital procurement:Blockchain-traceable bulk platforms are disintermediating traditional spice traders, allowing processors in India's Guntur belt to contract directly with European food manufacturers.
Industry Challenges
- Spectrophotometric color unit certification:Batch-to-batch CU consistency testing for E160c classification requires capital-intensive HPLC equipment that smaller grinding facilities in China's Xinjiang region struggle to finance.
- Organic equivalence documentation:Cross-border recognition between USDA NOP and EU organic standards creates compliance timeline friction for exporters seeking dual-market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paprika Powder Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweet Paprika, Smoked Paprika, Hot Paprika, Ground Paprika Application: Food Industry, Cosmetics, Pharmaceutical, Culinary Arts Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Form: Ground, Flakes, Paste, Whole |
| Companies Covered | Naturesmith Foods LLP, EVE SA, Le Comptoir Colonial, Botanic Healthcare, Qingdao Fumanxin Foods Co., Ltd., Sunrise Spices Exporters, Rubin Paprika Processing Ltd, Foodchem International Corporation, Kalsec Natural Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paprika Powder Market Trends and Innovations
Digital traceability infrastructure and precision drying technologies are compressing quality variance in paprika supply chains while regulatory divergence between jurisdictions is fragmenting formulation standards.
Near-infrared spectroscopy coupled with machine vision sorting is virtualizing quality control workflows in post-harvest processing. Spanish and Hungarian cooperatives deploying these systems are reducing manual grading labor by two-thirds while tightening capsanthin concentration tolerances. The technology is virtualizing the traditional trader-mediated quality assurance layer, enabling direct processor-to-manufacturer contracting with embedded specification guarantees.
EFSA's 2023 updated guidance on food additive specifications tightened heavy metal thresholds for botanical colorants entering European supply chains. The framework now requires documented soil testing and irrigation water analysis from cultivation sites, adding compliance layers for importers sourcing from non-EU growing regions. Hungarian and Spanish domestic processors with integrated field-to-facility traceability are capturing preferential supplier status against commodity traders lacking origin documentation.
Buyer concentration among multinational food manufacturers is compressing supplier qualification cycles from multi-year frameworks to single-season trial contracts. Procurement teams at European sauce and seasoning houses now demand simultaneous color performance data, pesticide residue panels, and carbon footprint disclosures before volume commitments. This pattern is most pronounced in Germany and the Netherlands, where retail consolidation has transferred formulation specification authority to centralized technical procurement functions.
Paprika Powder Market Segmentation
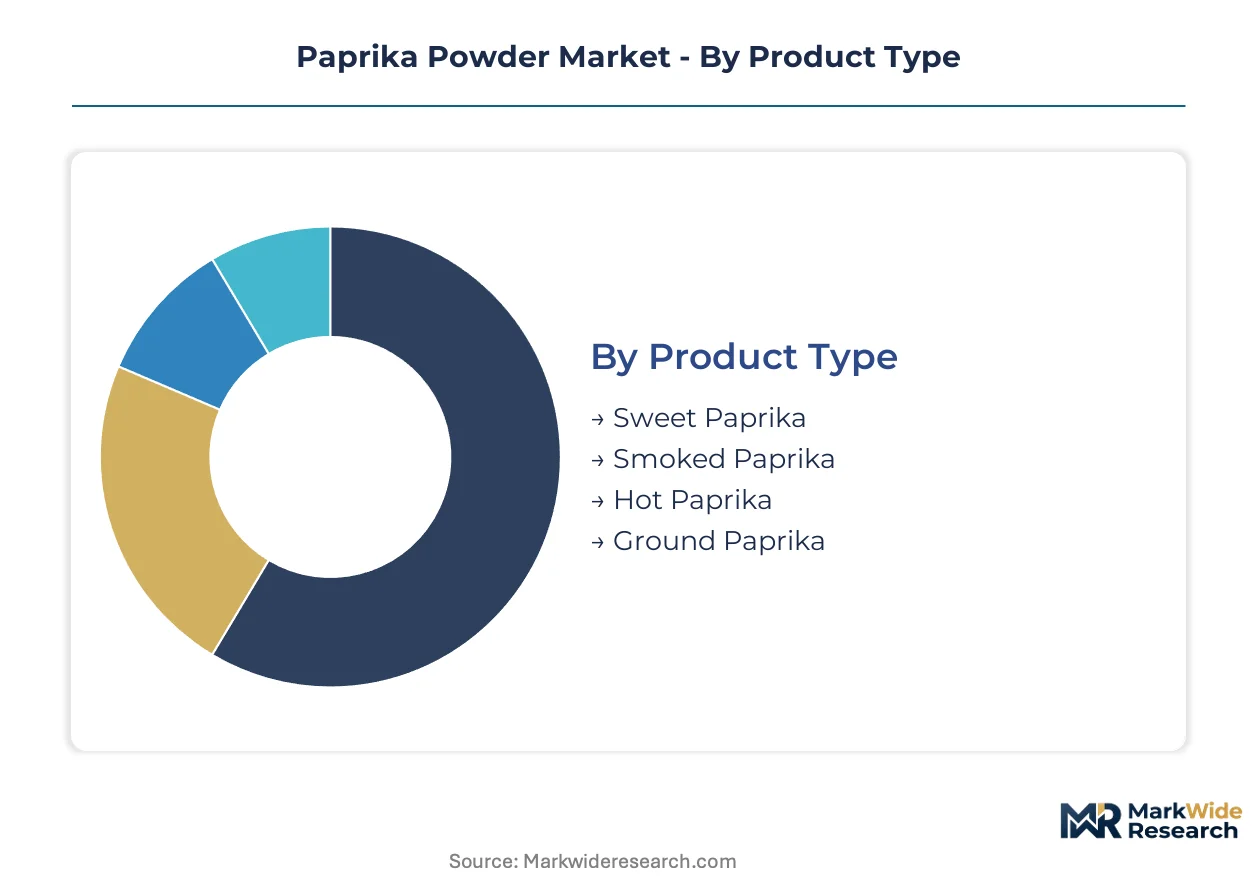
Paprika powder segmentation reflects divergent value capture strategies across commodity bulk trading and specialized extract markets. Color unit specifications, heat profiles, and carotenoid stability requirements drive distinct procurement patterns among food manufacturers, cosmetic formulators, and pharmaceutical buyers.
Product Type:
Sweet, smoked, and hot varieties span a functional spectrum from mass-market colorant to artisanal flavoring, with each commanding distinct specification tolerances and price positions.
- Sweet Paprika:Low-heat cultivars measuring 500–2,000 Scoville Heat Units deliver standardized red-orange coloration through high capsanthin concentration. German and Dutch sauce manufacturers specify CU values above 3,000 for consistent batch coloring, with procurement concentrating among vertically integrated Spanish processors in Extremadura.
- Smoked Paprika:Wood-fired dehydration over oak or beech imparts distinctive flavor compounds prized in specialty retail channels. Demand clusters in North American culinary arts segments where authentic Spanish pimentón de la Vera commands premium positioning against liquid smoke alternatives.
- Hot Paprika:Elevated capsaicin content serves ethnic food processing and artisanal condiment production. Hungarian processors in Kalocsa supply heat-calibrated grades to Central European sausage houses requiring precise Scoville consistency.
- Ground Paprika:Standard particle size milling for general-purpose food manufacturing without specialized heat or smoke treatment. Commodity grinding facilities in China's Xinjiang region compete on volume scale for bulk seasoning blends.
Established volume favors Sweet Paprika; emerging adoption favors Smoked Paprika.
Application:
End-use diversification stretches from high-volume food coloring to precision pharmaceutical extraction, with regulatory barriers steepening across the value chain.
- Food Industry:Natural colorant substitution for synthetic azo dyes dominates volume consumption. ECHA's REACH Annex XVII restrictions on Tartrazine and Sunset Yellow FCF redirect European bakery and confectionery procurement toward E160c-certified paprika oleoresins.
- Cosmetics:EU Cosmetics Regulation permits paprika-derived pigments in rinse-off formulations. German natural makeup brands source carotenoid extracts for lip tint and blush applications where botanical positioning commands shelf price premiums.
- Pharmaceutical:High-purity antioxidant extracts supply nutraceutical capsule production. Swiss and German formulators specify heavy metal thresholds below EFSA's tightened 2023 guidance, requiring documented soil testing from cultivation sites.
- Culinary Arts:Authentic flavor profiles drive specialty retail and foodservice procurement. Spanish denominación de origen paprikas from La Vera and Murcia anchor premium positioning in North American gourmet distribution.
Food Industry absorbs the largest volume flows; Pharmaceutical commands the steepest expansion trajectory.
Distribution Channel:
Channel selection tracks buyer scale and specification complexity, with digital infrastructure compressing traditional trader margins.
- Online Retail:Direct-to-consumer platforms serve artisanal buyers and small-batch food producers. Blockchain-traceable bulk marketplaces enable Indian Guntur processors to contract directly with European manufacturers, bypassing layered commission structures.
- Supermarkets:Mass-market retail placement requires third-party verified natural colorant documentation. North American private-label chains mandate clean-label certification for sauce and snack category shelf placement.
- Specialty Stores:Gourmet and ethnic food retailers stock denomination-of-origin Spanish and Hungarian varieties. Smoked paprika from Extremadura's La Vera zone commands dedicated shelf positioning in culinary-focused outlets.
- Wholesale:Bulk commodity trading serves industrial food processors with standardized CU specifications. Traditional spice traders in Rotterdam and Hamburg face margin compression from processor-direct digital procurement.
Wholesale retains the largest transaction value; Online Retail is climbing the fastest.
Form:
Physical presentation determines extraction efficiency, shelf stability, and end-use compatibility across processing temperatures.
- Ground:Fine particle milling maximizes surface area for colorant dispersion in low-moisture applications. Degradation constraints above 60°C limit high-heat food processing without microencapsulation investment.
- Flakes:Larger particle size preserves volatile oil compounds for flavor-forward applications. Hungarian and Spanish cooperatives deploy near-infrared spectroscopy sorting to standardize flake color consistency.
- Paste:Oil-based suspension extends carotenoid stability in ready-to-use food manufacturing. Oleoresin processors in India's Guntur belt supply paste concentrates to European sauce houses.
- Whole:Intact dried pods serve specialty culinary and limited extraction runs. Whole pod preservation enables controlled grinding for specific particle size requirements.
Ground dominates industrial procurement; Paste is gaining share fastest in sauce manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish buyers exhibit the lowest price elasticity, absorbing premiums for protected designation of origin certification, while Chinese processors face acute margin pressure from commodity-grade oversupply. German and Dutch food manufacturers balance specification rigor against total cost, driving procurement consolidation toward vertically integrated suppliers. Indian exporters navigate the steepest compliance burden for EU market access.
Spain
Extremadura's La Vera and Murcia denominaciones de origen command supply chain preference from European sauce houses seeking E160c colorant consistency. EFSA's 2023 tightened heavy metal thresholds favor domestic processors with integrated field-to-facility traceability against commodity importers. Cáceres province seed-to-extract pipelines yield cultivars exceeding 3,500 CU capsanthin content for industrial buyers.
Hungary
Kalocsa and Szeged-Tomato zone processors supply heat-calibrated grades to Central European sausage houses requiring precise Scoville consistency. REACH Annex XVII dye restrictions redirect regional procurement from synthetic azo dyes toward domestic paprika-derived carotenoids. Drought stress in concentrated growing belts compresses harvest yields and amplifies price volatility for oleoresin processors.
Germany
Swiss and German pharmaceutical formulators source high-purity antioxidant extracts for nutraceutical capsules, commanding premium pricing over food-grade specifications. ECHA's tightened limits on Tartrazine and Sunset Yellow FCF force bakery and confectionery reformulation toward botanical colorants. Retail consolidation transfers formulation specification authority to centralized technical procurement functions in Hamburg and Frankfurt.
China
Xinjiang growing belt grinding facilities compete on manufacturing scale for bulk seasoning blend commodity sales. Batch-to-batch CU consistency testing for E160c classification requires capital-intensive HPLC equipment that smaller processors struggle to finance. Cross-border recognition friction between USDA NOP and EU organic standards creates compliance timeline delays for dual-market access seekers.
India
Guntur belt processors leverage blockchain-traceable bulk platforms to contract directly with European food manufacturers, disintermediating traditional Rotterdam and Hamburg spice traders. FDA batch certification requirements for carotenoid extracts shape importer documentation and testing protocols. Near-infrared spectroscopy deployment tightens capsanthin concentration tolerances while reducing manual grading labor.
Paprika Powder Market Competitive Landscape
Capability concentration sits with seed-to-extract specialists; scale advantage sits with integrated grinding and drying operators. The market structures around three tiers: protected designation of origin cooperatives with traceable cultivation, oleoresin extractors serving pharmaceutical and nutraceutical channels, and commodity-grade volume processors competing on manufacturing throughput. Dominant competitive moves include backward integration into controlled cultivation regions and microencapsulation technology licensing for high-heat food applications.
Within the oleoresin extraction tier, Botanic Healthcare and Kalsec Natural Ingredients exemplify the seed-to-extract archetype, while Qingdao Fumanxin Foods Co., Ltd. occupies a position among scale-driven integrated processors. These three entities represent the strategic spectrum from specialized nutraceutical-grade supply to mass-market manufacturing throughput, with each archetype commanding distinct specification tolerances and procurement relationships.
| Leading Market Players |
|---|
| Naturesmith Foods LLP |
| EVE SA |
| Le Comptoir Colonial |
| Botanic Healthcare |
| Qingdao Fumanxin Foods Co., Ltd. |
| Sunrise Spices Exporters |
| Rubin Paprika Processing Ltd |
| Foodchem International Corporation |
| Kalsec Natural Ingredients |
| Others |
Pricing and Supply Chain Analysis
Spain's Extremadura and Hungary's Szeged-Tomato zone cultivation belts anchor upstream supply concentration, directing margin pools toward processors with integrated seed-to-extract pipelines and E160c color unit certification capabilities. REACH Annex XVII dye restrictions have transferred pricing power to certified clean-label suppliers while compressing commodity-grade grinding margins.
Pricing Analysis
After-sales revenue through technical color-matching services and long-term offtake contracts drives lifetime value for oleoresin processors. Three-tier pricing structure across premium denomination-of-origin, standard industrial-grade, and economy bulk commodity levels separates Spanish La Vera paprika from Xinjiang commodity powder. Price differentiation rests on capsanthin concentration certification and EU organic equivalence documentation. Cost compression in China's grinding tier is intensifying because smaller facilities cannot finance HPLC equipment for CU consistency testing. German sauce manufacturers exhibit lowest price sensitivity; bulk seasoning blenders in emerging markets show highest elasticity.
Supply Chain Analysis
Capsicum annuum feedstock cultivation concentrates in Spain, Hungary, and China's Xinjiang belt. Oleoresin extraction draws from dried pod supply, solvent processing inputs, and pharmaceutical-grade filtration systems. Single-source vulnerability runs through Hungary's drought-stressed Szeged-Tomato zone where recurring harvest compression amplifies price volatility. Distribution runs through Rotterdam and Hamburg spice traders facing disintermediation from blockchain-traceable direct-processor platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through EFSA's tightened heavy metal thresholds and REACH Annex XVII dye restrictions creates sustainable switching costs for certified suppliers.
For Market Incumbents: Insulate market position by deepening backward integration into controlled cultivation regions with documented soil testing and irrigation water analysis. Extend certification moats through simultaneous USDA NOP and EU organic equivalence to capture dual-market access. Turmeric and annatto substitution threats require microencapsulation R&D investment for high-heat food applications.
For New Entrants and Emerging Players: Pursue white-space opportunities in nutraceutical-grade oleoresin supply to Swiss and German pharmaceutical formulators demanding heavy metal thresholds below EFSA guidance. Cosmetic colorant applications under EU Cosmetics Regulation permit entry through rinse-off product formulation partnerships with natural makeup brands. Direct-to-manufacturer digital procurement platforms offer disintermediation go-to-market positioning.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed oleoresin extractors possessing seed-to-extract capabilities and established E160c certification infrastructure. Five-to-ten year viability hinges on climate adaptation investments in drought-stressed Hungarian and Spanish growing belts. The signal to watch is consolidation momentum among India's Guntur belt processors deploying near-infrared spectroscopy quality control.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controlled Cultivation | Spanish processors in Cáceres province secure capsanthin content above 3,500 CU through seed breeding pipelines. |
| Microencapsulation Technology Licensing | Enables paprika carotenoid stability in high-heat bakery applications above 60°C processing thresholds. |
| Blockchain-Traceable Digital Procurement Platform | Indian Guntur processors contract directly with European manufacturers, bypassing Rotterdam trader margins. |
| Dual Organic Certification Investment | Cross-border USDA NOP and EU organic equivalence reduces compliance timeline friction for dual-market access. |
| Nutraceutical-Grade Extraction Capacity Expansion | Swiss and German pharmaceutical formulators pay premium pricing for antioxidant supplement capsule supply. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with oleoresin extraction plant managers, European sauce house procurement leads, spice distribution channel partners, and pharmaceutical formulator technical directors; and secondary validation through EFSA additive guidance documents, ECHA REACH Annex XVII regulatory filings, customs trade data for paprika powder shipments, and SEC 10-K disclosures from listed natural ingredients companies. Bottom-up volume modeling across color unit specifications and top-down value triangulation against extraction capacity data were cross-referenced for convergence.
Forecast inputs considered product type segmentation across sweet, smoked, and hot varieties; application splits between food industry, cosmetics, pharmaceuticals, and culinary arts; and distribution channel dynamics including wholesale, online retail, supermarkets, and specialty stores. CAGRs were derived from regression analysis of historical procurement volume patterns and regulatory-driven substitution elasticities. Capsicum annuum breeding program yields and climate stress projections for Hungary's Szeged-Tomato zone informed supply-side constraints.
Sensitivities concentrate around EFSA regulatory enforcement intensity, drought frequency in Extremadura and Szeged-Tomato cultivation belts, and turmeric substitution rates in yellow-orange colorant segments. Forecasts embed assumptions about clean-label retail mandate expansion and carbon footprint disclosure requirements. Cross-checking against EU import statistics for E160c-classified colorants and pharmaceutical oleoresin customs data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Organic Spices and Herbs Market
Spices and Seasonings
Cajun Seasoning Market
Spices and Seasonings
Pepper Market
Spices and Seasonings
Ginger Salt Market
Spices and Seasonings
Poultry Seasoning Market
Spices and Seasonings
Dried Herbs Market
Spices and Seasonings
Global Black Pepper Market
Spices and Seasonings
Espresso Salt Market
Spices and Seasonings
Carthamus Yellow Market
Spices and Seasonings
Tamarind Extract Market
Spices and Seasonings
Onion Oil Market
Spices and Seasonings
Wild Cherry Powder Market
Spices and Seasonings
Plastic Spice Jars Market
Spices and Seasonings
Global Clove Market
Spices and Seasonings
Bay Leaf Market
Spices and Seasonings
Pumpkin Pie Spices Market