
 Organic Spices and Herbs Market | 2026-2036
Organic Spices and Herbs Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Spices and Herbs Market Outlook
USDA Organic certification is redrawing competitive boundaries in the organic spices and herbs supply base. McCormick & Company leverages its vertically integrated sourcing network across multiple equatorial origins. Simply Organic sustains brand equity through exclusive organic positioning in mainstream retail channels. Frontier Co-op anchors the North American cooperative purchasing model with member-governed quality protocols.
Organic spices and herbs denote plant-derived flavoring and aromatic materials cultivated without synthetic pesticides, genetically modified organisms, or irradiation, then processed to moisture specifications typically below 12 percent to prevent microbial degradation. These materials function as clean-label flavoring agents in food manufacturing, food service preparation, and direct consumer cooking applications. The powdered form commands the widest addressable market due to its compatibility with industrial blending and extended shelf stability. Whole spices retain premium positioning among specialty retail and food service buyers seeking visible provenance cues. The food service end user segment generates concentrated volume demand from chain restaurant reformulations targeting ingredient transparency claims.
USDA Organic standards, EU Organic Regulation 2018/848, and India's NPOP accreditation framework collectively determine which suppliers qualify for cross-border trade in certified organic spices. These certification regimes impose multi-year conversion timelines, traceability documentation, and residue testing that filter out conventional commodity traders. Stakeholders must monitor evolving equivalency agreements between the USDA National Organic Program and India's APEDA to anticipate sourcing disruption risks.
Market Dynamics
Certification scarcity is compressing supplier eligibility across the organic spices and herbs value chain, as multi-year conversion timelines and residue testing protocols filter out conventional commodity traders who lack traceable farmgate relationships.
Growth Catalysts
- EU Organic Regulation 2018/848:The regulation's stricter residue thresholds and group certification rules are accelerating farm-level consolidation in Madagascar and Vietnam, favoring cooperatives with documented traceability systems over spot-market intermediaries.
- Clean-label reformulation:Food service chains in the United States are specifying organic herb inputs for seasoning blends and prepared sauces, creating pull-through demand that extends backward to certified cultivation contracts in Kerala and Karnataka.
- Steam sterilization:Non-thermal decontamination technology is expanding addressable supply by enabling organic processors to meet microbial specifications without irradiation, opening EU market access for Indian and Sri Lankan exporters previously blocked by ethylene oxide restrictions.
Market Restraints
- Vanilla supply concentration:Madagascar's SAVA region produces over eighty percent of global Bourbon vanilla, exposing buyers to cyclone disruption and price volatility that conventional synthetic vanillin cannot fully hedge.
- Multi-year organic conversion:The USDA National Organic Program's thirty-six-month transition period locks land out of premium pricing during soil recovery, constraining acreage expansion in response to demand signals.
- Input cost volatility:Organic manure and biocontrol agent prices track fossil fuel and agricultural commodity indices, compressing farmgate margins when certification premiums fail to adjust within single growing seasons.
Strategic Opportunities
- Direct-to-chef distribution:Specialty spice merchants are bypassing traditional food service broadline distributors to sell traceable single-origin lots directly to independent restaurants, capturing margin and provenance storytelling value.
- Carbon credit stacking:Organic cultivation systems in India qualify for voluntary carbon market protocols, allowing farmers to layer climate finance revenue atop organic premiums and improve project economics.
- Regenerative organic certification:The Regenerative Organic Certified standard's soil health and animal welfare add-ons command additional shelf price premiums in United States natural retail channels beyond baseline USDA Organic.
Industry Challenges
- Certification timeline compression:Buyers demand twelve-month supplier onboarding while organic conversion and audit cycles require thirty-six months, creating procurement gaps filled by uncertified transitional material.
- Traceability system integration:Blockchain and ERP platforms at processing facilities must interface with paper-based farm records in origin countries, generating data reconciliation costs and verification delays.
- Post-harvest handling expertise:Moisture management and mold prevention during monsoon drying seasons require technical skills scarce among smallholder cooperatives, elevating rejection rates at EU border inspection points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Spices and Herbs Market |
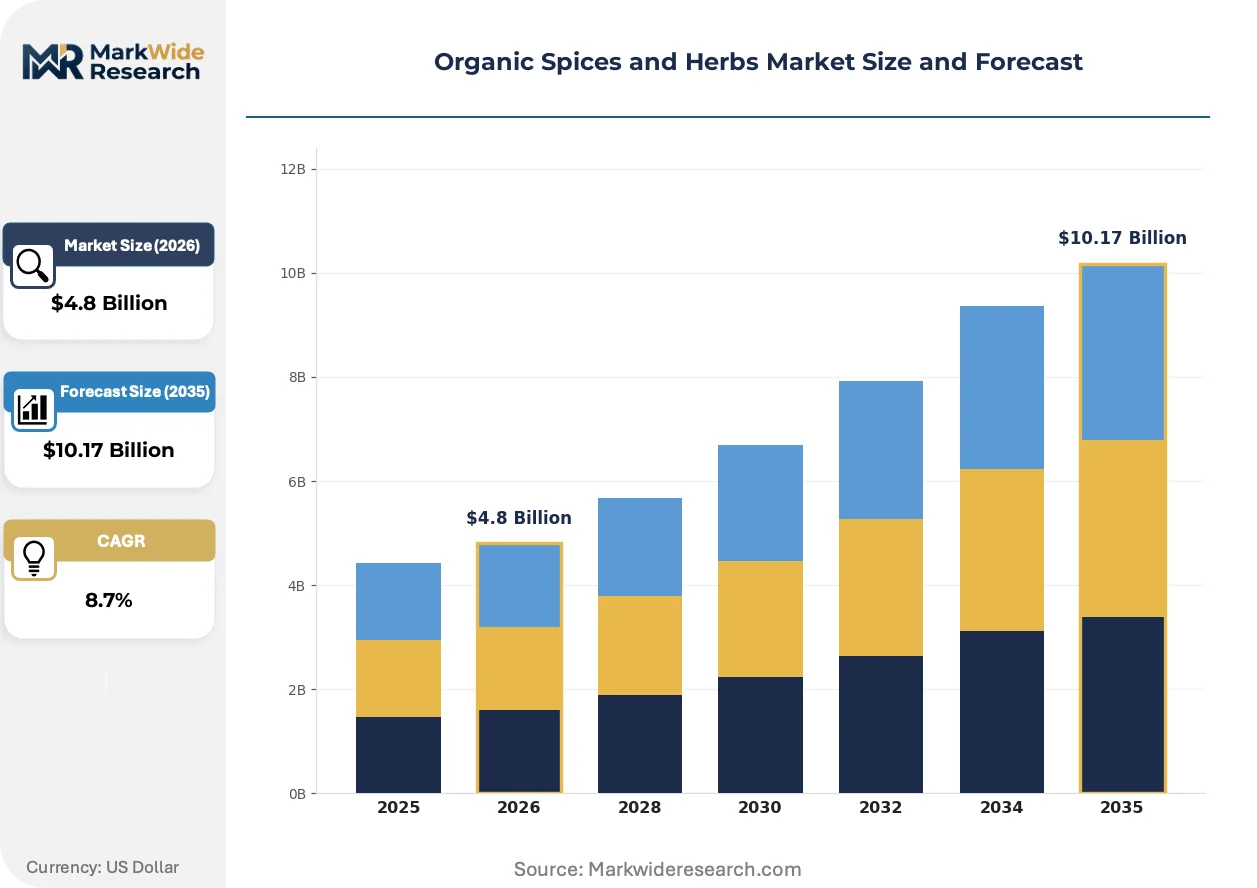
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cilantro, Oregano, Basil, Thyme Form: Whole, Powdered, Flakes, Crushed Distribution Channel: Retail, Online, Wholesale, Supermarkets End User: Food Service, Household, Food Processing, Retailers |
| Companies Covered | Rapid Organics Pvt Ltd, Curio Spice Company, McCormick & Company, Simply Organic, Suminter India Organics, Organic Spices Inc., Starwest Botanicals Inc., The Spice Hunter Inc., Frontier Co-op, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Spices and Herbs Market Strategic Shifts
Technology adoption and regulatory tightening are redrawing operational requirements across cultivation, processing, and distribution stages, with implications for capital deployment and supplier qualification criteria.
Near-infrared spectroscopy is displacing laboratory chromatography for rapid authenticity and adulteration screening at receiving docks. Large-scale food manufacturers in Germany and the Netherlands are deploying handheld NIR devices to verify botanical identity and detect synthetic dye contamination in turmeric and paprika lots within minutes rather than days. This displacement is compressing the economic viability of centralized third-party testing laboratories and shifting quality assurance budgets toward capital equipment and operator training.
REACH Annex XVII restrictions on ethylene oxide residues in food contact materials are forcing European importers to reject treated spices from major origins. The regulation's one-ppm detection limit has triggered supply chain reconfiguration, with processors in India and Vietnam investing in steam sterilization infrastructure to retain market access. Organic-certified material faces heightened scrutiny as conventional exporters attempt to pivot toward compliant treatment methods, creating certification authentication demand.
Buyer concentration among multinational food service reformulation programs is compressing supplier negotiation leverage. Chains with thousand-plus unit footprints are consolidating organic herb procurement under single-source contracts with multi-year volume commitments, displacing fragmented spot purchasing through regional distributors. This consolidation is most visible in the United States, where clean-label menu transparency claims have become competitive necessities for quick-service and fast-casual segments targeting health-conscious demographics.
Organic Spices and Herbs Market Segmentation
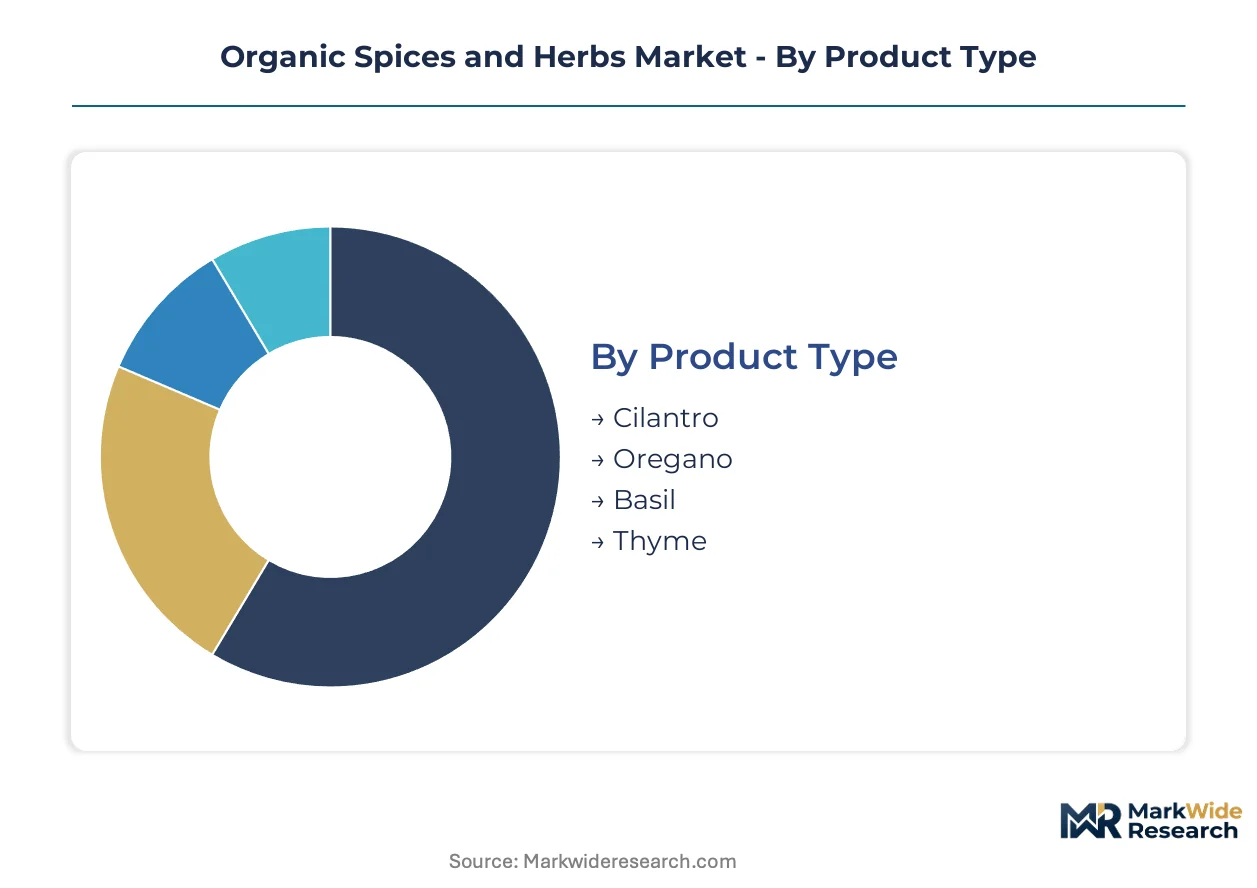
Segmentation in organic spices and herbs reveals how certification premiums, shelf stability requirements, and channel access rules create divergent margin structures across product formats and customer types. Buyers in food manufacturing and food service apply distinct procurement criteria that reshape supplier qualification priorities.
Product Type:
Margin pools concentrate in varietals where organic conversion timelines and regional specialization create supply scarcity. Cilantro and oregano command distinct premium trajectories based on perishability profiles and regional cultivation concentration.
- Cilantro:This leafy annual requires rapid post-harvest cooling to preserve volatile aromatic compounds, limiting organic sourcing to regions with established cold chain infrastructure such as California's Central Valley and coastal Karnataka. Demand from fresh salsa manufacturers and food service prep kitchens drives contract premiums for certified lots with documented harvest-to-dock traceability.
- Oregano:Mediterranean-origin cultivars carry terroir-linked pricing power in specialty retail, with Turkish and Greek organic harvests capturing shelf price multiples over commodity alternatives. Dried leaf oregano for pizza chain seasoning blends represents concentrated volume demand with stringent microbial specification requirements.
- Basil:Sweet basil dominates pesto manufacturing inputs, while Thai and holy basil varietals serve distinct ethnic food processing segments with separate organic certification audit protocols.
- Thyme:Low moisture content and robust essential oil retention make this perennial herb suitable for extended supply chains reaching northern European manufacturing hubs.
Cilantro holds installed capacity in North American fresh processing. Oregano is rotating up the share rankings in clean-label seasoning blend reformulations.
Form:
Processing intensity and capital equipment requirements stratify profitability across physical formats, with powder production demanding the most significant milling and contamination control investments.
- Powdered:Fine particle size enables homogeneous blending in industrial sauce and seasoning applications, though heat generation during milling degrades volatile oils and necessitates cryogenic processing for premium grades. Powdered turmeric and paprika face heightened adulteration scrutiny in EU import channels following REACH Annex XVII enforcement.
- Whole:Intact seeds, pods, and bark pieces carry provenance visibility valued by specialty retailers and independent restaurants seeking origin storytelling for menu transparency claims. Whole black pepper and cinnamon quills retain premium positioning in direct-to-chef distribution models bypassing broadline distributors.
- Flakes:Intermediate particle size suits visual garnish applications in food service where herb identity must remain discernible.
- Crushed:Coarse fragmentation balances surface area exposure for flavor release with reduced dusting losses during bulk handling operations.
Powdered form maintains dominant volume share in food manufacturing procurement. Whole spices are climbing the fastest in specialty retail channel expansion.
Distribution Channel:
Channel selection determines margin capture versus volume throughput tradeoffs, with direct relationships enabling certification authentication that third-party intermediaries cannot reliably verify.
- Wholesale:Food service broadline distributors consolidate organic herb procurement for multi-unit restaurant chains, extracting volume discounts while demanding multi-year supply commitments and documented traceability systems. This channel concentrates demand for standardized powdered formats with consistent color and moisture specifications.
- Retail:Mainstream grocery placement requires USDA Organic or EU Organic Regulation labeling compliance, with slotting fees and promotional spend compressing net margins for branded entrants competing against private label alternatives.
- Supermarkets:Natural and conventional grocery chains operate separate reset cycles for spice category planograms, with organic SKUs gaining linear footage in perimeter fresh departments.
- Online:Direct-to-consumer platforms enable single-origin storytelling and subscription replenishment models, though shipping costs and packaging requirements alter unit economics versus brick-and-mortar alternatives.
Wholesale channels hold established infrastructure for food service volume. Online distribution is gaining share fastest in specialty and direct-to-chef segments.
End User:
Customer type dictates specification stringency, with food processors applying residue thresholds and microbial limits that household buyers rarely enforce.
- Food Processing:Clean-label reformulation programs at sauce and seasoning manufacturers specify organic herb inputs to support ingredient transparency claims on retail packaging. These buyers require certificate of analysis documentation, steam sterilization validation, and lot-level traceability that filters out uncertified spot market suppliers.
- Food Service:Chain restaurant procurement teams consolidate organic seasoning blend specifications across thousand-plus unit footprints, creating concentrated demand pull with stringent food safety audit requirements.
- Household:Direct consumer purchases through retail and online channels prioritize packaging convenience and recipe inspiration content over technical specification documentation.
- Retailers:Private label development teams source organic herbs for store-brand spice lines, applying margin targets that compete with national branded alternatives.
Food Processing holds dominant procurement volume in certified organic inputs. Food Service is expanding most quickly in clean-label menu reformulation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Organic Regulation 2018/848 and India's NPOP accreditation framework are redirecting procurement flows toward certified origins with traceable farmgate systems. USDA National Organic Program equivalency negotiations with APEDA determine cross-border eligibility for Indian exporters. Madagascar's SAVA region, Vietnam's Central Highlands, and India's Kerala and Karnataka states anchor raw material concentration for vanilla, pepper, and cardamom respectively.
United States
Clean-label reformulation at food service chains drives organic herb procurement consolidation under multi-year contracts. FDA food safety modernization rules intersect with USDA Organic audit requirements for imported spice lots. California's Central Valley hosts contracted cilantro cultivation with rapid post-harvest cooling infrastructure serving fresh salsa manufacturers.
Germany
REACH Annex XVII ethylene oxide restrictions force rejection of treated spice imports from conventional origins. ECHA enforcement of one-ppm detection limits triggers supply chain reconfiguration toward steam-sterilized alternatives. Hamburg and Rotterdam ports serve as inspection gateways where near-infrared spectroscopy accelerates contamination screening for turmeric and paprika shipments.
India
NPOP-accredited cooperatives in Kerala and Karnataka capture contract premiums from European buyers demanding documented traceability. APEDA manages equivalency negotiations with USDA National Organic Program that determine American market access for Indian exporters. The Western Ghats region concentrates cardamom and pepper cultivation where smallholder cooperatives layer carbon credit revenue atop organic premiums.
Madagascar
Cyclone exposure in the SAVA region generates price volatility that synthetic vanillin cannot fully hedge for Bourbon vanilla buyers. The country's national agricultural regulator enforces group certification rules that favor documented cooperatives over spot-market intermediaries. Vanilla curing and conditioning infrastructure in Sambava and Antalaha faces moisture management challenges during monsoon seasons.
Vietnam
EU Organic Regulation stricter residue thresholds accelerate farm-level consolidation in the Central Highlands pepper belt. The Ministry of Agriculture and Rural Development oversees conversion timelines that lock land out of premium pricing during soil recovery. Dak Lak and Gia Lai provinces host cooperative processing facilities investing in steam sterilization to retain European market access.
Organic Spices and Herbs Market Competitive Environment
Listed leaders compete with private specialists across certification depth and origin control dimensions. The supplier base stratifies between vertically integrated multinationals with captive sourcing networks and cooperative-governed specialists with member-quality protocols. Three archetypes dominate: equatorial-origin aggregators with multi-crop farmgate relationships, North American brand houses with retail shelf positioning, and cooperative processors with democratic governance structures. Competitive moves center on backward integration into curing and sterilization infrastructure, plus direct-to-chef distribution bypassing broadline intermediaries.
Within the cooperative-processor tier, Frontier Co-op and Suminter India Organics exemplify member-governed quality systems that filter conventional commodity traders. Among brand-positioned players, Simply Organic occupies a premium-tier slot through exclusive organic positioning in mainstream retail channels. McCormick & Company anchors the vertically integrated archetype with multi-origin sourcing networks spanning Madagascar, Vietnam, and India. Rapid Organics Pvt Ltd represents the specialist fabricator category with concentrated Indian subcontinent operations.
| Leading Market Players |
|---|
| Rapid Organics Pvt Ltd |
| Curio Spice Company |
| McCormick & Company |
| Simply Organic |
| Suminter India Organics |
| Organic Spices Inc. |
| Starwest Botanicals Inc. |
| The Spice Hunter Inc. |
| Frontier Co-op |
| Others |
Value Chain & Pricing Dynamics
USDA Organic and EU Organic Regulation 2018/848 certification requirements simultaneously gate supplier eligibility and stratify price premiums across the organic spices and herbs value chain, compressing qualified sourcing pools while amplifying margin capture for certified cooperatives with documented traceability systems.
Pricing Analysis
Certification level (USDA Organic versus transitional or conventional) creates the primary spread between farmgate and shelf pricing tiers. Three-tier pricing structure across premium certified, standard organic, and economy conventional levels dominates procurement contracts, with EU Organic Regulation compliance commanding additional premiums over baseline USDA standards. Pricing pressure stems from input cost volatility in organic manure and biocontrol agents tracking fossil fuel indices. Food service chains with thousand-plus unit footprints exhibit lowest price sensitivity due to menu transparency claim requirements, while private label retail development teams face acute margin compression.
Supply Chain Analysis
Strategic stockpiling of whole spices during harvest windows contrasts with just-in-time powdered format procurement tied to food manufacturing batch schedules. Geographic concentration centers on Madagascar for vanilla, Vietnam for pepper, and India's Kerala and Karnataka states for cardamom and cinnamon. Raw material dependencies include Bourbon vanilla curing capacity, steam sterilization infrastructure, and cryogenic milling equipment for volatile oil retention. Single-source vulnerability in Madagascar's SAVA region exposes buyers to cyclone disruption. Distribution runs through Hamburg and Rotterdam inspection gateways for European entry, with direct-to-chef channels bypassing broadline intermediaries for specialty retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steam sterilization technology adoption represents a regulatory inflection disrupting ethylene oxide-dependent supply chains, creating first-mover advantage windows for compliant processors while accelerating certification authentication demand across European import channels.
For Market Incumbents: Fortify backward integration into curing and sterilization infrastructure across Madagascar, Vietnam, and Indian origins to capture margin pools eroding to spot-market intermediaries. McCormick-style multi-origin sourcing networks defend against single-source disruption while cooperative governance models like Frontier Co-op anchor member-quality protocols against commodity trader encroachment. Certification depth investment in Regenerative Organic Certified standards opens additional shelf price premiums beyond baseline USDA compliance. For New Entrants and Emerging Players: USDA National Organic Program equivalency fast-track negotiations with India's APEDA create procurement gap opportunities for transitional material during thirty-six-month conversion timelines. Direct-to-chef distribution bypassing broadline food service distributors captures provenance storytelling value in independent restaurant segments. Carbon credit stacking protocols in India's Western Ghats region enable climate finance revenue layering atop organic premiums for cooperative-structured entrants. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across steam sterilization infrastructure and near-infrared spectroscopy quality assurance equipment. Five-to-ten year viability favors processors with captive sourcing networks and documented traceability systems over conventional commodity traders. Acquisition targets should demonstrate established farmgate relationships in cyclone-exposed origins or EU Organic Regulation compliance infrastructure. Signal to monitor: equivalency agreement finalization between USDA and APEDA determining Indian exporter market access.| Strategic Initiative | Industry Significance |
|---|---|
| Steam Sterilization Infrastructure Investment | Enables EU market retention under REACH Annex XVII ethylene oxide restrictions for Indian and Vietnamese exporters. |
| Direct-to-Chef Distribution Buildout | Bypasses broadline food service intermediaries to capture margin and provenance value in independent restaurant channels. |
| Regenerative Organic Certification Pursuit | Commands additional shelf price premiums in United States natural retail beyond baseline USDA Organic positioning. |
| Carbon Credit Protocol Enrollment | Layers climate finance revenue atop organic premiums for Indian smallholder cooperatives in Western Ghats cultivation zones. |
| Near-Infrared Spectroscopy Deployment | Displaces centralized laboratory testing for rapid adulteration screening at German and Dutch manufacturing receiving docks. |
Study Parameters
Operator-level perspectives from organic spice procurement managers at food service chains, quality assurance directors at seasoning blend manufacturers, cooperative governance leaders in Kerala and Karnataka, and European import compliance officers anchored the qualitative base. Secondary validation drew from USDA National Organic Program equivalency filings, APEDA export documentation, ECHA REACH enforcement notices, and customs trade flow records. Bottom-up cultivation area estimates triangulated against top-down food manufacturing demand models across the projection horizon.
Sensitivity analysis around conversion timeline assumptions and cyclone frequency parameters shaped the analytical framework. Segmentation dimensions modeled include product form, certification tier, distribution channel, and end-user specification stringency. CAGRs derived from fitted growth curves applied to certified acreage expansion trajectories and food service reformulation program commitments. Industry-specific inputs encompassed vanilla curing capacity utilization and steam sterilization adoption rates across Indian and Vietnamese processing facilities.
Underlying assumptions cover sustained clean-label menu transparency investment by United States food service chains, with deviation risk concentrated in equivalency agreement delays between USDA and APEDA. Forecasts reflect these conditions without explicit probability weighting. Revision becomes warranted when ethylene oxide regulatory enforcement thresholds tighten beyond current one-ppm detection limits or cyclone disruption frequency in Madagascar's SAVA region exceeds historical baselines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Poultry Seasoning Market
Spices and Seasonings
Middle East and Africa Botanical Extract Market
Spices and Seasonings
Tamarind Extract Market
Spices and Seasonings
Chef Bases Market
Spices and Seasonings
Mustard Market
Spices and Seasonings
Europe Seasoning Market
Spices and Seasonings
Smoked Salt Market
Spices and Seasonings
All-Purpose Seasoning Market
Spices and Seasonings
Jalapeno Salt Market
Spices and Seasonings
Blended Spices Market
Spices and Seasonings
Achiote Powder Market
Spices and Seasonings
Cardamom Oil Market
Spices and Seasonings
US Spice and Seasonings Market
Spices and Seasonings
Habanero Salt Market
Spices and Seasonings
Bolivian Rose Salt Market
Spices and Seasonings
Serrata Extract Market