
 Boutique Salt Market | 2026-2036
Boutique Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Boutique Salt Market Outlook
EU REACH compliance is decoupling small importers from viable market participation. Maldon Salt Company leverages its Essex-based harvesting heritage to sustain British retail dominance. SaltWorks anchors North American supply through vertically integrated solar evaporation facilities in Washington State. Murray River Salt competes via its distinctive pink flake profile sourced from Australian inland brines.
Boutique salt denotes hand-harvested or minimally processed sodium chloride varieties distinguished by mineral content, crystal structure, moisture retention, and terroir-specific flavor profiles, serving primarily as a premium culinary finishing ingredient or wellness positioning element. Sea salt and Himalayan salt occupy the largest volume positions, with Himalayan salt commanding higher per-unit margins due to perceived trace mineral benefits. Flavored salt represents the fastest-expanding product type as infusion techniques diversify beyond conventional herb and smoke profiles into fermented and botanical blends.
FDA labeling requirements for sodium content disclosure shape American product formulation and portion packaging decisions, while EFSA purity standards govern allowable heavy metal thresholds for European import clearance. India's FSSAI mandates iodization for table salt but exempts specialty grades, creating a regulatory carve-out for artisan producers. Stakeholders must monitor evolving salt-as-nutrient versus salt-as-ingredient classification debates that threaten to reclassify boutique varieties under stricter dietary supplement or food additive regimes.
Market Dynamics
EU REACH compliance and the F-Gas Regulation are structurally decoupling small importers from viable European market participation, while traceability mandates from gourmet restaurant procurement departments concentrate demand around heritage-proven harvesting sites.
Growth Catalysts
- F-Gas Regulation:The EU's phasedown of hydrofluorocarbons in processing equipment elevates capital barriers for industrial-scale competitors, creating protected space for solar-evaporation artisans.
- Gourmet restaurant specification:Michelin-tier kitchens in France, Italy, and Spain now mandate origin documentation for finishing salts, locking in premium supply relationships.
- Botanical fermentation:Novel infusion techniques using koji and lacto-fermentation are expanding flavor salt repertoires beyond smoke and herb conventions.
Market Restraints
- Harvest concentration:Traditional fleur de sel production clusters on France's Guérande peninsula, exposing supply to single-region weather volatility.
- Import friction:EFSA heavy metal thresholds and REACH registration costs block artisan producers from India and Pakistan without dedicated compliance infrastructure.
- Table salt substitution:Iodized commodity salt at 1/50th the unit cost satisfies baseline culinary sodium needs for price-sensitive foodservice accounts.
Strategic Opportunities
- Japanese umami convergence:Collaboration between French sel gris producers and Japanese miso houses creates hybrid fermentation-salt products for export to North American specialty retailers.
- FSSAI exemption carve-out:India's specialty-grade iodization waiver permits artisan producers to access a 1.4 billion-person market without mandatory fortification investment.
- Direct-to-chef platforms:Vertical procurement apps connecting Australian pink flake harvesters directly to restaurant kitchens bypass traditional import-distributor markups.
Industry Challenges
- Palatability certification timelines:Novel fermented salt blends face extended EFSA novel food dossier review periods averaging 18-24 months.
- Heritage harvesting labor:Traditional raking skills for fleur de sel crystallization lack formal apprenticeship pipelines in coastal Brittany.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boutique Salt Market |
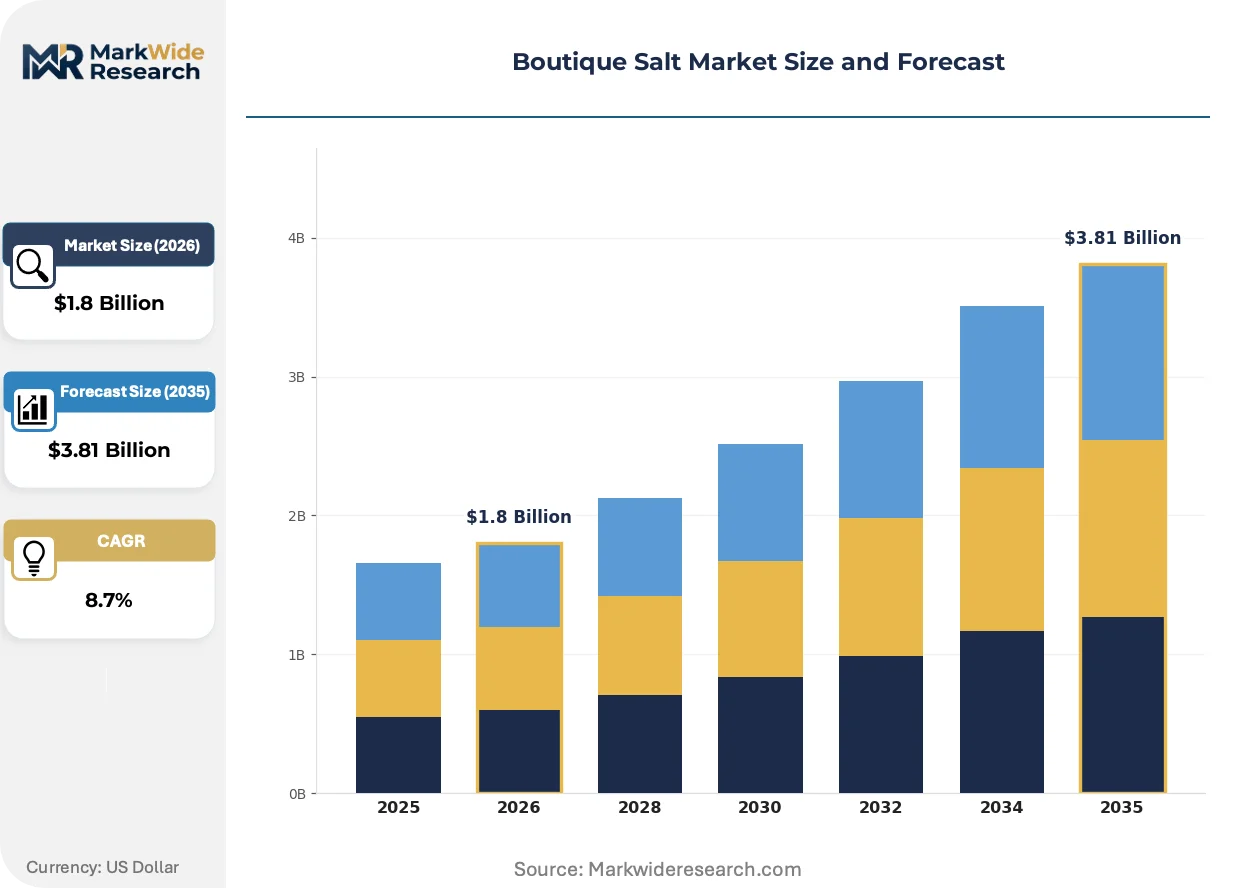
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Himalayan Salt, Sea Salt, Flavored Salt, Black Salt Packaging Type: Glass Jars, Pouches, Bulk Bags, Sachets End User: Restaurants, Home Cooks, Food Manufacturers, Health Stores Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Farmers' Markets |
| Companies Covered | Maldon Salt Company, SaltWorks, Falksalt, Himalayan Chef, Jacobsen Salt Co., Murray River Salt, Celtic Sea Salt, Redmond Real Salt, Bitterman Salt Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boutique Salt Market Strategic Shifts
Processing transparency and terroir authentication technologies are compressing the distance between harvest site and end-user verification, while regulatory classification debates threaten to recategorize mineral-rich varieties under supplement rather than ingredient regimes.
Hyperspectral imaging paired with blockchain provenance tracking is rewriting how authenticity is verified across the boutique salt value chain. Gourmet retailers in Germany and the Netherlands now require spectroscopic mineral fingerprinting for shelf placement. This compression of verification cost is enabling smaller harvesters to bypass traditional certification gatekeepers.
REACH Annex XVII restrictions on heavy metal content are tightening allowable lead and cadmium thresholds for imported specialty salts. European customs authorities now demand third-party laboratory certificates for each shipment lot. Himalayan-origin suppliers are responding by investing in washing and magnetic separation infrastructure to meet the revised purity bands.
Chef procurement teams are consolidating supplier relationships around vertically integrated harvesters who control evaporation, packaging, and cold-chain logistics internally. Traditional import-distributor networks in the United States are losing share to direct freight arrangements from Washington State solar facilities to restaurant group central kitchens. This disintermediation is most visible in California and New York metropolitan foodservice markets.
Boutique Salt Market Segmentation
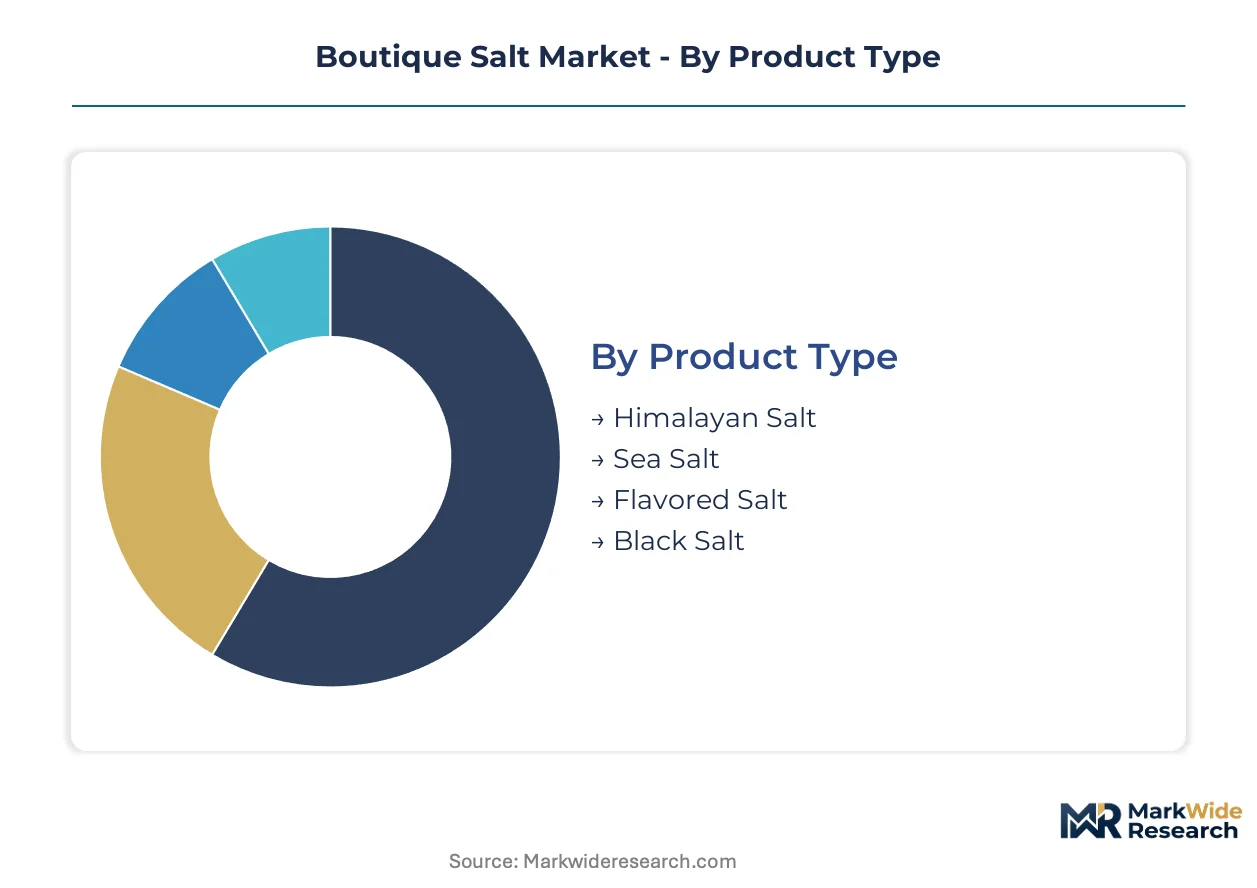
Boutique salt producers configure their operations around crystallization method and mineral signature, with each segment demanding distinct harvesting infrastructure and compliance protocols. Segmentation clarity determines which producers capture Michelin-tier procurement contracts versus commodity foodservice supply.
Product Type:
Solar evaporation sites and underground mining operations concentrate supply in terroir-proven locations, locking in origin-based pricing premiums.
- Himalayan Salt:Mined from Khewra salt deposits in Pakistan's Punjab region, this pink-hued variety carries elevated iron oxide and trace mineral content. Wellness retailers in Germany and the Netherlands stockpile spectroscopically certified lots to satisfy EFSA heavy metal thresholds.
- Sea Salt:Hand-raked from coastal evaporation ponds, fleur de sel and sel gris variants retain residual moisture and irregular crystal geometry. Brittany's Guérande peninsula supplies the majority of Michelin-starred kitchens across France, Italy, and Spain.
- Flavored Salt:Infusion techniques now span koji fermentation, lacto-fermented botanicals, and cold-smoked preparations.
- Black Salt:Kiln-fired Indian kala namak delivers sulfurous aroma profiles prized in South Asian cuisine and vegan egg-replacement formulations.
Himalayan salt absorbs the bulk of installed mining and washing capacity; flavored salt is expanding most quickly as fermentation techniques diversify beyond smoke and herb conventions.
Packaging Type:
Packaging selection tracks directly to end-use freshness requirements and retail channel shelf-life demands.
- Glass Jars:Hermetic sealing preserves moisture-sensitive fleur de sel crystallization structures. Premium grocers in California and New York metropolitan markets mandate tamper-evident closures for shelf placement.
- Pouches:Multi-layer barrier films with nitrogen flushing extend shelf stability for high-volume foodservice accounts. Australian pink flake exporters favor stand-up pouches for direct freight arrangements to restaurant group central kitchens.
- Bulk Bags:Food manufacturers sourcing for processed snack and seasoning blends require moisture-controlled super sacks.
- Sachets:Single-serve portions dominate airline catering and boutique hotel amenity programs.
Glass jars command the highest unit margins; pouches are climbing the fastest as direct-to-chef platforms displace traditional distributor networks.
End User:
Procurement sophistication varies dramatically across user categories, from traceability-mandated restaurant specifications to price-sensitive home cook experimentation.
- Restaurants:Chef procurement teams now require blockchain-documented provenance for finishing salt specifications. Washington State solar evaporation facilities ship direct to California and New York metropolitan foodservice markets, bypassing import-distributor markups.
- Home Cooks:Specialty retailers curate discovery-oriented assortments emphasizing terroir storytelling and harvest methodology education.
- Food Manufacturers:Processed food accounts prioritize batch consistency and iodization exemption documentation for export labeling.
- Health Stores:Wellness positioning demands third-party mineral analysis and heavy metal screening certificates.
Restaurants anchor premium volume commitments; health stores are gaining share fastest as mineral supplementation narratives expand consumer willingness-to-pay.
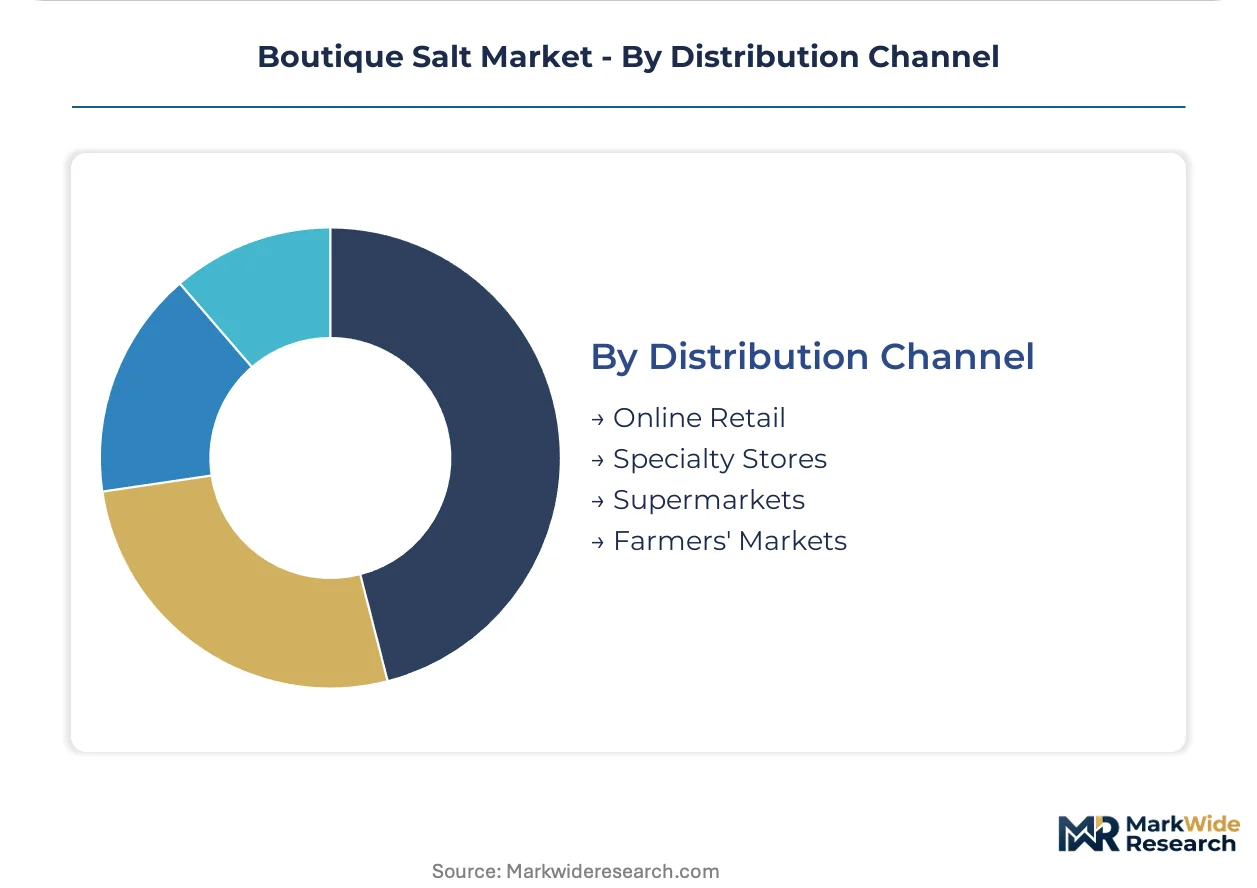
Distribution Channel:
Channel selection determines margin capture and brand narrative control, with disintermediation compressing traditional wholesale markups.
- Online Retail:Direct-to-consumer platforms enable harvester-controlled storytelling and subscription replenishment models. SaltWorks leverages vertically integrated Washington State facilities for domestic e-commerce fulfillment.
- Specialty Stores:Curated assortments in gourmet grocers require spectroscopic mineral fingerprinting for shelf placement authorization.
- Supermarkets:Mass retail placement demands scaled production and uniform packaging formats across SKU ranges.
- Farmers' Markets:Hyperlocal harvesters in France's Brittany coast sell unbranded fleur de sel crystallized within 48 hours of raking.
Online retail captures the steepest expansion trajectory; specialty stores retain the highest average transaction values per basket.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's Guérande peninsula operates as a de facto special economic zone for heritage salt harvesting, with Brittany's traditional raking methods attracting Michelin-tier procurement contracts from across Europe.
France
Gourmet restaurants in Paris, Lyon, and Marseille specify traceable origin fleur de sel for finishing dishes. EFSA heavy metal thresholds and REACH compliance requirements govern allowable import purity standards for specialty grades. The Guérande peninsula concentrates traditional solar evaporation operations where hand-raking skills sustain premium positioning against industrial competitors.
United States
Chef procurement teams in California and New York metropolitan markets mandate blockchain-documented provenance for restaurant supply. FDA labeling requirements for sodium content disclosure shape product formulation and portion packaging decisions. Washington State solar evaporation facilities ship direct to foodservice central kitchens, bypassing traditional import-distributor markups.
Germany
Wellness retailers in Berlin, Munich, and Hamburg stockpile spectroscopically certified Himalayan salt lots to satisfy mineral supplementation narratives. REACH Annex XVII restrictions on heavy metal content tighten allowable lead and cadmium thresholds for imported specialty salts. Gourmet grocers in the Rhine-Ruhr region now require spectroscopic mineral fingerprinting for boutique salt shelf placement authorization.
Australia
Health stores in Sydney and Melbourne drive demand for distinctive pink flake profiles sourced from inland brines. The country's national food standards regulator mandates labeling compliance for mineral content claims on wellness-positioned products. Murray River basin harvesting operations compete via direct-to-chef platforms connecting harvesters to restaurant kitchens without distributor intermediaries.
India
Artisan producers leverage FSSAI specialty-grade iodization exemptions to access domestic and export markets without mandatory fortification investment. The country's food safety regulator permits non-iodized salt for specialty grades, creating a regulatory carve-out for traditional black salt and kala namak producers. Rajasthan and Gujarat harbor underground mining and kiln-fired processing clusters serving South Asian cuisine and vegan egg-replacement formulations.
Boutique Salt Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the boutique salt value chain. The vendor base stratifies into three tiers: heritage-proven European harvesters, vertically integrated North American solar operators, and mineral-specialist South Asian mining houses. Two dominant competitive moves define current positioning: backward integration into captive evaporation and packaging infrastructure, and direct-to-chef platform development that displaces traditional wholesale networks.
Among heritage European harvesters, Maldon Salt Company and Falksalt occupy positions defined by geographic provenance and terroir authentication. SaltWorks anchors the North American tier through in-house production of solar-evaporated grades from Washington State facilities. These three exemplify how origin documentation and processing transparency now determine competitive viability against commodity salt alternatives.
| Leading Market Players |
|---|
| Maldon Salt Company |
| SaltWorks |
| Falksalt |
| Himalayan Chef |
| Jacobsen Salt Co. |
| Murray River Salt |
| Celtic Sea Salt |
| Redmond Real Salt |
| Bitterman Salt Co. |
| Others |
Value Chain & Pricing Dynamics
Backward integration into captive evaporation and packaging infrastructure anchors supply positions and pricing power for heritage harvesters facing REACH compliance cost escalation. Solar-evaporation artisans in Washington State and Brittany bypass import-distributor markups through direct freight arrangements, compressing delivered costs while preserving premium positioning against commodity alternatives.
Pricing Analysis
Short lead-time premiums for blockchain-documented provenance separate Michelin-tier procurement contracts from spot-market commodity salt. Three-tier pricing structure across heritage-certified, specialty-grade, and bulk foodservice levels tracks crystallization method and mineral authentication intensity. Cost compression in standard-grade pouches intensifies as Australian and Indian exporters scale direct-to-chef platforms. Home cooks exhibit highest price sensitivity, while chef procurement teams prioritize traceability over unit cost.
Supply Chain Analysis
Traditional raking skills shortage in coastal Brittany constrains fleur de sel output expansion despite demand concentration from French, Italian, and Spanish restaurants. Supply draws from Pakistan's Khewra mining corridor, Australia's Murray River basin, and France's Guérande peninsula as dominant extraction nodes. Solar evaporation ponds, hand-raking equipment, and spectroscopic certification infrastructure constitute critical input dependencies. Single-region weather volatility on the Guérande peninsula poses structural supply risk. Distribution runs through vertically integrated harvester-to-kitchen direct freight, displacing traditional import-distributor networks in California and New York metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Traditional fleur de sel harvesting labor scarcity props pricing premiums as apprenticeship pipelines fail to replenish coastal Brittany's raking workforce. Capacity constraints in heritage-proven origin sites concentrate procurement power among incumbents controlling authenticated supply.
For Market Incumbents: Extend certification infrastructure investment to lock in EFSA heavy metal compliance ahead of REACH Annex XVII threshold tightening. Deepen upstream control over solar evaporation ponds and cold-chain logistics to defend margin position against emerging Australian and Indian exporters scaling direct-to-chef platforms. For New Entrants and Emerging Players: Direct-to-chef mobile procurement applications offer the most penetrable route for Australian pink flake and Indian kala namak harvesters to bypass established distributor networks. Target California and New York metropolitan foodservice markets with blockchain-documented provenance and subscription replenishment models. Pursue FSSAI specialty-grade exemption positioning to access India's domestic market without iodization infrastructure investment. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified food-ingredient conglomerates seeking terroir-authenticated portfolio expansion. Long-term viability favors vertically integrated harvesters with captive evaporation, packaging, and direct freight capabilities across the analysis window. Watch for EFSA novel food dossier approval velocity as inflection signal for fermented salt blend commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Certification Investment | EFSA spectroscopic fingerprinting requirements in Germany and Netherlands mandate third-party mineral analysis for shelf placement authorization. |
| Direct-to-Chef Platform Development | Washington State solar facilities ship direct to California and New York restaurant group central kitchens, bypassing traditional import-distributor markups. |
| Botanical Fermentation R&D | Koji and lacto-fermentation techniques expand flavor salt repertoires beyond smoke and herb conventions for North American specialty retailers. |
| REACH Compliance Infrastructure | Annex XVII heavy metal threshold tightening blocks Indian and Pakistani artisan producers without dedicated washing and magnetic separation facilities. |
| FSSAI Exemption Leverage | India's specialty-grade iodization waiver permits traditional black salt producers to access domestic and export markets without mandatory fortification investment. |
Study Parameters
Trade customs databases, EFSA regulatory filings, and FSSAI exemption documentation formed the secondary backbone for supply-side validation. Primary interviews with chef procurement managers, heritage salt harvesters in Brittany, specialty retail category buyers, and REACH compliance consultants combined with secondary triangulation to construct demand and pricing intelligence. Bottom-up crystallization capacity estimates and top-down gourmet foodservice spend analysis were cross-referenced for segment sizing.
Bottom-up modeling of solar evaporation pond yields, mining extraction rates, and fermentation batch outputs anchored volume projections across the analysis window. Segmentation dimensions included crystallization method, mineral signature grade, packaging format, end-user procurement sophistication, and distribution channel control structure. CAGRs were derived from trend extrapolation of Michelin-tier restaurant specification growth, wellness retail mineral supplementation narratives, and direct-to-chef platform adoption curves.
The model holds under stable EFSA purity enforcement and F-Gas Regulation phasedown timelines; deviation in REACH Annex XVII threshold acceleration or Guérande peninsula weather disruption would shift supply availability and pricing premiums. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Pepper Market
Spices and Seasonings
Glass Spice Jars Market
Spices and Seasonings
Cinnamon Market
Spices and Seasonings
Wild Cherry Powder Market
Spices and Seasonings
Boswellia Extract Market
Spices and Seasonings
Chef Bases Market
Spices and Seasonings
Chipotle Salt Market
Spices and Seasonings
Lemon Salt Market
Spices and Seasonings
Peppermint Extract Market
Spices and Seasonings
Europe Spice and Herb Extracts Market
Spices and Seasonings
Ginger Oil Market
Spices and Seasonings
Gourmet Seaweed Seasoning Market
Spices and Seasonings
Celery Seed Extract Powder Market
Spices and Seasonings
Blended Spices Market
Spices and Seasonings
Meat Seasonings Market
Spices and Seasonings
Basil Essential Oil Market