
 North America Seasonings Market | 2026-2036
North America Seasonings Market Size, Share, and Industry Trends Forecast 2026-2036
North America Seasonings Market Analysis
Precision fermentation and enzymatic extraction is tilting formulation pipelines toward cleaner-label savory profiles without synthetic additives. McCormick & Company leverages vertical integration from raw spice sourcing to retail shelf placement across the United States. Kerry Group anchors its position through R&D intensity in taste modulation technologies for sodium reduction. Cargill Incorporated competes on manufacturing scale in industrial seasoning blends for protein processing customers.
Seasonings encompass dried or processed plant-derived substances—whole, ground, or extracted—that impart flavor, aroma, or color to food through volatile oil concentrations typically measured by gas chromatography. Their primary commercial purpose spans finished consumer goods, intermediate food manufacturing inputs, and food service batch preparation. Blends capture the deepest margin pools as proprietary formulations lock in customer switching costs across restaurant chains and ready-meal producers. Spices represent the fastest-growing product type as ethnic cuisine proliferation drives single-origin turmeric, cumin, and chili demand. Pouches gain share in retail channels due to portion control trends and reduced packaging material costs versus glass bottles.
FDA Food Safety Modernization Act rules and USDA organic certification requirements shape ingredient traceability burdens and label claim substantiation across the supply chain. Health Canada and PMRA pesticide residue limits for imported spices create additional compliance gates for cross-border suppliers. Stakeholders must monitor how state-level sodium warning laws in New York and California propagate to other jurisdictions and reshape formulation priorities.
Market Dynamics
Precision fermentation and enzymatic extraction are collapsing the cost premium between clean-label and conventional savory formulations, forcing incumbent blenders to retool production lines or cede shelf space to biotech-enabled challengers. This technological inflection is compressing formulation cycles from 18 months to under six months while FDA sodium reduction mandates tighten the specification window for industrial customers.
Growth Catalysts
- FDA Food Safety Modernization Act traceability rules:Batch-level digital tracking requirements are accelerating investment in blockchain-enabled supply chain platforms among mid-sized importers seeking compliance arbitrage.
- Mexican cuisine proliferation:Single-origin chili and cumin demand from food service operators in Texas and California is pulling volume through direct-sourcing relationships with Oaxaca and Sonora cooperatives.
- Enzymatic extraction:Clean-label umami enhancement without MSG or yeast extracts is unlocking reformulation contracts with frozen ready-meal producers facing sodium warning label exposure.
Market Restraints
- Input cost volatility:Climate-driven supply disruptions in Gujarat turmeric and Malabar black pepper are compressing blender margins and forcing price pass-through clauses in annual contracts.
- Supply concentration risk:Vietnam and Indonesia account for over 70% of global cassia and clove supply, creating single-point vulnerability for cinnamon-dominant seasoning portfolios.
- Technical limitation:Natural color stability in paprika and turmeric extracts degrades under LED retail lighting, constraining clean-label claims in transparent pouch formats.
Strategic Opportunities
- Underpenetrated Canadian food service:Sodium reduction mandates from Health Canada are creating first-mover advantage for taste-modulation technology licensors in Quebec and Ontario chain restaurants.
- Precision fermentation convergence:Biosynthetic heme and dairy protein platforms are enabling entirely new savory base categories that bypass agricultural commodity cycles.
- Direct-to-manufacturer e-procurement:Bulk spice platforms are disintermediating traditional importer-distributor networks for mid-sized protein processors seeking lot-specific certificates of analysis.
Industry Challenges
- Gas chromatography technician scarcity:Volatile oil quantification expertise is concentrated among retiring analytical chemists, constraining quality control throughput at expanding blend facilities.
- USDA organic certification timeline:Three-year transition requirements for conventional spice farms are mismatching customer clean-label procurement windows and forcing speculative inventory positions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Seasonings Market |
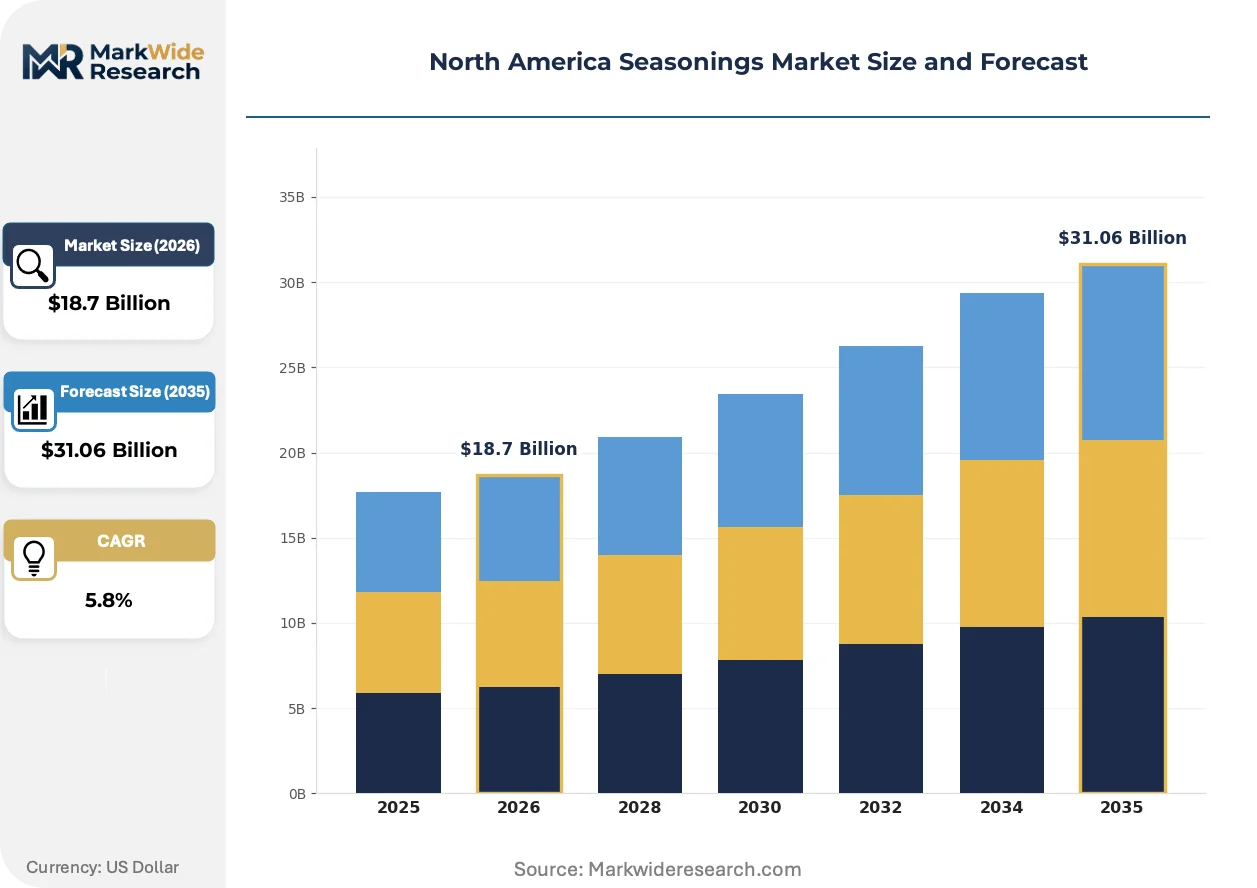
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbs, Spices, Blends, Sauces Packaging Type: Bottles, Pouches, Tubs, Sachets End User: Household, Food Service, Retail, Food Processing Distribution Channel: Supermarkets, Online Stores, Specialty Stores, Wholesale |
| Companies Covered | McCormick & Company Inc., Kerry Group PLC, Olam International, Döhler Group, All Seasonings Ingredients Inc., Cargill Incorporated, Ajinomoto Co. Inc., Horton Spice Mills Ltd., Newly Weds Foods Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Seasonings Market Emerging Trajectories
Biotechnology-enabled ingredient platforms are compressing the traditional agricultural-industrial processing boundary, enabling flavor profiles previously locked to specific geographies or harvest conditions. This shift is redistributing value capture toward fermentation infrastructure operators and away from conventional commodity traders.
Precision fermentation is collapsing the production economics of rare volatile compounds previously extracted from scarce botanical sources. Biosynthetic platforms now generate clean-label savory molecules at scale for frozen pizza and snack seasoning applications. Major protein processors are trialing these inputs to preempt sodium warning label exposure in California and New York jurisdictions.
FDA sodium reduction guidance and Health Canada front-of-package labeling regulations are mandating reformulation investment across the continent. Industrial seasoning blenders must now validate taste-equivalent sodium reductions through controlled consumer panels. Ready-meal manufacturers in the US Midwest and Ontario are accelerating RFP cycles to secure compliant supply before enforcement deadlines.
Food service procurement is consolidating around direct-import relationships for high-volume single-origin spices, bypassing traditional layered distributor markups. Large chain operators in Texas and California are establishing captive sourcing offices in Veracruz and Guadalajara. This disintermediation is compressing working capital cycles for blenders while exposing them to foreign exchange and phytosanitary inspection volatility.
North America Seasonings Market Segmentation
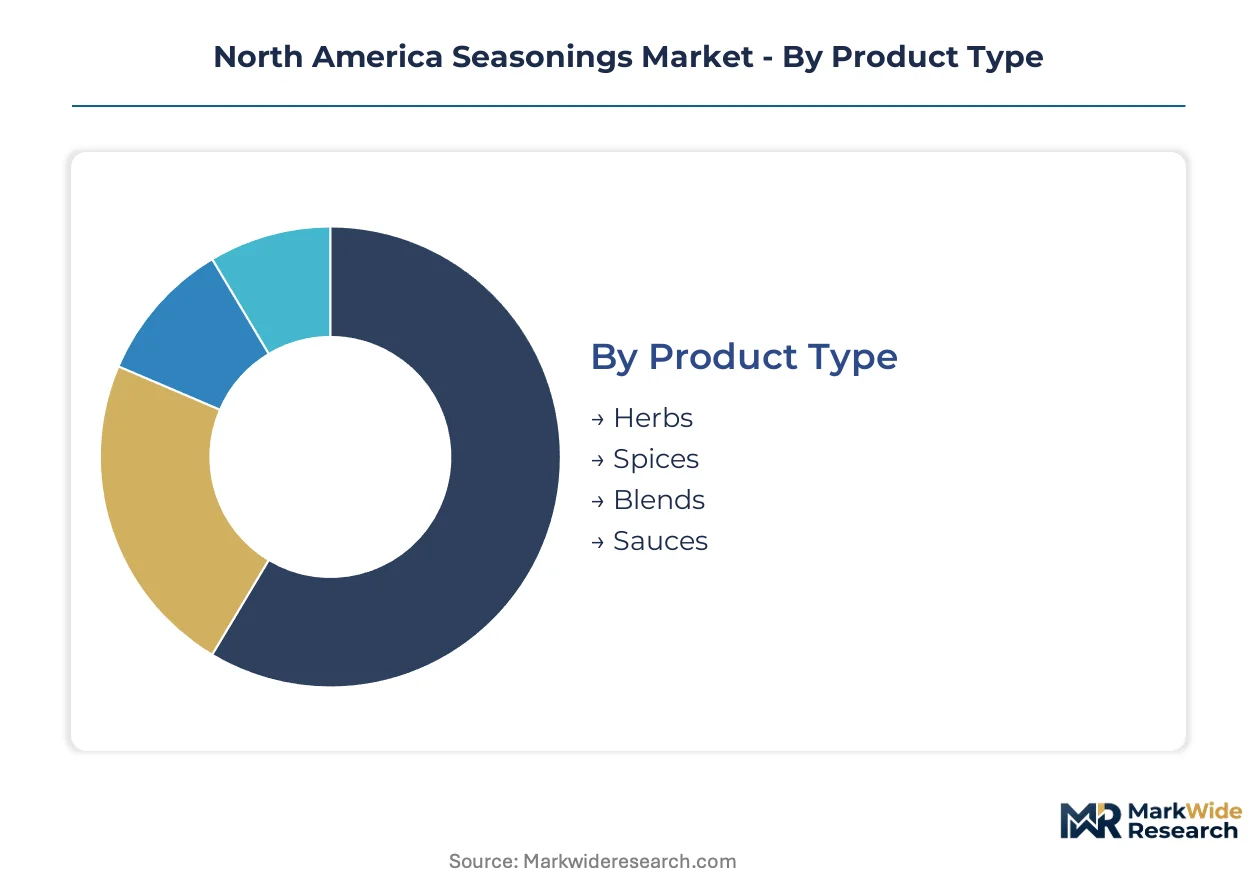
Segmentation in seasonings determines formulation complexity, shelf-life engineering, and compliance burden across distinct buyer workflows. Each dimension carries divergent margin profiles and regulatory exposure that shape supplier resource allocation.
Product Type:
After-sales intensity varies sharply across product types, with blends requiring ongoing technical support for reformulation while spices demand traceability documentation and herbs need freshness guarantees.
- Blends:Proprietary formulations combining multiple spices, herbs, and functional carriers into signature taste profiles. Restaurant chains in Texas and California lock in multi-year supply agreements to protect menu consistency, creating substantial switching costs for incumbent suppliers.
- Spices:Single-origin or standardized ground products including turmeric, cumin, and chili with volatile oil specifications verified through gas chromatography. Demand concentrates in the US Southwest where Mexican and fusion cuisines drive bulk consumption of Oaxaca-sourced chilis and Sonora cumin.
- Herbs:Dried leaf products with shorter shelf lives and moisture-sensitive packaging requirements. Basil, oregano, and cilantro variants serve pizza manufacturers and sauce blenders seeking clean-label ingredient declarations.
- Sauces:Liquid or semi-liquid flavor delivery systems incorporating seasonings into ready-to-use formats. Barbecue, hot sauce, and marinade applications dominate food processing procurement in the US Midwest.
By volume, blends lead. By growth pace, spices are ahead.
Packaging Type:
Cost tier stratification separates premium glass bottling from economy sachet formats, with mid-tier pouches capturing food service volume through reduced material spend and improved logistics density.
- Pouches:Flexible film structures with resealable closures or single-use tear formats. Portion control trends and reduced packaging material costs versus glass bottles drive adoption in retail channels across California and New York.
- Bottles:Glass or PET containers with shaker-fitment closures for tabletop and pantry storage. Premium positioning in specialty stores and supermarkets supports margin retention despite higher freight costs.
- Tubs:Rigid plastic containers for bulk institutional quantities. Food service operators in Texas prefer this format for back-of-house batch preparation with reduced handling labor.
- Sachets:Single-serve paper or film packets for portion-controlled dispensing. Quick-service restaurants and airline catering programs value precise inventory control and minimal waste.
Pouches dominate food service procurement by unit volume. Sachets climb fastest as portion-control mandates spread.
End User:
Application maturity separates established household consumption from emerging food processing automation, with food service representing the most contested middle ground for supplier loyalty programs.
- Food Service:Restaurants, cafeterias, and catering operations purchasing bulk formats with direct-import relationships. Chains in California and Texas are establishing captive sourcing offices in Veracruz and Guadalajara to bypass distributor markups.
- Food Processing:Ready-meal manufacturers, snack producers, and protein processors requiring validated sodium-reduction formulations. FDA labeling rules and Health Canada front-of-package regulations are accelerating RFP cycles in the US Midwest and Ontario.
- Household:Individual consumers purchasing retail formats through supermarkets and online channels. Clean-label claims and ethnic cuisine experimentation drive basket composition in urban markets.
- Retail:Private-label and branded product merchandising through grocery and specialty channels. Seasonal promotional calendars and shelf-space negotiations determine supplier access.
Food processing commands the highest per-account revenue. Food service expands most quickly through direct-sourcing disintermediation.
Distribution Channel:
Customer type concentration splits between price-sensitive wholesale volume and experience-driven specialty discovery, with online platforms eroding traditional supermarket dominance in urban corridors.
- Supermarkets:Mass-market retail with planogram-managed shelf space and promotional funding requirements. Category captains in the seasoning aisle leverage scan-data insights to defend placement in California and Northeast metropolitan stores.
- Online Stores:Direct-to-consumer and B2B platforms offering subscription replenishment and bulk procurement. Mid-sized protein processors are migrating to e-procurement for lot-specific certificates of analysis.
- Specialty Stores:Ethnic grocers, gourmet retailers, and natural-food channels with curated assortments. Mexican and Asian cuisine specialists in Texas and California drive single-origin spice discovery.
- Wholesale:Cash-and-carry and distributor-served accounts for independent restaurants and institutional buyers. Price transparency and volume rebates structure contract negotiations.
Supermarkets retain the largest transaction volume. Online stores gain share fastest through B2B platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexican spice exports flow northward into California and Texas food service networks, while Canadian processors source bulk seasonings through cross-border trade corridors. FDA traceability mandates and Health Canada sodium reduction programs are reshaping procurement patterns across the continent.
United States
California and Texas food service chains drive bulk consumption of Oaxaca-sourced chilis and Sonora cumin through direct-import relationships. FDA Food Safety Modernization Act batch-level tracking requirements are accelerating blockchain-enabled supply chain investments among mid-sized importers. Southwestern restaurant operators in Los Angeles and Houston are establishing captive sourcing offices to bypass traditional distributor markups.
Canada
Quebec and Ontario chain restaurants are accelerating taste-modulation technology adoption ahead of Health Canada front-of-package sodium labeling enforcement. PMRA pesticide residue limits for imported spices create additional compliance gates for cross-border suppliers. Toronto-based protein processors are migrating toward e-procurement platforms for lot-specific certificates of analysis.
Mexico
Veracruz and Guadalajara agricultural cooperatives supply single-origin chili and cumin to US Southwest food service operators through direct-trade agreements. The country's national food safety regulator maintains phytosanitary inspection protocols that govern export eligibility. Oaxaca spice farming clusters are expanding organic transition acreage to meet three-year USDA certification timelines demanded by US buyers.
North America Seasonings Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. The market structure consolidates around vertically integrated spice processors and R&D-intensive taste modulation licensors. Three archetypes dominate: agricultural commodity traders with captive sourcing networks, biotechnology-enabled fermentation platforms, and regional blend specialists serving food service accounts. M&A activity concentrates on taste technology acquisitions and direct-import relationship consolidation.
Within the integrated processing tier, McCormick & Company and Cargill Incorporated occupy positions spanning raw material sourcing through retail distribution. Kerry Group exemplifies the R&D-intensive archetype focused on sodium reduction formulations. These three entities represent distinct competitive vectors: agricultural supply chain control, manufacturing scale, and proprietary taste science.
| Leading Market Players |
|---|
| McCormick & Company Inc. |
| Kerry Group PLC |
| Olam International |
| Döhler Group |
| All Seasonings Ingredients Inc. |
| Cargill Incorporated |
| Ajinomoto Co. Inc. |
| Horton Spice Mills Ltd. |
| Newly Weds Foods Inc. |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Vietnam and Indonesia for cassia and clove supply determines both pricing tier spreads and supply chain shape across North American seasoning markets. Climate-driven disruptions in Gujarat turmeric and Malabar black pepper compress blender margins while forcing annual contract renegotiations with price pass-through clauses.
Pricing Analysis
Current-generation enzymatic extraction commands premium positioning against conventional solvent-based processing, while next-generation precision fermentation inputs are collapsing cost premiums between clean-label and synthetic formulations. Three-tier pricing structure across premium, standard, and economy levels stratifies by volatile oil concentration and organic certification status. Pricing pressure stems from FDA sodium reduction mandates tightening specification windows for industrial customers. Food processing buyers exhibit highest price sensitivity due to reformulation volume requirements, while specialty retail channels absorb premium positioning for single-origin provenance claims.
Supply Chain Analysis
Tariff exposure between Mexico and the United States dominates supply chain risk calculus for chili and cumin flows into California and Texas food service networks. Geographic supply concentration rests on Vietnam and Indonesia for cassia and clove, India for turmeric and black pepper, and Mexico for chili varieties. Raw material dependencies center on volatile oil-bearing botanicals, organic-certified acreage, and biosynthetic fermentation feedstocks. Distribution runs through direct-import relationships disintermediating traditional layered distributor networks for high-volume food service accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates opportunity as clean-label procurement windows mismatch conventional agricultural certification timelines, opening niches for biotechnology-enabled challengers and regional blend specialists.
For Market Incumbents: Build captive sourcing moats through backward integration into Oaxaca and Sonora cooperative partnerships to defend against direct-import disintermediation. Invest in gas chromatography capacity expansion to address technician scarcity constraining quality control throughput. Secure multi-year taste-modulation technology licenses ahead of Health Canada sodium enforcement deadlines. For New Entrants and Emerging Players: Pursue underpenetrated Canadian food service segments in Quebec and Ontario where sodium reduction mandates outpace incumbent formulation capabilities. Target mid-sized protein processors migrating to e-procurement platforms for lot-specific certificates of analysis. Lead with precision fermentation-enabled savory bases that bypass agricultural commodity cycle exposure. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors fermentation infrastructure operators over conventional commodity traders. Long-term viability over the coming decade hinges on biosynthetic platform economics achieving cost parity with botanical extraction. Acquisition candidates with captive sourcing relationships in Veracruz and Guadalajara agricultural clusters warrant priority attention. Monitor FDA traceability enforcement propagation as inflection indicator for blockchain-enabled supply chain platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Biosynthetic savory molecules unlock clean-label reformulation contracts with frozen ready-meal producers facing sodium warning exposure. |
| Direct-Import Relationship Consolidation | Captive sourcing offices in Veracruz and Guadalajara bypass distributor markups while exposing operators to phytosanitary inspection volatility. |
| Taste Modulation Technology Licensing | Sodium reduction formulation capabilities secure multi-year supply agreements with restaurant chains in Health Canada jurisdiction. |
| Blockchain Supply Chain Investment | Batch-level digital tracking platforms satisfy FDA Food Safety Modernization Act traceability requirements for mid-sized importers. |
| Organic Certification Pipeline Development | Three-year transition acreage expansion in Oaxaca farming clusters aligns with USDA procurement windows demanded by US buyers. |
Methodological Framework
Initial hypotheses were tested against primary input from seasoning blend formulation chemists, food service procurement directors, protein processing R&D leads, and agricultural cooperative managers and refined through secondary validation. Primary fieldwork combined structured interviews across stakeholder roles with facility observations in Texas and California food service operations. Secondary sources encompassed FDA enforcement discretion letters, USDA organic certification databases, Health Canada front-of-package labeling guidance, and customs trade flow records. Bottom-up volume modeling triangulated against top-down value estimates derived from industry revenue disclosures.
Demand-supply balance framing anchored the forecast framework across the analysis window. Segmentation dimensions modeled include product type, packaging format, end user category, and distribution channel, with additional granularity on volatile oil concentration tiers and organic certification status. CAGRs were derived from growth driver elasticity analysis applied to baseline consumption patterns. Industry-specific inputs incorporated FDA sodium reduction guidance enforcement timelines and Health Canada regulatory propagation assumptions.
Sensitivities concentrate around climate-driven supply disruptions in Gujarat and Malabar growing regions, FDA traceability rule enforcement intensity, and precision fermentation cost curve trajectories. Forecasts reflect documented assumptions regarding biotechnology adoption rates and regulatory propagation patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Peppermint Extract Market
Spices and Seasonings
Europe and Asia Juniper Berries Market
Spices and Seasonings
Cinnamon Market
Spices and Seasonings
Dried Spices Market
Spices and Seasonings
US Spice and Seasonings Market
Spices and Seasonings
Cardamom Oil Market
Spices and Seasonings
Habanero Salt Market
Spices and Seasonings
Ginger Oil Market
Spices and Seasonings
Chef Bases Market
Spices and Seasonings
Egypt Herbs and Spices Market
Spices and Seasonings
Incense Sticks (Agarbatti) Market
Spices and Seasonings
Gourmet Seaweed Seasoning Market
Spices and Seasonings
Onion Powder Market
Spices and Seasonings
Sriracha Market
Spices and Seasonings
Oregano Oil Market
Spices and Seasonings
Dried Herbs Market