
 Chile Fruits and Vegetables Market | 2026-2036
Chile Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Fruits and Vegetables Market Outlook
Precision-controlled post-harvest cold chain technology is reconfiguring how Chilean produce reaches distant export markets with minimal spoilage. Hortifrut leverages extensive blueberry genetics R&D to sustain year-round supply continuity across hemispheres. Exportadora Subsole anchors volume leadership in table grape exports through controlled-atmosphere logistics networks. Greenvic differentiates via organic certification depth across its berry and citrus portfolio.
Chile fruits and vegetables encompass fresh, minimally processed plant products cultivated across Mediterranean-climate valleys, with harvest cycles counter-seasonal to Northern Hemisphere suppliers and shelf-life parameters tightly governed by temperature-managed supply chains. The category serves retail, food service, and industrial processing channels demanding phytosanitary compliance and traceability documentation. Fruits command the dominant value share within product type segmentation, driven by premium berry and grape export volumes. Modified atmosphere packaging represents the fastest-growing packaging category as exporters seek extended transit windows for Asian and North American routes. The export end-use segment absorbs the highest margin pools, reflecting compliance costs and cold chain premiums embedded in FOB pricing structures.
SAG, Chile's national agricultural and livestock service, enforces phytosanitary certification aligned with USDA APHIS import requirements for US market entry. The EU's F-Gas Regulation and Chile's own refrigeration emissions standards are reshaping cold chain infrastructure investment priorities across the Central Valley. Stakeholders must monitor evolving maximum residue limits in destination markets and assess whether controlled-environment packaging upgrades justify the capital outlay against tightening EU and North American phytosanitary windows.
Market Dynamics
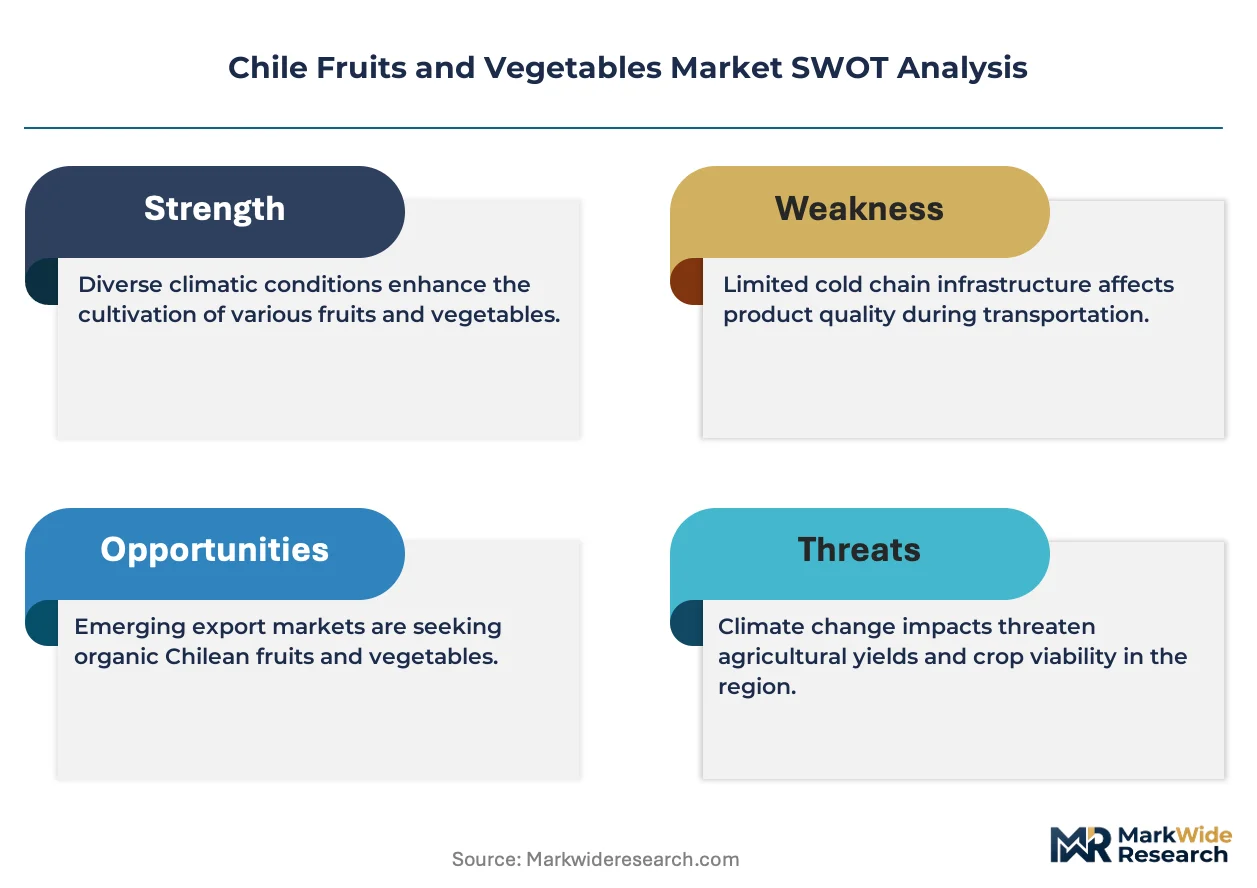
Chile's fruits and vegetables sector pivots on cold chain infrastructure expansion that extends shelf-life windows for trans-Pacific shipments, compressing spoilage losses while opening Asian market access previously unreachable for perishable berries and stone fruits.
Growth Catalysts
- USDA APHIS phytosanitary alignment:Chile's SAG certification protocols eliminate inspection bottlenecks at US ports, accelerating clearance times for table grape and blueberry consignments bound for California and New York distribution hubs.
- Modified atmosphere packaging:Film technologies with oxygen-scavenging layers extend transit viability for Chilean cherries to Shanghai and Seoul, enabling 21-day sea freight alternatives to air cargo.
- Maule Valley production clustering:Consolidated blueberry and raspberry operations around Linares and Parral generate scale economies in harvest labor pooling and shared cooling facility utilization.
Market Restraints
- Water scarcity in O'Higgins:Rapel Valley irrigation allocations tighten during drought cycles, constraining expansion of table grape acreage despite strong export pricing.
- EU F-Gas refrigeration standards:Cold chain infrastructure faces retrofit costs for hydrofluorocarbon phase-out, compressing margins on European-bound shipments already burdened by compliance documentation.
- Peruvian counter-seasonal competition:Ica and La Libertad valleys harvest overlapping windows with northern Chile, eroding price premiums in US retail contracts.
Strategic Opportunities
- India FSSAI market opening:Chilean stone fruits and citrus await phytosanitary protocol finalization with Indian regulators, representing latent demand from Mumbai and Delhi wholesale channels.
- Organic certification arbitrage:EU organic import quotas create pricing spreads that incentivize conversion of Maule Valley conventional acreage to certified organic production.
- Blockchain-IoT traceability convergence:Real-time temperature logging linked to distributed ledger verification commands premium positioning in Japanese supermarket chains demanding farm-to-shelf transparency.
Industry Challenges
- Refrigeration technician scarcity:Central Valley cold storage facilities compete for qualified personnel capable of maintaining controlled-atmosphere systems across multiple fruit varieties with divergent storage protocols.
- Phytosanitary certification timelines:SAG inspection backlogs during peak harvest compress export windows, forcing air freight substitution that erodes margins on lower-value citrus categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Fruits and Vegetables Market |
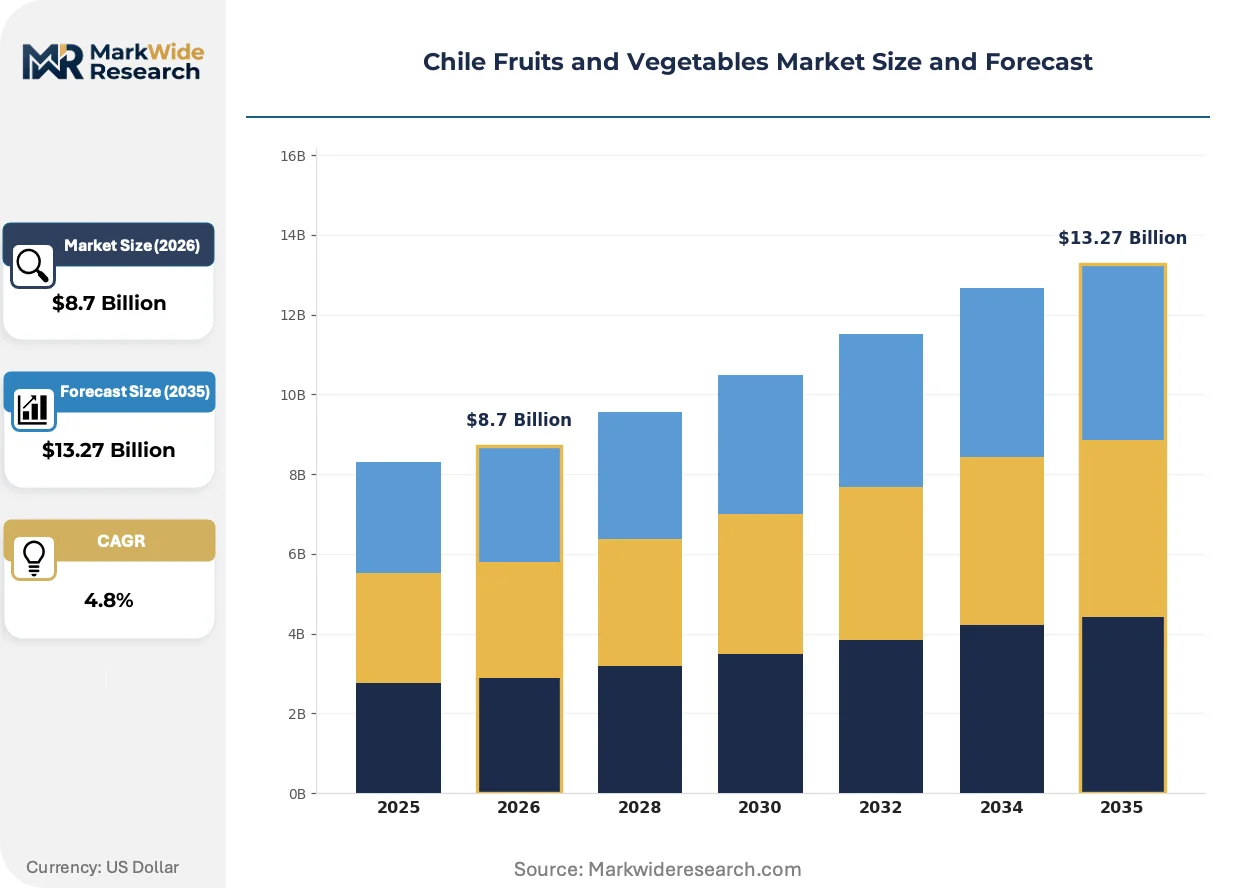
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Herbs, Nuts Distribution Channel: Supermarkets, Local Markets, Online Retail, Wholesalers Packaging Type: Bulk, Retail, Sustainable, Modified Atmosphere End Use: Household, Food Service, Processing, Export |
| Companies Covered | CULTIVA, Unifrutti Traders, Hortifrut, Prize Export, Exportadora Subsole, Copec Agro Industrial, Frutícola Santa Cruz, Greenvic, Australis Seafood, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Fruits and Vegetables Market Strategic Shifts
Cold chain digitization and packaging chemistry advances are compressing perishability constraints that historically limited Chile's export radius, while regulatory pressure on emissions intensifies infrastructure investment decisions across the Central Valley.
Controlled-atmosphere storage technology is migrating from static warehouse applications to mobile container environments, with Maersk and Hamburg Süd deploying reefers equipped with real-time ethylene scrubbing for Chilean blueberry routes. Asian supermarket buyers in Seoul and Tokyo now specify CA-container certification as a procurement condition, forcing exporters to absorb per-box premiums or lose shelf placement. The technology is migrating from premium berry categories to mid-tier stone fruits, compressing quality differentiation that previously justified price stratification.
Chile's own refrigeration emissions standards, layered atop EU F-Gas Regulation compliance requirements for export-bound equipment, mandate ammonia and CO2 cascade systems in new cold storage construction. Cold chain operators in Los Angeles and Rotterdam now audit Chilean supplier facilities for refrigerant inventory documentation, rejecting loads from non-compliant origins. The O'Higgins region bears disproportionate retrofit pressure given its concentration of legacy hydrofluorocarbon infrastructure serving grape export volume.
Direct procurement contracts between Chilean grower cooperatives and North American retail chains are displacing traditional importer-distributor intermediaries, compressing margin extraction layers in the supply chain. Walmart and Costco now negotiate FOB pricing directly with Curicó and Talca valley associations, bypassing Los Angeles-based fresh produce wholesalers. The pattern concentrates in table grapes and blueberries where volume consistency and phytosanitary documentation standardization reduce intermediary value-add.
Chile Fruits and Vegetables Market Segmentation
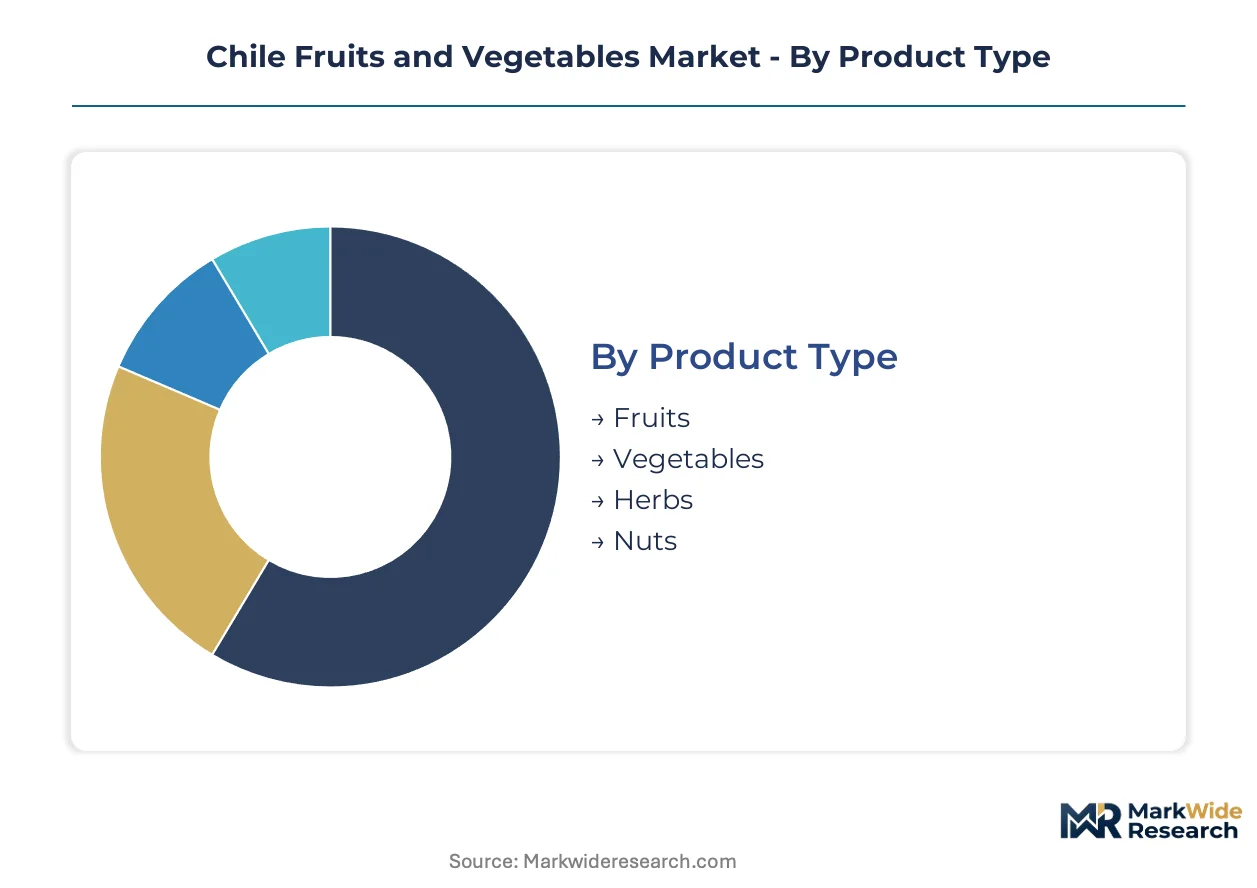
Segmentation in Chile's produce sector maps how export compliance requirements, shelf-life constraints, and channel economics fragment procurement strategies across distinct buyer profiles. Cold chain capabilities and phytosanitary documentation intensity vary sharply by segment, reshaping where capital concentrates.
Product Type:
Mature categories with established export infrastructure dominate revenue pools, while emerging segments exploit certification premiums and dietary trend tailwinds.
- Fruits:Table grapes, blueberries, cherries, and stone fruits constitute the core export volume, with Maule and O'Higgins valley clusters supplying counter-seasonal harvests to US and Asian retail channels. Phytosanitary certification costs per container run highest for this segment, compressing margins on smaller consignments.
- Vegetables:Asparagus, peppers, and tomatoes serve processing and fresh-cut channels, with shorter shelf-life windows limiting export radius compared to fruits. Labor-intensive harvest schedules concentrate employment in Central Valley communes during peak seasonal windows.
- Herbs:Cilantro, parsley, and oregano supply domestic food service and limited export niches demanding rapid air freight turnaround.
- Nuts:Walnuts and almonds from southern regions target ingredient manufacturing and snack processing, with hulling and shelling infrastructure determining farm-gate pricing power.
Fruits retains volume leadership; herbs holds the steepest expansion curve as fresh herb demand climbs in Santiago and Valparaíso restaurant channels.
Distribution Channel:
Channel economics stratify by buyer scale, documentation burden, and cold chain control requirements, with direct procurement displacing traditional intermediaries in premium categories.
- Supermarkets:Lider, Jumbo, and Unimarc chains enforce traceability protocols and private-label specifications that filter supplier eligibility. Consolidated procurement volumes extract price concessions from O'Higgins grape cooperatives.
- Local Markets:La Vega Central and regional ferias libres absorb surplus harvests rejected for export grading, with cash transactions and minimal cold chain overhead preserving farmer liquidity.
- Online Retail:Cornershop and Mercado Libre logistics networks are compressing delivery windows for packaged berries and prepared salads in Santiago metropolitan demand zones.
- Wholesalers:Central Mercado Lo Valledor intermediaries connect Maule Valley producers to regional retail and food service accounts, with quality arbitration and sorting services justifying margin extraction.
Supermarkets command procurement volume leadership; online retail is climbing the fastest as last-mile cold chain investments mature.
Packaging Type:
Packaging investment intensity tracks transit distance and shelf-life requirements, with regulatory pressure on materials reshaping capital allocation across the Central Valley.
- Bulk:Wooden bins and macro-perforated cartons serve domestic processing and short-haul wholesale channels where handling speed outweighs presentation requirements. Lowest unit cost positions this format for price-sensitive citrus categories.
- Retail:Clamshells and punnets with printed traceability codes satisfy supermarket grading and consumer visibility standards for berries and cherry tomatoes.
- Sustainable:Molded fiber and compostable films respond to EU retailer plastic reduction mandates and Santiago municipal waste regulations, with cost premiums currently absorbed in organic price tiers.
- Modified Atmosphere:Oxygen-scavenging film technologies extend cherry and blueberry viability for 21-day sea freight to Shanghai and Seoul, with CA-container certification now specified by Korean retail procurement teams.
Bulk retains volume leadership; modified atmosphere packaging posts the steepest expansion trajectory as Asian route volumes climb.
End Use:
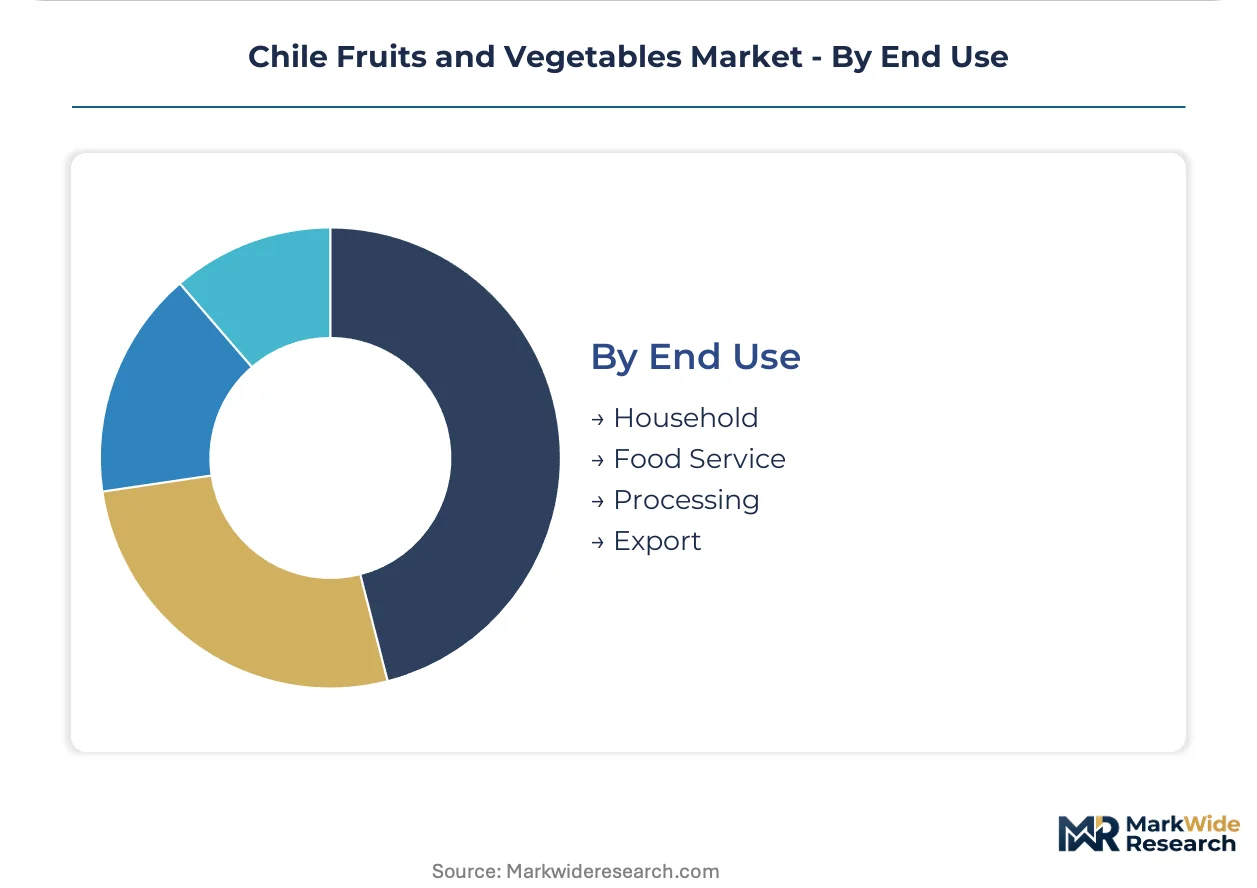
End-use segmentation aligns with documentation intensity and temperature control sophistication, with export channels absorbing disproportionate compliance investment.
- Household:Fresh consumption in Santiago, Concepción, and Valparaíso metro areas drives retail format demand, with seasonal price sensitivity peaking during domestic harvest gluts.
- Food Service:Restaurant and hotel channels in Providencia and Las Condes specify consistent sizing and ripeness staging for prepared salad and garnish applications.
- Processing:IQF freezing, juicing, and canning facilities in San Fernando and Curicó absorb grade-B harvests, with volume contracts providing price floors for conventional berry growers.
- Export:USDA APHIS and EU F-Gas compliance requirements filter supplier eligibility, with SAG phytosanitary certification timelines determining FOB pricing windows for US-bound table grape shipments.
Export commands value leadership; food service is gaining share fastest as Santiago restaurant density climbs post-pandemic recovery curves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented buyers in North America and Europe drive procurement concentration for Chilean counter-seasonal produce. Cold chain infrastructure investments and phytosanitary protocol alignment determine market access viability across destination corridors.
United States
California and New York distribution hubs absorb the majority of Chilean table grape and blueberry volumes. USDA APHIS certification requirements filter supplier eligibility, with SAG-aligned inspection protocols accelerating port clearance times. Los Angeles-based cold storage facilities audit Chilean origins for refrigerant compliance documentation.
China
Shanghai and Seoul retail channels specify modified atmosphere packaging certification for 21-day sea freight viability. Chinese import protocols for stone fruits and cherries tighten phytosanitary documentation requirements annually. Dalian and Qingdao port infrastructure investments expand reefer handling capacity for southern hemisphere counter-seasonal supply.
Germany
EU F-Gas Regulation compliance pressures Chilean exporters to retrofit cold chain equipment for hydrofluorocarbon phase-out. Hamburg and Rotterdam distribution hubs demand refrigerant inventory documentation audits. German retail chains source certified organic berries from Maule Valley conversions.
Japan
Tokyo and Osaka supermarket buyers mandate blockchain-IoT traceability for farm-to-shelf transparency premiums. METI-aligned import standards for pesticide residues shape Chilean grower chemical application protocols. Yokohama cold chain facilities specify real-time temperature logging for berry consignments.
India
Mumbai and Delhi wholesale channels await FSSAI phytosanitary protocol finalization for Chilean stone fruit and citrus entry. Indian cold storage infrastructure gaps limit current export viability despite latent demand. Navi Mumbai port authorities negotiate inspection capacity expansion for perishable cargo.
Chile Fruits and Vegetables Market Competitive Environment
Channel-controlling players compete with product-specialist players across procurement, logistics, and certification tiers. The market structure concentrates around export volume leaders with integrated cold chain assets and regional cooperatives pooling harvest labor and cooling capacity. Strategic archetypes span genetics-focused berry specialists, grape-dominant logistics operators, and organic-certified portfolio diversifiers. Competitive moves center on direct retail contract negotiation and controlled-atmosphere technology licensing.
Within the export logistics tier, Exportadora Subsole and Hortifrut exemplify scale-driven channel control, while Greenvic occupies a position in organic certification depth. CULTIVA and Unifrutti Traders represent diversified fruit portfolio operators with multi-category export capabilities. These archetypes reflect how cold chain investment intensity and phytosanitary compliance specialization stratify competitive positioning across North American and Asian destination markets.
| Leading Market Players |
|---|
| CULTIVA |
| Unifrutti Traders |
| Hortifrut |
| Prize Export |
| Exportadora Subsole |
| Copec Agro Industrial |
| Frutícola Santa Cruz |
| Greenvic |
| Australis Seafood |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Maule Valley cooling facilities during shoulder harvest periods compresses per-box handling margins and forces cooperative consolidation. SAG inspection bottlenecks at peak season tighten export windows, accelerating air freight substitution that erodes citrus category returns.
Pricing Analysis
Cost-plus contracts indexed to Los Angeles terminal market prices dominate table grape and blueberry offtake agreements, with FOB Valparaíso adjustments tracking weekly USDA AMS movement. Price differentiation separates USDA APHIS-certified organic tiers from conventional grades, with EU organic import quotas widening spreads. Pricing pressure intensifies as Peruvian Ica Valley harvests overlap northern Chilean windows, forcing contract renegotiation. Food service buyers in Santiago's Las Condes district exhibit highest price sensitivity; Japanese supermarket chains with blockchain-IoT mandates show lowest.
Supply Chain Analysis
Contract-manufacturing concentration rests with Hortifrut and Exportadora Subsole controlling controlled-atmosphere reefer capacity across Valparaíso and San Antonio ports. Geographic supply concentration centers on Chile's Central Valley, with secondary clustering in Peru's Ica Valley and Mexico's Sinaloa region for counter-seasonal overlap. Raw material dependencies include ammonia refrigerants, oxygen-scavenging film substrates, and phosphate fertilizers. Single-source vulnerability runs through Maersk and Hamburg Süd CA-container fleets. Distribution runs through direct procurement contracts with Walmart and Costco bypassing Los Angeles wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs Chilean produce export competitiveness, with blockchain-IoT traceability ecosystems in Japanese retail chains mandating interoperability standards that reshape supplier qualification.
For Market Incumbents: Build switching-cost moats through captive controlled-atmosphere reefer networks that lock in Asian retail procurement specifications. Defensive moves center on backward integration into blueberry genetics R&D and ammonia refrigeration retrofit completion ahead of EU F-Gas deadlines. Peruvian counter-seasonal expansion and SAG inspection backlog compression threaten margin structures; cold chain capacity addition in O'Higgins offsets water scarcity constraints. For New Entrants and Emerging Players: Pursue organic certification arbitrage in Maule Valley conventional acreage conversion, exploiting EU import quota pricing spreads. Most penetrable white space sits in India FSSAI protocol-finalization preparation for Mumbai wholesale entry. Direct procurement contract templates with North American retail chains offer lowest friction go-to-market angle versus Los Angeles importer-distributor intermediaries. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated cold chain operators with multi-year direct retail contracts and captive reefer fleets. Long-term viability favors scale players with SAG-aligned phytosanitary documentation infrastructure and controlled-atmosphere technology licensing positions. Acquisition targets should display ammonia/CO2 cascade refrigeration compliance and Asian route certification depth. Signal to watch: Indian FSSAI stone fruit protocol finalization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Atmosphere Reefer Fleet Expansion | Maersk and Hamburg Süd CA-container certification now conditions Korean retail shelf placement. |
| Backward Integration into Blueberry Genetics | Hortifrut's R&D pipeline sustains year-round supply continuity across hemispheric harvest windows. |
| Ammonia Refrigeration Retrofit Program | EU F-Gas Regulation and Chilean emissions standards mandate cascade system conversion in O'Higgins. |
| Direct Procurement Contract Negotiation | Walmart and Costco FOB pricing bypasses Los Angeles wholesaler margin extraction layers. |
| Blockchain-IoT Traceability Deployment | Japanese METI-aligned supermarket chains specify real-time temperature logging for premium positioning. |
Study Parameters
Initial hypotheses were tested against primary input from export operations managers at O'Higgins grape cooperatives, SAG phytosanitary certification officers, Los Angeles cold storage facility auditors, and Japanese supermarket procurement directors, then refined through secondary validation. Secondary sources included USDA APHIS import protocol documentation, EU F-Gas Regulation compliance filings, Chilean agricultural trade statistics, and refrigerated container shipping manifests. Bottom-up harvest volume modeling and top-down export value triangulation converged on segment-level estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by product type, distribution channel, packaging technology tier, and end-use application. CAGRs derived from historical export volume trajectories and forward capacity utilization assumptions. Industry-specific forecast inputs incorporated SAG inspection timeline variability and CA-container fleet deployment schedules.
Macroeconomic conditions sit as an overlay; deviation in ocean freight rates, Chilean peso exchange volatility, or EU organic import quota adjustments would shift the trajectory. Forecasts reflect documented assumptions about phytosanitary protocol stability and cold chain technology adoption curves. Quarterly review of SAG certification backlog indicators and Peruvian harvest calendar shifts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Lycopene Market
Fruits and Vegetables
IQF Fruits and Vegetables Market
Fruits and Vegetables
Dragon Fruit Powder Market
Fruits and Vegetables
Yellow Oyster Mushroom Market
Fruits and Vegetables
Fruit Packaging Market
Fruits and Vegetables
Fresh Cherries Market
Fruits and Vegetables
Brazil Fruits and Vegetables Market
Fruits and Vegetables
Fruit and Vegetable Pulp Market
Fruits and Vegetables
Plums and Sloes Market
Fruits and Vegetables
Pea Flakes Market
Fruits and Vegetables
Japan Fresh Fruits Market
Fruits and Vegetables
Dried Figs Market
Fruits and Vegetables
United Kingdom Fruits and Vegetables Market
Fruits and Vegetables
Gold Kiwifruit Market
Fruits and Vegetables
Tunisia Fruit and Vegetable Market
Fruits and Vegetables
Celery Juice Market